
 Japan Analog IC Market | 2026-2036
Japan Analog IC Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Analog IC Market Insights
Silicon carbide substrate integration is repositioning power management economics across Japan's analog IC sector. Rohm Semiconductor leverages captive SiC wafer supply to anchor its voltage regulator portfolio for automotive traction inverters. Renesas Electronics Corporation sustains broad operational amplifier R&D through consolidated fab operations in Naka and Saijo. Mitsubishi Electric Corporation dominates industrial-grade signal conditioner shipments to domestic robotics OEMs.
Analog integrated circuits process continuous electrical signals through transistor arrays fabricated in bipolar, CMOS, BiCMOS, or GaN processes, with specifications typically spanning microvolt offset voltages to megahertz bandwidth thresholds. Voltage regulators and signal conditioners command the deepest margin pools as automotive electrification and precision factory automation expand specification requirements. CMOS and BiCMOS technology segments are capturing design wins in portable consumer electronics and low-power sensor networks where quiescent current minimization determines selection criteria.
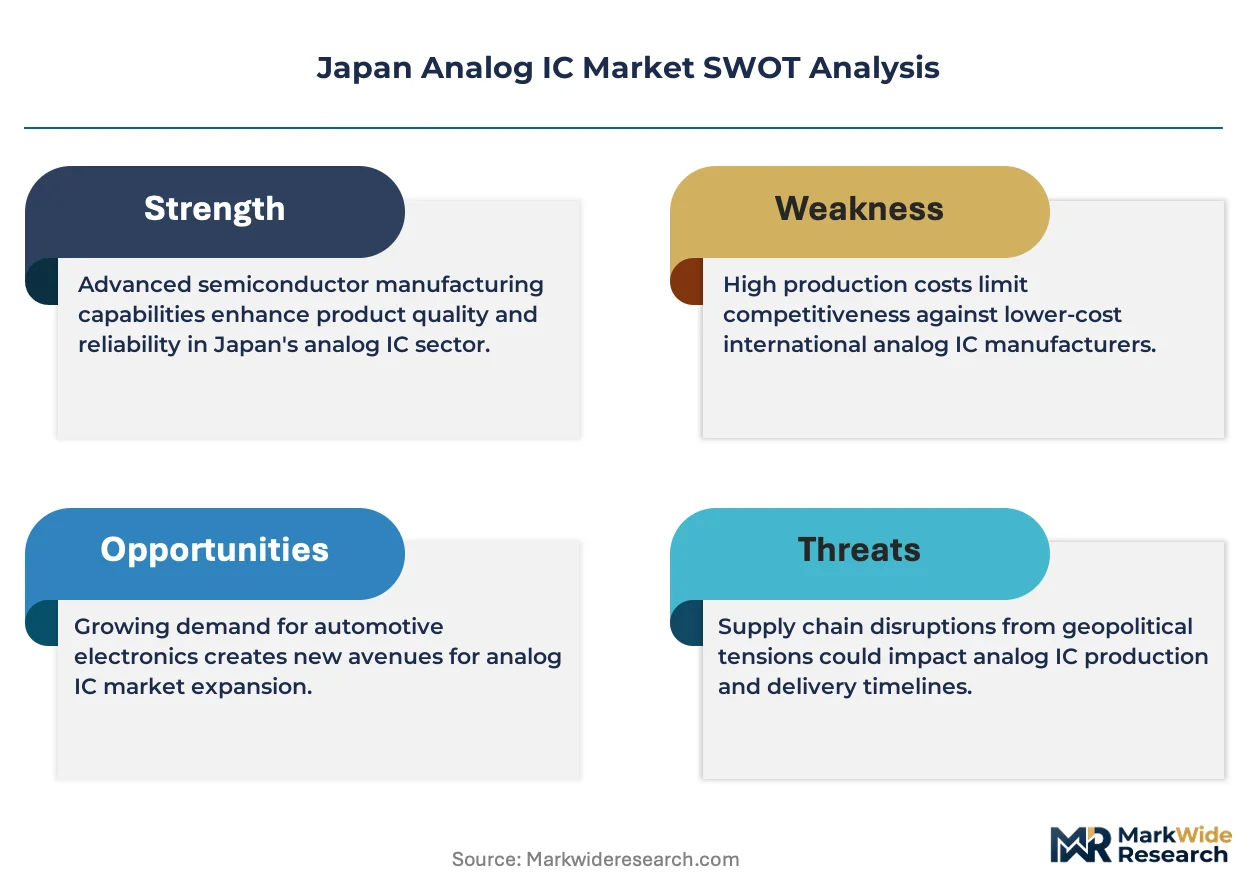
METI's semiconductor supply chain reinforcement framework and JIS standards for automotive electronic components are tightening domestic qualification protocols and accelerating local production incentives. PMDA coordination with international medical device standards indirectly shapes analog IC specifications for diagnostic equipment exported from Japan. Stakeholders must monitor METI subsidy allocation timing and foundry capacity expansion decisions in Kumamoto and Hiroshima prefectures to align procurement and inventory strategies.
Market Dynamics
Automotive electrification mandates from Toyota and Honda are compressing design cycles for precision voltage regulators while METI's semiconductor reinforcement policies reshape domestic fab capacity allocation across Kanto and Kyushu industrial corridors.
Growth Catalysts
- Automotive Electrification Mandates:Tier-1 suppliers to Toyota and Honda are expanding orders for high-voltage sensor interfaces and traction inverter control circuits. JIS automotive electronic component standards are accelerating qualification timelines for domestic analog IC vendors.
- METI Semiconductor Supply Chain Framework:Subsidy allocations for Kumamoto and Hiroshima foundry expansions are lowering capital barriers for BiCMOS process upgrades. Domestic production incentives are tightening procurement preferences for locally fabricated voltage regulators.
- Silicon Carbide Substrate Availability:Rohm Semiconductor's captive SiC wafer supply is anchoring power management economics for 800V automotive architectures. Wide-bandgap material integration is repositioning margin pools away from traditional silicon-based regulators.
Market Restraints
- 300mm Wafer Equipment Concentration:Lithography and epitaxy tool suppliers cluster in Dutch and Japanese equipment oligopolies, creating single-source vulnerability for analog IC foundry expansions in Kumamoto prefecture.
- Legacy Bipolar Process Lock-in:Industrial signal conditioning applications remain tethered to mature 180nm bipolar-CMOS-DMOS platforms with limited migration paths to advanced nodes, constraining die shrink economics.
- Specialty Substrate Cost Volatility:SiC wafer pricing fluctuations directly compress gross margins on automotive-grade voltage regulators, with 6-inch substrate supply concentrated among three global vendors.
Strategic Opportunities
- Medical Device Export Alignment:PMDA coordination with IEC 60601 standards for diagnostic equipment is creating specification pull for ultra-low-noise operational amplifiers in imaging and patient monitoring systems shipped to North American and European markets.
- Chiba Prefecture Packaging Cluster:Underutilized OSAT capacity in the Keiyo industrial zone offers test and assembly partnerships for fabless analog designers seeking JIS-qualified supply chains without Tokyo land cost premiums.
- GaN-on-Si Process Convergence:Integration of gallium nitride power devices with silicon control ICs in single packages is opening white space in compact motor drive applications for robotics OEMs in Kanagawa prefecture.
Industry Challenges
- Mixed-Signal Design Talent Scarcity:Analog IC layout expertise in precision matching and noise optimization is concentrating among engineers with 15-plus years of bipolar-CMOS experience, constraining team scaling for automotive qualification programs.
- JIS Certification Timeline Compression:Automotive electronic component standards now require accelerated reliability testing protocols that strain validation lab capacity, extending time-to-revenue for new voltage regulator introductions by domestic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Analog IC Market |
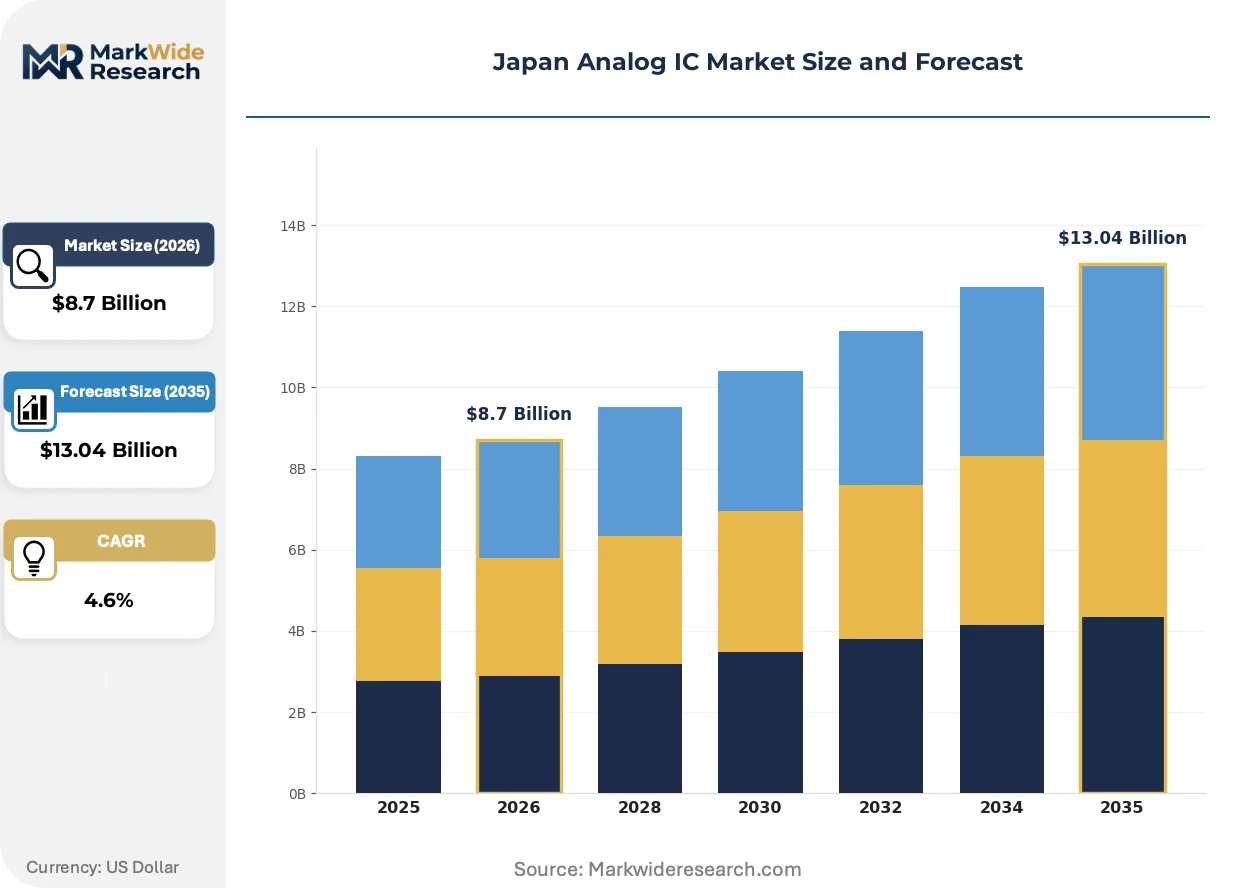
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operational Amplifiers, Comparators, Voltage Regulators, Signal Conditioners Technology: Bipolar, CMOS, BiCMOS, GaN End User: Consumer Electronics, Automotive, Industrial Automation, Telecommunications Application: Signal Processing, Power Management, Audio Applications, Sensor Interface |
| Companies Covered | Skyworks Solutions Inc., Rohm Semiconductor, Renesas Electronics Corporation, Microchip Technology Inc., NXP Semiconductors NV, Analog Devices KK, STMicroelectronics, Infineon Technologies AG, Mitsubishi Electric Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Analog IC Market Trends and Innovations
Silicon carbide power integration and METI industrial policy are restructuring fabrication economics while procurement patterns shift toward captive supply arrangements for automotive qualification security.
BiCMOS processes with deep-trench isolation are consolidating precision analog functions previously implemented in discrete component chains. Automotive tier-1 suppliers in Aichi and Shizuoka prefectures are adopting these integrated solutions for battery management systems, collapsing board space and passive component counts. The technology is consolidating subsystem economics around single-die voltage references and current sensors.
METI's semiconductor supply chain reinforcement framework is mandating domestic production ratios for critical automotive electronic components. Industrial consequence includes accelerated foundry investment decisions in Kumamoto and Hiroshima prefectures with preference for 40nm and above analog-capable nodes. Voltage regulator and signal conditioner segments face compressed qualification windows as JIS standards tighten automotive reliability thresholds.
Buyer concentration among Toyota, Honda, and Nissan procurement consortia is consolidating analog IC supplier bases around vertically integrated semiconductor divisions. Tier-2 component distributors in Tokyo and Osaka are losing share to direct foundry relationships as OEMs seek traceability for automotive qualification documentation. The shift is most visible in Kanto prefecture industrial corridors where just-in-time delivery requirements favor localized test and assembly partnerships.
Japan Analog IC Market Segmentation
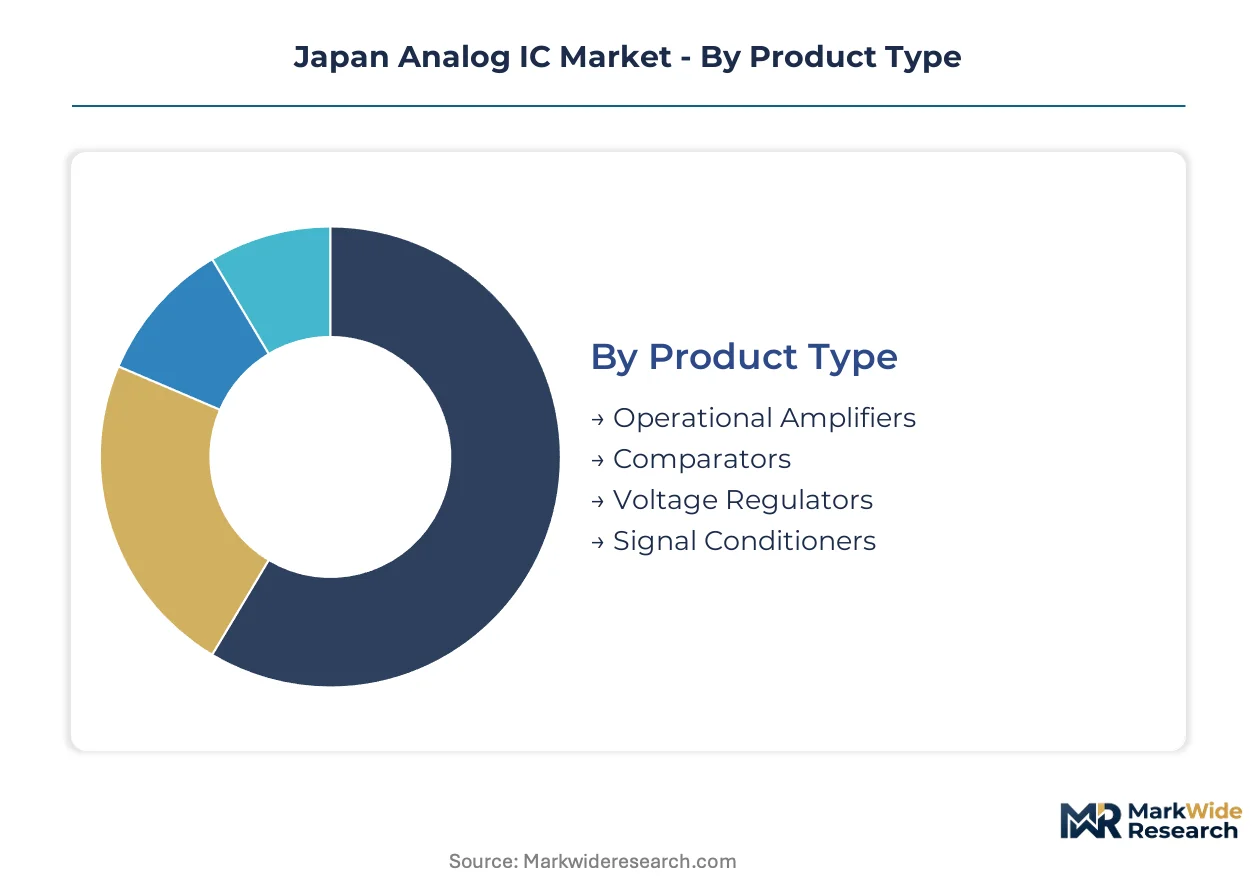
Japanese analog IC procurement patterns diverge sharply across product architectures and end-use specifications. METI's domestic production mandates and JIS automotive standards are segmenting supplier access based on qualification depth and captive fab capacity.
Product Type:
Supply concentration in automotive-grade voltage regulators is tightening procurement options for tier-1 suppliers to Toyota and Honda.
- Voltage Regulators:Precision voltage references and LDO circuits fabricated in BiCMOS and BCD processes dominate automotive power management. Demand concentrates in Aichi and Shizuoka prefectures where Toyota and Honda electrification programs require 800V-capable traction inverter control. METI subsidy allocations for Kumamoto foundry expansions are lowering capital barriers for domestic production.
- Signal Conditioners:Industrial-grade instrumentation amplifiers and isolation amplifiers process sensor outputs in factory automation environments. Mitsubishi Electric shipments to Kanagawa robotics OEMs anchor demand, though JIS certification timeline compression is extending validation cycles for new entrants.
- Operational Amplifiers:Precision bipolar and CMOS op-amps from Renesas Naka and Saijo fabs serve medical imaging and audio applications.
- Comparators:High-speed voltage comparators with microsecond response times support motor control and power sequencing functions.
Today's leader: Voltage Regulators. Tomorrow's challenger: Signal Conditioners.
Technology:
Process node economics in Japan's analog sector stratify around power efficiency thresholds and qualification heritage.
- BiCMOS:Deep-trench isolation processes integrate precision analog with moderate digital density for automotive battery management systems. Rohm Semiconductor and Renesas Electronics Corporation have consolidated design wins in Aichi prefecture tier-1 supplier channels where board space reduction drives integration value.
- Bipolar:Mature 180nm bipolar-CMOS-DMOS platforms retain lock-in for industrial signal conditioning despite limited die shrink economics. Legacy process dependency constrains margin expansion for Mitsubishi Electric's robotics-focused shipments.
- CMOS:Low-quiescent-current processes capture portable consumer electronics and sensor network applications in Tokyo and Osaka design houses.
- GaN:Gallium nitride power device integration with silicon control ICs is opening compact motor drive opportunities in Kanagawa prefecture robotics manufacturing.
BiCMOS commands current design win momentum. GaN integration paths are climbing the fastest as wide-bandgap economics mature.
End User:
Customer concentration among Toyota-Honda-Nissan procurement consortia is collapsing supplier tiers around direct foundry relationships.
- Automotive:Electrification mandates from Toyota and Honda are compressing design cycles for precision voltage regulators and high-voltage sensor interfaces. JIS automotive electronic component standards are accelerating qualification timelines for domestic vendors with captive SiC substrate supply.
- Industrial Automation:Factory robotics OEMs in Kanagawa and Chiba prefectures demand industrial-grade signal conditioners with extended temperature ranges. Mitsubishi Electric's consolidated fab operations sustain market position despite mixed-signal design talent scarcity.
- Consumer Electronics:Portable device manufacturers in Tokyo prioritize CMOS-based quiescent current minimization for battery life extension.
- Telecommunications:Base station and optical communication infrastructure in Kanto corridor requires high-linearity RF analog functions.
Automotive electrification programs anchor current procurement volume. Industrial Automation offers the steepest expansion trajectory as factory robotics density increases.
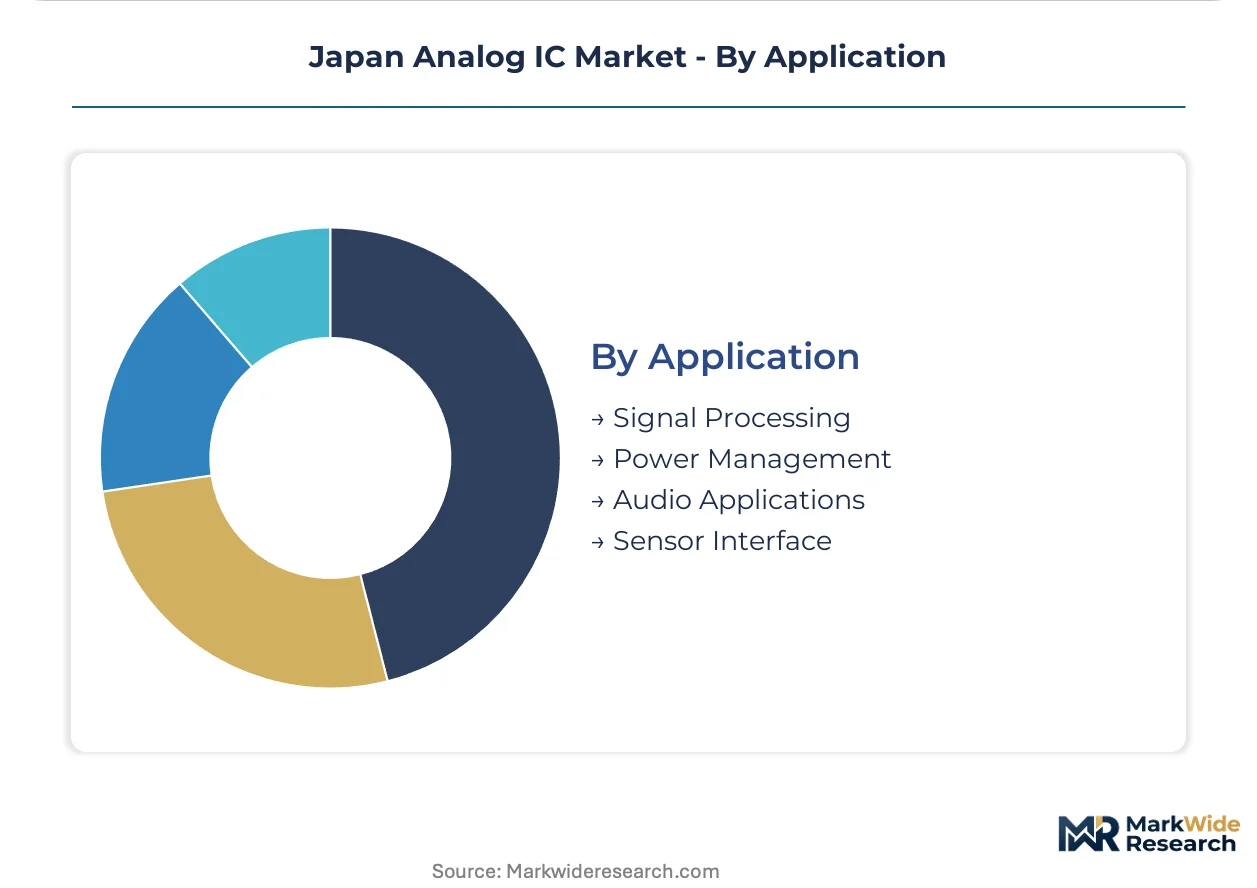
Application:
Functional integration trends are collapsing discrete component chains into single-die solutions across Japanese manufacturing.
- Power Management:Integrated voltage references, current sensors, and switching regulators are consolidating subsystem economics for automotive battery management. BiCMOS deep-trench isolation enables previously discrete functions to merge, reducing passive component counts in tier-1 supplier designs.
- Sensor Interface:Precision analog front-ends for automotive and industrial sensors require microvolt offset voltages and megahertz bandwidth thresholds. Signal conditioning chains for Toyota electrification platforms and Kanagawa robotics OEMs demand matched transistor arrays with temperature drift compensation.
- Signal Processing:Continuous-time and switched-capacitor filters support audio and communication systems in consumer and telecom segments.
- Audio Applications:Low-noise preamplifiers and Class-D drivers serve professional and consumer audio equipment manufactured in Tokyo and Osaka.
Power Management integration dominates current bill-of-material consolidation. Sensor Interface precision requirements are gaining share fastest as automotive electrification expands sensor counts per vehicle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kanto industrial corridor spanning Tokyo, Kanagawa, and Chiba prefectures anchors Japanese analog IC procurement volume. METI's semiconductor reinforcement policies concentrate foundry investments across this belt while JIS automotive standards tighten qualification protocols for domestic suppliers.
Kanto/Tokyo
Precision voltage regulators for automotive battery management systems dominate procurement from Aichi prefecture tier-1 suppliers. METI subsidy allocations for domestic production incentives are accelerating BiCMOS process qualification timelines. Tokyo-based design houses concentrate CMOS-based quiescent current minimization for portable consumer electronics.
Chubu/Nagoya
Toyota and Honda electrification programs in Aichi and Shizuoka prefectures are compressing design cycles for 800V-capable traction inverter control circuits. JIS automotive electronic component standards mandate accelerated reliability testing protocols that strain validation lab capacity. Nagoya industrial corridor suppliers are consolidating direct foundry relationships to secure traceability documentation.
Kansai/Osaka
Industrial-grade signal conditioners for factory robotics OEMs sustain demand from Mitsubishi Electric consolidated fab operations. PMDA coordination with IEC 60601 standards shapes ultra-low-noise operational amplifier specifications for diagnostic equipment exports. Osaka-based component distributors are losing share to direct procurement channels as buyer concentration tightens.
Kyushu
Kumamoto foundry expansions are lowering capital barriers for 40nm and above analog-capable node investments. Rohm Semiconductor leverages captive SiC wafer supply to anchor power management economics for automotive architectures. Hiroshima prefecture capacity decisions are reshaping regional procurement preferences for locally fabricated voltage regulators.
Chiba Prefecture
Underutilized OSAT capacity in the Keiyo industrial zone offers test and assembly partnerships for fabless analog designers. JIS-qualified supply chains in this corridor avoid Tokyo land cost premiums while maintaining just-in-time delivery requirements. Packaging cluster development is attracting sensor interface specialists serving Kanagawa robotics OEMs.
Japan Analog IC Market Competitive Landscape
Capacity expansion dominates the current landscape as METI subsidy allocations accelerate foundry investment decisions in Kumamoto and Hiroshima prefectures. The supplier base stratifies around vertically integrated semiconductor divisions, captive SiC substrate supply, and fabless designers seeking JIS-qualified partnerships. Three archetypes anchor competitive positioning: diversified electronics conglomerates with in-house fabrication, specialized power semiconductor vendors with wide-bandgap material control, and analog-focused subsidiaries of global chipmakers. Strategic moves concentrate on backward integration into substrate supply and geographic consolidation of test and assembly operations.
Among diversified Japanese electronics conglomerates, Rohm Semiconductor and Mitsubishi Electric Corporation exemplify the vertically integrated archetype with captive manufacturing assets. Renesas Electronics Corporation occupies a position bridging broad operational amplifier portfolios with consolidated domestic fab operations. These three entities anchor the competitive structure as METI domestic production mandates and automotive qualification requirements tighten supplier selection criteria around traceability and local fabrication.
| Leading Market Players |
|---|
| Skyworks Solutions Inc. |
| Rohm Semiconductor |
| Renesas Electronics Corporation |
| Microchip Technology Inc. |
| NXP Semiconductors NV |
| Analog Devices KK |
| STMicroelectronics |
| Infineon Technologies AG |
| Mitsubishi Electric Corporation |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide wafer costs cascade through automotive-grade voltage regulator pricing tiers as 6-inch substrate supply concentrates among three global vendors. BiCMOS process premiums for JIS-qualified automotive components separate captive-fab suppliers from fabless competitors serving industrial automation buyers.
Pricing Analysis
Input-cost pass-through from specialty substrate volatility dominates pricing dynamics for 800V traction inverter components. Three-tier pricing structure across JIS-certified automotive, industrial-grade, and consumer electronics tiers separates qualification heritage from volume scale. Cost compression in standard-grade signal conditioners intensifies as mature bipolar-CMOS-DMOS platforms face die shrink limitations. Tier-1 automotive suppliers exhibit lowest price sensitivity due to traceability mandates, while portable device manufacturers in Tokyo prioritize quiescent current minimization over unit cost.
Supply Chain Analysis
METI domestic production mandates are reshaping sourcing patterns toward Kumamoto and Hiroshima foundry capacity. Substrate supply draws from Japan, the United States, and Germany for SiC wafers; BiCMOS wafers source from domestic and Taiwanese foundry partners. Single-source vulnerability concentrates in Dutch and Japanese lithography equipment for 300mm expansions. Distribution runs through direct foundry relationships with Toyota-Honda-Nissan procurement consortia, bypassing traditional Tokyo and Osaka component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering as METI semiconductor reinforcement policies tighten domestic qualification thresholds and accelerate local production incentives.
For Market Incumbents: Cement automotive qualification moats by deepening captive SiC substrate supply and consolidating BiCMOS process R&D in Naka and Saijo fab operations. Threats from GaN-on-Si motor drive integration in Kanagawa robotics applications demand accelerated power management portfolio refresh. Channel control through direct tier-1 supplier relationships anchors pricing power against fabless competitors. For New Entrants and Emerging Players: Capture white space in Chiba Prefecture packaging partnerships for JIS-qualified test and assembly services without Tokyo land cost premiums. Underpenetrated medical device export channels for ultra-low-noise operational amplifiers offer fastest qualification paths through PMDA-IEC 60601 alignment. Go-to-market leverage rests on OSAT capacity partnerships in the Keiyo industrial zone. For Investors and Strategic Acquirers: Consolidation pressure builds where mixed-signal design talent scarcity constrains team scaling for automotive qualification programs. Long-term viability favors vertically integrated semiconductor divisions with captive fab capacity and SiC substrate control. Watch METI subsidy allocation timing as the inflection signal for foundry investment momentum in Kyushu.| Strategic Initiative | Industry Significance |
|---|---|
| Captive SiC Substrate Integration | Rohm Semiconductor's wafer supply anchors power management economics for 800V automotive architectures. |
| BiCMOS Process Qualification | Deep-trench isolation investments in Kumamoto foundries collapse discrete component chains for battery management systems. |
| JIS Certification Acceleration | Compressed automotive reliability timelines strain validation lab capacity and consolidate supplier tiers. |
| Chiba OSAT Partnership | Keiyo industrial zone packaging clusters attract fabless designers seeking JIS-qualified supply chains. |
| GaN-on-Si Motor Drive Development | Compact integration opens robotics OEM opportunities in Kanagawa prefecture manufacturing corridors. |
Research Methodology
Direct dialogue with analog IC design leads, tier-1 automotive supplier procurement officers, foundry operations managers, and METI policy specialists grounded qualitative insights. Secondary validation drew from METI subsidy allocation disclosures, JIS automotive electronic component standards documentation, PMDA medical device guidance, and SEC filings from listed semiconductor suppliers. Bottom-up segment modeling triangulated against top-down macroeconomic drivers.
Bottom-up volume builds aggregated product-type, technology node, and end-user segment trajectories across the projection horizon. Top-down macroeconomic anchors included automotive electrification capex cycles, factory robotics density trends, and medical device export volumes. Segmentation dimensions spanned voltage regulator and signal conditioner architectures, BiCMOS through GaN process tiers, and automotive through industrial automation demand clusters. CAGRs derived from regression analysis against historical qualification timeline compression and foundry capacity expansion announcements.
Substrate price volatility, METI policy timing shifts, and JIS certification backlog extensions are the dominant revision risks for forecast trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Comparator IC Market
IC (Integrated Circuits)
Global Analog Integrated Circuit (IC) Market
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market
IC (Integrated Circuits)
Automotive Integrated Circuit (Ics) Market
IC (Integrated Circuits)
Standard Logic IC Market
IC (Integrated Circuits)
Europe Integrated Circuits Market
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Display LSI IC Market
IC (Integrated Circuits)
NFC Tag Ics Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
Global SRAM and ROM Design IP Market
IC (Integrated Circuits)
Global Power Management Integrated Circuit (PMIC) Market
IC (Integrated Circuits)
Digital IC Market