
 Li-Ion Battery Protection Ics Market | 2026-2036
Li-Ion Battery Protection Ics Market Size, Share, and Industry Trends Forecast 2026-2036
Li-Ion Battery Protection Ics Market Foresight
The migration toward mixed-signal architectures with embedded firmware is reshaping how protection ICs integrate with battery management systems. Texas Instruments leverages its analog design heritage to sustain leadership in precision voltage monitoring solutions for high-cell-count packs. Renesas Electronics anchors its position through automotive-qualified ASIL-D compliant devices, while ON Semiconductor competes aggressively in the industrial and power tool segments with cost-optimized protection platforms.
Li-Ion Battery Protection ICs are semiconductor devices that monitor cell voltage, current, and temperature to prevent hazardous conditions including overcharge, over-discharge, and short circuits, typically operating with detection accuracy within millivolt tolerances and response times under microseconds. These circuits serve as mandatory safety layers in lithium-based energy storage systems across consumer, automotive, and industrial applications. The Protection Circuit Module category dominates unit volumes due to its ubiquity in smartphone and notebook battery packs, while the Smart Battery segment captures expanding margin pools as OEMs demand telemetry-enabled authentication and cycle-life optimization. Mixed-signal technology leads design activity by combining analog sensing precision with digital state-machine control, though pure analog solutions retain cost advantages in high-volume consumer electronics.
The US FAA and NHTSA enforce stringent battery safety standards for aviation and electric vehicle applications, directly mandating redundant protection circuitry and fault-isolation protocols that elevate IC complexity and average selling prices. In Europe, ECHA's REACH restrictions and the EU Battery Regulation's due diligence requirements are forcing suppliers to document material sourcing and recyclability, reshaping qualification timelines for new protection IC designs. Stakeholders must monitor how China's SAMR and GB standard updates for energy density thresholds will redirect R&D investment toward next-generation protection topologies capable of supporting silicon-anode and solid-state cell chemistries.
Market Dynamics
The automotive sector's pivot toward 800V architectures and silicon-anode chemistries is forcing protection IC suppliers to redesign detection thresholds and thermal monitoring algorithms from discrete analog foundations toward firmware-configurable platforms.
Growth Catalysts
- EU Battery Regulation due diligence mandates:Suppliers must document material sourcing and recyclability, extending qualification timelines but locking in long-term supplier relationships with certified IC vendors.
- Electric vehicle powertrain electrification:OEMs are scaling orders for multi-cell protection architectures capable of managing 100+ series cell configurations with ASIL-D functional safety ratings.
- East Asian foundry concentration:South Korean and Japanese semiconductor manufacturing clusters provide tier-one IDMs with captive capacity for automotive-qualified mixed-signal processes.
Market Restraints
- Wafer cost volatility:300mm analog-mixed signal process nodes face input cost pressure from specialty substrate suppliers concentrated in Taiwan and Japan.
- Automotive qualification friction:AEC-Q100 Grade 0 testing and ASIL-D certification cycles extend time-to-revenue by 18-24 months for new protection IC designs.
- Silicon-carbide MOSFET substitution:Wide-bandgap power semiconductors in battery disconnect circuits reduce reliance on traditional protection IC architectures in high-voltage packs.
Strategic Opportunities
- India PLI scheme for cell manufacturing:Domestic battery gigafactory construction creates demand for protection ICs qualified to BIS standards with localized technical support.
- Cloud-connected battery telemetry:Authentication and cycle-life optimization firmware embedded in smart protection platforms opens recurring revenue streams through over-the-air updates.
- Silicon-anode chemistry compatibility:Next-generation cells with higher energy density require redesigned overvoltage detection thresholds that obsolete legacy protection topologies.
Industry Challenges
- Mixed-signal design talent scarcity:Firmware-configurable protection architectures require analog designers with embedded systems expertise, a skill combination concentrated at a handful of semiconductor firms.
- Legacy pack integration complexity:New protection IC platforms must maintain backward compatibility with existing battery management system communication protocols while adding advanced fault-isolation capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Li-Ion Battery Protection Ics Market |
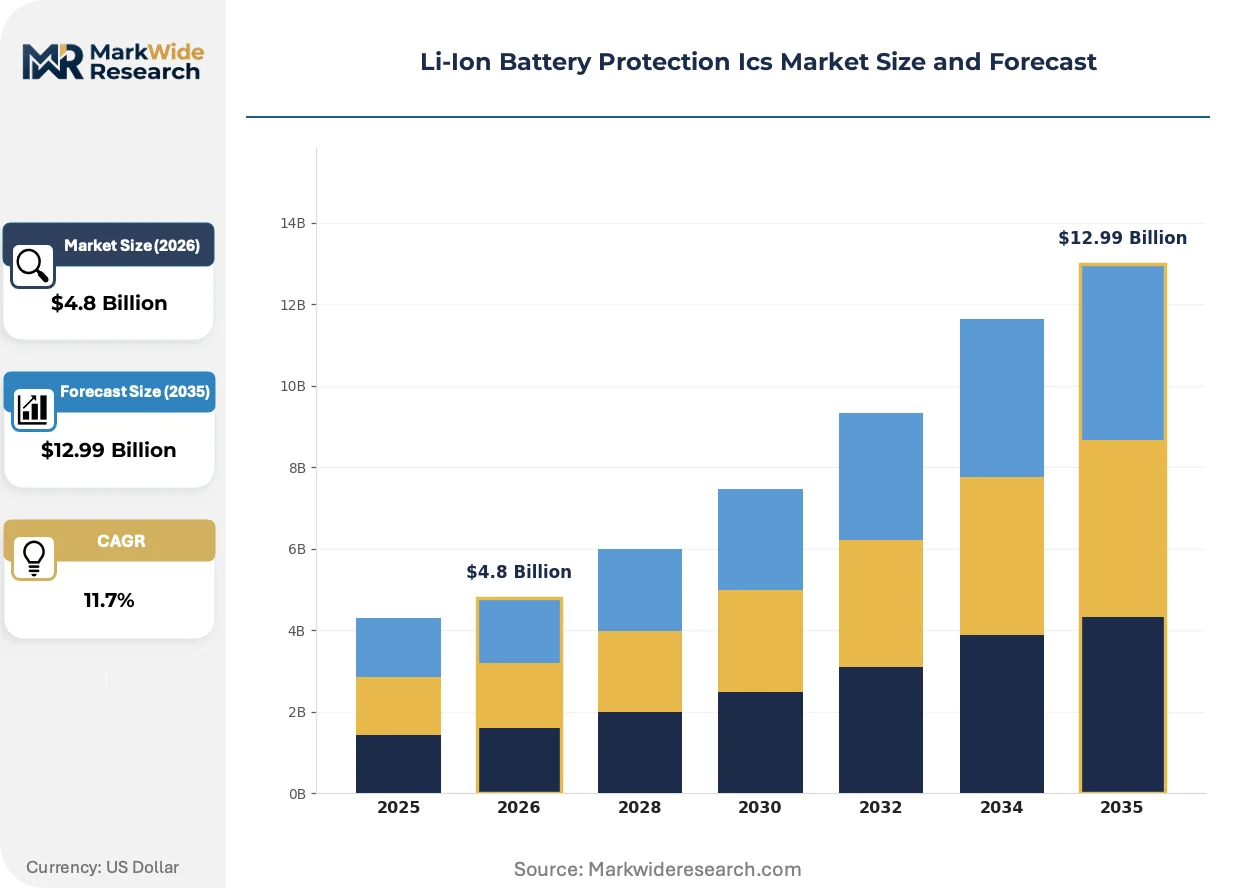
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Management System, Protection Circuit Module, Integrated Circuit, Smart Battery End User: Consumer Electronics, Automotive, Industrial, Renewable Energy Technology: Analog, Digital, Mixed-signal, Wireless Installation Type: On-board, Off-board, Embedded, Standalone |
| Companies Covered | MinebeaMitsumi, ABLIC Inc, Texas Instruments, Nisshinbo Micro Devices, Seiko Instruments, Renesas Electronics, Analog Devices, Ricoh, ON Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Li-Ion Battery Protection Ics Market Shifts & Advancements
Protection IC architectures are converging with battery management systems through embedded firmware and precision analog front-ends, compressing the traditional separation between safety monitoring and system control functions.
Integrated current-sensing with sub-milliohm shunt resistors is collapsing the discrete component count in high-cell-count packs. Electric vehicle manufacturers are adopting these monolithic solutions for 400V and 800V platforms to reduce PCB area and assembly cost. The structural consequence is collapsing bill-of-materials differentiation between premium and mid-tier protection platforms.
China's GB standards for battery safety are tightening thermal runaway propagation test requirements. SAMR-mandated energy density thresholds are forcing protection IC suppliers to validate designs against nail penetration and overcharge abuse scenarios that exceed previous certification baselines. Domestic cell manufacturers are responding by specifying protection platforms with redundant voltage monitoring and hardware-level fuse control.
Aftermarket battery authentication is shifting procurement preferences toward protection ICs with embedded secure element cryptography. Smartphone and notebook OEMs are displacing generic protection modules with vendor-locked platforms that prevent third-party cell substitution. This pattern is most visible in North American and European consumer electronics channels where warranty enforcement drives specification requirements.
Li-Ion Battery Protection Ics Market Segmentation
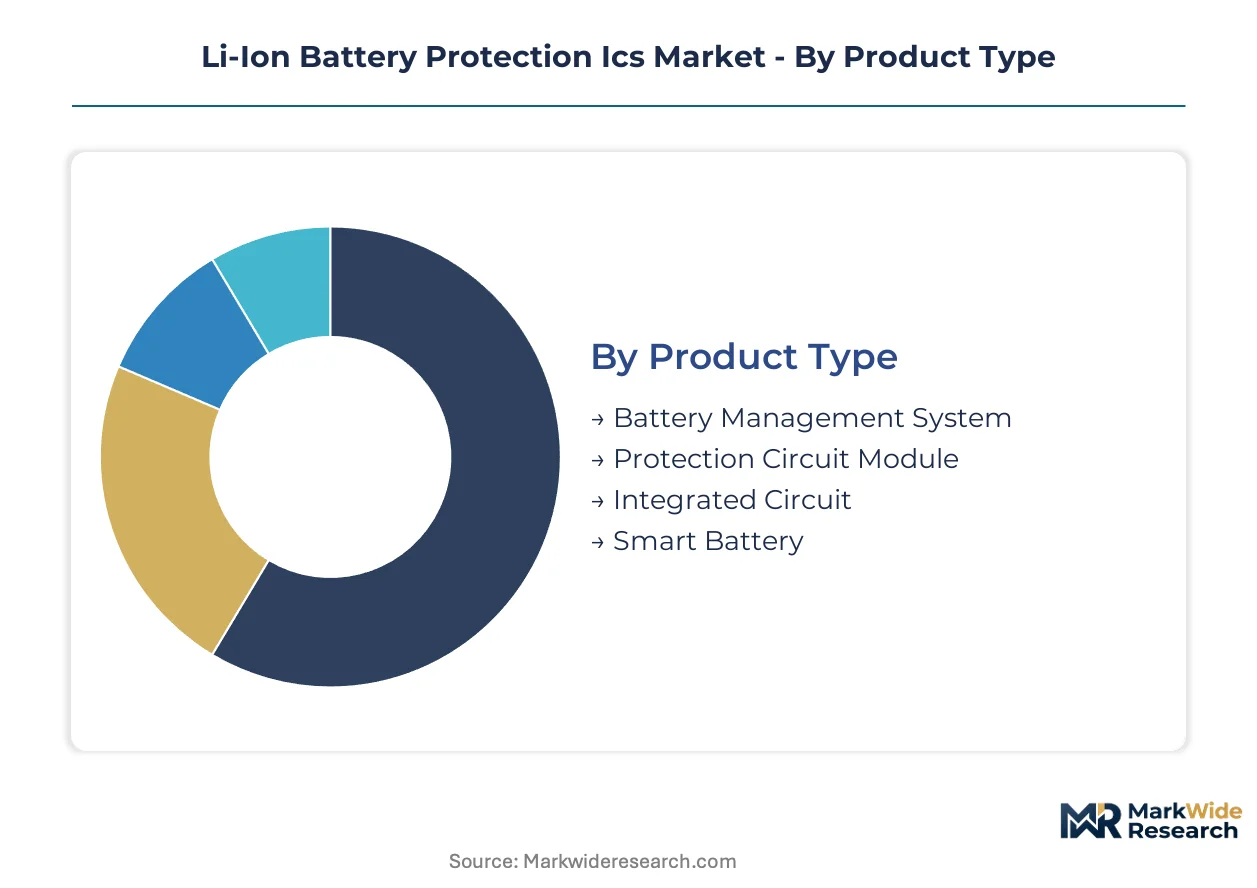
Protection IC segmentation reflects divergent service intensity across end-use applications. Automotive and industrial deployments demand extensive field calibration and firmware updates, while consumer electronics prioritize plug-and-play replacement economics.
Product Type:
After-sales service intensity varies sharply across product categories, with smart battery platforms requiring ongoing authentication management and cloud connectivity support that Protection Circuit Modules never need.
- Protection Circuit Module:Discrete analog assemblies combining voltage comparators, MOSFET drivers, and thermal fuses in compact PCB layouts. Demand concentrates in Chinese and Vietnamese contract manufacturers supplying smartphone and notebook OEMs, where cost-per-unit sensitivity limits margin expansion despite massive volumes.
- Smart Battery:Firmware-configurable platforms embedding authentication cryptography, coulomb counting, and telemetry interfaces for cycle-life optimization. Electric vehicle manufacturers in Germany and South Korea are specifying these for warranty-tracked battery packs, creating recurring revenue through over-the-air threshold updates.
- Battery Management System:Multi-cell architectures integrating protection functions with cell balancing and state-of-charge estimation.
- Integrated Circuit:Monolithic silicon solutions collapsing protection and sensing into single-die implementations for space-constrained wearables.
Protection Circuit Module holds the largest share; momentum sits with Smart Battery.
End User:
Cost tier stratification separates military-grade automotive qualification from consumer electronics commodity pricing, with industrial and renewable energy occupying intermediate positions defined by operational lifetime requirements.
- Automotive:ASIL-D compliant devices managing 100+ series cell configurations with redundant voltage monitoring and hardware fuse control. OEMs in Japan and South Korea are scaling orders for 800V silicon-anode compatible platforms as GB standards and EU Battery Regulation tighten thermal runaway test requirements.
- Consumer Electronics:High-volume, cost-optimized protection for single-cell and 2S-3S packs in smartphones, tablets, and wearables. Chinese EMS providers dominate procurement, though North American and European OEMs are specifying authentication-locked modules to block aftermarket cell substitution.
- Industrial:Extended temperature range devices for power tools, medical equipment, and material handling systems.
- Renewable Energy:Grid-scale storage protection managing thousands of cells in containerized battery systems.
Automotive commands premium pricing tiers; Consumer Electronics delivers volume scale.
Technology:
Application maturity determines technology selection, with established consumer electronics favoring proven analog approaches while emerging automotive architectures demand digital configurability.
- Mixed-signal:Combines precision analog front-ends with embedded state-machine control and firmware programmability. Foundries in South Korea and Japan are prioritizing automotive-qualified mixed-signal capacity as electric vehicle OEMs redesign detection algorithms for silicon-anode chemistries.
- Analog:Discrete comparator-based architectures with fixed thresholds and microsecond response times. Retains cost advantages in high-volume consumer electronics where detection accuracy within millivolt tolerances satisfies safety requirements without digital overhead.
- Digital:Software-defined protection with ADC-based sensing and processor-managed fault response.
- Wireless:RF-enabled monitoring eliminating wired communication harnesses in complex pack geometries.
Mixed-signal leads design activity; Analog retains cost-sensitive strongholds.
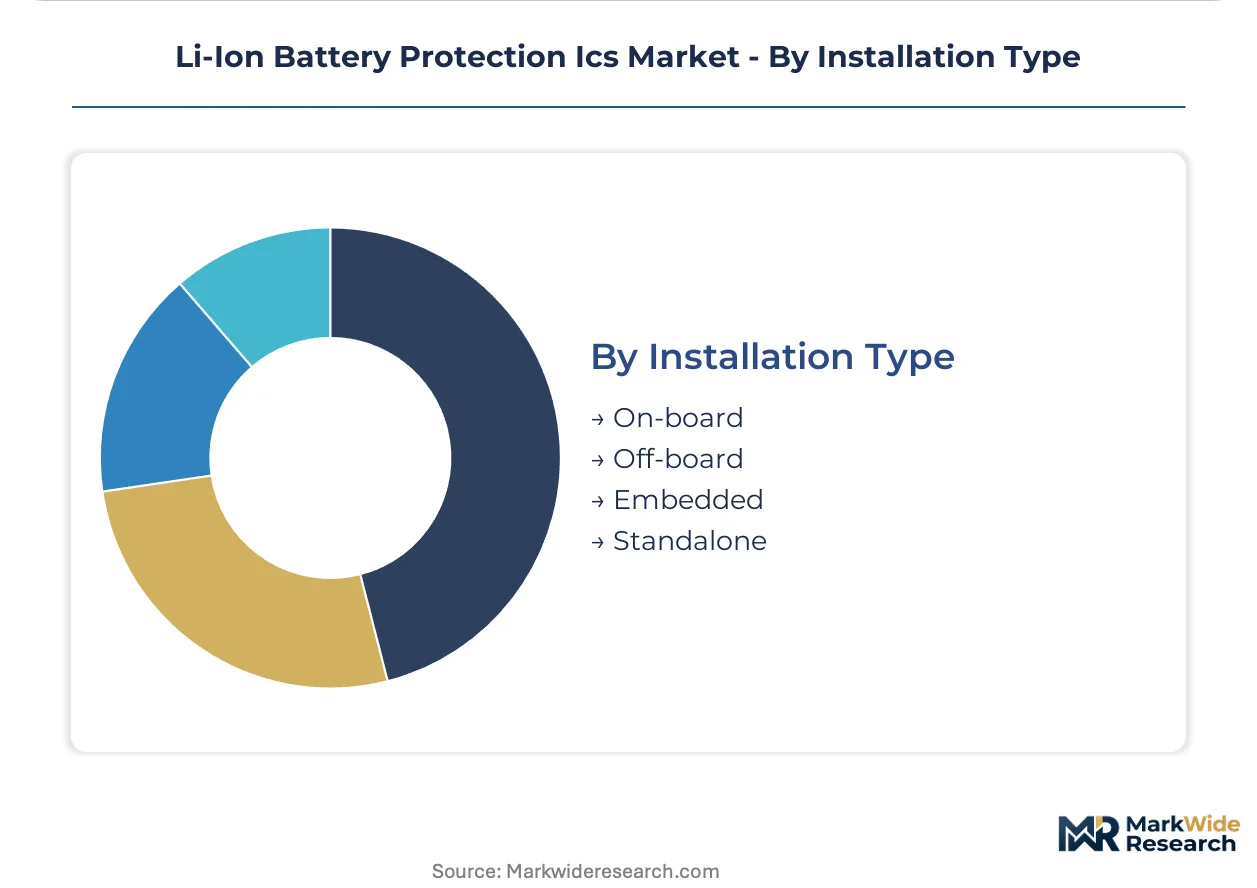
Installation Type:
Supply concentration in East Asian manufacturing clusters favors on-board and embedded configurations that integrate directly with battery management system PCBs fabricated in South Korean and Japanese facilities.
- On-board:Protection ICs mounted directly to battery pack PCBs alongside cells and passive components. Dominates automotive and industrial applications where vibration resistance and thermal coupling to cell surfaces are mandatory.
- Embedded:Die-level integration within battery management system ASICs or powertrain control modules. Tier-one semiconductor IDMs in Japan are embedding protection functions into broader system-on-chip designs to reduce PCB area in 400V and 800V electric vehicle platforms.
- Off-board:External monitoring units connected through wiring harnesses.
- Standalone:Discrete protection modules serving aftermarket replacement and repair markets.
On-board captures manufacturing integration trends; Embedded is climbing the fastest as system consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and South Korean protection IC suppliers dominate export flows into German and Chinese automotive battery pack assembly lines, with contract manufacturers in Vietnam and Mexico serving as secondary procurement channels for North American consumer electronics brands.
China
Domestic electric vehicle OEMs are scaling orders for multi-cell protection architectures as NIO, BYD, and CATL expand silicon-anode cell production. SAMR's updated GB standards mandate redundant voltage monitoring and thermal runaway propagation testing that exceed previous certification baselines. Shenzhen and Dongguan manufacturing clusters host tier-one semiconductor foundries supplying integrated device manufacturers with automotive-qualified mixed-signal capacity.
Germany
BMW and Volkswagen are specifying ASIL-D compliant protection platforms for 800V battery architectures entering production. The EU Battery Regulation's due diligence requirements force suppliers to document material sourcing and recyclability across supply chains. Stuttgart and Munich anchor the country's automotive electronics engineering concentration, with local system houses integrating protection ICs into battery management system designs.
United States
Tesla and Rivian are driving demand for firmware-configurable protection platforms capable of over-the-air threshold updates. The FAA and NHTSA enforce redundant protection circuitry mandates for aviation and electric vehicle applications that elevate IC complexity. Austin and Detroit metro areas concentrate battery pack engineering talent, with Texas emerging as a secondary hub for power electronics design.
Japan
Automotive-qualified ASIL-D devices from Renesas and other domestic suppliers serve Toyota and Honda electrification programs. METI's battery supply chain security initiatives prioritize domestic protection IC fabrication capacity for strategic industries. Tokyo and Nagoya manufacturing corridors retain captive mixed-signal foundry capacity serving tier-one integrated device manufacturers.
South Korea
Hyundai and Samsung SDI are procuring smart battery platforms with embedded authentication cryptography for warranty-tracked packs. MFDS-aligned safety standards for medical and industrial battery systems create parallel demand for precision voltage monitoring solutions. Seoul and Suwon semiconductor clusters provide automotive-qualified process nodes for protection IC designs targeting silicon-anode chemistries.
Li-Ion Battery Protection Ics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered certification grades. The market structure concentrates around analog-mixed signal semiconductor firms with captive automotive qualification capabilities, while fragmented specialists serve cost-optimized consumer electronics segments. Three archetypes dominate: integrated device manufacturers with foundry control, fabless design houses licensing to contract manufacturers, and captive suppliers serving affiliated battery cell producers. M&A activity targets firmware-configurable platform capabilities, with capacity expansion concentrated in South Korean and Japanese automotive-qualified process nodes.
Among Japan-based integrated device manufacturers, MinebeaMitsumi, Seiko Instruments, and Ricoh exemplify the captive supplier archetype, leveraging domestic foundry relationships to serve affiliated battery cell and precision component networks. These firms occupy positions where vertical integration into sensor and micro-motor product lines creates bundled procurement advantages for smartphone and notebook OEMs. Texas Instruments and ON Semiconductor represent the channel-controlling tier, with the former anchoring precision voltage monitoring solutions and the latter competing aggressively in industrial and power tool segments through cost-optimized protection platforms. Renesas Electronics sits within the automotive-specialist tier, its ASIL-D compliant devices serving tier-one OEMs requiring functional safety certification for high-cell-count electric vehicle packs.
| Leading Market Players |
|---|
| MinebeaMitsumi |
| ABLIC Inc |
| Texas Instruments |
| Nisshinbo Micro Devices |
| Seiko Instruments |
| Renesas Electronics |
| Analog Devices |
| Ricoh |
| ON Semiconductor |
| Others |
Supply & Pricing Matrix
Wafer fabrication concentration in South Korean and Japanese automotive-qualified mixed-signal foundries concentrates margin capture upstream, with tier-one integrated device manufacturers commanding premium pricing for ASIL-D certified devices while contract manufacturers absorb cost pressure in high-volume consumer electronics procurement.
Pricing Analysis
Next-generation silicon-anode compatible protection platforms command substantial premiums over legacy analog architectures, while pure analog solutions retain cost advantages in smartphone and notebook battery packs. Pricing stratifies across ASIL-D automotive certification tiers, standard industrial qualification levels, and economy consumer electronics grades, with automotive OEMs showing least price sensitivity due to warranty and liability exposure. Cost compression in consumer electronics tiers is intensifying because Chinese EMS providers dominate procurement and limit margin expansion despite massive volumes.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for protection IC vendors serving North American automotive OEMs. Manufacturing draws from South Korean foundry capacity, Japanese analog-mixed signal fabrication, and Taiwanese specialty substrate suppliers, with 300mm wafer supply resting on concentrated sources in East Asia. Single-source vulnerability in automotive-grade process nodes threatens qualification timelines for new protection IC designs. Distribution runs through tier-one semiconductor distributors serving integrated device manufacturers and direct procurement channels for affiliated battery cell producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
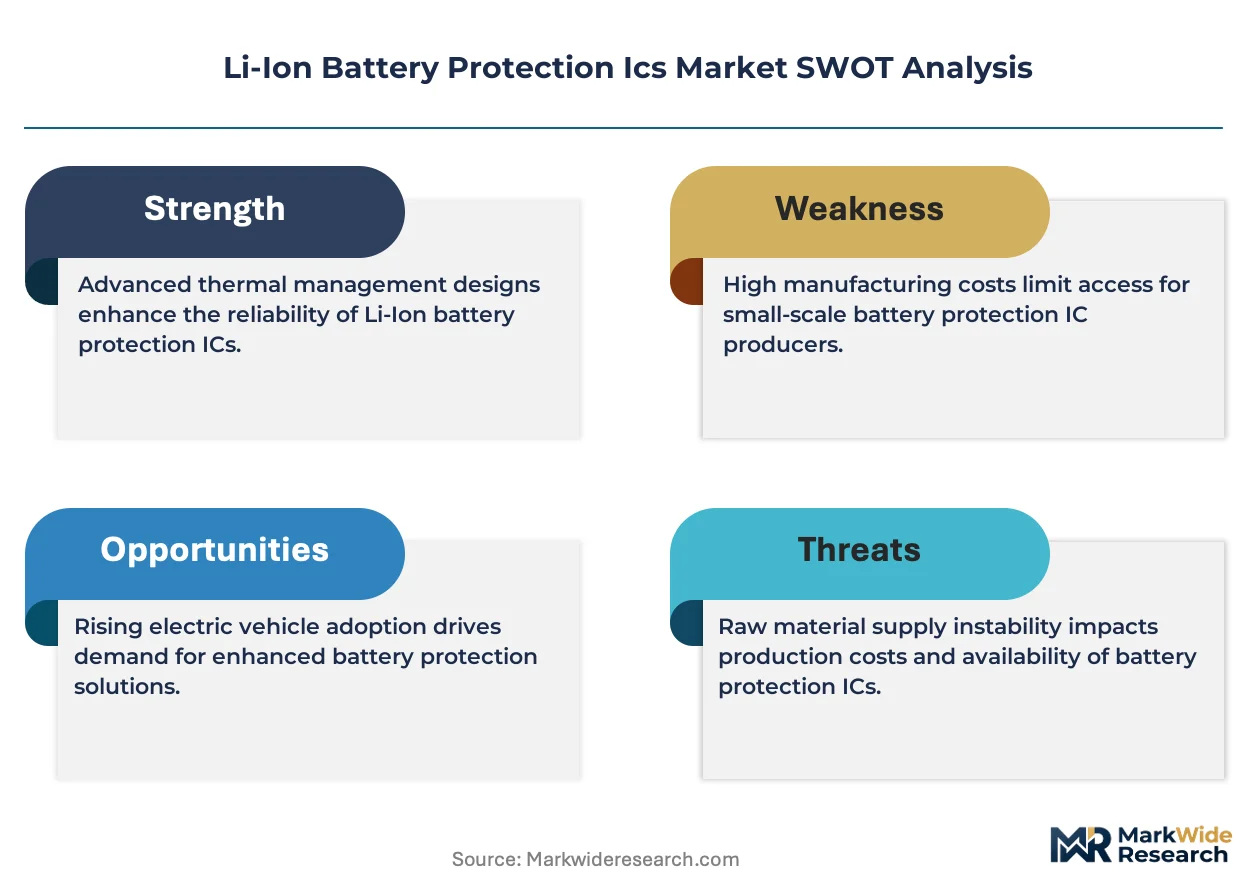
Silicon-carbide MOSFET substitution in battery disconnect circuits presents a credible displacement threat that incumbent protection IC suppliers must navigate through firmware-configurable platform differentiation.
For Market Incumbents: Insulate automotive revenue streams by deepening captive foundry relationships in South Korea and Japan to secure ASIL-D qualified capacity, while accelerating R&D investment in embedded authentication cryptography to block aftermarket cell substitution in consumer electronics channels. The priority lever sits with mixed-signal design talent retention, as firmware-configurable architectures require scarce analog-embedded systems expertise concentrated at a handful of semiconductor firms.
For New Entrants and Emerging Players: India's domestic battery gigafactory construction under the PLI scheme represents the most penetrable geographic white space, with BIS-standard qualification requirements creating barrier-to-entry advantages for early movers. Target industrial power tool and medical equipment segments with extended temperature range devices, where procurement patterns favor specialized technical support over volume scale. A localized application engineering presence in Mumbai and Bangalore accelerates design-win capture.
For Investors and Strategic Acquirers: Capital is best deployed toward fabless design houses with proven firmware-configurable protection platforms and existing automotive qualification relationships, as consolidation activity targets capabilities that compress time-to-revenue for silicon-anode compatible architectures. Long-term viability hinges on sustained electrification capital expenditure across OEM battery pack engineering. The signal to watch is ASIL-D certification cycle compression, which would indicate qualification friction easing and competitive entry accelerating.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Qualification Investment | ASIL-D certification locks in multi-year supplier relationships with German and South Korean OEMs. |
| Firmware-Configurable Platform Development | Embedded state-machine control enables over-the-air threshold updates for silicon-anode chemistries. |
| East Asian Foundry Capacity Expansion | South Korean and Japanese mixed-signal process nodes anchor automotive-qualified supply security. |
| Authentication Cryptography Integration | Secure element embedding blocks aftermarket cell substitution in North American consumer channels. |
| India Technical Support Localization | BIS-standard qualification expertise captures domestic gigafactory protection IC procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC semiconductor filings, customs trade data, and automotive OEM technical specifications. Semiconductor design executives, battery pack procurement managers at Tier 1 suppliers, and foundry operations directors provided qualitative input across South Korea, Japan, Germany, and the United States. Bottom-up triangulation of unit demand by end-use application converged with top-down validation against analog-mixed signal semiconductor revenue disclosures.
Forecast inputs include cell chemistry transition timelines, automotive platform voltage architecture roadmaps, and regulatory certification requirement evolution across the projection horizon. Segmentation modeling incorporates product type, end-use industry, technology generation, and geographic manufacturing cluster. CAGRs derive from fitted growth curves against observed adoption patterns in prior technology transitions, with electric vehicle production schedules and consumer electronics replacement cycles serving as demand anchors.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese foundries or accelerated silicon-carbide MOSFET adoption by automotive OEMs would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Bluetooth IC Market
IC (Integrated Circuits)
Global Application Specific Computer Analog IC Market
IC (Integrated Circuits)
Europe Analog IC Market
IC (Integrated Circuits)
Global Computer and Peripherals Special Purpose Logic Ic Market
IC (Integrated Circuits)
PFC Control IC Market
IC (Integrated Circuits)
Memory Integrated Circuits (IC) Market
IC (Integrated Circuits)
Application Specific Analog IC Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
Taiwan Integrated Circuits Market
IC (Integrated Circuits)
United States Analog Integrated Circuits Market
IC (Integrated Circuits)
RFID Reader IC Market
IC (Integrated Circuits)
Ultra Large Scale Ics Market
IC (Integrated Circuits)
United States Integrated Circuits Market
IC (Integrated Circuits)
Touch Controller IC Market
IC (Integrated Circuits)
Audio Power Amplifier IC Market