
 Global Semiconductor Timing IC Market | 2026-2036
Global Semiconductor Timing IC Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Timing IC Market Outlook
Silicon germanium is consolidating its position over legacy quartz in high-frequency timing architectures. Texas Instruments leverages integrated manufacturing to sustain cost advantages across automotive-grade oscillator portfolios. Analog Devices anchors its position through precision MEMS resonator technology leadership. Renesas Electronics competes on mixed-signal integration density for industrial control systems.
Semiconductor timing integrated circuits generate, distribute, and synchronize clock signals across electronic systems, typically operating at frequencies from kilohertz to tens of gigahertz with phase noise specifications below -150 dBc per hertz at offset. These devices enable deterministic data transfer in synchronous digital architectures spanning telecommunications infrastructure, automotive ADAS modules, and server motherboards. Digital timing products now capture expanding margin pools as software-defined clock trees replace fixed-function analog alternatives in 5G baseband units. CMOS technology dominates volume production while BiCMOS variants command premium positioning in microwave instrumentation and radar subsystems. Automotive applications represent the fastest-expanding demand vector as domain controller architectures multiply clock domains per vehicle platform.
FDA oversight of medical device timing accuracy, FCC electromagnetic compatibility mandates for telecommunications equipment, and EU REACH material restrictions on crystal oscillator packaging collectively elevate compliance costs for cross-border suppliers. Japan's METI semiconductor resilience programs and China's GB standards for domestic 5G infrastructure create divergent certification pathways that fragment product qualification cycles. Stakeholders must monitor how export control harmonization between the US Bureau of Industry and Security and EU dual-use regulations reshapes foundry access for advanced node timing devices.
Market Dynamics
Domain controller proliferation in automotive electronics is fragmenting clock tree architectures, multiplying discrete timing components per vehicle while compressing synchronization tolerances to sub-nanosecond thresholds.
Growth Catalysts
- EU Chips Act capacity subsidies:Foundry expansion across Dresden and Leuven is pulling precision timing device demand into European wafer fabrication ecosystems.
- 5G-Advanced base station deployment:Massive MIMO arrays require phase-synchronized clock distribution, expanding orders for low-jitter PLLs in telecommunications infrastructure.
- Silicon germanium process maturation:SiGe BiCMOS nodes now achieve quartz-comparable phase noise at fractional power consumption, accelerating displacement in microwave instrumentation.
Market Restraints
- AT-cut crystal supply concentration:Synthetic quartz blank production clusters in Japanese and Chinese facilities, exposing oscillator vendors to single-source geographic risk.
- EU REACH material restrictions:Cadmium and lead exemptions in hermetic packaging face sunset timelines, forcing qualification of alternative ceramic-sealing processes.
- MEMS resonator temperature drift:Silicon-based timing elements exhibit frequency instability beyond industrial temperature ranges, limiting penetration in aerospace and defense applications.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Domestic mobile and automotive module assembly is creating captive demand for locally sourced clock generators and buffers.
- Software-defined clock tree integration:Digital PLLs with field-programmable loop parameters enable single-SKU inventory strategies across 5G and automotive variants.
- Optical clock distribution in data centers:Co-packaged photonics architectures require picosecond-accurate timing references, opening premium positioning for optical-electrical conversion specialists.
Industry Challenges
- Phase noise metrology expertise scarcity:Characterization of sub-100 femtosecond jitter requires specialized RF engineering talent concentrated in legacy telecommunications hubs.
- Automotive AEC-Q100 qualification timelines:Extended temperature cycling and EMC testing compress product launch windows against accelerating vehicle platform cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Timing IC Market |
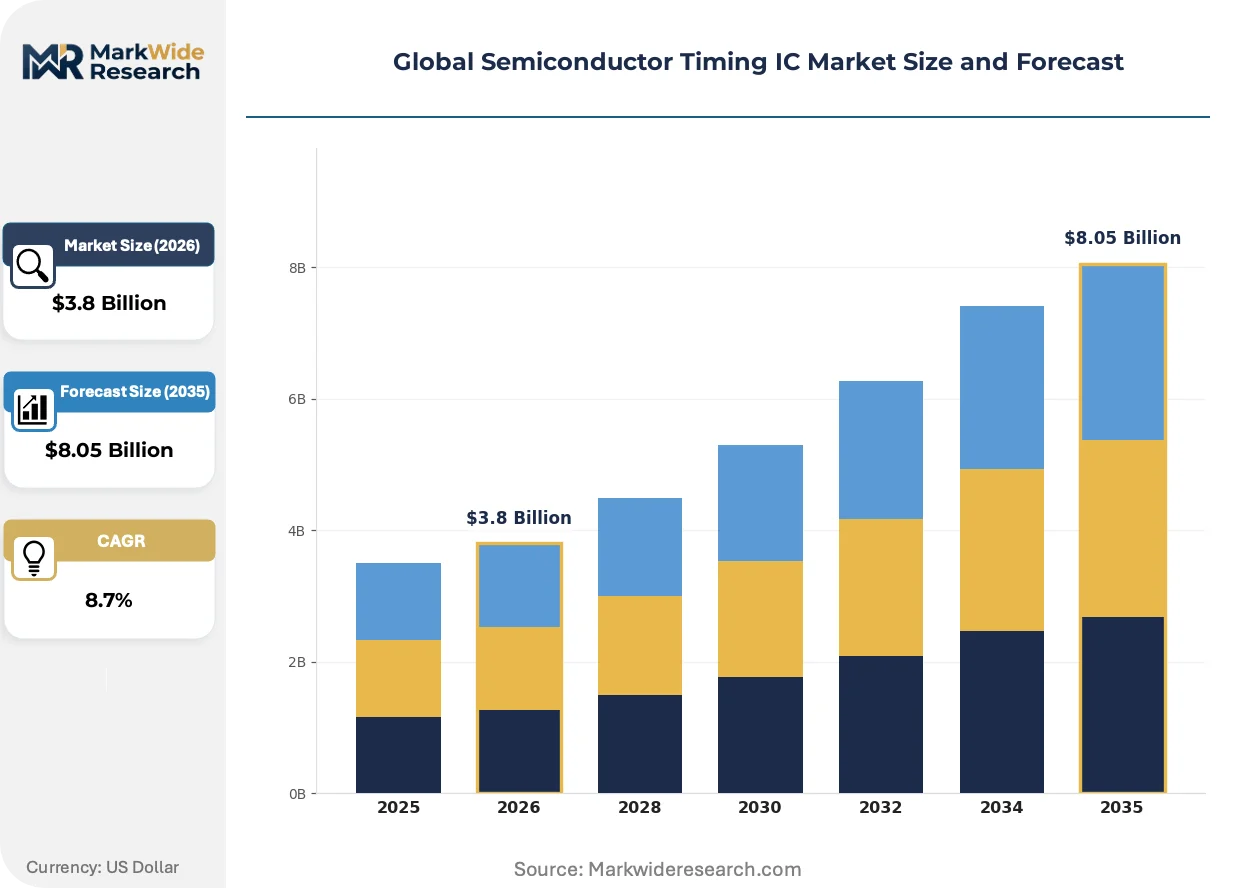
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Microcontroller, High-Speed Application: Consumer Electronics, Telecommunications, Automotive, Industrial Control End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Design Houses Technology: CMOS, BiCMOS, Hybrid, Others |
| Companies Covered | Texas Instruments Inc., Analog Devices, Inc., Renesas Electronics Corporation, Microchip Technology Inc., NXP Semiconductors, Infineon Technologies AG, Silicon Laboratories, SiTime Corporation, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Timing IC Market Strategic Shifts
Digital timing architectures are displacing fixed-function analog hierarchies, compressing bill-of-materials counts while enabling field-upgradable synchronization parameters through software-defined interfaces.
MEMS-based oscillators is modularizing frequency generation across automotive and industrial portfolios. Tier-1 module suppliers in Germany and Japan are qualifying silicon resonators for engine control and transmission systems. This technology is modularizing what were previously discrete crystal-plus-oscillator assemblies into monolithic CMOS-compatible die, collapsing board area requirements and enabling chip-scale packaging strategies.
Japan's METI semiconductor resilience programs are redirecting timing IC procurement toward domestic and allied-nation fabrication. Subsidized capacity expansion at legacy nodes in Hokkaido and Kyushu is pulling automotive-grade oscillator production away from concentrated foundry geographies. Automotive suppliers with Japan-certified supply chains are securing preferential allocation during capacity constraints.
Consolidated vendor-managed inventory programs are compressing distributor intermediation in high-volume telecommunications procurement. Original equipment manufacturers in Taiwan and South Korea now contract directly with timing IC specialists for 5G infrastructure builds, bypassing traditional component distribution channels. Direct engagement enables customized phase noise specifications and lot-traceability requirements that standard distributor SKUs cannot accommodate.
Global Semiconductor Timing IC Market Segmentation
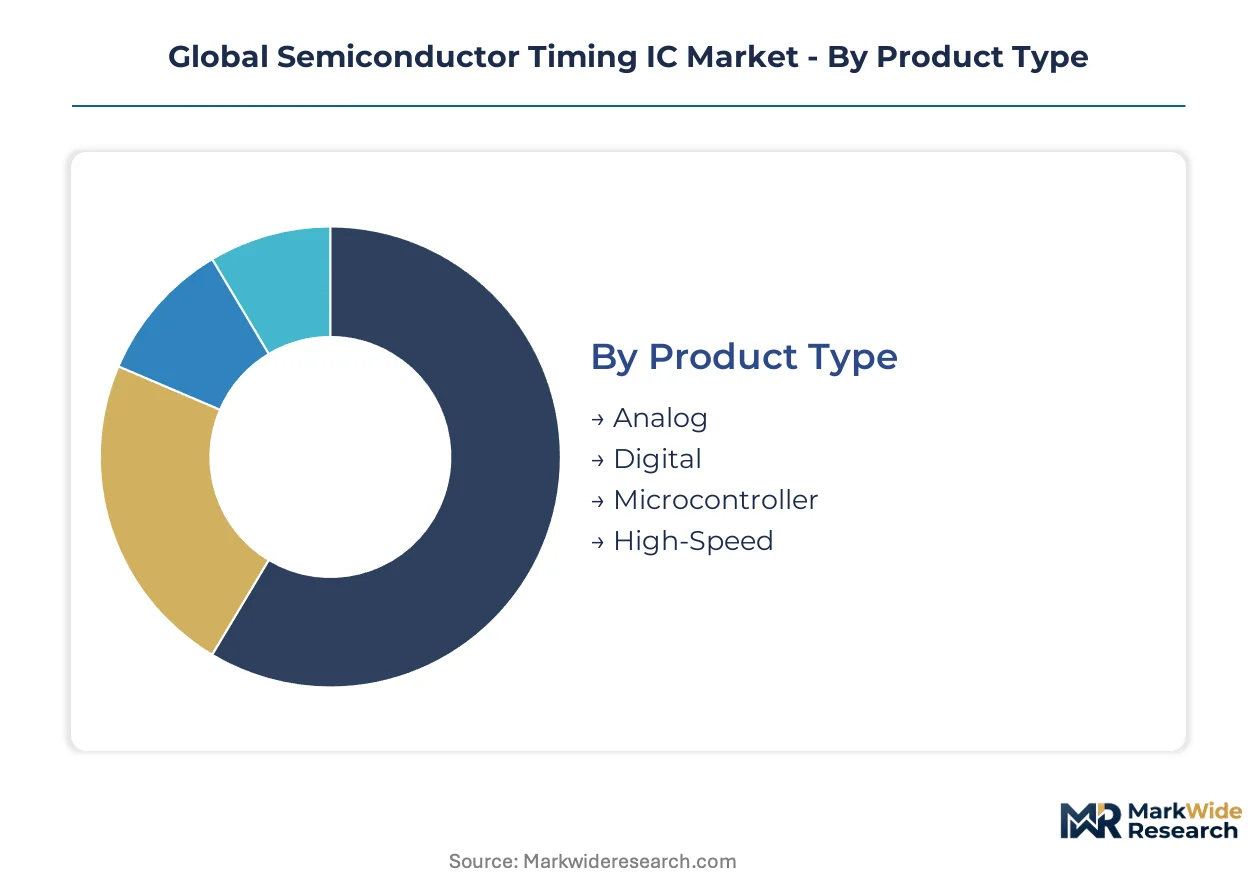
Timing IC architectures fragment sharply between standalone discrete components and deeply embedded system-on-chip implementations. Each segmentation dimension reveals distinct margin structures, qualification barriers, and procurement patterns that determine competitive positioning.
Product Type:
Analog and digital segments anchor opposite ends of the integration spectrum, with hybrid architectures occupying the middle ground where flexibility commands premium pricing.
- Analog:Fixed-function oscillator circuits deliver sub-picosecond jitter performance through precision voltage-controlled architectures. Telecom infrastructure in Germany and Japan drives procurement concentration, constrained by AT-cut crystal supply bottlenecks from Japanese blank manufacturers.
- Digital:Software-configurable PLL architectures enable field-programmable loop parameters and single-SKU inventory strategies. Data center operators in Taiwan and South Korea are expanding direct procurement of these devices for 5G-Advanced baseband units.
- Microcontroller:Integrated timing subsystems embedded within MCU die reduce board-level component counts for cost-sensitive consumer modules.
- High-Speed:Multi-gigahertz clock distribution circuits serve optical-electrical conversion in co-packaged photonics architectures.
Analog leads volumes today; digital is gaining share fastest.
Application:
End-use differentiation separates consumer-grade cost optimization from automotive reliability mandates and industrial longevity requirements.
- Automotive:Domain controller proliferation multiplies clock domains per vehicle platform while compressing synchronization tolerances to sub-nanosecond thresholds. Tier-1 module suppliers in Germany and Japan are qualifying MEMS resonators for engine control systems under METI resilience programs.
- Telecommunications:Massive MIMO arrays require phase-synchronized clock distribution across 5G-Advanced base stations. FCC electromagnetic compatibility mandates and EU REACH material restrictions elevate compliance costs for cross-border equipment vendors.
- Consumer Electronics:Mobile device assembly under India's PLI scheme creates captive demand for locally sourced clock generators and buffers.
- Industrial Control:Extended temperature cycling requirements and EMC testing compress product launch windows against accelerating equipment replacement cycles.
Telecommunications dominates revenue contribution; automotive shows the steepest expansion trajectory.
End User:
Procurement authority concentrates differently across direct OEM engagement, delegated Tier-1 sourcing, and fragmented aftermarket channels.
- OEMs:Original equipment manufacturers in Taiwan and South Korea now contract directly with timing IC specialists, bypassing traditional distribution channels for customized phase noise specifications and lot-traceability requirements.
- Tier-1 Suppliers:German and Japanese automotive module suppliers control oscillator qualification for vehicle platforms, creating captive demand pools for AEC-Q100 certified devices.
- Aftermarket Providers:Repair and replacement channels serve legacy telecommunications infrastructure with extended lifecycle support requirements.
- Design Houses:Fabless semiconductor specialists specify timing references for custom ASIC integration in aerospace and defense applications.
Tier-1 suppliers anchor current procurement volumes; OEM direct engagement is expanding most quickly.
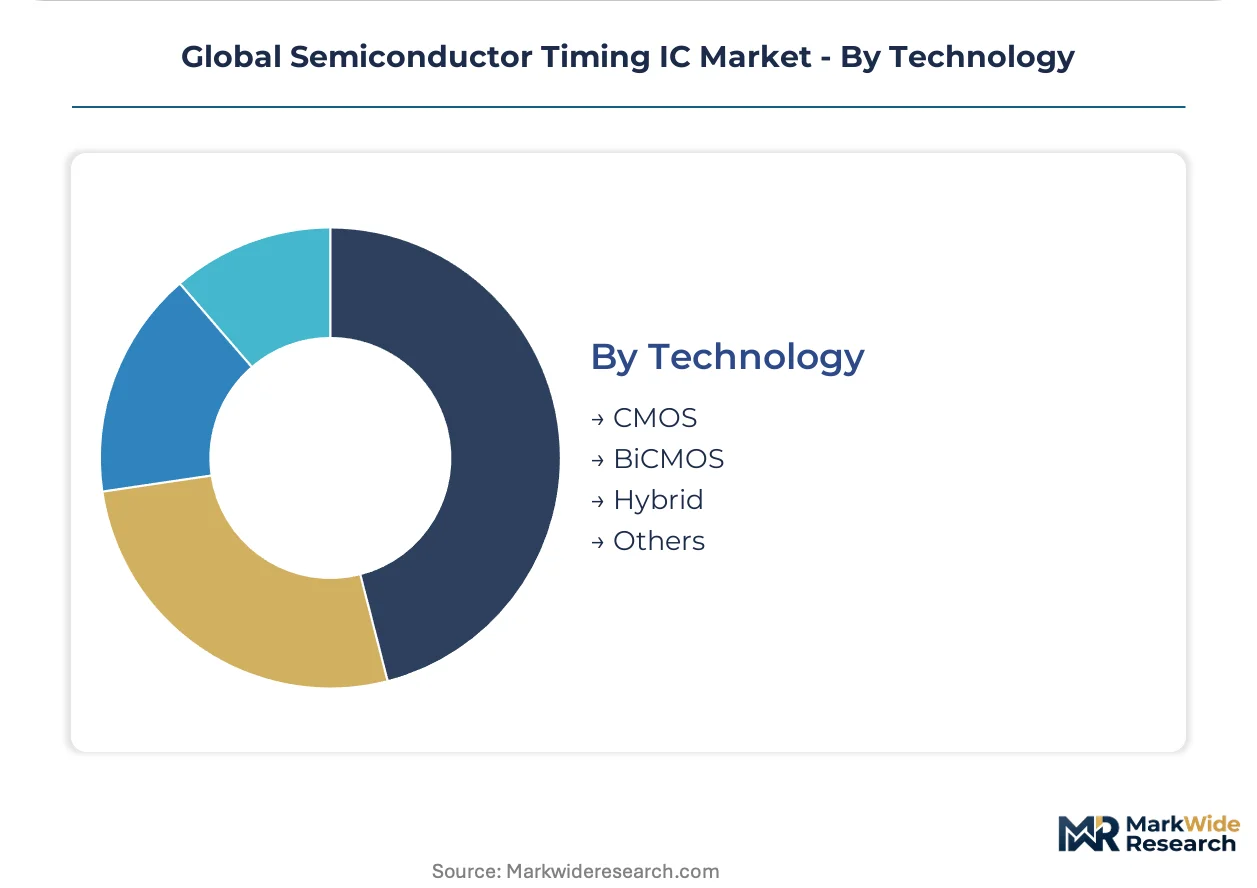
Technology:
Process node selection trades off power efficiency, frequency capability, and integration density against foundry access constraints.
- CMOS:Dominates volume production through mature node availability across Taiwan's foundry ecosystem. Digital timing products capture expanding margin pools as software-defined clock trees displace fixed-function alternatives.
- BiCMOS:Silicon germanium variants command premium positioning in microwave instrumentation and radar subsystems, achieving quartz-comparable phase noise at fractional power consumption.
- Hybrid:Multi-process integration combines CMOS logic with specialized analog front-ends for instrumentation applications requiring wide tuning range.
- Others:Emerging resonator technologies including MEMS and optical references occupy niche positioning in temperature-compensated applications.
CMOS leads production volumes today; BiCMOS is climbing the fastest in revenue per unit terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's foundry ecosystem concentrates precision timing IC fabrication, pulling design activity and procurement authority toward Hsinchu Science Park. Dresden's EU Chips Act subsidies are redirecting automotive-grade oscillator demand toward European wafer capacity. Japan's METI resilience programs fragment supply chains across allied-nation fabrication networks.
United States
Data center operators in Northern Virginia and Silicon Valley expand direct procurement of software-defined clock generators for AI training clusters. FCC electromagnetic compatibility mandates elevate compliance costs for telecommunications equipment crossing into Canadian and Mexican markets. Austin's semiconductor corridor anchors mixed-signal design houses specifying timing references for defense and aerospace applications.
Germany
Automotive domain controller proliferation in Stuttgart and Munich multiplies discrete timing components per vehicle platform while compressing synchronization tolerances. EU REACH material restrictions on cadmium and lead in hermetic packaging force qualification of alternative ceramic-sealing processes. Dresden's EU Chips Act subsidized fab expansion is pulling precision timing device demand into European wafer fabrication ecosystems.
Japan
Synthetic quartz blank production clusters in Yamanashi and Toyama prefectures expose oscillator vendors to single-source geographic risk in AT-cut crystal supply. METI semiconductor resilience programs redirect timing IC procurement toward domestic and allied-nation fabrication with subsidized capacity at legacy nodes in Hokkaido and Kyushu. Nagoya's automotive supplier corridor controls AEC-Q100 oscillator qualification for vehicle platforms.
China
GB standards for domestic 5G infrastructure create divergent certification pathways that fragment product qualification cycles for timing devices. MIIT semiconductor self-sufficiency targets accelerate local sourcing mandates for base station clock distribution circuits. Shanghai's Pudong Zhangjiang Hi-Tech Park concentrates fabless design houses developing MEMS resonator alternatives to Japanese quartz.
South Korea
Memory and logic foundry giants in Pyeongtaek and Hwaseong integrate precision timing subsystems directly into advanced packaging for HBM stacks. Direct OEM engagement with timing IC specialists bypasses traditional distribution channels for customized phase noise specifications. Seoul's telecommunications equipment vendors drive Massive MIMO array deployment requiring phase-synchronized clock distribution.
Global Semiconductor Timing IC Market Competitive Environment
Global majors compete with regional champions across integrated manufacturing versus fabless specialization. The vendor base stratifies into three tiers: IDMs capturing automotive-grade volume through captive fabs, fabless specialists commanding premium positioning in MEMS and optical timing, and diversified analog conglomerates leveraging portfolio breadth. Consolidation pressure intensifies as domain controller proliferation fragments clock tree architectures. Dominant competitive moves include backward integration into resonator materials and strategic partnerships with foundry ecosystems for advanced node access.
Within the diversified analog conglomerate tier, Texas Instruments Inc. and Analog Devices, Inc. exemplify integrated manufacturing strategies that sustain cost advantages across high-reliability portfolios. Renesas Electronics Corporation anchors the automotive-focused archetype through mixed-signal integration density for industrial control systems. These three companies sit within distinct competitive positions: IDM scale, precision technology leadership, and domain-specific integration respectively.
| Leading Market Players |
|---|
| Texas Instruments Inc. |
| Analog Devices, Inc. |
| Renesas Electronics Corporation |
| Microchip Technology Inc. |
| NXP Semiconductors |
| Infineon Technologies AG |
| Silicon Laboratories |
| SiTime Corporation |
| STMicroelectronics |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM consolidation around AEC-Q100 certification mandates is forcing oscillator vendors to absorb extended qualification costs, compressing margins on standard-grade products while enabling premium capture for automotive-qualified devices. This buyer-driven specification tightening feeds directly into foundry allocation strategies and tiered pricing architectures.
Pricing Analysis
Input-cost pass-through from synthetic quartz blank supply constraints in Japan and China is intensifying price pressure on legacy AT-cut crystal oscillators. Three-tier pricing structure across automotive-grade, industrial-grade, and commercial-grade certification levels separates margin pools, with automotive commanding substantial premiums due to temperature cycling requirements. Cost compression in commercial-grade segments runs through aggressive foundry capacity competition in Taiwan. Tier-1 automotive module suppliers exhibit lowest price sensitivity due to platform-lock-in effects, while consumer electronics assemblers under India's PLI scheme drive hardest bargain on clock generator unit costs.
Supply Chain Analysis
Regional distribution centers in Singapore and Rotterdam anchor hub-and-spoke patterns for precision timing device fulfillment, with direct OEM engagement increasingly bypassing traditional distributor channels. Manufacturing concentrates in Taiwan, South Korea, and Japan, with Dresden's EU Chips Act subsidies pulling automotive-grade capacity toward European wafer fabrication. Raw material dependencies center on high-purity synthetic quartz from Yamanashi prefecture, silicon germanium epitaxial wafers, and specialized ceramic packaging substrates. Single-source vulnerability in Japanese quartz blank production exposes oscillator vendors to geographic concentration risk. Distribution runs through consolidated vendor-managed inventory programs for high-volume telecommunications procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with semiconductor content expansion per vehicle platform delivering predictable demand growth irrespective of macroeconomic volatility. Domain controller proliferation ensures multi-year visibility on discrete timing component volume.
For Market Incumbents: Hedge against MEMS resonator displacement by securing captive quartz blank supply through backward integration into Japanese or Chinese synthetic crystal production. Accelerate AEC-Q100 certification pipelines to defend automotive socket positions from emerging SiGe BiCMOS specialists. Foundry capacity reservations at Dresden's EU Chips Act subsidized nodes provide geographic diversification against Taiwan concentration risk.
For New Entrants and Emerging Players: India's PLI scheme electronics assemblers represent an underserved buyer archetype seeking locally sourced clock generators with simplified customs documentation. Target optical-electrical conversion specialists in co-packaged photonics data center architectures as the most penetrable premium segment. Pursue design-in partnerships with fabless timing IC specialists rather than competing directly on foundry access.
For Investors and Strategic Acquirers: Asymmetric upside sits with MEMS resonator technology platforms that can achieve quartz-comparable phase noise performance. Long-term viability over the next decade hinges on displacement economics in automotive and industrial temperature ranges. Watch for inflection signals in aerospace qualification wins, as frequency stability beyond industrial temperature ranges remains the final MEMS penetration barrier.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resonator Materials | Captive quartz blank supply from Japanese manufacturers reduces single-source geographic exposure. |
| Software-Defined Clock Tree Development | Field-programmable PLL parameters enable single-SKU inventory strategies across 5G and automotive variants. |
| EU Chips Act Foundry Partnership | Dresden capacity access secures automotive-grade oscillator allocation preferentially during supply constraints. |
| MEMS Resonator Temperature Stability Investment | Frequency drift reduction beyond industrial ranges opens aerospace and defense qualification pathways. |
| Direct OEM Procurement Channel | Bypassing distributor intermediation captures customized phase noise specifications from Taiwan data center operators. |
Study Parameters
Multiple input streams — primary interviews with timing IC design engineers, automotive Tier-1 procurement directors, and foundry account managers; secondary validation through SEC semiconductor filings, EU Chips Act subsidy disclosures, and METI resilience program documentation; plus customs trade data on quartz blank imports — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured procurement authority shifts, qualification timeline compression, and resonator technology substitution patterns.
Data-stream reconciliation across product type, application, end-user procurement authority, and process technology dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level volume build-ups cross-checked against foundry capacity expansion announcements and equipment vendor order backlogs. Industry-specific forecast inputs included vehicle platform clock domain multiplication rates and 5G-Advanced base station deployment trajectories.
Inputs from automotive supplier associations and telecommunications equipment vendor disclosures were available through the study window; gaps in defense-aerospace procurement data introduce uncertainty bands around high-reliability segment projections. Forecasts reflect documented assumptions regarding foundry yield maturation and regulatory harmonization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Logic IC Market
IC (Integrated Circuits)
Programmable ASIC Market
IC (Integrated Circuits)
Japan Integrated Circuit (IC) Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
Ultra Large Scale Ics Market
IC (Integrated Circuits)
Americas Analog IC Market
IC (Integrated Circuits)
Europe Analog IC Market
IC (Integrated Circuits)
APAC Analog IC Market
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
GNSS IC Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
Global Power Management IC (PMIC) Market
IC (Integrated Circuits)
Americas Logic IC Market
IC (Integrated Circuits)
Battery Fuel Gauge IC Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Lithium Battery Charger Ics Market