
 Application Specific Integrated Circuit Market | 2026-2036
Application Specific Integrated Circuit Market Size, Share, and Industry Trends Forecast 2026-2036
Application Specific Integrated Circuit Market Analysis
Foundry capacity in Taiwan is rebalancing toward advanced-node and automotive-qualified production. Intel Corporation leverages its IDM 2.0 strategy to reclaim manufacturing leadership in the United States. Infineon Technologies AG anchors European supply security through its Dresden fab expansion. Qualcomm Technologies, Inc. specializes in modem-centric ASICs for 5G infrastructure.
An application specific integrated circuit is a non-standard semiconductor device fabricated to perform a dedicated function rather than general-purpose computation, typically manufactured through full-custom or standard-cell design flows with gate lengths at 7nm, 5nm, or mature nodes above 28nm for cost-sensitive applications. Its primary purpose is to optimize power efficiency, performance, and unit economics in high-volume end products. Mixed-signal ASICs command premium margins by integrating analog sensor interfaces with digital processing blocks on single die. Gate Array technology retains share in industrial control systems where design flexibility outweighs die-area efficiency. Full Custom designs dominate telecommunications infrastructure where power and latency specifications are non-negotiable.
The FDA regulates ASICs embedded in medical devices through 21 CFR Part 820 quality system requirements, while the FCC governs radio-frequency ASIC emissions under Part 15 and Part 18 rules in the United States. The EU AI Act and CE marking under the Radio Equipment Directive shape market access for edge-AI and connectivity ASICs in Europe. Stakeholders must monitor foundry allocation priority shifts between consumer electronics and automotive qualification tiers.
Market Dynamics
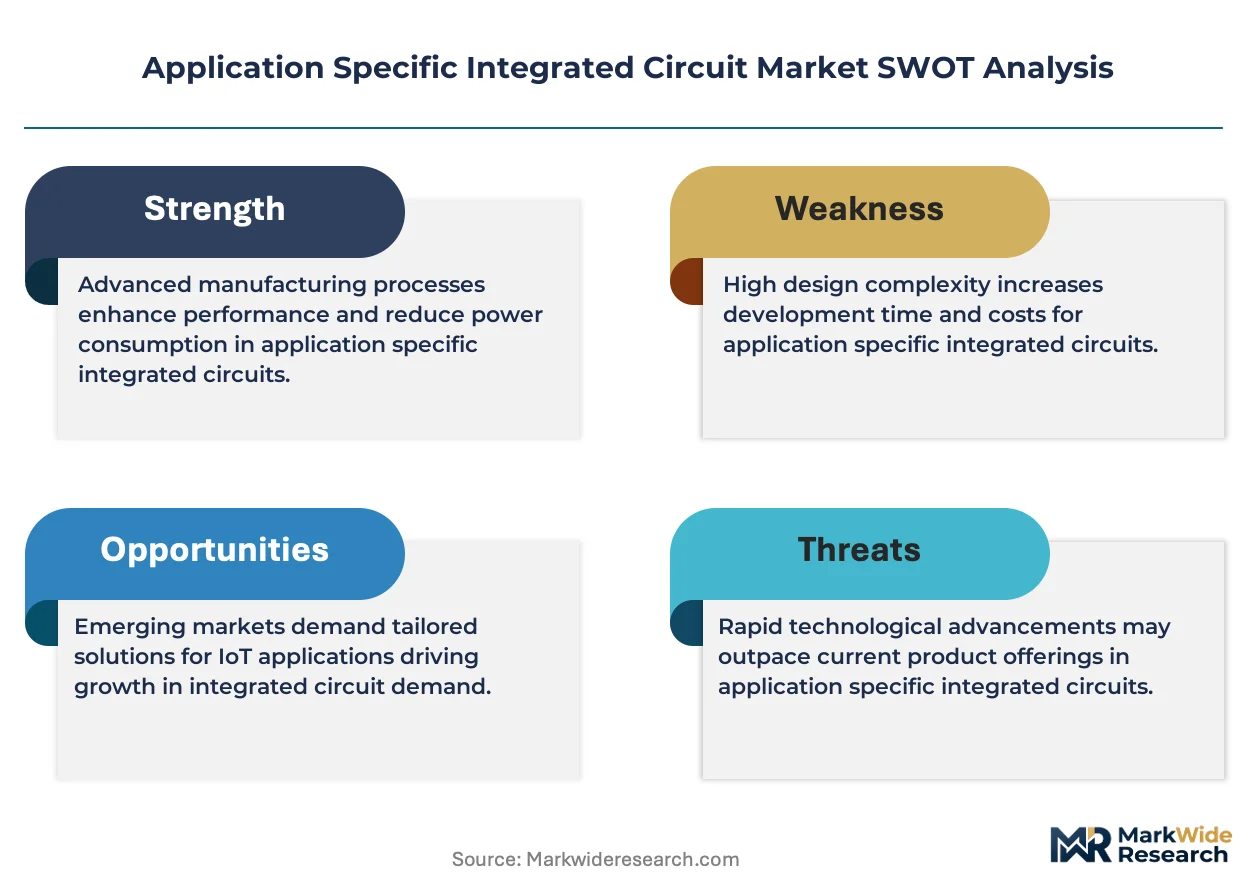
Foundry allocation priority between automotive qualification tiers and consumer electronics is compressing lead times for mixed-signal ASICs while extending advanced-node queues, forcing end-users to pre-book capacity through multi-year offtake agreements.
Growth Catalysts
- EU AI Act:Edge-AI inference mandates in industrial automation are pulling demand for low-power neural network accelerators fabricated at 5nm nodes.
- Electric vehicle powertrain electrification:Battery management systems require automotive-grade ASICs with ISO 26262 functional safety certification.
- Taiwan-South Korea fab expansion:New 28nm and 16nm lines dedicated to automotive qualification are easing supply constraints for sensor interface chips.
Market Restraints
- Photomask cost escalation:Full-custom designs at 3nm require mask sets exceeding twenty million dollars, freezing out mid-volume applications.
- Advanced-node equipment concentration:EUV lithography systems from ASML face allocation bottlenecks extending delivery timelines.
- Silicon carbide substrate substitution:Wide-bandgap power devices are displacing silicon-based ASICs in high-voltage motor control applications.
Strategic Opportunities
- India PLI scheme:Domestic electronics manufacturing incentives are creating captive demand for mature-node ASICs in telecom and automotive.
- Chiplets and 2.5D integration:Disaggregated die architectures enable cost-effective customization without full reticle masks.
- Digital twin integration:Pre-silicon validation platforms are compressing design cycles for medical device ASICs.
Industry Challenges
- Analog-mixed signal design expertise:Talent scarcity in RF and precision ADC design is extending recruitment cycles for fabless teams.
- AEC-Q100 qualification timelines:Automotive temperature-grade testing adds eighteen months to product ramps.
- Legacy node obsolescence management:End-of-life notifications for 180nm and 130nm processes force costly redesigns in industrial control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Application Specific Integrated Circuit Market |
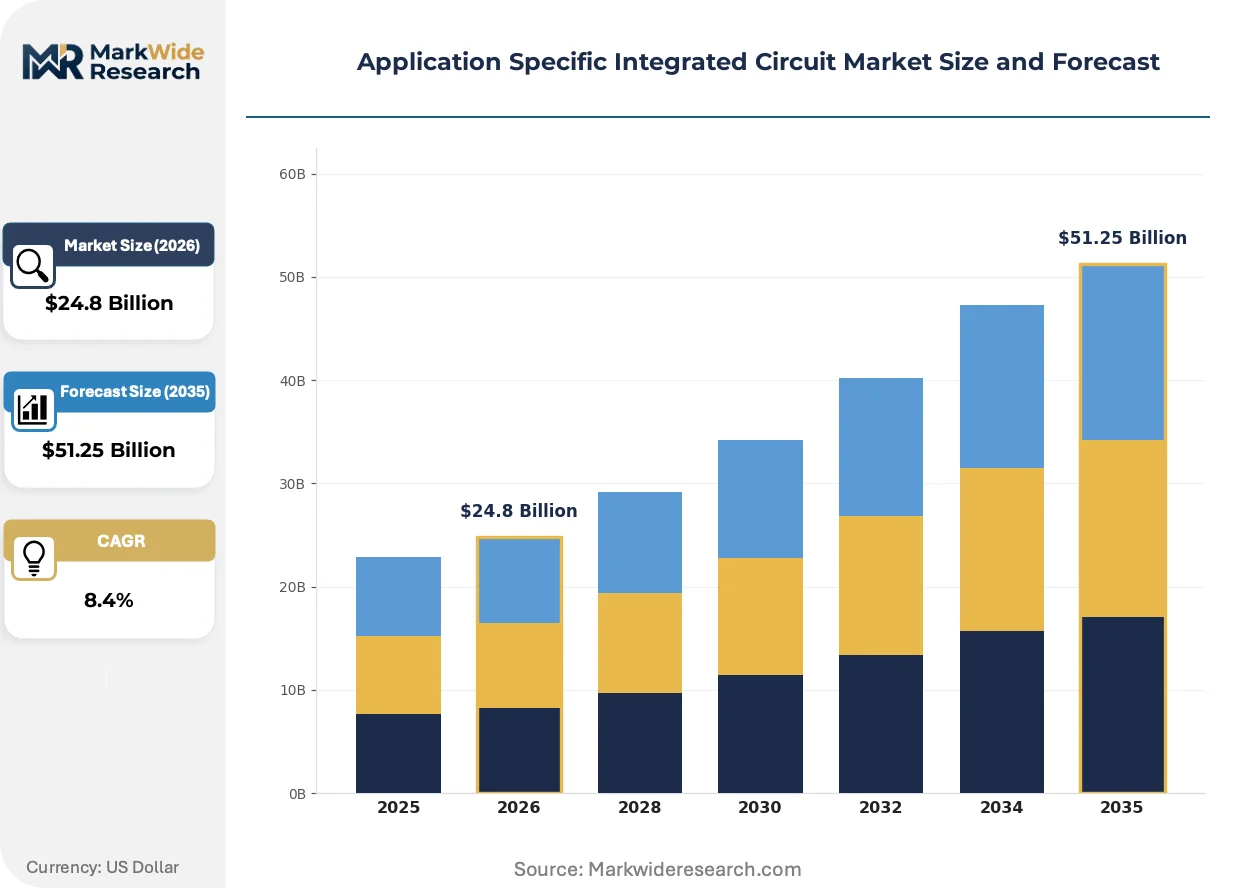
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog ASIC, Digital ASIC, Mixed-signal ASIC, Radio-frequency ASIC End User: Telecommunications, Automotive, Consumer Electronics, Industrial Technology: Standard Cell, Structured ASIC, Full Custom, Gate Array Application: Signal Processing, Data Processing, Control Systems, Networking |
| Companies Covered | Intel Corporation, Infineon Technologies AG, STMicroelectronics, Broadcom Inc, Texas Instruments Inc, Qualcomm Technologies, Inc., Renesas Electronics Corporation, NXP Semiconductors, Marvell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Application Specific Integrated Circuit Market Emerging Trajectories
Silicon photonics co-packaging and neuromorphic computing architectures are rewriting performance benchmarks for AI inference workloads, while regulatory pressure on supply chain transparency is accelerating design tool investments.
Photonic-electronic convergence is rewriting how data centers handle bandwidth bottlenecks. Co-packaged optics ASICs from Ayar Labs and Intel are entering pilot deployment with hyperscalers. This integration is compressing power-per-bit metrics by an order of magnitude compared to pluggable transceivers.
REACH substance restrictions and the EU Green Deal are forcing foundries to document Scope 3 emissions across chemical supply chains. Semiconductor manufacturers must now certify fluorinated gas abatement systems. Memory-intensive ASICs for AI training face heightened scrutiny under emerging carbon footprint labeling requirements.
Hyperscalers are consolidating ASIC procurement through captive design teams rather than merchant silicon vendors. Google, Amazon, and Microsoft now commission custom AI accelerators directly from foundries. This disintermediation is most visible in the United States, where cloud infrastructure capex dominates advanced-node allocation.
Application Specific Integrated Circuit Market Segmentation
ASIC buyers fragment sharply by technical risk tolerance and volume commitment. Telecommunications carriers demand full-custom designs with decade-long supply guarantees, while consumer electronics OEMs prioritize unit economics at mature nodes. Understanding these divergent procurement profiles is essential for foundry capacity planning and design service pricing.
Product Type:
Buyers in this category differentiate primarily by signal domain complexity and integration depth required.
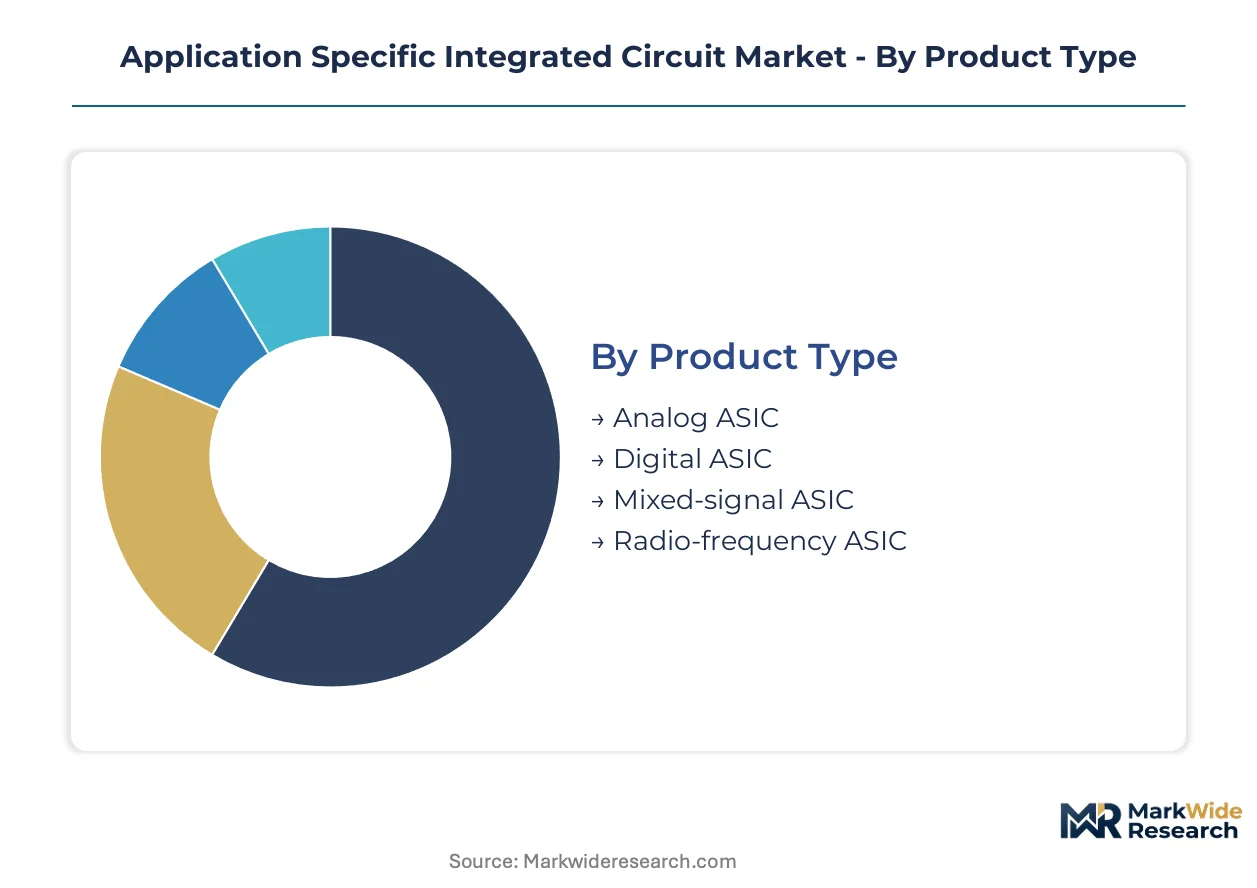
- Mixed-signal ASIC:Integrates precision analog front-ends with digital signal processing on monolithic die. Automotive battery management systems in Germany and sensor fusion modules in Japan's industrial automation sector drive foundry allocation toward AEC-Q100 qualified 40nm and 28nm lines.
- Digital ASIC:Pure logic implementations fabricated at 5nm and 3nm nodes for maximum computational density. Hyperscaler AI accelerators in the United States and 5G baseband processors in South Korea concentrate demand, with mask costs exceeding eight figures at leading-edge nodes.
- Analog ASIC:Discrete power management and sensor interface devices using mature 180nm to 90nm processes. Cost-sensitive industrial controls in China and medical devices regulated by FDA 21 CFR Part 820 dominate procurement volumes.
- Radio-frequency ASIC:Millimeter-wave transceivers and radar front-ends requiring specialized substrate materials and RF-aware layout. FCC Part 15 emissions compliance shapes design rules for US market access.
Volume sits with Analog ASIC; growth tilts toward Mixed-signal ASIC.
End User:
Qualification burden and design cycle length separate procurement behaviors across verticals.
- Automotive:Functional safety certification under ISO 26262 and AEC-Q100 temperature-grade testing add eighteen to twenty-four months to product ramps. Powertrain electrification in China's NEV sector and ADAS sensor fusion in Germany's premium vehicle segment pull capacity toward automotive-qualified 16nm and 28nm nodes.
- Telecommunications:Infrastructure equipment demands multi-source manufacturing agreements and decade-long supply continuity. 5G massive MIMO deployments in South Korea and India PLI-subsidized domestic equipment manufacturing expand addressable silicon content per base station.
- Consumer Electronics:Annual refresh cycles compress design windows to twelve months. Smartphone application processors and wearable sensor hubs prioritize die-area efficiency over absolute performance.
- Industrial:Extended product lifecycles and obsolescence management requirements favor Gate Array and Structured ASIC approaches. EU Green Deal carbon footprint disclosures now extend to embedded semiconductor content.
Revenue concentrates in Telecommunications; margin expansion is steepest in Automotive.
Technology:
Non-recurring engineering investment and design flexibility tradeoffs define buyer selection criteria.
- Full Custom:Transistor-level optimization for power, performance, and area at maximum density. Hyperscaler AI training accelerators and 5G mmWave beamformers justify mask costs through million-unit annual volumes.
- Standard Cell:Synthesized logic from pre-characterized libraries enabling rapid iteration. Fabless design teams in India and Israel leverage mature EDA toolchains for cost-optimized networking silicon.
- Structured ASIC:Pre-diffused base layers with customizable metal interconnect reduce NRE by sixty to eighty percent versus full-custom approaches. Mid-volume industrial controllers and medical imaging subsystems balance unit economics with performance requirements.
- Gate Array:Lowest non-recurring cost with post-fabrication programming flexibility. Legacy industrial control systems and aerospace applications requiring decade-long supply continuity maintain procurement despite die-area inefficiency.
Design starts favor Standard Cell; average selling price leadership belongs to Full Custom.
Application:
Latency tolerance and data throughput requirements segment architectural approaches.
- Networking:Switch fabric and packet processing silicon demanding deterministic latency at terabit-per-second scale. Co-packaged optics integration from Intel and Ayar Labs targets hyperscaler data center buildouts in the United States.
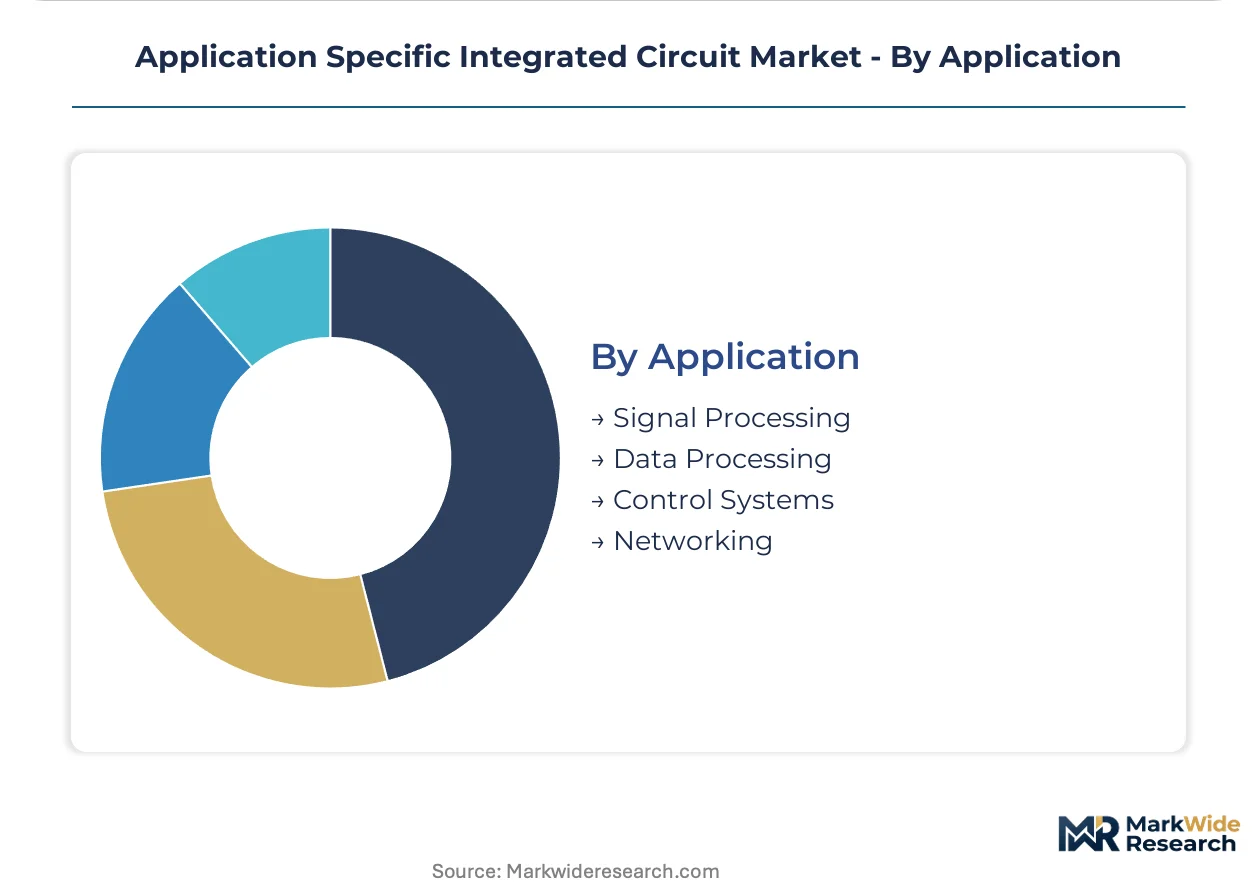
- Signal Processing:Real-time audio, video, and sensor data pipelines requiring dedicated multiply-accumulate arrays. Edge-AI inference mandates under the EU AI Act pull demand for low-power neural network accelerators.
- Data Processing:General-purpose compute offload and storage controllers. Chiplets and 2.5D integration enable cost-effective customization without monolithic reticle limits.
- Control Systems:Deterministic real-time response for motor drives and robotic actuators. Silicon carbide substrate substitution in high-voltage motor control is displacing legacy silicon-based ASICs in traction inverter applications.
Unit volume clusters in Control Systems; technology premium captures Networking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silicon feedstock from Germany's Wacker Chemie operations and Arizona's Hemlock Semiconductor facilities anchors geographic concentration for ASIC wafer production. Foundry investments cluster where governments underwrite capital-intensive fab construction through production incentives and trade-adjusted tariff regimes.
United States
Hyperscaler data center buildouts in Virginia's Loudoun County and Oregon's Hillsboro pull demand for AI training accelerators fabricated at 5nm nodes. The CHIPS and Science Act directs $52 billion toward domestic semiconductor manufacturing through NIST-administered grants. Intel's IDM 2.0 strategy centers on Arizona and Ohio fab complexes to reclaim process leadership from Asian foundries.
China
Electric vehicle powertrain electrification and 5G base station deployment concentrate demand for automotive-grade and telecommunications ASICs. MIIT's Made in China 2025 semiconductor localization targets drive state-backed capital allocation toward 28nm and 14nm domestic production lines. Yangtze Memory Technologies and SMIC anchor Shanghai and Wuhan clusters despite EUV equipment access constraints.
Germany
ADAS sensor fusion modules for premium automotive OEMs in Stuttgart and Munich require ISO 26262-certified mixed-signal ASICs. The EU Chips Act channels €43 billion toward European foundry capacity through IPCEI framework subsidies. Infineon's Dresden fab expansion anchors continental supply security for automotive qualification tiers.
South Korea
5G massive MIMO infrastructure and high-bandwidth memory controllers pull capacity toward Samsung Foundry and SK Hynix integration strategies. K-Semiconductor Belt legislation underwrites Yongin and Pyeongtaek fab clusters with tax credits and utility concessions. Seoul-based design houses specialize in modem-centric ASICs for telecommunications infrastructure.
India
Domestic telecom equipment manufacturing under PLI scheme incentives creates captive demand for mature-node networking silicon. BIS certification requirements and CEA power sector mandates shape local procurement specifications for industrial control ASICs. Bengaluru and Hyderabad fabless design teams leverage government-supported semiconductor R&D parks for cost-optimized standard-cell implementations.
Application Specific Integrated Circuit Market Vendor Landscape
Global majors compete with regional champions across foundry capacity allocation and automotive qualification expertise. The vendor base stratifies into three tiers: integrated device manufacturers with captive fabs, pure-play foundries with multi-source manufacturing agreements, and fabless design houses specializing in vertical applications. Strategic archetypes include IDM 2.0 converters reclaiming process leadership, European automotive specialists securing supply chain sovereignty, and hyperscaler-captive design teams disintermediating merchant silicon vendors. Competitive moves concentrate on multi-year offtake agreements for advanced-node capacity and backward integration into substrate materials.
Within the integrated device manufacturer tier, Intel Corporation exemplifies the IDM 2.0 archetype through foundry service expansion and process technology reclamation. Infineon Technologies AG and STMicroelectronics occupy positions as European automotive-qualified specialists with Dresden and Crolles fab anchors. Qualcomm Technologies, Inc. represents the fabless telecommunications specialist model, commissioning custom modem-centric designs directly from Taiwan and South Korea foundries. These three entities illustrate divergent strategic postures: captive manufacturing revival, regional supply security prioritization, and disaggregated design-fabrication optimization.
| Leading Market Players |
|---|
| Intel Corporation |
| Infineon Technologies AG |
| STMicroelectronics |
| Broadcom Inc |
| Texas Instruments Inc |
| Qualcomm Technologies, Inc. |
| Renesas Electronics Corporation |
| NXP Semiconductors |
| Marvell |
| Others |
Supply Flow & Price Mechanics
Photomask cost escalation at 3nm nodes simultaneously compresses mid-volume design economics and concentrates pricing power among foundries with EUV lithography fleets. Taiwan Semiconductor Manufacturing and Samsung Foundry leverage multi-year offtake agreements to lock in premium pricing for automotive-qualified capacity, while fabless teams absorb NRE burden through structured ASIC alternatives.
Pricing Analysis
Extended warranty and AEC-Q100 qualification support packages are unbundled from base wafer pricing at automotive-grade nodes, creating transparent cost tiers. Pricing stratifies across full-custom, standard-cell, and structured ASIC implementations based on mask complexity and volume commitment. Cost compression in mature-node analog ASICs is intensifying because China's domestic foundry expansion adds supply-side pressure. Consumer electronics OEMs exhibit highest price sensitivity due to annual refresh cycles, while telecommunications carriers accept premium pricing for decade-long supply guarantees.
Supply Chain Analysis
Process engineer and analog-mixed signal designer scarcity in Taiwan, South Korea, and Arizona constrains capacity expansion velocity despite capital availability. Silicon feedstock draws from Wacker Chemie's German operations and Hemlock Semiconductor's Arizona facilities, while EUV equipment sourcing rests on ASML's Veldhoven production. Single-source vulnerability in advanced-node lithography systems creates systemic concentration risk. Distribution runs through direct foundry relationships for hyperscalers and merchant design houses for mid-volume industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photomask cost barriers and EUV equipment bottlenecks are forcing consolidation among fabless design houses unable to secure multi-year capacity commitments. Weaker players without automotive qualification expertise or hyperscaler relationships face exit pressure.
For Market Incumbents: Lock in foundry allocation priority through pre-paid capacity reservations at Taiwan and South Korea facilities. Deepen backward integration into silicon carbide substrate supply chains to defend against wide-bandgap substitution in power applications. Infineon's Dresden expansion model demonstrates how captive automotive qualification capability insulates margin structure. For New Entrants and Emerging Players: Mid-volume industrial controllers requiring ISO 26262 certification but lacking million-unit scale represent the most penetrable buyer archetype. India's PLI-subsidized telecom equipment manufacturing creates captive demand for mature-node networking silicon. Commission structured ASIC designs from Bengaluru-based fabless teams to minimize NRE exposure while building foundry relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler-captive design team acquisitions and automotive-qualified fab assets. The five-to-ten year viability window favors targets with AEC-Q100 certification infrastructure and multi-source manufacturing agreements. Monitor EUV equipment delivery timelines at ASML as the critical inflection signal for advanced-node pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Foundry Offtake Agreement | Secures automotive-qualified capacity at Taiwan Semiconductor Manufacturing against allocation competition. |
| Backward Integration into SiC Substrates | Captures supply chain margin in electric vehicle traction inverter applications displacing silicon. |
| Structured ASIC Platform Launch | Reduces NRE burden for mid-volume industrial customers unable to justify full-custom mask costs. |
| AEC-Q100 Certification Infrastructure Buildout | Enables premium pricing in Germany's ADAS sensor fusion module procurement. |
| Co-Packaged Optics Integration | Compresses power-per-bit metrics for hyperscaler data center buildouts in Virginia and Oregon. |
Methodological Framework
Document review covered SEC 10-K filings from integrated device manufacturers, EU Chips Act implementation documents, and MIIT semiconductor localization directives, complemented by interviews with foundry planning executives, fabless design house CTOs, automotive Tier 1 procurement directors, and hyperscaler infrastructure engineers. Secondary validation drew from customs wafer import data, SEMI equipment shipment reports, and AEC-Q100 qualification databases. Bottom-up design start estimates and top-down foundry revenue triangulation anchored market sizing.
Segment-level outputs across product type, end user, technology, and application dimensions were generated through driver elasticity modeling over the projection horizon. CAGRs were derived from foundry capacity expansion schedules and end-use demand elasticity coefficients. Specific forecast inputs included EUV lithography equipment delivery timelines and India PLI scheme disbursement trajectories for domestic electronics manufacturing.
Revisions become necessary when EUV equipment access restrictions, automotive demand cyclicality, or silicon carbide substrate cost curves materially deviate from baseline assumptions. Forecasts reflect documented foundry capex plans and regulatory implementation schedules. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Energy Metering IC Chip Market
IC (Integrated Circuits)
Isolated Interface Chip Market
IC (Integrated Circuits)
Global Application Specific Automotive Analog IC Market
IC (Integrated Circuits)
Battery Fuel Gauge IC Market
IC (Integrated Circuits)
Global Interface IC Market
IC (Integrated Circuits)
CMOS Power Amplifier Market
IC (Integrated Circuits)
Embedded Universal Integrated Circuit Card (eUICC) Market
IC (Integrated Circuits)
Communication Special Purpose Logic IC Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
Integrated CMOS Tri-Gate Transistor Market
IC (Integrated Circuits)
Global Amplifier and Comparator IC Market
IC (Integrated Circuits)
RFID Reader IC Market
IC (Integrated Circuits)
APAC Analog IC Market
IC (Integrated Circuits)
Touch Controller IC Market
IC (Integrated Circuits)
United States Integrated Circuits Market
IC (Integrated Circuits)
GNSS IC Market