
 Global Synchronous Motor Market | 2026-2036
Global Synchronous Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Synchronous Motor Market Foresight
Project finance for large industrial motor fleets is tilting competitive dynamics toward capital-rich suppliers. Siemens AG leverages in-house power electronics manufacturing to sustain margin on premium permanent magnet systems. WEG S.A. anchors its position through deep vertical integration in South American foundry and lamination operations. Nidec Corporation specializes in compact, high-speed designs that dominate aerospace equipment and robotics applications.
A synchronous motor maintains constant rotor speed synchronized with supply frequency, typically operating at power factors from unity to 0.8 leading through adjustable field excitation. Its primary purpose is delivering precise, efficient rotational power for continuous-duty industrial processes where speed stability directly affects output quality. Permanent magnet synchronous motors now command the largest value share as rare-earth magnet costs stabilize and efficiency thresholds tighten. Field oriented control technology represents the fastest-expanding segment, displacing simpler scalar methods in precision robotics and marine propulsion where torque response determines system performance. Electrically excited variants retain strong positions in power generation above ten megawatts, where rotor field adjustability enables reactive power management.
The EU Green Deal's ecodesign requirements and China's GB motor efficiency standards are converging on IE4/IE5 minimums, forcing redesigns across permanent magnet and electrically excited product lines. Japan's METI enforces Top Runner standards that effectively block lower-efficiency imports from non-compliant jurisdictions. Stakeholders must monitor how carbon border adjustment mechanisms reshape landed costs for motors manufactured in regions with divergent electricity grid intensities.
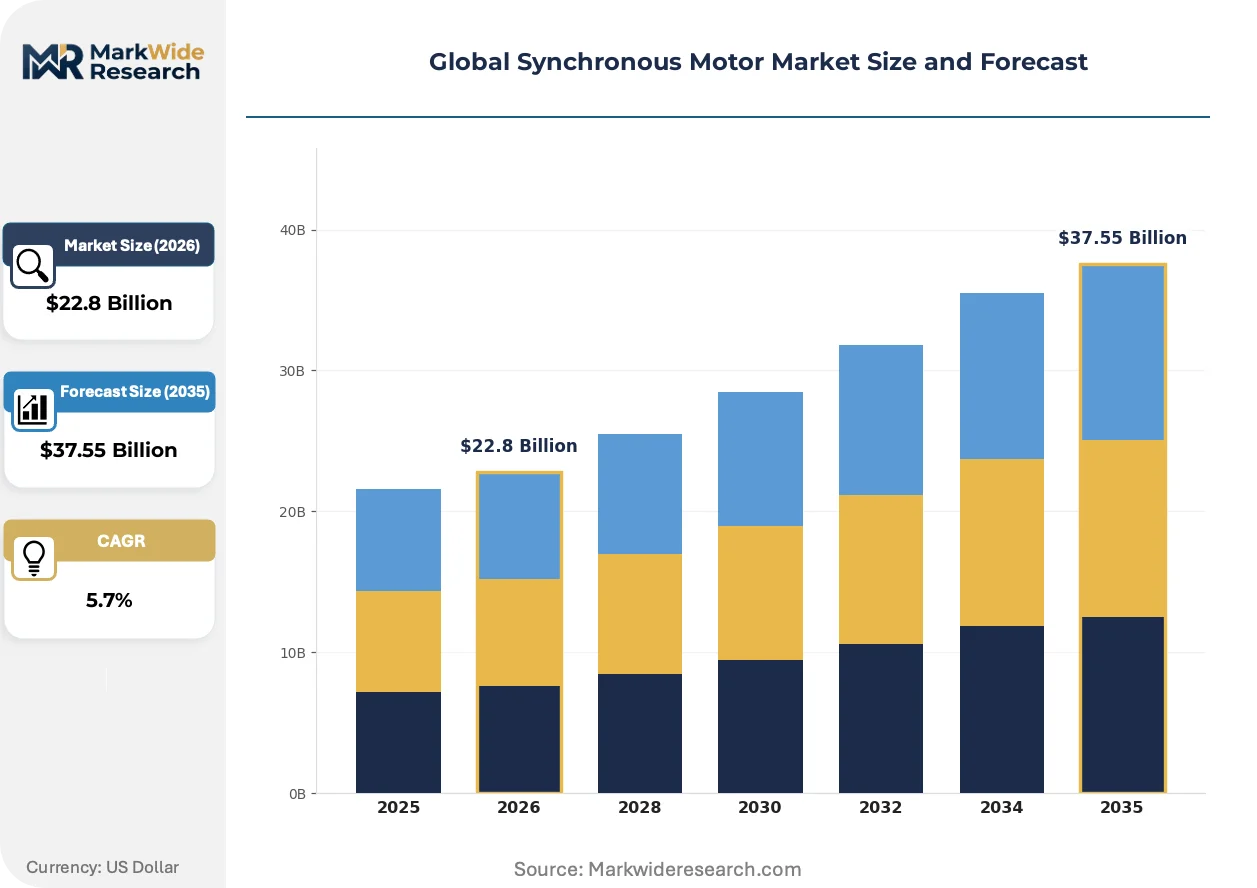
Market Dynamics
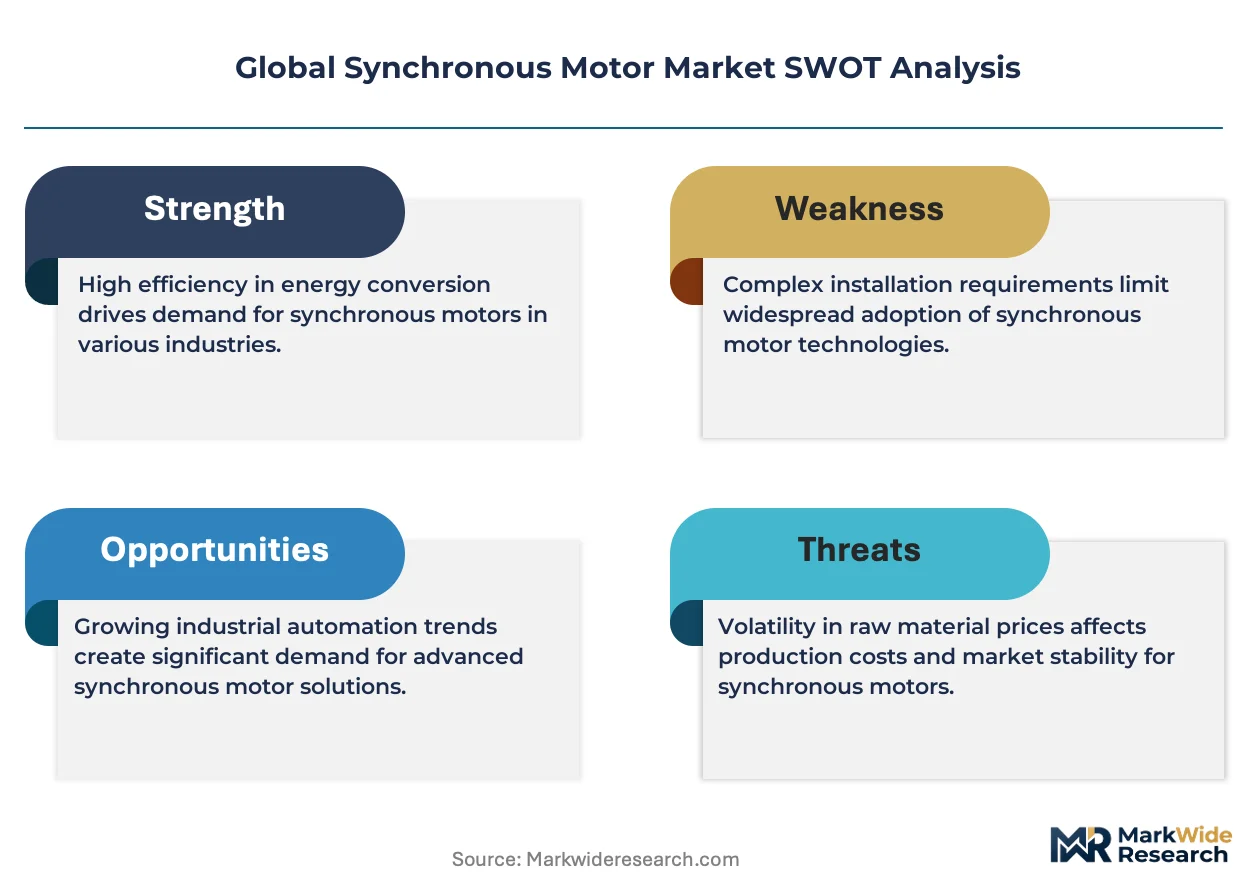
Permanent magnet supply concentration and efficiency mandate convergence are compressing supplier margins while accelerating design obsolescence for electrically excited architectures. Field oriented control adoption in marine propulsion and precision robotics is redrawing competitive boundaries between motor and drive system suppliers.
Growth Catalysts
- EU Green Deal ecodesign requirements:IE4/IE5 minimum efficiency standards force fleet replacements across German process industries and compress payback periods for premium permanent magnet systems.
- Marine propulsion electrification:Classification society rules for harbor emissions tighten operational envelopes for conventional diesel-electric systems in Rotterdam and Singapore port zones.
- India's PLI scheme for advanced chemistry cell manufacturing:Gigafactory buildouts create captive demand for high-speed winding equipment and precision coating line drives.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium and dysprosium price swings from Chinese processing concentration destabilize permanent magnet motor quoting cycles.
- Electrically excited rotor complexity:Brush and slip-ring maintenance requirements limit adoption in unmanned subsea installations and satellite actuation.
- Japan METI Top Runner enforcement:Non-compliant import blocks from lower-efficiency manufacturing jurisdictions fragment supplier access.
Strategic Opportunities
- Brazilian offshore pre-salt expansion:Subsea compression and pump drive retrofits favor synchronous architectures for constant-speed gas handling.
- Field oriented control-encoder convergence:Integrated position sensing eliminates separate feedback loops in collaborative robotics and semiconductor handling.
- Carbon border adjustment mechanism phase-in:EU CBAM scope expansion rewards motors manufactured on low-grid-intensity electricity in France and Sweden.
Industry Challenges
- Power electronics-motor thermal integration:SiC and GaN switching frequencies push bearing currents and insulation stress beyond conventional design margins.
- IEC 60034-18-41 partial discharge certification:Random-wound stator qualification timelines extend by eight to fourteen months for inverter-fed duty ratings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Synchronous Motor Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $37.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent Magnet, Electrically Excited, Brushless, Cylindrical Rotor, Salient Pole Technology: Direct Torque Control, Vector Control, Sensorless Control, Field Oriented Control Application: Power Generation, Textile Machinery, Aerospace Equipment, Robotics, Marine Propulsion End User: Manufacturing Plants, Defense Contractors, Research Laboratories, Transport Operators |
| Companies Covered | ABB Ltd., Siemens AG, WEG S.A., Nidec Corporation, Toshiba Corporation, General Electric Company, Mitsubishi Electric Corporation, Schneider Electric SE, Rockwell Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Synchronous Motor Market Shifts & Advancements
Digital twin deployment and real-time thermal modeling are compressing prototype validation cycles while enabling predictive maintenance contracts. Supplier differentiation increasingly hinges on software-integrated system architectures rather than standalone electromechanical performance.
Axial flux permanent magnet topologies are digitizing motor-drive system integration by embedding torque and temperature telemetry directly into stator windings. Aerospace actuator manufacturers in Toulouse and Hamburg adopt these architectures for envelope-constrained flight control surfaces. The technology is digitizing condition-based maintenance contracts that unbundle hardware from availability guarantees.
China's GB 18613-2020 efficiency standards and dual carbon enforcement tighten domestic market access while creating export pressure on non-compliant inventories. MIIT certification timelines now require third-party testing at designated Shanghai and Beijing laboratories. Manufacturers with captive rare-earth processing in Baotou and Ganzhou capture margin that importers forfeit to compliance costs.
Marine operators now specify integrated propulsion-as-a-service contracts that transfer operational risk to system suppliers. Classification societies in Oslo and London rewrite warranty terms around fuel consumption guarantees rather than equipment availability. This restructuring concentrates procurement authority with fleet technical managers in Copenhagen and Singapore while displacing traditional shipyard specification authority.
Global Synchronous Motor Market Segmentation
Synchronous motor procurement patterns diverge sharply across excitation architectures and control methodologies. Permanent magnet designs compete against electrically excited alternatives on lifecycle cost rather than upfront capital. Application-specific torque precision requirements fragment supplier specialization across marine, aerospace, and industrial automation verticals.
Product Type:
Cost tier differentiation separates rare-earth dependent architectures from conventional wound-field alternatives.
- Permanent Magnet:Neodymium-iron-boron or ferrite magnets embedded in rotor laminations deliver superior power density and IE5 efficiency compliance. Demand concentrates in German process industries and Japanese robotics OEMs where EU Green Deal mandates accelerate fleet replacement cycles.
- Electrically Excited:Rotor windings fed through slip rings enable adjustable power factor and reactive power compensation. Power generation above ten megawatts in Swedish and French grid interconnection projects sustains procurement volumes despite maintenance-intensive architectures.
- Brushless:Elimination of mechanical commutation through electronic switching extends service intervals in unmanned subsea installations.
- Cylindrical Rotor:Uniform air-gap geometry suits high-speed compressor drives in Brazilian offshore pre-salt gas handling.
- Salient Pole:Projected pole construction delivers high starting torque for reciprocating pump loads in Indian petrochemical complexes.
Permanent magnet systems command the established base. The steepest expansion runs through brushless architectures.
Technology:
Control algorithm sophistication determines torque response bandwidth and encoder integration requirements.
- Field Oriented Control:Decoupled flux and torque current components enable sub-millisecond transient response. Marine propulsion electrification in Rotterdam and Singapore port zones drives specification for integrated drive-motor systems with classification society certification.
- Direct Torque Control:Hysteresis-based switching minimizes torque ripple for precision semiconductor wafer handling equipment. Japanese and German machine tool builders specify this architecture for spindle applications requiring surface finish repeatability.
- Vector Control:Indirect field orientation through current model reference finds cost-optimized deployment in Indian textile winding machinery.
- Sensorless Control:Elimination of physical encoders reduces failure modes in satellite actuation and deep-sea remotely operated vehicles.
Field oriented control anchors the established base. The steepest expansion runs through sensorless implementations.
Application:
End-use torque precision requirements and duty cycle intensity segment procurement authority across equipment OEMs and fleet operators.
- Marine Propulsion:Integrated electric propulsion systems replace mechanical gearing in cruise vessels and offshore support fleets. Classification society fuel consumption guarantees in Oslo and London restructure procurement toward system suppliers offering availability contracts.
- Robotics:Collaborative and industrial robotic joints demand compact, high-speed designs with integrated position sensing. Nidec Corporation specialization in this segment captures aerospace equipment and precision assembly demand in Toulouse and Hamburg manufacturing clusters.
- Power Generation:Synchronous condensers and pumped hydro motor-generators require adjustable excitation for grid stability services.
- Aerospace Equipment:Axial flux topologies with embedded telemetry address envelope-constrained flight control surface actuation.
- Textile Machinery:Constant-tension winding drives in India's PLI-supported gigafactory coating lines specify precise speed holding.
Power generation commands the established base. The steepest expansion runs through marine propulsion.
End User:
Customer technical capability and fleet scale determine specification authority and service contract structures.
- Manufacturing Plants:Process industry operators in Germany and Japan specify IE4/IE5 efficiency tiers with predictive maintenance integration. Siemens AG leverages power electronics manufacturing integration to capture premium permanent magnet system contracts.
- Transport Operators:Marine and rail fleet technical managers in Copenhagen and Singapore consolidate procurement authority through propulsion-as-a-service contracts that transfer operational risk to suppliers.
- Defense Contractors:Unmanned platform requirements drive brushless and sensorless specifications for reduced maintenance signatures.
- Research Laboratories:Custom torque-speed envelope requirements for test stands sustain low-volume, high-margin specialist suppliers.
Manufacturing plants command the established base. The steepest expansion runs through transport operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in synchronous motor trade reveal concentrated manufacturing in Germany, Japan, and China against rising captive demand in India and Brazil. Capital-rich suppliers leverage domestic efficiency mandates to defend home market positions while penetrating tariff-adjusted export channels.
Germany
Process industry fleet replacements under EU Green Deal IE4/IE5 mandates sustain premium permanent magnet procurement from Siemens AG and ABB Ltd. The country's national efficiency regulator enforces ecodesign requirements that compress payback periods for high-efficiency systems. Industrial clusters in Bavaria and North Rhine-Westphalia anchor German motor manufacturing and drive specification authority across European process industries.
Japan
Robotics OEMs and machine tool builders in Nagoya and Osaka generate concentrated demand for compact, high-speed synchronous designs. METI Top Runner standards block lower-efficiency imports from non-compliant jurisdictions, fragmenting supplier access. Nidec Corporation specialization in precision aerospace and robotics applications captures domestic demand while setting technical benchmarks for collaborative robot joint motors.
China
GB 18613-2020 efficiency standards and dual carbon enforcement tighten domestic market access while pressuring non-compliant export inventories. MIIT certification requires third-party testing at designated Shanghai and Beijing laboratories, extending qualification timelines. Captive rare-earth processing in Baotou and Ganzhou enables margin capture that importers forfeit to compliance costs and carbon border adjustment exposure.
India
PLI scheme-supported gigafactory buildouts create captive demand for high-speed winding equipment and precision coating line drives in Gujarat and Tamil Nadu. The Central Electricity Authority enforces efficiency standards that accelerate industrial motor fleet turnover. Manufacturing reshoring concentrates procurement authority with domestic process operators seeking to reduce import dependence on Chinese and European suppliers.
Brazil
Offshore pre-salt expansion drives subsea compression and pump drive retrofits favoring synchronous architectures for constant-speed gas handling. ANVISA and national petroleum regulator requirements shape equipment certification for unmanned subsea installations. WEG S.A. leverages deep foundry and lamination integration in Santa Catarina to capture South American offshore project specifications.
Global Synchronous Motor Market Competitive Landscape
On the supply side, the industry is consolidating around capital-rich diversified industrials with captive power electronics and rare-earth processing capabilities. Three strategic archetypes dominate: vertically integrated European-Japanese conglomerates with in-house semiconductor fabrication, South American specialists with captive lamination and foundry operations, and compact-motor precision specialists serving aerospace and robotics niches. Competitive intensity concentrates on M&A-driven technology acquisition and geographic expansion through local certification partnerships.
Within the diversified industrial tier, Siemens AG exemplifies the power electronics-integrated archetype, while WEG S.A. occupies the South American vertical integration position. Nidec Corporation represents the compact precision specialist segment. These three anchors illustrate how supplier differentiation increasingly hinges on software-integrated system architectures and predictive maintenance contracting rather than standalone electromechanical performance metrics.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| WEG S.A. |
| Nidec Corporation |
| Toshiba Corporation |
| General Electric Company |
| Mitsubishi Electric Corporation |
| Schneider Electric SE |
| Rockwell Automation |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese rare-earth processing facilities compresses magnet pricing and forces European and Japanese motor manufacturers into defensive procurement postures. This utilization imbalance ripples through permanent magnet motor quoting cycles, amplifying margin pressure on suppliers without captive upstream material access.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on IE4/IE5 certification grade and volume scale, with German process industry fleets commanding favorable terms against smaller Indian textile operators. Pricing pressure stems from neodymium cost volatility originating in Baotou processing concentration. Small-to-mid manufacturing plants exhibit highest price sensitivity, while marine fleet technical managers prioritize availability guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from European automotive OEMs strain working capital for mid-tier lamination suppliers. Geographic supply concentrates in China for rare-earth magnets, Germany for precision windings, and Japan for high-speed bearing assemblies. Raw material dependencies center on neodymium-iron-boron alloys, electrical steel laminations, and silicon carbide power modules. Single-source vulnerability in Chinese magnet processing creates structural exposure. Distribution runs through direct OEM contracts for large fleets and specialized distributors for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent synchronous motor suppliers face substitution pressure from integrated motor-drive systems that collapse traditional component boundaries. Defense requires anchoring in software-integrated architectures rather than standalone electromechanical performance.
For Market Incumbents: Entrench through backward integration into rare-earth magnet sourcing and predictive maintenance software stacks. Siemens AG exemplifies power electronics integration that defends premium positioning against Asian cost competitors. Captive foundry operations in Germany and Japan insulate against carbon border adjustment exposure. Threat vector: compact axial flux architectures from aerospace specialists migrating into industrial automation.
For New Entrants and Emerging Players: Mid-market Indian gigafactory equipment suppliers represent the most penetrable entry point, with CEA efficiency mandates accelerating fleet replacement beyond domestic supplier capacity. Brazilian offshore pre-salt subsea compression retrofits offer second-mover opportunity as WEG S.A. capacity constraints emerge. Go-to-market angle: sensorless control architectures that eliminate encoder costs for unmanned installations.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because capital requirements for IE5 certification and MIIT testing infrastructure favor scaled diversified industrials over specialist motor houses. Acquisition target archetype: compact-motor precision specialists with aerospace robotics positioning and embedded telemetry IP. Signal to watch: marine propulsion-as-a-service contract structures that transfer operational risk and concentrate procurement authority with fleet technical managers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Processing | Captive magnet supply in Baotou or Ganzhou insulates margin from Chinese export quota volatility. |
| Field Oriented Control-Encoder Convergence | Integrated position sensing eliminates separate feedback loops for Nidec Corporation's robotics specialization. |
| Predictive Maintenance Platform Development | Digital twin deployment enables availability contracts that restructure procurement authority in Copenhagen and Singapore. |
| MIIT Certification Partnership | Third-party testing at designated Shanghai and Beijing laboratories accelerates Chinese market access timelines. |
| Marine Propulsion-as-a-Service Launch | Fuel consumption guarantees from classification societies in Oslo and London displace traditional shipyard specification. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers, OEM procurement teams, aftermarket service heads, and marine fleet technical managers and refined through secondary validation. Primary fieldwork combined structured interviews with maintenance directors at German process industries and procurement leads at Indian gigafactory equipment suppliers. Secondary sources encompassed MIIT certification databases, EU ecodesign directive filings, IEC 60034 efficiency standard documentation, and customs trade records for rare-earth magnet flows. Bottom-up unit economics triangulated against top-down sectoral demand models.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include excitation architecture, control methodology, torque precision tier, and regional regulatory cluster. CAGRs derived from installed base turnover rates and efficiency mandate compliance deadlines. Industry-specific forecast inputs incorporated GB 18613-2020 enforcement timelines and EU carbon border adjustment mechanism phase-in assumptions.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity pricing, rare-earth export quotas, or marine fuel taxation would shift the trajectory. Forecasts reflect documented assumptions around technology substitution rates and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
High Voltage Ceramic Zinc Oxide Surge Arrester Market
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
North America Telecom Power Systems Market
Power Systems
Traction Inverter Market
Power Systems
High Voltage Direct Current Power Supply Market
Power Systems
Low Voltage DC Circuit Breaker Market
Power Systems
Japan Surge Protector Market
Power Systems
Shunt Voltage References Market
Power Systems
Thyristor Market
Power Systems
Buck-Boost Controller Market
Power Systems
Harmonic Generators Market
Power Systems
Wireless Battery Monitoring System Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
North America Variable Frequency Drive Market
Power Systems
Power Electronics Market
Power Systems
Converter Modules Market