
 Display LSI IC Market | 2026-2036
Display LSI IC Market Size, Share, and Industry Trends Forecast 2026-2036
Display LSI IC Market Analysis
Multi-source procurement is consolidating as panel makers reduce vendor lists amid yield-sensitive OLED ramp-ups. Samsung Electronics (System LSI) leverages captive demand from its display affiliate to sustain process-node leadership in mobile DDICs. Novatek Microelectronics anchors Taiwan's fabless ecosystem with broad LCD and OLED coverage across Chinese panel customers.
A display LSI IC is a mixed-signal semiconductor that converts digital video data into analog or timed digital signals driving pixel arrays, typically fabricated on 40nm to 28nm nodes with integrated gamma correction and power management. Its primary purpose is to control row and column drivers in flat-panel displays while minimizing electromagnetic interference and power dissipation. OLED Drivers command premium margins as foldable and LTPO panel penetration deepens, whereas LCD Drivers retain volume dominance in cost-sensitive TV and monitor segments. Mixed-Signal technology captures the largest design-in share by unifying timing controllers with source drivers on single die for space-constrained smartphones.
South Korea's Ministry of Trade, Industry and Energy (METI-equivalent industrial policy) channels domestic foundry capacity toward strategic display chip production under national semiconductor frameworks. China's MIIT enforces GB standards on electromagnetic compatibility and energy efficiency that constrain non-compliant IC imports into domestic panel supply chains. The EU's REACH and RoHS directives limit hazardous substances in semiconductor packaging, affecting material choices for European-bound automotive display modules. Stakeholders must monitor how geopolitical export controls on advanced lithography equipment reshape foundry access for next-generation OLED driver designs.
Market Dynamics
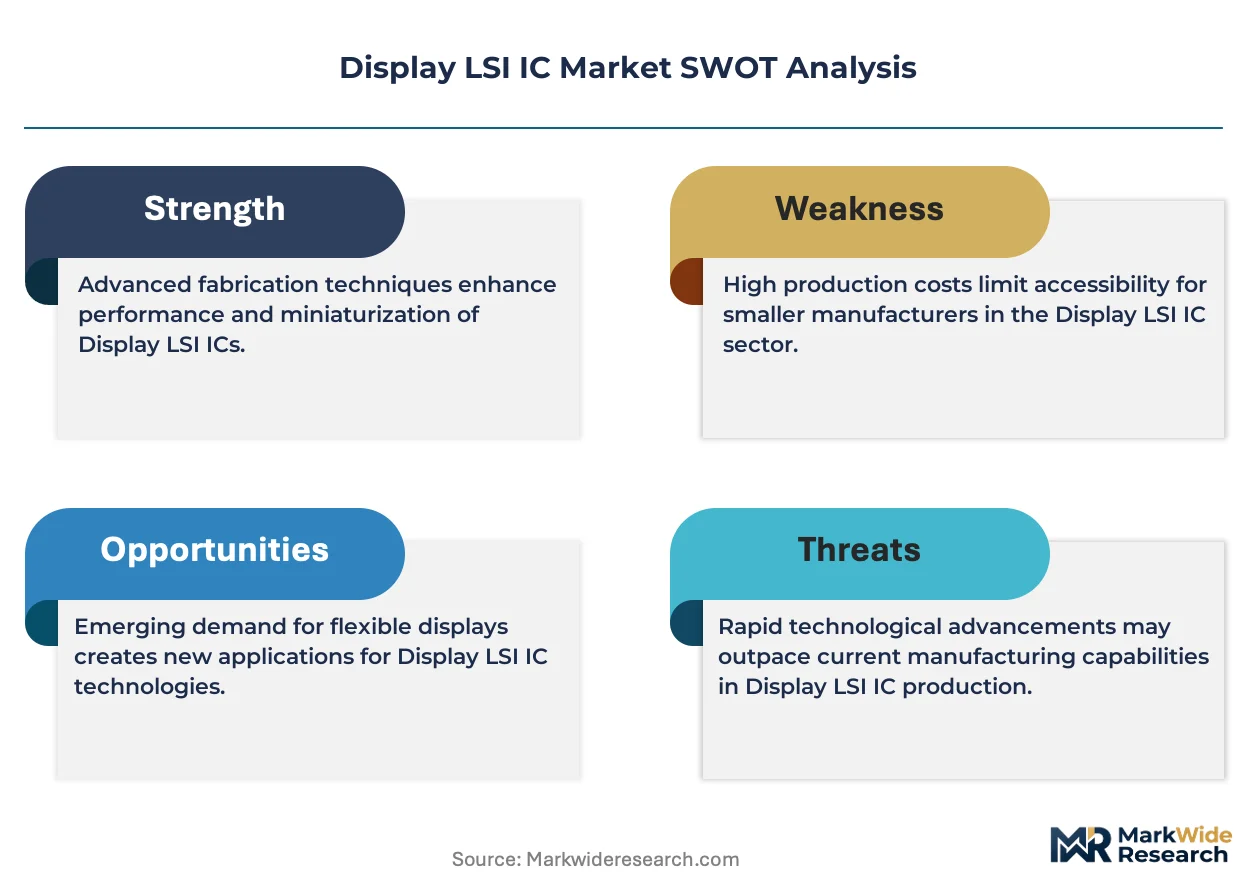
Automotive display integration is compressing design cycles as OEMs demand larger curved panels, forcing foundry capacity reallocation toward mixed-signal OLED driver production.
Growth Catalysts
- Dual carbon goals:China's energy-efficiency mandates under MIIT are accelerating fab upgrades toward low-power process nodes, pulling demand for advanced display LSIs.
- Foldable panel penetration:LTPO backplane technology in smartphones requires precision timing controllers, expanding the addressable premium segment.
- Seoul-Gumi cluster concentration:South Korea's foundry ecosystem around Samsung and SK Hynix is anchoring captive DDIC production for domestic panel affiliates.
Market Restraints
- Advanced lithography equipment constraints:Export controls on EUV and DUV systems are restricting 28nm migration for next-generation OLED drivers.
- Gamma reference voltage precision:Analog circuit matching requirements at sub-40nm nodes are elevating design complexity and tape-out costs.
- EMI shielding material volatility:Palladium and nickel prices in package substrates are compressing margins on high-pin-count automotive drivers.
Strategic Opportunities
- India display fab buildout:PLI scheme incentives for panel manufacturing are creating greenfield demand for timing controller and source driver localization.
- Vehicle cockpit consolidation:Single-chip integration of cluster, infotainment, and HUD control is opening TAM expansion in premium automotive.
- EU automotive safety mandates:EASA-equivalent standards for driver distraction are mandating higher refresh rates and faster response times in instrument clusters.
Industry Challenges
- Mixed-signal design talent scarcity:Analog-digital co-verification expertise is concentrating at senior levels, elongating recruitment cycles for fabless houses.
- Automotive qualification timelines:AEC-Q100 Grade 1 certification for extended temperature operation requires 18-24 month validation, delaying revenue recognition.
- Legacy LCD driver obsolescence management:End-of-life planning for mature 55nm nodes is forcing inventory hedging amid unpredictable TV replacement demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Display LSI IC Market |
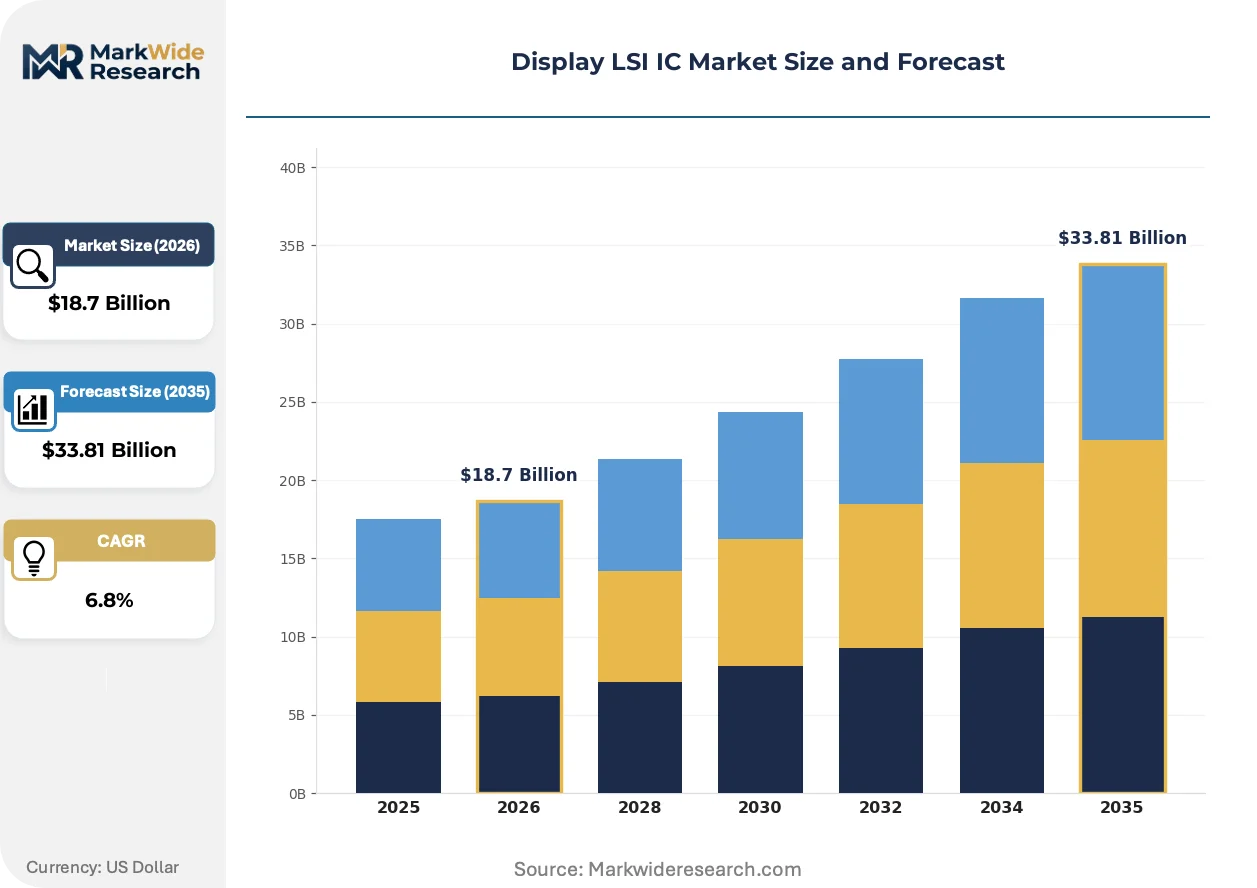
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD Drivers, OLED Drivers, TFT Controllers, Image Processors Technology: Analog, Digital, Mixed-Signal, ASIC Application: Smartphones, Tablets, TVs, Monitors End User: Consumer Electronics, Automotive, Medical Devices, Industrial Applications |
| Companies Covered | LX Semicon, MediaTek, Novatek Microelectronics, Realtek Semiconductor, Texas Instruments, Himax Technologies, Synaptics, Silicon Works, Samsung Electronics (System LSI), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Display LSI IC Market Emerging Trajectories
Process-node migration and packaging evolution are redefining competitive advantage in display signal conditioning, with single-die integration displacing multi-chip module architectures.
Integrated T-con and source driver architectures on 28nm nodes are consolidating timing control and pixel driving functions into monolithic solutions. Automotive Tier 1s are adopting these for curved instrument clusters at accelerated qualification paces. This consolidation is compressing bill-of-materials counts and electromagnetic interference pathways in space-constrained vehicle cabins.
China's MIIT GB standards on electromagnetic compatibility are tightening conducted emission limits for semiconductor imports into domestic panel supply chains. Non-compliant IC vendors face exclusion from approved supplier lists for government-backed display projects. Korean and Taiwanese foundry customers are redesigning power-ground layouts to satisfy these radiated emission thresholds.
Direct foundry relationships are displacing merchant distributor channels for high-volume panel makers. Samsung Display and BOE are negotiating wafer starts directly with foundry operations, bypassing traditional fabless intermediaries. This pattern is most visible in South Korea and China, where captive demand justifies dedicated capacity allocation agreements.
Display LSI IC Market Segmentation
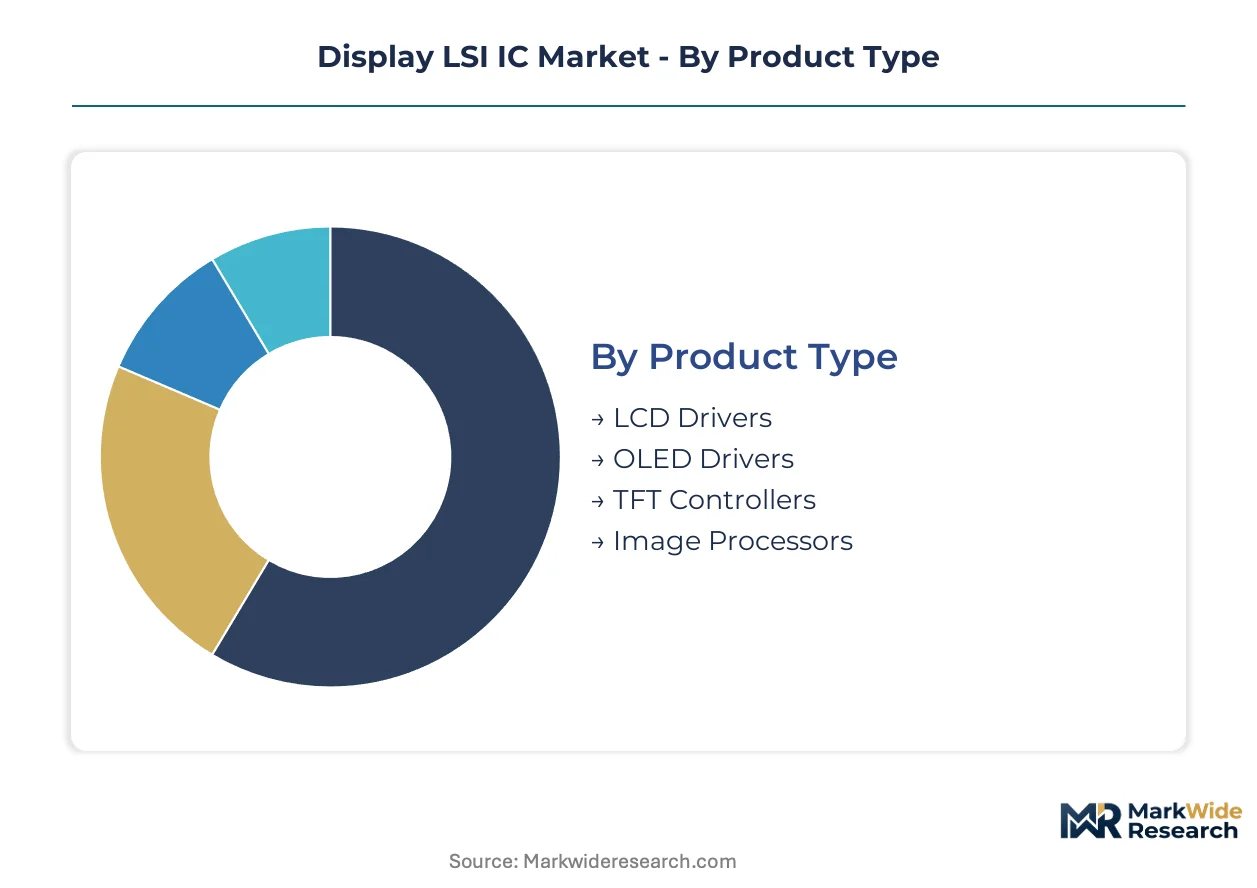
Display LSI IC segmentation reflects diverging upgrade cycles across display technologies. Panel makers prioritize semiconductor replacements that extend product lifecycles while enabling feature differentiation in saturated end-use categories.
Product Type:
Replacement cycles vary sharply by display technology maturity, with newer backplane architectures demanding more frequent silicon refreshes.
- OLED Drivers:These mixed-signal ICs integrate timing control, gamma correction, and power management for organic pixel arrays. Foldable smartphone panels in South Korea's Seoul-Gumi corridor consume the premium tier, as mechanical stress tolerance requirements accelerate design iterations.
- LCD Drivers:Mature voltage-buffer architectures serve high-volume TV and monitor production. China's MIIT energy-efficiency mandates under dual carbon goals are forcing node shrinks from 55nm toward 40nm in domestic fab upgrades, sustaining demand despite OLED substitution.
- TFT Controllers:Row-driver sequencing chips for thin-film transistor backplanes.
- Image Processors:Scalar and color-enhancement engines for high-dynamic-range panels.
Volume placements concentrate in LCD Drivers; the faster expansion belongs to OLED Drivers.
Technology:
Process-node economics separate viable production tiers, with analog-intensive designs commanding premium mask costs at advanced geometries.
- Mixed-Signal:Unified timing-controller and source-driver architectures dominate smartphone space constraints. Samsung Electronics leverages captive System LSI capacity for 28nm monolithic integration, compressing electromagnetic interference pathways in foldable devices.
- ASIC:Customer-specific implementations for automotive instrument clusters carry extended qualification timelines. AEC-Q100 Grade 1 certification requirements in Germany's KBA regulatory sphere elongate design cycles to 18-24 months.
- Analog:Discrete gamma-reference and level-shifter circuits.
- Digital:Pure-logic timing controllers for cost-optimized panels.
Customer concentration favors Mixed-Signal; ASIC climbs fastest on automotive cockpit consolidation.
Application:
Screen-size scaling determines pin-count and package substrate requirements, with larger formats multiplying I/O complexity.
- Smartphones:LTPO backplane adoption requires precision variable-refresh timing. BOE and Samsung Display negotiate direct foundry relationships for high-volume 28nm wafer starts, bypassing traditional fabless intermediaries.
- TVs:8K resolution timing controllers demand 120Hz signal integrity across extended cable runs. China's GB electromagnetic compatibility standards constrain non-compliant IC imports into domestic panel supply chains.
- Tablets:Mid-size format drivers balancing mobility and productivity.
- Monitors:Gaming-oriented high-refresh implementations.
Unit economics favor TV volumes; smartphone applications gain share fastest on foldable penetration.
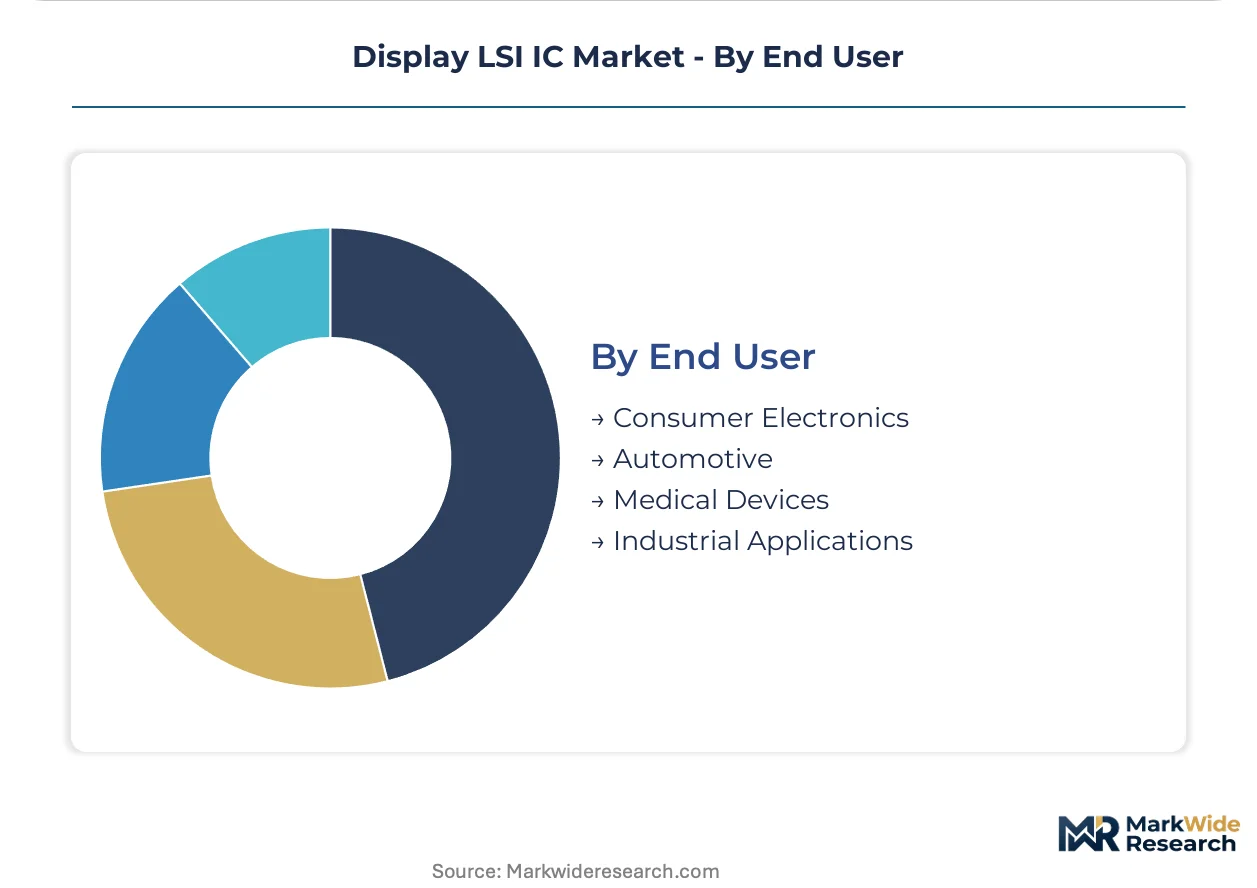
End User:
Qualification severity and temperature-range requirements fragment procurement patterns across customer classes.
- Automotive:Curved instrument clusters and head-up displays require AEC-Q100 Grade 1 operation from -40°C to 125°C. EU automotive safety mandates through EASA-equivalent standards mandate higher refresh rates, pulling timing controller specifications upward.
- Consumer Electronics:Annual product cycles compress design windows. South Korea's Ministry of Trade, Industry and Energy channels domestic foundry capacity toward strategic display chip production under national semiconductor frameworks.
- Medical Devices:Diagnostic imaging panels requiring extended color gamut precision.
- Industrial Applications:HMI interfaces for factory automation with wide-temperature tolerance.
Procurement scale concentrates in Consumer Electronics; Automotive expands most quickly on cockpit digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silicon feedstock from German chemical processors anchors European supply chains for automotive-grade display semiconductors. South Korean foundry capacity concentrates around Seoul-Gumi corridor for captive OLED driver production. Chinese gallium arsenide refineries feed domestic panel manufacturing under MIIT energy-efficiency mandates.
South Korea
Seoul-Gumi industrial belt hosts Samsung Electronics System LSI and SK Hynix captive foundry operations serving domestic panel affiliates. METI-equivalent industrial policy channels wafer starts toward strategic display chip production under national semiconductor frameworks. Samsung Display negotiates direct foundry relationships for 28nm mixed-signal OLED driver wafers, bypassing traditional fabless intermediaries.
China
BOE and TCL CSOT panel operations in Beijing and Shenzhen drive timing controller demand for 8K TV and foldable smartphone formats. MIIT enforces GB standards on electromagnetic compatibility and energy efficiency that constrain non-compliant IC imports into domestic supply chains. Yangtze River Delta fabs around Shanghai upgrade from 55nm toward 40nm nodes under dual carbon goals.
United States
Texas Instruments and Synaptics serve automotive Tier 1s with AEC-Q100 qualified drivers for curved instrument clusters. NHTSA safety standards and EPA emissions frameworks indirectly shape automotive display refresh rate requirements through vehicle electrification mandates. Arizona and Texas foundry investments by Intel and TSMC create alternative capacity for fabless design houses.
Taiwan
Novatek Microelectronics and Realtek Semiconductor anchor fabless ecosystems with broad LCD and OLED coverage across Chinese panel customers. Hsinchu Science Park concentrates mixed-signal design talent for gamma-correction and power-management integration. Direct foundry relationships with TSMC secure 28nm capacity for smartphone timing controller production.
Germany
KBA regulatory sphere mandates AEC-Q100 Grade 1 certification for automotive display modules operating in extended temperature ranges. Bavaria and Baden-Württemberg host Bosch and Continental Tier 1 operations specifying high-refresh instrument cluster controllers. REACH and RoHS directives limit hazardous substances in semiconductor packaging for European-bound modules.
Display LSI IC Market Vendor Landscape
Global majors compete with regional champions across captive foundry access and fabless design specialization. The vendor base separates into three tiers: integrated device manufacturers with captive demand, pure-play fabless houses with broad panel customer coverage, and analog specialists with automotive qualification expertise. Strategic consolidation centers on foundry capacity allocation agreements and direct wafer start negotiations with high-volume panel makers. Technology licensing and backward integration into gamma-reference IP represent dominant competitive vectors.
Among South Korea-based integrated operations, Samsung Electronics System LSI exemplifies captive supply chain architecture leveraging affiliate demand. Taiwan's fabless tier includes Novatek Microelectronics and Realtek Semiconductor, occupying positions defined by Chinese panel customer relationships. Texas Instruments represents the analog-specialist archetype with automotive-grade qualification depth.
| Leading Market Players |
|---|
| LX Semicon |
| MediaTek |
| Novatek Microelectronics |
| Realtek Semiconductor |
| Texas Instruments |
| Himax Technologies |
| Synaptics |
| Silicon Works |
| Samsung Electronics (System LSI) |
| Others |
Supply Flow & Price Mechanics
Palladium and nickel price indices on the London Metal Exchange cascade through package substrate costs into three distinct pricing tiers for display LSI IC procurement. Panel makers absorb elevated material expenses in premium automotive driver segments while squeezing standard-tier LCD driver margins through consolidated vendor lists.
Pricing Analysis
Warranty and failure-analysis bundling separate premium automotive-grade drivers from unbundled consumer electronics procurement. Three-tier pricing structure across AEC-Q100 Grade 1 certified, industrial-temperature, and commercial-grade products reflects qualification severity and temperature-range testing investment. Cost compression in mature LCD driver tiers intensifies as Chinese panel makers consolidate 55nm wafer starts toward captive foundry arrangements. Consumer electronics buyers exhibit highest price sensitivity due to annual product refresh cycles compressing design windows.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Taiwanese foundry capacity for 28nm mixed-signal OLED driver production. High-purity silicon feedstock draws from German chemical processors, gallium arsenide refineries feed from Chinese domestic operations, and advanced photoresist materials rest on Japanese suppliers. Export controls on EUV and DUV lithography equipment create structural risk for node migration roadmaps. Distribution runs through direct foundry relationships displacing merchant distributor channels for high-volume panel makers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity constraints for 28nm mixed-signal processes prop pricing power across automotive and foldable smartphone driver tiers. Supply scarcity favors incumbents with captive wafer allocation agreements.
For Market Incumbents: Extend process-node leadership through dedicated capacity reservations at foundry partners serving Seoul-Gumi corridor operations. Defend against fabless entrants by deepening backward integration into gamma-reference IP and power-management subsystems. Accelerate AEC-Q100 Grade 1 certification pipelines before EU automotive safety mandates tighten refresh rate specifications. For New Entrants and Emerging Players: Enter via India's PLI scheme display fab buildout creating greenfield demand for timing controller localization. Target automotive Tier 2 suppliers in Germany's KBA regulatory sphere requiring second-source qualification for curved instrument cluster programs. Pursue direct foundry relationships bypassing traditional fabless intermediaries in Chinese Yangtze River Delta manufacturing zones. For Investors and Strategic Acquirers: Distressed-cycle entries favor analog-specialist fabless houses with automotive qualification depth in Taiwan's Hsinchu Science Park ecosystem. Long-term viability centers on mixed-signal design talent retention and 28nm capacity access across a five-to-ten year horizon. Monitor MIIT GB standard enforcement on electromagnetic compatibility as inflection indicator for non-compliant IC vendor exclusion from government-backed panel projects.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Foundry Partnership | Samsung Display and BOE negotiate wafer starts bypassing traditional fabless intermediaries for cost control. |
| Automotive Certification Investment | AEC-Q100 Grade 1 qualification opens curved instrument cluster supply to Tier 1s under EASA-equivalent standards. |
| Gamma-Reference IP Acquisition | Backward integration into analog circuit matching expertise reduces tape-out costs at sub-40nm nodes. |
| India Manufacturing Localization | PLI scheme incentives create greenfield timing controller demand for domestic panel fab operations. |
| MIIT Compliance Redesign | Power-ground layout modifications satisfy GB electromagnetic compatibility thresholds for Chinese supply chain access. |
Methodological Framework
SEC 10-K filings, MIIT GB standard documentation, and foundry utilization disclosures formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with display driver IC design leads, automotive Tier 1 procurement officers, and panel maker supply chain directors combined with secondary validation through customs records and semiconductor trade association data. Bottom-up wafer start estimates and top-down display panel shipment analysis enabled triangulation across independent calculation paths.
Bottom-up modeling of 28nm and 40nm wafer starts by application and technology type anchored volume projections across the analysis window. Segmentation dimensions included product type, process node, display technology, end-use sector, and regional foundry cluster. CAGRs derived from logistic diffusion curves for OLED penetration rates and linear extrapolation of automotive display content per vehicle. Industry-specific inputs captured LTPO backplane adoption timelines and dual carbon goal fab upgrade schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control escalation on advanced lithography equipment and palladium price volatility in package substrates. Forecasts reflect documented assumptions on foundry capacity allocation and panel maker consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Motor Driver IC Market
IC (Integrated Circuits)
Mixed Signal IC Market
IC (Integrated Circuits)
Semiconductor Integrated Circuit Chip Market
IC (Integrated Circuits)
Embedded Universal Integrated Circuit Card (eUICC) Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
Americas Logic IC Market
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Power Management IC (PMIC) Market
IC (Integrated Circuits)
Japan Analog IC Market
IC (Integrated Circuits)
Motor Control IC Market
IC (Integrated Circuits)
Global Semiconductor Timing IC Market
IC (Integrated Circuits)
Isolated Interface Chip Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
Automotive Integrated Circuit (Ics) Market
IC (Integrated Circuits)
NFC Reader Ics Market
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market