
 NFC Reader Ics Market | 2026-2036
NFC Reader Ics Market Size, Share, and Industry Trends Forecast 2026-2036
NFC Reader Ics Market Foresight
South Korea is tilting toward advanced NFC controller production as domestic foundries expand 8-inch RF-CMOS capacity. NXP Semiconductors leverages its secure-element IP portfolio to dominate automotive keyless-entry applications. STMicroelectronics anchors European supply through dedicated NFC wafer fabrication in France and Italy.
NFC reader integrated circuits are mixed-signal semiconductors operating at 13.56 MHz with embedded RF front-ends, protocol controllers, and cryptographic engines for ISO 14443 and ISO 18092 compliance. These devices enable contactless communication between terminals and credentials for payment authentication, physical access, and device pairing. Secure elements command premium margins due to Common Criteria certification requirements and banking-grade tamper resistance. Card emulation technology is displacing dedicated plastic credentials in transit systems across Asia. Mobile payments applications concentrate volume demand as smartphone OEMs integrate multifunctional NFC controllers.
FCC Part 15 rules in the United States govern unintentional radiators and shape transmitter power limits for reader IC certification. ETSI EN 300 330 in Europe mandates spectrum efficiency and interference mitigation for short-range devices. The EU Radio Equipment Directive now requires cybersecurity assessments for NFC-enabled connected equipment. Stakeholders must monitor evolving payment-network tokenization standards and sovereign digital-identity frameworks as these will determine which secure-element architectures achieve design wins in next-generation government and financial applications.
Market Dynamics
Mobile payment infrastructure is concentrating demand around secure-element architectures as smartphone OEMs integrate multifunctional NFC controllers into flagship and mid-tier device portfolios simultaneously.
Growth Catalysts
- EU Radio Equipment Directive:Cybersecurity assessment mandates for NFC-enabled connected equipment are accelerating design wins for certified secure-element suppliers in automotive and financial terminals.
- Transit credential digitization:Card emulation technology is eliminating dedicated plastic credentials across Asian metro systems, expanding addressable unit volumes for reader IC vendors.
- China smartphone ecosystem:Domestic OEM expansion of NFC-enabled portfolios is concentrating procurement power and driving 8-inch RF-CMOS foundry investments.
Market Restraints
- Common Criteria certification timelines:Banking-grade tamper resistance requirements extend product development cycles by 18-24 months and concentrate supply among pre-qualified vendors.
- 8-inch wafer capacity constraints:RF-CMOS production bottlenecks at mature-node foundries limit supply elasticity during demand surges.
- Bluetooth Low Energy substitution:Device pairing and short-range data exchange applications are migrating to BLE-UWB combinations in premium automotive keyless entry systems.
Strategic Opportunities
- Sovereign digital identity frameworks:Government-issued mobile credentials in the European Union and Gulf Cooperation Council states are creating new secure-element procurement channels.
- India payment infrastructure:UPI-NFC convergence and RuPay contactless expansion are opening volume opportunities in a historically underpenetrated terminal market.
- Automotive digital key standardization:CCC Digital Key specification adoption is converging NFC with UWB and BLE in unified access control modules.
Industry Challenges
- RF-CMOS analog design talent scarcity:Mixed-signal expertise for 13.56 MHz front-end optimization is concentrated among a shrinking pool of experienced architects.
- Payment network tokenization fragmentation:Proprietary implementations by Visa, Mastercard, and domestic schemes complicate secure-element firmware development and recertification.
- Legacy terminal infrastructure refresh cycles:EMV migration completion in mature markets has extended replacement timelines for merchant reader hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NFC Reader Ics Market |
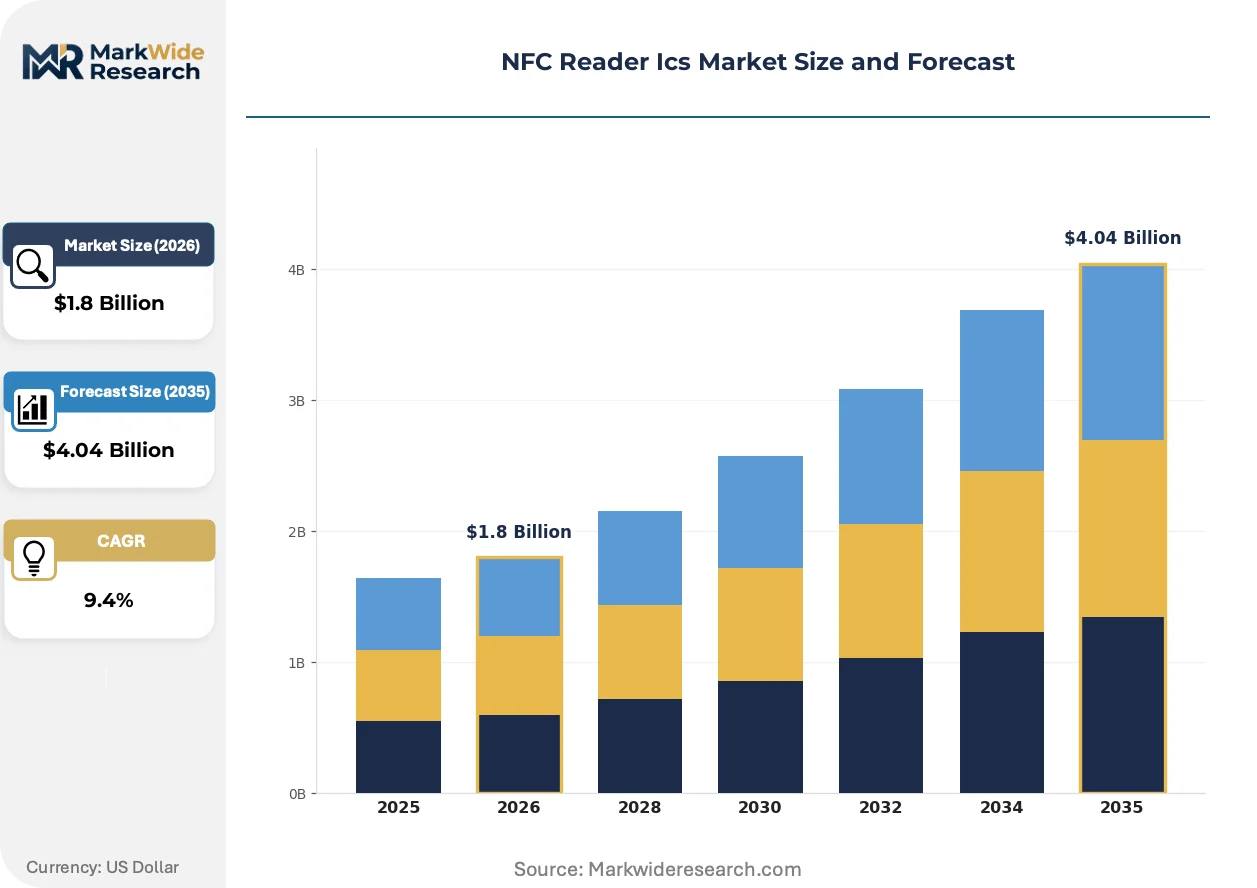
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contactless Readers, Secure Elements, NFC Controllers, NFC Antennas Technology: Passive NFC, Active NFC, Peer-to-Peer, Card Emulation End User: Retail, Transportation, Healthcare, Automotive Application: Mobile Payments, Access Control, Smart Posters, Data Exchange |
| Companies Covered | NXP Semiconductors, STMicroelectronics, Infineon Technologies, Broadcom, Texas Instruments, Qualcomm Technologies, Renesas Electronics Corporation, Sony Corporation, Microchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NFC Reader Ics Market Shifts & Advancements
Architectural consolidation around software-defined secure elements is compressing hardware differentiation while expanding firmware monetization opportunities for incumbent suppliers.
Embedded secure elements with integrated biometric authentication pipelines are digitizing physical access and payment authorization workflows. Transit authorities in Singapore and South Korea are deploying these modules for fare gate and turnstile retrofits. The technology is digitizing credential issuance and revocation processes that previously required plastic card distribution networks.
ETSI EN 300 330 spectrum efficiency mandates are tightening spurious emission limits for short-range devices operating in the 13.56 MHz band. European terminal manufacturers are redesigning RF front-end matching networks to maintain interoperability margins. Automotive OEMs supplying the EU market are pre-certifying combined NFC-UWB modules under the updated framework.
Merchant acquirers are unbundling terminal hardware from payment processing contracts and shifting toward subscription-based device-as-a-service models. ISOs and payment facilitators in the United States are consolidating procurement through aggregator platforms. This restructuring is most visible among mid-market retail chains seeking operational expenditure predictability over capital-intensive POS refresh programs.
NFC Reader Ics Market Segmentation
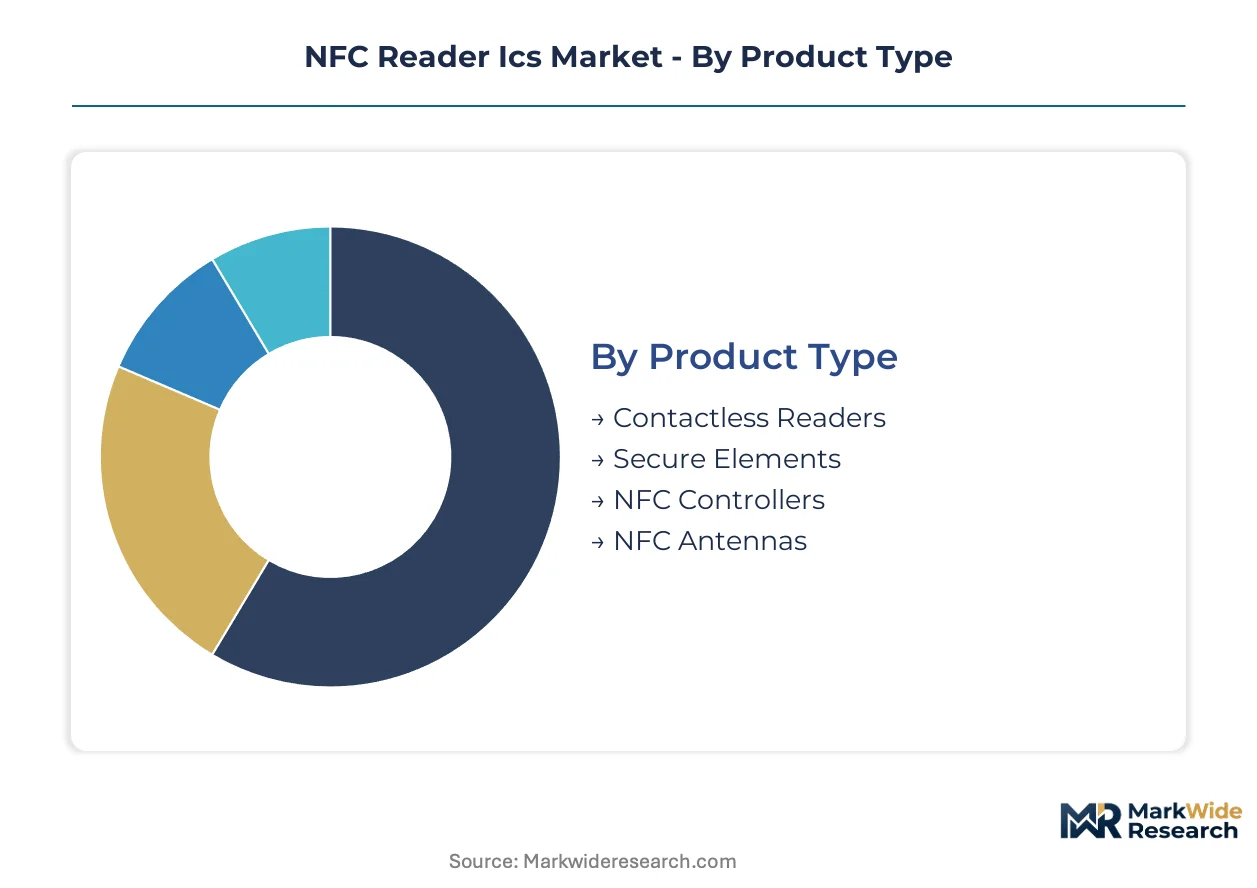
NFC reader IC segmentation reveals how architectural choices cascade through certification requirements, foundry partnerships, and end-use qualification timelines. Product type and technology selections determine whether suppliers compete on volume economics or secure-element premiums.
Product Type:
Cost tier differentiation separates commodity RF components from banking-grade secure modules with Common Criteria certification.
- Secure Elements:These tamper-resistant modules embed cryptographic engines and hardware-isolated credential storage. Demand concentrates in EU automotive keyless-entry systems where the Radio Equipment Directive mandates cybersecurity assessments for connected equipment.
- NFC Controllers:Mixed-signal devices integrate 13.56 MHz RF front-ends with protocol handlers for ISO 14443 and ISO 18092 compliance. Chinese smartphone OEMs are driving procurement volume as domestic foundries expand 8-inch RF-CMOS capacity.
- Contactless Readers:Terminal-integrated modules for payment and access applications.
- NFC Antennas:Passive inductive components optimized for specific form-factor constraints.
Secure elements hold installed capacity in financial terminals. NFC controllers are rotating up the share rankings through smartphone integration.
Technology:
Application requirements dictate power budgets, latency tolerance, and whether devices initiate or respond to RF field activation.
- Card Emulation:Host-card emulation and secure-element-based credential presentation enable smartphones to substitute physical transit and payment cards. Asian metro authorities in Singapore and South Korea are eliminating plastic credential issuance through this technology.
- Peer-to-Peer:Symmetric link establishment supports device pairing and authenticated data exchange without network infrastructure. Automotive OEMs are converging this with UWB and BLE under CCC Digital Key specifications for unified access control.
- Passive NFC:Reader-powered operation for tags and simple credentials.
- Active NFC:Battery-assisted transmission for extended range or higher data rates.
Card emulation holds installed capacity in transit infrastructure. Peer-to-peer is rotating up the share rankings through automotive digital key adoption.
End User:
Customer type determines certification depth, with financial and automotive applications demanding banking-grade tamper resistance.
- Retail:Merchant terminals and POS infrastructure drive volume demand for contactless readers. India's UPI-NFC convergence and RuPay contactless expansion are opening procurement channels in a historically terminal-constrained market.
- Automotive:Digital key modules and secure vehicle access systems command premium margins. FCC Part 15 rules in the United States govern transmitter power limits for reader IC certification in this segment.
- Transportation:Fare collection and credential management systems.
- Healthcare:Patient identification and equipment pairing applications.
Retail holds installed capacity in terminal deployments. Automotive is rotating up the share rankings through connected vehicle mandates.
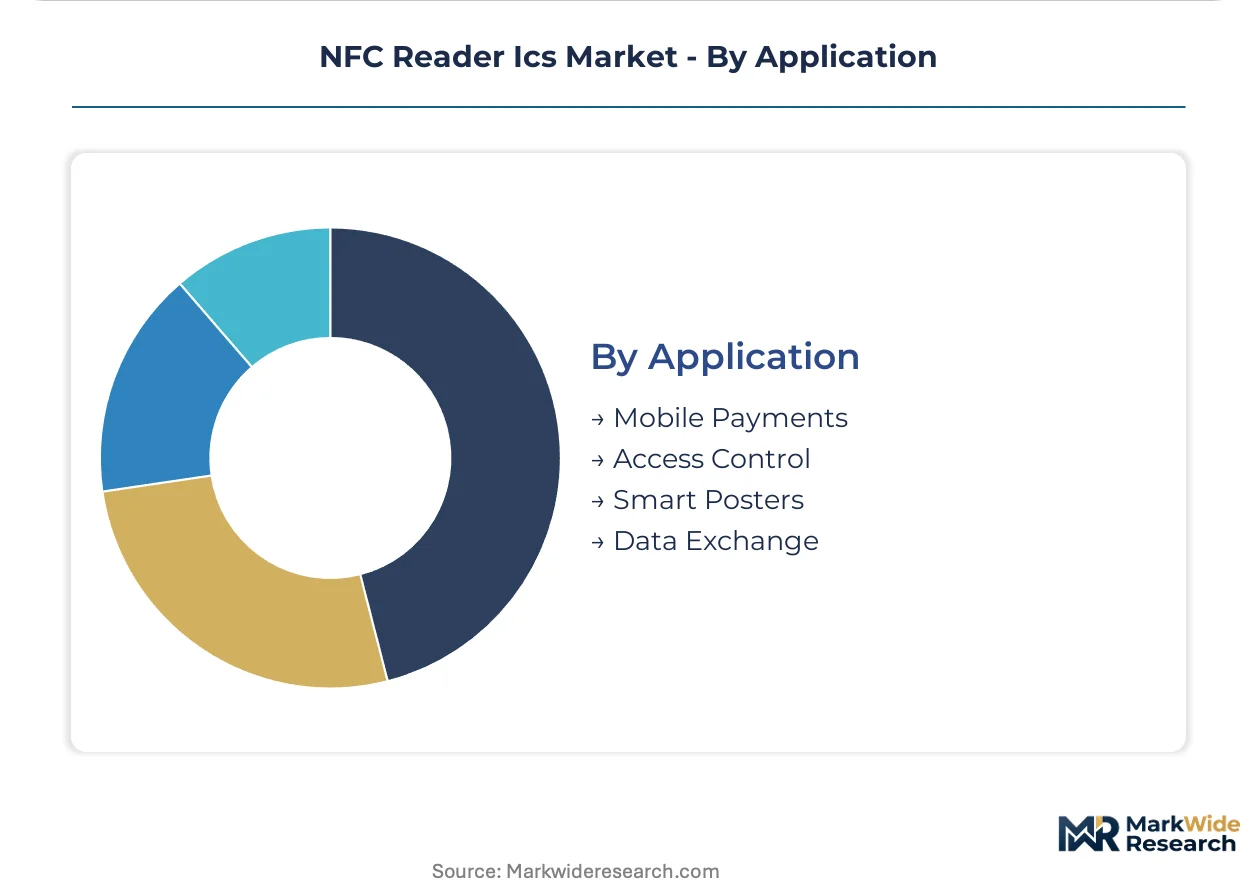
Application:
Volume concentration varies by whether implementations require network-tokenized payment authorization or offline credential verification.
- Mobile Payments:Smartphone-integrated NFC enables contactless transaction authorization through EMV tokenization. Payment network fragmentation between Visa, Mastercard, and domestic schemes complicates secure-element firmware development.
- Access Control:Physical and logical security applications span enterprise, residential, and automotive contexts. Gulf Cooperation Council states are deploying government-issued mobile credentials through sovereign digital identity frameworks.
- Data Exchange:Device-to-device content transfer and Bluetooth pairing initiation.
- Smart Posters:Marketing and information retrieval through tag interaction.
Mobile payments hold installed capacity in consumer device integration. Access control is rotating up the share rankings through government credential digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 rules in the United States anchor the regulatory framework for NFC reader IC certification, while the EU Radio Equipment Directive and China's MIIT standards create parallel compliance corridors that shape regional competitive positioning.
United States
Mobile payment infrastructure expansion and automotive digital key adoption drive procurement volume for secure-element architectures. FCC Part 15 governs unintentional radiator limits and transmitter power certification for reader ICs deployed in payment terminals and vehicle access modules. Silicon Valley clusters concentrate fintech-terminal integration activity, while Detroit-area automotive OEMs pre-certify combined NFC-UWB modules for connected vehicle platforms.
China
Domestic smartphone OEMs are expanding NFC-enabled device portfolios across flagship and mid-tier segments simultaneously. MIIT sets electromagnetic compatibility and spectrum efficiency requirements for short-range devices operating at 13.56 MHz. The Yangtze River Delta anchors RF-CMOS foundry investments, with Shanghai and Suzhou fabs expanding 8-inch capacity to meet concentrated procurement demand from local device manufacturers.
Germany
Automotive keyless-entry systems and industrial IoT credential management sustain demand for Common Criteria-certified secure elements. KBA coordinates with EU regulators on cybersecurity assessment implementation under the Radio Equipment Directive for connected vehicle components. Bavaria's automotive electronics corridor, centered on Munich and Ingolstadt, hosts pre-certification testing for unified NFC-UWB-BLE access control modules.
South Korea
Transit credential digitization and government mobile identity frameworks accelerate card-emulation technology deployment. MFDS oversees device certification while the national digital ID program creates secure-element procurement channels. Seoul Capital Area foundries are expanding 8-inch RF-CMOS capacity to capture smartphone controller demand, with Pangyo and Suwon clusters specializing in mixed-signal analog design.
India
UPI-NFC convergence and RuPay contactless expansion are opening terminal market opportunities in a historically hardware-constrained payments infrastructure. RBI regulates payment system security standards while the PLI scheme incentivizes domestic electronics manufacturing. Karnataka's Bangalore cluster hosts terminal integration activity, with Gujarat and Tamil Nadu emerging as contract manufacturing locations for merchant reader hardware.
NFC Reader Ics Market Competitive Landscape
IDM-heavy semiconductor conglomerates and secure-element specialists split the market between volume-driven controller production and premium-certified module supply. The vendor base concentrates among pre-qualified suppliers capable of navigating 18-24 month Common Criteria certification timelines for banking-grade applications. Three archetypes dominate: vertically integrated European IDMs with captive secure-element IP, Asia-Pacific foundry-affiliated controller suppliers, and mixed-signal specialists with RF-CMOS analog design depth. Competitive moves center on strategic partnerships for automotive digital key standardization and capacity reservations at 8-inch RF-CMOS foundries.
Within the IDM tier, NXP Semiconductors and STMicroelectronics exemplify secure-element architecture leadership, with the former representing automotive keyless-entry application dominance and the latter anchoring European supply through dedicated wafer fabrication. Infineon Technologies occupies a position bridging industrial IoT credential management and payment terminal security, reflecting the German industrial electronics heritage.
| Leading Market Players |
|---|
| NXP Semiconductors |
| STMicroelectronics |
| Infineon Technologies |
| Broadcom |
| Texas Instruments |
| Qualcomm Technologies |
| Renesas Electronics Corporation |
| Sony Corporation |
| Microchip Technology |
| Others |
Supply & Pricing Matrix
Shanghai-to-Rotterdam container freight corridors transmit cost volatility through 8-inch wafer procurement, concentrating margin pressure on RF-CMOS controller suppliers while amplifying price spreads between Common Criteria-certified secure elements and commodity NFC components.
Pricing Analysis
Geographic price spreads between EU-certified automotive modules and Asian smartphone controllers exceed three-to-one ratios. Three-tier pricing structure across banking-grade secure elements, industrial controllers, and consumer-grade readers reflects Common Criteria certification depth and foundry node maturity. Cost compression in mid-tier smartphone controllers is intensifying because Chinese OEMs consolidate procurement through domestic aggregator platforms. Merchant acquirers exhibit highest price sensitivity as terminal hardware unbundling shifts capital expenditure toward operational expenditure models.
Supply Chain Analysis
Silicon feedstock draws from polysilicon purification in China, Germany, and the United States before wafering operations in Taiwan and South Korea. RF-CMOS production rests on 200mm silicon wafers, specialty analog IP libraries, and noble metal sputtering targets for antenna metallization. Single-source vulnerability concentrates in 8-inch foundry capacity at mature nodes where mixed-signal expertise is tethered to shrinking architect pools. Distribution runs through IDM direct sales for automotive OEMs and merchant acquirer aggregator platforms for retail terminal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF-CMOS analog design expertise has contracted to a handful of experienced architects, creating structural bottlenecks that favor incumbents with captive talent pipelines and forcing new entrants toward firmware differentiation rather than hardware innovation.
For Market Incumbents: Build certification moats through accelerated Common Criteria EAL5+ investment cycles before EU Radio Equipment Directive mandates harden procurement requirements. Secure 8-inch foundry capacity reservations at Yangtze River Delta and Seoul Capital Area fabs to preempt RF-CMOS supply crunches. Counter BLE-UWB substitution threats in automotive digital key applications by pre-integrating peer-to-peer protocols under CCC Digital Key specifications. For New Entrants and Emerging Players: India's UPI-NFC terminal retrofit wave represents the most penetrable entry point for controller suppliers lacking secure-element certification depth. Government mobile credential pilots in Gulf Cooperation Council states offer white-space procurement channels outside incumbent banking-grade strongholds. Pursue device-as-a-service partnerships with payment facilitators to bypass capital-intensive merchant hardware refresh cycles. For Investors and Strategic Acquirers: Mixed-signal specialists with embedded biometric authentication pipelines present acquisition profiles aligned with transit authority modernization budgets and sovereign digital identity framework rollouts. Long-term viability hinges on automotive OEM consolidation around unified NFC-UWB-BLE access modules versus fragmentation into single-protocol implementations. Monitor CCC Digital Key specification adoption rates as inflection indicator for controller architecture standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Secure-Element Certification Acceleration | EU Radio Equipment Directive cybersecurity assessments favor pre-qualified suppliers in automotive and financial terminal procurement. |
| 8-inch RF-CMOS Capacity Reservation | Foundry partnerships at Shanghai and Suwon fabs insulate supply elasticity against smartphone OEM demand surges. |
| Biometric Authentication Pipeline Integration | Singapore and South Korea transit authorities deploy embedded modules for fare gate retrofit programs. |
| CCC Digital Key Pre-Certification | Automotive OEMs in Bavaria and Detroit converge NFC with UWB and BLE under unified access control specifications. |
| UPI-NFC Terminal Partnership | RuPay contactless expansion opens procurement channels in India's historically hardware-constrained payment infrastructure. |
Research Methodology
Initial hypotheses were tested against primary input from semiconductor platform engineers, payment terminal procurement managers, automotive OEM access system architects, and RF-CMOS foundry operations directors and refined through secondary validation against SEC 10-K filings, MIIT electromagnetic compatibility disclosures, ETSI EN 300 330 regulatory updates, and customs trade data for 13.56 MHz component flows. Bottom-up unit demand estimates triangulated against top-down value projections across the analysis window.
Demand-supply-balance framing anchored the analytical framework across product type, technology mode, end-use vertical, and regional regulatory cluster dimensions. CAGRs were derived from segment-level volume trajectories and value-per-unit erosion curves. Forecast inputs incorporated EMV tokenization standard evolution, sovereign digital identity framework deployment schedules, and automotive digital key specification adoption curves without year-specific anchoring.
Practitioners should monitor Common Criteria certification queue lengths, 8-inch foundry utilization rates, and BLE-UWB substitution signals in premium automotive platforms for early signals of forecast revision. Cross-checking against IHS Markit vehicle production databases and RBI payment system security circulars is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
United States Analog Integrated Circuits Market
IC (Integrated Circuits)
Energy Metering IC Chip Market
IC (Integrated Circuits)
Monolithic Microwave IC (MMIC) Market
IC (Integrated Circuits)
LED Driver IC Market
IC (Integrated Circuits)
Global Application Specific Consumer Analog Integrated Circuit Market
IC (Integrated Circuits)
Global Special Purpose Logic IC Market
IC (Integrated Circuits)
South Korea Analog Integrated Circuits Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
United States Integrated Circuits Market
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market
IC (Integrated Circuits)
Motor Driver IC Market
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market
IC (Integrated Circuits)
Rugged IC Market
IC (Integrated Circuits)
Global Amplifier and Comparator IC Market
IC (Integrated Circuits)
Asia Pacific Logic IC Market
IC (Integrated Circuits)
Americas Analog IC Market