
 Smart Gate Driver Market | 2026-2036
Smart Gate Driver Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Gate Driver Market Insights
Silicon carbide is consolidating its position as the preferred substrate material over traditional silicon in high-frequency gate driver designs, compressing switching losses and enabling compact thermal management. Infineon Technologies leverages its captive SiC wafer supply to anchor premium automotive design-ins. Texas Instruments competes through integrated isolation and protection IP that simplifies BOM complexity for mid-range industrial customers.
A smart gate driver is a specialized power electronics integrated circuit that translates low-voltage control signals into precisely timed high-current gate pulses, typically delivering 2-10 A peak drive capability with propagation delays below 50 ns to switch power transistors efficiently. Its primary commercial purpose is to protect expensive power stages from shoot-through, overcurrent, and thermal runaway while maximizing switching frequency and efficiency in inverter and converter topologies. SiC drivers currently command the strongest margin pools as automotive OEMs qualify them for 800 V traction inverters, while GaN drivers represent the fastest-growing category as consumer adapter and server power supply designs push beyond 100 kHz. Capacitive isolation technology leads volume shipments due to cost scalability, though optical isolation sustains dominance in safety-critical rail and medical applications where reinforced isolation ratings are mandatory.
FDA device safety standards, EPA industrial efficiency mandates, and AEC-Q100/Q101 automotive qualification frameworks collectively shape product roadmaps, certification timelines, and customer access requirements across the supply chain. The EU Green Deal and F-Gas Regulation are accelerating demand for efficient power conversion in heat pump and HVAC systems, tightening efficiency thresholds that gate driver architectures must enable. Stakeholders should monitor SiC substrate supply agreements and isolation technology patent positions as these will determine which suppliers capture design wins in next-generation electrification platforms.
Market Dynamics
The transition from silicon to silicon carbide power devices is compressing switching losses and forcing gate driver architectures to evolve propagation delay specifications below 40 nanoseconds. This substrate migration is redrawing competitive boundaries across automotive traction, renewable inverters, and industrial motor drives.
Growth Catalysts
- Automotive 800 V platforms:OEM qualification programs for traction inverters are pulling SiC gate driver volumes into six-figure annual unit shipments. AEC-Q101 stress testing mandates are accelerating supplier certification cycles.
- EU F-Gas Regulation:Efficiency thresholds for heat pump compressors are tightening, forcing HVAC manufacturers to specify gate drivers capable of 99% inverter efficiency at partial load.
- GaN device maturation:Consumer adapter and server power supply designs above 100 kHz are creating parallel demand for ultra-fast gate drivers with sub-10 ns propagation skew.
Market Restraints
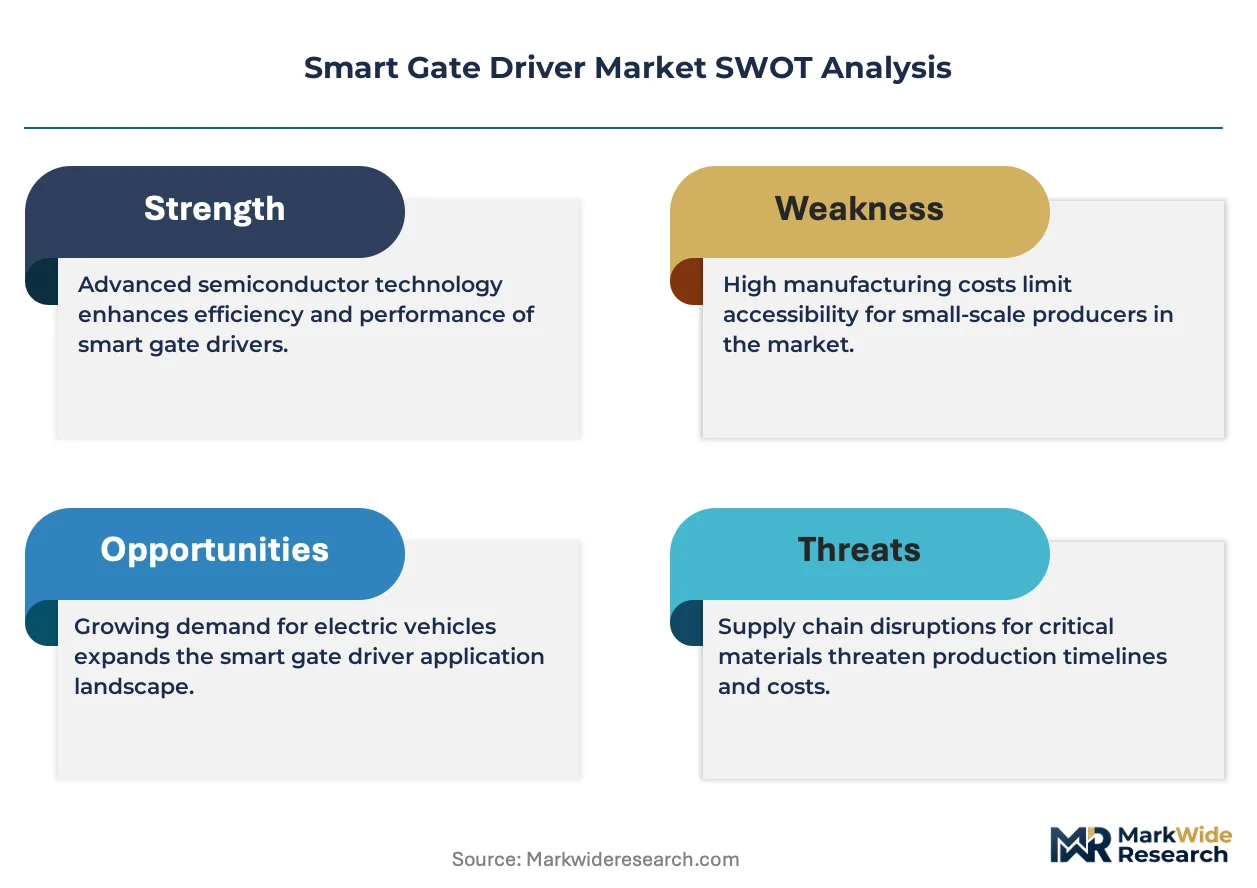
- SiC substrate supply concentration:Wolfspeed, Coherent, and Infineon control over 70% of merchant 150 mm SiC wafer supply, creating allocation risk for second-tier gate driver vendors.
- Isolation technology cost spread:Capacitive isolation dies require specialized foundry capacity at TSMC and GlobalFoundries, limiting cost-down trajectories against optical alternatives.
- GaN reliability qualification gaps:JEDEC standards for GaN power device gate oxide robustness remain incomplete, slowing automotive design-in confidence.
Strategic Opportunities
- India renewable inverter manufacturing:PLI scheme incentives for domestic solar and wind converter production are creating localized gate driver procurement requirements.
- Functional safety integration:Gate drivers with embedded STP and DESAT protection are converging with ISO 26262 ASIL-D requirements, enabling premium pricing in automotive.
- Direct OEM engagement models:Tier-one automotive suppliers are bypassing traditional distribution to negotiate multi-year gate driver supply agreements directly with semiconductor vendors.
Industry Challenges
- Power electronics talent scarcity:Mixed-signal IC designers with expertise in high-voltage isolation and electromagnetic compatibility are concentrated at a handful of universities and incumbent suppliers.
- Automotive qualification timelines:AEC-Q100 Grade 0 thermal cycling and HTOL testing extends product development cycles to 24-36 months, locking working capital.
- IP fragmentation in isolation:Patent thickets around capacitive and magnetic isolation topologies are forcing licensing negotiations or workarounds that add die area.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Gate Driver Market |
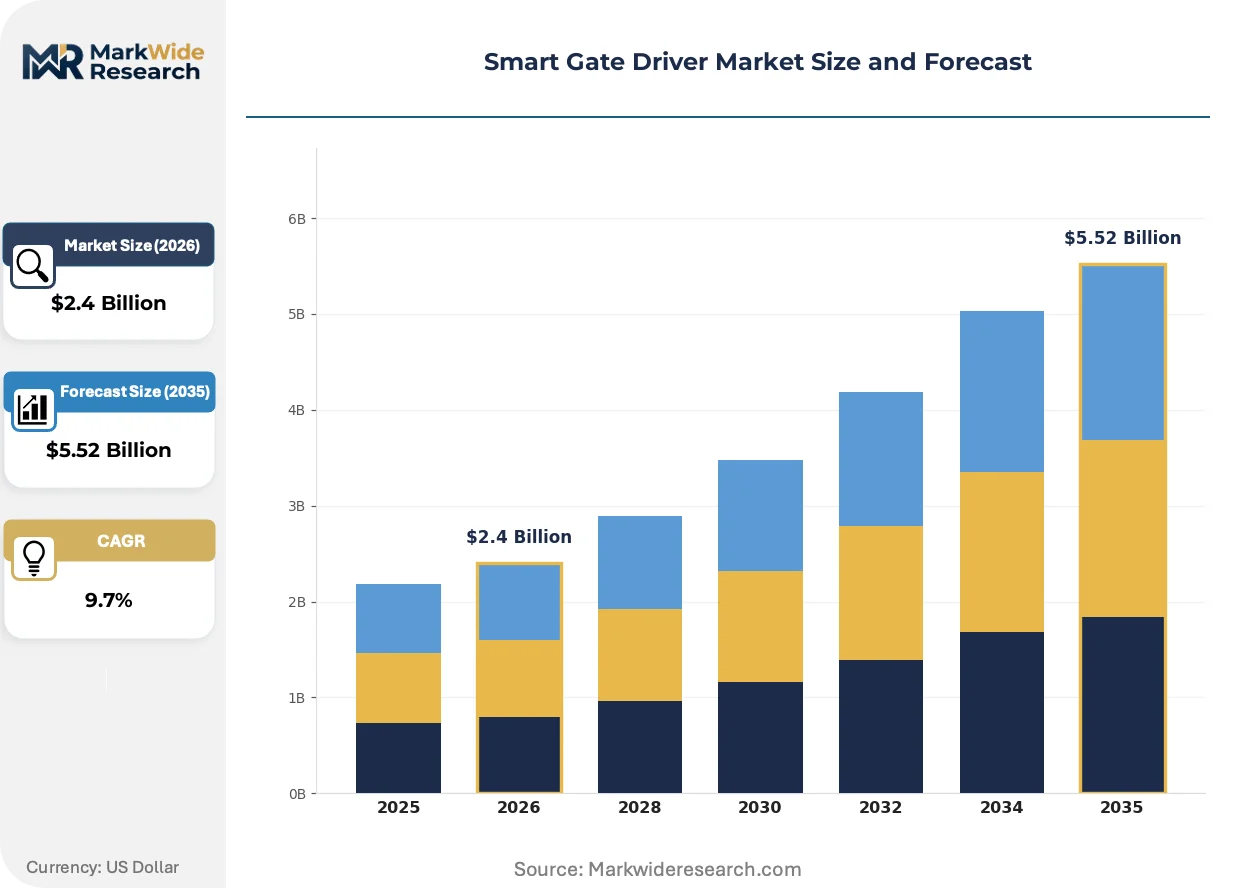
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IGBT Driver, MOSFET Driver, SiC Driver, GaN Driver Technology: Optical Isolation, Isolation Transformer, Capacitive Isolation, Digital Control End User: Automotive, Consumer Electronics, Industrial Automation, Renewable Energy Application: Power Conversion, Motor Control, Lighting Solutions, Uninterruptible Power Supply |
| Companies Covered | Infineon Technologies, Texas Instruments, STMicroelectronics, ON Semiconductor, NXP Semiconductors, ROHM Semiconductor, Analog Devices, Microchip Technology, Renesas Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Gate Driver Market Trends and Innovations
Integration density and functional safety are converging to redefine gate driver value propositions. Vendors are embedding protection, diagnostics, and isolation into single-package solutions that reduce external component counts and accelerate customer time-to-market.
Silicon carbide gate driver ICs are absorbing the thermal and switching stress previously managed by external passive networks. Automotive inverter engineers at tier-one suppliers are specifying these devices for 800 V platforms launching between 2026 and 2028. This absorption of protection functionality into the driver die is eliminating discrete desaturation diodes and Miller clamp circuits from BOMs.
EPA industrial efficiency mandates and the EU Green Deal are tightening minimum performance standards for motor drives and power supplies. Gate driver architectures must now enable 98.5% peak efficiency in variable frequency drives to satisfy compliance thresholds. Industrial OEMs in Germany and the US are responding by qualifying drivers with adaptive dead-time control and active Miller clamping.
Buyer consolidation among automotive tier-ones is compressing supplier negotiation cycles and demanding multi-year price-down commitments. Procurement teams at Bosch, Denso, and Vitesco are unbundling gate driver sourcing from power module purchases to secure direct semiconductor vendor relationships. This pattern is most visible in China, where domestic inverter manufacturers are negotiating captive capacity agreements with Infineon and STMicroelectronics.
Smart Gate Driver Market Segmentation
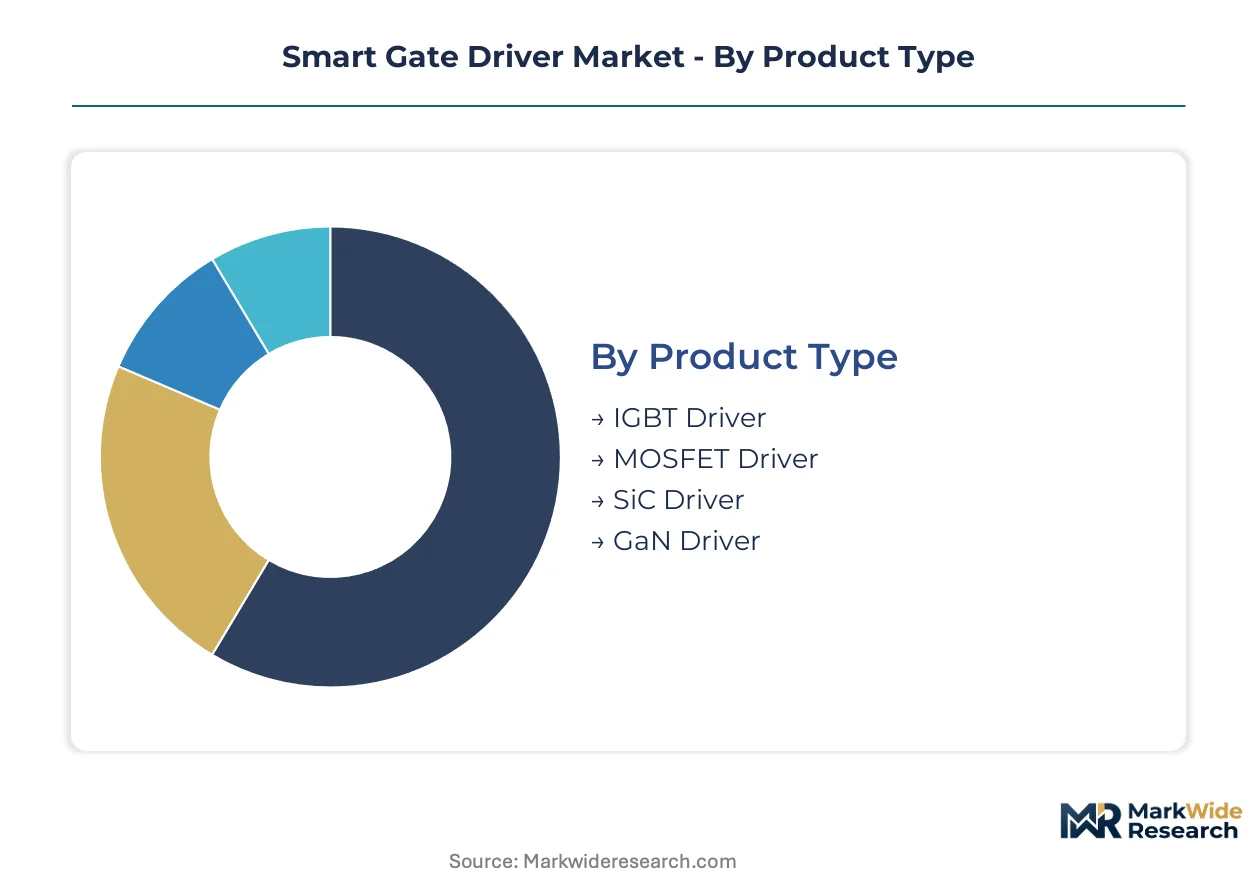
Segmentation in smart gate drivers reveals how qualification burdens, switching frequency demands, and isolation requirements fragment procurement patterns across automotive, industrial, and consumer verticals. Each dimension carries distinct certification roadmaps and margin structures that determine supplier competitiveness.
Product Type:
IGBT drivers carry AEC-Q100 Grade 0 thermal cycling mandates for automotive traction inverters, while SiC and GaN variants face evolving JEDEC qualification gaps that extend design-in timelines for safety-critical applications.
- IGBT Driver:Mature trench-gate and field-stop architectures dominate 400 V automotive inverters and industrial motor drives. Demand concentrates in Germany and Japan where tier-one automotive suppliers qualify these devices for hybrid powertrains under AEC-Q100 stress testing protocols.
- SiC Driver:Delivers 2-10 A peak current with sub-40 ns propagation delay to match silicon carbide switching speeds. Procurement in China is accelerating as domestic OEMs scale 800 V traction inverter production and negotiate captive wafer supply agreements.
- MOSFET Driver:Cost-optimized designs for sub-100 kHz industrial and consumer applications. Volume shipments track China appliance manufacturing and India motor drive localization under PLI scheme incentives.
- GaN Driver:Ultra-fast sub-10 ns propagation skew enables 100+ kHz switching in server power supplies and compact adapters. Reliability qualification gaps slow automotive adoption despite superior efficiency metrics.
Leading the category by volume: IGBT Driver. Growing fastest: SiC Driver.
Technology:
Isolation technology selection determines foundry partnerships, die area costs, and regulatory compliance pathways across medical, rail, and automotive safety tiers.
- Capacitive Isolation:CMOS-compatible processes at TSMC and GlobalFoundries enable cost scaling for high-volume industrial and consumer applications. Supply concentration at specialized foundry nodes limits price-down trajectories against optical alternatives.
- Optical Isolation:Reinforced isolation ratings satisfy FDA device safety standards and EU MDR requirements for medical imaging and patient-contact equipment. Dominates safety-critical rail signaling where failure modes must be deterministic.
- Isolation Transformer:Magnetic coupling architectures deliver high common-mode transient immunity for harsh industrial environments. Deployment concentrates in German factory automation and US oilfield power conversion.
- Digital Control:Integrated SPI interfaces and adaptive dead-time algorithms enable firmware-configurable protection thresholds. Adoption accelerates in automotive where ISO 26262 ASIL-D functional safety integration commands premium pricing.
Widest deployment: Capacitive Isolation. Steepest expansion trajectory: Digital Control.
End User:
End-user concentration shapes pricing power, with automotive procurement teams unbundling gate driver sourcing from power module purchases to secure direct semiconductor vendor relationships.
- Automotive:800 V platform qualification programs pull six-figure annual unit shipments. AEC-Q101 stress testing mandates compress supplier certification cycles to 18-24 months.
- Industrial Automation:EPA efficiency mandates and EU Green Deal thresholds force 98.5% peak efficiency specifications. German and US OEMs prioritize adaptive dead-time control and active Miller clamping.
- Renewable Energy:India PLI scheme incentives for domestic solar and wind converter production create localized procurement requirements. Inverter manufacturers in Gujarat and Tamil Nadu negotiate multi-year supply agreements.
- Consumer Electronics:GaN-enabled adapter designs above 100 kHz drive demand for compact, cost-optimized drivers. Volume concentrates with China ODMs serving laptop and smartphone OEMs.
Highest revenue concentration: Automotive. Gaining share fastest: Renewable Energy.
Application:
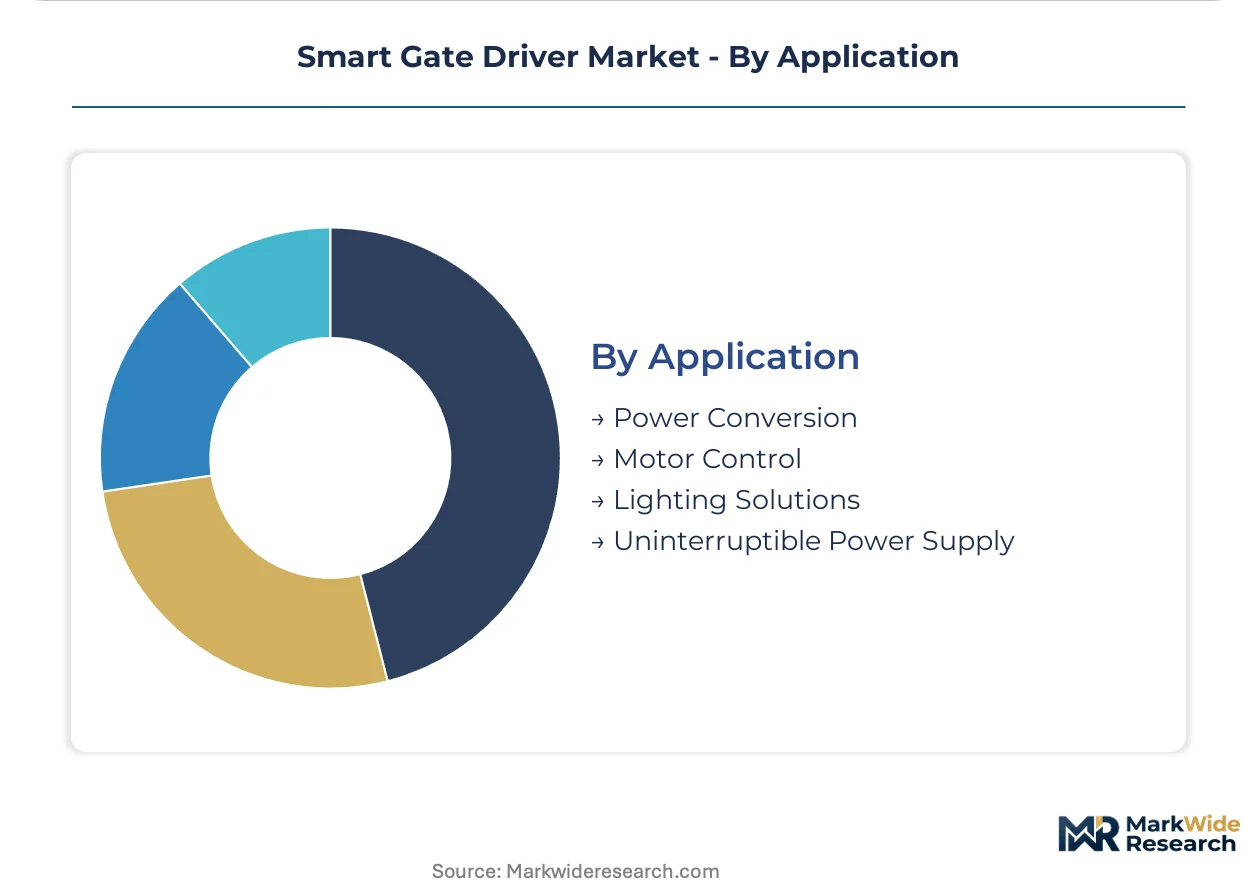
Application-level segmentation exposes divergent switching frequency, thermal cycling, and protection integration requirements that determine BOM complexity and external component counts.
- Power Conversion:Encompasses DC-DC and AC-DC stages in server power supplies, EV onboard chargers, and renewable inverters. China domestic inverter production scales fastest.
- Motor Control:Variable frequency drives for HVAC compressors and industrial machinery face EU F-Gas Regulation efficiency thresholds. Heat pump manufacturers specify 99% inverter efficiency at partial load.
- Uninterruptible Power Supply:Double-conversion online topologies demand robust short-circuit protection and thermal shutdown. Procurement tracks data center buildouts in Virginia, Frankfurt, and Singapore.
- Lighting Solutions:Solid-state ballast and LED driver applications at lower voltage and frequency tiers. Cost pressure from China lighting OEMs favors integrated single-chip solutions.
Dominant by unit volume: Power Conversion. Expanding most quickly: Motor Control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China, where domestic inverter production and renewable energy deployment are scaling fastest. Germany and the United States anchor automotive qualification programs. India and Japan complete the geographic spread with localized manufacturing incentives and tier-one supplier ecosystems.
China
Domestic OEMs are scaling 800 V traction inverter production and negotiating captive wafer supply agreements. The MIIT dual carbon goals accelerate renewable energy deployment and EV powertrain localization. Inverter manufacturers in Shenzhen and Shanghai are driving six-figure annual unit procurement of SiC gate drivers.
Germany
Tier-one automotive suppliers qualify gate drivers for hybrid powertrains under AEC-Q100 stress testing protocols. The EU F-Gas Regulation tightens efficiency thresholds for HVAC compressor applications. Industrial OEMs in Bavaria and Baden-Württemberg prioritize adaptive dead-time control and active Miller clamping for factory automation.
United States
EPA industrial efficiency mandates force 98.5% peak efficiency specifications in variable frequency drives. Data center buildouts in Virginia and Texas pull demand for UPS gate drivers with robust short-circuit protection. Automotive design-ins track 800 V platform launches between 2026 and 2028.
India
PLI scheme incentives for domestic solar and wind converter production create localized procurement requirements. The CEA mandates domestic content in renewable energy projects. Inverter manufacturers in Gujarat and Tamil Nadu negotiate multi-year supply agreements directly with semiconductor vendors.
Japan
METI efficiency standards and automotive tier-one supplier ecosystems sustain demand for high-reliability gate drivers. Industrial motor drive manufacturers in Nagoya and Osaka specify devices for 99% inverter efficiency at partial load. Hybrid powertrain programs maintain IGBT driver volumes.
Smart Gate Driver Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers secure captive SiC wafer supply and specialized foundry partnerships. The vendor base concentrates around integrated device manufacturers with in-house substrate control, fabless specialists with isolation IP, and diversified analog conglomerates with broad automotive portfolios. Strategic archetypes include SiC-integrated incumbents, capacitive isolation specialists, and functional safety integrators. Competitive moves center on multi-year direct OEM supply agreements and ISO 26262 ASIL-D certification acceleration.
Among European-integrated device manufacturers, Infineon Technologies and STMicroelectronics occupy positions anchored by captive SiC wafer supply and premium automotive design-ins. Texas Instruments exemplifies the North American analog conglomerate archetype with integrated isolation and protection IP that simplifies BOM complexity. Japanese diversified electronics suppliers including Renesas Electronics sit within tier-one automotive qualification ecosystems with established AEC-Q100 Grade 0 track records.
| Leading Market Players |
|---|
| Infineon Technologies |
| Texas Instruments |
| STMicroelectronics |
| ON Semiconductor |
| NXP Semiconductors |
| ROHM Semiconductor |
| Analog Devices |
| Microchip Technology |
| Renesas Electronics |
| Others |
Pricing and Supply Chain Analysis
Tier-one automotive procurement teams at Bosch, Denso, and Vitesco command contract-based long-term offtake agreements that compress supplier margins through multi-year price-down commitments. This buyer concentration forces gate driver vendors to absorb cost volatility from captive SiC wafer supply agreements while maintaining AEC-Q101 qualification investments.
Pricing Analysis
High-volume IGBT drivers for 400 V hybrid powertrains trade at economy margins, while SiC drivers for 800 V platforms capture premium pricing through AEC-Q101 Grade 0 certification tiers. Pricing stratifies across automotive-qualified, industrial-grade, and consumer-optimized tiers. Cost compression in the industrial segment intensifies as EPA efficiency mandates force 98.5% peak efficiency specifications without commensurate price tolerance. Consumer electronics buyers exhibit highest price sensitivity, whereas automotive OEMs prioritize qualification track records over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Wolfspeed, Coherent, and Infineon controlling over 70% of merchant 150 mm SiC wafer supply. Raw material dependencies center on high-purity SiC substrates, specialized CMOS foundry capacity at TSMC and GlobalFoundries, and reinforced isolation die materials. Tariff exposure on semiconductor equipment imports threatens cost-down trajectories for capacitive isolation architectures. Distribution runs through direct OEM engagement models that bypass traditional component distribution for multi-year supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around suppliers with captive substrate control and functional safety certification, as AEC-Q101 qualification timelines and SiC supply concentration force weaker players toward exit or acquisition.
For Market Incumbents: Deepen backward integration into SiC wafer supply through captive agreements with Wolfspeed or Coherent, while accelerating ISO 26262 ASIL-D certification pipelines to defend against capacitive isolation specialists encroaching on automotive design-ins. Lock in direct multi-year supply contracts with China-based inverter manufacturers before localized procurement requirements harden under MIIT dual carbon goals. For New Entrants and Emerging Players: Begin with India renewable inverter manufacturing under PLI scheme incentives, where domestic content mandates and nascent supplier ecosystems create procurement openings for qualified gate drivers. Target industrial motor control applications in Germany and the United States, where EPA efficiency mandates and EU F-Gas Regulation tighten specifications faster than incumbent R&D cycles can adapt. Pursue foundry partnerships at GlobalFoundries for capacitive isolation IP to bypass patent thickets held by established vendors. For Investors and Strategic Acquirers: The window for entry favors fabless specialists with magnetic isolation IP and automotive qualification momentum. Long-term viability hinges on substrate supply security and functional safety integration depth over the next decade. Watch for inflection when JEDEC GaN reliability standards finalize, as this will unlock automotive design-in confidence and reshape competitive boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Captive SiC Wafer Supply Agreement | Secures substrate allocation for 800 V traction inverter qualification programs at tier-one automotive suppliers. |
| ISO 26262 ASIL-D Certification Acceleration | Enables premium pricing in automotive by embedding STP and DESAT protection into single-package solutions. |
| Direct OEM Engagement Model | Bypasses distribution to negotiate multi-year supply agreements with China-based inverter manufacturers. |
| Capacitive Isolation Foundry Partnership | Accesses specialized CMOS capacity at TSMC and GlobalFoundries for cost-scalable industrial and consumer applications. |
| India Manufacturing Localization | Captures PLI scheme incentives for domestic solar and wind converter procurement requirements under CEA mandates. |
Research Methodology
Document review covered SEC semiconductor filings, AEC-Q stress testing protocols, and customs trade data, complemented by interviews with power electronics IC design leads, tier-one automotive procurement managers, renewable inverter manufacturing heads, and foundry capacity planners. Secondary validation drew from MIIT dual carbon policy documents, EPA industrial efficiency mandates, and EU F-Gas Regulation thresholds. Bottom-up unit demand estimates from application-level deployment data were triangulated against top-down market sizing from supplier revenue disclosures.
Segment-level outputs across product type, isolation technology, end user, and application dimensions were generated through driver-inverter pairing analysis and qualification timeline modeling. CAGRs were derived from deployment trajectory assumptions tied to EV platform launch schedules and renewable energy buildout targets. Forecast inputs incorporated SiC substrate supply expansion plans, JEDEC GaN reliability standard development status, and foundry capacity allocation announcements.
SiC substrate supply disruptions, delays in JEDEC GaN qualification standards, and automotive platform launch postponements are the dominant revision risks to modeled demand. Forecasts reflect documented assumptions about technology substitution rates and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
AIN DBC Ceramic Substrate Market
Semiconductor Devices
IT & Telecom Discrete Semiconductor Market
Semiconductor Devices
Semiconductor Wafer Frame Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
China MLCC Market
Semiconductor Devices
Semiconductor Memory Market
Semiconductor Devices
Silicon Wafer Market
Semiconductor Devices
Global Small Signal Transistor Market
Semiconductor Devices
Field Effect Transistor Market
Semiconductor Devices
Global Vacuum Capacitors Market
Semiconductor Devices
Graphene Electronics Market
Semiconductor Devices
Middle East Distribution Panel Market
Semiconductor Devices
Europe Semiconductor Device Market
Semiconductor Devices
Gan on Diamond Technology Market
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market