
 Analog IC Market | 2026-2036
Analog IC Market Size, Share, and Industry Trends Forecast 2026-2036
Analog IC Market Analysis
Market Context
East Asian foundry networks is pivoting toward specialty analog processes to serve automotive and industrial clients. Texas Instruments sustains broadest catalog depth across operational amplifiers and voltage regulators. Infineon Technologies anchors European automotive qualification pipelines with AEC-Q100-compliant linear devices. STMicroelectronics leverages vertically integrated fab capacity in France and Italy to control mixed-signal supply.
Technical Definition and Segment Structure
An analog integrated circuit processes continuous electrical signals through transistors, resistors, and capacitors fabricated on a single semiconductor die, typically operating across voltage ranges from millivolts to hundreds of volts with bandwidths spanning DC to multi-gigahertz frequencies. CMOS technology dominates consumer electronics applications where low static power consumption proves decisive, while BiCMOS variants capture premium industrial slots demanding merged analog-digital performance. Automotive Systems application segment draws the fastest investment as OEMs specify grade-zero temperature operation for battery management and motor control. Voltage Regulators product category commands concentrated margin pools due to tight load-transient specifications in data center and telecom power architectures.
Regulatory Environment
EU Green Deal automotive emissions mandates through ECHA substance restrictions and CE marking requirements shape material selection and qualification timelines for European-bound analog components. FDA electromagnetic compatibility standards for medical electronics and FAA DO-160G environmental test criteria for avionics create tiered certification barriers that filter supplier participation. Stakeholders must monitor evolving ISO 26262 functional safety grades as autonomous driving architectures proliferate mixed-signal sensor interfaces.
Market Dynamics
Automotive electrification is forcing analog IC suppliers to requalify entire product portfolios for grade-zero temperature operation, compressing development cycles while expanding addressable content per vehicle.
Growth Catalysts
- EU Green Deal automotive mandates:ECHA substance restrictions under REACH are accelerating replacement of legacy voltage regulators with halogen-free alternatives in German and French automotive supply chains.
- Battery management systems:Lithium-ion cell balancing architectures require precision analog front-ends, pulling signal-conditioning IC demand across electric vehicle platforms.
- Taiwanese foundry specialization:TSMC and UMC are expanding 40nm and 28nm BCD process capacity specifically for power management and motor driver applications.
Market Restraints
- 300mm silicon wafer cost volatility:Raw substrate prices swing with polysilicon spot markets, compressing gross margins for commodity linear regulators.
- East Asian foundry concentration:Over 70% of advanced analog CMOS capacity sits in Taiwan and South Korea, creating single-point-of-failure exposure for European and North American fabless designers.
- ISO 26262 functional safety certification:ASIL-D qualification timelines stretch 18-24 months, freezing product roadmaps for safety-critical automotive interfaces.
Strategic Opportunities
- India PLI scheme for semiconductors:Central government incentives are attracting analog packaging and test investments in Gujarat and Karnataka, creating alternative supply nodes outside East Asia.
- Silicon carbide gate driver integration:Merged analog-digital controllers for 800V EV powertrains represent unclaimed white space between discrete and fully integrated solutions.
- Direct OEM contracting:Tier-1 automotive suppliers are bypassing traditional distribution to negotiate multi-year analog IC supply agreements directly with foundries.
Industry Challenges
- Analog design talent scarcity:Experienced circuit designers capable of noise-optimized layout in advanced nodes command premium compensation, constraining R&D expansion at mid-cap suppliers.
- Legacy system integration friction:New precision ADCs must interface with decades-old 12V automotive harness architectures, requiring voltage level translation and EMI shielding that adds cost and complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Analog IC Market |
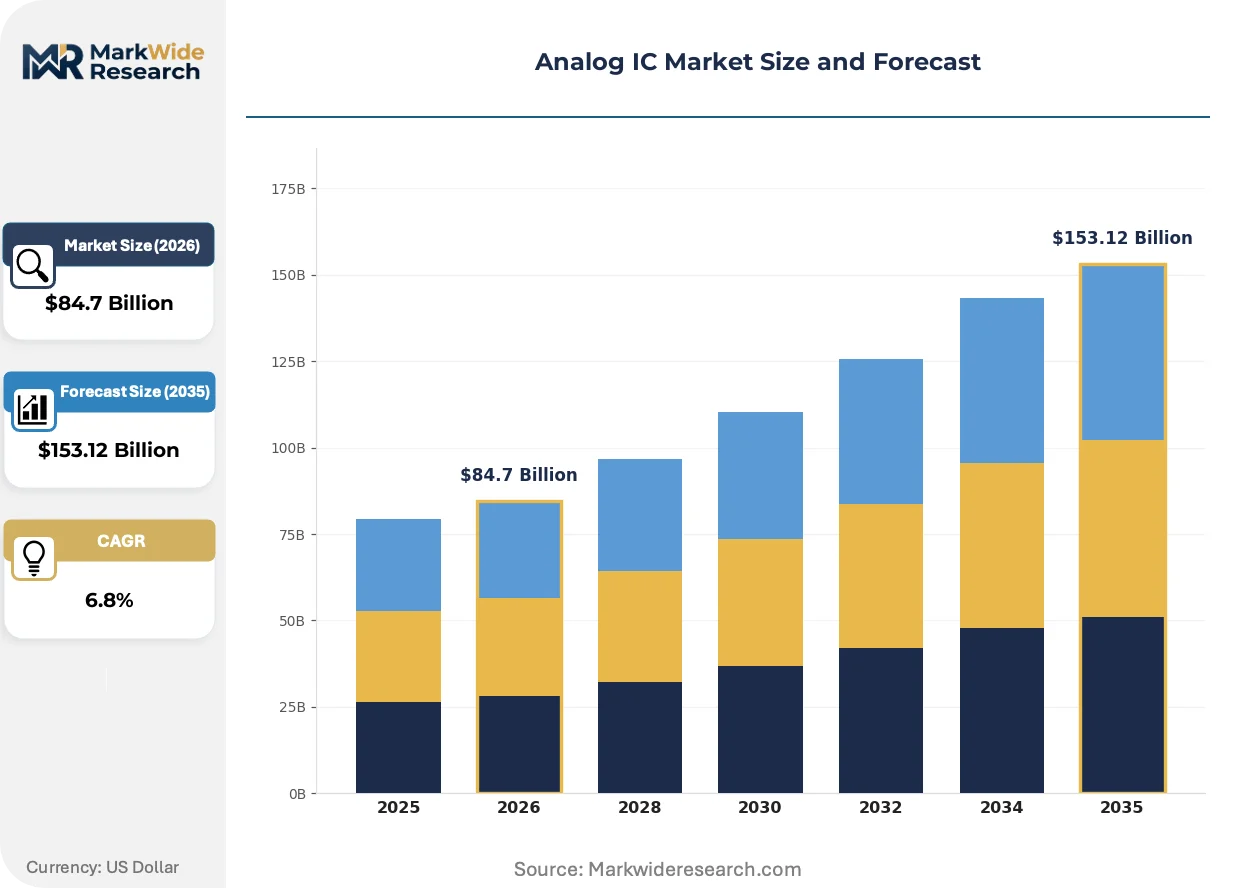
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $153.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operational Amplifiers, Voltage Regulators, Comparators, Linear Devices Technology: BiCMOS, CMOS, BJT, GaAs Application: Consumer Electronics, Automotive Systems, Industrial Equipment, Communication Systems End User: OEMs, Contract Manufacturers, Distributors, Aftermarket Providers |
| Companies Covered | NXP Semiconductors, Renesas Electronics, Texas Instruments, ON Semiconductor, Microchip Technology, Analog Devices, STMicroelectronics, Maxim Integrated, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analog IC Market Emerging Trajectories
Gallium nitride power stages are compressing magnetics size in switching regulators, while artificial intelligence inference at the edge is driving demand for ultra-low-power analog sensor interfaces.
Digital power management controllers with embedded ADCs is integrating real-time loop compensation algorithms that previously required discrete DSP chips. Data center power architects at hyperscale operators are adopting these controllers for 48V bus regulation. The technology is integrating power-stage monitoring with predictive fault detection, collapsing the traditional separation between analog power trains and digital supervision layers.
EU F-Gas Regulation phase-down schedules are banning sulfur hexafluoride in medium-voltage switchgear, forcing analog IC suppliers to develop alternative arc-detection circuits using precision current sensing. Industrial equipment OEMs in Germany and Italy must redesign protection systems by mandated deadlines. High-voltage analog front-ends for SF6-free switchgear now represent the fastest-growing subsegment within industrial signal conditioning.
Automotive OEMs are consolidating analog component suppliers from twenty-plus vendors to fewer than five strategic partners per vehicle platform, compressing qualification overhead but concentrating negotiation leverage. Tier-1 module manufacturers are responding by offering complete analog subsystems rather than discrete ICs. This consolidation is most advanced in German premium electric vehicle programs, where battery management analog content has centralized under single-source agreements.
Analog IC Market Segmentation
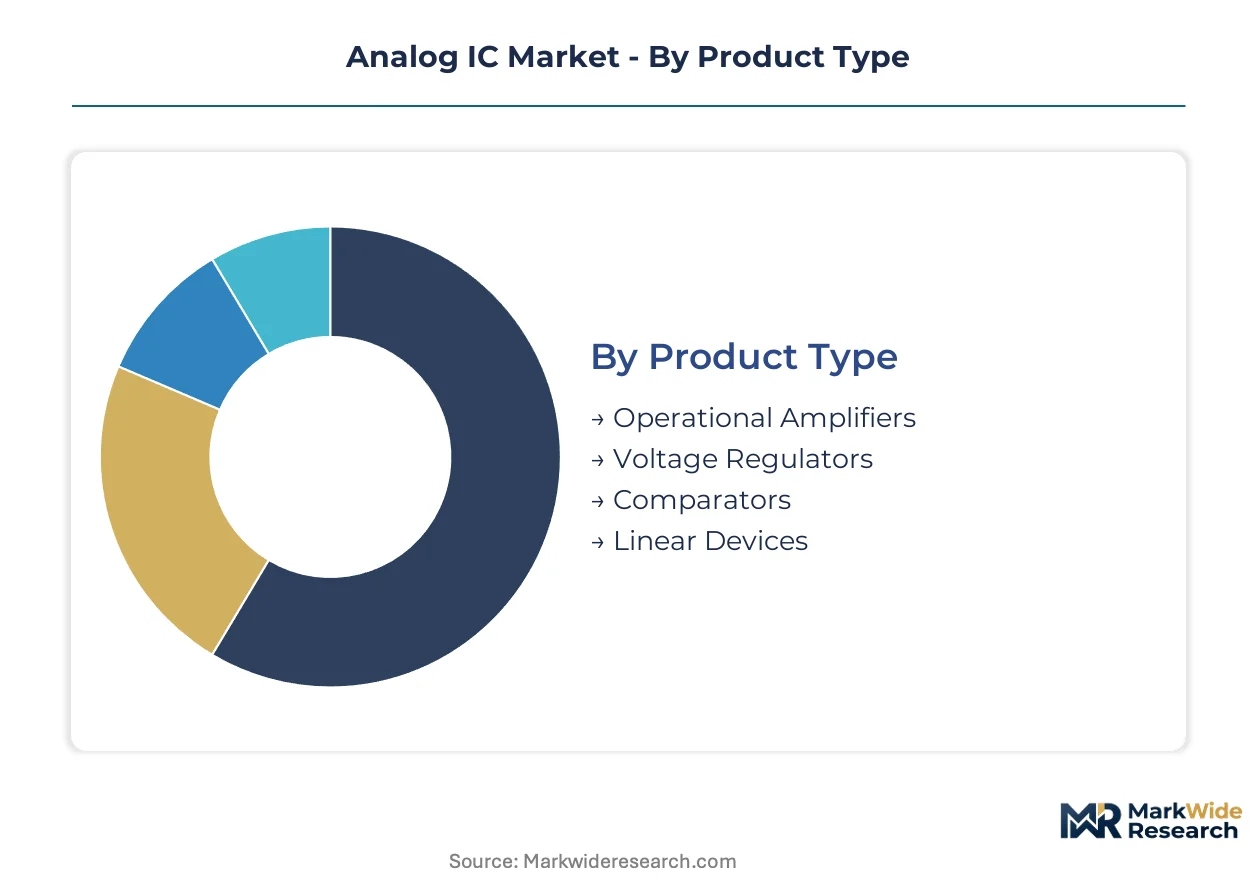
Analog IC purchasing decisions diverge sharply across technical specifications, thermal requirements, and qualification burdens. Each segmentation axis reveals distinct margin structures and supplier concentration patterns that shape competitive positioning.
Product Type:
Buyers differentiate primarily by precision requirements and load-transient response specifications rather than unit economics.
- Voltage Regulators:These devices maintain stable output voltage despite input variations and load changes through feedback control loops. Data center power architects in Virginia and Texas specify tight load-transient windows for 48V bus regulation, pulling demand for multi-phase controllers with embedded telemetry.
- Operational Amplifiers:High-gain differential amplifiers with near-infinite input impedance serve signal-conditioning chains. German automotive suppliers are qualifying zero-drift architectures for battery management front-ends under tightened ECHA substance timelines.
- Comparators:High-speed voltage-level detectors trigger digital logic from analog thresholds. Window-detector variants with integrated references simplify brownout protection in industrial motor drives.
- Linear Devices:General-purpose analog building blocks include buffers, current mirrors, and voltage references. Standard catalog parts face margin compression from Asian merchant suppliers.
Volume sits with Linear Devices; growth tilts toward Voltage Regulators.
Technology:
Process selection trades off power consumption, frequency response, and integration density against foundry availability and mask costs.
- CMOS:Dominant technology for consumer electronics leverages low static power and scalable digital integration. Korean smartphone OEMs specify sub-threshold operation for always-on sensor hubs.
- BiCMOS:Merged bipolar-CMOS processes deliver high transconductance with logic compatibility. Japanese automotive module suppliers are locking 40nm BCD capacity at TSMC for integrated motor drivers.
- BJT:Pure bipolar junction transistors retain niche positions in high-voltage, high-current linear regulators. Legacy fab equipment in Europe sustains limited specialty production.
- GaAs:Gallium arsenide enables millimeter-wave and optical front-ends beyond silicon limits. Defense and telecom infrastructure in the US absorb limited merchant supply.
CMOS commands unit volume; BiCMOS captures value expansion.
Application:
End-use contexts impose divergent temperature ranges, reliability grades, and certification burdens that filter supplier participation.
- Automotive Systems:Grade-zero operation from minus forty to one hundred fifty degrees Celsius with AEC-Q100 qualification. Battery management and motor control content per vehicle is climbing fastest among all application verticals.
- Industrial Equipment:Extended temperature operation with reinforced isolation for factory automation. EU F-Gas Regulation deadlines are forcing redesign of arc-detection circuits in German and Italian medium-voltage switchgear.
- Consumer Electronics:Cost-optimized specifications with rapid product cycles. Wearable device manufacturers in Shenzhen prioritize sub-microamp quiescent current for always-on analog sensor interfaces.
- Communication Systems:Low-noise amplification and precision timing for base stations and optical networks. 5G massive MIMO deployments in South Korea and Japan are pulling demand for high-linearity RF signal chains.
Consumer Electronics holds shipment volume; Automotive Systems shows steepest expansion trajectory.
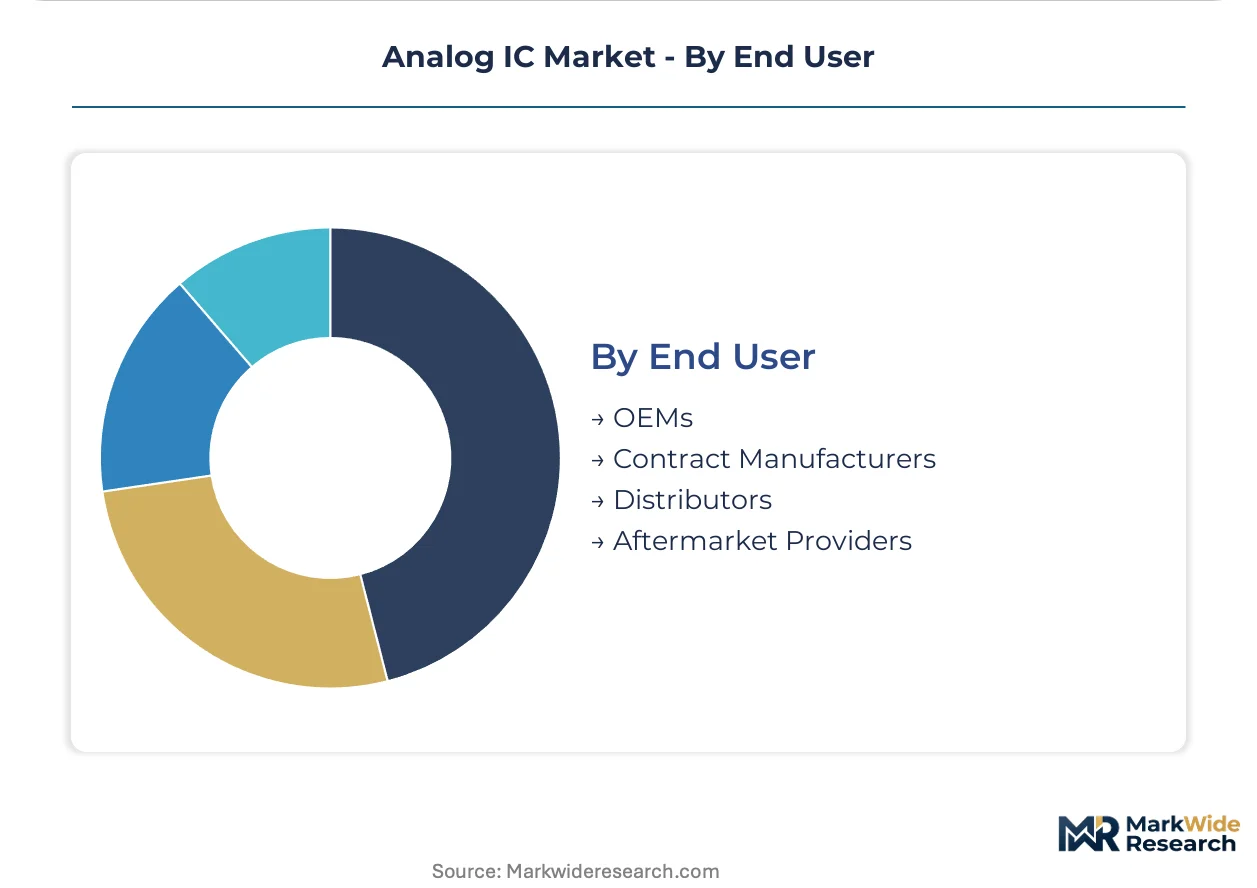
End User:
Channel structure determines pricing leverage, technical support requirements, and inventory risk allocation across the value chain.
- OEMs:Original equipment manufacturers with captive design teams specify custom parametric performance. German premium EV programs are consolidating analog suppliers from fragmented vendor bases to single-source agreements per platform.
- Contract Manufacturers:Electronics manufacturing services providers procure on consignment or turnkey basis. Foxconn and Pegatron operations in Taiwan and Mexico manage buffer stock for consumer electronics brands.
- Distributors:Arrow, Avnet, and WPG Holdings provide technical selection support and inventory financing. Distributor concentration in North America and Europe creates margin pressure on commodity linear parts.
- Aftermarket Providers:Repair and replacement channels for industrial and automotive installed base. Long-tail demand for obsolete automotive-grade parts sustains specialized brokers.
Distributors handle transaction volume; OEMs drive specification value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silicon feedstock from Hallein, Austria anchors European wafer production for precision analog components serving automotive electrification programs.
United States
Virginia and Texas data centers specify tight load-transient windows for 48V bus regulation, pulling demand for multi-phase voltage controllers. FDA electromagnetic compatibility standards for medical electronics create tiered certification barriers that filter supplier participation. Phoenix and Austin clusters concentrate fabless design houses specializing in industrial signal-conditioning architectures.
Germany
Premium electric vehicle platforms are consolidating analog suppliers from fragmented vendor bases to single-source agreements per platform. EU Green Deal automotive mandates through ECHA substance restrictions accelerate replacement of legacy voltage regulators with halogen-free alternatives. Stuttgart and Munich industrial corridors anchor AEC-Q100-compliant linear device qualification pipelines.
Japan
Automotive module suppliers are locking 40nm BCD capacity at foundries for integrated motor driver applications. METI industrial policy supports domestic BiCMOS process development for merged analog-digital performance. Tokyo-Osaka manufacturing belts sustain captive production of high-voltage linear regulators for industrial equipment.
South Korea
Smartphone OEMs specify sub-threshold CMOS operation for always-on sensor hubs in wearable devices. MFDS medical device regulations shape electromagnetic compatibility requirements for diagnostic analog front-ends. Seoul-Incheon semiconductor clusters concentrate advanced foundry capacity for power management ICs.
India
Central government PLI scheme incentives are attracting analog packaging and test investments in Gujarat and Karnataka, creating alternative supply nodes outside East Asia. BIS certification requirements for industrial electronics filter component import approvals. Bangalore and Ahmedabad emerging as mixed-signal design centers serving automotive and telecom clients.
Analog IC Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue silicon carbide gate driver integration and 800V EV powertrain architectures. The vendor base clusters around three maturity tiers: broad-catalog incumbents with captive fab capacity, fabless specialists targeting automotive qualification pipelines, and regional merchant suppliers competing on consumer electronics unit economics. Strategic archetypes include vertically integrated European automotive specialists, East Asian foundry-affiliated power management houses, and diversified North American industrial analog portfolios. Competitive moves concentrate on multi-year direct OEM contracting and BCD process capacity expansion at Taiwanese foundries.
Within the broad-catalog tier, Texas Instruments and Analog Devices exemplify diversified industrial and automotive positioning across operational amplifiers and voltage regulators. Infineon Technologies anchors European automotive qualification pipelines with AEC-Q100-compliant linear devices. STMicroelectronics occupies a position leveraging vertically integrated fab capacity in France and Italy to control mixed-signal supply chains for battery management systems.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Renesas Electronics |
| Texas Instruments |
| ON Semiconductor |
| Microchip Technology |
| Analog Devices |
| STMicroelectronics |
| Maxim Integrated |
| Infineon Technologies |
| Others |
Supply Flow & Price Mechanics
Polysilicon wafer substrate costs cascade through three distinct pricing tiers for analog IC buyers, with 300mm silicon volatility compressing margins on commodity linear regulators while automotive-grade voltage regulators command premium positions through bundled AEC-Q100 qualification support.
Pricing Analysis
Warranty and technical service bundling separates automotive-grade suppliers from merchant competitors, with German OEMs demanding multi-year field failure coverage as standard. Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer-optimized levels reflects certification burden differentials rather than unit economics alone. Cost compression in standard linear devices is intensifying because Taiwanese foundry capacity prioritizes premium BCD processes. Contract manufacturers in Mexico and Taiwan exhibit highest price sensitivity, while German premium EV programs tolerate substantial premiums for single-source reliability guarantees.
Supply Chain Analysis
AEC-Q100 qualification timelines of 18-24 months gate supplier participation, freezing product roadmaps for safety-critical interfaces and concentrating sourcing leverage among pre-qualified vendors. Foundry capacity concentrates in Taiwan, South Korea, and Japan, with TSMC and UMC anchoring advanced BCD process supply. Raw material dependencies span high-purity silicon feedstock from Austria, specialty gases for epitaxy, and gold wire for packaging. Single-source vulnerability runs through Taiwanese foundry concentration exceeding seventy percent of advanced analog CMOS capacity. Distribution runs through Arrow, Avnet, and WPG Holdings for technical selection support and inventory financing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity bottlenecks for automotive-grade BCD processes prop pricing power, with 40nm and 28nm node constraints at TSMC and UMC limiting supply expansion despite OEM demand acceleration.
For Market Incumbents: Anticipate margin pressure from silicon carbide gate driver integration by securing 800V EV powertrain qualification pipelines before emerging entrants achieve ASIL-D certification. Deepen backward integration into captive fab capacity in France, Italy, or Germany to insulate against Taiwanese foundry concentration risk. Prioritize multi-year direct OEM contracting with German and Japanese automotive programs to lock volume commitments. For New Entrants and Emerging Players: Begin with silicon carbide gate driver integration for 800V EV architectures, the fastest-expanding white space between discrete and fully integrated solutions. Target India's Gujarat and Karnataka packaging clusters, where PLI scheme incentives reduce capital barriers for test and assembly investments. Pursue direct foundry partnerships rather than distributor channels to bypass incumbent technical selection control. For Investors and Strategic Acquirers: TSMC BCD capacity allocation announcements are the leading indicator that automotive analog supply constraints will persist or ease. Five-to-ten year viability favors vertically integrated European automotive specialists with captive AEC-Q100 qualification pipelines over fabless competitors exposed to foundry pricing cycles. Monitor Indian PLI scheme disbursement velocity as signal for alternative supply node maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Direct OEM Contracting | Bypasses distributor margin layers and locks volume commitments from German premium EV programs. |
| BCD Process Capacity Expansion | TSMC and UMC investments in 40nm nodes serve automotive motor driver and power management demand. |
| Silicon Carbide Gate Driver Integration | Merged analog-digital controllers address 800V EV powertrain white space between discrete solutions. |
| India PLI Scheme Participation | Gujarat and Karnataka packaging investments create alternative supply nodes outside East Asian concentration. |
| AEC-Q100 Qualification Pipeline Investment | 18-24 month ASIL-D timelines freeze competitor roadmaps and sustain incumbent pricing power. |
Methodological Framework
Document review covered SEC 10-K filings, ECHA REACH substance restriction updates, and foundry capacity announcements from TSMC and UMC, complemented by interviews with analog IC design directors, Tier 1 automotive procurement managers, and industrial equipment OEM technical leads. Secondary validation drew from customs trade data, AEC-Q100 qualification registries, and EU F-Gas Regulation implementation timelines. Bottom-up segment sizing triangulated against top-down semiconductor industry association aggregates.
Segment-level projections across voltage regulators, operational amplifiers, comparators, and linear devices incorporated technology splits between CMOS, BiCMOS, BJT, and GaAs processes. Application segmentation modeled automotive systems, industrial equipment, consumer electronics, and communication systems with distinct thermal and certification requirements. End-user channel structure differentiated OEM direct contracting, contract manufacturer consignment, distributor technical support, and aftermarket broker networks. CAGRs derived from regression against vehicle electrification content curves, data center power architecture transitions, and foundry capacity expansion schedules.
Underlying measurement precision varies by segment; automotive-grade voltage regulators with consolidated OEM sourcing carry tighter precision than fragmented consumer linear devices. Forecasts reflect assumptions about BCD process yield improvements, EU Green Deal implementation velocity, and Taiwanese foundry allocation priorities. A model refresh is warranted upon material change in TSMC automotive capacity expansion announcements or ECHA substance restriction enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market
IC (Integrated Circuits)
Programmable ASIC Market
IC (Integrated Circuits)
Japan Analog IC Market
IC (Integrated Circuits)
Global Special Purpose Logic IC Market
IC (Integrated Circuits)
Global Interface IC Market
IC (Integrated Circuits)
RFID Reader IC Market
IC (Integrated Circuits)
Digital IC Market
IC (Integrated Circuits)
Europe Analog IC Market
IC (Integrated Circuits)
Audio Power Amplifier IC Market
IC (Integrated Circuits)
Americas Analog IC Market
IC (Integrated Circuits)
South Korea Integrated Circuits Market
IC (Integrated Circuits)
Japan Integrated Circuit (IC) Market
IC (Integrated Circuits)
Automotive IC Market
IC (Integrated Circuits)
Global Application Specific Automotive Analog IC Market
IC (Integrated Circuits)
Global Application Specific Computer Analog IC Market
IC (Integrated Circuits)
Memory Integrated Circuits (IC) Market