
 Europe Integrated Circuits Market | 2026-2036
Europe Integrated Circuits Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Integrated Circuits Market Insights
Germany's Dresden-Leipzig semiconductor corridor is rewriting the geographic logic of European chip supply. Infineon Technologies AG anchors high-volume power semiconductor production from its Dresden fab complex. STMicroelectronics N.V. competes through embedded security and automotive microcontroller specialization. NXP Semiconductors N.V. dominates vehicle networking and radar processing for European tier-1 suppliers.
Integrated circuits are miniaturized electronic assemblies of transistors, resistors, and capacitors fabricated on monocrystalline silicon wafers using photolithography, etching, and doping processes, typically measured by node size in nanometers and designed to perform computation, signal processing, or power control functions. Their primary purpose spans consumer devices, automotive systems, industrial machinery, and telecommunications infrastructure where reliable electronic control determines product performance. Power Management ICs command disproportionate margin pools as electrification multiplies voltage regulation needs across every end-use category. Mixed-Signal ICs sustain above-average growth by bridging analog sensor inputs with digital processing in automotive and industrial domains. CMOS technology leads volume production due to its favorable power-delay product and scalability across node generations.
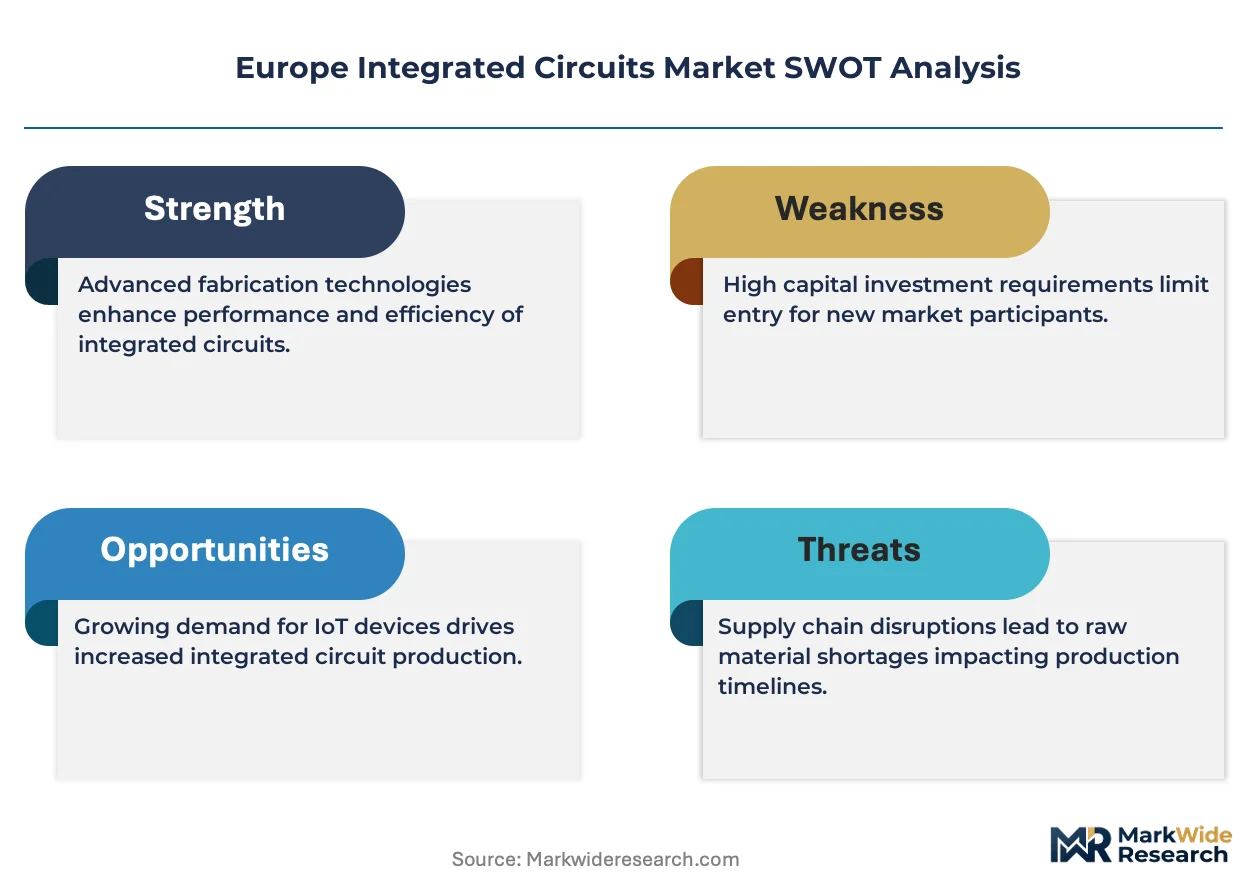
The EU Chips Act, REACH chemical safety standards, and CE marking directives collectively reshape demand by mandating localized production incentives, restricting hazardous substances in semiconductor materials, and enforcing electromagnetic compatibility for market access. ECHA substance restrictions on fluorinated compounds directly affect etching chemistries and cleanroom processes at European fabs. Stakeholders must weigh the capital intensity of EU-funded greenfield fabs against the established cost structures of Asian foundry partnerships when planning capacity additions.
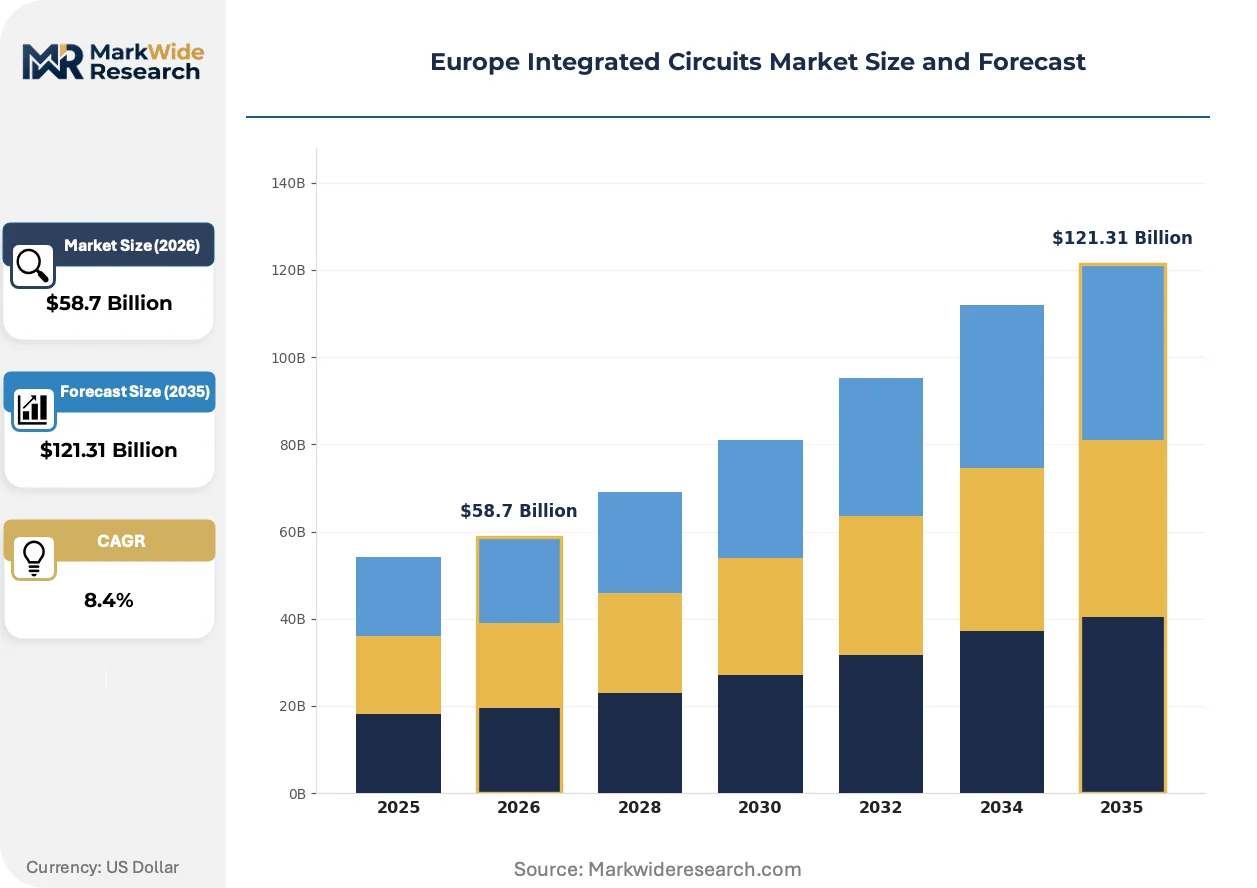
Market Dynamics
EU Chips Act funding is accelerating fab construction timelines across the continent while automotive electrification multiplies semiconductor content per vehicle. This dual pressure is compressing design-to-production cycles and reshaping supplier relationships.
Growth Catalysts
- Automotive electrification:Battery management systems and inverter controls multiply Power Management IC demand across German, French, and Italian OEM supply chains. Voltage regulation complexity rises with each platform generation.
- EU Chips Act capital allocation:Public co-financing for Dresden, Magdeburg, and Crolles greenfield fabs lowers effective cost of capital for 300mm capacity additions. Member states compete for anchor tenant commitments.
- REACH substance restrictions:ECHA fluorinated compound limits are forcing process chemistry substitutions that favor European equipment vendors with local service infrastructure.
Market Restraints
- Neon and palladium supply concentration:Ukrainian and Russian sourcing disruptions for laser gases and catalytic materials create input volatility for photolithography and electroplating operations.
- 300mm wafer equipment lead times:Lithography scanner delivery stretches from 12 to 30 months, constraining EU-funded capacity ramps regardless of capital availability.
- CMOS node scaling economics:Sub-7nm development costs exceed viable returns for European IDMs without foundry scale, capping advanced logic participation.
Strategic Opportunities
- Polish and Romanian packaging corridors:Lower labor costs and EU structural funds position Eastern European countries for advanced substrate and fan-out wafer-level packaging investments.
- GaN-on-Si power integration:Gallium nitride epitaxy on silicon substrates enables 650V automotive inverter applications at silicon cost structures, opening mid-voltage segments.
- CSRD supply chain disclosure:Corporate sustainability reporting mandates create first-mover advantage for European fabs with verified Scope 3 emissions data and renewable energy sourcing.
Industry Challenges
- Process engineer scarcity:Cleanroom operations and yield engineering expertise concentrates among aging workforces in Dresden and Eindhoven, constraining multi-site expansion.
- Automotive qualification timelines:AEC-Q100 Grade 0 certification cycles extend 18-24 months, misaligning semiconductor release schedules with vehicle platform launches.
- Legacy vehicle architecture integration:Domain controller consolidation requires backward compatibility with 12V electrical systems and CAN bus protocols, complicating silicon definition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Integrated Circuits Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog ICs, Digital ICs, Mixed-Signal ICs, Power Management ICs Technology: CMOS, BiCMOS, Bipolar, SOI Application: Consumer Electronics, Automotive Electronics, Industrial Automation, Communication Equipment End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Distributors |
| Companies Covered | Infineon Technologies AG, STMicroelectronics N.V., NXP Semiconductors N.V., Texas Instruments Inc, Analog Devices Inc, Intel Corporation, ON Semiconductor Corporation, Microchip Technology Inc., Renesas Electronics Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Integrated Circuits Market Trends and Innovations
Process-node specialization is fragmenting as automotive reliability requirements diverge from mobile performance metrics. European IDMs are optimizing for voltage tolerance and thermal cycling rather than transistor density alone.
Chiplets are collapsing the monolithic die economics that dominated automotive microcontroller design for two decades. German tier-1 suppliers now specify multi-die packages with standardized interconnects to mix process nodes within single control units. This modularity reduces retooling costs when functional blocks require updates.
F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon replacement in etch and chamber cleaning processes. European fabs must qualify fluorine-free chemistries by 2030, driving equipment retrofits and process requalification. Memory and logic production lines face disproportionate disruption given their higher chamber cleaning frequency.
Automotive procurement is consolidating supplier panels as OEMs reduce qualified vendor lists for critical semiconductors. Long-term offtake agreements with minimum volume guarantees are displacing spot market purchases for power discretes and MCUs. This shift is most visible in German and Swedish OEM direct material strategies, where supply security now outweighs unit cost minimization.
Europe Integrated Circuits Market Segmentation
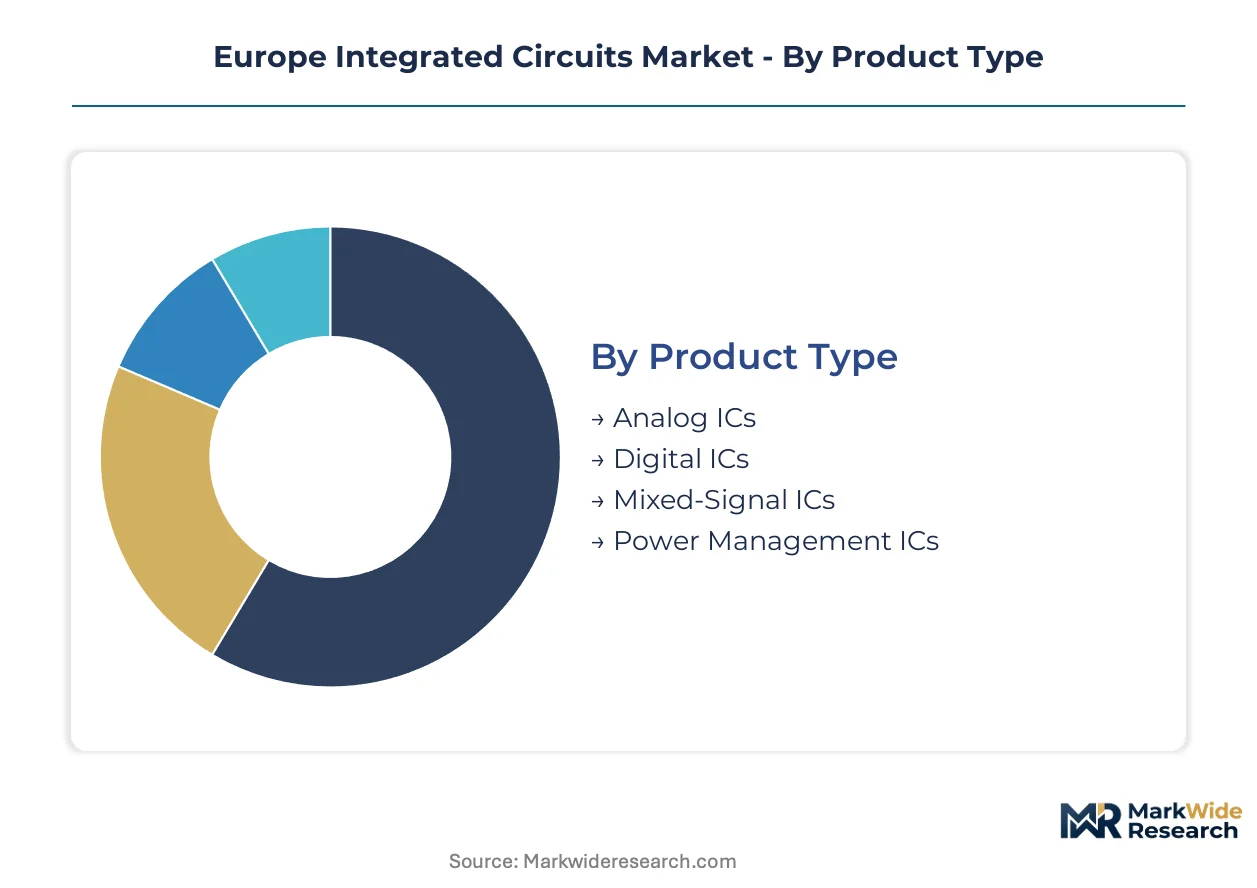
Segmentation reveals how electrification timelines and qualification cycles create divergent growth velocities across European chip categories. Automotive electrification compresses refresh cycles for power components while extending them for safety-critical digital systems.
Product Type:
Power Management ICs turn inventory fastest as EV platform ramps accelerate voltage regulator procurement, while automotive-grade Digital ICs face the longest design-in cycles due to AEC-Q100 certification requirements.
- Analog ICs:Continuous signal processing devices built on mature node processes, handling sensor interfacing and audio amplification. German industrial automation OEMs in the Ruhr Valley drive steady demand for precision signal conditioning in motor control applications, though node migration lags behind digital counterparts.
- Digital ICs:Binary logic devices including microprocessors, memory, and programmable logic fabricated at advanced nodes. France's aerospace and defense corridor around Toulouse sustains demand for radiation-hardened digital components with decade-long qualification horizons.
- Mixed-Signal ICs:Data converters and sensor interfaces bridging analog inputs with digital processing in single die. Italian automotive clusters near Turin specify these for battery management systems where precision ADCs monitor cell voltages.
- Power Management ICs:Voltage regulators, DC-DC converters, and battery chargers managing energy distribution. Dresden-based IDMs ship these to Stuttgart OEMs for 800V inverter architectures, with 18-month platform cycles driving rapid specification turnover.
Power Management ICs anchor the volume base while Mixed-Signal ICs gain share at the steepest rate.
Technology:
Process maturity creates a cost-performance hierarchy where established nodes dominate automotive volume while specialized substrates command premium positioning.
- CMOS:Dominant complementary metal-oxide-semiconductor technology leveraging complementary n-type and p-type transistors for low static power. Dutch equipment vendors supply lithography systems enabling CMOS scaling across Dresden and Crolles fabs, with automotive reliability requirements now prioritizing voltage tolerance over density.
- BiCMOS:Hybrid process integrating bipolar junction transistors with CMOS logic for high-speed analog-digital interfaces. RF front-end modules for 5G base stations in Ericsson's Swedish supply chain exploit BiCMOS linearity advantages.
- Bipolar:Traditional junction transistor technology offering superior current drive and linearity. Legacy industrial drives in Bavarian manufacturing plants maintain demand for robust bipolar power devices despite CMOS encroachment.
- SOI:Silicon-on-insulator substrates isolating active devices from bulk silicon to reduce parasitic capacitance. Aerospace applications across European space agencies specify SOI for radiation hardness in satellite payloads.
CMOS underpins the volume foundation as SOI captures the most rapid expansion in aerospace and defense niches.
Application:
End-use diversification spreads demand across qualification regimes from consumer-grade rapid cycles to automotive safety-critical longevity.
- Consumer Electronics:Smartphones, wearables, and home appliances requiring annual refresh cycles. Nordic design houses in Finland and Sweden specify these for mobile devices, though European consumer IC demand increasingly flows through Asian assembly channels.
- Automotive Electronics:Powertrain control, ADAS processing, and infotainment systems with 10-15 year service life requirements. German OEMs in Munich and Wolfsburg dominate procurement, with domain controller consolidation reshaping silicon specifications.
- Industrial Automation:PLCs, motor drives, and robotic controllers demanding 20-year availability guarantees. Swiss machinery builders around Zurich specify extended-temperature components for precision manufacturing equipment.
- Communication Equipment:5G infrastructure, optical transport, and satellite ground stations. Nokia's Finnish supply chain and Ericsson's Swedish operations anchor European demand for high-frequency RF and baseband processing.
Automotive Electronics anchors the volume base while Industrial Automation gains share at the steepest rate.
End User:
Procurement authority concentration determines pricing leverage and design-in influence across the value chain.
- OEMs:Vehicle and equipment manufacturers with direct semiconductor procurement teams. Volkswagen Group and BMW in Germany now qualify power discretes directly, bypassing traditional tier-1 mediation for supply security.
- Tier-1 Suppliers:Bosch, Continental, and Valeo integrating semiconductors into subsystems. These suppliers maintain design authority for domain controllers and sensor modules, specifying mixed-signal components for platform compatibility.
- Aftermarket Providers:Replacement component distributors serving repair networks. Eastern European logistics hubs in Poland and Czechia handle inventory for legacy vehicle support, with long-tail demand for discontinued automotive MCUs.
- Distributors:Arrow Electronics and Avnet managing inventory and technical support across fragmented demand. These intermediaries consolidate orders from mid-sized industrial customers lacking direct fab relationships.
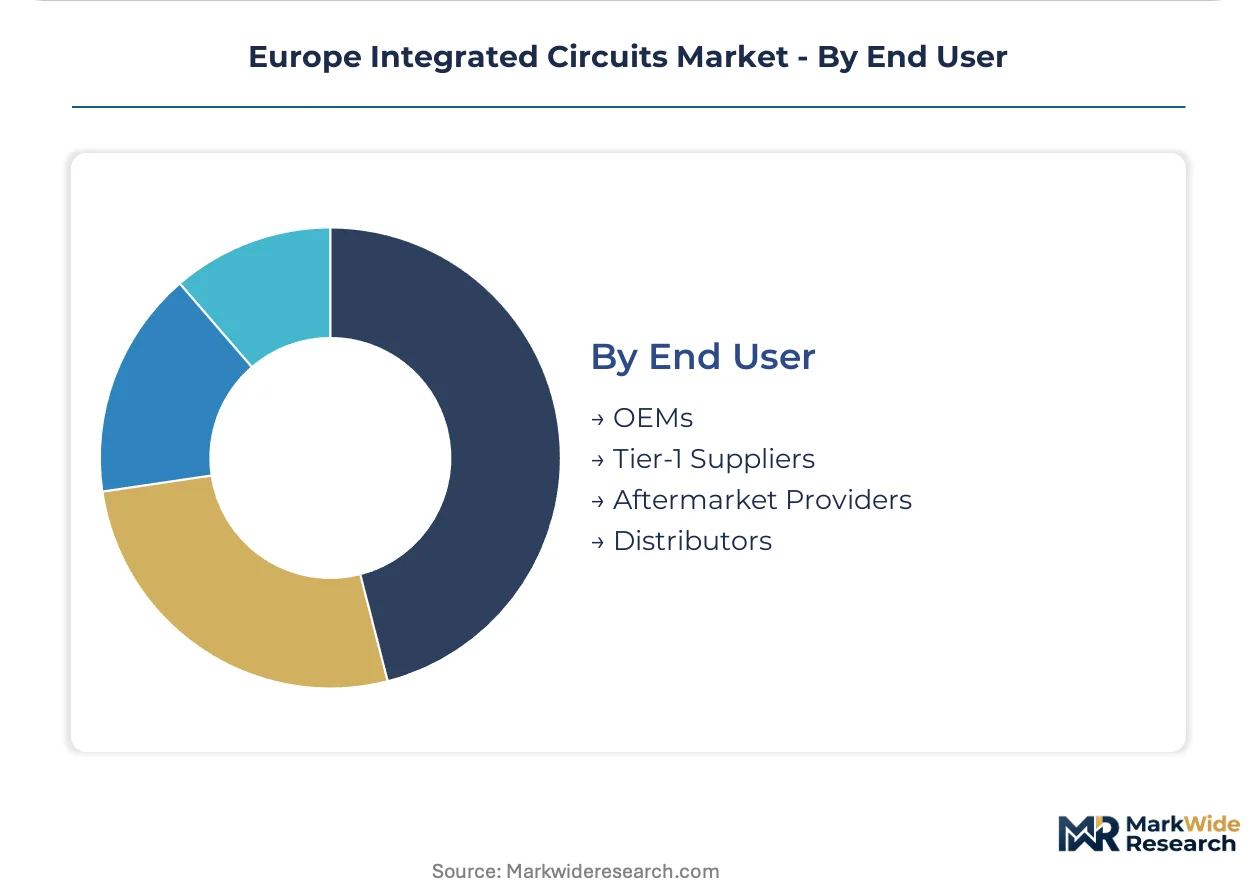
Tier-1 Suppliers anchor the volume base while OEM direct procurement gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fab capacity concentrates in Central Europe's automotive corridor while design activity clusters in Western European aerospace and defense hubs. The EU Chips Act redistributes public capital across member states with varying industrial bases. Eastern European packaging investments are capturing backend value that previously flowed to Asia.
Germany
Dresden's 300mm wafer complex and Magdeburg's greenfield Intel fab anchor continental logic production. The German government allocates federal matching funds under EU Chips Act co-financing rules. Stuttgart OEM procurement teams now qualify power semiconductors directly, bypassing traditional tier-1 channels for supply security.
France
Crolles hosts STMicroelectronics' FD-SOI pilot line serving aerospace and automotive sensor applications. ANSM and DGAC coordinate export controls on radiation-hardened components for satellite payloads. Toulouse's aerospace cluster sustains decade-long qualification cycles for defense-grade digital ICs.
Netherlands
ASML's lithography systems enable node scaling across European fabs, with Veldhoven engineering teams supporting scanner installation timelines. The Dutch national growth fund participates in EU Chips Act facility investments. Eindhoven's Brainport ecosystem concentrates photonics and RF design expertise for 5G infrastructure.
Italy
Turin's automotive cluster specifies mixed-signal battery management ICs for 800V EV platforms. Invitalia manages state aid notifications for Agrate Brianza fab expansions under EU competition rules. Milanese design houses concentrate on industrial automation controllers with 20-year availability guarantees.
Poland
Wrocław and Kraków logistics hubs handle semiconductor distribution for Eastern European industrial customers. EU structural funds co-finance advanced substrate packaging investments in Lower Silesia. The Polish Investment and Trade Agency recruits fan-out wafer-level packaging specialists from Asian equipment vendors.
Europe Integrated Circuits Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream where qualification cycles and fab access determine margin capture. European IDMs retain design authority over automotive power and mixed-signal categories while foundry partnerships handle advanced logic. Three archetypes dominate: diversified European conglomerates with captive fabs, fabless design houses licensing process technology, and Asian foundries serving European customers through local sales engineering. Competitive moves center on multi-year offtake agreements with automotive OEMs and selective fab capacity expansion using public co-financing.
Among diversified European fabricators, Infineon Technologies AG exemplifies the vertically integrated power semiconductor archetype with its Dresden manufacturing complex. STMicroelectronics N.V. occupies a comparable position in mixed-signal and automotive microcontroller categories, while NXP Semiconductors N.V. represents the vehicle networking specialization tier. These three anchors demonstrate how European IDMs balance captive production with foundry relationships for advanced node requirements.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| STMicroelectronics N.V. |
| NXP Semiconductors N.V. |
| Texas Instruments Inc |
| Analog Devices Inc |
| Intel Corporation |
| ON Semiconductor Corporation |
| Microchip Technology Inc. |
| Renesas Electronics Corporation |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp semiconductor logistics corridor channels wafers and equipment into Central European fabs, with freight cost volatility feeding directly into landed cost calculations for Power Management ICs and reinforcing price stratification between automotive-grade certified and industrial-grade unqualified components.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across European semiconductor procurement. Three-tier pricing structure across AEC-Q100 Grade 0 certified, industrial-temperature, and consumer-grade components separates qualified automotive supply from unqualified alternatives. Price differentiation hinges on certification grade and volume scale, with German OEM direct procurement teams commanding steepest discounts at 100k-unit annual offtakes. Cost compression in industrial-grade analog segments is intensifying because Eastern European distributors consolidate fragmented demand. Aftermarket providers serving legacy vehicle repair networks exhibit highest price sensitivity, while aerospace procurement around Toulouse demonstrates lowest sensitivity due to decade-long qualification lock-in.
Supply Chain Analysis
Tariff exposure between Taiwan and the European Union dominates supply chain risk calculus for advanced lithography equipment and 300mm wafer substrates. Geographic concentration centers on Taiwan for leading-edge foundry capacity, the Netherlands for lithography systems, and Germany for automotive-qualified IDM production. Raw material dependencies draw from Ukrainian neon gas supplies, Russian palladium for electroplating, and Chinese rare earth processing for magnet materials in packaging equipment. Single-source vulnerability pervades EUV scanner procurement from ASML's Veldhoven engineering complex. Distribution runs through Arrow Electronics and Avnet hubs in Poland and Czechia, consolidating fragmented industrial demand across Eastern European manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive domain controller consolidation is collapsing the interoperability boundaries between powertrain, chassis, and infotainment silicon, creating platform-economics inflection where chiplets and standardized interconnects reward ecosystem orchestrators over monolithic die specialists.
For Market Incumbents: Insulate captive fab utilization against foundry price volatility by deepening backward integration into 300mm wafer starting material through long-term supply agreements with Siltronic and SK Siltron. Prioritize AEC-Q100 Grade 0 certification investment for Mixed-Signal IC portfolios before German OEM procurement teams complete vendor panel consolidation. Channel control over Dresden-Leipzig corridor logistics infrastructure defends margin position against emerging Polish packaging competitors. For New Entrants and Emerging Players: Pursue GaN-on-Si power integration for 650V automotive inverter applications where incumbent silicon cost structures create white-space opportunity. Target Romanian and Polish advanced substrate packaging corridors where EU structural funds lower capital barriers and qualified engineering talent concentrates near Wrocław equipment vendor facilities. Go-to-market angle should emphasize CSRD-compliant Scope 3 emissions data for European OEM sustainability procurement mandates. For Investors and Strategic Acquirers: Fabless design houses with automotive functional safety certification and foundry partnerships at 40-90nm nodes represent acquisition targets with defensible positioning as advanced logic development costs exceed viable returns. Long-term viability across the analysis window favors specialists bridging analog sensor interfaces with digital processing in battery management and radar fusion applications. Inflection indicator to monitor: German tier-1 supplier qualification timelines compressing below 18 months for multi-die chiplets, signaling ecosystem maturity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU Chips Act Co-Financing Participation | Public capital allocation lowers effective cost of capital for Dresden and Magdeburg 300mm capacity additions. |
| GaN-on-Si Epitaxy Qualification | 650V automotive inverter applications open mid-voltage segments at silicon-equivalent cost structures. |
| Multi-Die Chiplet Package Development | German tier-1 suppliers now specify standardized interconnects to mix process nodes within control units. |
| CSRD Supply Chain Disclosure Compliance | Corporate sustainability reporting mandates create first-mover advantage for verified Scope 3 emissions data. |
| Eastern European Packaging Corridor Investment | Polish and Romanian advanced substrate facilities capture backend value previously flowing to Asian assembly. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEMI capacity forecasts, ECHA substance restriction filings, and EU Chips Act funding disclosures. Semiconductor fabrication executives, automotive tier-1 procurement directors, cleanroom equipment vendor application engineers, and Eindhoven Brainport ecosystem managers contributed structured interviews. Secondary validation drew from SEC 10-K filings of European IDMs, IHS Markit vehicle production databases, and ANSM export control notifications for radiation-hardened components. Bottom-up wafer demand modeling triangulates against top-down OEM semiconductor content per vehicle estimates.
Forecast inputs include automotive electrification platform ramps, EU Chips Act capital allocation timelines, and REACH fluorinated compound phase-down schedules. Segmentation dimensions span product type, technology node maturity, application qualification regime, and end-user procurement authority. CAGRs derive from unit volume build-ups across vehicle production forecasts and content-per-vehicle trajectories, cross-referenced against foundry capacity expansion announcements at Dresden, Crolles, and Magdeburg sites. Industry-specific inputs incorporate AEC-Q100 certification cycle durations and F-Gas Regulation equipment retrofit requirements.
Macroeconomic conditions sit as an overlay; deviation in eurozone industrial production indices, automotive OEM platform launch schedules, or neon gas supply restoration timelines would shift the trajectory. Forecasts reflect documented assumptions about EU Chips Act disbursement pacing and automotive domain controller consolidation adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market
IC (Integrated Circuits)
Application Specific Analog IC Market
IC (Integrated Circuits)
Asia Pacific Integrated Circuit (IC) Market
IC (Integrated Circuits)
Automotive Integrated Circuit (Ics) Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market
IC (Integrated Circuits)
RFID Reader IC Market
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
Global Application Specific Consumer Analog Integrated Circuit Market
IC (Integrated Circuits)
GNSS IC Market
IC (Integrated Circuits)
Global Application Specific Automotive Analog IC Market
IC (Integrated Circuits)
Programmable ASIC Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Display LSI IC Market
IC (Integrated Circuits)
Semiconductor Integrated Circuit Chip Market