
 Chemical Detection Armband Market | 2026-2036
Chemical Detection Armband Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Detection Armband Market Analytics
Emergency response procurement is decoupling from military-first development cycles as civilian hazardous material teams accelerate standalone armband adoption. Smiths Detection leverages its airport and defense channel infrastructure to sustain dual-use distribution across NATO-aligned emergency services. Bruker Corporation anchors its position through R&D intensity in miniaturized optical sensing, while 908 Devices competes on portable mass spectrometry integration for field-validated chemical identification.
A chemical detection armband is a wearable sensor system incorporating electrochemical cells, conductive polymer films, or optical indicator layers designed to detect and alarm against toxic industrial chemicals, chemical warfare agents, or hazardous vapors in real time; units typically achieve response thresholds below one minute with power budgets under 500 milliwatts for eight-hour occupational shifts. The primary commercial purpose centers on eliminating the gap between portable detection and personal protection by providing continuous, skin-proximate monitoring without handheld operation. Wearable Devices dominates unit volume among product types as form-factor miniaturization crosses occupational acceptability thresholds, while Electrochemical Sensors capture the deepest margin pools due to reproducible manufacturing and calibration stability. Optical Sensing leads technology tier growth in military specifications where multi-agent discrimination at parts-per-billion sensitivity commands premium positioning.
NIOSH, OSHA, and EPA frameworks collectively shape product standards by mandating minimum detection thresholds, alarm response times, and interoperability with existing personal protective equipment across United States industrial and first-responder deployments. REACH and CE marking requirements in Europe restrict certain conductive polymer substrates while accelerating substitution toward RoHS-compliant electrochemical architectures. Stakeholders must monitor divergence between military specification cycles and civilian regulatory refresh timelines, as misalignment creates inventory stranding risk for manufacturers serving both channels.
Market Dynamics
Military procurement decoupling from handheld detector programs is compressing development cycles for wearable chemical sensors, forcing manufacturers to prioritize soldier-chemical interoperability over legacy platform compatibility.
Growth Catalysts
- NIOSH Certification Tightening:Stricter test protocols for electrochemical sensor accuracy under OSHA-aligned frameworks are accelerating replacement demand among industrial safety managers in the United States.
- Military Modernization Budgets:Defense ministries in South Korea and Germany are carving dedicated lines for soldier-worn chemical detection, bypassing traditional multi-year handheld procurement schedules.
- Form-Factor Miniaturization:Conductive polymer films achieving sub-500 milliwatt power budgets are crossing occupational acceptability thresholds for eight-hour shift wear.
Market Restraints
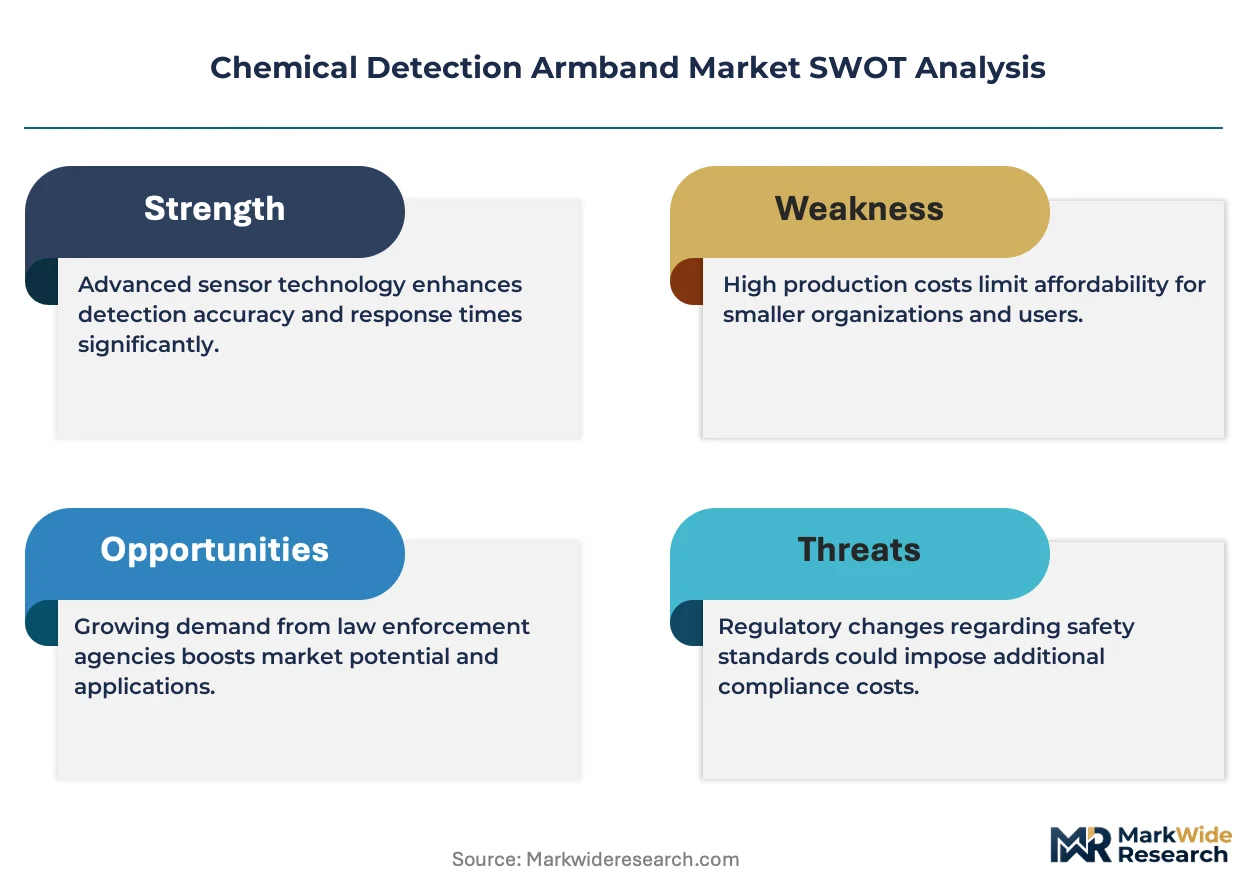
- Calibration Stability Costs:Electrochemical sensor drift rates require quarterly recalibration cycles that inflate total cost of ownership for small-to-mid industrial operators.
- Conductive Polymer Supply Concentration:RoHS-compliant substrate manufacturing concentrates among East Asian specialty chemical suppliers, exposing buyers to input volatility.
- Multi-Agent Discrimination Limits:Optical sensing architectures struggle to distinguish closely related organophosphorus compounds at parts-per-billion thresholds without false-positive rates above military specification tolerance.
Strategic Opportunities
- Emergency Services Channel Expansion:Civilian hazardous material teams in NATO-aligned countries are accelerating standalone armband adoption outside military-first development cycles.
- CE Marking Substitution Window:REACH restrictions on legacy conductive polymers create first-mover advantage for electrochemical architecture suppliers with pre-certified RoHS compliance.
- Mass Spectrometry Convergence:Portable MS integration with wearable form factors enables field-validated chemical identification previously requiring laboratory bench systems.
Industry Challenges
- Dual-Use Inventory Stranding:Manufacturers serving military and civilian channels face misalignment between defense specification cycles and NIOSH regulatory refresh timelines.
- Electrochemical Sensor Talent Scarcity:Reproducible manufacturing expertise for thin-film electrode deposition concentrates among aging specialist workforces in Germany and the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Detection Armband Market |
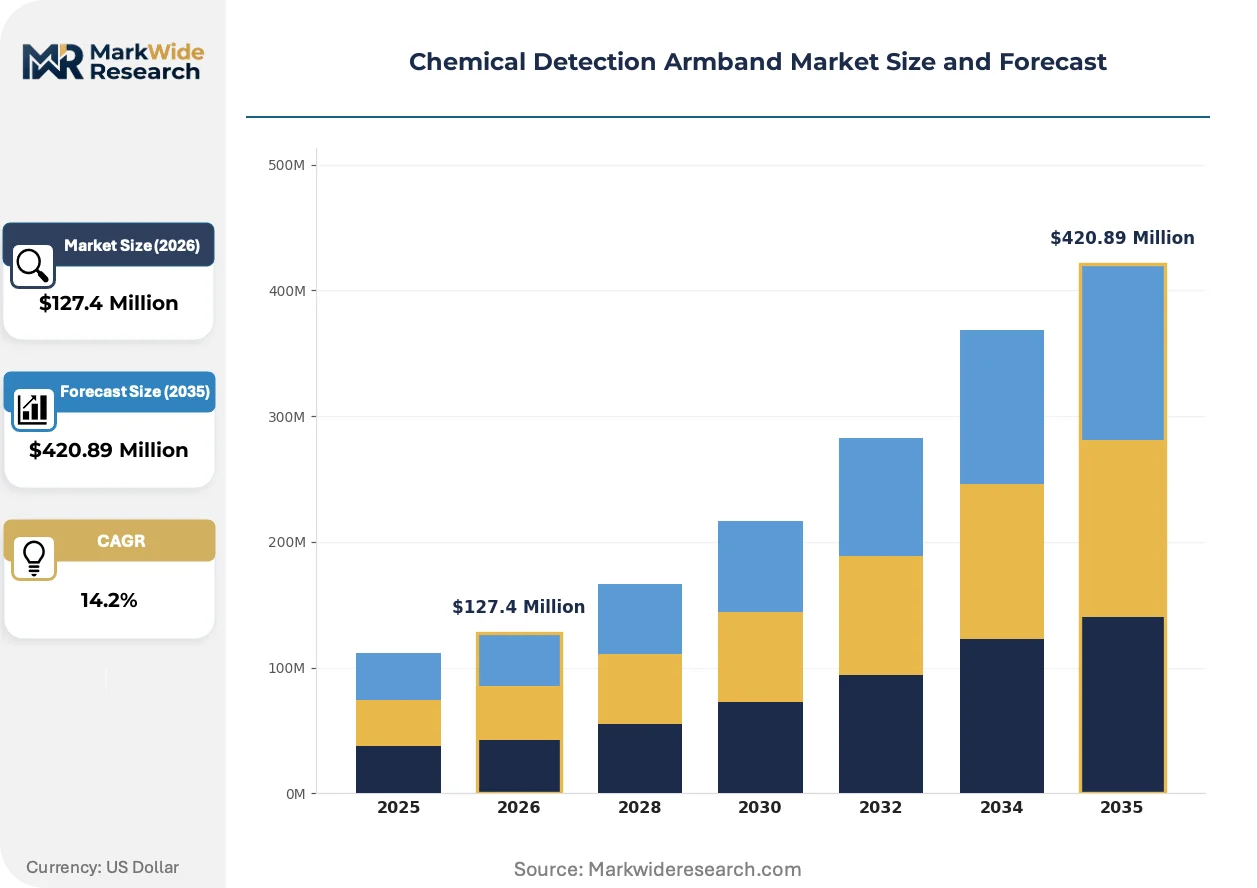
| Market Size in 2026 | $127.4 Million |
| Market Size in 2035 | $420.89 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Sensors, Wearable Devices, Detection Kits, Personal Monitors Technology: Optical Sensing, Electrochemical Sensors, Conductive Polymers, Chemical Tags End User: Military, Emergency Responders, Industrial Workers, Healthcare Application: Hazardous Material Handling, Emergency Response, Outdoor Activities, Environmental Monitoring |
| Companies Covered | Smiths Detection, Agilent Technologies, Bruker Corporation, Thermo Fisher Scientific, Honeywell International, MSA Safety, Chemring Group, Teledyne FLIR, 908 Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Detection Armband Market Evolving Landscape
Miniaturized sensing architectures are compressing the gap between portable detection and continuous personal monitoring, while regulatory divergence between military and civilian certification paths is fragmenting product development roadmaps.
Optical indicator layers incorporating photonic crystal arrays are automating real-time spectral analysis for chemical warfare agent identification. Military procurement offices in the United States and South Korea are specifying these architectures for next-generation soldier programs. The technology is automating multi-agent discrimination workflows that previously required handheld spectrometer operation, compressing response timelines below one-minute thresholds.
REACH substance restrictions on halogenated conductive polymers are forcing substrate substitutions toward metal-organic framework composites. European industrial safety mandates are accelerating CE marking renewal cycles for existing armband inventories. German chemical manufacturers are responding by vertically integrating electrochemical cell production to capture margin pools eroded by RoHS compliance costs.
Outcome-based leasing contracts for personal exposure monitoring are displacing capital purchase models among United States industrial operators. Safety managers at petrochemical facilities in Texas and Louisiana are unbundling device procurement from calibration service agreements. This shift concentrates vendor selection criteria on NIOSH-certified accuracy guarantees rather than upfront hardware pricing.
Chemical Detection Armband Market Segmentation
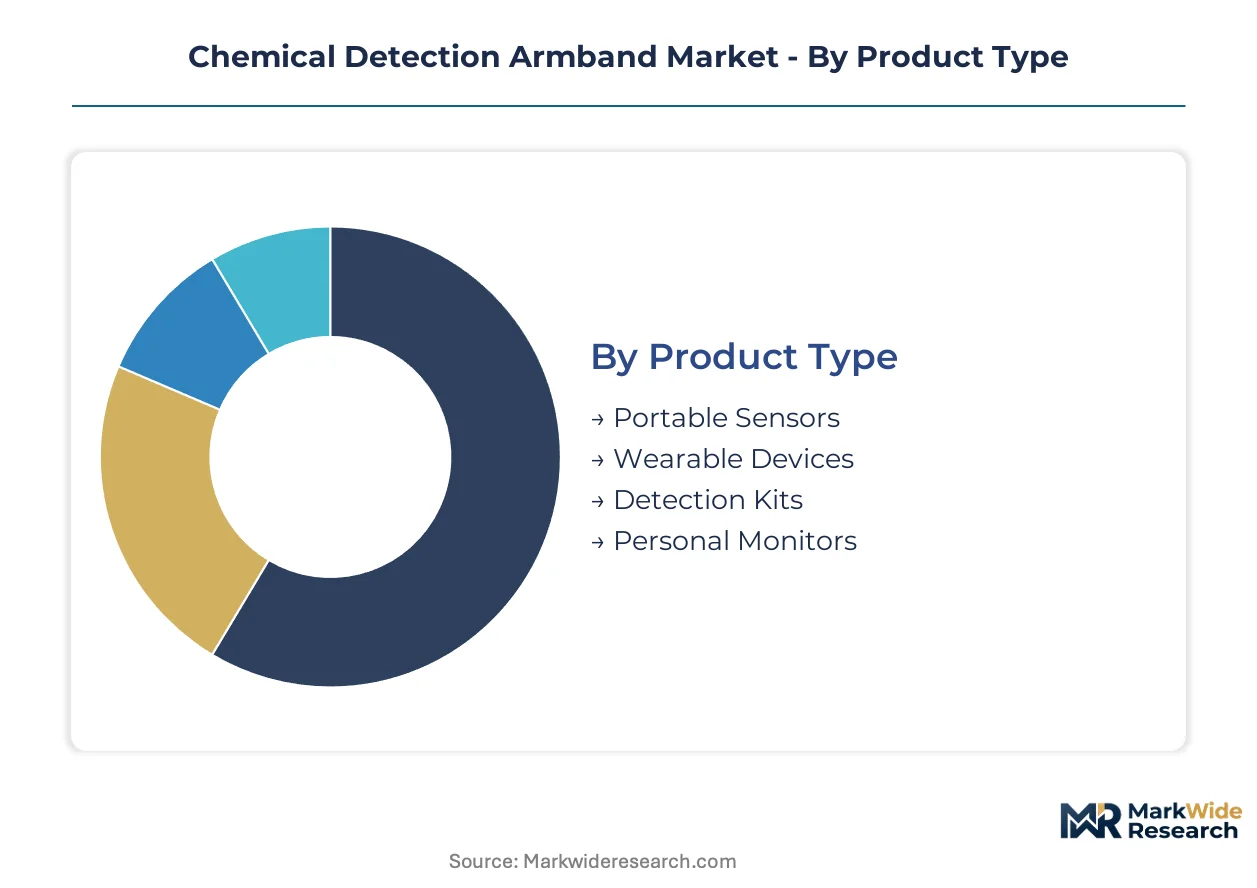
Segmentation in chemical detection armbands reveals how certification requirements, power budgets, and interoperability standards fragment addressable demand across military, industrial, and civilian channels. Understanding these divides clarifies why certain technologies command premium positioning while others compete on unit economics.
Product Type:
Wearable Devices and Personal Monitors carry the heaviest NIOSH certification burden for eight-hour occupational shift validation, while Portable Sensors and Detection Kits face lighter field-deployment standards.
- Wearable Devices:Skin-proximate form factors incorporating electrochemical cells or conductive polymer films achieve sub-500 milliwatt power budgets for continuous monitoring. Demand concentrates among United States petrochemical facilities and South Korean defense ministries where soldier-chemical interoperability mandates drive procurement. Form-factor miniaturization has crossed occupational acceptability thresholds, displacing handheld alternatives in hazardous material handling.
- Personal Monitors:Dedicated exposure tracking units integrate alarm thresholds calibrated to OSHA-aligned frameworks for toxic industrial chemicals. German industrial safety managers prioritize these for REACH-compliant manufacturing environments where RoHS substrate restrictions accelerate hardware refresh cycles. Calibration stability requirements inflate total cost of ownership through quarterly recalibration service agreements.
- Portable Sensors:Handheld-interoperable units bridge wearable and traditional detection modalities for emergency response teams requiring rapid deployment flexibility.
- Detection Kits:Modular cartridge-based systems enable field-swappable sensor arrays for multi-agent discrimination without full device replacement.
Wearable Devices sits at the top of the volume ranking, with Personal Monitors climbing the fastest.
Technology:
Cost tiers separate optical architectures commanding military premiums from electrochemical platforms dominating industrial safety procurement.
- Electrochemical Sensors:Thin-film electrode deposition on reproducible manufacturing lines captures the deepest margin pools through calibration stability and NIOSH-certified accuracy guarantees. United States industrial operators favor these for outcome-based leasing contracts that unbundle hardware from service agreements. Talent scarcity for electrode deposition expertise concentrates among aging specialist workforces in Germany.
- Optical Sensing:Photonic crystal arrays automating real-time spectral analysis achieve parts-per-billion sensitivity for chemical warfare agent identification. Military specifications in the United States and South Korea specify these architectures despite false-positive challenges with closely related organophosphorus compounds. Multi-agent discrimination capabilities command premium positioning above electrochemical alternatives.
- Conductive Polymers:Halogenated substrate formulations face REACH phase-out pressures, forcing substitution toward metal-organic framework composites for CE marking compliance.
- Chemical Tags:Colorimetric indicator layers provide passive detection without power requirements for backup confirmation workflows in resource-constrained settings.
Electrochemical Sensors dominates unit economics, while Optical Sensing gains share fastest in defense procurement channels.
End User:
Customer type determines whether procurement flows through defense ministry specification cycles or civilian regulatory refresh timelines.
- Military:Soldier-worn chemical detection programs in Germany and South Korea bypass traditional multi-year handheld procurement schedules with dedicated modernization budget lines. Specifications prioritize one-minute response thresholds and interoperability with existing personal protective equipment.
- Industrial Workers:Petrochemical facilities in Texas and Louisiana drive replacement demand as NIOSH tightens test protocols for electrochemical sensor accuracy. Safety managers select vendors based on certified accuracy guarantees rather than upfront hardware pricing.
- Emergency Responders:NATO-aligned hazardous material teams accelerate standalone armband adoption outside military-first development cycles, creating dual-use inventory stranding risks for manufacturers.
- Healthcare:Hospital exposure monitoring for anesthetic gases and sterilization chemicals represents an emerging application with distinct calibration requirements from industrial or military specifications.
Military anchors procurement value, with Emergency Responders expanding most quickly as civilian channels decouple from defense development cycles.
Application:
Geographic clustering shapes demand intensity, with hazardous material handling concentrated in United States Gulf Coast petrochemical corridors and emergency response procurement accelerating across NATO-aligned urban centers.
- Hazardous Material Handling:Continuous monitoring requirements in chemical manufacturing and storage facilities drive eight-hour shift wearability standards. REACH and RoHS compliance costs in European operations accelerate substrate substitution toward electrochemical architectures.
- Emergency Response:Field-validated chemical identification needs push integration of portable mass spectrometry with wearable form factors. Civilian hazardous material teams specify standalone adoption independent of military procurement timelines.
- Outdoor Activities:Recreational and agricultural applications for pesticide and solvent exposure monitoring represent a price-sensitive segment with lighter certification requirements.
- Environmental Monitoring:Fixed-site perimeter detection and mobile survey applications hybridize wearable portability with data logging for regulatory reporting to EPA frameworks.
Hazardous Material Handling leads volume deployment, with Emergency Response showing the steepest expansion trajectory as procurement patterns shift toward civilian-first development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as REACH compliance costs in Europe push substrate production toward jurisdictions with lighter chemical safety mandates. Producers are relocating electrochemical cell assembly to exploit gaps between NIOSH certification requirements and CE marking timelines.
United States
Petrochemical facilities along the Texas and Louisiana Gulf Coast drive replacement demand as NIOSH tightens test protocols for electrochemical sensor accuracy. OSHA-aligned frameworks mandate minimum detection thresholds for eight-hour occupational shifts. Houston-area safety managers unbundle device procurement from calibration service agreements, concentrating vendor selection on certified accuracy guarantees.
Germany
Defense ministries carve dedicated budget lines for soldier-worn chemical detection, bypassing traditional multi-year handheld procurement schedules. REACH substance restrictions on halogenated conductive polymers force substrate substitutions toward metal-organic framework composites. Bavarian chemical manufacturers respond by integrating electrochemical cell production in-house to capture margin pools eroded by RoHS compliance costs.
South Korea
Military modernization programs specify photonic crystal arrays for next-generation soldier systems requiring one-minute response thresholds. The country's national defense procurement agency prioritizes interoperability with existing personal protective equipment. Seoul-based research institutes collaborate with domestic specialty chemical suppliers to reduce dependence on East Asian substrate sources.
United Kingdom
NATO-aligned emergency services accelerate standalone armband adoption outside military-first development cycles. CE marking renewal cycles compress as REACH restrictions phase out legacy conductive polymer inventories. London metropolitan hazardous material teams specify field-validated chemical identification capabilities previously requiring laboratory bench systems.
Japan
Industrial safety managers at Osaka-area electronics manufacturing facilities adopt wearable exposure monitors for solvent and chemical vapor detection. METI guidelines for personal protective equipment interoperability shape procurement specifications for eight-hour shift wearability. Nagoya-based automotive suppliers extend chemical detection protocols from paint shop operations to battery manufacturing lines.
Chemical Detection Armband Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent detection specialists expand from handheld platforms into wearable form factors. The vendor base clusters around three strategic archetypes: defense-electronics conglomerates with soldier-system integration capabilities, analytical instrumentation houses with optical sensing R&D depth, and industrial safety specialists with NIOSH certification expertise. Technology licensing and backward integration into electrochemical cell production represent the two most visible competitive moves as margin pressure intensifies on substrate procurement.
Within the defense-electronics tier, Smiths Detection and Chemring Group exemplify players leveraging existing NATO channel infrastructure for dual-use distribution. Bruker Corporation anchors the analytical instrumentation segment, while 908 Devices occupies a position at the convergence point between portable mass spectrometry and wearable integration. These three names illustrate how competitive positioning fragments across military specification cycles, civilian regulatory refresh timelines, and emerging emergency services channels.
| Leading Market Players |
|---|
| Smiths Detection |
| Agilent Technologies |
| Bruker Corporation |
| Thermo Fisher Scientific |
| Honeywell International |
| MSA Safety |
| Chemring Group |
| Teledyne FLIR |
| 908 Devices |
| Others |
Value Network & Pricing Analysis
Family-owned German electrochemical specialists anchor upstream electrode deposition capacity, tightening pricing discipline for NIOSH-certified accuracy guarantees while compressing distributor margins across United States industrial procurement channels.
Pricing Analysis
Distributor margins in the 15-25 percent range separate defense-electronics conglomerates from industrial safety specialists competing on certified accuracy guarantees rather than hardware pricing. Three-tier pricing structure across military-specification, industrial-grade, and emergency-response tiers reflects NIOSH certification burden and calibration service bundling. Cost compression in the conductive polymer substrate tier intensifies as REACH phase-outs force RoHS-compliant substitution toward metal-organic framework composites. Petrochemical facilities in Texas and Louisiana exhibit lowest price sensitivity due to outcome-based leasing contracts that prioritize accuracy guarantees over upfront capital expenditure.
Supply Chain Analysis
Regional distribution centers in Germany, South Korea, and the United States feed hub-and-spoke patterns serving NATO-aligned defense ministries and industrial safety managers with distinct specification cycles. Electrochemical cell assembly draws from East Asian specialty chemical suppliers for halogenated conductive polymers facing REACH restrictions, while thin-film electrode deposition expertise concentrates among aging specialist workforces in Bavaria. Single-source vulnerability in RoHS-compliant substrate manufacturing exposes buyers to input volatility as European chemical manufacturers vertically integrate production. Distribution runs through dual-use channels serving military procurement offices and civilian emergency services with misaligned inventory refresh timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory layering, with NIOSH certification tightening for electrochemical sensor accuracy accelerating replacement demand among United States industrial operators.
For Market Incumbents: Anticipate margin compression from portable mass spectrometry convergence by deepening captive supply of electrochemical cells and securing NIOSH-certified accuracy guarantees through backward integration into thin-film electrode deposition. Lock in multi-year calibration service agreements with Gulf Coast petrochemical facilities before outcome-based leasing models fully commoditize hardware procurement. For New Entrants and Emerging Players: Begin with NATO-aligned emergency services channels where civilian hazardous material teams accelerate standalone armband adoption outside military-first development cycles. Target healthcare exposure monitoring for anesthetic gases and sterilization chemicals as the most penetrable application with distinct calibration requirements from incumbent industrial specifications. Pursue field-validated chemical identification capabilities through portable mass spectrometry integration as the primary go-to-market differentiator. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap industrial safety specialists with NIOSH certification expertise but limited defense channel access, offering buy-and-build platforms for dual-use portfolio expansion. Long-term viability hinges on regulatory arbitrage between military specification cycles and civilian refresh timelines. Monitor divergence between CE marking renewal velocity and NIOSH protocol updates as the critical inflection signal for inventory stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrochemical Cell Production | Bavarian chemical manufacturers capture margin pools eroded by RoHS compliance costs. |
| NIOSH Certification Investment | Industrial safety specialists lock in outcome-based leasing contracts with Gulf Coast petrochemical facilities. |
| Portable Mass Spectrometry Integration | 908 Devices converges wearable form factors with field-validated chemical identification capabilities. |
| Dual-Use Channel Expansion | Smiths Detection leverages NATO infrastructure to sustain distribution across emergency services procurement. |
| Metal-Organic Framework Composite Substitution | German manufacturers respond to REACH halogenated polymer phase-outs with RoHS-compliant substrate architectures. |
Research Methodology
Multiple input streams — primary interviews with defense procurement officers, industrial safety managers, and electrochemical manufacturing specialists; secondary validation through SEC filings, customs trade data, and NIOSH certification databases; and technical literature on photonic crystal array architectures — were reconciled through bottom-up unit economics and top-down market sizing triangulation.
Data-stream reconciliation anchored volume projections to military modernization budget allocations in South Korea and Germany, industrial safety mandate compliance costs in United States petrochemical corridors, and emergency services procurement decoupling trends across NATO-aligned urban centers. Segmentation modeling spanned product type, technology tier, end-user archetype, and application with cross-validation against electrochemical sensor drift rate assumptions and optical sensing false-positive tolerances. CAGRs were derived from replacement cycle compression and form-factor miniaturization adoption curves.
Several conditions sit outside the modeled scope, including sudden REACH substance restriction acceleration, breakthrough organophosphorus discrimination architectures eliminating optical sensing false-positive rates, and sovereign defense budget reallocation away from soldier-worn chemical detection programs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Pyro Electric Infrared Detectors Market
Detection and Regulation Devices
Carbon Monoxide (Co) Detector Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
Surge Suppression IC Market
Detection and Regulation Devices
Europe Gas Detectors Market
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
Registering Clock Driver (RCD) Market
Detection and Regulation Devices
Portable Radar Detectors Market
Detection and Regulation Devices
X-Ray Detectors Market
Detection and Regulation Devices
Global Gas Detection System Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Wireless Gas Detection System Market
Detection and Regulation Devices
Europe Portable Gas Detector Market
Detection and Regulation Devices
Global Inflation Device Market