
 Americas Logic IC Market | 2026-2036
Americas Logic IC Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Logic IC Market Insights
The foundry-to-fabless capability gap is collapsing as capital requirements for leading-edge nodes exceed $20 billion per fabrication facility. Intel Corporation sustains vertically integrated manufacturing across Arizona, New Mexico, and Oregon, leveraging government co-investment to rebuild process leadership. Advanced Micro Devices competes through pure-play foundry partnerships that minimize fixed-asset exposure while concentrating engineering resources on chiplet architectures. Qualcomm anchors its position in wireless baseband and RF logic through decades of accumulated cellular standard-essential patent portfolios.
Americas Logic ICs comprise integrated circuits performing computational, signal processing, and control functions, fabricated on silicon wafers using lithography nodes ranging from mature 28nm to advanced 3nm processes, with transistor densities exceeding 100 million per square millimeter in leading-edge digital devices. These components execute binary logic operations in electronic systems spanning smartphones, data centers, vehicles, and industrial equipment. Digital logic ICs dominate value generation due to relentless node shrinkage and AI workload expansion, while mixed-signal variants capture widening margin pools as automotive sensor fusion and 5G baseband integration demand analog-digital coexistence on single dies. Power management ICs within the product type taxonomy are gaining structural prominence from electric vehicle inverter controls and hyperscale data center efficiency mandates.
The U.S. Department of Commerce administers CHIPS Act funding disbursements contingent on domestic content and national security guardrails, reshaping where logic IC capacity locates across the Americas. Mexico's Secretariat of Economy coordinates maquiladora incentives with U.S. customs frameworks under USMCA provisions, influencing assembly and test site selection. Brazil's ANATEL certification requirements for telecommunications equipment create non-tariff market access conditions for logic IC suppliers serving Latin American infrastructure builds. Stakeholders must monitor how U.S. export control expansions on advanced computing hardware redirect Chinese demand toward alternative semiconductor sources and whether Americas-based capacity can capture redirected volumes without triggering reciprocal trade barriers.
Market Dynamics
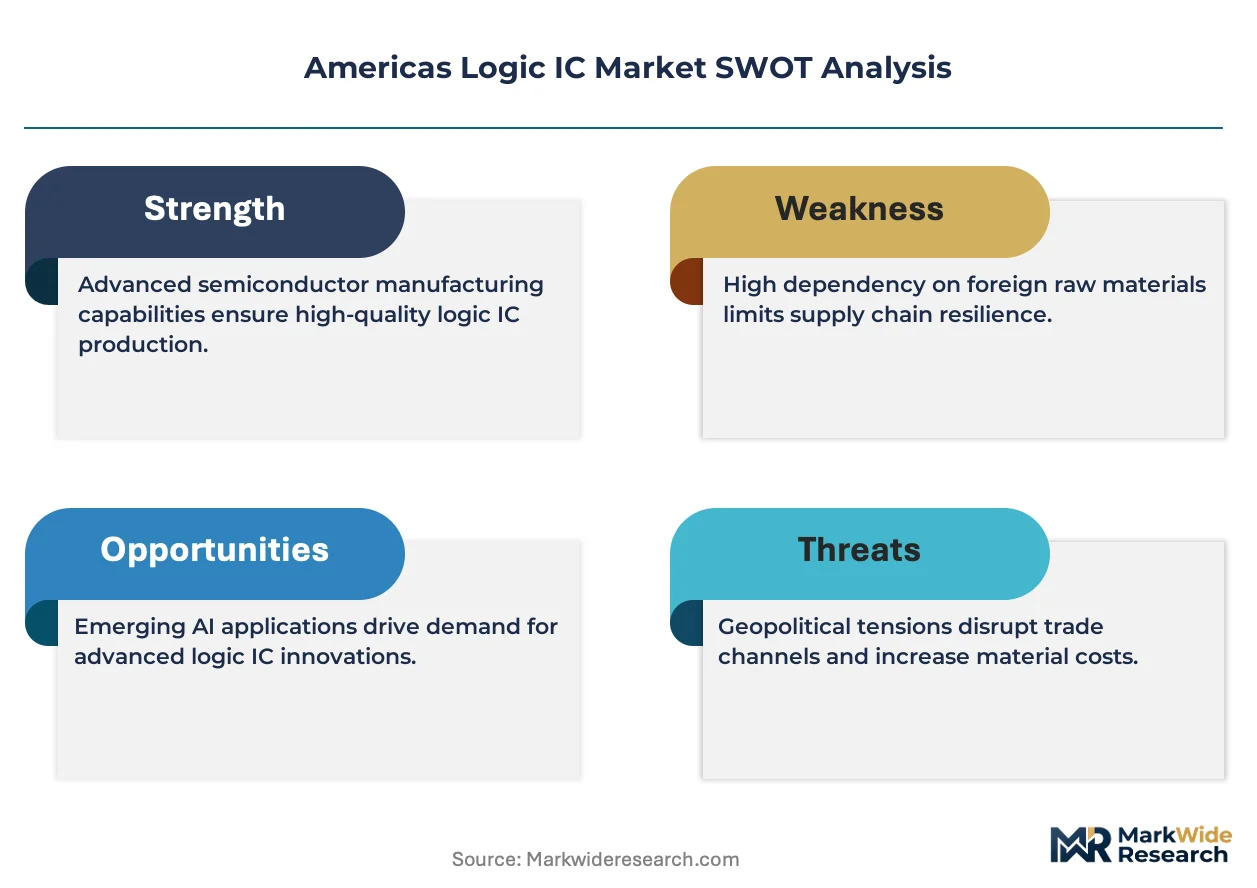
CHIPS Act disbursements from the U.S. Department of Commerce are restructuring capital flows across semiconductor fabrication, collapsing the historical cost barrier that favored Asian concentration for leading-edge logic IC production.
Growth Catalysts
- Electrified powertrains:Automotive OEMs across the Americas are integrating inverter control modules and battery management systems that demand high-reliability logic ICs at 28nm and above.
- USMCA customs frameworks:Mexico's maquiladora incentives coordinate with U.S. tariff provisions to pull assembly and test operations toward northern border states.
- AI workload expansion:Hyperscale data centers in Virginia, Oregon, and Texas are deploying accelerator chips that consume advanced-node digital logic at unprecedented density.
Market Restraints
- Leading-edge fabrication economics:Capital requirements exceeding $20 billion per facility restrict viable entrants to a handful of government-backed consortia.
- Asian supply concentration:Advanced packaging and substrate materials remain concentrated in Taiwan and South Korea, creating single-source vulnerabilities for Americas-based fabs.
- EUV lithography scarcity:ASML's extreme ultraviolet tool output limits node advancement velocity regardless of capital availability.
Strategic Opportunities
- Nearshored automotive clusters:Guanajuato and Nuevo León in Mexico are attracting Tier 1 suppliers seeking proximity to Texas and Michigan OEM assembly plants.
- Chiplet architecture proliferation:Disaggregation of system-on-chip designs into modular chiplets enables fabless competitors to access leading-edge performance without captive fabrication.
- IRA clean energy credits:Inflation Reduction Act provisions for domestic manufacturing are offsetting facility energy costs for logic IC producers qualifying under domestic content thresholds.
Industry Challenges
- Process engineering talent scarcity:Leading-edge node development requires specialists in computational lithography and materials science that U.S. universities produce insufficiently.
- Export control compliance complexity:U.S. Bureau of Industry and Security restrictions on advanced computing hardware to China force bifurcated product roadmaps and customer segmentation.
- Legacy node profitability pressure:Mature process lines at 28nm and above face margin compression as Chinese fabs expand capacity in automotive and industrial segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Logic IC Market |
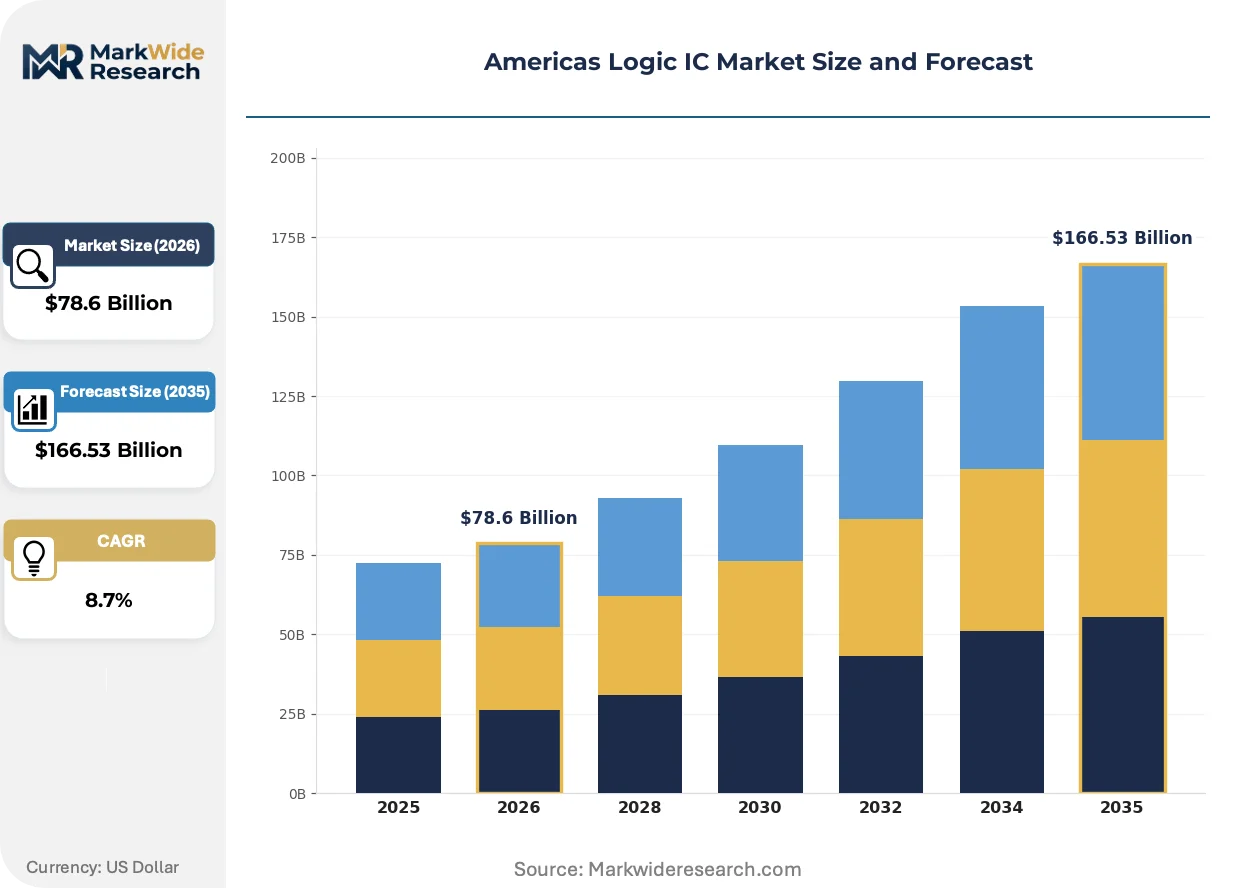
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $166.53 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Mixed-Signal, Power Management Application: Automotive Electronics, Consumer Electronics, Industrial Automation, Telecommunications Technology: CMOS, Bipolar, BiCMOS, GaAs End User: OEMs, Tier-1 Suppliers, Semiconductor Manufacturers, Aftermarket Providers |
| Companies Covered | Analog Devices, Intel Corporation, Texas Instruments, Advanced Micro Devices, Broadcom, Qualcomm, NXP Semiconductors, STMicroelectronics, Infineon Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Logic IC Market Trends and Innovations
Logic IC architecture is bifurcating between monolithic system-on-chip designs for mobile and consumer applications and disaggregated chiplet assemblies for data center and automotive workloads.
Chiplet-based integration is fragmenting the traditional system-on-chip market by enabling heterogeneous die stacking from multiple process nodes. Automotive suppliers in Michigan and Texas are adopting chiplet architectures to mix 5nm digital compute with 40nm analog I/O on single packages. This modular approach compresses time-to-market for advanced driver-assistance systems while reducing reliance on single-node wafer supply.
The CHIPS and Science Act is mandating domestic content thresholds for federal funding recipients, reshaping supplier qualification criteria. Equipment vendors must now certify U.S.-sourced components percentages to participate in funded fab construction. Arizona and Ohio projects are requiring construction materials and subsystems from qualified domestic suppliers, extending localization beyond wafer fabrication into capital equipment supply chains.
Hyperscale buyers are consolidating procurement authority into centralized semiconductor commodity teams that negotiate multi-year foundry commitments directly. Traditional distribution channels serving industrial and automotive segments are losing volume to these direct engagements. This concentration is most visible in California and Washington state, where cloud providers now contract wafer starts at leading-edge nodes without intermediary representation.
Americas Logic IC Market Segmentation
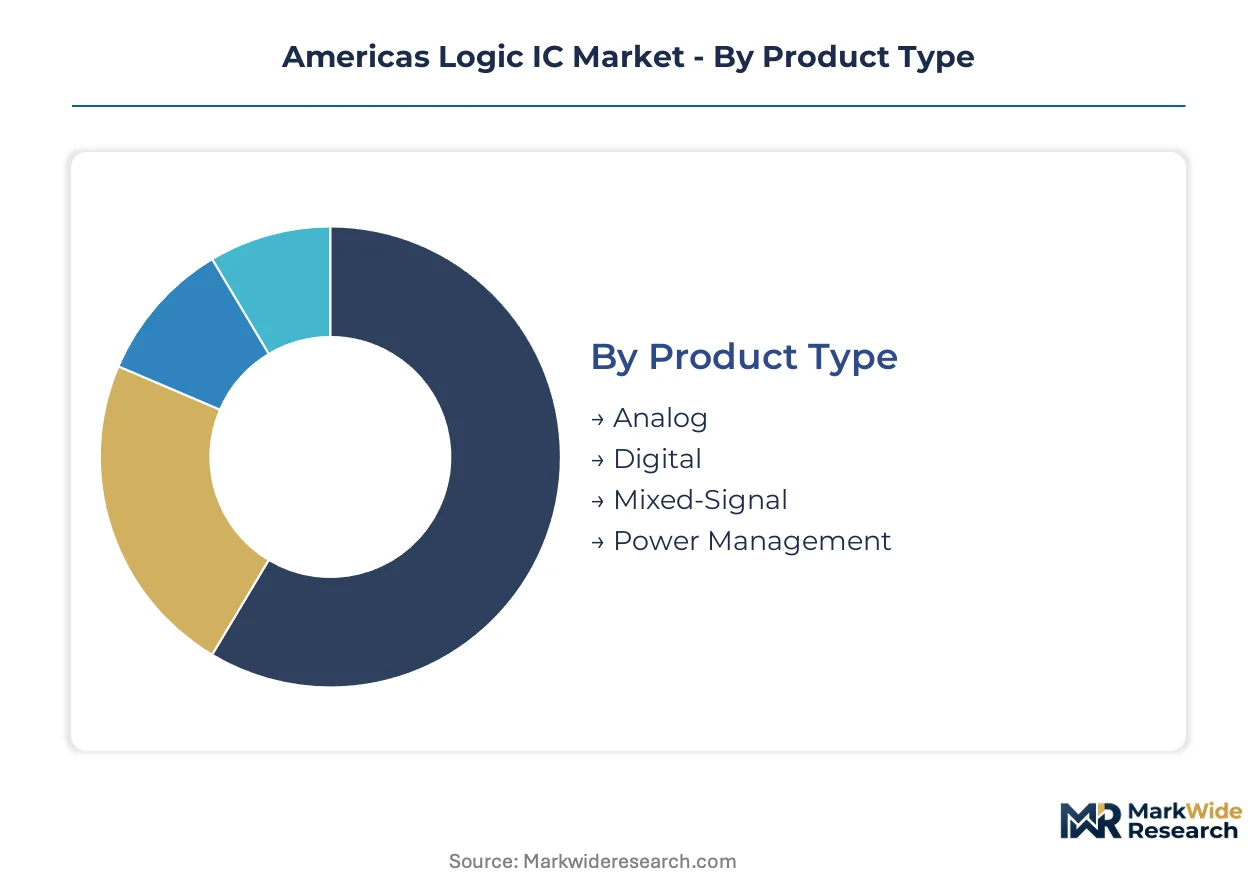
Logic IC procurement patterns diverge sharply across application environments, with automotive qualification requirements and data center performance thresholds imposing incompatible design constraints on shared process nodes. Understanding these segment boundaries clarifies where margin pools concentrate and which technology transitions threaten incumbent positions.
Product Type:
CHIPS Act funding eligibility varies by product category, with digital logic receiving priority allocation for leading-edge node development while mixed-signal and power management ICs qualify under mature process expansion provisions.
- Digital:Binary logic circuits fabricated at 3nm to 28nm nodes execute computational workloads in data centers and smartphones. Hyperscale buyers in Virginia and Oregon are locking in multi-year wafer commitments at 5nm and below, exhausting available leading-edge capacity from domestic foundries.
- Power Management:Voltage regulation and power conversion circuits integrate analog control loops with digital telemetry. Electric vehicle inverter modules produced in Texas and Michigan are consuming automotive-grade PMICs at 40nm and above, with qualification cycles exceeding 18 months.
- Mixed-Signal:Analog-digital coexistence on single dies enables sensor fusion and RF baseband integration.
- Analog:Continuous signal processing circuits operate without discrete state transitions.
Digital handles the majority of throughput; Power Management is expanding most quickly on share.
Application:
End-use concentration determines which regulatory frameworks govern qualification, with automotive electronics subject to NHTSA functional safety mandates and telecommunications equipment falling under FCC certification requirements.
- Automotive Electronics:Advanced driver-assistance systems and electrified powertrains demand logic ICs with AEC-Q100 Grade 1 temperature ratings and ISO 26262 functional safety certification. OEMs in Michigan and Tier-1 suppliers in Guanajuato are qualifying 28nm digital controllers for battery management and motor control applications.
- Telecommunications:5G baseband processors and RF transceivers require mixed-signal integration at 7nm and below. Infrastructure deployment by carriers in Brazil triggers ANATEL certification requirements that filter supplier eligibility for Latin American market access.
- Consumer Electronics:Mobile application processors and peripheral controllers prioritize density and power efficiency.
- Industrial Automation:Programmable logic controllers and motor drives emphasize reliability over node advancement.
Automotive Electronics commands the dominant revenue position; Telecommunications is climbing the fastest on volume contribution.
Technology:
Process selection locks in foundry partnerships and equipment depreciation schedules, with CMOS dominance at advanced nodes contrasting against persistent bipolar demand for high-voltage industrial applications.
- CMOS:Complementary metal-oxide-semiconductor logic achieves the highest transistor density and lowest static power consumption. Foundry investments in Arizona and Ohio are concentrating exclusively on CMOS variants at 7nm and below, with EUV lithography deployment determining yield trajectories.
- BiCMOS:Bipolar-CMOS integration combines high-speed analog performance with digital density for RF and mixed-signal applications. 5G mmWave beamforming modules in base stations and automotive radar sensors in Michigan assembly plants are sustaining process development at specialty foundries.
- Bipolar:Junction transistor architectures persist in high-voltage power applications.
- GaAs:Gallium arsenide substrates enable millimeter-wave frequencies beyond silicon capabilities.
CMOS carries the volume base; BiCMOS is gaining share fastest in revenue terms.
End User:
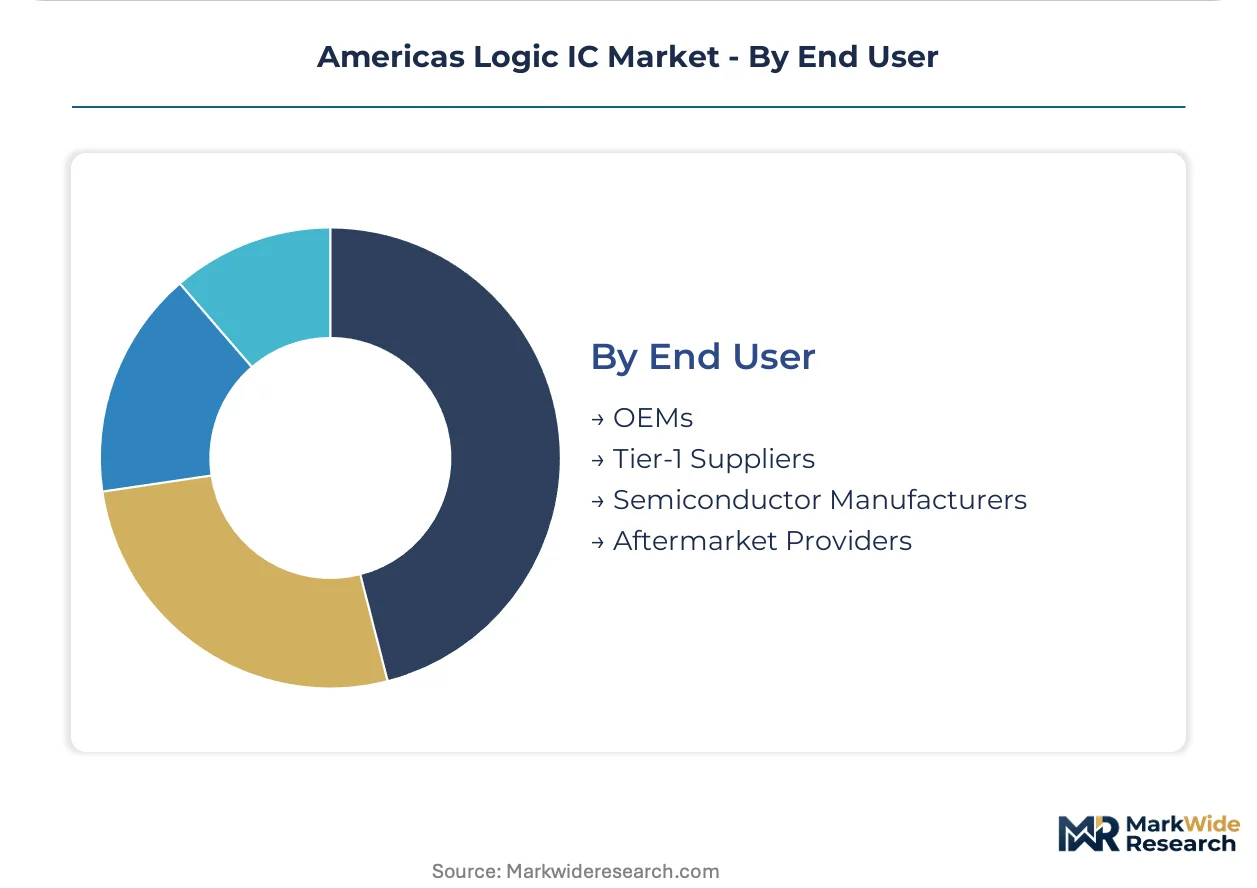
Procurement authority concentration varies by buyer type, with OEMs and hyperscale operators consolidating direct foundry relationships while Tier-1 suppliers and aftermarket providers remain dependent on distribution channels.
- OEMs:Original equipment manufacturers in automotive and consumer electronics are establishing dedicated semiconductor commodity teams that negotiate wafer starts directly with foundries. Detroit-based automakers and Silicon Valley device manufacturers are bypassing traditional distribution for advanced-node logic procurement.
- Semiconductor Manufacturers:IDMs and fabless designers with captive packaging operations are securing substrate supply agreements ahead of capacity constraints. Intel's vertically integrated model across Arizona, New Mexico, and Oregon exemplifies this category's capital intensity and government co-investment dependence.
- Tier-1 Suppliers:Automotive subsystem integrators face margin pressure from OEM direct-sourcing initiatives.
- Aftermarket Providers:Replacement component distributors serve repair and refurbishment channels.
OEMs dominate direct procurement volume; Semiconductor Manufacturers are expanding most rapidly on capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States-based foundries while Mexican assembly operations compete on logistics proximity rather than technology premium. This asymmetry shapes capital allocation across the Americas semiconductor corridor.
United States
Hyperscale data center buildouts in Virginia and Oregon consume advanced-node digital logic at unprecedented density. The CHIPS Act administered by the U.S. Department of Commerce mandates domestic content thresholds for federal funding recipients. Intel Corporation sustains vertically integrated manufacturing across Arizona, New Mexico, and Oregon, leveraging government co-investment to rebuild process leadership at leading-edge nodes.
Mexico
Automotive OEMs are integrating inverter control modules and battery management systems that demand high-reliability logic ICs at mature nodes. The Secretariat of Economy coordinates maquiladora incentives with U.S. customs frameworks under USMCA provisions. Guanajuato and Nuevo León are attracting Tier 1 suppliers seeking proximity to Texas and Michigan OEM assembly plants.
Canada
AI workload expansion drives demand for accelerator chips in Ontario and Quebec data center clusters. Health Canada certification requirements for telecommunications equipment create non-tariff market access conditions for logic IC suppliers. Toronto-Waterloo corridor engineering talent supports fabless design operations serving North American automotive and industrial segments.
Brazil
Telecommunications infrastructure deployment by carriers triggers sustained demand for mixed-signal logic ICs in 5G baseband and RF applications. ANATEL certification requirements for telecommunications equipment filter supplier eligibility for Latin American market access. São Paulo industrial zones concentrate assembly operations serving regional consumer electronics and automotive aftermarket channels.
Americas Logic IC Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure across the Americas. Vertically integrated manufacturers with captive fabrication compete against fabless designers leveraging pure-play foundry partnerships. Three archetypes dominate: government-backed integrated device manufacturers, capital-light fabless specialists, and automotive-qualified mixed-signal suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing multi-year wafer commitments and substrate supply agreements ahead of tightening supply.
Within the integrated manufacturing tier, Intel Corporation exemplifies the government-co-investment archetype sustaining captive fabrication across multiple U.S. states. Advanced Micro Devices and Qualcomm occupy positions on the fabless vector, concentrating engineering resources on chiplet architectures and wireless baseband integration respectively while minimizing fixed-asset exposure through foundry partnerships.
| Leading Market Players |
|---|
| Analog Devices |
| Intel Corporation |
| Texas Instruments |
| Advanced Micro Devices |
| Broadcom |
| Qualcomm |
| NXP Semiconductors |
| STMicroelectronics |
| Infineon Technologies |
| Others |
Pricing and Supply Chain Analysis
Long-term wafer offtake agreements between hyperscale data center operators and Arizona-based foundries lock in both advanced-node supply access and multi-year price visibility, insulating buyers from spot-market volatility while committing suppliers to capacity utilization guarantees under CHIPS Act domestic content thresholds.
Pricing Analysis
Configured-to-order pricing for automotive-qualified logic ICs commands substantial premiums over standard catalog offerings, with AEC-Q100 Grade 1 certification and ISO 26262 functional safety compliance driving tiered pricing stratification across 28nm to 5nm process nodes. Contract-based long-term offtake dominates hyperscale procurement, while spot transactions persist for industrial and aftermarket segments where volume scale and customization level determine final unit economics. Cost compression in mature-node automotive controllers is intensifying because Chinese fab capacity expansion feeds oversupply in 28nm and above segments. Tier-1 automotive suppliers exhibit highest price sensitivity due to OEM direct-sourcing pressure, whereas cloud infrastructure operators demonstrate lowest sensitivity given performance-per-watt optimization priorities.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach and container availability constraints on Asia-North America trade lanes elevate inbound logistics costs for substrate materials and specialty chemicals, compressing margins on packaged logic ICs assembled in Mexican maquiladora facilities. Wafer fabrication concentrates in Taiwan, South Korea, and the United States, with advanced packaging and substrate materials drawing from Taiwanese and South Korean suppliers. High-purity silicon wafers, photoresist chemicals, and EUV pellicles constitute critical input dependencies. Single-source vulnerability in EUV lithography equipment from ASML creates structural supply chain risk. Distribution runs through authorized distributors serving industrial and automotive aftermarket channels, while hyperscale buyers engage foundries through direct procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Logic IC vendors are capturing expanding service-attach revenue through firmware update subscriptions and predictive maintenance analytics layers that compound faster than hardware shipment growth, particularly in automotive battery management and data center accelerator deployments.
For Market Incumbents: Shield leading-edge process leadership through accelerated EUV lithography yield improvement programs at Arizona and Ohio facilities, while consolidating substrate supply agreements ahead of advanced packaging capacity constraints. Threat from fabless competitors leveraging chiplet architectures demands defensive certification investment in automotive functional safety standards and channel control over Tier-1 supplier qualification pipelines. For New Entrants and Emerging Players: Anchor in nearshored automotive assembly clusters across Guanajuato and Nuevo León where proximity to Texas OEM plants creates penetrable white-space for battery management and inverter control modules at 40nm and above mature nodes. Target industrial automation segments in Brazil's São Paulo industrial zones through ANATEL-certified telecommunications equipment integration as the go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward automotive-qualified mixed-signal specialists with established AEC-Q100 certification and captive packaging capabilities that compound margin expansion through electrified powertrain content growth. Long-term viability hinges on defensible process-node positioning against Chinese fab expansion. Watch EUV tool delivery schedules from ASML as the inflection indicator for leading-edge capacity expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Wafer Commitment | Hyperscale data center operators in Virginia secure dedicated 5nm capacity from Arizona foundries. |
| Automotive Certification Investment | AEC-Q100 Grade 1 qualification opens battery management system procurement at Detroit OEMs. |
| Chiplet Architecture Partnership | Heterogeneous integration agreements enable fabless competitors to access leading-edge performance. |
| Nearshored Assembly Expansion | Maquiladora facilities in Nuevo León reduce logistics proximity to Texas OEM assembly plants. |
| Substrate Supply Agreement | Advanced packaging material commitments mitigate single-source vulnerability from Taiwanese suppliers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC semiconductor filings, U.S. Department of Commerce CHIPS Act disbursement records, and foundry capex disclosures, combining structured interviews with fab operations executives, Tier-1 automotive supplier procurement leads, hyperscale data center infrastructure planners, and semiconductor distribution channel managers. Secondary validation draws from customs trade data, ANATEL certification registries, and EUV lithography equipment delivery schedules. Bottom-up wafer demand modeling triangulates against top-down semiconductor consumption forecasts across the Americas.
Segmentation dimensions modeled include product type taxonomy, application environment qualification requirements, process technology node, and end-user procurement authority concentration across the analysis window. CAGRs derive from regression against historical foundry utilization rates, automotive electronics content-per-vehicle trajectories, and hyperscale data center deployment pipelines. Industry-specific forecast inputs incorporate EUV tool delivery constraints and CHIPS Act domestic content threshold compliance timelines.
Decision-makers should treat outputs as directional under assumptions of sustained U.S. export control enforcement and ASML EUV output constraints; material deviation would warrant model refresh. Specific risk factors include reciprocal trade barrier escalation, Chinese mature-node capacity overshoot, and process engineering talent scarcity in computational lithography. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Computer and Peripherals Standard Logic IC Market
IC (Integrated Circuits)
Global Special Purpose Logic IC Market
IC (Integrated Circuits)
China Analog IC Market
IC (Integrated Circuits)
Display LSI IC Market
IC (Integrated Circuits)
Global Application Specific Computer Analog IC Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
Logic IC Market
IC (Integrated Circuits)
Digital Potentiometer IC Market
IC (Integrated Circuits)
Japan Integrated Circuit (IC) Market
IC (Integrated Circuits)
Japan Analog IC Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market
IC (Integrated Circuits)
Global Analog Integrated Circuit (IC) Market
IC (Integrated Circuits)
Communication Special Purpose Logic IC Market
IC (Integrated Circuits)
South Korea Analog Integrated Circuits Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market