
 UV Conveyor Systems Market | 2026-2036
UV Conveyor Systems Market Size, Share, and Industry Trends Forecast 2026-2036
UV Conveyor Systems Market Analytics
Software-defined intensity control and remote monitoring subscriptions are restructuring how UV conveyor systems generate recurring revenue. Nordson Corporation leverages its global service infrastructure to anchor long-term contracts in automotive coating lines. IST METZ GmbH sustains technology leadership through deep specialization in mercury vapor and LED curing architectures. Excelitas Technologies Corp. differentiates by dominating precision UV source integration for electronics manufacturing.
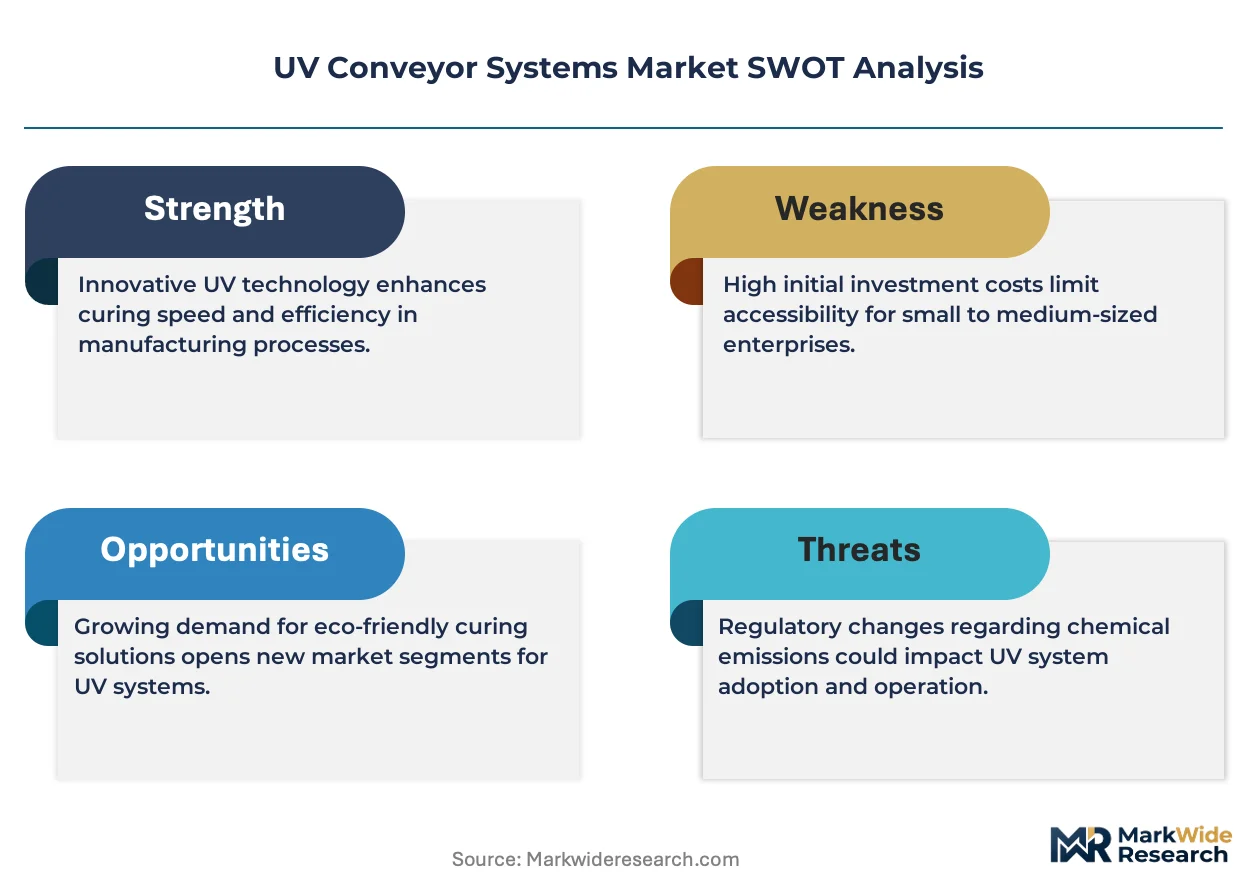
UV conveyor systems transport products through controlled ultraviolet radiation zones to cure inks, coatings, and adhesives or to sterilize surfaces, typically operating at belt speeds from 1 to 30 meters per minute with irradiance levels measured in watts per square centimeter. Belt conveyor configurations occupy the largest installed base due to their versatility across flat and contoured substrates, while modular conveyor designs represent the fastest-expanding category as manufacturers demand reconfigurable line layouts for batch-size-one production. LED technology segments are capturing disproportionate margin pools because semiconductor-based sources eliminate mercury handling compliance costs and reduce energy consumption against legacy mercury vapor installations.
FDA validation requirements govern UV sterilization deployments in United States healthcare settings, while EPA regulations restrict mercury content in discarded lamps, accelerating LED substitution. The EU RoHS directive and REACH framework impose substance restrictions and registration obligations on UV system components sold across European member states. Stakeholders must monitor evolving photobiological safety standards from IEC and national electrical codes as UV-C applications expand beyond industrial curing into antimicrobial surface treatment protocols.
Market Dynamics
Mercury vapor-to-LED source substitution is compressing equipment replacement cycles while simultaneously fragmenting vendor revenue streams away from lamp sales toward semiconductor module integration and predictive maintenance subscriptions.
Growth Catalysts
- REACH VOC limits:European coating facilities face tightening volatile organic compound thresholds under ECHA enforcement, accelerating solvent-free UV curing adoption across automotive paint lines.
- Electronics miniaturization:Printed circuit board assembly plants in Germany and China are expanding high-throughput curing tunnels to handle flexible substrate throughput demands.
- Medical sterilization protocols:FDA validation requirements for UV-C surface treatment are expanding system deployments in United States hospital central sterile supply departments.
Market Restraints
- LED module cost concentration:Semiconductor die supply concentrates among East Asian foundries, exposing system integrators to input price volatility and allocation constraints.
- Mercury lamp disposal friction:EPA mercury content restrictions impose hazardous waste handling costs on legacy installed bases, delaying full fleet conversions despite operational savings.
- Optical engineering scarcity:Deep UV-C optical design expertise resides within a narrow specialist labor pool, constraining manufacturer expansion timelines.
Strategic Opportunities
- Modular reconfiguration demand:Batch-size-one manufacturing trends in Germany are driving specification for plug-and-play conveyor segments that reconfigure without mechanical overhaul.
- Antimicrobial food packaging:FDA food contact surface regulations are opening UV-C sterilization applications for conveyor-treated flexible films in protein processing facilities.
- Software-defined intensity:Remote irradiance calibration and belt-speed synchronization via industrial IoT platforms are creating recurring revenue attachment opportunities for system OEMs.
Industry Challenges
- IEC photobiological certification timelines:Third-party safety validation for UV-C wavelength exposure limits extends product launch schedules by six to twelve months.
- Legacy PLC integration complexity:Brownfield automotive paint lines operate on proprietary control architectures that resist seamless communication with modern UV source management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Conveyor Systems Market |
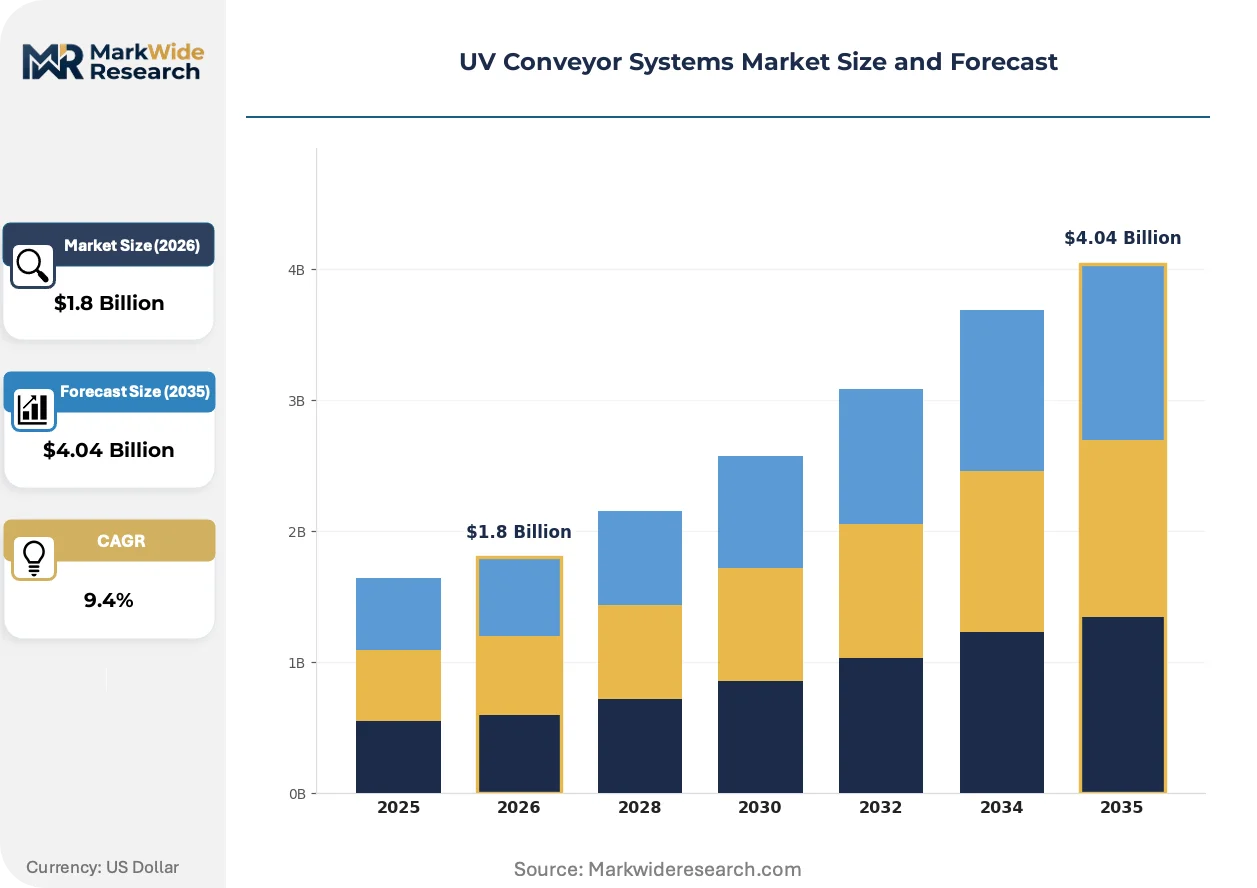
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Conveyor, Belt Conveyor, Modular Conveyor, Wire Mesh Conveyor End User: Healthcare, Food & Beverage, Electronics, Automotive Installation: Fixed, Portable, Integrated, Customizable Technology: LED, Mercury Vapor, Microwave, Others |
| Companies Covered | UVITRON, Dymax Corporation, American Ultraviolet, Systematic Automation Inc., UV Light Technology Limited, CureUV.com, Nordson Corporation, IST METZ GmbH, Excelitas Technologies Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Conveyor Systems Market Evolving Landscape
Digital intensity control architectures and semiconductor-based source technologies are converging to displace electromechanical legacy systems, redefining how conveyor operators procure, operate, and maintain UV curing infrastructure.
Semiconductor UV-C LED arrays are consolidating wavelength precision and instantaneous on-off capability into single-source platforms that eliminate warm-up delays and mercury handling protocols. Medical device sterilization facilities in the United States are specifying these systems for validated production lines where dose repeatability governs regulatory approval. The technology is consolidating previously separate mechanical shutter, cooling, and arc-lamp replacement workflows into unified solid-state modules with predictive failure monitoring.
EPA mercury lamp disposal rules are tightening enforcement thresholds for industrial waste streams containing gaseous mercury, forcing facility operators to accelerate capital planning for LED retrofits ahead of original depreciation schedules. Automotive coating plants in Michigan and South Carolina face compressed compliance timelines as state environmental agencies align with federal hazardous waste classifications. Tier-one suppliers are responding by bundling LED source upgrades with extended service contracts that transfer regulatory liability to equipment vendors.
Conveyor operators are unbundling capital acquisition from performance guarantees through irradiance-based service agreements where vendors retain source ownership and charge per cured unit. Electronics contract manufacturers in Shenzhen and Dongguan are piloting these models to eliminate upfront LED module capex while locking in dose consistency for high-mix PCB production. The shift is most visible in Asia-Pacific surface-mount technology facilities where depreciation pressures and rapid product changeovers favor operational expenditure structures over equipment ownership.
UV Conveyor Systems Market Segmentation
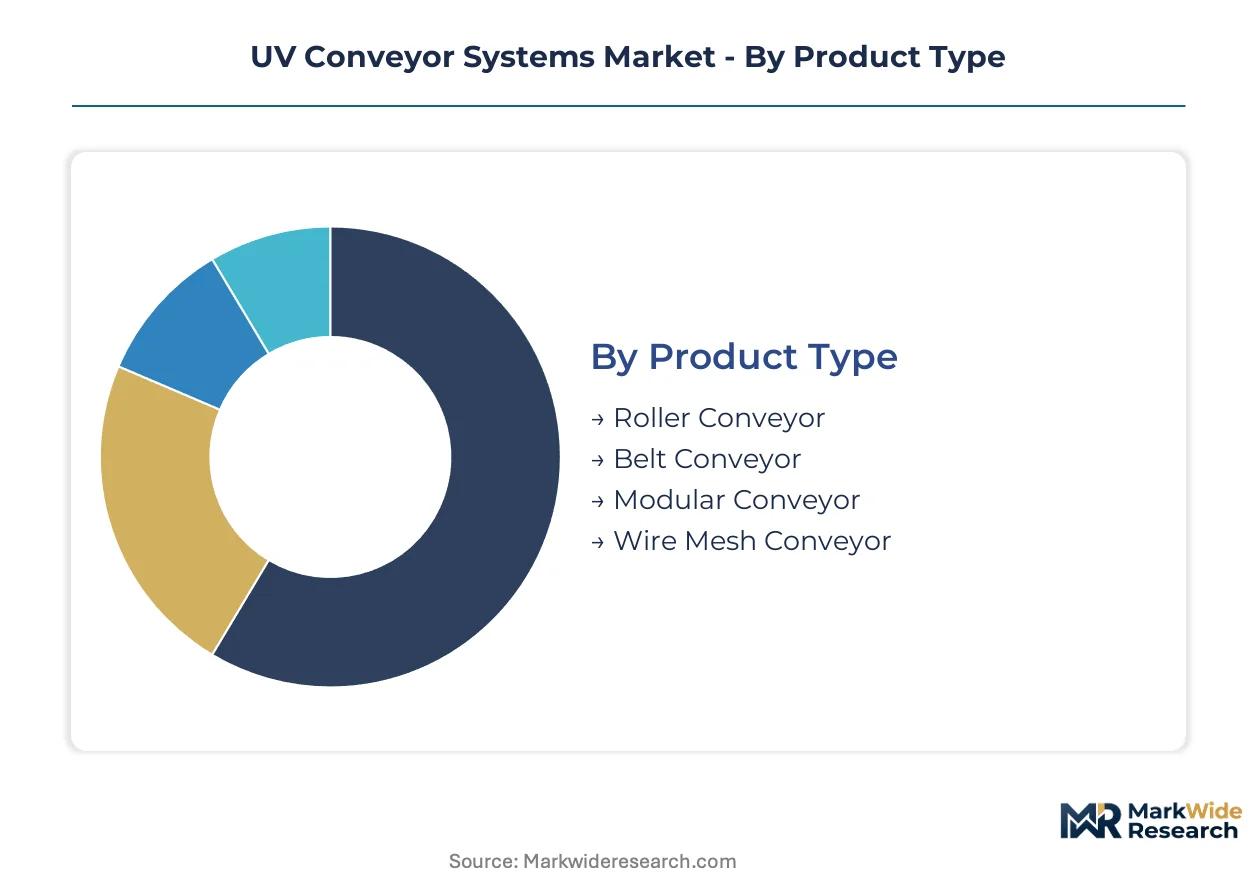
UV conveyor system procurement diverges sharply across substrate handling requirements, sterilization protocols, and source technologies. Specification choices determine energy consumption profiles, regulatory compliance burdens, and reconfiguration flexibility for batch-size-one production.
Product Type:
Belt geometries dominate where flat or contoured substrates require consistent irradiance exposure across variable throughput speeds.
- Belt Conveyor:Flat or contoured belts transport substrates through UV zones at speeds from 1 to 30 meters per minute. Electronics manufacturers in Germany and China specify these for high-throughput PCB curing where flexible substrate handling governs line efficiency.
- Modular Conveyor:Plug-and-play segments reconfigure without mechanical overhaul. Batch-size-one manufacturing trends in German automotive paint lines are concentrating specification here as plants demand rapid layout changes for mixed-model production.
- Roller Conveyor:Cylindrical rollers handle rigid substrates and heavy loads in continuous processing environments. Metal finishing operations favor these configurations for coating cure cycles.
- Wire Mesh Conveyor:Open-weave metal belts enable 360-degree UV exposure for complex geometries. Medical device sterilization facilities deploy these where shadow-free irradiance validates FDA compliance.
Mature deployment sits with Belt Conveyor configurations. Newer deployment is concentrated in Modular Conveyor systems.
End User:
Application environments dictate wavelength selection, dose validation requirements, and surface treatment protocols.
- Electronics:Surface-mount technology facilities require precision curing of adhesives and conformal coatings on miniaturized PCB assemblies. Shenzhen and Dongguan contract manufacturers are expanding UV tunnel capacity for flexible substrate throughput.
- Automotive:Paint lines and coating operations demand solvent-free cure cycles under tightening ECHA VOC thresholds. Michigan and South Carolina assembly plants face compressed compliance timelines for mercury-to-LED conversions.
- Healthcare:FDA validation governs UV-C sterilization deployments in hospital central sterile supply departments. United States medical device producers specify dose-repeatable systems for regulatory approval.
- Food & Beverage:FDA food contact surface regulations are opening UV-C applications for conveyor-treated flexible films in protein processing facilities.
Electronics and Automotive command the largest installed bases. Healthcare represents the steepest expansion trajectory as antimicrobial protocols extend beyond industrial curing.
Installation:
Capital deployment models range from permanent infrastructure to reconfigurable equipment-as-service structures.
- Fixed:Permanent installations anchor high-volume production lines where throughput predictability justifies dedicated infrastructure. Legacy automotive paint facilities in Germany operate predominantly fixed configurations.
- Integrated:UV sources embedded within existing production lines require seamless PLC communication. Brownfield automotive plants face complexity integrating modern source management with proprietary control architectures.
- Portable:Mobile units serve temporary sterilization needs and contract manufacturing flexibility. Electronics job shops in Dongguan deploy these for high-mix, low-volume contracts.
- Customizable:Specification-built systems accommodate unique substrate geometries or multi-stage cure protocols. Medical device sterilization facilities favor these for validated production lines.
Fixed installations retain the largest footprint. Integrated and Customizable configurations are gaining share fastest as brownfield retrofits and validation requirements reshape procurement.
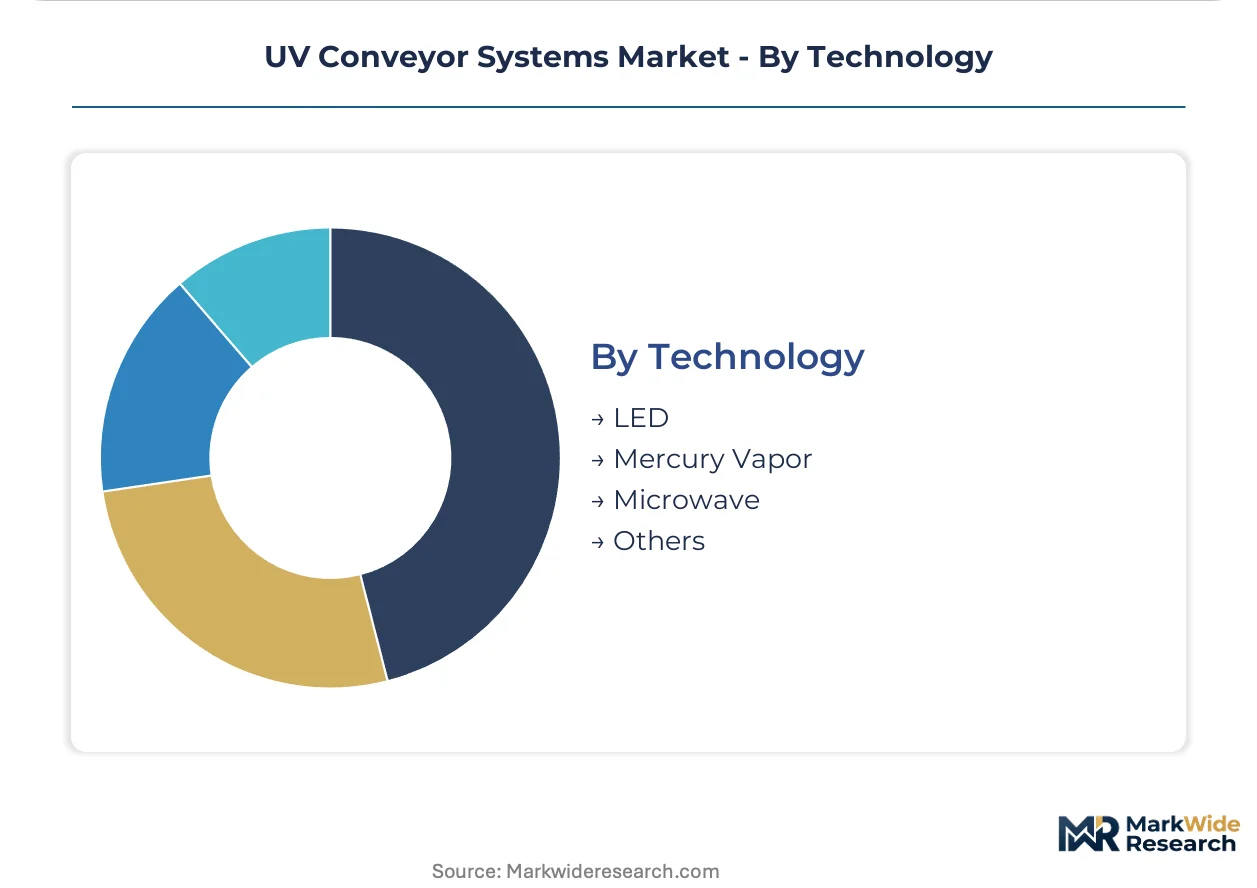
Technology:
Source architecture determines energy efficiency, mercury compliance exposure, and wavelength precision.
- LED:Semiconductor-based sources eliminate warm-up delays and mercury handling protocols. EPA disposal rules for gaseous mercury are accelerating LED specification in United States facilities ahead of original depreciation schedules.
- Mercury Vapor:Legacy arc-lamp technology retains installed base in cost-sensitive applications. Hazardous waste handling costs under EPA restrictions are compressing replacement cycles despite operational savings.
- Microwave:Electrodeless lamp excitation extends source lifetime in high-duty-cycle environments. Specialty coating operations specify these where continuous operation dominates.
- Others:Emerging excimer and laser-based sources address niche wavelength requirements. Research applications and semiconductor lithography represent primary demand pockets.
Mercury Vapor retains legacy dominance. LED is displacing predecessor technologies across all high-throughput segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen and Dongguan anchor electronics manufacturing demand for UV conveyor systems, with contract manufacturers expanding high-throughput curing tunnels for flexible PCB substrates. EPA mercury disposal rules and ECHA REACH enforcement are compressing replacement cycles across automotive paint lines in Michigan and Bavaria.
United States
Automotive coating plants in Michigan and South Carolina face compressed compliance timelines for mercury-to-LED conversions under EPA hazardous waste classifications. FDA validation requirements govern UV-C sterilization deployments in hospital central sterile supply departments. Medical device producers in Minnesota and Massachusetts specify dose-repeatable systems for regulatory approval.
Germany
Automotive paint lines in Bavaria and Baden-Württemberg demand solvent-free cure cycles under tightening ECHA VOC thresholds. Batch-size-one manufacturing trends in Stuttgart industrial corridors drive specification for modular conveyor segments. REACH framework substance restrictions impose registration obligations on UV system components sold across European member states.
China
Surface-mount technology facilities in Shenzhen and Dongguan expand UV tunnel capacity for miniaturized PCB assemblies. Contract manufacturers pilot irradiance-based service agreements to eliminate upfront LED module capex. MIIT industrial standards and dual carbon goals accelerate semiconductor-based source adoption in high-mix production environments.
Japan
Precision electronics manufacturers in Kanto and Kansai regions specify UV curing for conformal coatings on advanced substrate assemblies. METI energy efficiency directives favor LED source retrofits in legacy industrial facilities. Optical engineering expertise concentrates in Nagoya industrial clusters for deep UV-C optical design applications.
South Korea
Display panel and semiconductor packaging facilities in Seoul Capital Area deploy UV conveyor systems for adhesive curing and surface sterilization. MFDS medical device regulations shape validation requirements for healthcare applications. Busan-Ulsan industrial complexes integrate UV-C sterilization into food contact surface treatment protocols for protein processing.
UV Conveyor Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the UV conveyor systems landscape. The vendor base stratifies between integrated system OEMs, specialized source technology providers, and regional fabrication houses. Three archetypes dominate: multinational industrial equipment conglomerates with global service infrastructure, European precision engineering specialists, and Asia-Pacific contract manufacturers. Competitive moves center on LED source module integration partnerships and predictive maintenance subscription models.
Among US-based industrial equipment providers, Nordson Corporation and Dymax Corporation represent the multinational conglomerate archetype with anchored positions in automotive coating and electronics assembly lines. IST METZ GmbH exemplifies the European precision engineering specialist, while UVITRON occupies a position within the North American fabrication tier serving mid-market electronics manufacturers.
| Leading Market Players |
|---|
| UVITRON |
| Dymax Corporation |
| American Ultraviolet |
| Systematic Automation Inc. |
| UV Light Technology Limited |
| CureUV.com |
| Nordson Corporation |
| IST METZ GmbH |
| Excelitas Technologies Corp. |
| Others |
Value Network & Pricing Analysis
Electronics contract manufacturers in Shenzhen and Dongguan demanding irradiance-based service agreements are forcing equipment vendors to retain source ownership and absorb upfront LED module capex, compressing margins and restructuring supplier cash flow cycles toward per-cured-unit revenue streams.
Pricing Analysis
Cost-down pressure on mid-tier system integrators accelerates because semiconductor die supply concentrates among East Asian foundries, exposing vendors to input price volatility. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated medical sterilization systems from automotive paint line configurations and portable electronics job shop units. Price differentiation hinges on certification grade and after-sales service bundling. Tier-one automotive suppliers in Michigan exhibit lowest price sensitivity due to regulatory liability transfer requirements, while contract manufacturers in Dongguan face acute capex constraints.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for deep UV-C LED semiconductor dies, while China dominates optical component fabrication and Germany anchors precision mechanical subsystem engineering. Raw material dependencies include gallium nitride wafers, aluminum nitride substrates, and quartz optical elements. Supply chain risk centers on tariff exposure for semiconductor modules crossing regional trade boundaries. Distribution runs through direct OEM relationships for large automotive and electronics accounts, with regional fabrication houses serving mid-market customers via distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UV conveyor systems market sits in a technology-transition phase where semiconductor-based LED sources are displacing legacy mercury vapor installations, reconfiguring vendor revenue models and procurement structures across industrial curing and sterilization applications.
For Market Incumbents: To counter margin compression from irradiance-based service agreements, prioritize backward integration into LED module assembly and predictive maintenance software stacks. Anchor long-term contracts through global service infrastructure investments in automotive coating corridors. Defend technology leadership by deepening specialization in mercury-to-LED retrofit architectures for brownfield paint lines.
For New Entrants and Emerging Players: Systems integrators in secondary electronics manufacturing clusters represent the most penetrable channel partner type for modular conveyor segment sales. Target antimicrobial food packaging applications for UV-C sterilization in protein processing facilities where FDA food contact surface regulations are opening new specification pathways. Enter through plug-and-play conveyor segment partnerships with German automotive suppliers demanding batch-size-one reconfiguration capability.
For Investors and Strategic Acquirers: The window for entry favors precision optical engineering specialists with deep UV-C design expertise. Long-term viability over the next decade rests on capturing semiconductor source integration capabilities and software-defined intensity control platforms. Watch for inflection where IEC photobiological certification timelines compress from twelve to six months, signaling regulatory maturation enabling faster product launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| LED Source Module Integration | Semiconductor-based sources eliminate EPA mercury disposal compliance costs for United States facilities. |
| Predictive Maintenance Subscription | Remote monitoring platforms generate recurring revenue attachment for system OEMs serving automotive lines. |
| Modular Conveyor Segment Development | Plug-and-play configurations capture German automotive demand for batch-size-one manufacturing flexibility. |
| FDA Validation Pathway Investment | Dose-repeatable systems unlock hospital central sterile supply department procurement in United States healthcare. |
| Optical Engineering Specialist Acquisition | Deep UV-C design expertise resides in narrow labor pools constraining manufacturer expansion timelines. |
Research Methodology
Independent corroboration across primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors, combined with secondary validation through SEC 10-K filings, customs and trade data, EPA hazardous waste enforcement records, and IEC photobiological safety standards, underwrites the qualitative findings. Bottom-up demand modeling across end-user segments triangulates against top-down supply-side capacity assessments.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by source technology, conveyor configuration, installation type, and end-user industry. CAGRs derive from weighted average of segment-specific growth coefficients calibrated to regulatory enforcement timelines and capital expenditure survey data. Forecast inputs include ECHA REACH VOC threshold implementation schedules and MIIT industrial standards adoption curves for semiconductor-based sources.
Caveats apply where EPA mercury disposal rule enforcement intensity or IEC certification timeline compression could materially shift the outlook. Forecasts reflect documented assumptions about LED module cost curves and foundry capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Ultrasonic Cleaning Equipment Market
Industrial Equipment
Dust Extraction System Market
Industrial Equipment
Global Servo Motor Market
Industrial Equipment
Air Preparation Equipment (FRL) Market
Industrial Equipment
Robotic Ultrasonic NDT Cells for Weld and Pressure Vessel Inspection Market
Industrial Equipment
Europe Vacuum Pump Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Femtosecond Fiber Lasers Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Demagnetizer Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
Actuators Market
Industrial Equipment
Rotary Scroll Air Compressor Market
Industrial Equipment
Global Industrial Weighing Machines Market