
 Digital Audio IC Market | 2026-2036
Digital Audio IC Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Audio IC Market Outlook
Market Context
Gallium nitride is restructuring power-stage economics in Class-D amplifier stages, trimming heat dissipation requirements and enabling smaller form factors. Texas Instruments leverages captive GaN-on-Si foundry partnerships to protect amplifier margins. Cirrus Logic anchors its position through CODEC specialization for smartphone OEMs. Qualcomm competes by integrating audio DSP cores with Bluetooth protocol stacks in single-die solutions.
Technical Definition and Segment Structure
Digital Audio ICs are mixed-signal semiconductor devices that convert, process, or amplify audio signals between analog and digital domains, typically operating at sampling rates from 44.1 kHz to 384 kHz with 16-bit to 32-bit resolution. These components serve as the signal-chain backbone in consumer electronics, automotive infotainment, and professional broadcasting equipment. Bluetooth-enabled ICs represent the fastest-expanding technology segment, driven by TWS earbuds and wireless speaker protocols. Codec integration dominates value capture, combining ADC, DAC, and signal processing in single-package solutions that command premium positioning. Wired analog architectures persist in professional audio and automotive head units where latency tolerance is minimal.
Regulatory Environment
FCC Part 15 emissions standards in the United States and CE marking under the EU Radio Equipment Directive constrain transmitter-integrated audio SoC designs. Japan's METI enforces energy-efficiency benchmarks for battery-powered audio devices. China's MIIT certifies wireless transmission modules through SRRC type-approval processes. Stakeholders must track harmonization gaps between regional RF certification regimes before committing to single-platform Bluetooth LE Audio architectures.
Market Dynamics
Semiconductor foundries are reallocating 12-inch wafer capacity toward mixed-signal audio devices as GaN-on-Si processes mature, compressing amplifier thermal budgets and enabling smaller Class-D stages in portable electronics.
Growth Catalysts
- EU F-Gas Regulation:Halogen-free substrate mandates are accelerating material transitions in high-layer-count PCBs for automotive head units and professional audio gear.
- Bluetooth LE Audio:The Auracast broadcast protocol is creating new deployment models in public venues, transportation hubs, and assistive listening systems.
- China TWS ecosystem:Domestic OEM qualification programs for local codec suppliers are reshaping procurement patterns in Shenzhen and Dongguan manufacturing clusters.
Market Restraints
- 12-inch wafer allocation constraints:Foundry capacity for 40nm-28nm mixed-signal nodes remains tight as automotive and industrial demand competes for the same process technology.
- Indium phosphide substrate costs:High-performance optical audio interfaces face input cost volatility from limited III-V compound semiconductor supply.
- REACH SVHC compliance:Substance of very high concern candidate list expansions are forcing reformulation of solder masks and conformal coatings in EU-bound products.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing are attracting audio IC packaging and testing investments to Gujarat and Tamil Nadu.
- Automotive zonal audio:Ethernet-based A2B and AVB protocols are converging with domain controller architectures in electric vehicle cabin designs.
- Japan METI energy efficiency:Battery-powered device benchmarks are creating preference pull for ultra-low-power voice-activated codec implementations.
Industry Challenges
- RF coexistence certification:Bluetooth 5.3 and Wi-Fi 6E module integration requires complex electromagnetic compatibility validation timelines for simultaneous operation.
- Analog design talent scarcity:Mixed-signal IC layout expertise is concentrating among senior practitioners as university programs emphasize digital specializations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Audio IC Market |
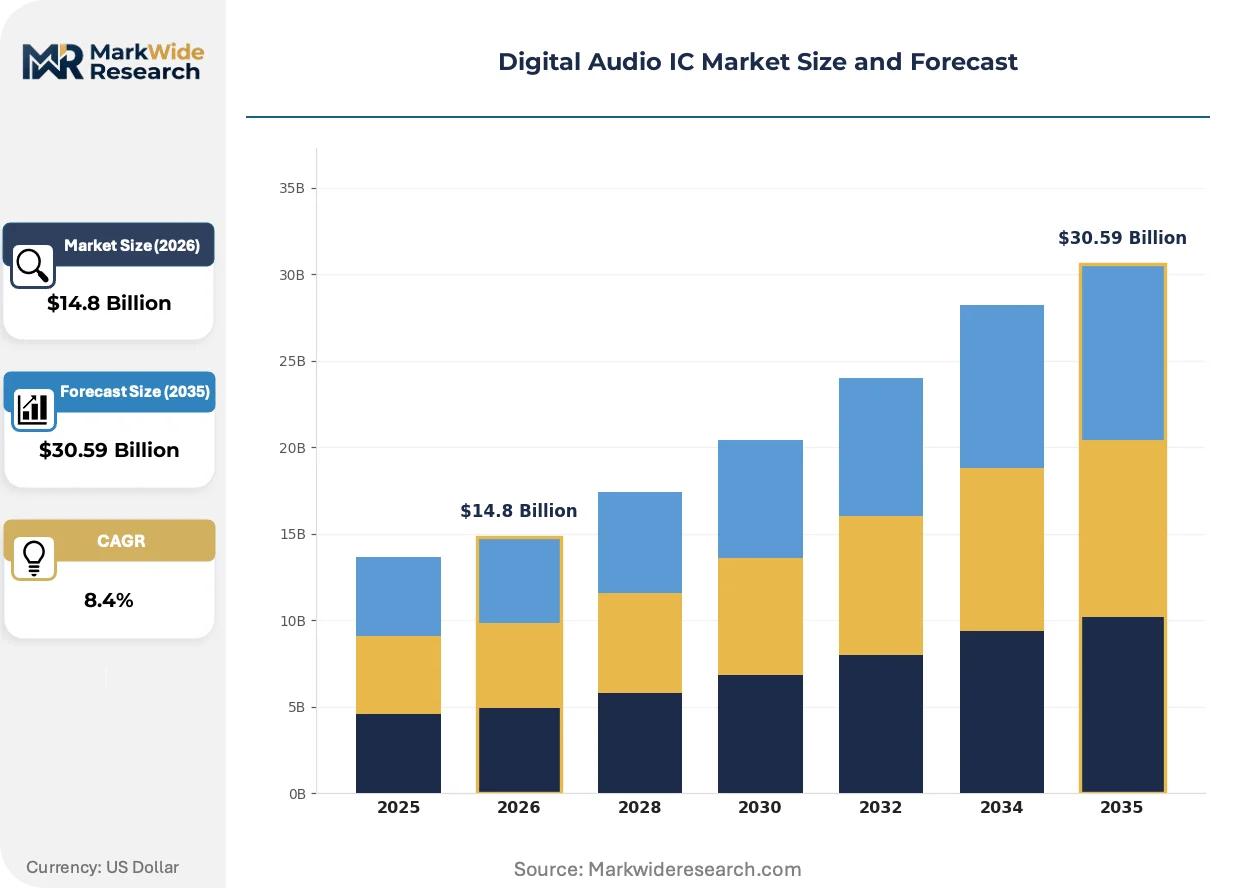
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DAC, ADC, Amplifier, Codec Technology: Bluetooth, Wi-Fi, Wired, Analog End User: Consumer Electronics, Automotive, Professional Audio, Telecommunications Application: Home Audio Systems, Wearable Devices, Mobile Phones, Broadcasting |
| Companies Covered | Texas Instruments, Analog Devices, Cirrus Logic, STMicroelectronics, NXP Semiconductors, Infineon Technologies, Renesas Electronics, Qualcomm, Realtek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Audio IC Market Strategic Shifts
Audio semiconductor architectures are pivoting from discrete component stacks toward highly integrated SoC platforms, with software-defined signal paths displacing fixed-function analog blocks across consumer and automotive tiers.
AI-driven noise suppression and spatial audio rendering are rewriting the functional boundary between hardware codecs and cloud-based processing. Smartphone OEMs are adopting neural audio accelerators that partition workloads between on-device inference and edge servers. This architecture is compressing the traditional premium tier for dedicated DSP silicon in mid-range devices.
China's MIIT SRRC type-approval processes are tightening transmitter power specifications for 2.4GHz audio devices, extending certification timelines by three to six months for foreign suppliers. Manufacturers are responding with pre-certified module strategies that shift regulatory burden to domestic distributors. The policy friction is most acute for TWS products targeting China's e-commerce festival cycles.
Automotive audio procurement is migrating from tier-one supplier dominance toward direct OEM engagement with semiconductor vendors. European premium marques are establishing technical centers in Munich and Stuttgart for acoustic tuning collaboration. This disintermediation is visible most clearly in electric vehicle platforms where cabin noise profiles differ fundamentally from internal combustion architectures.
Digital Audio IC Market Segmentation
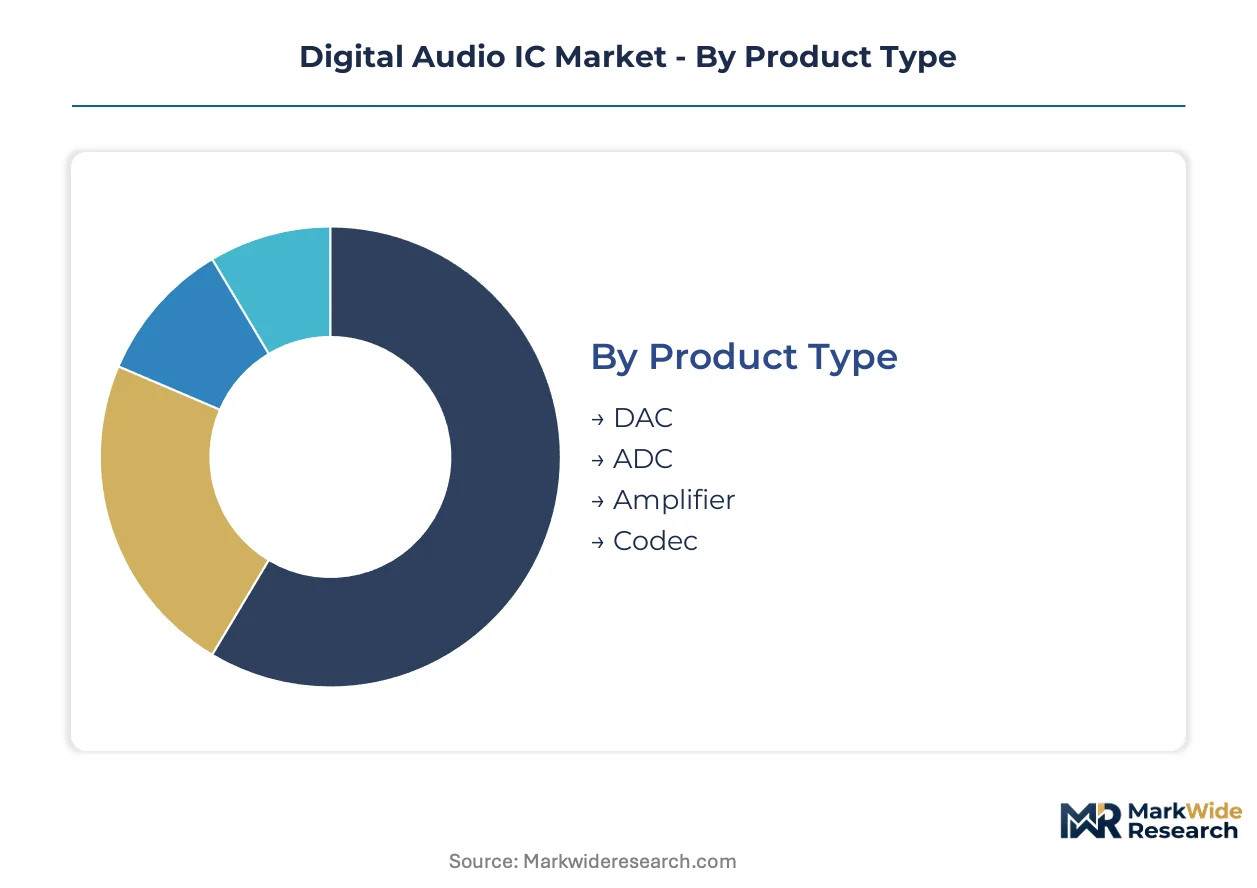
Audio IC procurement patterns diverge sharply across signal-chain positions, with integration levels and wireless certification burdens determining vendor selection criteria. Manufacturers optimize die size and thermal budgets differently depending on whether the target application prioritizes battery life, latency tolerance, or channel density.
Product Type:
Codec integration demands the heaviest upfront mask costs due to multi-domain analog-digital fusion, while discrete converters suit lower-volume professional tiers with looser power constraints.
- Codec:Single-package solutions merge ADC, DAC, and DSP cores for smartphone OEMs and TWS earbuds. Demand concentrates in Shenzhen manufacturing clusters where domestic qualification programs are displacing foreign suppliers. Mixed-signal layout expertise scarcity is lengthening design cycles for 28nm implementations.
- Amplifier:Class-D stages leveraging GaN-on-Si processes are trimming heat dissipation requirements in portable electronics. Automotive head units in Stuttgart and Munich technical centers specify these for electric vehicle cabin architectures where thermal budgets are tighter than internal combustion platforms.
- DAC:Standalone converters serve professional audio interfaces requiring 32-bit resolution and sub-nanosecond jitter specifications. Mastering studios in London and Nashville maintain demand for discrete architectures.
- ADC:Front-end digitization for broadcasting and live sound applications. Broadcast trucks across North America specify these for multi-channel concert recording.
Most installed capacity flows through Codec. Expansion is steepest in Amplifier.
Technology:
Wireless protocol integration determines certification timeline length, with Bluetooth LE Audio creating new deployment models against Wi-Fi 6E coexistence complexity.
- Bluetooth:LE Audio and Auracast broadcast protocols are restructuring public venue deployments in transportation hubs and assistive listening systems. China's MIIT SRRC type-approval processes are extending certification timelines by three to six months for foreign suppliers targeting e-commerce festival cycles.
- Wired:Ethernet-based A2B and AVB protocols are converging with zonal audio architectures in electric vehicles. European premium marques specify these for deterministic latency in cabin domain controllers.
- Wi-Fi:Multi-room synchronized streaming for residential installations. Whole-home audio deployments in California and New York metro areas favor these for bandwidth headroom.
- Analog:Persistent in professional monitoring and vintage equipment restoration. Recording studios in Tokyo and Berlin maintain demand for discrete op-amp signal paths.
Bluetooth captures the greatest volume of new design wins. Wired is climbing the fastest in automotive procurement.
End User:
Automotive qualification cycles stretch three to five years, while consumer electronics refresh annually, compressing margin structures for suppliers serving both tiers.
- Consumer Electronics:TWS earbuds and smart speakers dominate unit volume. Dongguan manufacturing clusters are qualifying local codec suppliers under domestic OEM programs.
- Automotive:Zonal audio architectures in electric vehicles require A2B protocol integration. Cabin noise profiles differ fundamentally from internal combustion platforms, demanding retuned DSP coefficients.
- Professional Audio:Broadcast and live sound applications prioritize channel density and deterministic latency. OB trucks across Germany specify redundant converter architectures.
- Telecommunications:VoIP infrastructure and conferencing endpoints. Enterprise deployments in Singapore and Sydney are refreshing codec fleets for hybrid work patterns.
Consumer Electronics absorbs the greatest wafer output. Automotive is expanding most quickly in absolute dollar terms.
Application:
Wearable devices impose the most severe power constraints, driving ultra-low-power voice-activated implementations under Japan METI energy efficiency benchmarks.
- Wearable Devices:TWS earbuds and hearing aids demand sub-milliwatt standby consumption. Japan METI benchmarks are creating preference pull for voice-activated codec implementations.
- Mobile Phones:Smartphone OEMs are adopting neural audio accelerators that partition workloads between on-device inference and edge servers. This architecture compresses the traditional premium tier for dedicated DSP silicon.
- Home Audio Systems:Soundbars and multi-room speakers. Residential installations in Seoul and São Paulo favor wireless protocols for retrofit convenience.
- Broadcasting:Radio transmission and streaming infrastructure. Public broadcasters in Paris and Vienna maintain upgrade cycles for HD Radio and DAB+ transitions.
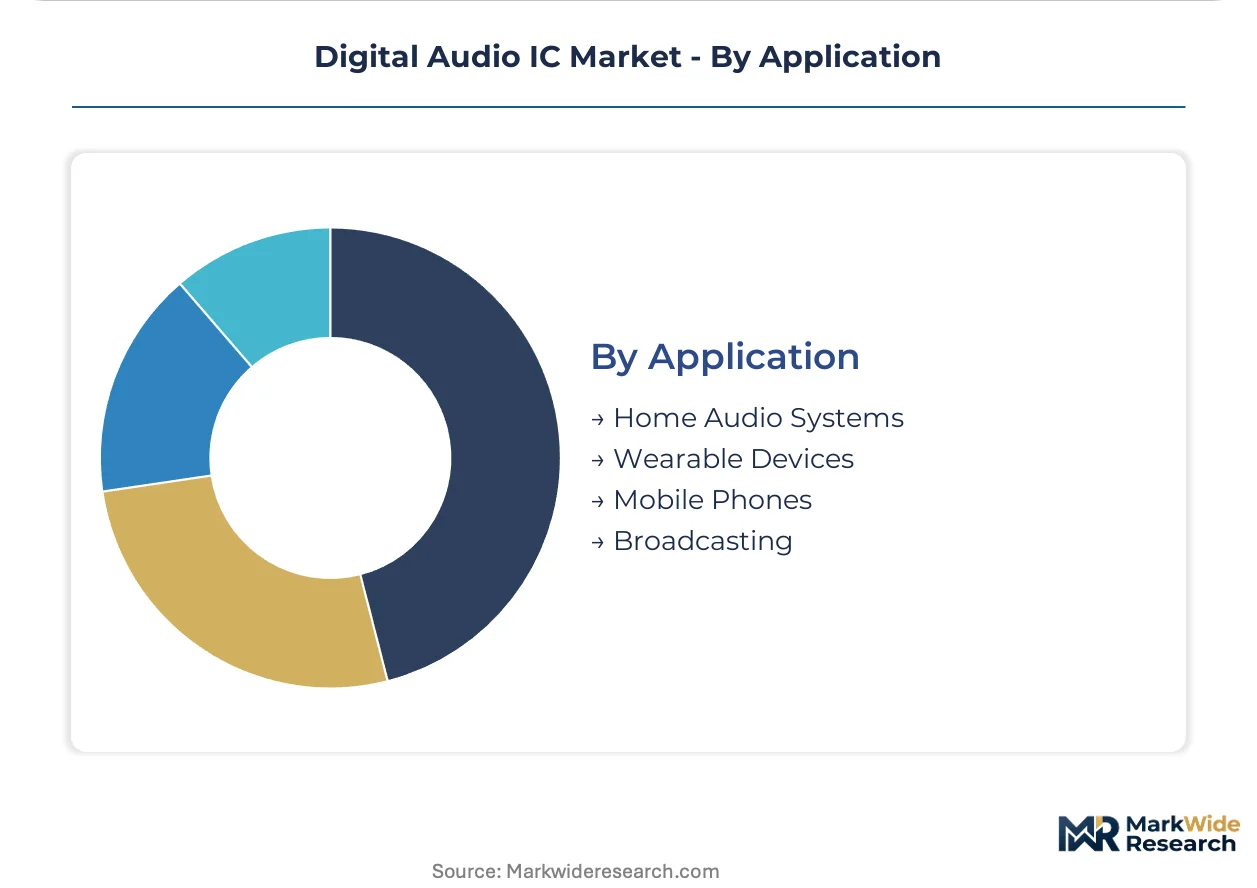
Mobile Phones commands the largest single-application revenue pool. Wearable Devices is gaining share fastest on unit volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's manufacturing ecosystem anchors procurement patterns for codec suppliers serving TWS and smart speaker OEMs. Domestic qualification programs are displacing foreign vendors in Dongguan clusters. The report examines five countries where audio IC demand concentrates across consumer electronics, automotive, and professional tiers.
China
Domestic OEM qualification programs are reshaping procurement in Shenzhen and Dongguan manufacturing clusters. MIIT's SRRC type-approval processes extend certification timelines by three to six months for foreign suppliers targeting e-commerce festival cycles. Local codec vendors are capturing share in TWS earbuds as smartphone OEMs diversify supply chains.
United States
FCC Part 15 emissions standards constrain transmitter-integrated audio SoC designs for consumer electronics. Smartphone OEMs in California are adopting neural audio accelerators that partition workloads between on-device inference and edge servers. Texas Instruments leverages captive GaN-on-Si foundry partnerships to protect amplifier margins.
Germany
European premium automotive marques are establishing technical centers in Munich and Stuttgart for acoustic tuning collaboration. EU F-Gas Regulation and REACH compliance push manufacturers toward halogen-free substrate materials in high-layer-count PCBs. Zonal audio architectures in electric vehicles require A2B protocol integration with domain controllers.
Japan
METI enforces energy-efficiency benchmarks for battery-powered audio devices, creating preference pull for ultra-low-power voice-activated codec implementations. Kanto region semiconductor fabricators supply mixed-signal devices for hearing aids and wearables. Broadcast infrastructure in Tokyo maintains upgrade cycles for professional audio equipment.
India
Production-linked incentives for electronics manufacturing are attracting audio IC packaging and testing investments to Gujarat and Tamil Nadu. BIS certification requirements for wireless transmission modules create regulatory friction for imported components. Domestic OEMs in Bengaluru are qualifying local suppliers for smart speaker and soundbar production.
Digital Audio IC Market Competitive Environment
Capacity expansion dominates the current landscape as semiconductor foundries reallocate 12-inch wafer resources toward mixed-signal audio devices. The vendor base stratifies across three tiers: diversified semiconductor conglomerates with captive foundry access, fabless specialists concentrating on CODEC integration, and regional suppliers serving cost-optimized consumer tiers. M&A activity and strategic partnerships represent the primary competitive vectors as firms secure GaN-on-Si process technology and Bluetooth protocol stack integration.
Among diversified semiconductor conglomerates, Texas Instruments and Qualcomm exemplify scale-driven positioning through captive manufacturing and protocol integration respectively. Cirrus Logic occupies a specialist tier focused on CODEC optimization for smartphone OEMs. Analog Devices and STMicroelectronics represent European and American anchors in automotive and industrial audio segments. These five entities illustrate the competitive archetypes—integrated conglomerate, fabless specialist, and diversified industrial supplier—that structure procurement decisions across consumer, automotive, and professional end markets.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| Cirrus Logic |
| STMicroelectronics |
| NXP Semiconductors |
| Infineon Technologies |
| Renesas Electronics |
| Qualcomm |
| Realtek |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM qualification cycles stretching three to five years are forcing foundries to reserve 12-inch wafer capacity for mixed-signal audio devices under long-term offtake agreements, compressing spot-market availability and amplifying price volatility for consumer-tier codec procurement.
Pricing Analysis
GaN-on-Si substrate costs and 28nm mask charges pass through directly to Class-D amplifier and integrated codec quotations. Three-tier pricing structure across premium, standard, and economy levels separates automotive-qualified parts with AEC-Q100 certification from consumer-tier alternatives. Cost compression in TWS earbuds intensifies because Shenzhen OEMs are consolidating supplier panels around domestic codec vendors. Consumer electronics buyers exhibit highest price sensitivity; automotive procurement teams prioritize thermal reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Singapore and Hong Kong manage hub-and-spoke fulfillment for Asia-Pacific manufacturing clusters. Taiwan, South Korea, and China anchor wafer fabrication for mixed-signal audio devices. Indium phosphide substrates, gallium nitride epiwafers, and halogen-free laminates constitute critical input dependencies. Single-source vulnerability concentrates in III-V compound semiconductor supply for optical audio interfaces. Distribution runs through authorized distributors serving Shenzhen and Dongguan electronics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaN-on-Si process maturation is compressing amplifier thermal budgets and enabling premium-tier positioning for Class-D stages, expanding margin capture for suppliers with captive foundry access.
For Market Incumbents: To counter domestic codec qualification programs in Shenzhen manufacturing clusters, Texas Instruments and Qualcomm should deepen captive GaN-on-Si foundry partnerships while accelerating AEC-Q100 certification pipelines for automotive zonal audio architectures. Channel control through pre-certified module strategies shifts China's MIIT SRRC regulatory burden toward domestic distributors. For New Entrants and Emerging Players: Direct-to-OEM engagement models bypass tier-one supplier dominance in European electric vehicle platforms. White-space concentrates in India PLI scheme packaging investments for Gujarat and Tamil Nadu facilities. Voice-activated codec implementations under Japan METI benchmarks offer the most penetrable premium tier. Technical center partnerships with Stuttgart acoustic tuning clusters provide go-to-market credibility. For Investors and Strategic Acquirers: Asymmetric upside sits with fabless specialists holding Bluetooth LE Audio protocol stack integration and 28nm mixed-signal layout expertise. Long-term viability hinges on automotive qualification pipeline depth and electric vehicle platform content expansion. Watch for Auracast broadcast protocol deployment velocity in transportation hubs as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-Si Process Partnership | Captive foundry access protects Class-D amplifier margins against substrate cost volatility. |
| Bluetooth LE Audio Integration | Single-die DSP and protocol stack solutions capture TWS OEM design wins in Shenzhen. |
| AEC-Q100 Certification Pipeline | Automotive qualification unlocks zonal audio procurement from Munich and Stuttgart marques. |
| Pre-Certified Module Strategy | Domestic distributor partnerships compress China MIIT SRRC approval timelines for foreign suppliers. |
| Technical Center Establishment | Acoustic tuning collaboration in European automotive clusters disintermediates tier-one suppliers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with semiconductor foundry planning officers, codec vendor product managers, automotive OEM acoustic engineers, and Shenzhen electronics procurement leads with secondary validation against SEC 10-K filings, foundry capacity announcements, and MIIT SRRC certification databases. Bottom-up die-size and wafer-start estimates triangulated against top-down OEM bill-of-materials analysis.
Segment-weighting approaches distributed revenue across codec, amplifier, DAC, and ADC product types; Bluetooth, wired, Wi-Fi, and analog technology tiers; and consumer electronics, automotive, professional audio, and telecommunications end users. CAGRs derived from foundry capacity expansion schedules, electric vehicle platform launch cadences, and Bluetooth LE Audio protocol adoption curves across the analysis window. GaN-on-Si process yield assumptions and China domestic qualification program velocity shaped regional growth differentials.
The model assumes a particular technology adoption path; alternative pathways for gallium nitride power-stage integration would alter the outlook. Forecasts reflect documented assumptions around foundry allocation priorities and regulatory harmonization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Ultra Large Scale Ics Market
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market
IC (Integrated Circuits)
Global Analog Integrated Circuit (IC) Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
RFID Reader IC Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
Asia Pacific Integrated Circuit (IC) Market
IC (Integrated Circuits)
Automotive Integrated Circuit (Ics) Market
IC (Integrated Circuits)
Logic IC Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
Americas Analog IC Market
IC (Integrated Circuits)
Gate Driver IC Market
IC (Integrated Circuits)
Embedded Universal Integrated Circuit Card (eUICC) Market
IC (Integrated Circuits)
Audio Power Amplifier IC Market
IC (Integrated Circuits)
Global Interface IC Market
IC (Integrated Circuits)
Mixed-Signal Microcontroller Market