
 Body Worn Antenna Market | 2026-2036
Body Worn Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Body Worn Antenna Market Outlook
Defense equipment leasing and performance-based logistics contracts are fragmenting the traditional capital-sales model for tactical antenna procurement. BAE Systems leverages its sovereign UK manufacturing base to sustain long-term service contracts with the British Army. Cobham anchors its competitive position through specialized on-body RF integration for special operations forces across multiple NATO countries. Thales Group differentiates via vertically controlled supply chains spanning European and Asia-Pacific military customers.
Body worn antennas are compact radiating elements engineered for integration with human-carried platforms, typically operating across VHF through microwave frequencies with power handling below 50 watts and emphasizing conformal mounting to preserve operator mobility. These devices serve military dismounts, first responders, and industrial workers requiring uninterrupted voice and data connectivity without encumbering physical performance. Patch antennas dominate current military procurement volumes due to proven reliability in harsh environmental conditions, while textile antennas represent the fastest-expanding segment as conductive fiber weaving processes mature for smart uniform applications. Flexible antennas command premium positioning in healthcare and fitness tracker end uses where skin-contact biocompatibility drives material selection costs.
FCC Part 15 emissions limits govern civilian wearable RF devices in the United States, while ETSI EN 300 328 harmonizes wideband transmission standards across European markets and ITAR regulations constrain cross-border technology transfer for military-grade antenna specifications. These overlapping compliance frameworks elevate testing costs and extend product qualification timelines, particularly for dual-use technologies spanning defense and commercial markets. Stakeholders must monitor evolving spectrum allocation decisions and export control harmonization between allied defense procurement blocs.
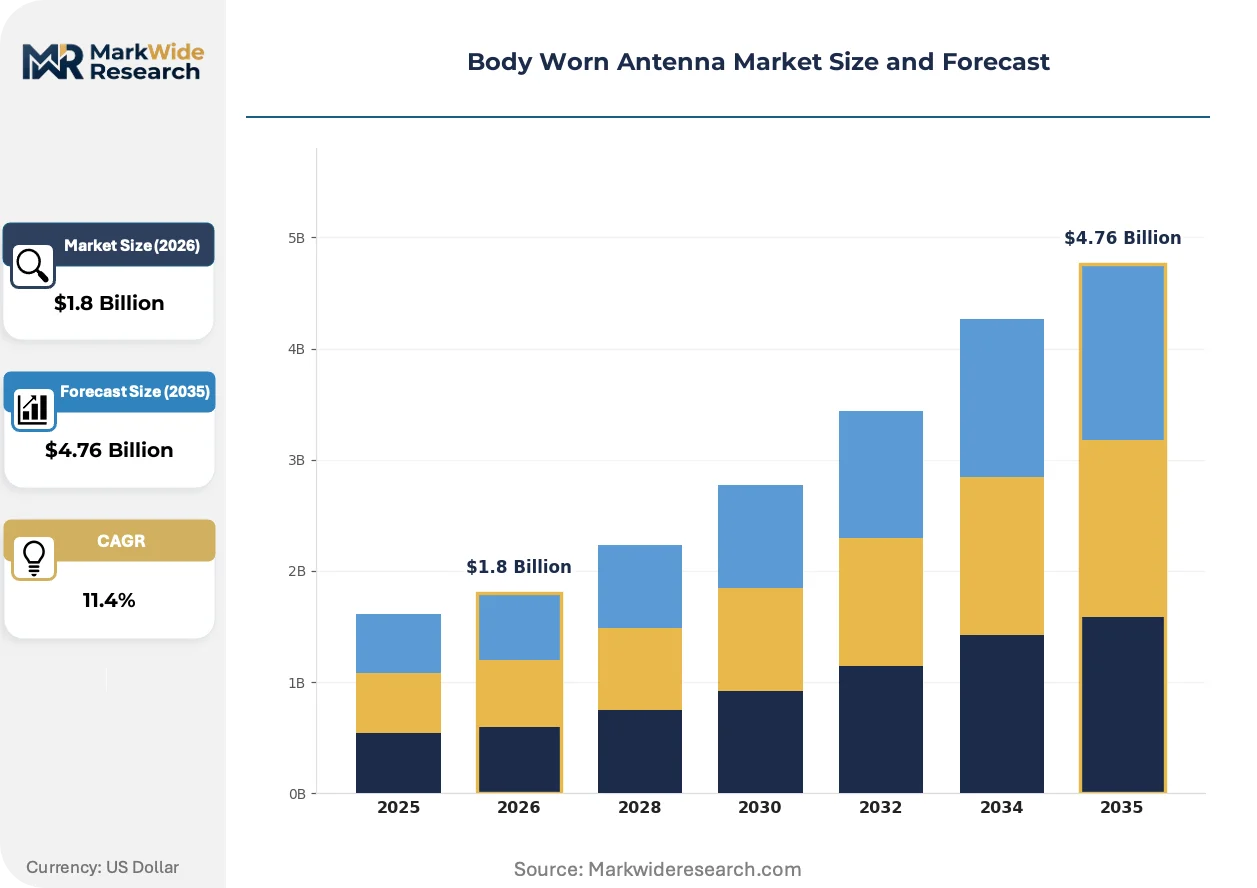
Market Dynamics
Military procurement programs across NATO member states are accelerating adoption of textile-integrated RF systems for dismounted soldier modernization, compressing supplier qualification timelines and reshaping competitive positioning around sovereign manufacturing capabilities.
Growth Catalysts
- EU Radio Equipment Directive:Tightening electromagnetic compatibility certification requirements for wearable communication devices is elevating technical barriers and consolidating demand around qualified suppliers.
- Conductive fiber weaving:Maturation of textile antenna manufacturing processes is enabling conformal RF integration into smart uniforms without compromising operator mobility.
- Bundeswehr equipment upgrades:German defense procurement is clustering supplier activity in the Munich-Ulm industrial corridor, creating localized ecosystem effects.
Market Restraints
- ITAR export controls:Cross-border technology transfer constraints for military-grade antenna specifications fragment supplier access to allied defense markets.
- Testing cost escalation:Overlapping FCC Part 15, ETSI EN 300 328, and ITAR compliance frameworks extend product qualification timelines and elevate fixed costs.
- Dual-use classification ambiguity:Technologies spanning defense and commercial applications face unpredictable regulatory routing, delaying market entry.
Strategic Opportunities
- Healthcare and fitness trackers:Flexible antennas with skin-contact biocompatibility command premium positioning where material selection costs drive differentiation.
- Performance-based logistics contracts:Defense equipment leasing is fragmenting traditional capital-sales models, creating recurring revenue streams for integrated service providers.
- First responder modernization:Public safety agencies in France and Germany are adopting body-worn RF systems for interoperable emergency communications.
Industry Challenges
- RF-human interaction modeling:Specialized electromagnetic simulation expertise for on-body propagation remains scarce, constraining design iteration speed.
- Legacy platform integration:Backward compatibility requirements with existing soldier radio systems complicate antenna interface standardization.
- Certification timeline compression:Accelerated procurement schedules conflict with extended electromagnetic compatibility validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Worn Antenna Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patch Antennas, Flexible Antennas, Textile Antennas, Embedded Antennas End User: Healthcare Professionals, Fitness Trackers, Military Personnel, Smart Clothing Users Installation: On-Body Installation, Wearable Devices, Implant Integration, Clothing Integration Technology: Passive Antennas, Active Antennas, Multi-band Antennas, Directional Antennas |
| Companies Covered | Alaris Antennas, Antenna Products, BAE Systems, Cobham, Thales Group, Northrop Grumman Corporation, Panorama Antennas Ltd, Rohde & Schwarz, Southwest Antennas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Worn Antenna Market Strategic Shifts
Textile-integrated RF architectures are displacing rigid patch configurations across military and first responder applications, compressing the trade-off between conformal wearability and electromagnetic performance.
Conductive polymer weaving is virtualizing traditional copper-trace antenna manufacturing. Special operations forces across multiple NATO countries are piloting garment-embedded VHF systems for signature reduction. This convergence is collapsing the distinction between uniform supplier and RF subsystem vendor.
REACH substance restrictions and RoHS hazardous material limits are tightening material selection criteria for wearable electronics. European manufacturers are reformulating conductive inks and substrate adhesives to maintain supply chain access. Medical and industrial wearable segments face the steepest compliance cost escalation.
Defense buyers are unbundling antenna hardware from radio platform procurement, creating standalone subsystem competitions. British and German military procurement offices now specify open-architecture RF interfaces. This pattern is most pronounced in special forces equipment refresh cycles where rapid technology insertion outweighs platform commonality.
Body Worn Antenna Market Segmentation
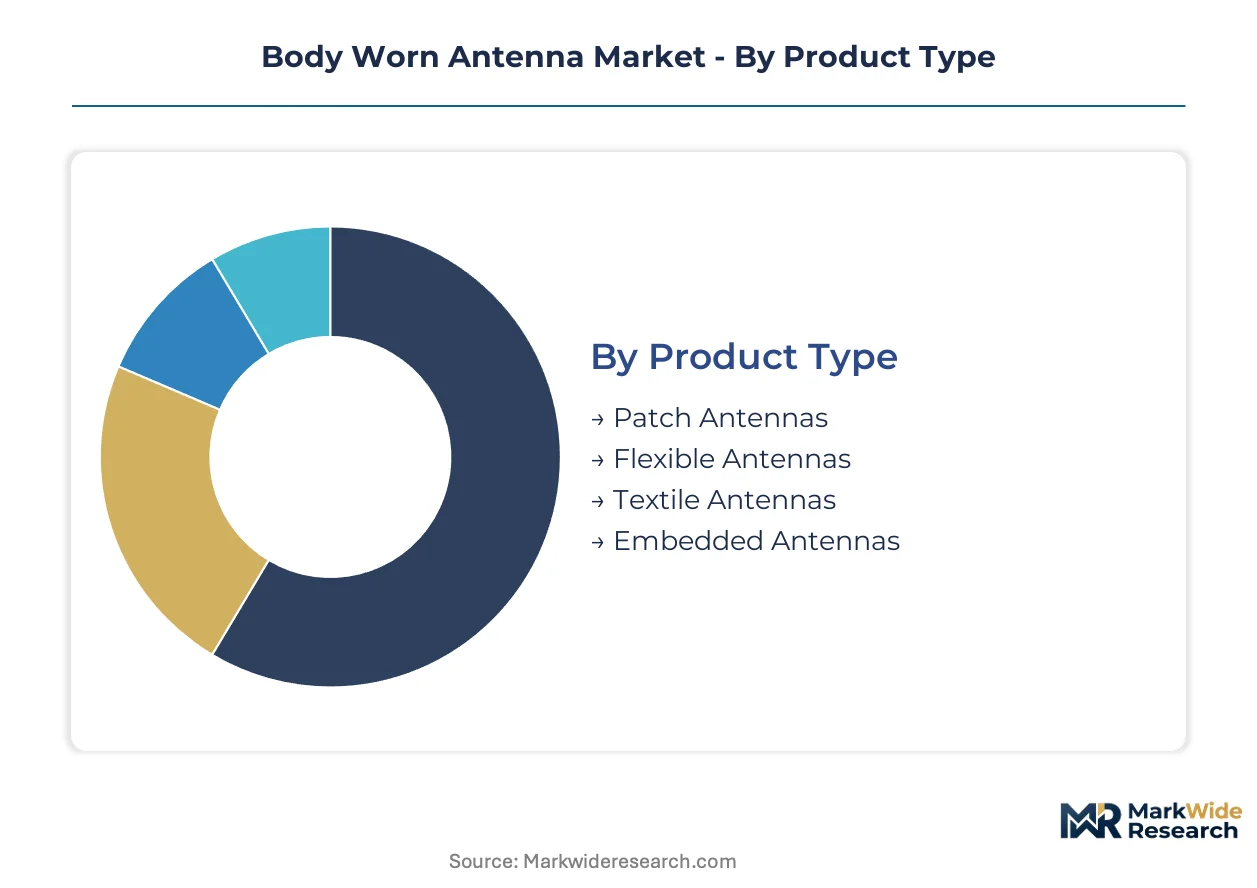
Body worn antenna procurement splits across four structural dimensions that reshape supplier priorities. Product type determines manufacturing process maturity and certification pathway. End user selection drives RF power requirements and biocompatibility standards. Installation method governs interface complexity with legacy platforms. Technology choice constrains spectrum agility and signal processing integration.
Product Type:
Cost tier separates mature volume production from emerging premium configurations.
- Patch Antennas:Rigid ceramic or composite substrates with etched copper traces deliver proven reliability in military field conditions. Bundeswehr procurement concentrates demand in Germany's defense industrial corridor around Munich and Ulm for dismounted soldier modernization programs.
- Textile Antennas:Conductive fiber weaving processes embed RF elements directly into fabric structures without compromising operator mobility. NATO special operations forces across multiple member states are piloting garment-embedded VHF systems for signature reduction.
- Flexible Antennas:Polymer substrates with printed conductive traces conform to curved body surfaces for healthcare monitoring applications.
- Embedded Antennas:Miniaturized elements integrated within device housings serve fitness tracker manufacturers requiring space-constrained RF solutions.
Patch antennas command the established base. The steepest expansion runs through textile antennas.
End User:
Application context dictates electromagnetic exposure limits and interoperability requirements.
- Military Personnel:Dismounted soldiers require VHF through microwave operation with power handling below 50 watts and harsh environmental resilience. British Army service contracts and NATO procurement programs concentrate demand around sovereign manufacturing capabilities.
- Healthcare Professionals:Patient monitoring systems demand skin-contact biocompatibility and FCC Part 15 emissions compliance for continuous wear.
- Fitness Trackers:Consumer wearable manufacturers prioritize cost-optimized single-band solutions with simplified certification pathways.
- Smart Clothing Users:Industrial and commercial uniform applications integrate RF for workforce tracking and safety communications.
Military personnel anchor procurement volume. Healthcare professionals are gaining share fastest.
Installation:
Physical mounting location determines RF-human interaction modeling complexity and legacy system compatibility.
- On-Body Installation:Direct skin or equipment mounting requires specialized electromagnetic simulation for propagation analysis. Scarce design expertise constrains iteration speed for conformal antenna development.
- Clothing Integration:Textile-embedded architectures displace rigid configurations as conductive weaving matures for smart uniform applications.
- Wearable Devices:Accessory-mounted antennas in watches and badges serve first responder modernization programs in France and Germany.
- Implant Integration:Biocompatible encapsulation and extreme miniaturization support medical device applications with stringent FDA and EMA approval requirements.
On-body installation maintains the largest installed base. Clothing integration shows the strongest forward momentum.
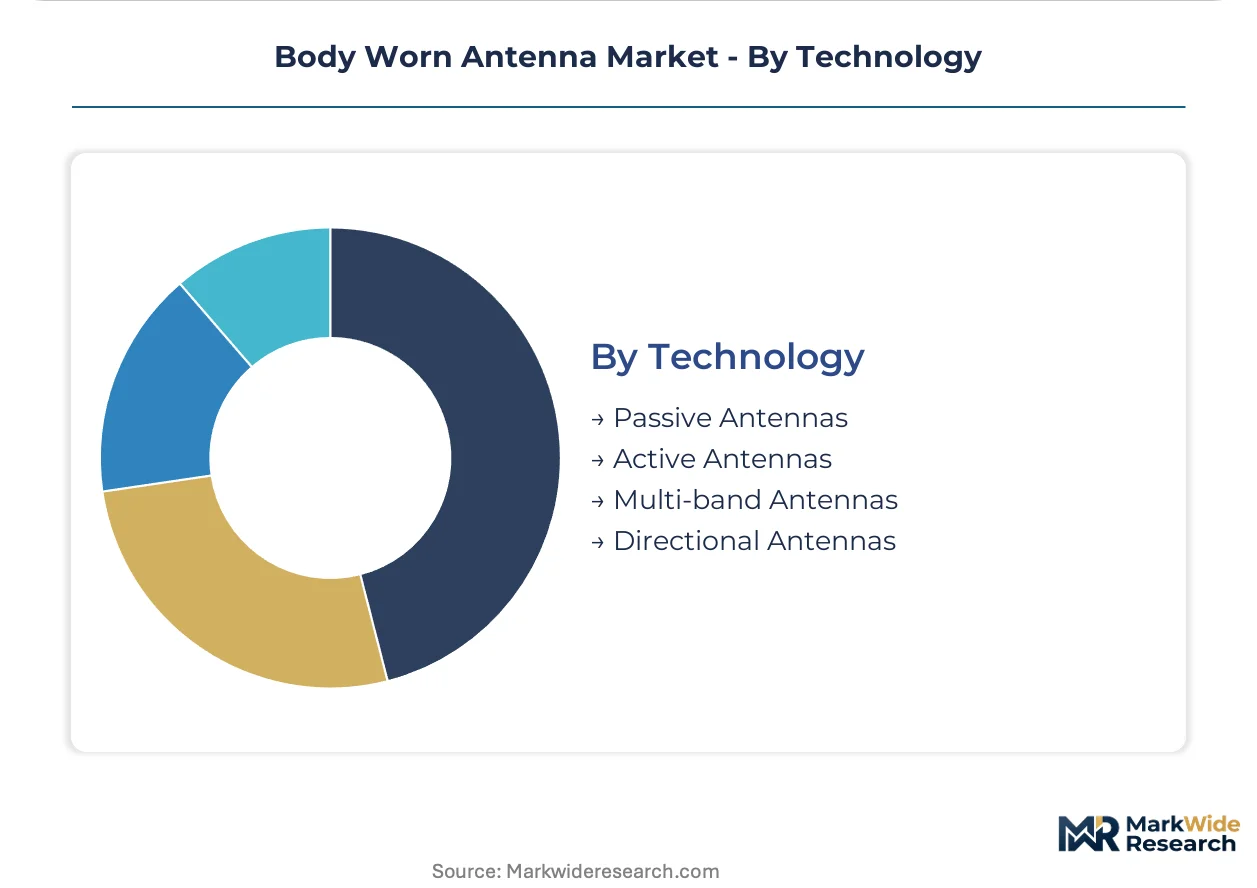
Technology:
Signal processing architecture separates passive reception from active amplification and beam control capabilities.
- Passive Antennas:Simple radiating elements without integrated electronics dominate current military procurement volumes due to reliability in harsh conditions and simplified maintenance protocols.
- Active Antennas:Integrated low-noise amplifiers and filtering improve sensitivity for weak signal environments. Special forces equipment refresh cycles favor rapid technology insertion over platform commonality.
- Multi-band Antennas:Single-element broadband operation reduces equipment count for dismounted soldiers managing multiple radio systems.
- Directional Antennas:Beam-steering capabilities enhance link budget for satellite communications and electronic warfare applications.
Passive antennas retain the dominant share. Active antennas demonstrate the steepest adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices and first responder agencies concentrate demand across five national markets where textile-integrated RF modernization programs are accelerating. Sovereign manufacturing requirements and electromagnetic compatibility certification timelines reshape supplier access in each geography.
United States
Special operations forces and dismounted soldier programs drive textile antenna adoption for signature reduction. FCC Part 15 emissions limits govern civilian wearable RF devices while ITAR regulations constrain cross-border technology transfer for military-grade specifications. Boston-area defense contractors and California RF specialists cluster around Pentagon procurement channels.
Germany
Bundeswehr equipment upgrades concentrate supplier activity in the Munich-Ulm industrial corridor for dismounted soldier modernization. The EU Radio Equipment Directive tightens electromagnetic compatibility certification requirements for wearable communication devices. Bavarian textile-integrated RF manufacturers leverage proximity to federal procurement offices.
United Kingdom
British Army service contracts sustain long-term relationships with sovereign manufacturing bases for tactical antenna procurement. Performance-based logistics contracts fragment traditional capital-sales models. Southwest England and Scottish defense corridors host specialized on-body RF integration facilities.
France
Public safety agencies adopt body-worn RF systems for interoperable emergency communications alongside military modernization. ANSM and CNIL oversight intersects with EU-wide CE marking requirements for wearable electronics. Paris-region defense contractors and Lyon-area textile specialists coordinate on smart uniform development.
Israel
Special forces equipment refresh cycles favor rapid technology insertion over platform commonality for garment-embedded VHF systems. The national defense establishment prioritizes sovereign RF-human interaction modeling capabilities. Tel Aviv and Haifa technology corridors concentrate electromagnetic simulation expertise for conformal antenna design.
Body Worn Antenna Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market consolidating around sovereign manufacturing capabilities and electromagnetic compatibility certification. Tier-one defense contractors anchor procurement relationships through performance-based logistics contracts while mid-scale RF specialists capture textile-integrated subsystems. Three archetypes dominate: vertically integrated prime contractors, specialized antenna fabricators, and smart uniform technology integrators. M&A activity concentrates on conductive fiber weaving capabilities and electromagnetic simulation software assets.
Within the prime contractor tier, BAE Systems exemplifies channel control through sovereign UK manufacturing relationships, while Thales Group occupies a position spanning European and Asia-Pacific defense customers. Cobham sits within the specialized RF integration segment, representing the archetype of on-body antenna expertise for special operations applications. These three anchors illustrate how competitive positioning stratifies across platform-level contracts, subsystem supply, and garment-embedded technology insertion.
| Leading Market Players |
|---|
| Alaris Antennas |
| Antenna Products |
| BAE Systems |
| Cobham |
| Thales Group |
| Northrop Grumman Corporation |
| Panorama Antennas Ltd |
| Rohde & Schwarz |
| Southwest Antennas |
| Others |
Value Chain & Pricing Dynamics
Conductive fiber weaving capacity clusters in Germany's Munich-Ulm corridor and Israel's Tel Aviv-Haifa technology belt, anchoring margin capture for textile-integrated RF subsystems downstream. Military procurement offices concentrate buying power through performance-based logistics contracts, compressing supplier pricing autonomy while elevating certification-grade premiums.
Pricing Analysis
Certification level creates the primary spread between military-grade ITAR-compliant systems and commercial FCC Part 15 devices. Three-tier pricing structure across ITAR-restricted, CE-marked, and unlicensed consumer grades reflects compliance investment amortization. Cost compression in commercial fitness tracker segments is intensifying because conductive polymer substrate suppliers face REACH substance restriction reformulation costs. Healthcare buyers exhibit the lowest price sensitivity due to FDA biocompatibility requirements, while consumer wearable manufacturers prioritize unit cost above electromagnetic performance.
Supply Chain Analysis
Silver-coated nylon yarn and copper conductive thread feed from textile mills in Germany, Israel, and the United Kingdom. Specialized electromagnetic simulation software and RF-human interaction modeling expertise rest on Israeli and US defense contractor ecosystems. Single-source vulnerability concentrates in conductive ink formulation, where European REACH compliance has eliminated multiple legacy suppliers. Distribution runs through prime contractor channel control for military end users, with direct OEM supply agreements serving healthcare and fitness tracker manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cycles are entering an upswing phase as NATO dismounted soldier modernization programs accelerate textile-integrated RF adoption. Equipment refresh timelines compress supplier qualification windows, favoring incumbent positioning.
For Market Incumbents: Harden sovereign manufacturing footprints against ITAR fragmentation by anchoring production in Munich-Ulm and Tel Aviv-Haifa corridors where electromagnetic simulation talent pools concentrate. Deepen backward integration into conductive fiber weaving to capture textile antenna margin expansion as NATO special operations forces displace rigid patch configurations.
For New Entrants and Emerging Players: First responder modernization programs in France and Germany represent the most penetrable entry point, with ANSM and CNIL regulatory pathways less congested than military ITAR channels. Healthcare flexible antenna segments for patient monitoring systems offer secondary white-space, where skin-contact biocompatibility requirements deter commodity competitors. A direct OEM supply partnership with Bavarian textile-integrated RF manufacturers accelerates EU Radio Equipment Directive certification.
For Investors and Strategic Acquirers: Capital is best deployed toward electromagnetic simulation software assets and conductive fiber weaving capabilities that underpin next-generation conformal antenna architectures. Long-term viability hinges on exposure to defense procurement cycles with healthcare diversification for cyclical smoothing. The signal to watch is Bundeswehr equipment upgrade contract awards, which cascade through supplier ecosystems with 12-18 month lag.
| Strategic Initiative | Industry Significance |
|---|---|
| Conductive Fiber Weaving Acquisition | Captures textile antenna margin expansion as NATO forces modernize dismounted soldier systems. |
| Electromagnetic Simulation Software Investment | Addresses scarce RF-human interaction modeling expertise constraining design iteration speed. |
| EU Radio Equipment Directive Certification | Unlocks Bundeswehr procurement channels in the Munich-Ulm defense industrial corridor. |
| Performance-Based Logistics Contracting | Transforms capital-sales relationships into recurring revenue streams with British Army service contracts. |
| Healthcare Biocompatibility Pathway | Opens FDA and EMA patient monitoring segments with premium material selection cost recovery. |
Study Parameters
Cross-validation between procurement officer interviews at NATO defense ministries and secondary regulatory filings anchors the qualitative findings. Primary fieldwork encompassed antenna subsystem program managers, textile-integrated RF manufacturing engineers, electromagnetic simulation specialists, and hospital biomedical equipment procurement leads. Secondary sources included ITAR-controlled technology transfer documentation, EU Radio Equipment Directive harmonized standards, FCC Part 15 emissions databases, and REACH substance restriction amendments. Bottom-up segmentation modeling triangulated against top-down defense budget allocation analysis.
Calibration against historical procurement cycle patterns and technology insertion timelines informed the projection framework across the analysis window. Segmentation dimensions spanned product type, end user archetype, installation method, and technology architecture, with additional modeling of certification pathway complexity. CAGRs derived from equipment refresh schedule acceleration and conductive weaving process maturation curves. Forecast inputs incorporated Bundeswehr modernization program announcements and special operations forces pilot program expansion signals.
Practitioners should monitor ITAR regulatory harmonization negotiations and REACH substance restriction amendments for early signals of supply chain disruption or certification timeline extension. Cross-checking against NATO defense expenditure commitments and national military procurement office budget disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Wireless Sensors Network Market
Sensors and Controls
Europe Vibration Sensors Market
Sensors and Controls
Wind Vane Sensor Market
Sensors and Controls
Asia-Pacific Sensors Market
Sensors and Controls
Biopotential Sensor Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Inline Viscosity Sensor Market
Sensors and Controls
Non-Contact Sensor Market
Sensors and Controls
Asia-Pacific Thermocouple Temperature Sensors Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
SQUID Sensor Market
Sensors and Controls
Microseismic Monitoring Technology Market
Sensors and Controls
Portable Air Purifier Market
Sensors and Controls
Distance Measurement Sensor Market
Sensors and Controls
North America MEMS and Sensors Market
Sensors and Controls
Global Optogenetics Actuators and Sensors Market