
 Monoclonal Antibody Therapy Market | 2026-2036
Monoclonal Antibody Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Monoclonal Antibody Therapy Market Intelligence
A long-standing reliance on large hospital systems for therapy administration is unwinding as specialty clinics capture a greater share of patient treatment. This shift favors companies with targeted commercial strategies for complex biologics. Roche leverages its extensive oncology portfolio and companion diagnostic expertise to support specialized care centers. AbbVie sustains its leadership in the autoimmune space through a focus on next-generation humanized antibody development.
Monoclonal antibody therapy utilizes laboratory-produced proteins that mimic the immune system's ability to fight pathogens and abnormal cells. These molecules are designed with high specificity, binding to a single epitope on a target antigen, such as a receptor on a cancer cell. Fully human antibodies, produced via transgenic mice or phage display, are gaining prominence over older chimeric versions due to improved safety profiles. While oncology constitutes the largest therapy area, applications in autoimmune disorders represent the fastest-growing segment.
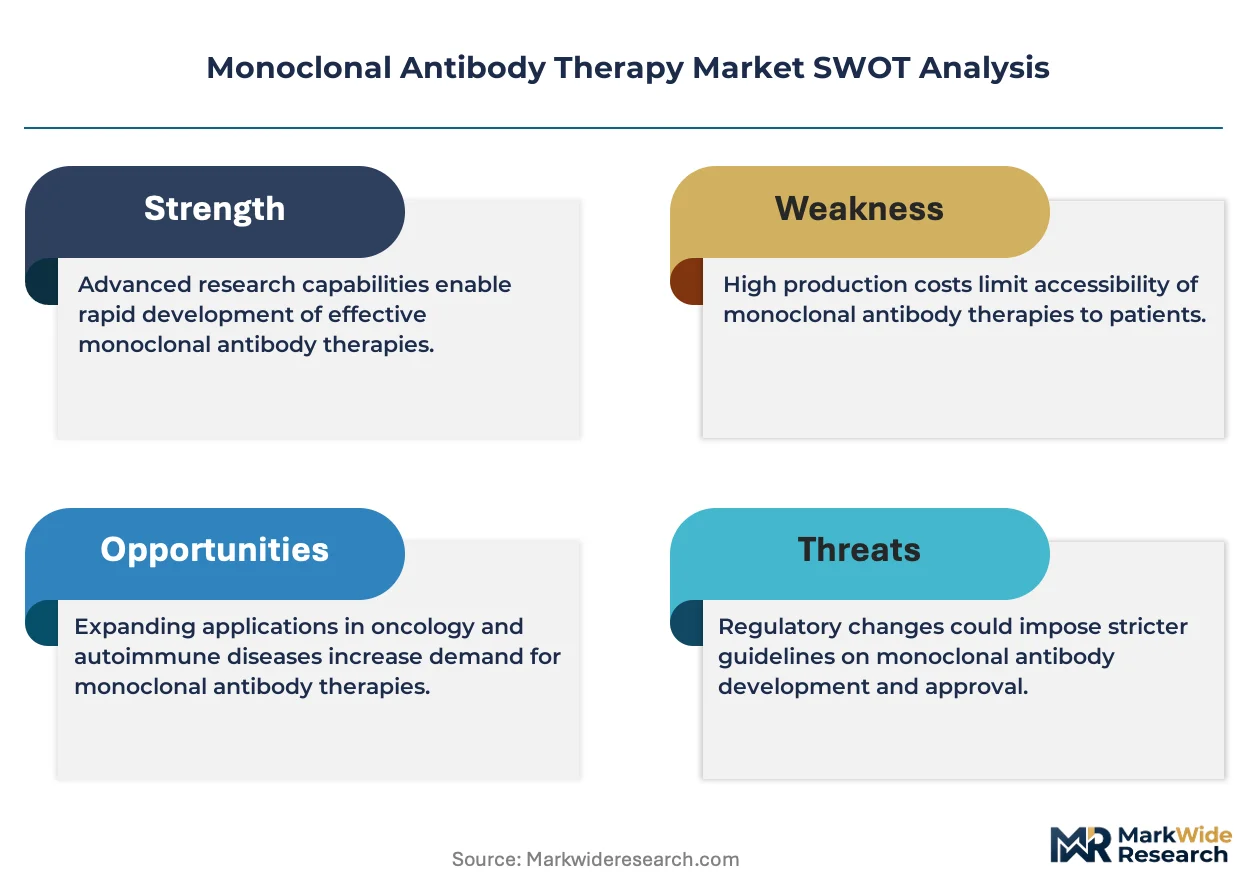
Regulatory frameworks from the United States FDA and the European Medicines Agency (EMA) set stringent standards for clinical trial efficacy and manufacturing quality. Guidelines from bodies like China's NMPA on biosimilar development and interchangeability directly impact market access and pricing strategies. Navigating the evolving intellectual property landscape while managing the high costs of biologics development will determine long-term profitability for therapy innovators.
Market Dynamics
The monoclonal antibody therapy market's evolution is defined by the tension between accelerated regulatory pathways and the immense capital investment required for biologic development. This dynamic forces innovators to balance rapid pipeline advancement with the long-term financial risks of clinical failure and manufacturing scale-up.
Growth Catalysts
- Next-Generation Antibody Formats:The transition from chimeric and humanized antibodies to fully human platforms, developed via phage display or transgenic mice, is enhancing therapeutic efficacy and reducing immunogenicity, which expands the addressable patient population.
- Regulatory Streamlining:The FDA's accelerated approval pathway and the EMA's PRIME scheme provide expedited routes for novel biologics targeting unmet medical needs, particularly in oncology, which shortens development timelines.
- Expanding Healthcare Access:Government initiatives in countries like China are expanding health insurance coverage and hospital infrastructure, creating significant new demand for advanced therapies, including monoclonal antibodies for cancer and autoimmune diseases.
Market Restraints
- High Development and Manufacturing Costs:The intrinsic complexity of biologic production, including cell line development and purification, results in extremely high costs that limit market entry and constrain pricing flexibility for innovators.
- Immunogenicity and Safety Concerns:Despite advances, the potential for patients to develop anti-drug antibodies remains a clinical restraint, which can compromise treatment efficacy and lead to adverse events, requiring careful patient monitoring.
- Biosimilar Interchangeability Hurdles:Divergent guidelines from the FDA and EMA on establishing biosimilar interchangeability create regulatory complexity and market access uncertainty, slowing the erosion of originator market share and delaying cost reductions.
Strategic Opportunities
- Therapeutic Area Expansion:While oncology is a mature segment, significant opportunity exists in applying monoclonal antibody technology to new indications in neurology, cardiovascular disease, and infectious diseases where treatment options are limited.
- AI in Drug Discovery:The convergence of artificial intelligence with genomic data presents an opportunity to accelerate the identification of novel drug targets and predict antibody binding affinity, potentially reducing discovery timelines and costs.
- Subcutaneous Formulation Development:Developing subcutaneous delivery options for existing intravenous therapies offers a path to move treatment from hospitals to clinics or homes, improving patient convenience and creating product differentiation.
Industry Challenges
- Intellectual Property Complexity:Navigating a dense landscape of patents covering antibody sequences, manufacturing processes, and formulation technologies creates a constant risk of litigation and requires sophisticated IP management strategies.
- Cold Chain Logistics:The requirement for stringent temperature control throughout the supply chain for most biologics presents a significant logistical and cost challenge, particularly when distributing to emerging markets with less developed infrastructure.
- Bioprocessing Talent Scarcity:A shortage of skilled personnel with expertise in large-scale mammalian cell culture, purification, and analytical characterization creates a bottleneck for manufacturing scale-up and process optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monoclonal Antibody Therapy Market |
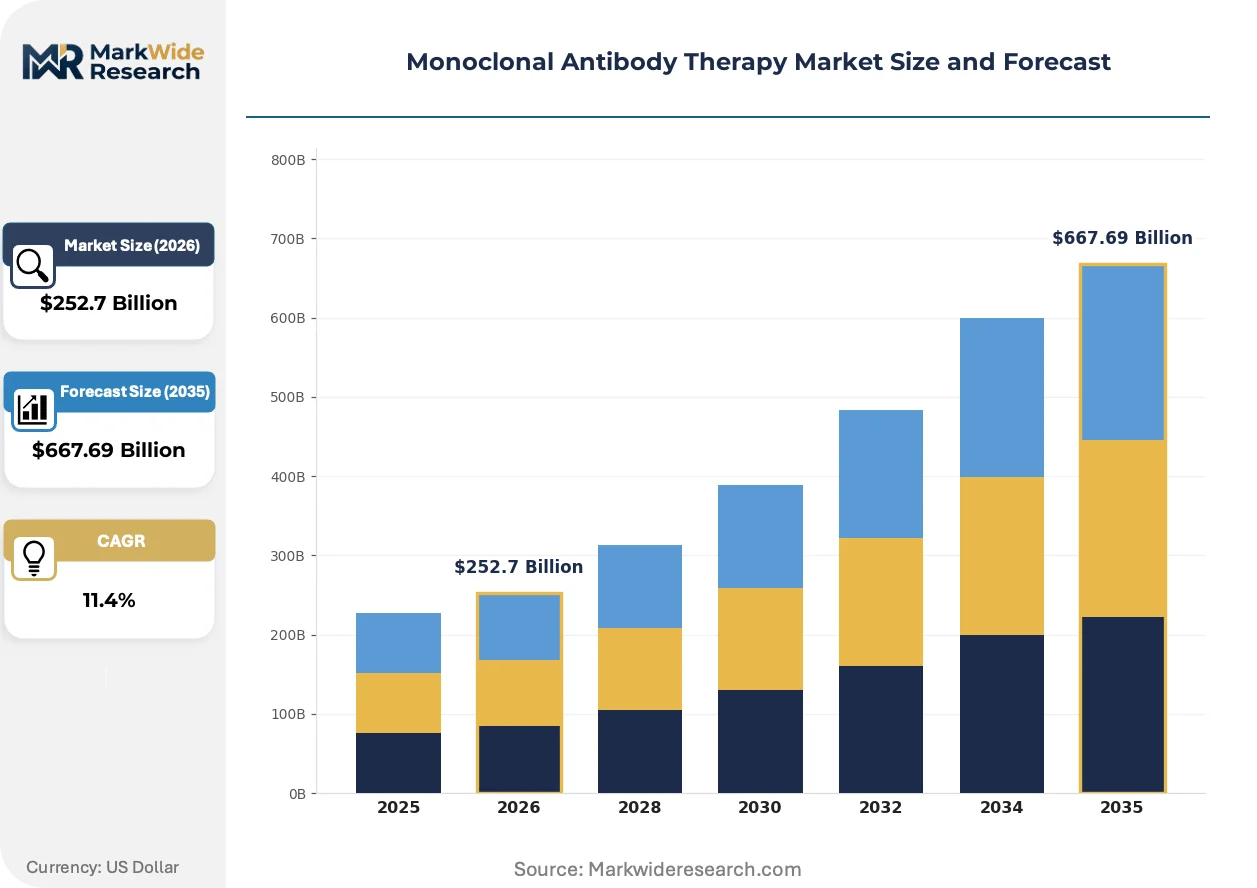
| Market Size in 2026 | $252.7 Billion |
| Market Size in 2035 | $667.69 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chimeric Antibodies, Humanized Antibodies, Fully Human Antibodies, Murine Antibodies, Bispecific Antibodies Therapy Area: Oncology, Autoimmune Disorders, Infectious Diseases, Neurological Disorders, Cardiovascular Conditions End User: Hospitals, Specialty Clinics, Research Laboratories, Diagnostic Centers, Blood Banks Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral, Topical |
| Companies Covered | AbbVie, AstraZeneca, Johnson & Johnson, Eli Lilly & Co., Novartis, Roche, Pfizer, Sanofi, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monoclonal Antibody Therapy Market Strategic Shifts & Innovations
Technological sophistication is advancing monoclonal antibody therapy beyond simple antagonists toward multi-functional platforms. This evolution, combined with new regulatory frameworks and patient-centric delivery models, is reshaping the therapeutic landscape for complex diseases.
Bispecific antibodies are engineered proteins designed to bind to two different epitopes, either on the same or different antigens. Oncology and immunology researchers are rapidly adopting these constructs for clinical studies due to their potential for enhanced tumor targeting or immune cell engagement. This targeted approach is fragmenting the traditional "one-target, one-drug" development paradigm by enabling more precise therapeutic intervention.
The European Medicines Agency's PRIME scheme offers early and enhanced scientific support to developers of promising medicines. This initiative accelerates the assessment of marketing authorization applications for therapies addressing significant unmet medical needs, including novel biologics. The oncology and rare disease segments are most affected, as companies adjust clinical trial designs to meet PRIME eligibility criteria and secure faster market access.
A patient-centric shift is moving therapy administration from centralized hospital infusion centers to specialty clinics and home-based care. This disrupts the established hospital-pharmacy distribution channel, favoring therapies with stable, subcutaneous formulations over those requiring intravenous infusion. This change in care delivery is most visible in the United States for the management of chronic autoimmune conditions like rheumatoid arthritis.
Monoclonal Antibody Therapy Market Segmentation
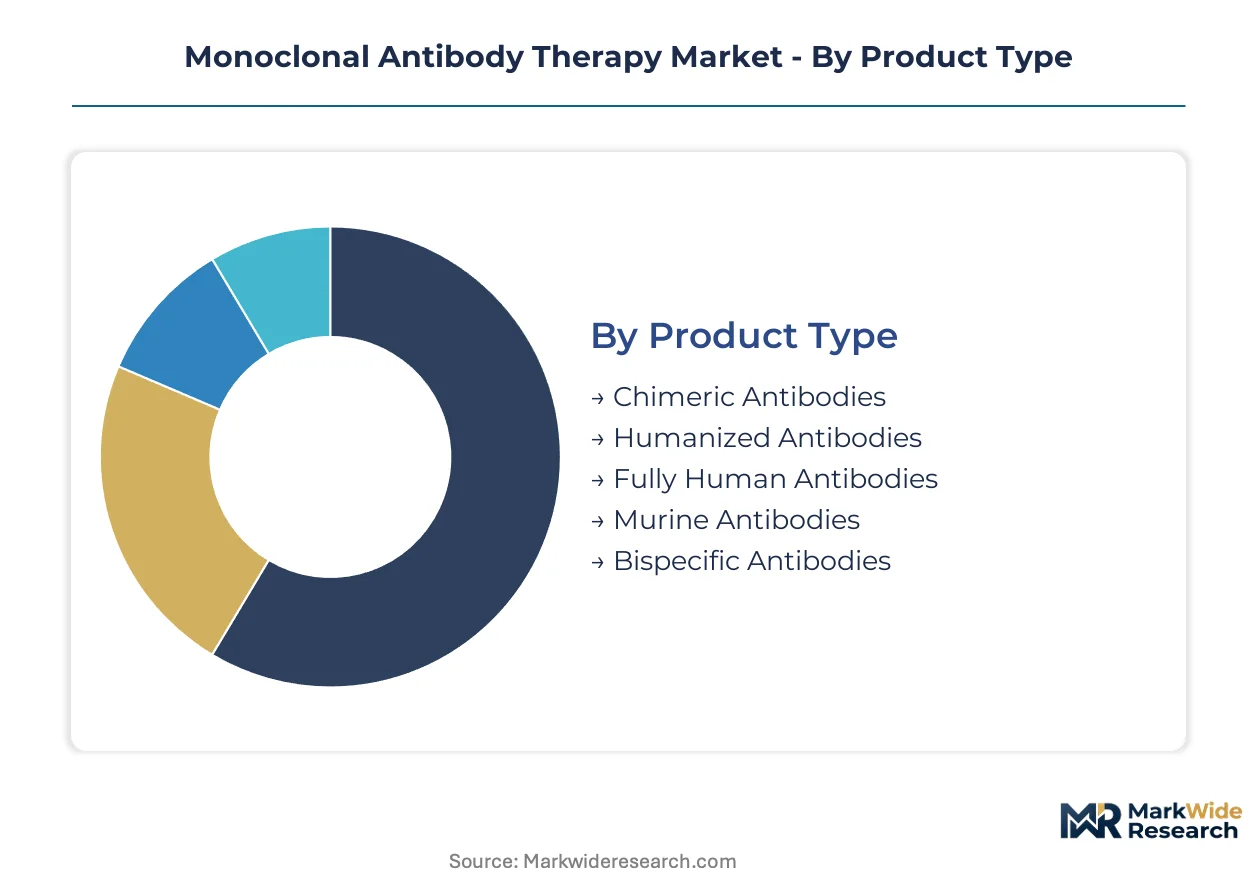
The Monoclonal Antibody Therapy Market exhibits distinct segmentation across various dimensions, reflecting the diverse scientific approaches, clinical applications, and delivery mechanisms shaping its evolution. Understanding these segments is crucial for identifying areas of innovation, market concentration, and strategic growth.
Product Type:
The market for monoclonal antibody product types exhibits varied adoption rates across different geographies, influenced by regulatory acceptance and local manufacturing capabilities.
- Fully Human Antibodies:These biologics are engineered to mimic human antibodies closely, minimizing immunogenicity and improving safety profiles for patients. Demand concentrates in advanced healthcare markets like the United States and European Union, where long-term treatment efficacy is prioritized.
- Bispecific Antibodies:Engineered to bind to two distinct epitopes, these advanced constructs offer enhanced therapeutic precision, particularly in oncology and immunology. Clinical adoption is accelerating globally, driven by their potential to overcome resistance mechanisms in cancer.
- Chimeric Antibodies:These antibodies combine murine variable regions with human constant regions, offering improved efficacy over purely murine versions but still carrying some risk of immunogenicity.
- Humanized Antibodies:Predominantly human in origin, these antibodies have only small portions derived from non-human species, significantly reducing immunogenic responses in patients.
- Murine Antibodies:Derived entirely from mouse cells, these were among the earliest forms of monoclonal antibodies but are largely superseded due to high immunogenicity in human patients.
Humanized Antibodies holds the largest share; momentum sits with Bispecific Antibodies.
Therapy Area:
Therapy area segmentation highlights the diverse clinical applications for monoclonal antibodies, reflecting varying patient populations and disease prevalence globally.
- Oncology:This segment encompasses a wide range of cancer treatments, targeting specific markers on tumor cells or engaging immune cells to fight malignancies. Demand is consistently high across all major economies, particularly in China due to expanding healthcare access and government initiatives.
- Autoimmune Disorders:Monoclonal antibodies in this area modulate the immune system to treat conditions like rheumatoid arthritis, psoriasis, and Crohn's disease. This segment is experiencing rapid expansion, driven by the development of next-generation humanized antibodies and patient-centric delivery options.
- Infectious Diseases:Antibodies are developed to neutralize pathogens or block their entry into host cells, offering passive immunity against viral and bacterial infections.
- Neurological Disorders:This emerging application area focuses on targeting specific proteins or pathways implicated in neurodegenerative diseases such as Alzheimer's and multiple sclerosis.
- Cardiovascular Conditions:Monoclonal antibodies are being investigated for their potential to lower cholesterol, prevent blood clots, and treat inflammatory heart conditions.
Oncology treatments represent the largest application area, while autoimmune disorders are expanding most quickly.
End User:
End-user segments illustrate the evolving landscape of therapy administration, driven by shifts in healthcare delivery models and patient convenience preferences.
- Hospitals:Large hospital systems have historically been the primary sites for monoclonal antibody administration, particularly for complex intravenous infusions and initial patient monitoring. This segment continues to manage a significant volume of advanced therapies.
- Specialty Clinics:These outpatient facilities are capturing an increasing share of therapy administration, offering specialized care and often more convenient access for patients. This shift is particularly evident for chronic autoimmune conditions in the United States.
- Research Laboratories:These facilities utilize monoclonal antibodies extensively for basic scientific research, drug discovery, and preclinical development across various disease areas.
- Diagnostic Centers:Monoclonal antibodies serve as key reagents in various diagnostic tests, enabling precise identification of biomarkers and disease states.
- Blood Banks:Antibodies are employed in blood typing, cross-matching, and screening for infectious agents to ensure the safety of blood transfusions.
Hospitals constitute the primary end-user segment, with specialty clinics gaining significant traction.
Delivery Mode:
Delivery mode segmentation reflects the ongoing innovation in patient administration, aiming to enhance convenience and reduce healthcare infrastructure reliance.
- Intravenous:This traditional delivery method involves administering antibodies directly into a patient's vein, often requiring hospital or clinic visits and trained medical personnel. Intravenous delivery remains common for initial doses and complex biologics.
- Subcutaneous:This method involves injecting the antibody under the skin, allowing for self-administration or administration in specialty clinics, improving patient convenience. Development of stable subcutaneous formulations is a strategic opportunity for therapy innovators.
- Intramuscular:Antibodies are injected directly into a muscle, providing an alternative to intravenous delivery for certain indications.
- Oral:Oral delivery of antibodies is a highly challenging but actively researched area, aiming to overcome degradation in the digestive system.
- Topical:Topical application of antibodies is limited to specific conditions affecting the skin or mucous membranes, offering localized treatment.
Intravenous administration remains the most established method, though subcutaneous options are seeing accelerated development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The development and manufacturing of monoclonal antibodies are concentrating in regions with robust biopharmaceutical infrastructure and advanced regulatory frameworks. This supply-side concentration drives innovation and market penetration in key global economies. These areas benefit from significant R&D investment and a skilled workforce, supporting the complex production processes required for biologics.
United States
Demand for monoclonal antibody therapies in the United States is driven by high prevalence of chronic diseases and significant investment in oncology treatments. The FDA's accelerated approval pathway provides expedited routes for novel biologics, shortening time to market. The Boston-Cambridge biotech hub remains a critical center for advanced antibody research and development.
Germany
Germany's market for monoclonal antibodies benefits from a strong healthcare system and a focus on high-value biologics for chronic conditions. The European Medicines Agency's PRIME scheme offers early scientific support for promising medicines. The Munich and Heidelberg regions are key areas for biopharmaceutical R&D and manufacturing.
China
Expanding healthcare access and government initiatives to combat cancer are significant demand drivers for monoclonal antibodies in China. The NMPA's evolving guidelines on biosimilar development directly impact market access and pricing strategies. Major biotech parks in Shanghai and Beijing are rapidly expanding their capabilities in biologics production.
Japan
An aging population and a strong emphasis on novel therapies for oncology and rare diseases fuel demand for monoclonal antibodies in Japan. The PMDA's fast-track review process supports the introduction of innovative treatments. Pharmaceutical innovation clusters in Tokyo and Osaka drive significant research and development efforts.
Switzerland
Switzerland maintains a strong position in high-value biologics and precision medicine due to its advanced pharmaceutical industry. Swissmedic enforces stringent quality standards for clinical trials and manufacturing processes. Basel's pharmaceutical cluster is a global hub for biologics research, development, and production.
Monoclonal Antibody Therapy Market Key Industry Players
Concentration sits with established pharmaceutical companies and specialized biotechnology firms possessing extensive R&D capabilities. The market structure involves a tiered landscape, with large, diversified pharmaceutical giants competing alongside innovative, often smaller, biotech companies. Strategic archetypes include integrated biologics developers and focused therapeutic area specialists. Dominant competitive moves include strategic partnerships for pipeline advancement and portfolio diversification into new disease indications.
Within the integrated biologics developer archetype, Roche and Johnson & Johnson exemplify companies with broad therapeutic portfolios and significant global reach. These entities anchor substantial R&D investments in novel antibody formats and manufacturing scale-up. AbbVie, a prominent player, occupies a strong position in the autoimmune space, representing a focus on next-generation humanized antibody development.
| Leading Market Players |
|---|
| AbbVie |
| AstraZeneca |
| Johnson & Johnson |
| Eli Lilly & Co. |
| Novartis |
| Roche |
| Pfizer |
| Sanofi |
| Merck & Co. |
| Others |
Cost & Logistics Intelligence
The European Medicines Agency's PRIME scheme, alongside other regulatory frameworks, gates both supply qualification and price differentiation for novel monoclonal antibodies. This regulatory oversight ensures product quality while influencing market access and pricing power for innovators.
Pricing Analysis
The United States FDA's accelerated approval pathway dictates the pricing tier structure for novel biologics. Value-based pricing models dominate, reflecting the significant clinical efficacy and R&D investment in these therapies. Clinical efficacy and patient convenience, particularly with subcutaneous formulations, are primary differentiation drivers. Pricing pressure stems from the increasing availability of biosimilars, especially in established therapy areas. Government payers and large health systems exhibit the most price sensitivity, balancing budget constraints against patient outcomes.
Supply Chain Analysis
Stringent cold chain logistics costs significantly impact the monoclonal antibody supply chain, particularly for global distribution. Geographic supply concentration for advanced manufacturing capabilities resides primarily in the United States, Germany, and Switzerland. The production process draws from specialized inputs like cell culture media, purification resins, and single-use bioreactors. Single-source vulnerability for these critical components presents a structural supply chain risk. Distribution runs primarily through hospital pharmacies and specialty clinics, with a growing shift towards home-based care for certain indications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The monoclonal antibody market exhibits signs of cyclical recovery, driven by renewed investment in novel biologic platforms and expanding healthcare access.
For Market Incumbents: Fortify core therapeutic areas through continuous pipeline diversification and enhanced companion diagnostic integration. This strategy helps counter biosimilar erosion and maintain market leadership. Investment in next-generation antibody formats, such as bispecifics, serves as a key lever for sustained innovation and competitive advantage.
For New Entrants and Emerging Players: Lead with innovation in underexplored therapeutic areas like neurology or infectious diseases to establish market niches. The rare disease segment offers a penetrable entry point due to significant unmet medical needs and regulatory incentives. An effective go-to-market angle involves leveraging artificial intelligence for accelerated drug target identification and optimized clinical trial design.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across complex biologics manufacturing, indicating sustained growth potential over the next decade. Acquisition targets should focus on specialized biotechnology firms with advanced platform technologies or promising clinical-stage assets. Clinical trial success rates for novel antibody formats in challenging indications serve as a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market access for novel bispecific antibodies in oncology. |
| Manufacturing Scale-Up | Secures supply for high-demand fully human antibodies in autoimmune disorders. |
| Licensing Agreement | Expands geographic reach for established monoclonal antibodies in China. |
| Pipeline Diversification | Reduces reliance on oncology by exploring neurological indications. |
| Subcutaneous Formulation Development | Improves patient convenience for chronic autoimmune therapy administration. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during the data collection phase, combining primary interviews with robust secondary validation. Primary insights were gathered from drug development executives, regulatory affairs leads, hospital procurement managers, and specialty clinic directors. Secondary data sources included United States FDA filings, European Medicines Agency submissions, ClinicalTrials.gov, and China's NMPA guidelines, ensuring comprehensive market understanding through bottom-up and top-down triangulation.
The analytical framework projects market trajectories across the analysis window, integrating volume and value outputs. Segmentation dimensions modeled include product type, therapy area, end-user, delivery mode, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical data trends and projected market dynamics. Industry-specific forecast inputs included clinical trial success rates for novel biologics and anticipated biosimilar market entry timelines.
Forecasts assume regulatory continuity in the United States FDA, European Medicines Agency, and China's NMPA; material policy shifts would require re-modeling. These projections reflect assumptions regarding technological advancements and market adoption rates. Unexpected clinical trial failures or new intellectual property challenges represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Neurodegenerative Disease Market
Specialty Medicine
Fascioliasis Treatment Market
Specialty Medicine
Kaposi Sarcoma Market
Specialty Medicine
US Mobile Physician Practice Market
Specialty Medicine
Cerebral Vein Thrombosis Treatment Market
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Geographic Atrophy Market
Specialty Medicine
Global Sarcopenia Treatment Market
Specialty Medicine
Dementia Management Market
Specialty Medicine
Relapsing-Remitting Multiple Sclerosis (MS) Market
Specialty Medicine
Disruptive Behavior Disorder (DBD) Treatment Market
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Global Spinal Muscular Atrophy Treatment Market
Specialty Medicine
Strep Throat Treatment Market
Specialty Medicine
Klinefelter Syndrome Treatment Market