
 Kaposi Sarcoma Market | 2026-2036
Kaposi Sarcoma Market Size, Share, and Industry Trends Forecast 2026-2036
Kaposi Sarcoma Market Outlook
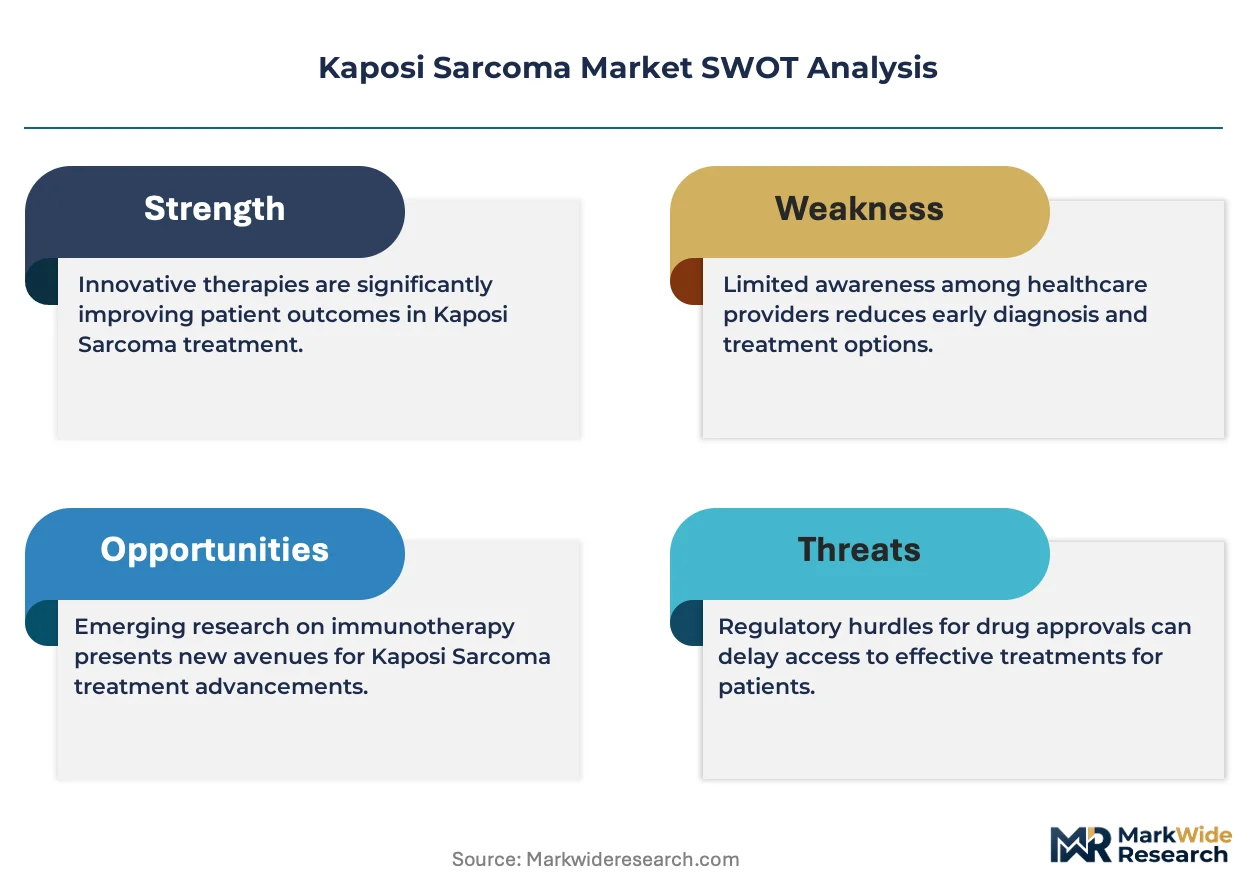
Oncology centers are gaining share as the primary buyer archetype for Kaposi sarcoma therapeutics, while general hospital procurement is bifurcating toward specialized care networks. Bristol-Myers Squibb leverages its immuno-oncology portfolio to anchor positioning in combination therapy protocols. Merck & Co. sustains competitive presence through PD-1 inhibitor applications in virally driven malignancies. Pfizer Inc. differentiates via targeted kinase inhibitor development for advanced-stage patients.
Kaposi sarcoma is a multicentric vascular tumor arising from human herpesvirus-8 infection, characterized by spindle cell proliferation and vascular channel formation with variable clinical presentation across cutaneous, mucosal, and visceral sites. The condition serves as an AIDS-defining illness and requires antiretroviral backbone therapy alongside cytotoxic or biologic agents. Immunotherapy represents the fastest-expanding product type segment, driven by checkpoint inhibitor approvals and durable response data in relapsed settings. Combination therapy protocols capture the deepest margin pools by requiring multi-agent regimens with complex administration schedules. Outpatient care applications are maturing as oral formulations and subcutaneous delivery reduce hospital dependency.
The FDA's orphan drug designation and breakthrough therapy pathways compress development timelines for Kaposi sarcoma indications, while EMA's PRIME eligibility criteria create parallel access momentum in European markets. WHO inclusion of Kaposi sarcoma in essential medicines frameworks shapes procurement standards across low-resource settings where HIV burden remains concentrated. Stakeholders must monitor evolving biosimilar entry timelines for paclitaxel and liposomal doxorubicin, as these events will reshape pricing architecture and portfolio prioritization decisions.
Market Dynamics
Checkpoint inhibitor approvals are fragmenting treatment hierarchies in Kaposi sarcoma care, displacing cytotoxic backbones with durable response data in relapsed HIV-associated cases. Oncology centers now prioritize immunotherapy protocols that reduce hospital dependency.
Growth Catalysts
- FDA Breakthrough Therapy Pathway:Accelerated approval timelines compress development cycles for rare cancer indications, enabling faster patient access to novel agents.
- Antiretroviral backbone integration:HIV treatment centers embed Kaposi sarcoma protocols into existing care infrastructure, expanding addressable patient pools through co-managed disease models.
- Liposomal formulation advances:Improved drug delivery technologies reduce systemic toxicity profiles, enabling outpatient administration and protocol expansion.
Market Restraints
- Paclitaxel supply concentration:Active pharmaceutical ingredient production clusters in Asian manufacturing hubs, exposing procurement to geopolitical and logistics disruptions.
- Specialized pathology requirements:Human herpesvirus-8 diagnostic confirmation demands immunohistochemistry expertise unavailable in resource-limited settings.
- Orphan drug pricing frameworks:Reimbursement mechanisms for ultra-rare indications create access barriers in public health systems with fixed pharmaceutical budgets.
Strategic Opportunities
- Sub-Saharan Africa penetration:WHO essential medicines inclusion creates procurement standardization opportunities where HIV-associated disease burden concentrates.
- Subcutaneous delivery convergence:Combination of biologic stabilization technologies with injection devices enables home-based administration, reducing oncology center capacity constraints.
- Biosimilar entry timelines:Liposomal doxorubicin patent expirations open margin capture opportunities for manufacturers with complex generic capabilities.
Industry Challenges
- Immuno-oncology talent scarcity:Clinical trial design for virally driven malignancies requires specialized expertise in HIV oncology, limiting site activation speed.
- Multi-agent protocol complexity:Combination therapy regimens demand coordination across antiretroviral, cytotoxic, and biologic scheduling, complicating pharmacy operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kaposi Sarcoma Market |
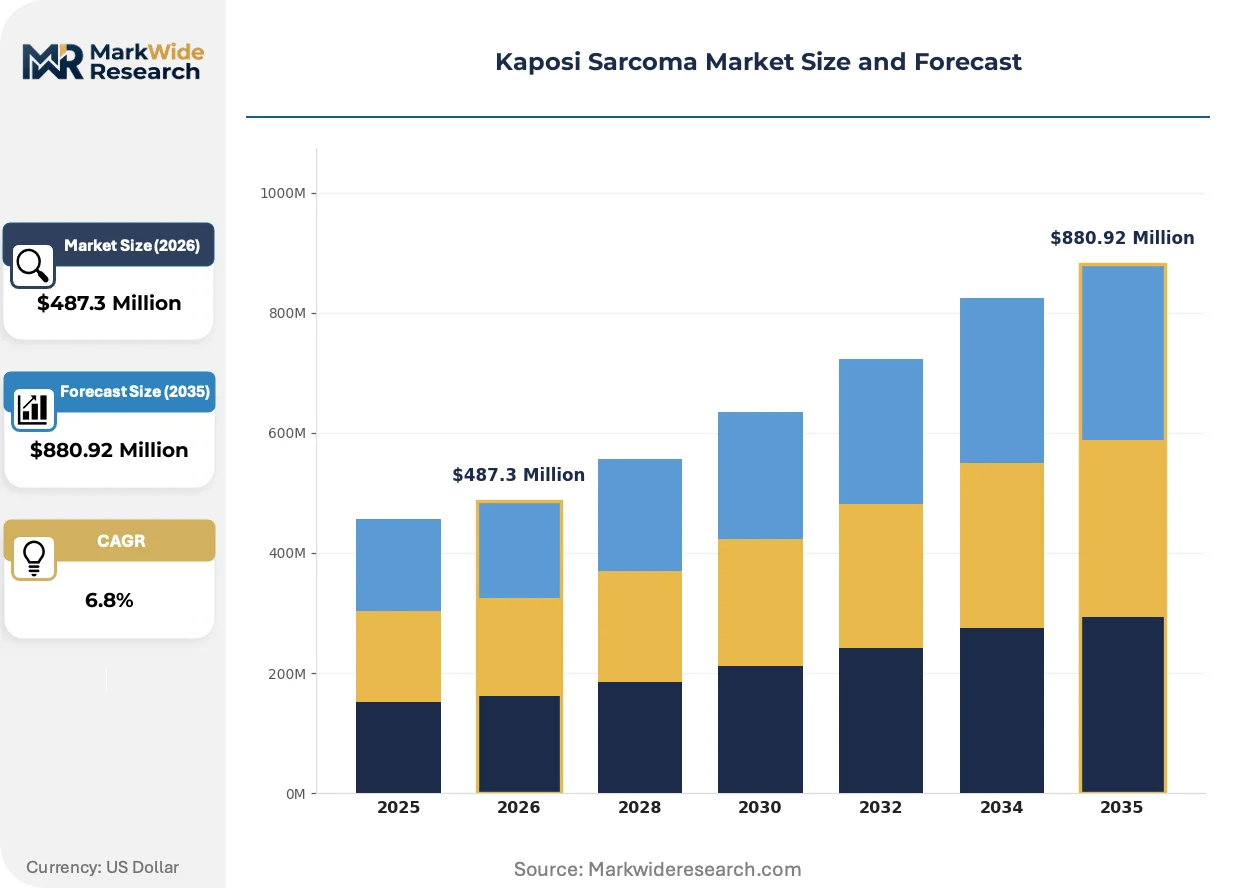
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiretroviral Therapy, Chemotherapy, Immunotherapy, Radiation Therapy Application: Hospital Treatment, Outpatient Care, Home Care, Clinical Trials End User: Oncology Centers, Research Institutions, Physicians, Patients Treatment Protocol: Combination Therapy, Monotherapy, Palliative Care, Surgical Intervention |
| Companies Covered | Bristol-Myers Squibb, Merck & Co., Pfizer Inc., AstraZeneca Plc, Baxter International, Navidea Biopharmaceuticals, Regeneron Pharmaceuticals, Eisai Inc., Gilead Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kaposi Sarcoma Market Strategic Shifts
Immunotherapy protocols are displacing established cytotoxic standards through durable response data, while regulatory pathways compress development timelines. Distribution models adapt to outpatient administration requirements.
Checkpoint inhibitor development is fragmenting first-line treatment hierarchies in HIV-associated Kaposi sarcoma. Oncology centers adopt PD-1 blockade protocols for relapsed cases, compressing cytotoxic agent utilization. This shift enables margin capture through complex biologic administration while reducing hospital bed dependency.
EMA PRIME eligibility criteria are accelerating parallel access momentum for breakthrough therapies in European markets. Manufacturers leverage centralized assessment procedures to synchronize launch timelines across member states. HIV treatment networks in Germany, France, and Italy now demand early access programs for novel immunotherapies.
Specialized care networks are consolidating Kaposi sarcoma treatment away from general hospital procurement. Oncology centers capture patient flows through dedicated sarcoma units with embedded HIV expertise. This concentration is most visible in United States metropolitan markets where reimbursement frameworks reward protocol complexity.
Kaposi Sarcoma Market Segmentation
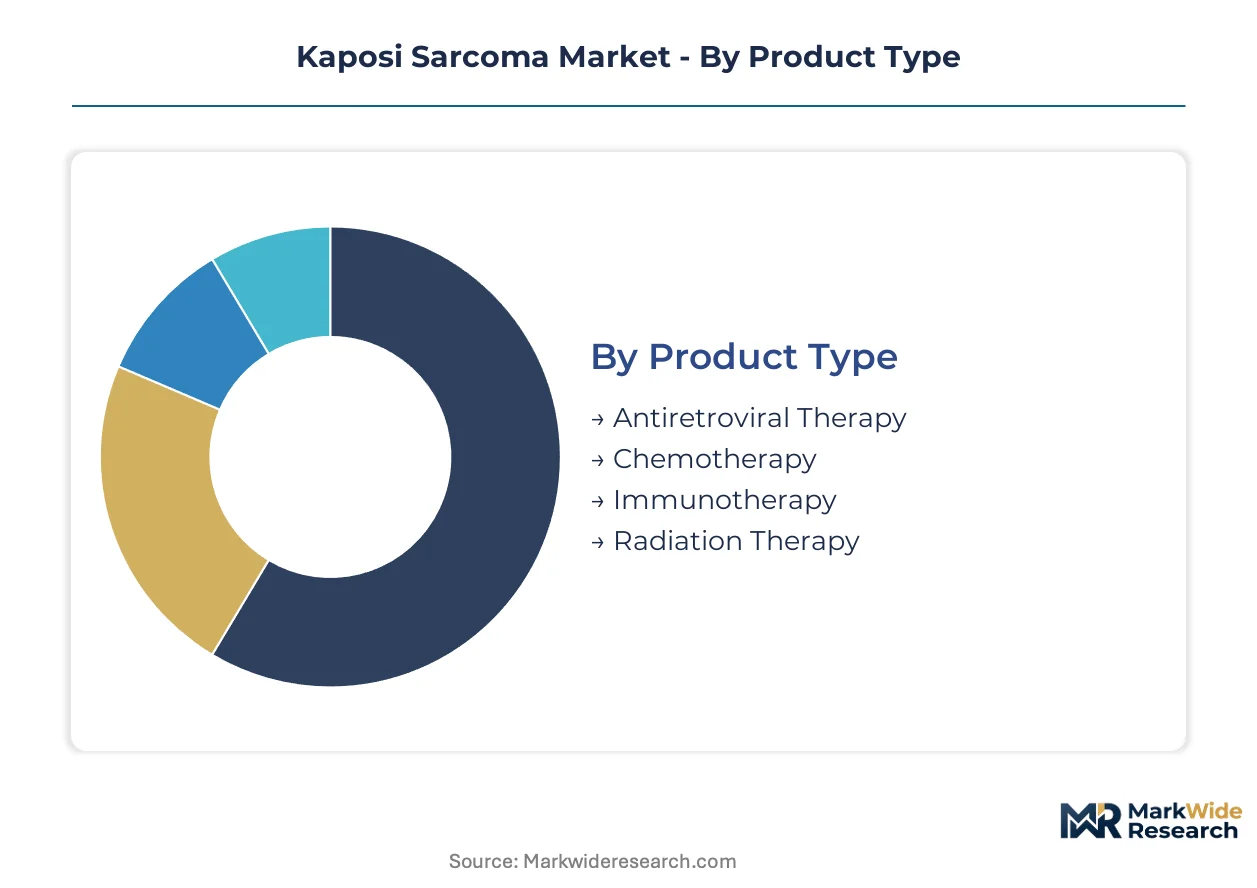
Treatment modality selection in Kaposi sarcoma hinges on HIV status, disease staging, and care setting infrastructure. Segmentation reveals how channel economics and patient flow patterns reshape competitive priorities across therapeutic categories.
Product Type:
Channel distribution varies sharply across product categories, with hospital-administered agents flowing through oncology center pharmacy networks while oral therapies reach patients via specialty retail and mail-order channels.
- Antiretroviral Therapy:Foundation of HIV-associated Kaposi sarcoma management, combining nucleoside reverse transcriptase inhibitors with protease or integrase inhibitors to restore immune function. Demand concentrates in infectious disease clinics within major metropolitan treatment centers, driven by WHO essential medicines procurement standards in high-burden regions. By volume, Antiretroviral Therapy leads. By growth pace, Immunotherapy is ahead.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 pathways deliver durable responses in relapsed disease with reduced systemic toxicity versus cytotoxic alternatives. Oncology centers in the United States and Western Europe prioritize these protocols for advanced-stage patients, propelled by FDA breakthrough therapy designations compressing access timelines.
- Chemotherapy:Liposomal doxorubicin and paclitaxel remain standard first-line options for symptomatic visceral or extensive cutaneous disease, administered through infusion centers with cardiac monitoring capabilities.
- Radiation Therapy:Localized treatment for symptomatic lesions or cosmetically significant involvement, delivered through linear accelerator networks with electron beam capacity.
Margin structures favor biologics and targeted agents over commoditized cytotoxics, though biosimilar entry timelines will reshape pricing architecture for established chemotherapy backbones.
Application:
Care setting selection reflects disease severity, treatment toxicity profiles, and reimbursement incentives that reward outpatient migration where clinical protocols permit.
- Hospital Treatment:Required for intensive combination regimens, visceral crisis management, and complicated HIV co-morbidities demanding multidisciplinary oversight. Concentrates in academic medical centers with embedded infectious disease and oncology expertise, constrained by bed capacity limitations and inpatient reimbursement compression.
- Outpatient Care:Infusion centers and oncology clinics administer liposomal formulations and immunotherapy with same-day discharge protocols. United States metropolitan markets show fastest expansion here, fueled by site-of-service differentials favoring ambulatory settings.
- Home Care:Oral antiretroviral maintenance and emerging subcutaneous biologic delivery reduce facility dependency for stable patients.
- Clinical Trials:Access to novel agents prior to regulatory approval, concentrated in NIH-designated cancer centers and HIV oncology research networks.
Hospital treatment retains the highest acuity patient share. Outpatient care is expanding most quickly as formulation innovations enable community-based administration.
End User:
Procurement authority and clinical decision-making diverge across stakeholder types, with specialized oncology centers capturing complex case referrals while community physicians manage stable disease.
- Oncology Centers:Dedicated sarcoma units with HIV oncology expertise handle advanced disease, combination protocols, and clinical trial enrollment. Demand clusters in United States urban corridors with specialized reimbursement frameworks supporting protocol complexity.
- Physicians:Infectious disease specialists and dermatologists manage early-stage cutaneous disease and antiretroviral coordination in community settings.
- Research Institutions:Academic medical centers with NCI designation drive investigator-initiated studies and pharmaceutical-sponsored trials for novel mechanisms.
- Patients:Direct access channels expand through patient assistance programs and specialty pharmacy services for oral therapy fulfillment.
Oncology centers command the premium case volume. Research institutions are gaining influence fastest as immunotherapy development accelerates.
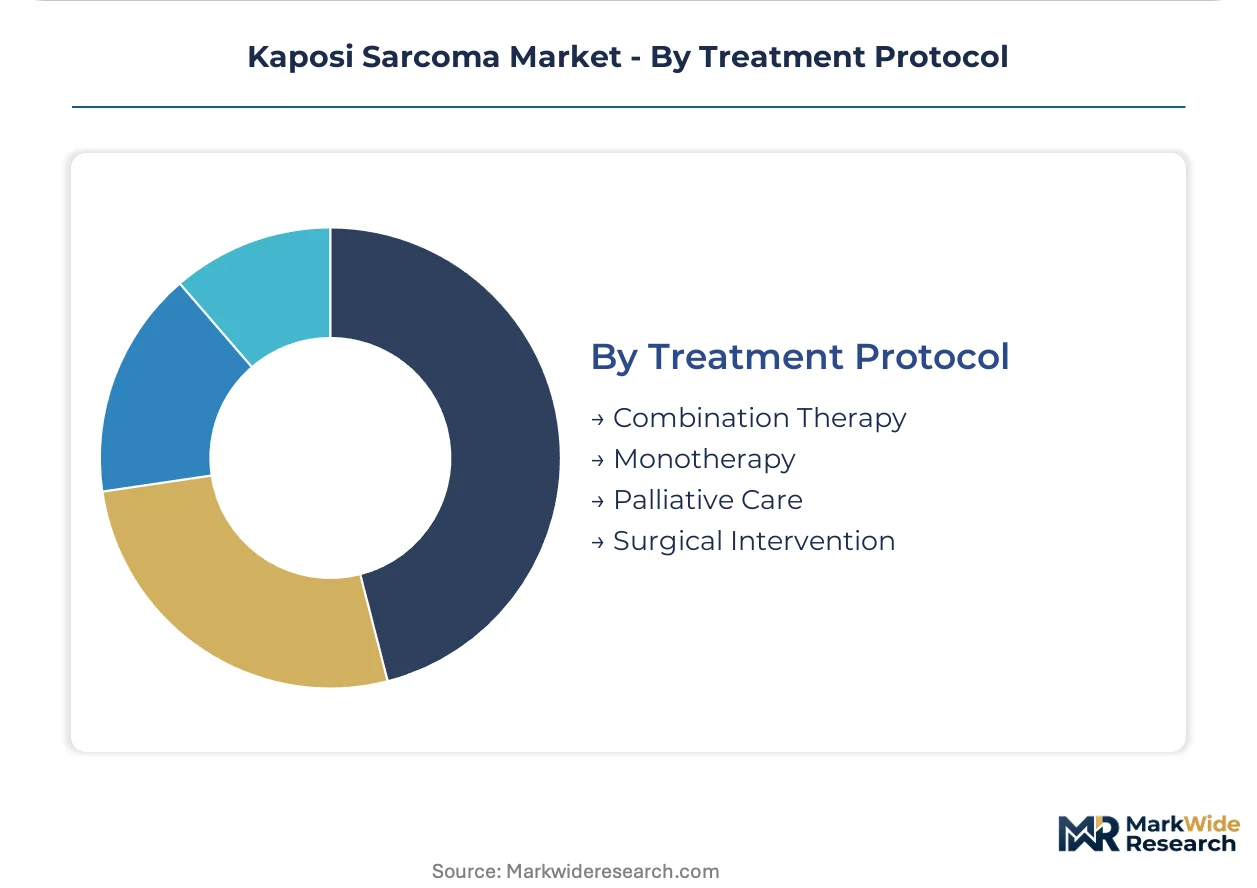
Treatment Protocol:
Protocol complexity determines supply chain requirements, with multi-agent regimens demanding sophisticated pharmacy compounding and scheduling coordination.
- Combination Therapy:Integration of antiretroviral, cytotoxic, and biologic agents requires cross-specialty coordination and represents the deepest margin opportunity. Oncology centers with embedded HIV expertise dominate this segment, supported by reimbursement mechanisms rewarding multi-agent administration.
- Monotherapy:Single-agent immunotherapy or chemotherapy for patients with contraindications to intensive regimens or limited performance status.
- Palliative Care:Symptom-focused radiation and low-dose chemotherapy for end-stage disease, delivered through hospice-affiliated networks.
- Surgical Intervention:Local excision or laser therapy for isolated cosmetically significant lesions, performed in dermatology and surgical oncology clinics.
Combination therapy generates the highest revenue per patient. Monotherapy protocols are expanding most quickly as checkpoint inhibitors displace cytotoxic backbones in relapsed settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based oncology centers export treatment protocols and clinical expertise to European and Latin American markets through telemedicine partnerships and training programs. Germany and France import these frameworks while adapting them to EMA regulatory requirements. Sub-Saharan African nations receive essential medicines through WHO-coordinated procurement channels.
United States
FDA breakthrough therapy designations compress immunotherapy access timelines for HIV-associated cases. The Orphan Drug Act provides tax incentives and market exclusivity for rare cancer indications. New York and San Francisco metropolitan clusters concentrate specialized sarcoma units with embedded infectious disease expertise.
Germany
EMA PRIME eligibility criteria accelerate parallel market access for checkpoint inhibitors. The country's national pharmaceutical regulator enforces stringent pharmacovigilance for biologic combination protocols. Berlin and Munich academic medical centers drive investigator-initiated trials for novel mechanisms.
France
ANSM early access programs enable compassionate use of immunotherapies prior to formal reimbursement. Temporary authorization for use pathways bridge regulatory gaps for ultra-rare oncology indications. Paris and Lyon treatment networks integrate HIV oncology into existing infectious disease infrastructure.
Italy
AIFA managed entry agreements negotiate outcome-based pricing for high-cost biologics. Regional health authorities in Lombardy and Emilia-Romagna concentrate procurement authority for specialized cancer therapies. Milan and Bologna oncology centers pioneer ambulatory administration models.
South Africa
WHO essential medicines inclusion shapes public sector procurement standards for paclitaxel and liposomal doxorubicin. The national health department coordinates antiretroviral and oncology supply chains through centralized tender processes. Gauteng and Western Cape provinces host the continent's highest concentration of HIV-associated Kaposi sarcoma treatment capacity.
Kaposi Sarcoma Market Competitive Environment
Player mix skews toward integrated pharmaceutical conglomerates with immuno-oncology portfolios. The structure concentrates around three strategic archetypes: checkpoint inhibitor specialists, antiretroviral backbone providers, and complex generic manufacturers. Consolidation pressure intensifies as biosimilar entry timelines reshape pricing architecture for established cytotoxics. Dominant competitive moves include portfolio diversification into combination therapy protocols and geographic expansion through WHO essential medicines procurement channels.
Within the immuno-oncology tier, Bristol-Myers Squibb, Merck & Co., and Pfizer Inc. exemplify divergent strategic positioning. Bristol-Myers Squibb occupies a position anchored in combination therapy development. Merck & Co. represents the PD-1 inhibitor application model for virally driven malignancies. Pfizer Inc. sits within the targeted kinase inhibitor specialization for advanced-stage patients. These three entities collectively illustrate how therapeutic modality focus shapes competitive differentiation in orphan oncology indications.
| Leading Market Players |
|---|
| Bristol-Myers Squibb |
| Merck & Co. |
| Pfizer Inc. |
| AstraZeneca Plc |
| Baxter International |
| Navidea Biopharmaceuticals |
| Regeneron Pharmaceuticals |
| Eisai Inc. |
| Gilead Sciences |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety day API inventory cycles at oncology center pharmacies concentrate procurement leverage among buyers with cold-chain infrastructure, amplifying price negotiation power for liposomal formulations while squeezing margin capture for manufacturers without backward integration into active pharmaceutical ingredient production.
Pricing Analysis
Checkpoint inhibitor premium pricing versus cytotoxic chemotherapy standard pricing versus biosimilar paclitaxel economy pricing defines the three-tier pricing structure across premium, standard, and economy levels in Kaposi sarcoma therapeutics. Price differentiation rests on FDA breakthrough therapy designation status and administration complexity. Pricing pressure stems from pending liposomal doxorubicin patent expirations. Public health systems in high-burden HIV regions exhibit highest price sensitivity; United States oncology centers demonstrate lowest sensitivity due to reimbursement differentials.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for paclitaxel active pharmaceutical ingredients, compressing margin structures for manufacturers without regional manufacturing footprints. API production clusters in India, China, and South Korea feed formulation facilities in Western Europe and North America. Supply chains draw from taxane plant feedstock, liposome excipient chemicals, and biologic stabilizers. Single-source vulnerability concentrates in Asian API manufacturing hubs. Distribution runs through oncology center pharmacy networks with specialty cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kaposi sarcoma therapeutics represent a service-attach opportunity where patient assistance programs and adherence monitoring services expand faster than drug hardware revenues, creating recurring revenue layers that offset biosimilar-driven price erosion in core chemotherapy agents.
For Market Incumbents: Compound defensive positioning through FDA breakthrough therapy pathway submissions for combination protocols and captive liposomal formulation manufacturing capacity in North American facilities. Biosimilar entry timelines threaten paclitaxel margin pools. Vertical integration into subcutaneous delivery device production secures protocol complexity premiums. For New Entrants and Emerging Players: FDA orphan drug designation fast-track enables market entry through HIV-associated indication carve-outs before expanding to classic Kaposi sarcoma populations. Sub-Saharan Africa procurement channels present the most penetrable geography. Outpatient administration partnerships with infectious disease clinics offer the strongest go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical conglomerates divesting legacy oncology assets with declining growth profiles. Long-term viability hinges on immunotherapy pipeline depth and HIV oncology clinical expertise. Monitor biosimilar launch announcements as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Submission | Accelerated approval compresses development timelines for checkpoint inhibitors in HIV-associated indications. |
| Backward Integration into API Manufacturing | Captive taxane production insulates margin structures from Asian supply concentration risks. |
| Sub-Saharan Africa Distribution Partnership | WHO essential medicines procurement channels unlock high-volume, price-elastic demand pools. |
| Subcutaneous Formulation Development | Home administration capability reduces oncology center capacity constraints and expands addressable settings. |
| Biosimilar Defense Strategy | Complex generic capabilities in liposomal delivery protect market position against doxorubicin patent cliffs. |
Study Parameters
Cross-validation between formulary director interviews and FDA approval documentation anchors the qualitative findings in this study. Primary fieldwork encompassed drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists across United States and European markets. Secondary sources included FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation ensured segmentation integrity.
Sensitivity analysis frameworks tested forecast robustness across immunotherapy penetration scenarios and biosimilar entry timing assumptions over the projection horizon. The analytical framework modeled treatment line, administration route, HIV status segmentation, and regional regulatory cluster dimensions. CAGRs derived from patient incidence projections, pricing trajectory assumptions, and protocol adoption curves. Forecast inputs incorporated antiretroviral therapy integration rates and checkpoint inhibitor durable response data.
Underlying assumptions cover stable HIV epidemiology and continued FDA breakthrough therapy pathway availability, with deviation risk concentrated in biosimilar launch acceleration and geopolitical API supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
North America Precision Medicine Market
Specialty Medicine
Multiple Sclerosis Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Global Hammertoe Market
Specialty Medicine
Hypothyroidism Market
Specialty Medicine
Bipolar Disorder Therapeutics Market
Specialty Medicine
Healthcare Specialty Enzymes Market
Specialty Medicine
Hepatic Insufficiency/Liver Failure Market
Specialty Medicine
Toxic Epidermal Neurolysis Market
Specialty Medicine
Hypopigmentation Disorder Treatment Market
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
Acute Hepatic Porphyria (AHP) Treatment Market
Specialty Medicine
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Anaplastic Astrocytoma Market