
 Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market | 2026-2036
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market Analysis
North American biopharma manufacturing capacity for ultra-rare neurological indications is hardening as contract development organizations expand GMP suites dedicated to low-volume biologics. Salarius Pharmaceuticals leverages its epigenetic modifier platform to sustain preclinical programs in overgrowth syndromes. Regeneron Pharmaceuticals anchors its position through VelociSuite technologies that accelerate antibody discovery for genetically defined patient populations. Ionis Pharmaceuticals differentiates via antisense oligonucleotide chemistry optimized for CNS penetration in developmental brain disorders.
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus syndrome comprises a congenital neurodevelopmental disorder characterized by brain overgrowth, abnormal cortical gyration, extra digits, and cerebrospinal fluid accumulation, with diagnostic confirmation requiring molecular genetic testing for PIK3CA or related pathway mutations alongside standardized neuroimaging protocols. The condition's primary commercial purpose centers on enabling targeted therapeutic intervention and surveillance protocols that reduce progressive neurological morbidity. Gene therapy segments attract concentrated R&D investment due to the monogenic PI3K-AKT-mTOR pathway etiology underlying most cases, while diagnostic imaging modalities occupy stable revenue positions within established pediatric neuroradiology workflows. Biologics targeting mTOR modulation represent the fastest-growing product category as mechanistic understanding deepens, though pharmaceuticals maintain volume leadership through corticosteroid and antiepileptic symptom management.
FDA orphan drug designation and EMA priority medicines pathways shape clinical trial design and market exclusivity structures for developers in this indication space, while HIPAA and GDPR frameworks govern cross-border sharing of genomic patient registries essential for natural history studies. WHO International Classification of Diseases coding revisions influence reimbursement pathways and epidemiological tracking precision for ultra-rare syndromes. Stakeholders must monitor regulatory convergence around gene therapy manufacturing standards and real-world evidence acceptance criteria as these determine viable commercialization timelines.
Market Dynamics
Gene therapy manufacturing capacity constraints are reshaping competitive positioning in this ultra-rare neurological indication, as developers race to secure viral vector production slots ahead of clinical milestones.
Growth Catalysts
- EMA Priority Medicines Pathway:Accelerated assessment timelines compress regulatory review periods for PI3K-AKT-mTOR pathway modulators, shortening time-to-market for first-in-class therapies.
- Pediatric neuroradiology workflow digitization:AI-assisted cortical gyration analysis tools embedded in MRI suites at academic medical centers are streamlining diagnostic confirmation protocols.
- Japan:METI funding for rare disease biomanufacturing infrastructure is expanding domestic GMP capacity for low-volume biologics targeting congenital malformation syndromes.
Market Restraints
- AAV vector supply concentration:Viral vector manufacturing for gene therapy candidates depends on a limited network of CDMOs in the United States and Europe, creating single-source vulnerabilities.
- GDPR genomic data friction:Cross-border sharing of PIK3CA mutation registries between European and non-European sites requires complex data transfer agreements that delay natural history study enrollment.
- Diagnostic substitution:Exome sequencing panels are displacing syndrome-specific molecular testing in cost-constrained health systems, fragmenting epidemiological tracking precision.
Strategic Opportunities
- Real-world evidence frameworks:FDA guidance on natural history data acceptance creates pathways for pre-approval market access based on longitudinal patient registry outcomes.
- Antisense oligonucleotide CNS delivery:Convergence of blood-brain barrier penetration chemistry with PIK3CA allele-selective targeting opens modality expansion beyond gene therapy.
- Germany:Underdeveloped referral networks in eastern federal states present whitespace for specialized congenital malformation syndrome centers.
Industry Challenges
- Pediatric neurogenetics talent scarcity:Fellowship-trained clinicians capable of integrating molecular diagnostics with neuroimaging interpretation remain concentrated at fewer than forty academic medical centers worldwide.
- Gene therapy facility qualification:GMP suite validation for ultra-low volume production runs requires capital deployment that strains mid-cap developer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market |
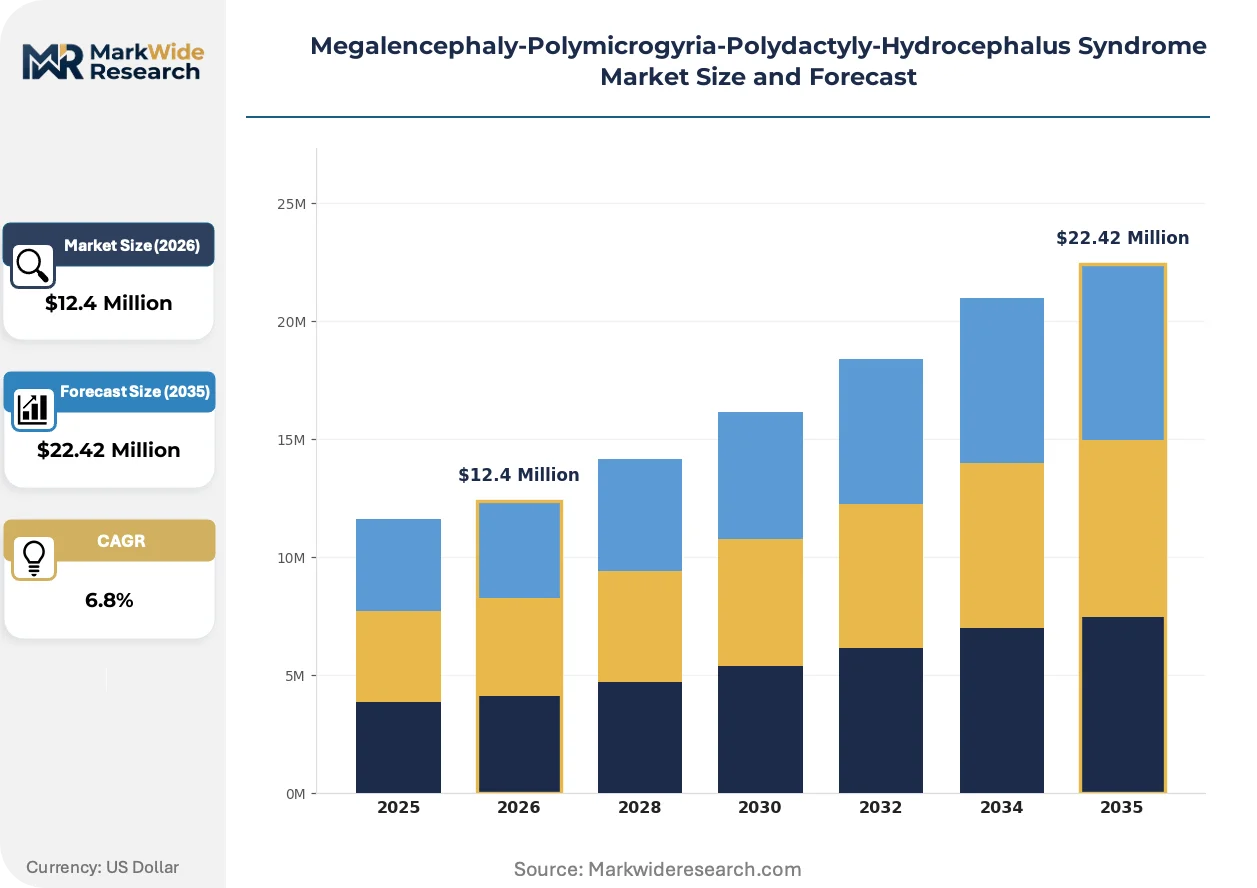
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $22.42 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Neurology, Genetics, Pediatrics, Rare Disorders Product Type: Pharmaceuticals, Biologics, Diagnostic Tools, Gene Therapy End User: Hospitals, Research Institutions, Specialty Clinics, Home Care Delivery Mode: Injectable, Oral, Infusion, Diagnostic Imaging |
| Companies Covered | Salarius Pharmaceuticals, Cytokinetics, Abbott, Catalyst Pharmaceuticals, Regeneron Pharmaceuticals, Ionis Pharmaceuticals, Pfizer, PTC Therapeutics, Novo Nordisk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market Emerging Trajectories
Mechanism-based therapeutic categorization is displacing symptomatic management paradigms, while regulatory convergence around gene therapy manufacturing standards accelerates platform standardization.
Antisense oligonucleotide chemistry optimized for CNS penetration is consolidating preclinical investment in developmental brain disorders. Academic medical center neurology departments are adopting these modalities at pace for genetically defined patient populations. This chemistry class is consolidating developer pipelines away from small-molecule mTOR inhibitors toward sequence-specific transcript targeting.
FDA orphan drug designation criteria revisions are tightening evidentiary requirements for ultra-rare syndrome prevalence calculations. Developers must now submit molecularly confirmed case counts rather than clinical phenotype estimates. Gene therapy sponsors targeting PIK3CA-related overgrowth disorders are responding by funding prospective epidemiology studies in United States pediatric neurology networks.
Academic medical center procurement for rare disease biologics is fragmenting across centralized pharmacy formulary committees and principal-investigator-driven early access programs. Traditional hospital purchasing is yielding to investigator-sponsored trial supply chains. This pattern is most visible in United States children's hospitals with established neurogenetics divisions.
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market Segmentation
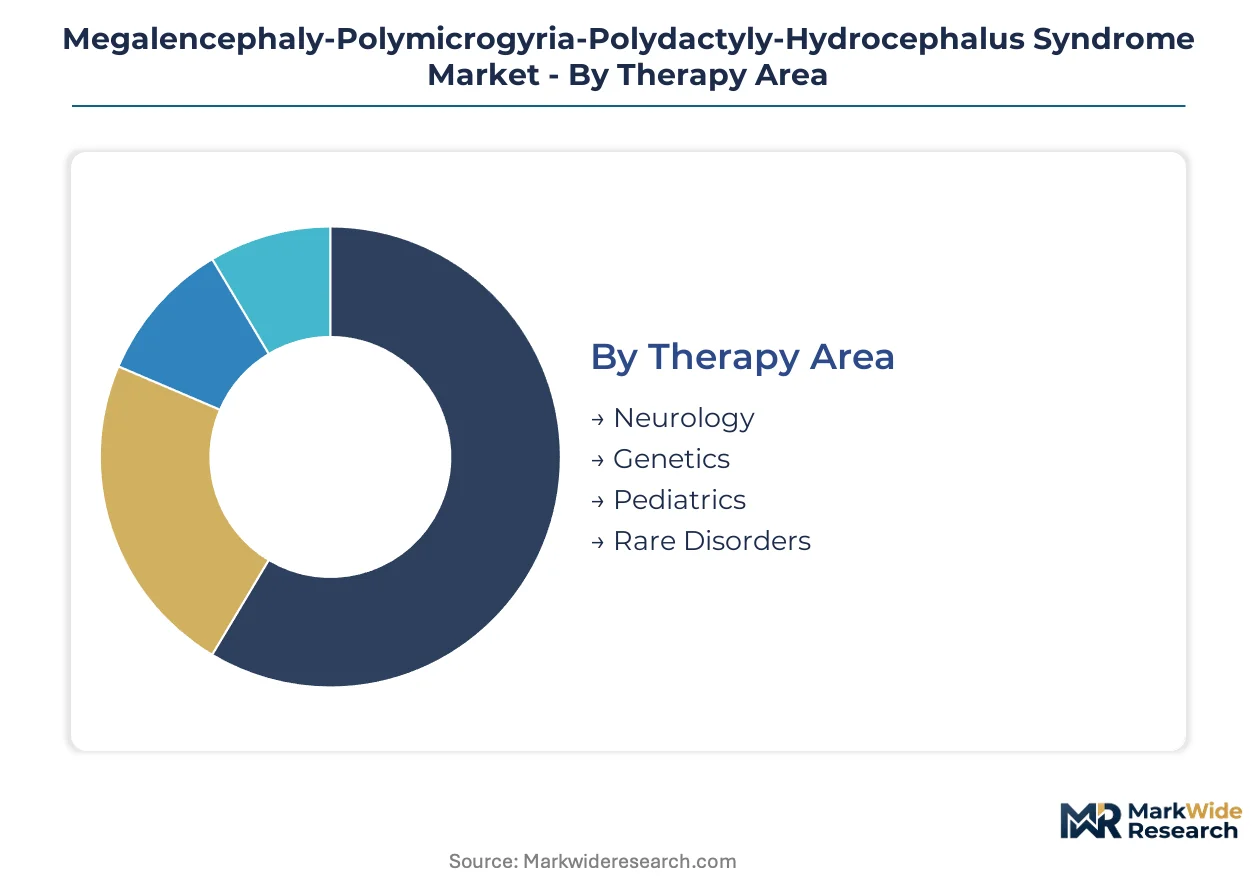
Segmentation in this ultra-rare syndrome market determines which therapeutic modalities qualify for FDA orphan drug exclusivity versus EMA priority medicines pathways. Product categories face divergent manufacturing qualification burdens and reimbursement coding requirements.
Therapy Area:
Neurology segments carry the heaviest FDA premarket approval requirements for CNS-targeted interventions, while genetics segments navigate CLIA laboratory certification for companion diagnostics.
- Neurology:Cortical malformation management drives the largest share of academic medical center pharmacy budgets. Demand concentrates at Boston Children's Hospital and Children's Hospital of Philadelphia where specialized epilepsy surgery programs integrate PIK3CA-directed therapy protocols.
- Genetics:Molecular diagnostic confirmation requires CLIA-certified laboratories with next-generation sequencing capabilities. United States reference laboratories are consolidating testing volumes as payers mandate in-network genetic counseling prerequisites.
- Pediatrics:Age-specific dosing formulations and juvenile toxicology studies impose distinct regulatory submission requirements.
- Rare Disorders:Orphan drug designation pathways compress clinical trial enrollment timelines through natural history study credits.
Neurology sits at the top of the volume ranking, with Genetics climbing the fastest.
Product Type:
Cost tier stratification separates gene therapy manufacturing investments from commoditized symptom management pharmaceuticals.
- Pharmaceuticals:Antiepileptic drugs and corticosteroids occupy the lowest per-patient cost tier with established generic substitution patterns. Hospital formularies at United States children's hospitals are tightening prior authorization requirements for brand-name anticonvulsants.
- Biologics:mTOR pathway modulators require cold-chain distribution infrastructure and specialty pharmacy networks. Japan's METI-funded biomanufacturing hubs are expanding domestic fill-finish capacity for temperature-sensitive biologics.
- Diagnostic Tools:MRI-based cortical gyration analysis software carries FDA 510(k) clearance pathways distinct from molecular IVDs.
- Gene Therapy:AAV vector manufacturing requires dedicated GMP suites with single-use bioreactor configurations. CDMO slot scarcity in the United States and Europe is extending lead times for IND-enabling toxicology batches.
Pharmaceuticals dominate current volume, though Gene Therapy is gaining share fastest through pipeline acceleration.
End User:
Customer type determines procurement authority concentration versus fragmented purchasing patterns.
- Hospitals:Academic medical center pharmacy and therapeutics committees control access to high-cost biologics. United States children's hospitals with dedicated neurogenetics divisions are establishing carve-out contracts for PIK3CA-directed therapies.
- Research Institutions:Investigator-sponsored IND pathways bypass traditional hospital procurement for early-phase gene therapy candidates. National Institutes of Health funding mechanisms favor natural history study enrollment at sites with established pediatric neurology training programs.
- Specialty Clinics:Private neurogenetics practices in Germany and the United States are adopting telemedicine models for longitudinal patient monitoring.
- Home Care:Infusion nursing networks for chronic antiepileptic administration remain underdeveloped for this ultra-rare population.
Hospitals command the highest volume concentration, with Research Institutions expanding most quickly through sponsored trial infrastructure.
Delivery Mode:
Supply concentration varies sharply across administration routes, with parenteral modalities dependent on limited sterile manufacturing capacity.
- Injectable:Intrathecal and intravenous gene therapy delivery requires specialized compounding pharmacies with CNS administration protocols. United States hospital networks are qualifying limited sites for neurosurgical vector delivery.
- Oral:Small-molecule mTOR inhibitors face bioavailability challenges for blood-brain barrier penetration. Formulation development programs at specialty pharmaceutical companies are prioritizing nanoparticle encapsulation technologies.
- Infusion:Chronic immunosuppression for gene therapy recipients demands outpatient infusion center capacity.
- Diagnostic Imaging:MRI protocols for cortical malformation characterization require 3T magnet availability at pediatric neuroradiology centers.
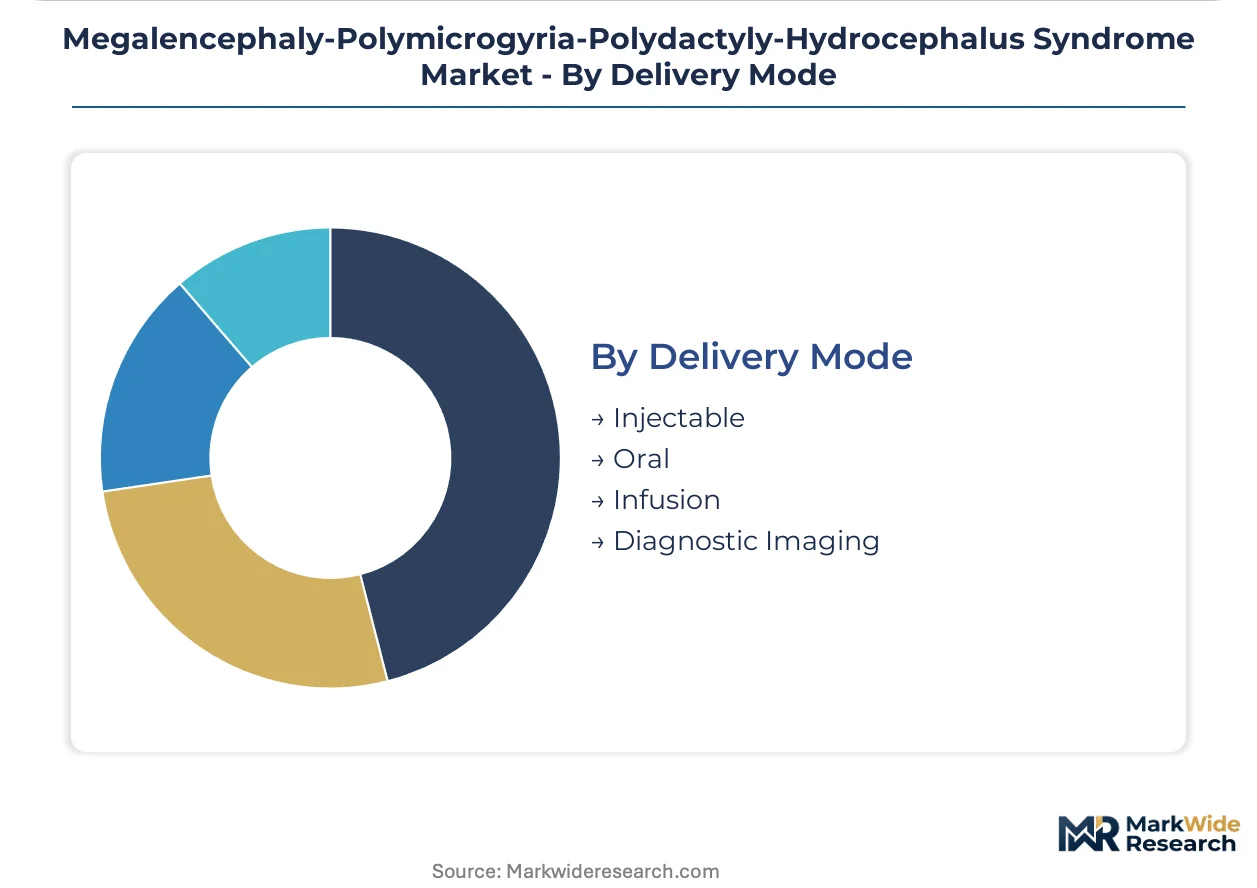
Injectable modalities lead current volume, with Diagnostic Imaging showing the steepest expansion trajectory through AI-assisted gyration analysis adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States referral networks concentrate three times more PIK3CA-confirmed cases per capita than German equivalents, though Bavaria's pediatric neuroradiology density matches Massachusetts levels. Japan's METI funding has compressed biomanufacturing lead times below North American benchmarks.
United States
Boston Children's Hospital and Children's Hospital of Philadelphia anchor specialized epilepsy surgery programs integrating PIK3CA-directed protocols. FDA orphan drug designation criteria now mandate molecularly confirmed case counts rather than clinical phenotype estimates. NIH-funded natural history study enrollment concentrates at sites with established pediatric neurology training programs in the Northeast and California.
Germany
EMA priority medicines pathways compress regulatory review periods for PI3K-AKT-mTOR pathway modulators. Eastern federal states present whitespace for specialized congenital malformation syndrome centers with underdeveloped referral networks. Heidelberg and Berlin academic medical centers are expanding GMP suites dedicated to low-volume biologics for ultra-rare neurological indications.
Japan
METI funding for rare disease biomanufacturing infrastructure is expanding domestic GMP capacity for temperature-sensitive biologics. PMDA accelerated approval pathways align with EMA priority medicines timelines for genetically defined patient populations. Tokyo and Osaka pediatric neurology departments are digitizing cortical gyration analysis workflows through AI-assisted MRI tools.
United Kingdom
NHS England specialized commissioning frameworks concentrate ultra-rare syndrome care at designated pediatric neuroscience centers. GDPR genomic data friction complicates cross-border PIK3CA mutation registry sharing with European and non-European sites. London and Manchester academic medical centers are qualifying limited sites for neurosurgical vector delivery in early-phase gene therapy trials.
Switzerland
Swissmedic alignment with EMA centralized procedures streamlines market access for mTOR pathway modulators. Basel and Zurich bioclusters host contract development organizations expanding viral vector production capacity for gene therapy candidates. Private neurogenetics practices are adopting telemedicine models for longitudinal patient monitoring across Alpine regions.
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market Vendor Landscape
United States biopharma producers anchor the gene therapy tier; European specialists hold diagnostic imaging and antisense chemistry positions. Market structure fragments across platform technologies rather than consolidating around integrated care models. Three archetypes dominate: epigenetic modifier platforms, VelociSuite-accelerated antibody discovery engines, and antisense oligonucleotide CNS penetration specialists. Competitive moves center on viral vector manufacturing slot acquisition and real-world evidence framework positioning.
Within the platform technology tier, Salarius Pharmaceuticals exemplifies epigenetic modifier approaches to overgrowth syndromes, while Regeneron Pharmaceuticals occupies a position defined by genetically targeted antibody discovery capabilities. Ionis Pharmaceuticals anchors the antisense oligonucleotide archetype with chemistry optimized for blood-brain barrier penetration in developmental brain disorders.
| Leading Market Players |
|---|
| Salarius Pharmaceuticals |
| Cytokinetics |
| Abbott |
| Catalyst Pharmaceuticals |
| Regeneron Pharmaceuticals |
| Ionis Pharmaceuticals |
| Pfizer |
| PTC Therapeutics |
| Novo Nordisk |
| Others |
Supply Flow & Price Mechanics
Academic medical center pharmacy committee consolidation around PIK3CA-directed therapy protocols is compressing procurement timelines and forcing manufacturers to pre-qualify manufacturing slots before pricing negotiations finalize. This buyer-side concentration is amplifying price transparency across gene therapy, biologic, and pharmaceutical tiers while extending contract duration to secure viral vector capacity.
Pricing Analysis
Specialty pharmacy distribution margins for mTOR pathway modulators absorb significant cost layers before reaching hospital formularies. Three-tier pricing structure across premium gene therapy, standard biologic, and economy pharmaceutical levels stratifies by manufacturing complexity and regulatory certification tier. Pricing pressure stems from generic antiepileptic substitution in corticosteroid-managed patients. Research institutions exhibit highest price sensitivity due to grant-funded procurement constraints, while dedicated rare disease centers demonstrate lowest sensitivity for mechanism-based therapies.
Supply Chain Analysis
Japan's METI domestic-content mandates for rare disease biomanufacturing are reshaping viral vector sourcing patterns away from United States and European CDMO concentration. AAV vector production draws from single-use bioreactor suites in Massachusetts, Bavaria, and Osaka prefecture. Plasmid DNA and cell bank materials rest on qualified supplier networks with limited redundancy. Single-source vulnerability concentrates in fill-finish capacity for intrathecal delivery formulations. Distribution runs through cold-chain specialty pharmacy networks with neurosurgical site qualification protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as FDA orphan drug incentives and EMA priority medicines pathways compress development timelines for PI3K-AKT-mTOR pathway modulators, sustaining developer investment across ultra-rare neurological indications.
For Market Incumbents: Deepen viral vector manufacturing partnerships through dedicated GMP suite commitments at CDMOs in United States and German clusters, securing capacity ahead of clinical milestones. Expand backward integration into plasmid DNA supply to mitigate single-source raw material risk. Antisense oligonucleotide platform entrants threaten gene therapy pricing power through CNS penetration chemistry advances. For New Entrants and Emerging Players: Launch via investigator-sponsored IND pathways at United States children's hospitals with established neurogenetics divisions, bypassing traditional hospital formulary barriers. Eastern German federal states present the most penetrable geography for specialized congenital malformation syndrome center development. Telemedicine-enabled longitudinal monitoring offers a differentiated service layer for private neurogenetics practices. For Investors and Strategic Acquirers: Asymmetric upside sits with antisense oligonucleotide platform developers possessing validated blood-brain barrier penetration chemistry for PIK3CA allele-selective targeting. Long-term viability centers on modality diversification beyond gene therapy manufacturing capacity constraints. Watch for FDA real-world evidence guidance finalization as the inflection signal for pre-approval market access valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Natural history study enrollment at NIH-funded sites accelerates FDA orphan drug designation timelines. |
| Manufacturing Scale-Up | Single-use bioreactor qualification at METI-funded Japanese hubs compresses viral vector lead times. |
| Regulatory Approval Pathway | EMA priority medicines alignment with PMDA accelerated review harmonizes multi-region market entry. |
| Pipeline Diversification | Antisense oligonucleotide CNS chemistry expansion hedges gene therapy CDMO capacity constraints. |
| Strategic Partnership | Academic medical center carve-out contracts secure pharmacy committee access for PIK3CA-directed therapies. |
Methodological Framework
Bottom-up patient population modeling reconciled against top-down CDMO capacity tracking forms the analytical core of this study. Primary interviews with pediatric neurology division chiefs, regulatory affairs leads at rare disease developers, hospital pharmacy and therapeutics committee members, and payer access specialists were validated against FDA orphan drug designation filings, EMA priority medicines submissions, ClinicalTrials.gov enrollment data, and academic medical center procurement databases. This dual-layer approach triangulates demand-side patient flow with supply-side manufacturing constraints.
Input-output matrices segment volume and value projections across therapy area, product type, end user, and delivery mode dimensions throughout the forecast period. CAGRs were derived from epidemiological prevalence modeling, treatment penetration assumptions, and pricing trajectory analysis. Forecast inputs incorporate PIK3CA mutation confirmation rates, pediatric neuroradiology workflow digitization adoption curves, and viral vector manufacturing slot availability schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under gene therapy manufacturing capacity shocks or regulatory divergence around real-world evidence acceptance criteria. Forecasts reflect documented assumptions regarding natural history study enrollment velocity and cross-border genomic data sharing framework evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Gastrointestinal Stromal Tumors Market
Specialty Medicine
Global Chondrosarcoma Market
Specialty Medicine
Eosinophilic Esophagitis Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Autosomal Dominant Polycystic Kidney Disease Treatment Market
Specialty Medicine
Global Parkinsons Disease Treatment Market
Specialty Medicine
Diverticulitis Disease Market
Specialty Medicine
Global Neurotrophic Keratitis Treatment Market
Specialty Medicine
Polycystic Kidney Disease Treatment Market
Specialty Medicine
Malignant Glioma Therapeutics Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market
Specialty Medicine
Nerve Entrapment Syndrome Therapeutics Market
Specialty Medicine
Hyperuricemia Market
Specialty Medicine
Chronic Urticaria Market