
 Relapsing-Remitting Multiple Sclerosis (MS) Market | 2026-2036
Relapsing-Remitting Multiple Sclerosis (MS) Market Size, Share, and Industry Trends Forecast 2026-2036
Relapsing-Remitting Multiple Sclerosis (MS) Market Analytics
Platform licensing revenue from specialty pharmacy networks is tilting toward manufacturers with integrated patient-support infrastructure. Biogen leverages its longstanding multiple sclerosis franchise to sustain high-touch patient adherence programs across North American and European markets. Roche anchors its position through advanced subcutaneous delivery systems that reduce hospital dependency for relapsing-remitting patients. Novartis competes on oral therapy convenience, differentiating its portfolio from infusion-dependent alternatives.
Relapsing-remitting multiple sclerosis constitutes the most common clinical course of MS, characterized by discrete inflammatory episodes followed by partial or complete recovery periods, with disease-modifying therapies targeting T-cell and B-cell mediated demyelination to reduce relapse frequency and delay disability progression. The primary commercial purpose centers on slowing neurodegeneration while preserving patient functional status across decades of chronic management. Disease-modifying therapies command the dominant value pool given their chronic administration profile and biologic manufacturing complexity, while oral administration routes are gaining preference among newly diagnosed patients seeking to avoid injection burden. Injectable segments retain substantial volume among established cases with stable therapeutic responses, and specialty pharmacies increasingly capture distribution margin through hub services and prior-authorization management.
FDA accelerated approval pathways and EMA conditional marketing authorization frameworks shape competitive timelines by permitting earlier commercial entry based on surrogate endpoints such as MRI lesion reduction. The European Medicines Agency's pharmacovigilance requirements and the FDA's Risk Evaluation and Mitigation Strategy mandates for teratogenic therapies constrain prescribing flexibility and necessitate robust patient-monitoring infrastructure. Stakeholders must monitor evolving payer evidence requirements for comparative effectiveness data, as health technology assessment bodies in Germany, France, and England tighten reimbursement criteria for therapies lacking head-to-head trial results against established standards.
Market Dynamics
Specialty pharmacy networks and integrated patient-support infrastructure are consolidating distribution control, tilting commercial advantage toward manufacturers that own the full adherence-monitoring value chain rather than those relying on fragmented wholesale channels.
Growth Catalysts
- FDA Accelerated Approval:Surrogate endpoint frameworks permit earlier commercial entry based on MRI lesion reduction, compressing development timelines for disease-modifying therapies.
- Subcutaneous Delivery Systems:Advanced injection technologies reduce hospital dependency and shift administration toward home settings, expanding addressable patient populations.
- Germany:Neurology clinics in this market are expanding patient access programs, driving volume growth for established injectable therapies through streamlined reimbursement pathways.
Market Restraints
- EMA Pharmacovigilance Requirements:Post-authorization safety monitoring mandates for teratogenic therapies constrain prescribing flexibility and elevate compliance costs across European markets.
- Biologic Manufacturing Concentration:Production of monoclonal antibodies and fusion proteins clusters among a limited supplier base, creating vulnerability to capacity constraints and quality events.
- Comparative Effectiveness Evidence Gaps:Health technology assessment bodies in France, England, and Germany tighten reimbursement criteria for therapies lacking head-to-head trial data against established standards.
Strategic Opportunities
- Oral Therapy Preference:Newly diagnosed patients in the United States are actively selecting small-molecule formulations over injection-dependent alternatives, creating white space for convenience-focused portfolios.
- Integrated Digital Adherence Platforms:Convergence of remote monitoring technology with specialty pharmacy hub services enables real-time injection tracking and proactive intervention.
- Prior-Authorization Management Services:Specialty pharmacies capturing distribution margin through streamlined payer navigation represent an underexploited channel for manufacturer partnership.
Industry Challenges
- Neuroimmunology Specialist Shortage:The limited pool of clinicians trained in MS diagnosis and long-term disease management creates bottlenecks for patient onboarding and therapy initiation.
- Risk Evaluation and Mitigation Strategy Complexity:FDA-mandated REMS programs for teratogenic therapies require extensive patient-monitoring infrastructure that strains smaller market participants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Relapsing-Remitting Multiple Sclerosis (MS) Market |
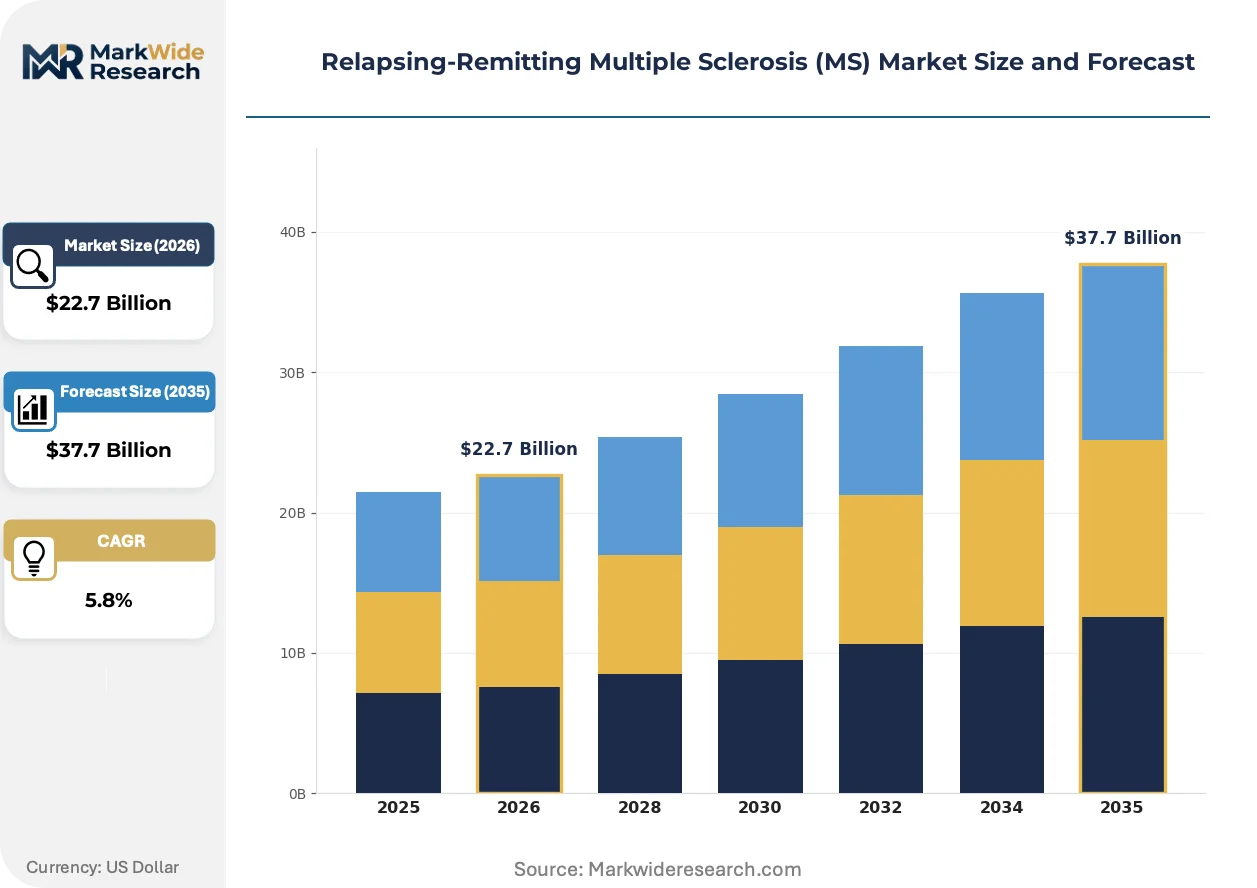
| Market Size in 2026 | $22.7 Billion |
| Market Size in 2035 | $37.7 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Disease-Modifying Therapies, Corticosteroids, Symptomatic Treatments, Plasma Exchange Administration Route: Oral, Injectable, Intravenous, Subcutaneous Patient Type: New Diagnoses, Established Cases, Relapsing Patients, First-Line Treatment Candidates Healthcare Setting: Hospitals, Clinics, Home Care, Specialty Pharmacies |
| Companies Covered | Biogen, Roche, Novartis, Sanofi, Merck KGaA, Teva Pharmaceutical Industries, Bristol Myers Squibb, Eli Lilly, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Relapsing-Remitting Multiple Sclerosis (MS) Market Evolving Landscape
Digital infrastructure is penetrating the chronic disease management workflow, compressing the interval between clinical events and therapeutic adjustments while redistributing economic value from acute care settings toward continuous monitoring platforms.
Remote patient monitoring technology is digitizing the relapse detection and adherence verification processes that previously required in-person neurology visits. Large integrated health systems in the United States are deploying these platforms at scale for their established MS populations. The technology is digitizing care coordination by enabling real-time injection confirmation and automated escalation pathways to specialty nurses.
EMA conditional marketing authorization frameworks are permitting earlier patient access based on phase 2 biomarker data while mandating rigorous post-market confirmatory trials. This regulatory architecture accelerates commercial timelines but elevates portfolio risk for therapies that fail to confirm clinical benefit. Subcutaneous biologic manufacturers face the steepest compliance burden under these evolving evidentiary standards.
Patient self-administration preferences are displacing infusion-center dependency among relapsing-remitting populations with stable disease courses. Neurology practices in Germany and the United States are restructuring their service models around home-based injection training and telehealth follow-up. This behavioral shift is most pronounced among working-age patients seeking to minimize workplace disruption from chronic therapy management.
Relapsing-Remitting Multiple Sclerosis (MS) Market Segmentation
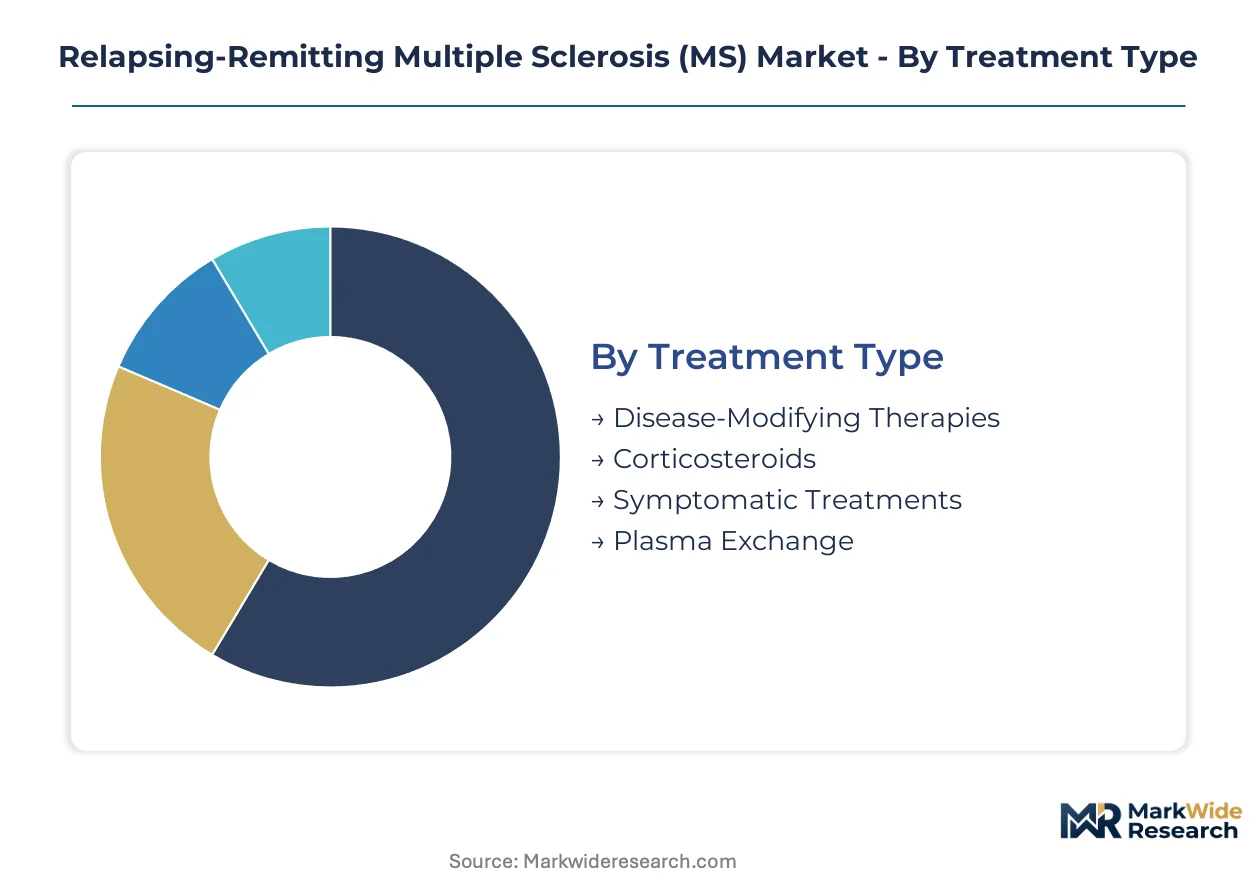
Segmentation in relapsing-remitting multiple sclerosis reveals divergent commercial strategies across therapy modalities and care delivery models. Manufacturers must align portfolio investments with distinct patient journey stages and reimbursement pathways.
Treatment Type:
Mature biologic platforms coexist with emerging small-molecule alternatives across the therapeutic landscape.
- Disease-Modifying Therapies:Monoclonal antibodies and fusion proteins targeting B-cell and T-cell pathways form the revenue backbone, with demand concentrating in Germany and the United States where prior-authorization frameworks for biologics are most established. Manufacturing complexity and chronic administration profiles sustain premium positioning.
- Corticosteroids:Acute relapse management relies on high-dose methylprednisolone protocols administered in hospital or infusion center settings. Volume concentrates in emergency neurology departments and urgent care pathways, constrained by payer limits on annual treatment episodes.
- Symptomatic Treatments:Spasticity, fatigue, and neuropathic pain management address residual disability between relapses.
- Plasma Exchange:Severe, steroid-refractory relapses in specialized centers drive intermittent demand.
Disease-Modifying Therapies handles the majority of throughput; Corticosteroids is the fastest mover on share.
Administration Route:
Cost tier differentiation separates hospital-dependent infusion models from self-administered alternatives.
- Oral:Small-molecule formulations eliminate injection burden and enable discreet workplace administration. Newly diagnosed patients in the United States actively select this convenience profile, driving fastest share expansion among working-age demographics seeking minimal lifestyle disruption.
- Injectable:Intramuscular and subcutaneous platforms retain substantial volume among established cases with stable therapeutic responses, supported by Biogen's high-touch adherence infrastructure across North American specialty pharmacy networks.
- Intravenous:Hospital-based infusion of monoclonal antibodies requires substantial infrastructure investment.
- Subcutaneous:Advanced delivery systems from Roche reduce hospital dependency and shift administration toward home settings.
Injectable handles the majority of throughput; Oral is expanding most quickly on share.
Patient Type:
Volume distribution skews toward established chronic populations while commercial focus targets conversion points in the diagnostic pathway.
- New Diagnoses:First-line therapy selection represents the highest-value decision point, with oral small-molecules capturing preference among patients seeking to avoid injection burden. Neurology practices in Germany and the United States are restructuring service models around rapid onboarding.
- Established Cases:Long-term disease-modifying therapy users with stable disease courses generate predictable refill revenue through specialty pharmacy channels, though switching pressure intensifies as novel mechanisms enter the market.
- Relapsing Patients:Breakthrough disease activity triggers therapy escalation and payer reauthorization cycles.
- First-Line Treatment Candidates:Treatment-naïve patients present the cleanest comparative effectiveness evaluation opportunity for new entrants.
Established Cases handles the majority of throughput; New Diagnoses is gaining share fastest.
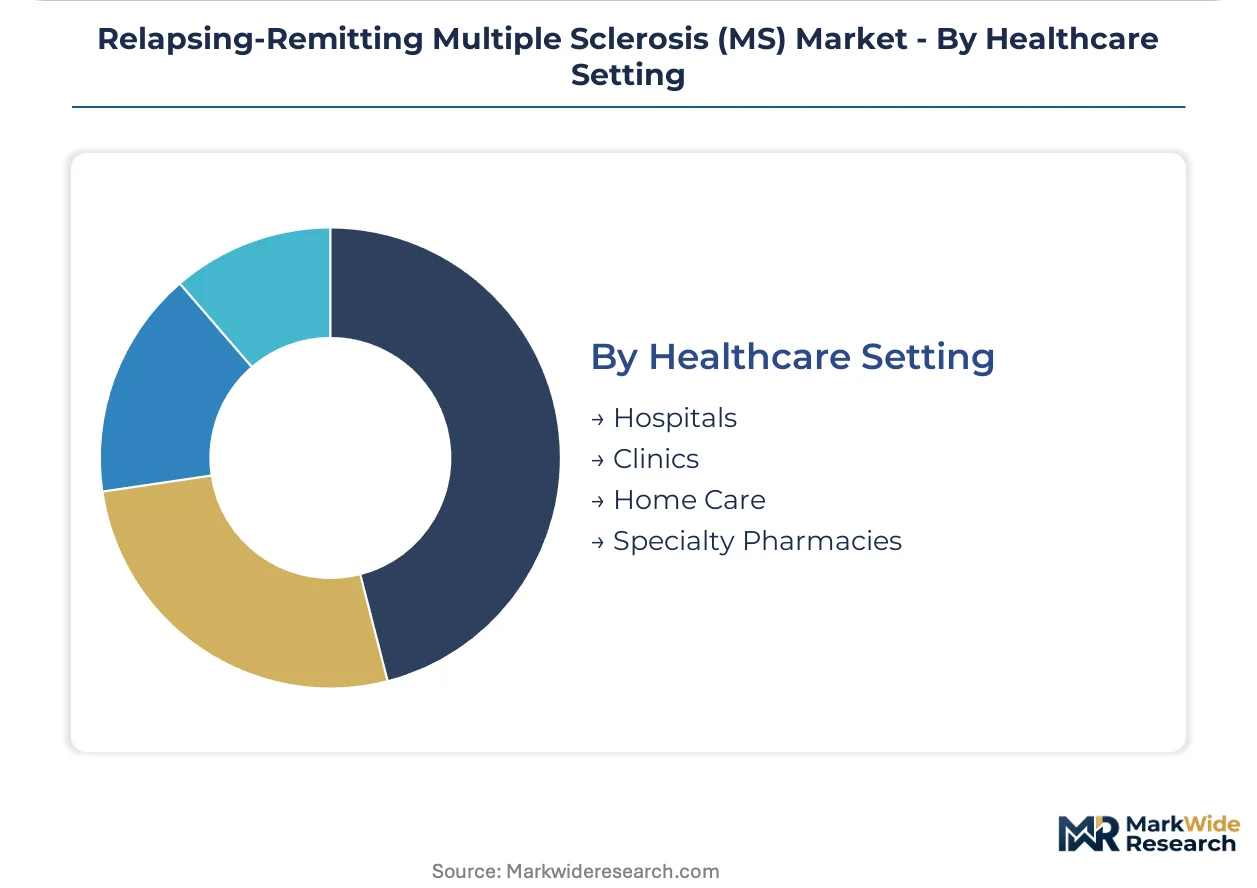
Healthcare Setting:
Supply concentration in integrated specialty pharmacy networks is displacing fragmented wholesale distribution.
- Specialty Pharmacies:Hub services and prior-authorization management capture distribution margin while providing manufacturer-sponsored adherence monitoring. Large integrated networks in the United States deploy digital infrastructure for real-time injection tracking and proactive nurse intervention.
- Hospitals:Acute relapse management and initial infusion-based therapy initiation retain high-value episodes, though subcutaneous alternatives erode chronic patient dependency on hospital infrastructure.
- Clinics:Neurology practices in Germany are expanding patient access programs for injectable therapies through streamlined reimbursement pathways.
- Home Care:Self-administration training and telehealth follow-up expand addressable populations among mobility-limited patients.
Specialty Pharmacies handles the majority of throughput; Home Care is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across markets. Patients in the United States face substantial out-of-pocket exposure for biologic therapies, while German and Swiss reimbursement frameworks buffer consumer sensitivity through statutory health insurance integration.
United States
Commercial payer prior-authorization requirements drive therapy selection toward established disease-modifying therapies with robust real-world evidence portfolios. FDA Risk Evaluation and Mitigation Strategy mandates for teratogenic therapies constrain prescribing flexibility and necessitate certified pharmacy networks. Neurology practices in Greater Boston and the Pacific Northwest are deploying remote patient monitoring infrastructure to digitize adherence verification.
Germany
Neurology clinics in Bavaria and North Rhine-Westphalia are expanding patient access programs for injectable therapies through streamlined reimbursement pathways under the statutory health insurance system. The Federal Joint Committee (G-BA) health technology assessment framework tightens evidence requirements for therapies lacking head-to-head trial data against established standards. Manufacturing clusters in Hesse and Baden-Württemberg sustain biologic production capacity for European supply.
France
The Haute Autorité de Santé comparative effectiveness review process delays market access for novel mechanisms lacking demonstrated superiority over existing standards. Hospital-based neurology departments in Île-de-France and Auvergne-Rhône-Alpes retain dominant infusion-center infrastructure for monoclonal antibody administration. Regional disparities in specialist density create access bottlenecks for rural patient populations in Nouvelle-Aquitaine.
United Kingdom
NICE technology appraisal criteria prioritize cost-effectiveness thresholds that favor oral small-molecule formulations over biologic alternatives for first-line therapy selection. NHS England specialized commissioning frameworks concentrate high-cost therapy administration in designated neurology centers across London, Manchester, and Birmingham. Devolved health systems in Scotland and Wales maintain independent access pathways with variable reimbursement timelines.
Switzerland
Swissmedic marketing authorization timelines and mandatory health insurance coverage create favorable commercial conditions for subcutaneous delivery platforms. The Federal Office of Public Health comparative effectiveness review process evaluates therapies against established standards within twelve months of EMA approval. Basel and Zurich anchor biopharmaceutical R&D clusters with integrated patient-support infrastructure for chronic disease management.
Relapsing-Remitting Multiple Sclerosis (MS) Market Competitive Landscape
Integrated biopharmaceutical conglomerates and specialty neurology-focused developers split the market along therapy-modality lines. The competitive structure concentrates around three archetypes: legacy neurology franchise holders with deep patient-support infrastructure, diversified biologics manufacturers leveraging subcutaneous delivery innovation, and oral small-molecule specialists competing on convenience differentiation. Dominant competitive moves include strategic partnerships with specialty pharmacy networks and portfolio diversification across administration routes to capture switching patients.
Within the legacy franchise tier, Biogen exemplifies sustained market presence through high-touch adherence programming. Roche anchors the biologics-delivery innovation vector through advanced subcutaneous systems. Novartis occupies the oral-therapy convenience position, differentiating from infusion-dependent alternatives. These three companies represent distinct strategic postures without implying specific market share claims.
| Leading Market Players |
|---|
| Biogen |
| Roche |
| Novartis |
| Sanofi |
| Merck KGaA |
| Teva Pharmaceutical Industries |
| Bristol Myers Squibb |
| Eli Lilly |
| AstraZeneca |
| Others |
Value Network & Pricing Analysis
Undercapacity in biologic active pharmaceutical ingredient manufacturing across Ireland and Singapore is compressing supplier bargaining power while elevating price premiums for monoclonal antibody therapies. This utilization squeeze forces contract manufacturers to prioritize established pharmaceutical relationships, reinforcing tiered access patterns across European and North American markets.
Pricing Analysis
Adherence-monitoring service contracts generate lifetime value exceeding the initial therapy acquisition cost by substantial multiples. Three-tier pricing structure across premium biologics, standard injectables, and economy oral formulations stratifies the market, with FDA REMS certification requirements and real-world evidence portfolios serving as the primary differentiation drivers. Pricing pressure stems from health technology assessment bodies in Germany and England demanding head-to-head trial data for reimbursement eligibility. Newly diagnosed patients in the United States exhibit highest price sensitivity due to out-of-pocket exposure, while established cases with stable responses demonstrate lowest sensitivity given switching costs.
Supply Chain Analysis
Contract manufacturing concentration rests with Lonza, Boehringer Ingelheim, and Samsung Biologics for monoclonal antibody production. Biologic supply anchors in Ireland, Singapore, and Switzerland, with fill-finish capacity drawing from specialized facilities in Germany and the United States. Raw material dependencies center on recombinant cell lines, single-use bioreactor systems, and temperature-controlled logistics infrastructure. Single-source vulnerability for critical monoclonal antibody production creates exposure to quality events and capacity constraints. Distribution runs through integrated specialty pharmacy networks that capture margin via hub services and prior-authorization management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substitution defense defines strategic priority as oral small-molecule therapies displace injection-dependent alternatives among treatment-naïve patient populations. Incumbents must navigate convenience-driven switching pressure while preserving established patient adherence infrastructure.
For Market Incumbents: Entrench market position through backward integration into subcutaneous delivery device manufacturing and captive supply of critical monoclonal antibody capacity in Ireland or Singapore. Expand high-touch adherence programming to offset oral therapy convenience advantages, while investing in real-world evidence generation to satisfy German G-BA and English NICE comparative effectiveness requirements.
For New Entrants and Emerging Players: Pursue white-space opportunity in integrated digital adherence platforms that converge remote monitoring with specialty pharmacy hub services. Target newly diagnosed patients in United States commercial payer segments where oral therapy preference is most pronounced, deploying direct-to-patient onboarding models that bypass traditional neurology practice bottlenecks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across subcutaneous biologics manufacturing due to advanced delivery system complexity and EMA pharmacovigilance compliance infrastructure. Five-to-ten-year viability favors platforms with demonstrated REMS program execution and established specialty pharmacy network partnerships. Monitor FDA accelerated approval confirmation trial outcomes as the critical inflection signal for portfolio risk reassessment.
| Strategic Initiative | Industry Significance |
|---|---|
| Specialty Pharmacy Network Partnership | Biogen's hub service integration captures distribution margin and adherence data across North American markets. |
| Subcutaneous Delivery System Development | Roche's advanced injection platforms reduce hospital dependency and expand addressable patient populations. |
| Real-World Evidence Generation | Robust post-market data satisfies German G-BA and English NICE head-to-head trial requirements for reimbursement. |
| Integrated Digital Adherence Platform | Remote monitoring convergence enables real-time injection tracking and proactive nurse intervention at scale. |
| Regulatory Approval Pathway Optimization | FDA accelerated approval and EMA conditional authorization compress commercial timelines for surrogate endpoint frameworks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down revenue triangulation were cross-checked against specialty pharmacy dispensing data and statutory health insurance reimbursement records.
Forecast inputs span treatment line, administration route, patient population, and regional regulatory cluster across the projection horizon. CAGRs were derived from segmented volume projections calibrated to therapy initiation rates, switching patterns, and discontinuation curves. Modeling incorporated FDA REMS program expansion timelines, EMA pharmacovigilance mandate evolution, and health technology assessment body evidence requirement shifts.
Macroeconomic conditions sit as an overlay; deviation in biologic manufacturing input costs, reimbursement policy, or regulatory approval timelines would shift the trajectory. Forecasts reflect documented assumptions about patient adherence rates, specialty pharmacy network concentration, and comparative effectiveness evidence standards. Quarterly review of FDA confirmation trial readouts, EMA safety signal reports, and German G-BA appraisal decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Malignant Pleural Effusion Market
Specialty Medicine
Acrocallosal Syndrome Therapeutics Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Glioblastoma Multiforme Treatment (GBM) Market
Specialty Medicine
Prostate Cancer Therapeutics Market
Specialty Medicine
Cachexia Treatment Market
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Cutaneous B-Cell Lymphoma Treatment Market
Specialty Medicine
North America Precision Medicine Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Tonsil Cancer Market
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
Pseudobulbar Treatment Market
Specialty Medicine
HER2 Positive Gastric Cancer Market