
 Global Sarcopenia Treatment Market | 2026-2036
Global Sarcopenia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sarcopenia Treatment Market Foresight
Recombinant peptide formulations are broadening therapeutic options for age-related muscle atrophy. Pfizer Inc. leverages its biologics infrastructure to sustain development of myostatin-targeting compounds. Novartis AG anchors its position through metabolic enhancement research programs. Amgen Inc. differentiates via bone-muscle crosstalk investigations that occupy a distinct niche in the pipeline.
Sarcopenia treatment encompasses pharmacological and nutritional interventions designed to preserve or restore skeletal muscle mass, strength, and physical function in aging populations; peptide therapies typically employ recombinant growth factors or myostatin inhibitors administered via subcutaneous injection to stimulate muscle protein synthesis. The primary purpose is reducing frailty, fall incidence, and disability-related healthcare utilization among individuals over sixty-five. Nutritional supplements command the largest revenue pool due to established reimbursement and over-the-counter accessibility, while peptide segments attract the fastest development velocity as clinical data accumulates for myostatin pathway modulation. Injectable delivery modes concentrate margin capture in specialized clinic settings where administration oversight justifies premium positioning.
FDA orphan drug designations and EMA conditional marketing authorizations are accelerating review timelines for sarcopenia-targeted therapies, while Japan's PMDA maintains distinct efficacy endpoints for sarcopenia-specific indications that shape trial design requirements. WHO inclusion of sarcopenia in ICD-11 is expanding diagnostic coding availability and reimbursement eligibility across healthcare systems. Stakeholders must monitor regulatory divergence between muscle-mass endpoints and functional-outcome measures as payers evaluate coverage criteria for emerging therapeutic classes.
Market Dynamics
Peptide-based myostatin inhibitors are compressing development timelines and forcing nutritional supplement incumbents to defend reimbursement positioning against injectable biologics.
Growth Catalysts
- ICD-11 diagnostic coding:WHO's inclusion of sarcopenia in the International Classification of Diseases is expanding insurance eligibility and physician screening protocols across healthcare systems.
- Japan's METI guidelines:The Ministry of Economy, Trade and Industry has established specific efficacy endpoints that accelerate domestic trial design and commercialization pathways.
- Geriatric care facilities:Long-term care operators in the United States, Germany, and Japan are integrating muscle-wasting protocols into standardized fall-prevention programs.
Market Restraints
- Recombinant protein manufacturing:Bioreactor capacity constraints and single-use component costs concentrate production among contract manufacturers in Switzerland and Ireland.
- Functional-outcome measurement:Payers require gait-speed and grip-strength data that extend trial duration beyond muscle-mass biomarkers preferred by developers.
- Oral peptide bioavailability:Gastric degradation forces subcutaneous delivery, limiting patient adherence relative to small-molecule alternatives in development.
Strategic Opportunities
- Home-based administration:Prefilled autoinjector formats are opening direct-to-patient channels that bypass clinic-based infusion centers.
- Cachexia-sarcopenia overlap:Oncology supportive care represents an adjacent indication with shared mechanistic targets and accelerated FDA review pathways.
- South Korean manufacturing:MFDS regulatory alignment with ICH standards and lower biologics production costs attract contract development investments.
Industry Challenges
- Muscle-imaging standardization:DEXA, CT, and MRI protocols lack harmonization across FDA, EMA, and PMDA submissions, complicating multi-regional trial design.
- Specialized endocrinology workforce:Clinicians trained in growth-factor therapeutics remain concentrated in academic medical centers, constraining community adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sarcopenia Treatment Market |
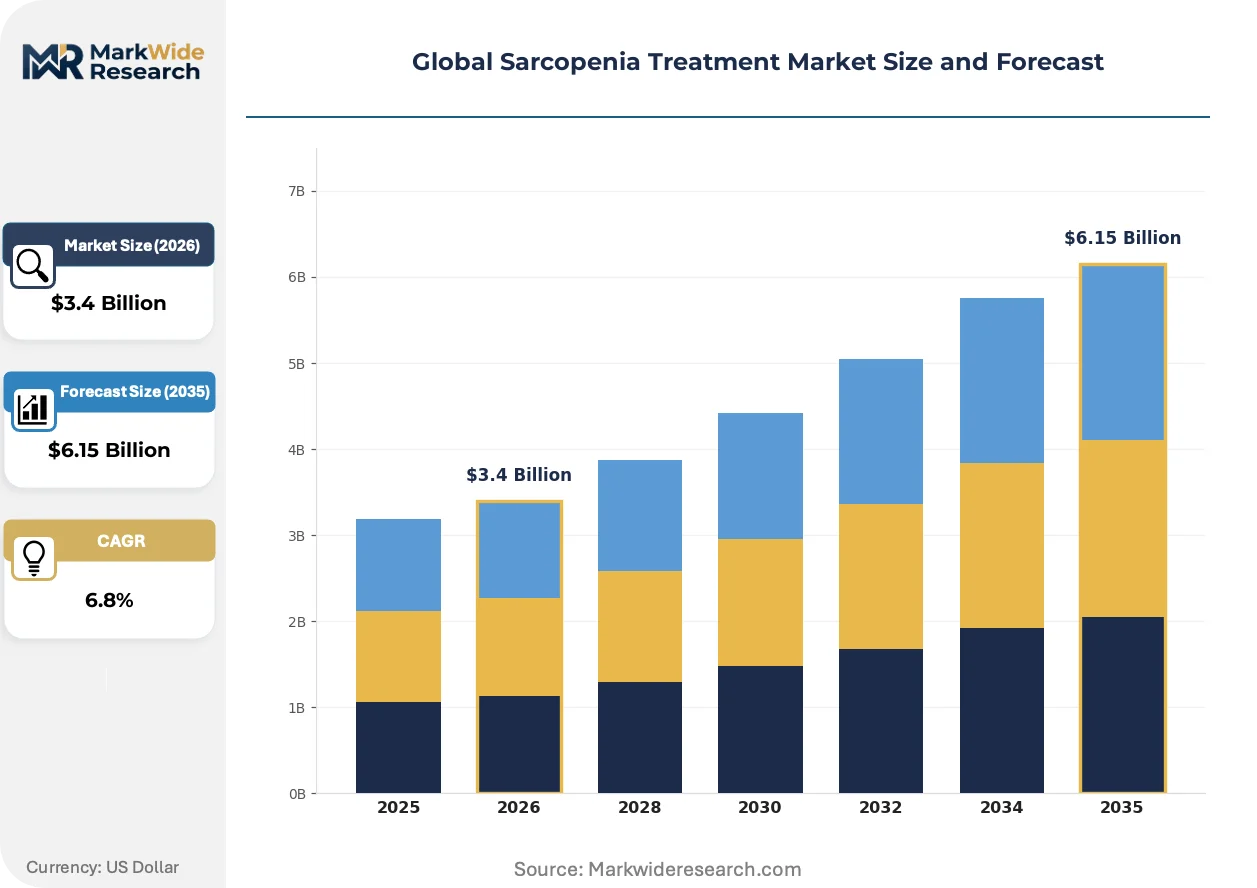
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Nutritional Supplements, Hormone Therapy, Peptides, Enzyme Inhibitors, Others Therapy Area: Muscle Regeneration, Metabolic Enhancement, Inflammation Control, Hormonal Balance, Neuromuscular Function, Bone Health End User: Geriatric Care Facilities, Rehabilitation Centers, Specialized Clinics, Home Healthcare Providers, Research Institutes Delivery Mode: Oral, Injectable, Topical, Transdermal, Intravenous |
| Companies Covered | Pfizer Inc., Novartis AG, Bayer AG, Abbott Laboratories, Nestle Health Science, GlaxoSmithKline plc, Sanofi, Amgen Inc., Biophytis SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sarcopenia Treatment Market Shifts & Advancements
Bioconjugate delivery systems and real-world evidence collection are reconfiguring how muscle-wasting therapies demonstrate value to reimbursement authorities.
Dual-action fusion proteins that simultaneously block myostatin and activate activin type IIB receptors are electrifying the competitive landscape. Geriatric medicine departments at academic hospitals in the United States and Japan are prioritizing these candidates in early-access programs. The technology is compressing the efficacy gap between nutritional interventions and full biologic therapy, forcing mid-tier supplement manufacturers to reposition around compliance and cost rather than outcomes.
EMA's conditional marketing authorization pathway for medicines addressing unmet medical needs is shortening pre-approval data requirements for sarcopenia-targeted therapies. Developers can now submit on surrogate endpoints with post-marketing commitments for functional outcomes. Small and mid-cap biotech firms with limited commercial infrastructure are responding by prioritizing European launch sequencing ahead of United States FDA submissions.
Hospital purchasing coalitions are consolidating procurement authority for specialty biologics under centralized pharmacy and therapeutics committees. Independent long-term care operators and regional health systems are losing direct negotiating leverage with manufacturers. This concentration is most visible in Germany, where hospital federation purchasing agreements now cover injectable peptide therapies previously acquired through wholesaler relationships.
Global Sarcopenia Treatment Market Segmentation
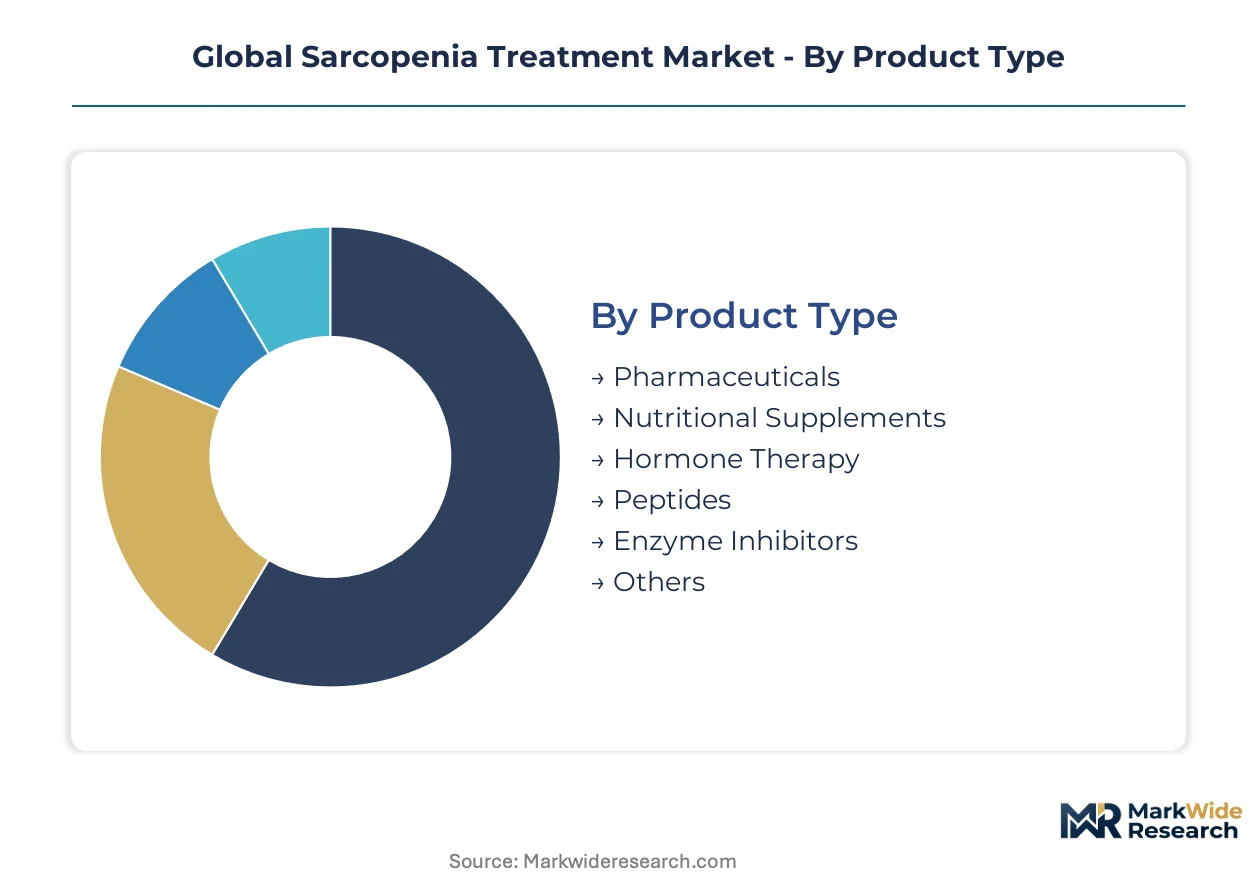
Peptide biologics and nutritional supplements operate on fundamentally different margin structures within sarcopenia care. Therapy selection hinges on reimbursement pathways, administration infrastructure, and patient functional status rather than clinical efficacy alone.
Product Type:
Volume concentrates in over-the-counter nutritional formulations while premium capture belongs to injectable biologics requiring cold-chain distribution and clinical oversight.
- Pharmaceuticals:Small-molecule anabolic agents and selective androgen receptor modulators comprise this segment. Demand clusters in Germany and Japan where centralized pharmacy committees negotiate formulary placement for muscle-wasting indications.
- Nutritional Supplements:Branched-chain amino acid formulations, vitamin D complexes, and protein-fortified medical foods dominate prescription volumes. Long-term care operators in the United States purchase through group purchasing organizations that squeeze wholesale margins.
- Hormone Therapy:Testosterone and growth hormone replacement protocols face reimbursement restrictions from Medicare and commercial payers.
- Peptides:Recombinant myostatin inhibitors and IGF-1 analogs command the steepest expansion trajectory. Prefilled autoinjector formats are opening home administration channels that bypass clinic-based infusion centers.
- Enzyme Inhibitors:Proteasome and autophagy pathway modulators remain preclinical or early-phase development candidates.
- Others:Stem cell therapies and gene transfer approaches occupy experimental niches within academic medical center protocols.
Mature deployment sits with Nutritional Supplements. Newer deployment is concentrated in Peptides.
Therapy Area:
Application logic follows the physiological cascade from muscle protein synthesis through systemic metabolic support.
- Muscle Regeneration:Direct myofiber repair mechanisms target satellite cell activation and myonuclear accretion. Japanese PMDA guidelines explicitly recognize muscle mass endpoints for this category, accelerating domestic trial design.
- Metabolic Enhancement:Mitochondrial biogenesis and glucose uptake optimization address insulin resistance common in sarcopenic obesity. Novartis anchors research programs here, pursuing distinct positioning from myostatin-targeting competitors.
- Inflammation Control:IL-6 and TNF-alpha pathway modulation targets the inflammatory milieu of aging.
- Hormonal Balance:DHEA and selective estrogen receptor modulation address endocrine decline.
- Neuromuscular Function:Motor unit preservation strategies target the nerve-muscle interface.
- Bone Health:Osteosarcopenia protocols exploit muscle-bone crosstalk. Amgen differentiates via investigations in this niche.
Clinical validation concentrates in Muscle Regeneration. Emerging interest is expanding fastest in Metabolic Enhancement.
End User:
Procurement authority is consolidating under centralized pharmacy and therapeutics committees, squeezing independent operators.
- Geriatric Care Facilities:Nursing homes and assisted living operators integrate muscle-wasting protocols into standardized fall-prevention programs. Japan's METI guidelines shape procurement specifications for these institutions.
- Rehabilitation Centers:Post-acute facilities prioritize functional outcome measures including gait speed and timed up-and-go performance. Payer requirements for this data extend trial duration beyond muscle-mass biomarkers preferred by developers.
- Specialized Clinics:Endocrinology and geriatric medicine departments concentrate growth-factor therapeutic expertise.
- Home Healthcare Providers:Visiting nurse organizations are gaining formulary influence as autoinjector formats enable subcutaneous administration outside clinical settings.
- Research Institutes:Academic medical centers in the United States and Japan prioritize dual-action fusion proteins in early-access programs.
Established volume flows through Geriatric Care Facilities. Fastest expansion is occurring in Home Healthcare Providers.
Delivery Mode:
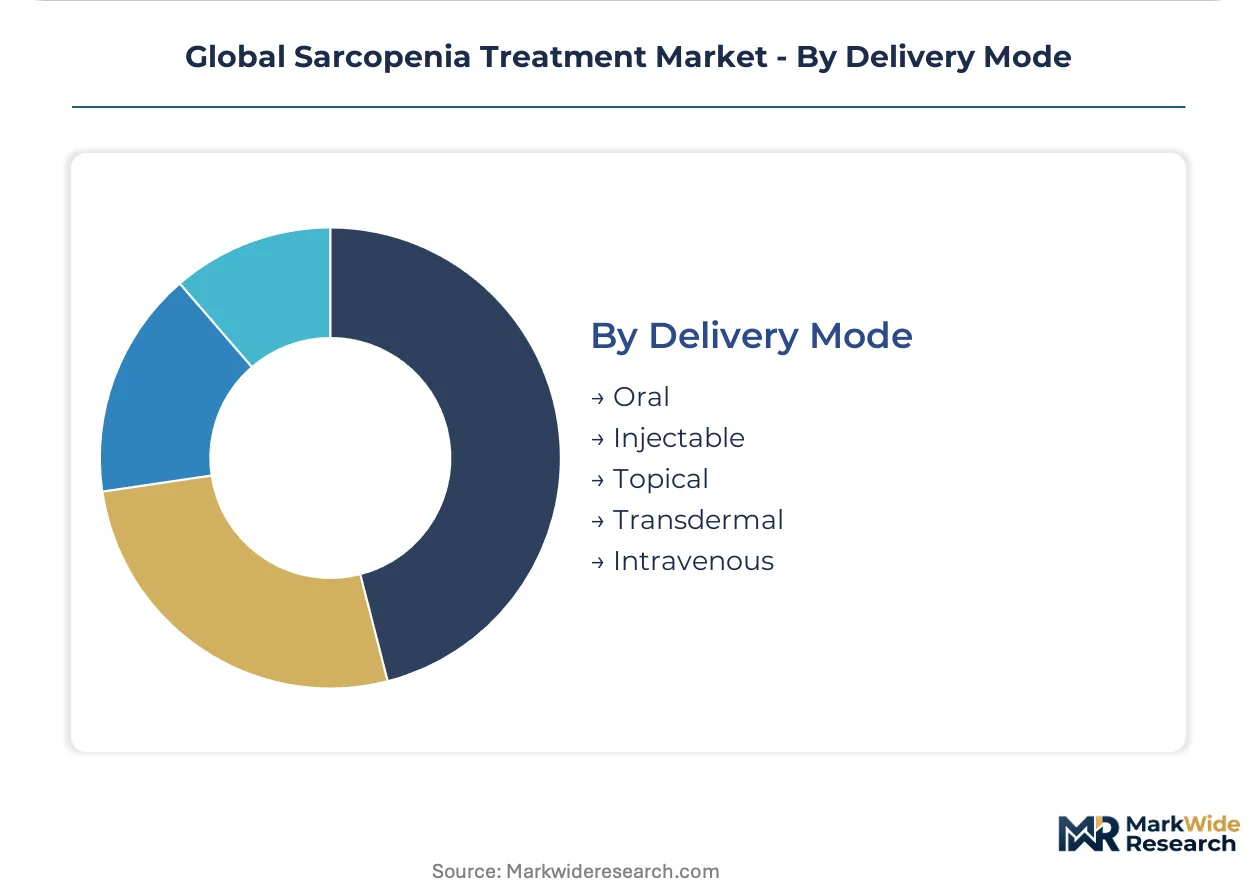
Patient adherence and reimbursement complexity separate oral convenience from injectable efficacy.
- Oral:Small molecules and nutritional formulations offer patient convenience but face gastric degradation limitations for peptide therapeutics. OTC accessibility drives volume in United States retail pharmacy channels.
- Injectable:Subcutaneous delivery concentrates margin capture in specialized clinic settings where administration oversight justifies premium positioning. Cold-chain requirements restrict distribution to contract manufacturers in Switzerland and Ireland.
- Topical:Transdermal hormone patches address compliance concerns for testosterone replacement.
- Transdermal:Microneedle and iontophoresis technologies seek to bridge bioavailability and convenience gaps.
- Intravenous:Hospital-based infusion for acute sarcopenia interventions remains limited to oncology supportive care overlaps.
Volume dominance rests with Oral formats. Technology investment is concentrating in Injectable and Transdermal innovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Kansai Biomedical Special Zone and Osaka's regenerative medicine cluster concentrate peptide manufacturing infrastructure for sarcopenia therapeutics. Tax incentives for cell-culture facilities draw contract development organizations to the region. METI's streamlined approval pathways accelerate commercialization timelines for domestic developers.
United States
Medicare Advantage plans in Florida and Arizona now cover functional-assessment protocols for sarcopenia screening in senior living communities. FDA's Center for Drug Evaluation and Research issued draft guidance on muscle-wasting endpoints in 2023, clarifying biomarker acceptance criteria for Phase III trials. The Greater Boston biotech corridor hosts concentrated myostatin-inhibitor development programs at academic medical centers.
Japan
PMDA's sarcopenia-specific efficacy endpoints permit muscle-mass primary outcomes that shorten trial duration versus functional-measure requirements elsewhere. METI's regenerative medicine regulatory sandbox allows conditional marketing authorization for peptide therapies demonstrating surrogate benefit. Osaka's Kansai cluster anchors domestic bioreactor capacity for recombinant protein production.
Germany
Hospital federation purchasing agreements now centralize procurement authority for injectable peptide therapies under pharmacy and therapeutics committees. EMA's conditional marketing authorization pathway attracts developers seeking accelerated European entry. The Rhine-Main biotech corridor around Frankfurt concentrates contract manufacturing for cold-chain biologics.
Switzerland
Swissmedic's alignment with EMA standards enables parallel submission strategies for muscle-wasting therapeutics. The Basel biopharma cluster leverages existing biologics infrastructure originally developed for oncology and immunology applications. Cantonal tax incentives for R&D-intensive operations sustain contract manufacturing investments.
South Korea
MFDS regulatory harmonization with ICH standards reduces duplicate clinical trial requirements for sarcopenia indications. The Songdo International Business District's free economic zone offers ten-year corporate tax exemptions for biologics manufacturing facilities. Seoul Capital Area hospitals participate in multinational myostatin-inhibitor trials through early-access frameworks.
Global Sarcopenia Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with nutritional supplement incumbents defending retail pharmacy positioning against injectable biologic entrants. The peptide therapy segment concentrates among biopharma conglomerates with existing biologics infrastructure, while medical nutrition remains fragmented across food-science multinationals and regional formulators. Three archetypes dominate: integrated biopharma developers with myostatin-targeting pipelines, diversified nutrition-science conglomerates with established geriatric care distribution, and specialized biotech firms pursuing conditional authorization pathways. Competitive moves center on bioconjugate delivery system licensing and real-world evidence partnerships with long-term care operators.
Within the integrated biopharma tier, Pfizer Inc. and Novartis AG occupy positions anchored by existing biologics manufacturing networks and metabolic research programs. Amgen Inc. exemplifies the bone-muscle crosstalk specialization archetype, leveraging investigative pathways distinct from direct myostatin inhibition. These three entities represent the dominant development concentration for recombinant peptide formulations targeting age-related muscle atrophy.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Bayer AG |
| Abbott Laboratories |
| Nestle Health Science |
| GlaxoSmithKline plc |
| Sanofi |
| Amgen Inc. |
| Biophytis SA |
| Others |
Supply & Pricing Matrix
Injectable biologic premiums and nutritional supplement commoditization create a stark bifurcation that manifests in divergent supply chain configurations across the sarcopenia treatment landscape. Cold-chain bioreactor capacity constraints in Switzerland and Ireland prop pricing power for recombinant peptide manufacturers, while over-the-counter amino acid formulations compete on volume through retail pharmacy channels.
Pricing Analysis
Volume concentrates in low-margin nutritional supplements while margin capture belongs to injectable biologics requiring clinical oversight. Three-tier pricing structure across premium peptide therapies, standard medical foods, and economy OTC supplements reflects reimbursement eligibility and administration complexity. Pricing pressure stems from Medicare Advantage formulary negotiations squeezing nutritional supplement margins. Long-term care operators exhibit highest price sensitivity due to group purchasing organization consolidation, while specialized endocrinology clinics accept premium positioning for myostatin inhibitors.
Supply Chain Analysis
Dual-sourcing requirements from hospital purchasing coalitions mandate multi-supplier qualification for recombinant protein manufacturers. Bioreactor capacity concentrates in Switzerland, Ireland, and South Korea, with single-use component dependencies tethered to German and Japanese precision engineering suppliers. Tariff exposure on Chinese-sourced raw materials for nutritional formulations presents structural vulnerability. Distribution runs through centralized pharmacy and therapeutics committees at hospital federations, bypassing traditional wholesaler relationships for injectable therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioreactor capacity scarcity props pricing across peptide segments, constraining supply expansion and sustaining margin structures for qualified manufacturers.
For Market Incumbents: To counter nutritional supplement commoditization, peptide developers should deepen backward integration into bioreactor capacity in South Korea's Songdo free economic zone. Securing EMA conditional marketing authorization ahead of FDA submission accelerates revenue recognition while competitors await functional-outcome data collection. For New Entrants and Emerging Players: Prefilled autoinjector technology offers a technology-first wedge into home healthcare channels bypassing clinic-based infusion centers. South Korean manufacturing partnerships exploit MFDS-ICH regulatory harmonization and ten-year tax exemptions. Target rehabilitation centers in Japan where METI guidelines permit muscle-mass endpoints shortening trial duration. For Investors and Strategic Acquirers: Re-rating potential sits with dual-action fusion protein developers given PMDA's accelerated approval pathways and early-access program prioritization at academic medical centers. Long-term viability hinges on real-world evidence collection partnerships with geriatric care facility operators. Watch for FDA draft guidance finalization on muscle-wasting endpoints as inflection indicator for Phase III capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA conditional authorization accelerates European market entry ahead of FDA timelines. |
| Manufacturing Scale-Up | South Korean bioreactor investments exploit MFDS harmonization and tax incentives. |
| Licensing Agreement | Bioconjugate delivery system partnerships differentiate peptide formulations from nutritional competitors. |
| Clinical Trial Advancement | Japan's muscle-mass endpoints compress development timelines versus functional-measure requirements. |
| Pipeline Diversification | Cachexia-sarcopenia overlap indications access oncology supportive care reimbursement pathways. |
Research Methodology
Independent corroboration across regulatory filings, hospital procurement databases, and clinical trial registries underwrites the qualitative findings in this analysis. Primary interviews with drug development executives, formulary directors at Medicare Advantage plans, and geriatric care facility procurement managers combined with secondary validation from FDA guidance documents, EMA assessment reports, and PMDA consultation minutes. Bottom-up patient population sizing and top-down healthcare expenditure analysis triangulate market estimates.
Rate-of-change decomposition across the projection horizon separates volume expansion from price evolution in peptide and nutritional segments. The analytical framework models therapy area, delivery mode, and end-user channel dimensions alongside regional regulatory cluster variations. CAGRs derive from patient cohort growth, reimbursement expansion trajectories, and bioreactor capacity buildout assumptions. Forecast inputs include ICD-11 diagnostic coding adoption curves and METI guideline implementation timelines.
Several conditions sit outside the modeled scope, including stem cell therapy regulatory reclassification and gene transfer approach clinical success. Forecasts reflect assumptions on payer acceptance of surrogate endpoints and home administration infrastructure buildout. A model refresh is warranted upon material change in FDA muscle-wasting endpoint guidance finalization or EMA conditional authorization precedent for sarcopenia indications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Global Brain Tumor Therapeutics Market
Specialty Medicine
Autism Spectrum Disorder Management Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
Perennial Allergic Rhinitis Market
Specialty Medicine
Dupuytrens Disease Market
Specialty Medicine
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market
Specialty Medicine
Europe Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Soft Tissue Sarcoma Market
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Ulcerative Colitis Therapeutics Market
Specialty Medicine
Pemphigus Vulgaris (PV) Treatment Market
Specialty Medicine
Angioimmunoblastic T-Cell Lymphoma (AILT) Market
Specialty Medicine
Global Hypoparathyroidism Treatment Market
Specialty Medicine
Cubital Tunnel Syndrome Market