
 Fascioliasis Treatment Market | 2026-2036
Fascioliasis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Fascioliasis Treatment Market Analysis
Livestock veterinary channels is repositioning the commercial gravity of fascioliasis therapeutics away from purely human hospital procurement. Novartis leverages its tropical disease portfolio to sustain access programs in endemic zones. Cipla Inc. anchors its position through cost-optimized manufacturing of benzimidazole derivatives. Zoetis Inc. dominates the veterinary segment with specialized flukicide formulations for cattle and sheep operations.
Fascioliasis treatment encompasses chemotherapeutic agents targeting Fasciola hepatica and Fasciola gigantica trematode infections, primarily comprising benzimidazole compounds such as triclabendazole that disrupt parasite microtubule function and tegument integrity. These formulations serve both human clinical settings for hepatic fascioliasis and veterinary applications for liver fluke control in ruminant populations. Triclabendazole retains the largest therapeutic share despite emerging resistance patterns, while nitazoxanide gains traction as an alternative in mixed parasitic infections. The oral delivery mode leads in human applications, whereas injectable formulations command premium positioning in veterinary settings where compliance and efficacy duration determine procurement decisions.
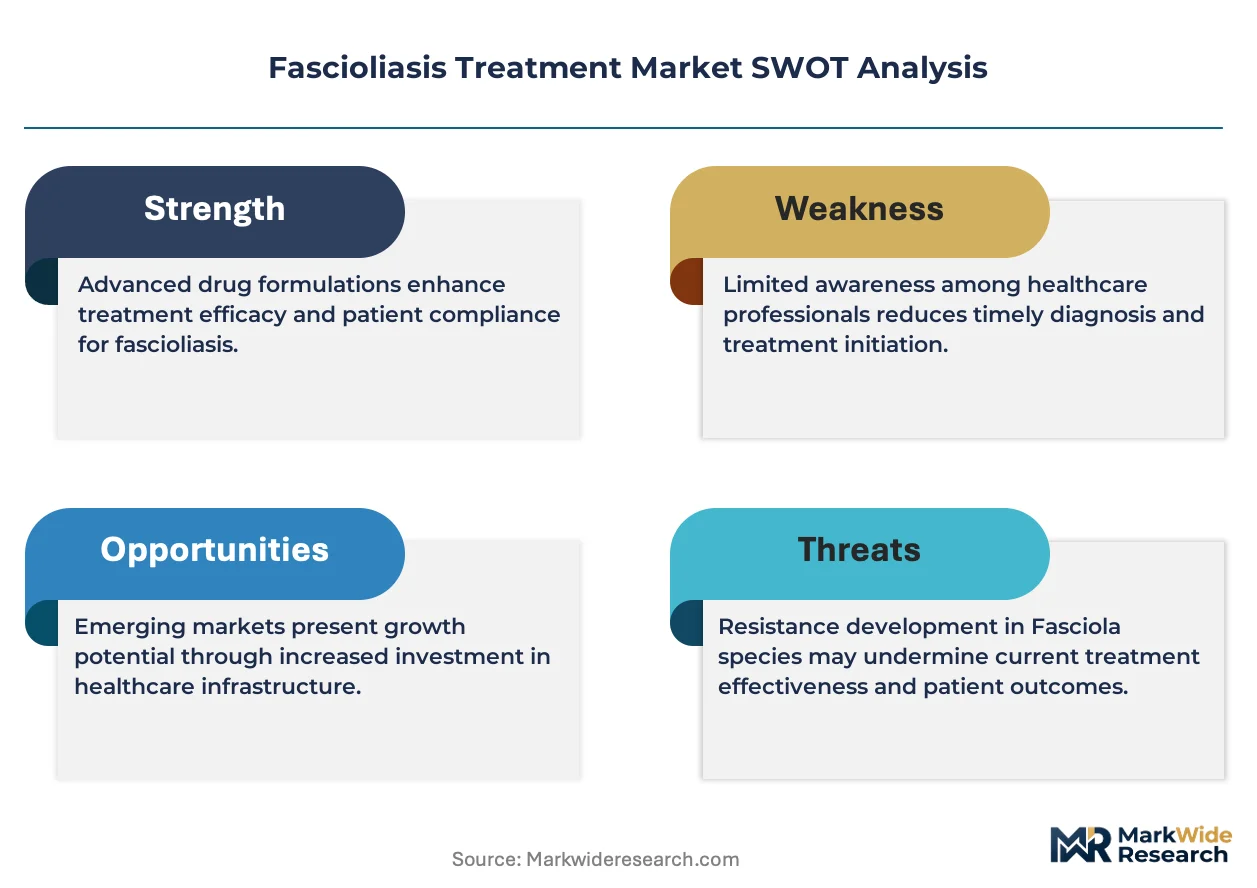
The WHO, FDA, and EMA collectively shape product standards through prequalification pathways, bioequivalence requirements, and veterinary residue limits that determine market access for generic and innovator manufacturers alike. National regulators in endemic countries reference these frameworks to authorize emergency stockpiles and mass drug administration campaigns. Stakeholders must monitor triclabendazole resistance surveillance data and alternative compound pipelines to anticipate shifts in formulary design and procurement specifications.
Market Dynamics
Triclabendazole resistance surveillance networks are forcing anthelmintic manufacturers to diversify active ingredient portfolios while veterinary procurement consolidates around efficacy-guaranteed suppliers. This structural pressure is compressing margins for single-compound producers and accelerating biological alternative development timelines.
Growth Catalysts
- WHO NTD Listing:Bolivia, Peru, and Vietnam have expanded national deworming program budgets following fascioliasis inclusion on the neglected tropical diseases register. Mass drug administration campaigns now reach highland corridors previously excluded from systematic treatment.
- Veterinary Cold-Chain Gaps:Limited refrigeration infrastructure across Andean smallholder regions sustains demand for thermostable benzimidazole formulations over biological alternatives requiring controlled storage.
- Triclabendazole Resistance Monitoring:Standardized surveillance protocols in livestock-dense regions generate recurring diagnostic and therapeutic procurement cycles from veterinary clinics.
Market Restraints
- API Supply Concentration:Benzimidazole active pharmaceutical ingredient production clusters in specific Asian manufacturing zones, exposing formulators to geopolitical disruption and customs processing delays.
- EMA Veterinary Residue Limits:Stringent maximum residue level enforcement for triclabendazole metabolites in milk and meat extends withdrawal periods, reducing treatment compliance among cost-sensitive smallholders.
- Nitazoxanide Substitution:This broad-spectrum antiparasitic is capturing mixed-infection cases where clinicians suspect concurrent protozoal burden, fragmenting the flukicide-dedicated market.
Strategic Opportunities
- Vietnam Highland Expansion:Northern provinces bordering Laos show rising fascioliasis incidence among water buffalo herds with minimal veterinary service penetration, creating first-mover positioning for mobile clinic networks.
- Combination Formulation Development:Fixed-dose pairing of triclabendazole with closantel addresses emerging resistance while simplifying dosing protocols for para-veterinary workers.
- Emergency Stockpile Mandates:National regulators in endemic Andean countries are authorizing strategic anthelmintic reserves for outbreak response, generating non-cyclical procurement volumes.
Industry Challenges
- Parasitology Diagnostic Skill Gap:Accurate fascioliasis identification requires copromicroscopy expertise that is scarce in remote veterinary posts, leading to empirical treatment and resistance acceleration.
- Multispecies Formulation Complexity:Dosing differentiation between cattle, sheep, and human patients fragments production runs and complicates inventory management for generic manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fascioliasis Treatment Market |
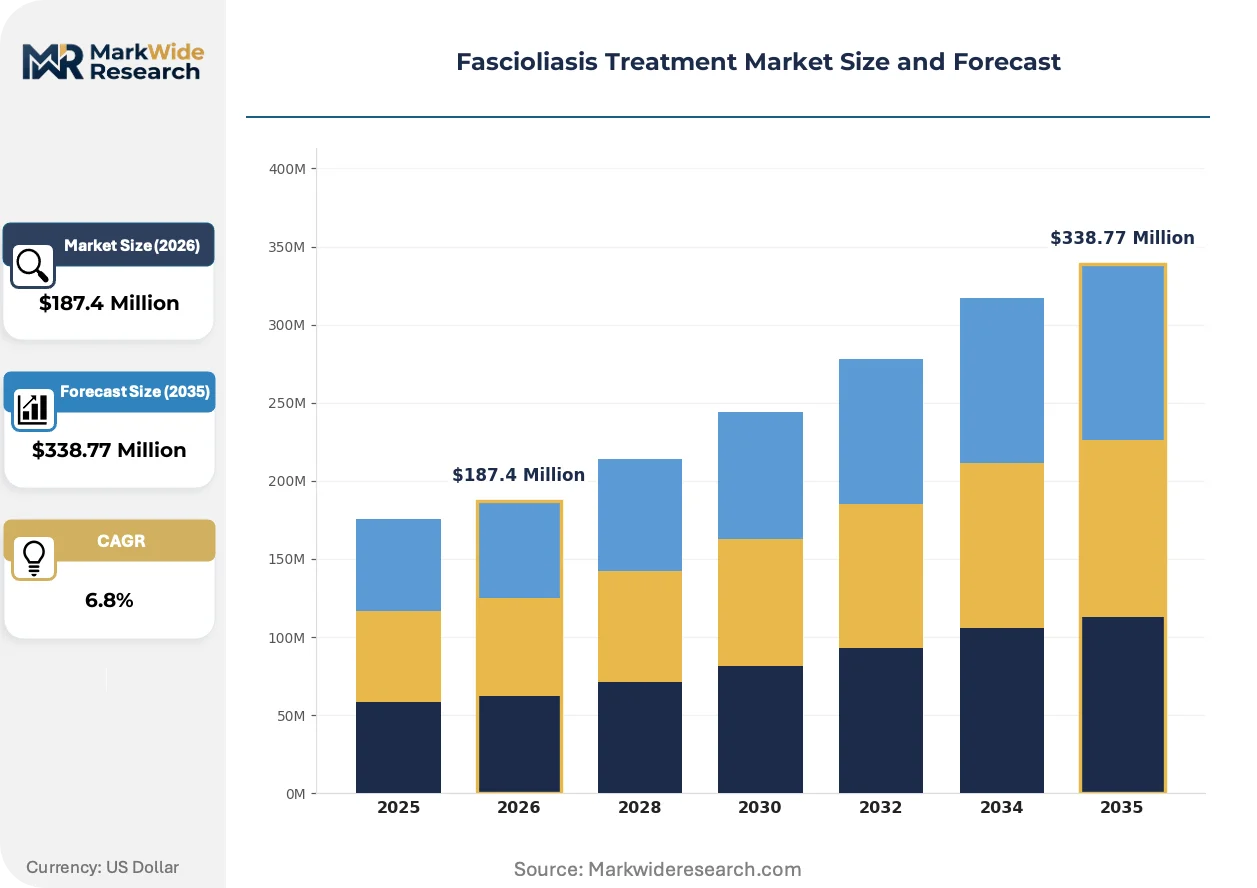
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Praziquantel, Triclabendazole, Nitazoxanide, Others Delivery Mode: Oral, Injectable, Topical, Others End User: Hospitals, Clinics, Home Care, Pharmacies Therapy Area: Parasitic Infections, Gastrointestinal Disorders, Veterinary Care, Others |
| Companies Covered | Novartis, Cipla Inc., Sun Pharmaceutical Industries Limited, Zoetis Inc., Merck, Bayer, Emcure Pharmaceuticals Limited, Johnson & Johnson Private Limited, Romark Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fascioliasis Treatment Market Emerging Trajectories
Anthelmintic development is pivoting from single-compound dominance toward resistance-management architectures that integrate diagnostics, combination therapies, and biological alternatives into coordinated intervention packages.
Controlled-release injectable formulations are modularizing treatment protocols for commercial cattle operations. Large-scale ranches in Brazil and Australia have adopted these depot systems to reduce mustering frequency and labor costs. The technology is compressing the competitive window for oral benzimidazole producers in intensive livestock sectors.
EMA revised veterinary medicine regulations now mandate environmental risk assessments for antiparasitic metabolites in aquatic ecosystems. This framework is extending development timelines for new flukicides and favoring manufacturers with existing ecotoxicology datasets. European formulators are responding by prioritizing biodegradability in candidate selection pipelines.
Smallholder dairy cooperatives are consolidating anthelmintic purchasing through regional veterinary associations. These intermediaries negotiate volume discounts and quality verification that individual farmers cannot secure. The pattern is most pronounced in Peruvian Andean communities where collective procurement now accounts for a substantial share of triclabendazole distribution.
Fascioliasis Treatment Market Segmentation
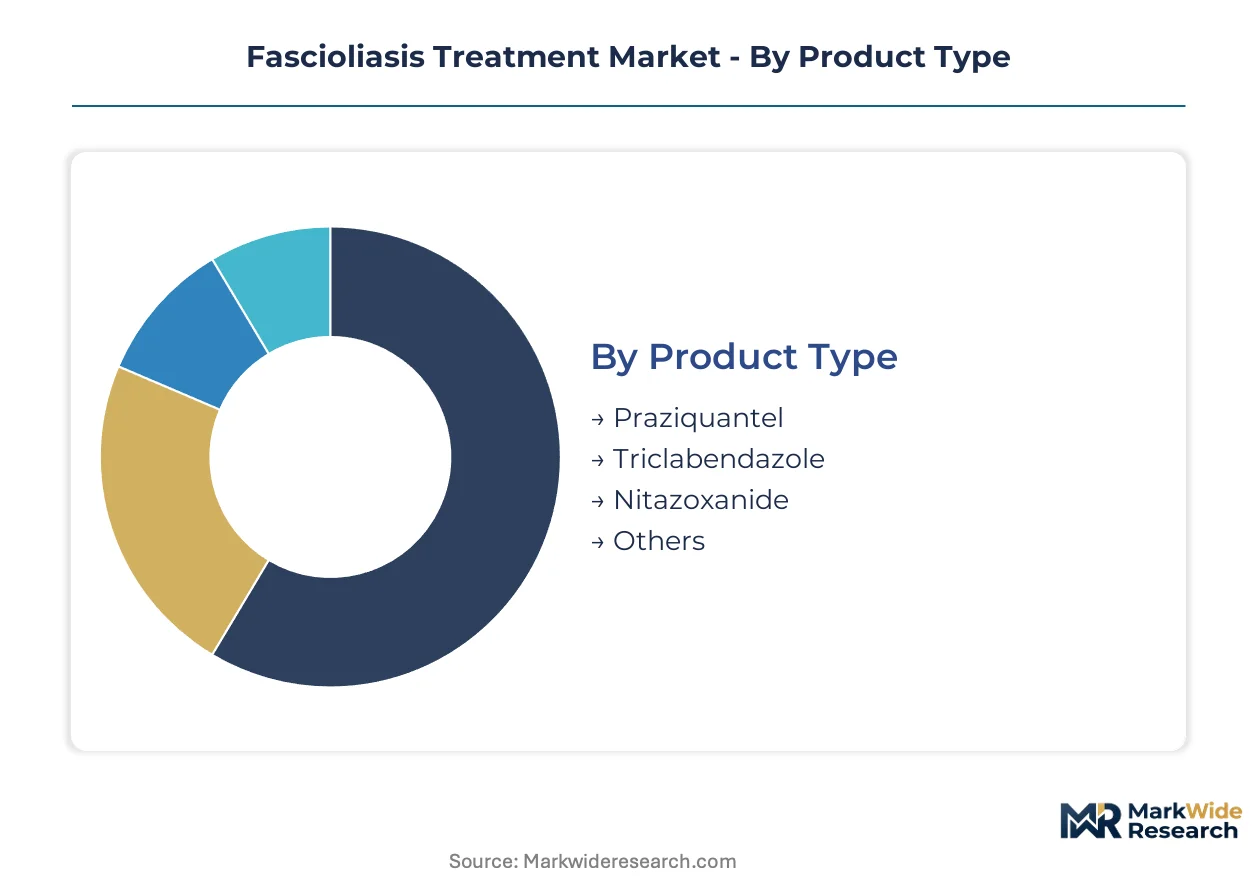
Anthelmintic procurement specifications diverge sharply between human clinical and veterinary channels, with regulatory pathways determining which formulations achieve formulary inclusion. Understanding segment boundaries clarifies where manufacturers must invest in bioequivalence studies versus residue monitoring infrastructure.
Product Type:
WHO prequalification status and national essential medicines listings create tiered access for active pharmaceutical ingredients across endemic markets.
- Triclabendazole:Benzimidazole compound disrupting parasite microtubule function and tegument integrity. Demand concentrates in Andean highland corridors where smallholder dairy farming intersects with triclabendazole resistance monitoring requirements.
- Praziquantel:Pyrazinoisoquinoline derivative primarily targeting cestode and trematode infections beyond fascioliasis. Veterinary clinics in livestock-dense regions procure this alternative where mixed helminth burdens complicate empirical treatment selection.
- Nitazoxanide:Broad-spectrum antiparasitic capturing mixed-infection cases with suspected concurrent protozoal burden.
- Others:Closantel and albendazole formulations addressing emerging resistance patterns in specific geographies.
Leading the category by volume: Triclabendazole. Growing fastest: Nitazoxanide.
Delivery Mode:
Cold-chain infrastructure gaps and labor economics determine which formulations penetrate smallholder versus commercial operations.
- Oral:Tablet and suspension formulations dominating human applications and smallholder veterinary use. Thermostable benzimidazole tablets sustain demand across Andean regions lacking refrigeration infrastructure for biological alternatives.
- Injectable:Depot formulations commanding premium positioning in commercial cattle operations. Large-scale ranches in Brazil have adopted controlled-release systems to reduce mustering frequency and labor costs.
- Topical:Pour-on formulations serving sheep operations where handling stress reduction outweighs unit cost premiums.
- Others:Intraruminal bolus technologies for extended-release applications in extensive grazing systems.
Dominant by procurement value: Injectable. Expanding most quickly: Oral generics through mass drug administration channels.
End User:
Procurement consolidation patterns and reimbursement pathways fragment demand across institutional and retail channels.
- Hospitals:Tertiary referral centers managing complicated hepatic fascioliasis cases requiring imaging-guided intervention. Urban hospital networks in Bolivia anchor human therapeutic demand through national deworming program referrals.
- Clinics:Primary health posts and veterinary clinics serving as distribution nodes for mass drug administration campaigns. Peruvian Andean communities route collective procurement through regional veterinary associations securing volume discounts.
- Home Care:Self-administered oral regimens for confirmed cases with mild hepatic involvement.
- Pharmacies:Retail dispensing for private-pay veterinary clients and human patients outside public program coverage.
Highest transaction volume: Clinics. Steepest expansion trajectory: Pharmacies serving emerging private veterinary markets.
Therapy Area:
Diagnostic capability availability determines whether fascioliasis receives targeted flukicide therapy or broad-spectrum empirical treatment.
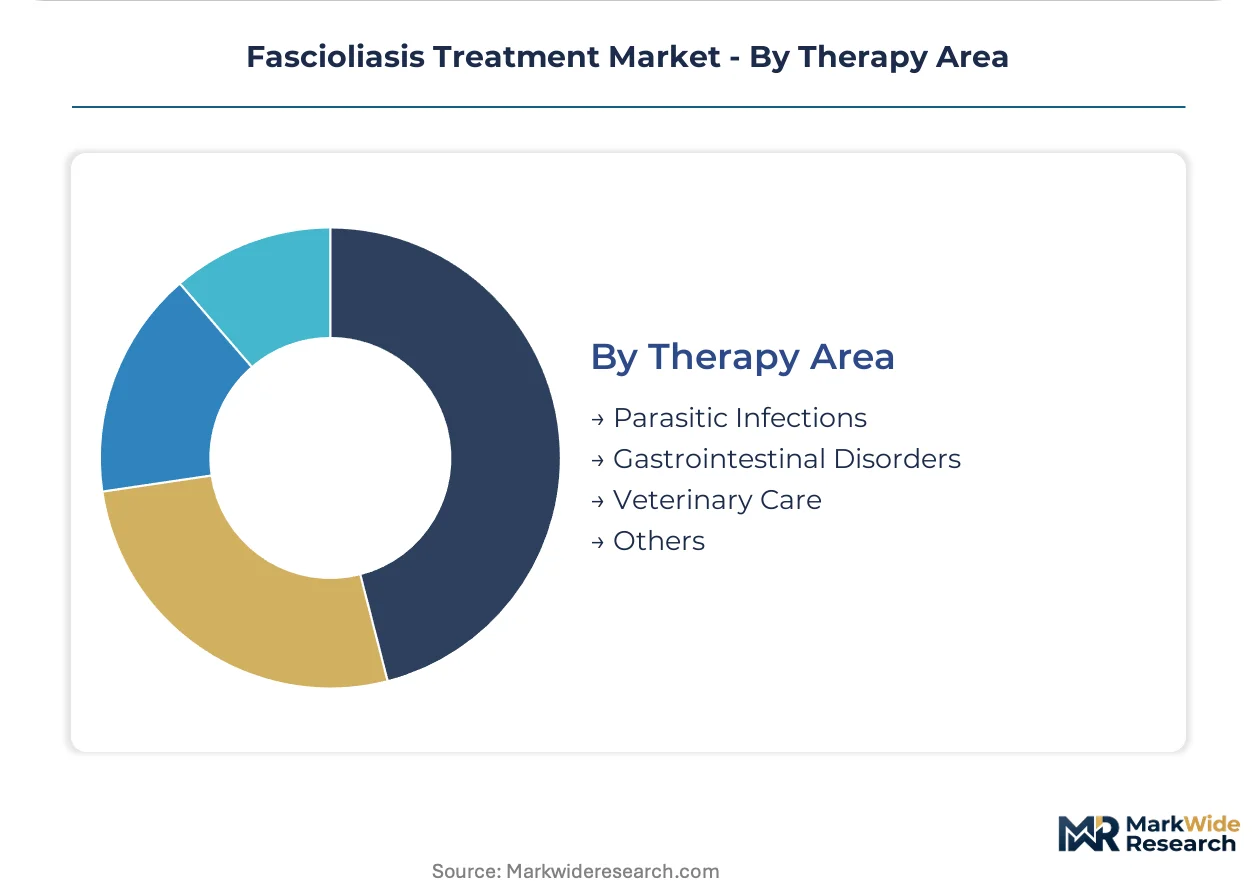
- Parasitic Infections:Dedicated anthelmintic protocols for confirmed Fasciola hepatica and Fasciola gigantica infections. Copromicroscopy expertise scarcity in remote veterinary posts drives empirical treatment patterns accelerating resistance development.
- Veterinary Care:Liver fluke control integrated into ruminant herd health programs. EMA veterinary residue limits for triclabendazole metabolites extend milk and meat withdrawal periods, reducing compliance among cost-sensitive smallholders.
- Gastrointestinal Disorders:Differential diagnosis pathways where abdominal imaging reveals hepatic lesions of uncertain etiology.
- Others:Research applications and exotic animal medicine representing niche procurement volumes.
Largest absolute demand: Parasitic Infections. Gaining share fastest: Veterinary Care through cooperative purchasing consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API synthesis clusters in Asian manufacturing zones while consumption concentrates in Andean highlands and Southeast Asian livestock corridors. This geographic mismatch shapes procurement patterns and regulatory compliance burdens.
Bolivia
Smallholder dairy cooperatives in the Altiplano region drive bulk triclabendazole procurement through collective purchasing agreements. The national neglected tropical disease program channels WHO funding into mass drug administration campaigns reaching previously excluded highland corridors. Veterinary clinics in La Paz and Cochabamba anchor distribution networks for thermostable benzimidazole formulations.
Peru
Regional veterinary associations in the central Andes consolidate anthelmintic demand from dispersed dairy communities. The country's health ministry references WHO prequalification pathways to authorize emergency stockpiles for outbreak response. Cusco and Puno provinces exhibit concentrated procurement through cooperative purchasing structures.
Vietnam
Northern provinces bordering Laos report rising fascioliasis incidence among water buffalo herds with minimal veterinary service penetration. The national pharmaceutical regulator aligns bioequivalence requirements with WHO standards to accelerate generic authorization. Mobile clinic networks in Lào Cai and Sơn La provinces create first-mover positioning opportunities.
Brazil
Large-scale cattle ranches in Mato Grosso and Goiás have adopted controlled-release injectable formulations to reduce mustering frequency. ANVISA mandates environmental risk assessments for antiparasitic metabolites in aquatic ecosystems. São Paulo-based distributors command premium positioning in the commercial livestock segment.
Switzerland
Swissmedic enforces stringent veterinary residue limits for triclabendazole metabolites in milk and meat exports. Basel anchors European headquarters for tropical disease access programs targeting endemic zones. The regulatory framework extends withdrawal periods, influencing formulation development priorities for suppliers serving European markets.
Fascioliasis Treatment Market Vendor Landscape
Top-tier vendors anchor the branded pharmaceutical segment, while generic manufacturers compete on cost-optimized benzimidazole production. The market exhibits tiered concentration with innovator portfolios facing pressure from regional formulators. Strategic archetypes include tropical disease access program operators, veterinary flukicide specialists, and broad-spectrum antiparasitic developers. Portfolio diversification into combination formulations and geographic expansion through mobile clinic partnerships represent dominant competitive vectors.
Within the innovator tier, Novartis occupies a position exemplifying tropical disease portfolio sustainability through endemic zone access programs. Among veterinary-focused specialists, Zoetis Inc. anchors the livestock flukicide segment with dedicated ruminant formulations. Cipla Inc. represents the cost-optimized generic archetype, manufacturing benzimidazole derivatives for price-sensitive procurement channels. These three entities collectively illustrate the competitive spectrum spanning branded access programs, veterinary specialization, and generic volume production.
| Leading Market Players |
|---|
| Novartis |
| Cipla Inc. |
| Sun Pharmaceutical Industries Limited |
| Zoetis Inc. |
| Merck |
| Bayer |
| Emcure Pharmaceuticals Limited |
| Johnson & Johnson Private Limited |
| Romark Laboratories |
| Others |
Supply Flow & Price Mechanics
Active pharmaceutical ingredient spot prices for benzimidazole compounds cascade through formulator margins into three-tier pricing structures separating innovator access programs from regional generic suppliers and economy-tier veterinary distributors across Andean procurement corridors.
Pricing Analysis
Margin tightening in veterinary injectable tiers reflects EMA residue limit compliance costs and extended withdrawal period guarantees demanded by European export-oriented producers. Pricing stratifies across premium depot formulations, standard oral benzimidazole tablets, and economy bulk powder for cooperative purchasing. Cost-down pressure on human tablet segments accelerates because WHO prequalification pathways compress generic authorization timelines in Bolivia and Peru. Smallholder dairy cooperatives exhibit highest price sensitivity, while commercial cattle operations in Brazil absorb premium positioning for labor-saving controlled-release systems.
Supply Chain Analysis
Dual-sourcing mandates from ANVISA and Swissmedic force formulators to qualify API suppliers across India, China, and domestic European synthesis facilities simultaneously. Benzimidazole active ingredients draw from concentrated Asian manufacturing zones, while triclabendazole precursor chemicals hinge on specialized intermediate producers. Single-source vulnerability in high-purity API grades exposes veterinary formulators to customs processing delays. Distribution runs through São Paulo-based distributors for South American commercial livestock segments and La Paz regional veterinary associations for Andean smallholder consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance narrative where EMA veterinary residue limits and WHO prequalification pathways erect regulatory moats favoring manufacturers with existing ecotoxicology datasets and bioequivalence infrastructure.
For Market Incumbents: Anticipate nitazoxanide substitution acceleration in mixed-infection diagnostic pathways by securing combination formulation pipelines pairing triclabendazole with closantel. Anchor backward integration into benzimidazole API synthesis to defend margin position against Indian and Chinese generic cost structures. Prioritize mobile clinic network partnerships in Vietnam's northern highlands before first-mover windows close. For New Entrants and Emerging Players: Begin with veterinary diagnostic service bundling in Peruvian Andean communities where copromicroscopy skill scarcity creates adjacent revenue attachment to anthelmintic distribution. Target water buffalo operations in Lào Cai and Sơn La provinces where veterinary service penetration remains minimal and cooperative purchasing structures have not yet consolidated. Deploy para-veterinary training programs as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap veterinary formulators with existing WHO prequalification status and Andean distribution licenses in Bolivia and Peru. Long-term viability rests on resistance-management architecture positioning rather than single-compound dominance. Monitor triclabendazole resistance surveillance network expansion as the inflection signal for combination therapy portfolio premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Combination Formulation Development | Fixed-dose triclabendazole-closantel pairing addresses emerging resistance while simplifying para-veterinary dosing protocols. |
| Mobile Clinic Network Expansion | Vietnam's northern highland provinces offer first-mover positioning where water buffalo fascioliasis incidence rises without veterinary service penetration. |
| API Backward Integration | In-house benzimidazole synthesis reduces exposure to Indian and Chinese manufacturing zone geopolitical disruption. |
| EMA Ecotoxicology Dataset Investment | Existing environmental risk assessment infrastructure accelerates flukicide development timelines under revised veterinary medicine regulations. |
| Cooperative Purchasing Partnership | Peruvian Andean dairy association consolidation creates volume-committed distribution channels inaccessible to individual farmer sales. |
Methodological Framework
WHO epidemiological surveillance reports, national veterinary service procurement databases, and EMA veterinary medicine registration filings formed the secondary backbone for this analysis. Primary interviews with veterinary pharmaceutical regulatory affairs leads, Andean cooperative purchasing managers, and parasitology diagnostic laboratory directors combined with secondary validation across Bolivia, Peru, and Vietnam. FDA and EMA submission records for triclabendazole formulations anchored supply-side characterization. Bottom-up procurement volume estimates from regional veterinary associations triangulated against top-down national deworming program budget allocations.
Historical trendline analysis across benzimidazole API pricing indices and veterinary anthelmintic procurement cycles established baseline trajectory parameters. The analytical framework modeled segmentation dimensions spanning product type, delivery mode, end user category, and therapy area across the projection horizon. CAGRs derived from regression analysis of procurement volume trends and resistance surveillance network expansion rates. Forecast inputs incorporated WHO neglected tropical disease program funding trajectories and EMA environmental risk assessment regulatory phase-in schedules.
Underlying measurement precision varies by segment; hospital and clinic procurement channels carry tighter precision than dispersed smallholder veterinary transactions. Forecasts reflect documented assumptions regarding triclabendazole resistance progression rates and national deworming program budget continuity. Deviation in EMA veterinary residue limit enforcement stringency or WHO prequalification pathway acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Post-Traumatic Stress Disorder Treatment Market
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
Idiopathic Short Stature Market
Specialty Medicine
Thoracic Outlet Syndrome Market
Specialty Medicine
Severe Hypertriglyceridemia (SHTG) Treatment Market
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
Global Vasculitis Treatment Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Transthyretin (TTR) Amyloidosis Market
Specialty Medicine
US Mobile Physician Practice Market
Specialty Medicine
Bipolar Disorder (BPD) Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Fibroadenoma Market