
 Cerebral Vein Thrombosis Treatment Market | 2026-2036
Cerebral Vein Thrombosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
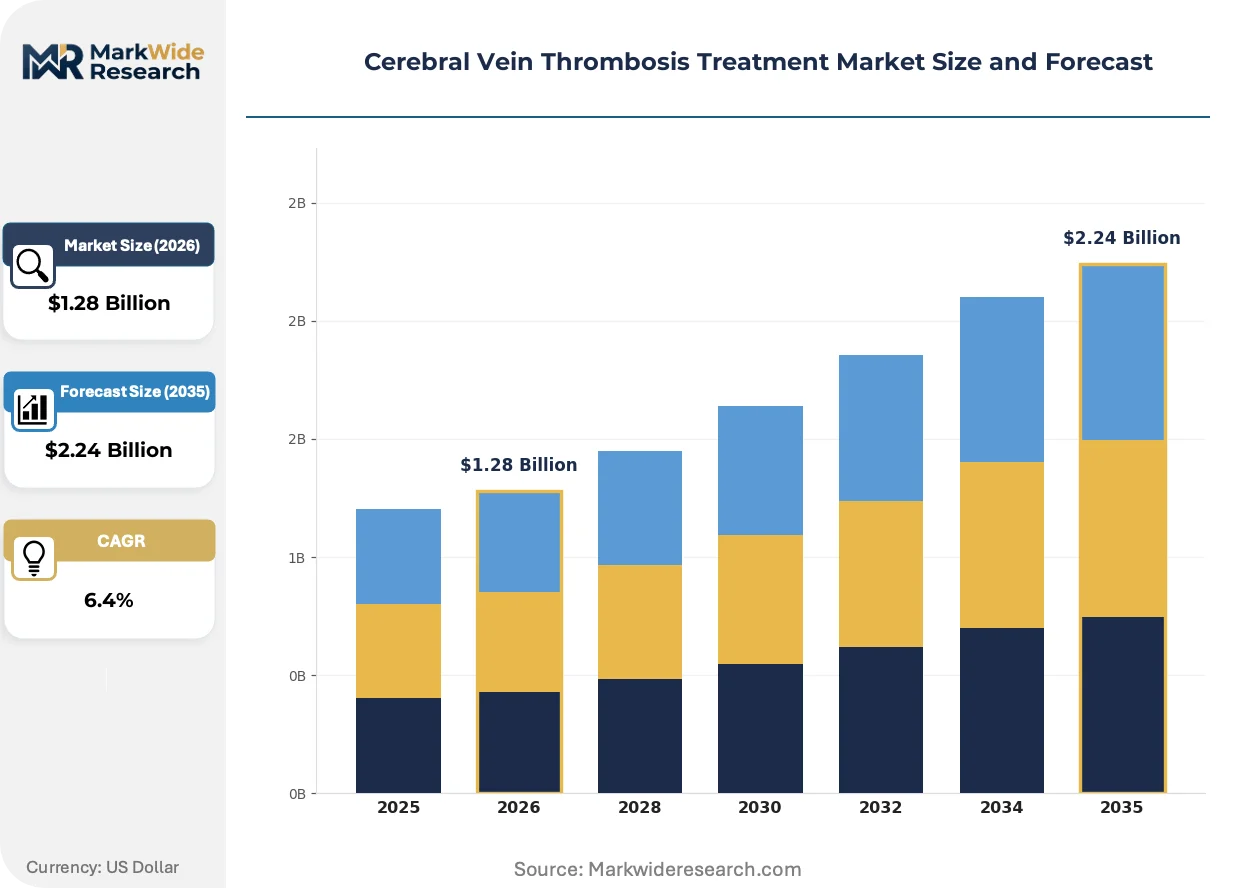
Cerebral Vein Thrombosis Treatment Market Outlook
EU MDR compliance deadlines for neurovascular device classes is hardening quality-system requirements across the supply base. Boston Scientific Corporation leverages its interventional neurology portfolio to sustain catheter-based thrombectomy leadership in European tertiary centers. Pfizer anchors anticoagulant R&D through targeted kinase inhibitor programs, while Daiichi Sankyo competes on oral factor Xa differentiation in Asian and European hospital formularies.
Cerebral vein thrombosis treatment encompasses pharmacological, interventional, and supportive modalities directed at restoring venous outflow and preventing hemorrhagic transformation in dural venous sinus occlusion. Thrombolytic administration requires precise dosing calibrated to patient weight and clot burden, with endovascular mechanical thrombectomy reserved for cases exhibiting clinical deterioration despite maximal medical therapy. Anticoagulants occupy the largest revenue pool among product types due to front-line guideline endorsement and extended outpatient dosing requirements. Hospitals dominate end-user demand through 24-hour neurocritical care capacity and on-site interventional neuroradiology staffing, while home care segments gain traction for stable patients transitioning to oral anticoagulant maintenance.
FDA neurology device premarket pathways, EMA MDR technical documentation requirements, and WHO essential medicines list inclusion criteria collectively determine market access velocity and reimbursement tiers for new cerebral vein thrombosis therapies. FDA breakthrough device designation for thrombectomy platforms compresses trial timelines, whereas EMA notified body capacity constraints extend conformity assessment durations for European market entry. Stakeholders must monitor evolving anticoagulant reversal agent availability and health technology assessment body positioning for novel oral agents across major hospital purchasing consortia.
Market Dynamics
Mechanical thrombectomy is absorbing clinical decision-making from systemic thrombolysis as neurovascular centers consolidate interventional capabilities around 24-hour neuroradiology staffing models.
Growth Catalysts
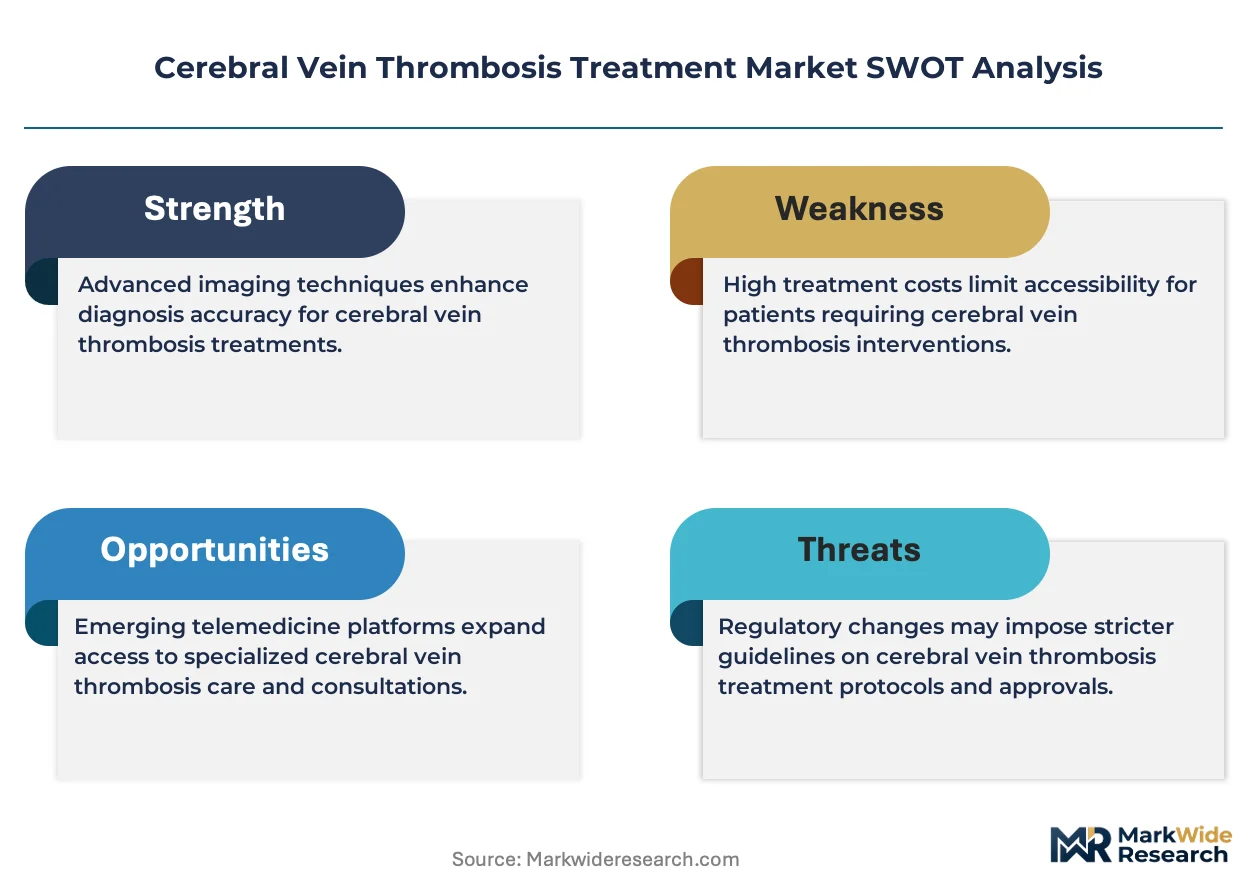
- FDA breakthrough device designation:Compressed trial timelines for thrombectomy platforms accelerate commercialization pathways in US tertiary centers.
- Extended oral anticoagulant dosing:Front-line guideline endorsement creates sustained outpatient pharmacy demand across hospital formularies.
- German neurovascular center clustering:University hospitals in Berlin, Munich, and Heidelberg concentrate specialized referral networks and interventional volume.
Market Restraints
- Heparin price volatility:Unfractionated heparin supply concentration in Asian API manufacturers creates input cost instability for compounding pharmacies.
- EMA notified body capacity constraints:Extended conformity assessment durations delay European market entry for novel device classes.
- Conservative clinical thresholds:Stringent patient selection criteria for endovascular intervention limit addressable case volumes in community hospitals.
Strategic Opportunities
- Home care transition protocols:Stable patients moving to oral anticoagulant maintenance create new reimbursement channels outside hospital walls.
- EU MDR technical documentation harmonization:Streamlined quality-system requirements reduce regulatory friction for multi-country device launches.
- Artificial intelligence imaging integration:Automated clot burden quantification converges with interventional planning software in neuroradiology workflows.
Industry Challenges
- Interventional neuroradiologist scarcity:Fellowship-trained specialists remain concentrated in academic medical centers, constraining 24-hour thrombectomy coverage.
- Anticoagulant reversal agent availability gaps:Andexanet alfa and idarucizumab stocking requirements strain hospital pharmacy budgets and cold-chain logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cerebral Vein Thrombosis Treatment Market |
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticoagulants, Thrombolytics, Surgical Treatments, Supportive Care End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Administration Route: Intravenous, Oral, Subcutaneous, Transfusions Management Strategy: Preventive Care, Acute Treatment, Long-term Management, Patient Education |
| Companies Covered | Boston Scientific Corporation, AngioDynamics, Cardinal Health, Johnson & Johnson Services, Inc., Pfizer, Bristol-Myers Squibb, C. H. Boehringer Sohn, Daiichi Sankyo, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cerebral Vein Thrombosis Treatment Market Strategic Shifts
Digital health infrastructure is reshaping how cerebral vein thrombosis cases are triaged, diagnosed, and routed to intervention, compressing door-to-needle timelines across networked neurovascular centers.
Stent retriever technology is absorbing market preference from aspiration-only systems as randomized trial data solidifies superior recanalization rates in dense clot burdens. Academic medical centers in Germany and the United States are standardizing combined aspiration-stent retriever protocols. Device manufacturers are absorbing R&D investment toward integrated delivery platforms that collapse procedure steps.
EMA MDR implementation is forcing neurovascular device manufacturers to rebuild technical documentation for legacy product lines. Notified body backlogs extend conformity assessment timelines by 12-18 months for Class III implantable devices. European hospital purchasing consortia are responding by consolidating supplier relationships with established MDR-compliant portfolios.
Centralized stroke center certification is concentrating patient volume in designated comprehensive centers with interventional neuroradiology coverage. Community hospitals without 24-hour neuroradiology are transferring acute cases via telestroke networks rather than maintaining standalone capabilities. This geographic consolidation is most visible in US metropolitan areas where certificate-of-need regulations shape center designation.
Cerebral Vein Thrombosis Treatment Market Segmentation
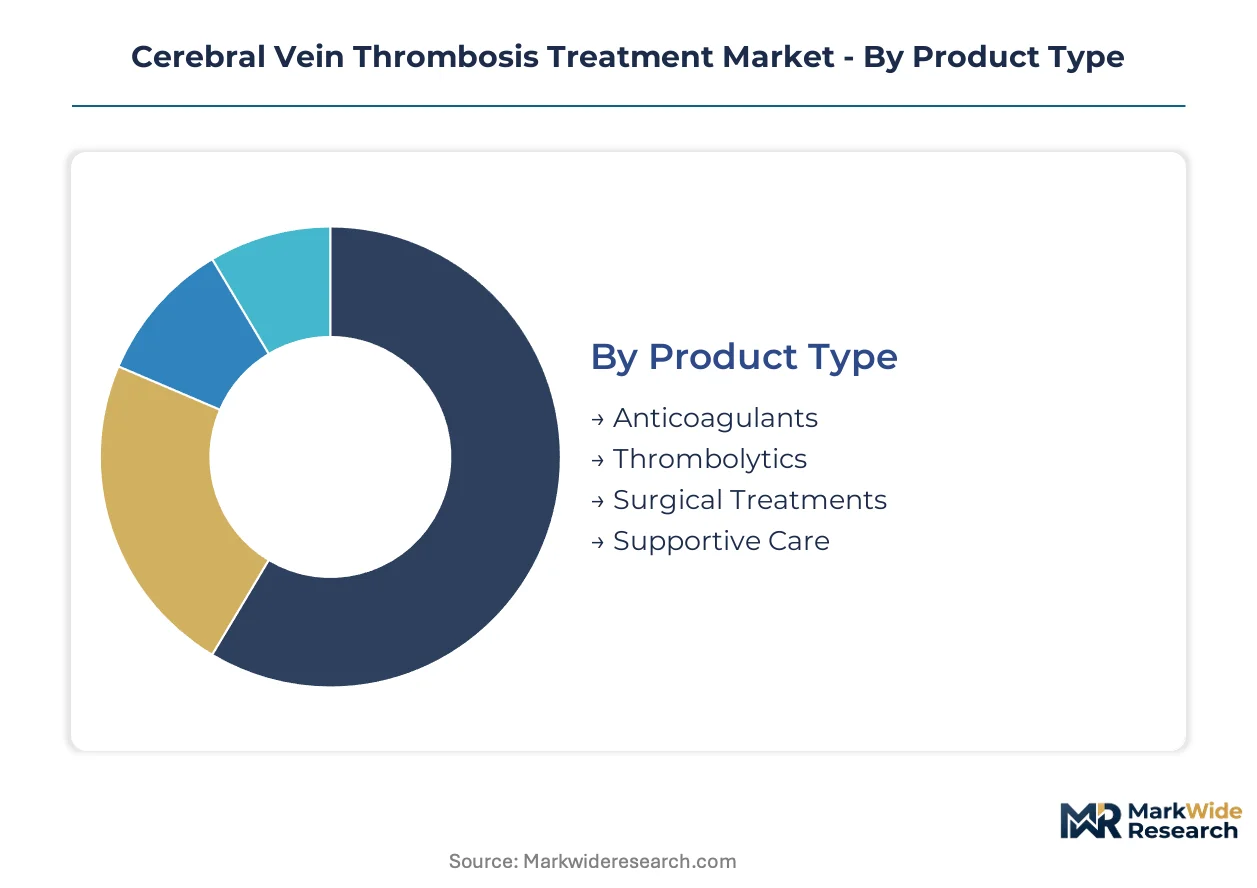
Treatment modality selection in cerebral vein thrombosis hinges on clot acuity, hemorrhage risk, and institutional interventional capability. Segmentation reveals where pharmacological front-line therapy yields to mechanical intervention, and which care settings capture patient transitions across the disease trajectory.
Product Type:
Anticoagulants command the revenue premium through extended outpatient dosing, while thrombolytics and surgical interventions concentrate in high-acuity tertiary centers with 24-hour neuroradiology coverage.
- Anticoagulants:Oral factor Xa inhibitors and vitamin K antagonists form the pharmacological backbone of CVT management. Front-line guideline endorsement from the American Heart Association and European Stroke Organization sustains demand across hospital formularies in Germany, France, and the United States, with outpatient maintenance driving recurring pharmacy revenue.
- Thrombolytics:Systemic tissue plasminogen activator and catheter-directed thrombolysis target patients with deteriorating neurological status despite anticoagulation. Administration concentrates in comprehensive stroke centers in Berlin, Munich, and Heidelberg, where interventional neuroradiology teams manage hemorrhagic transformation risk through intensive care protocols.
- Surgical Treatments:Decompressive craniectomy and direct venous sinus thrombectomy address malignant cerebral edema refractory to medical therapy. Case volume clusters in university hospitals with neurosurgical residency programs.
- Supportive Care:Intracranial pressure monitoring, antiepileptic prophylaxis, and fluid management stabilize patients pending definitive therapy. Demand scales with neurocritical care bed expansion.
Today's leader: Anticoagulants. Tomorrow's challenger: Thrombolytics.
End User:
Hospital infrastructure determines intervention access, while cost pressures and oral anticoagulant stability shift post-acute monitoring toward lower-acuity settings.
- Hospitals:Tertiary centers with interventional neuroradiology staffing capture thrombectomy-eligible cases through 24-hour coverage models. FDA breakthrough device designation for mechanical thrombectomy platforms accelerates adoption in US academic medical centers, while EMA MDR compliance requirements filter supplier relationships toward established device manufacturers.
- Home Care:Stable patients transitioning to oral anticoagulant maintenance create reimbursement channels outside institutional walls. Remote INR monitoring and direct-to-patient pharmacy dispensing expand in Germany and the Netherlands, where integrated care contracts reward reduced readmission rates.
- Clinics:Outpatient neurology practices manage stable CVT follow-up and anticoagulant titration. Volume concentrates in urban areas with stroke specialist density.
- Rehabilitation Centers:Post-thrombectomy recovery and cognitive rehabilitation address residual deficits. Demand correlates with stroke network centralization.
Volume concentrates in hospitals. Margin expansion tracks home care.
Administration Route:
Route selection follows disease phase: intravenous dominates acute stabilization, oral captures chronic maintenance, and subcutaneous bridges peri-procedural transitions.
- Intravenous:Unfractionated heparin infusion enables rapid reversal in acute CVT with hemorrhagic transformation risk. Supply concentration in Asian API manufacturers creates input cost volatility for compounding pharmacies serving European and North American hospitals.
- Oral:Direct oral anticoagulants displace warfarin in stable outpatient maintenance. Formulary positioning hinges on health technology assessment outcomes in Germany's G-BA and England's NICE.
- Subcutaneous:Low-molecular-weight heparin facilitates bridging therapy and pregnancy-associated CVT management. Administration concentrates in anticoagulation clinic protocols.
- Transfusions:Fresh frozen plasma and platelet support address coagulopathy in complex cases. Utilization scales with neurosurgical intervention volume.
Acute dependence: Intravenous. Chronic conversion: Oral.
Management Strategy:
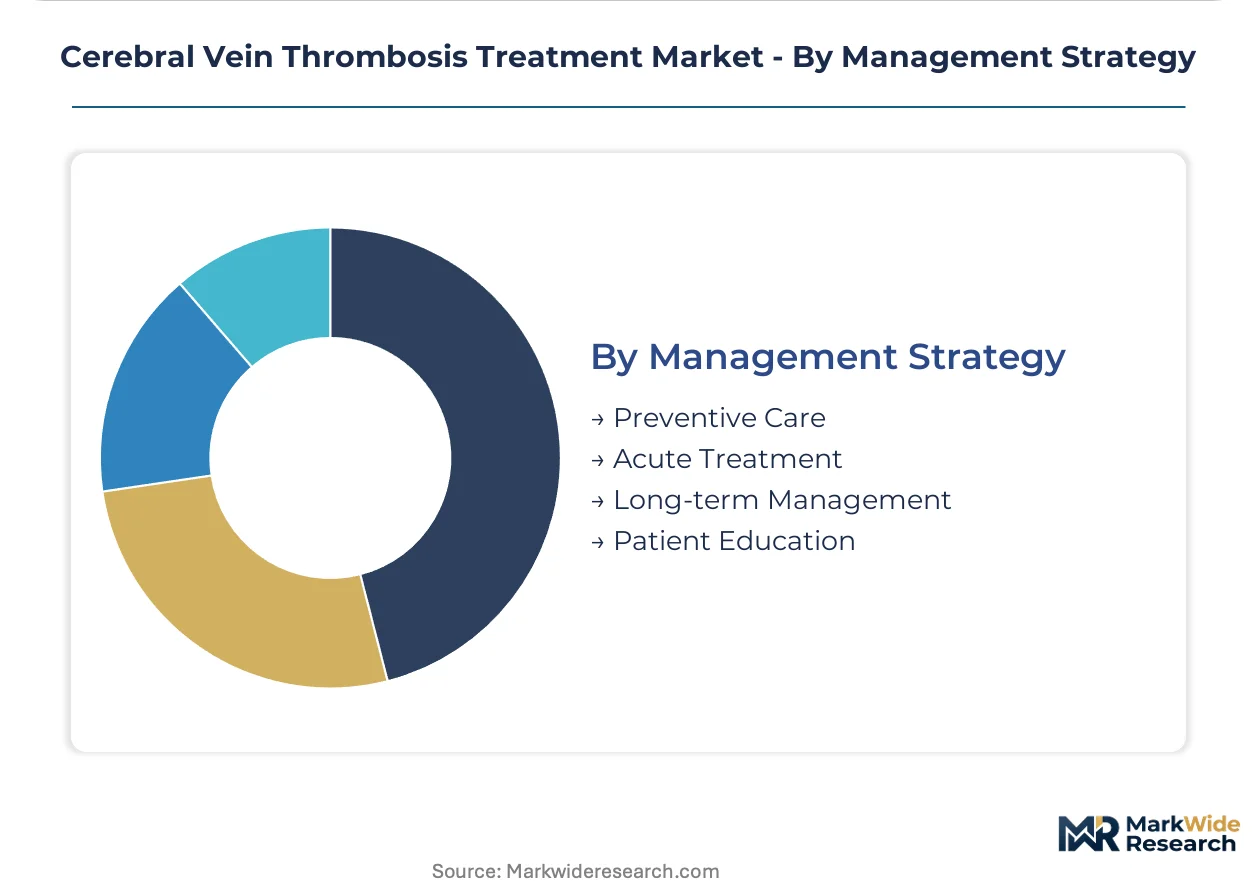
Strategy allocation reflects disease natural history: acute intervention stabilizes, long-term management prevents recurrence, and patient education drives adherence.
- Acute Treatment:Anticoagulation initiation and thrombectomy decision-making compress door-to-needle timelines. Telestroke networks in the United States and Germany route patients toward comprehensive centers with interventional capability.
- Long-term Management:Extended anticoagulation duration, typically 3-12 months, prevents recurrent venous thromboembolism. Duration determination integrates thrombophilia testing and provoked versus unprovoked event classification.
- Preventive Care:Prophylactic anticoagulation in high-risk contexts—postpartum, oral contraceptive use, malignancy—targets modifiable risk factors. Screening protocols concentrate in obstetric and oncology practices.
- Patient Education:Adherence counseling and lifestyle modification support therapeutic persistence. Digital health platforms in Sweden and Denmark automate medication reminders and symptom reporting.
Revenue concentration: Acute Treatment. Steepest expansion trajectory: Long-term Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interventional neuroradiology fellowship programs concentrate in German university hospitals, anchoring European thrombectomy capacity. This talent density shapes referral patterns and device procurement decisions across the continent.
United States
Comprehensive stroke center certification concentrates patient volume in designated academic medical centers with 24-hour neuroradiology coverage. FDA breakthrough device designation for mechanical thrombectomy platforms compresses trial timelines and accelerates commercialization in tertiary centers. Boston Scientific Corporation anchors catheter-based thrombectomy supply relationships across major hospital purchasing consortia.
Germany
Specialized neurovascular centers cluster around university hospitals in Berlin, Munich, and Heidelberg, creating dense referral networks for complex CVT cases. EMA MDR compliance deadlines harden quality-system requirements across the neurovascular device supply base. EMA notified body capacity constraints extend conformity assessment durations by 12-18 months for Class III implantable devices.
Japan
PMDA regulatory pathways govern market access for novel anticoagulant therapies, with health technology assessment outcomes determining formulary positioning in hospital purchasing. METI industrial policy supports domestic medical device manufacturing capabilities. Tokyo and Osaka metropolitan areas concentrate interventional neuroradiology staffing and neurocritical care bed capacity.
United Kingdom
NICE health technology assessment criteria determine reimbursement tiers for novel oral anticoagulants across NHS hospital formularies. NHS England stroke network centralization routes acute CVT cases toward comprehensive centers with thrombectomy capability. London and the Southeast concentrate interventional neuroradiology specialists and neurovascular research activity.
France
ANSM regulatory oversight governs neurovascular device market entry, with CE marking requirements filtering supplier relationships toward MDR-compliant portfolios. HAS health technology assessment positioning shapes hospital pharmacy procurement for direct oral anticoagulants. Paris and Lyon academic medical centers anchor national thrombectomy referral networks and clinical trial infrastructure.
Cerebral Vein Thrombosis Treatment Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the cerebral vein thrombosis treatment landscape. The market structure consolidates around interventional device manufacturers with established regulatory dossiers and pharmaceutical companies with extended anticoagulant portfolios. Three archetypes dominate: integrated interventional neurology platforms, targeted kinase inhibitor specialists, and oral factor Xa differentiation players. M&A activity concentrates on thrombectomy platform capabilities, while strategic partnerships bridge device-pharmaceutical combination therapy protocols.
Within the integrated interventional neurology tier, Boston Scientific Corporation and Johnson & Johnson Services, Inc. occupy positions anchored by catheter-based thrombectomy portfolios and European tertiary center relationships. Among oral anticoagulant specialists, Pfizer and Daiichi Sankyo exemplify competing pathways through targeted kinase inhibitor programs and factor Xa differentiation strategies respectively. Cardinal Health represents the distribution and supply chain archetype, bridging manufacturer production with hospital pharmacy and interventional suite logistics.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| AngioDynamics |
| Cardinal Health |
| Johnson & Johnson Services, Inc. |
| Pfizer |
| Bristol-Myers Squibb |
| C. H. Boehringer Sohn |
| Daiichi Sankyo |
| Roche |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up interventional device specialists anchor supply consolidation across European tertiary centers, translating concentrated manufacturing footprints into disciplined pricing power for thrombectomy platforms while compressing margins for unfractionated heparin compounding pharmacies exposed to API volatility.
Pricing Analysis
Bundled procedure-and-device contracts dominate comprehensive stroke center procurement, separating premium integrated thrombectomy platforms from unbundled component sourcing in community hospitals. Price differentiation hinges on FDA breakthrough designation tier and MDR compliance certification, with German university hospitals absorbing premium positioning for 24-hour neuroradiology coverage. Cost compression in standard anticoagulant tiers intensifies because of oral factor Xa generic entry. Home care segments exhibit highest price sensitivity; interventional suite buyers prioritize technical performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from GPO contracts and NHS purchasing consortia mandate multi-supplier qualification for mechanical thrombectomy devices, fragmenting procurement across Boston Scientific and Johnson & Johnson portfolios. Manufacturing concentrates in Ireland, Costa Rica, and Malaysia for catheter-based platforms; API production for heparin feeds from China and India. Single-source vulnerability concentrates in stent retriever nitinol wire supply. Distribution runs through Cardinal Health and regional specialty distributors into hospital interventional suites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cerebral vein thrombosis treatment market compounds steadily as extended oral anticoagulant maintenance creates recurring pharmacy revenue pools resistant to acute care cyclicality.
For Market Incumbents: Deploy MDR technical documentation harmonization to accelerate multi-country device launches before notified body backlogs extend further. Consolidate interventional neuroradiology training partnerships with Heidelberg and Munich academic centers to lock referral network loyalty against emerging platform competitors. Deepen backward integration into nitinol shape-memory alloy supply to neutralize wire shortage risks. For New Entrants and Emerging Players: Enter via home care transition protocols for stable CVT patients, the most penetrable segment where remote INR monitoring and direct-to-patient dispensing remain underdeveloped outside Germany and the Netherlands. Target anticoagulation clinic partnerships as the go-to-market anchor, leveraging integrated care contract incentives that reward readmission reduction. For Investors and Strategic Acquirers: Valuations sit cheapest among MDR-compliant mid-cap device manufacturers with legacy thrombectomy portfolios awaiting European market re-entry. Long-term viability frames around 5-10 year oral anticoagulant persistence curves and stroke network centralization tailwinds. Monitor EMA notified body capacity expansion announcements as the inflection signal for European device approval velocity.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Harmonization | Streamlined quality-system requirements reduce regulatory friction for multi-country neurovascular device launches. |
| Hospital System Partnership | Exclusive supply agreements with Berlin and Munich university hospitals concentrate interventional volume and referral capture. |
| Software Companion Development | AI-powered clot burden quantification integrates with interventional planning workflows in neuroradiology suites. |
| Reimbursement Strategy | G-BA and NICE health technology assessment positioning determines formulary access for oral factor Xa inhibitors. |
| CE Marking Pathway | Notified body conformity assessment timelines dictate European market entry sequencing for novel thrombectomy platforms. |
Study Parameters
Multiple input streams — primary interviews with interventional neuroradiologists and hospital pharmacy directors, secondary validation through FDA 510(k) filings and EMA MDR technical documentation databases, and procurement database analysis from German G-BA and NHS Supply Chain — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included stroke network administrators, GPO contracts managers, biomedical engineers, and anticoagulation clinic specialists. Secondary sources encompassed ClinicalTrials.gov entries, hospital purchasing consortium tender documents, and WHO essential medicines list criteria.
Data-stream reconciliation across treatment modality segmentation, end-user channel analysis, and regional regulatory clustering shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed product type, administration route, management strategy, and care setting transition patterns. CAGRs were derived from patient volume epidemiology, procedure adoption curves, and pharmaceutical persistency assumptions. Forecast inputs incorporated interventional neuroradiology fellowship pipeline data and MDR notified body capacity constraints.
Inputs from EMA conformity assessment databases and German hospital procurement records were available through the study window; gaps in real-time anticoagulant reversal agent stocking data introduce uncertainty bands around acute care cost assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Pigmentation Disorders Treatment Market
Specialty Medicine
Chronic Obstructive Pulmonary Disease Therapeutics Market
Specialty Medicine
Hypophosphatasia Treatment Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Ragweed Pollen Allergy Treatment Market
Specialty Medicine
ADHD Therapeutics Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Necrotizing Fasciitis Treatment Market
Specialty Medicine
Global Targeted Cancer Therapy Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Global Specialty Injectable Generics Market
Specialty Medicine
Whim Syndrome Management Market
Specialty Medicine
Spinal and Bulbar Muscular Atrophy Treatment Market
Specialty Medicine
Chronic Urticaria Market
Specialty Medicine
Neurodegenerative Disease Market
Specialty Medicine
Benign and Malignant Soft Tissue Tumors Treatment Market