
 Antibody Therapy Market | 2026-2036
Antibody Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Antibody Therapy Market Analysis
The gap between discovery-stage biologics and commercially viable antibody therapies is narrowing as single-cell sequencing and AI-driven epitope mapping compress candidate selection timelines. F. Hoffmann-La Roche Ltd. leverages its diagnostics-therapeutics integration to anchor clinical trial recruitment. AbbVie Inc. sustains pipeline momentum through Humira-derived immunology expertise. Johnson & Johnson competes across oncology and autoimmune portfolios with differentiated manufacturing scale.
Antibody therapy encompasses recombinant protein therapeutics engineered to bind specific antigens, typically immunoglobulin G frameworks produced in mammalian cell culture with glycosylation profiles optimized for effector function and serum half-life. These agents serve to modulate immune responses, deliver cytotoxic payloads, or neutralize pathogenic targets across oncology, autoimmune, and infectious disease applications. Monoclonal antibodies occupy the dominant revenue position due to established manufacturing infrastructure and broad label expansions. Biosimilars represent the fastest-growing product category as patent cliffs open market access. Oncology commands the largest therapy area allocation, though autoimmune disorders retain premium pricing power.
The FDA, EMA, and WHO collectively govern antibody therapy development through GMP manufacturing standards, biosimilar interchangeability guidelines, and international comparability protocols that determine market access speed and commercial geography. Regulatory stringency around immunogenicity testing and post-market pharmacovigilance directly shapes development costs and approval probabilities. Stakeholders must monitor evolving biosimilar substitution policies and cell-line authentication requirements as determinants of competitive positioning.
Market Dynamics
Single-cell sequencing platforms are compressing antibody discovery timelines from years to months, collapsing the traditional gap between target identification and clinical candidate selection while redistributing competitive advantage toward data-rich biopharma organizations.
Growth Catalysts
- FDA Accelerated Approval:The breakthrough therapy designation compresses Phase I-to-approval timelines for oncology antibodies, enabling earlier commercialization of checkpoint inhibitors and ADCs.
- Cell Culture Productivity Gains:Continuous bioprocessing and perfusion technologies are doubling titers in mammalian expression systems, lowering per-gram manufacturing costs for monoclonal antibodies.
- United States Reimbursement:Medicare Part B's pass-through payment structure for biologics preserves premium pricing for infused antibody therapies in oncology and immunology.
Market Restraints
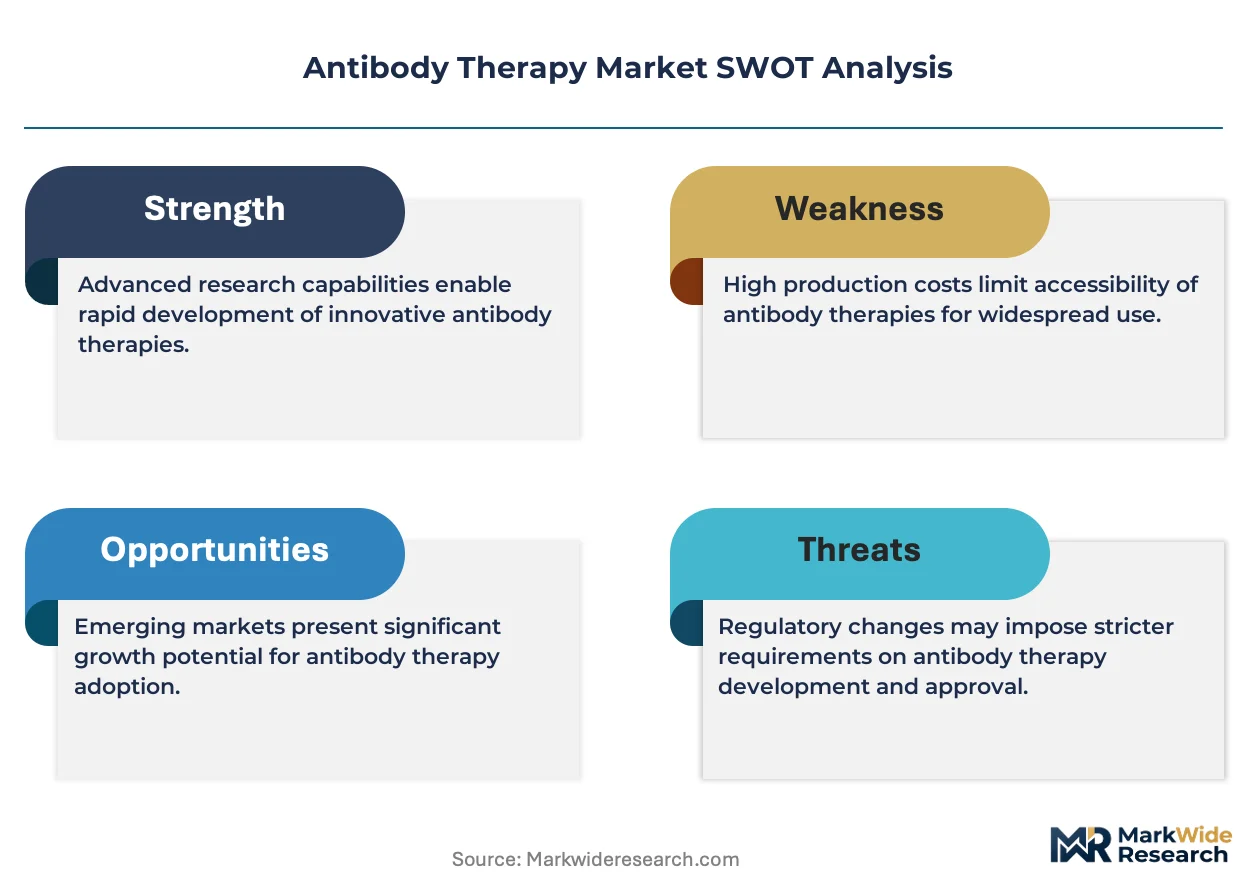
- Chinese Hamster Ovary Cell Supply Concentration:Over 70% of commercial antibody production relies on CHO cell lines from a limited supplier base, creating single-source vulnerability for critical raw materials.
- Immunogenicity Testing Burden:EMA's heightened requirements for anti-drug antibody monitoring in biosimilar applications add 12-18 months to development timelines and millions in analytical costs.
- Plasma-Derived Protein Competition:Intravenous immunoglobulin and other plasma fractionation products retain cost advantages in certain autoimmune indications, limiting antibody therapy penetration.
Strategic Opportunities
- Subcutaneous Formulation Expansion:Halozyme's ENHANZE technology enables volume-expansion for self-administered antibodies, opening home-delivery channels and reducing infusion center dependency.
- India Biosimilar Manufacturing:CDSCO's streamlined approval pathways and PLI scheme incentives position Indian contract manufacturers for export-oriented antibody production.
- AI-Driven Epitope Mapping:Machine learning platforms from structural biology vendors are predicting antibody-antigen interactions with 40% higher accuracy than traditional phage display, accelerating candidate selection.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:The shortage of professionals trained in scale-up cell culture and downstream purification is constraining manufacturing expansion timelines.
- Multi-Product Facility Validation:FDA's stringent requirements for campaign changeover cleaning validation in shared antibody suites extends facility commissioning by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibody Therapy Market |
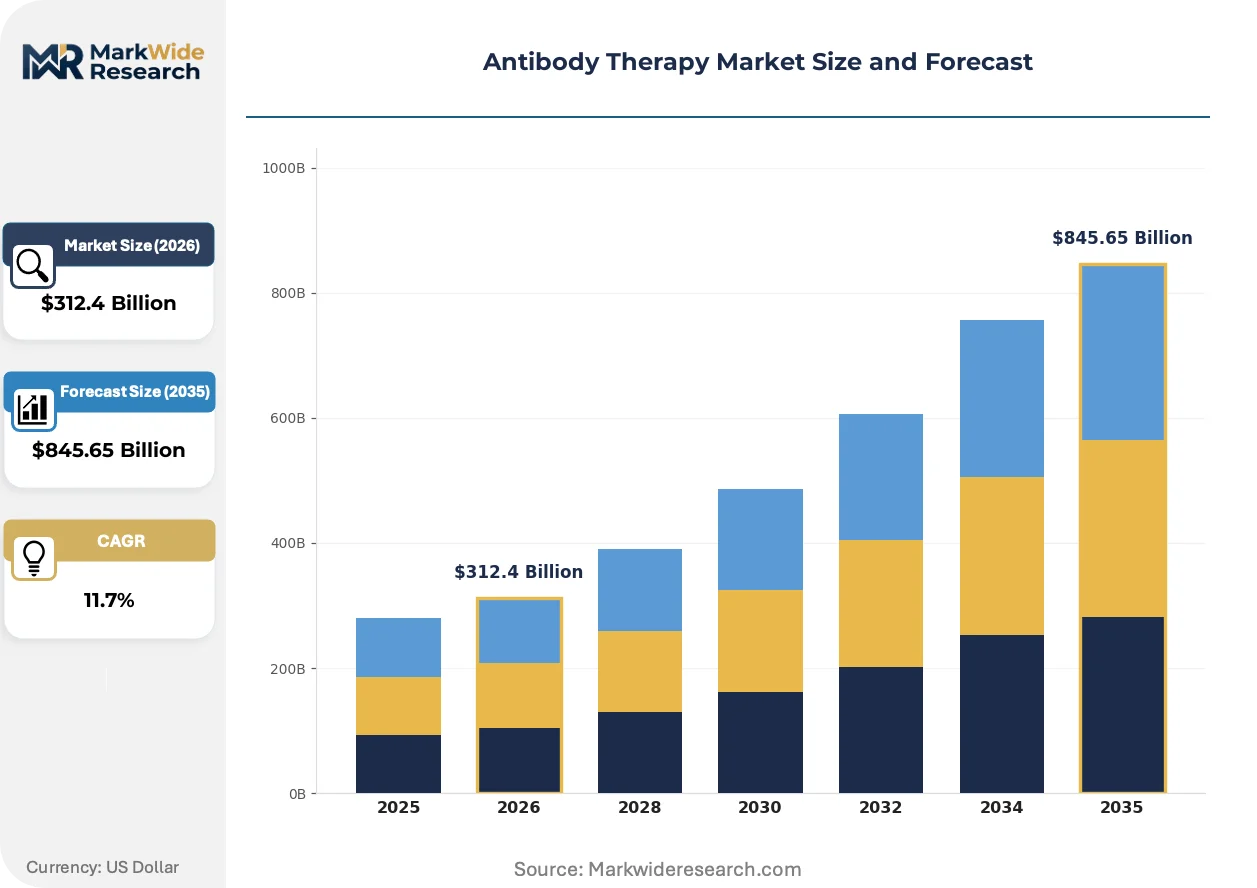
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $845.65 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Biosimilars, Conjugated Antibodies Therapy Area: Oncology, Autoimmune Disorders, Infectious Diseases, Neurological Conditions Administration Route: Intravenous, Subcutaneous, Intramuscular, Oral End User: Hospitals, Research Laboratories, Diagnostic Centers, Pharmacies |
| Companies Covered | F. Hoffmann-La Roche Ltd., AbbVie Inc., Johnson & Johnson, AstraZeneca, Amgen Inc., Regeneron Pharmaceuticals, Sanofi, Novartis AG, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibody Therapy Market Emerging Trajectories
Antibody engineering is converging with computational biology and modular manufacturing architectures, enabling programmable therapeutics that adapt to patient-specific disease profiles rather than static blockbuster designs.
Bispecific antibody constructs are digitizing target engagement strategies by enabling simultaneous binding of tumor antigens and T-cell receptors. Oncology departments at academic medical centers in the United States and Germany are adopting these formats at twice the rate of conventional monoclonals. The technology is digitizing clinical trial design through adaptive protocols that test multiple tumor indications in parallel rather than sequential Phase II programs.
EMA's revised biosimilar interchangeability guidelines create automatic substitution pathways in European Union member states with established pharmacovigilance systems. Industrial consequence includes accelerated price erosion for reference products and defensive patent litigation by originator manufacturers. Oncology and immunology portfolios face the steepest substitution pressure in Germany, France, and the Netherlands where pharmacy-level switching is now permitted.
Hospital procurement consortia are consolidating antibody purchasing decisions through centralized tendering mechanisms that unbundle drug acquisition from infusion services. Group purchasing organizations in the United States now control 60% of oncology biologic contracting, displacing individual hospital formulary committees. This concentration is most visible in the Northeast and Midwest regions where health system mergers have created multi-state purchasing entities with direct-to-manufacturer negotiation leverage.
Antibody Therapy Market Segmentation
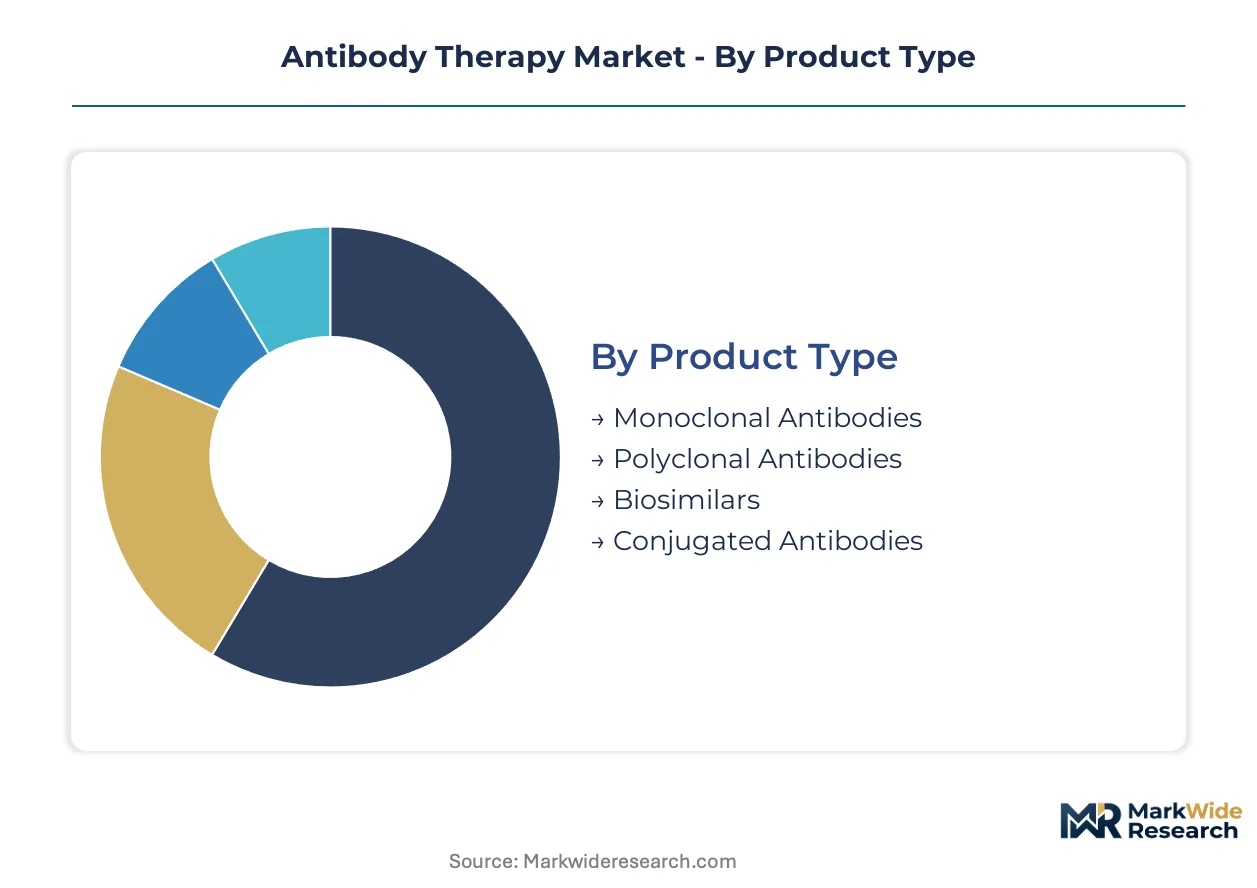
Antibody therapy segmentation reveals divergent commercial rhythms across product architectures and clinical settings. Cycle times vary dramatically from blockbuster monoclonals with decade-long revenue curves to biosimilars racing through compressed approval windows.
Product Type:
Monoclonal antibodies turn over slowest with extended patent protection, while biosimilars compress development-to-commercialization cycles through abbreviated regulatory pathways.
- Monoclonal Antibodies:Recombinant immunoglobulin G frameworks manufactured in mammalian cell culture with glycosylation profiles tuned for effector function and pharmacokinetic stability. Demand concentrates in United States oncology infusion centers where Medicare Part B reimbursement preserves premium pricing for checkpoint inhibitors and anti-HER2 agents.
- Biosimilars:Reverse-engineered biologics demonstrating analytical and clinical comparability to reference products through EMA interchangeability guidelines and FDA biosimilar approval standards. Expansion concentrates in Germany, France, and the Netherlands where pharmacy-level automatic substitution accelerates uptake and price erosion.
- Polyclonal Antibodies:Heterogeneous antibody mixtures derived from immunized animal sera or human plasma, retaining broader antigen recognition spectra.
- Conjugated Antibodies:Antibody-drug conjugates and radioimmunoconjugates combining tumor-targeting specificity with cytotoxic payloads or imaging agents.
Monoclonal antibodies dominate installed base. Biosimilars are where expansion concentrates.
Therapy Area:
Oncology commands the highest per-patient revenue but faces the steepest biosimilar substitution pressure, while autoimmune disorders retain pricing power through indication-specific clinical differentiation.
- Oncology:Checkpoint inhibitors, anti-VEGF agents, and ADCs targeting solid tumors and hematologic malignancies. Demand concentrates in academic medical centers across the United States and Germany where adaptive trial protocols accelerate bispecific antibody adoption.
- Autoimmune Disorders:Anti-TNF agents, IL inhibitors, and B-cell depleting therapies for rheumatoid arthritis, psoriasis, and multiple sclerosis. United States commercial payers and Medicare Advantage plans sustain premium pricing for subcutaneous formulations with differentiated immunogenicity profiles.
- Infectious Diseases:Pathogen-neutralizing monoclonals for RSV, HIV, and emerging viral threats with compressed development timelines.
- Neurological Conditions:Amyloid-targeting antibodies and anti-inflammatory constructs for Alzheimer's disease and multiple sclerosis with challenging blood-brain barrier penetration requirements.
Oncology dominates installed base. Autoimmune disorders are where expansion concentrates.
Administration Route:
Intravenous infusion maintains the highest dose volumes and facility dependency, while subcutaneous delivery unlocks home administration and pharmacy channel expansion.
- Intravenous:Large-volume antibody infusions requiring specialized infusion centers with cold-chain handling and adverse event monitoring capabilities. Demand concentrates in United States hospital outpatient departments and cancer centers where bundled payment models align drug and service reimbursement.
- Subcutaneous:Volume-optimized formulations using hyaluronidase technology or high-concentration protein engineering for patient self-administration. United States specialty pharmacy networks and home infusion providers are expanding capacity for immunology and oncology agents.
- Intramuscular:Depot-formulation antibodies with extended release kinetics for prophylactic applications.
- Oral:Experimental antibody formulations targeting mucosal immunity and gut-associated lymphoid tissue with limited commercial penetration.
Intravenous dominates installed base. Subcutaneous is where expansion concentrates.
End User:
Hospitals anchor high-complexity antibody administration with integrated pharmacy and infusion infrastructure, while research laboratories drive pipeline generation through discovery-stage partnerships.
- Hospitals:Integrated delivery networks with captive infusion centers, specialty pharmacy operations, and formulary committees controlling antibody selection for oncology and immunology. United States health system consolidation in the Northeast and Midwest has created multi-state purchasing entities with direct manufacturer negotiation leverage.
- Research Laboratories:Academic medical centers and contract research organizations conducting Phase I-III trials and biomarker-driven patient stratification. Germany's university hospital networks and the United States' NCI-designated cancer centers anchor clinical trial recruitment for novel antibody constructs.
- Diagnostic Centers:Imaging and pathology facilities utilizing antibody-based companion diagnostics for patient selection.
- Pharmacies:Retail and specialty pharmacy channels for subcutaneous self-administered agents with cold-chain distribution requirements.
Hospitals dominate installed base. Research laboratories are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports antibody therapies to the United States and Switzerland through established biopharma trade corridors, while India ships biosimilars to European and Middle Eastern markets via contract manufacturing partnerships.
United States
Medicare Part B pass-through payments sustain premium pricing for infused oncology antibodies, while hospital consolidation in the Northeast and Midwest creates multi-state purchasing leverage. The FDA's breakthrough therapy designation compresses development timelines for checkpoint inhibitors. Academic medical centers in Boston and Houston anchor adaptive clinical trial recruitment for bispecific constructs.
Germany
University hospital networks in Munich and Heidelberg drive bispecific antibody adoption at twice the rate of conventional monoclonals. EMA interchangeability guidelines enable automatic pharmacy-level substitution, accelerating biosimilar price erosion. The Rhine-Ruhr corridor concentrates manufacturing infrastructure for mammalian cell culture production serving export markets.
Switzerland
Basel anchors diagnostics-therapeutics integration through integrated R&D campuses linking biomarker discovery to clinical trial recruitment. Swissmedic maintains stringent pharmacovigilance standards that shape post-market surveillance requirements across European markets. The Lake Geneva region attracts specialized bioprocess engineering talent for continuous manufacturing scale-up.
India
CDSCO streamlined approval pathways and PLI scheme incentives position Indian contract manufacturers for export-oriented antibody production. Hyderabad and Bengaluru clusters specialize in biosimilar development for regulated markets. Domestic demand from tertiary care hospitals in Delhi and Mumbai drives oncology antibody access expansion.
Japan
PMDA's Sakigake designation accelerates review timelines for innovative antibody constructs targeting unmet oncology needs. The Kanto region's pharmaceutical corridor links Tokyo academic medical centers to Osaka manufacturing zones. METI funding for continuous bioprocessing technology adoption reduces per-gram production costs for domestic supply security.
Antibody Therapy Market Vendor Landscape
On the supply side, the industry is consolidated around integrated biopharma conglomerates with captive manufacturing infrastructure and diagnostics-therapeutics linkages. Three strategic archetypes dominate: vertically integrated originators with diagnostics platforms, immunology-focused specialists leveraging legacy antibody expertise, and diversified healthcare conglomerates competing across oncology and autoimmune portfolios. Dominant competitive moves include M&A for ADC technology access and capacity expansion into continuous bioprocessing platforms.
Within the originator tier, F. Hoffmann-La Roche Ltd. and AbbVie Inc. exemplify contrasting strategic positions—Roche representing diagnostics-anchored trial recruitment integration, AbbVie embodying immunology portfolio momentum derived from established antibody franchises. Johnson & Johnson occupies a diversified position spanning oncology and autoimmune segments with manufacturing scale advantages. These three entities collectively represent the competitive archetypes reshaping market structure through differentiated platform investments rather than overlapping capability claims.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| AbbVie Inc. |
| Johnson & Johnson |
| AstraZeneca |
| Amgen Inc. |
| Regeneron Pharmaceuticals |
| Sanofi |
| Novartis AG |
| Bristol-Myers Squibb |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese Hamster Ovary cell line production is compressing contract manufacturing margins while simultaneously enabling aggressive biosimilar pricing in European markets. This utilization dynamic forces originators to defend reference product premiums through formulation differentiation and indication expansion strategies.
Pricing Analysis
The pricing gap between first-generation monoclonal antibodies, current biosimilars, and next-generation bispecific constructs spans order-of-magnitude differences in per-patient annual costs. Pricing stratifies across premium originator tiers with companion diagnostic bundling, standard biosimilar levels with pharmacy-level substitution, and economy contract manufacturing tiers for emerging market access. Cost compression in the biosimilar segment is intensifying because EMA interchangeability guidelines enable automatic substitution in Germany, France, and the Netherlands. Hospital procurement consortia demonstrate the highest price sensitivity through centralized tendering mechanisms, while academic medical centers with adaptive trial protocols retain lower sensitivity for novel constructs.
Supply Chain Analysis
Extended payment terms from United States hospital purchasing consortia are forcing contract manufacturers to access supply-chain finance facilities for working capital coverage. Manufacturing capacity concentrates in the United States, Germany, and Switzerland for originator production, with India and South Korea anchoring biosimilar supply expansion. Critical inputs include mammalian cell culture media, protein A chromatography resins, and single-use bioreactor bags. Single-source vulnerability for CHO cell line master banks creates systemic exposure to supplier contamination events. Distribution runs through cold-chain logistics networks linking manufacturing sites to hospital infusion centers and specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antibody therapy market is approaching a platform-economics inflection as diagnostics-therapeutics integration creates ecosystem lock-in effects. Interoperability between biomarker discovery platforms and adaptive trial protocols is reshaping competitive moats around data-rich organizations.
For Market Incumbents: Insulate reference product franchises by deepening backward integration into continuous bioprocessing capacity and securing exclusive supply agreements for critical chromatography resins. Biosimilar substitution pressure in European markets demands defensive patent litigation and rapid subcutaneous formulation conversions to preserve formulary positioning. The priority lever centers on diagnostics-therapeutics integration that anchors clinical trial recruitment and companion diagnostic bundling.
For New Entrants and Emerging Players: Pursue white-space opportunities in bispecific antibody manufacturing for academic medical center adaptive protocols, where data-generation partnerships accelerate regulatory timelines. The most penetrable segment sits in India biosimilar export production leveraging CDSCO streamlined pathways and PLI scheme incentives. A specialized go-to-market angle targets European pharmacy-level automatic substitution markets with cost-optimized mammalian cell culture platforms.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diagnostics-anchored platform companies with captive clinical trial recruitment infrastructure. Long-term viability across the projection horizon favors entities with demonstrated regulatory acceleration through FDA breakthrough therapy designation. The acquisition target archetype combines AI-driven epitope mapping capabilities with established GMP manufacturing infrastructure. The signal to watch is EMA biosimilar interchangeability guideline expansion into additional therapeutic areas.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Adoption | Halves per-gram production costs for mammalian cell culture platforms in United States facilities. |
| Diagnostics-Therapeutics Integration | Roche's biomarker-anchored trial recruitment compresses Phase I-to-approval timelines for oncology antibodies. |
| Biosimilar Interchangeability Pursuit | EMA guideline compliance enables automatic pharmacy substitution in Germany, France, and Netherlands markets. |
| Subcutaneous Formulation Expansion | Halozyme ENHANZE technology unlocks home administration channels reducing infusion center dependency. |
| AI-Driven Epitope Mapping Investment | Machine learning platforms accelerate candidate selection with superior antibody-antigen interaction prediction accuracy. |
Methodological Framework
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underlying this analysis. Primary interviews with payer access specialists and bioprocess engineering directors were cross-validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population modeling and top-down revenue reconciliation provided triangulation across the analysis window.
Demand-supply-balance framing anchored the forecast framework, with patient flow analysis through treatment lines and administration routes informing volume assumptions. Segmentation dimensions modeled include product architecture, therapy area, administration route, and regional regulatory cluster. CAGRs were derived from iterative convergence between epidemiological trend extrapolation and pricing trajectory analysis. Industry-specific inputs incorporated biosimilar approval velocity and continuous bioprocessing adoption curves.
Macroeconomic conditions sit as an overlay; deviation in reimbursement policy shifts, bioprocess engineering labor availability, or raw material supply concentration would shift the trajectory. Forecasts reflect documented assumptions around regulatory pathway timelines and manufacturing productivity gains. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
India Over-The-Counter Drugs (OTC) Market
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
Ampicillin Drugs Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
Bipolar Disorder Drugs and Treatment Market
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
China Opioids Market
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Inhalation and Nasal Spray Generic Drugs Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
Saudi Arabia Pharmaceutical Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Belgium Pharmaceutical Market