
 United States Drug Delivery Devices Market | 2026-2036
United States Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United States Drug Delivery Devices Market Analytics
Homecare settings is repositioning demand toward patient-administered therapies, shifting procurement priorities away from hospital-centric models. Becton, Dickinson and Company leverages its vertical integration across prefilled syringes and pen injectors to control supply chains. West Pharmaceutical Services, Inc. specializes in elastomer and containment solutions for biologics. Medtronic plc anchors its position through infusion pump platforms with embedded connectivity.
United States drug delivery devices are engineered systems designed to administer pharmaceutical agents through controlled release kinetics, incorporating specifications such as flow-rate precision within five percent tolerance and biocompatible materials meeting ISO 10993 standards. These devices serve the primary commercial purpose of improving therapeutic adherence, reducing dosing variability, and enabling self-administration across chronic disease populations. Injectable delivery mode dominates value generation due to biologics proliferation, while smart devices within the technology dimension represent the fastest-expanding margin pool as connectivity and dose-tracking capabilities reshape reimbursement logic. Transdermal patches occupy a mature niche with stable hospital adoption but limited homecare traction compared to pump and inhaler alternatives.
FDA, HIPAA, and ISO 13485 collectively govern device safety, data privacy in connected platforms, and quality management system compliance across the United States market. FDA combination product regulations shape demand by extending review timelines for drug-device pairings, while HIPAA constrains how smart delivery systems transmit patient dosing data. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled dosing algorithms and state-level telehealth reimbursement policies that determine homecare device economics.
Market Dynamics
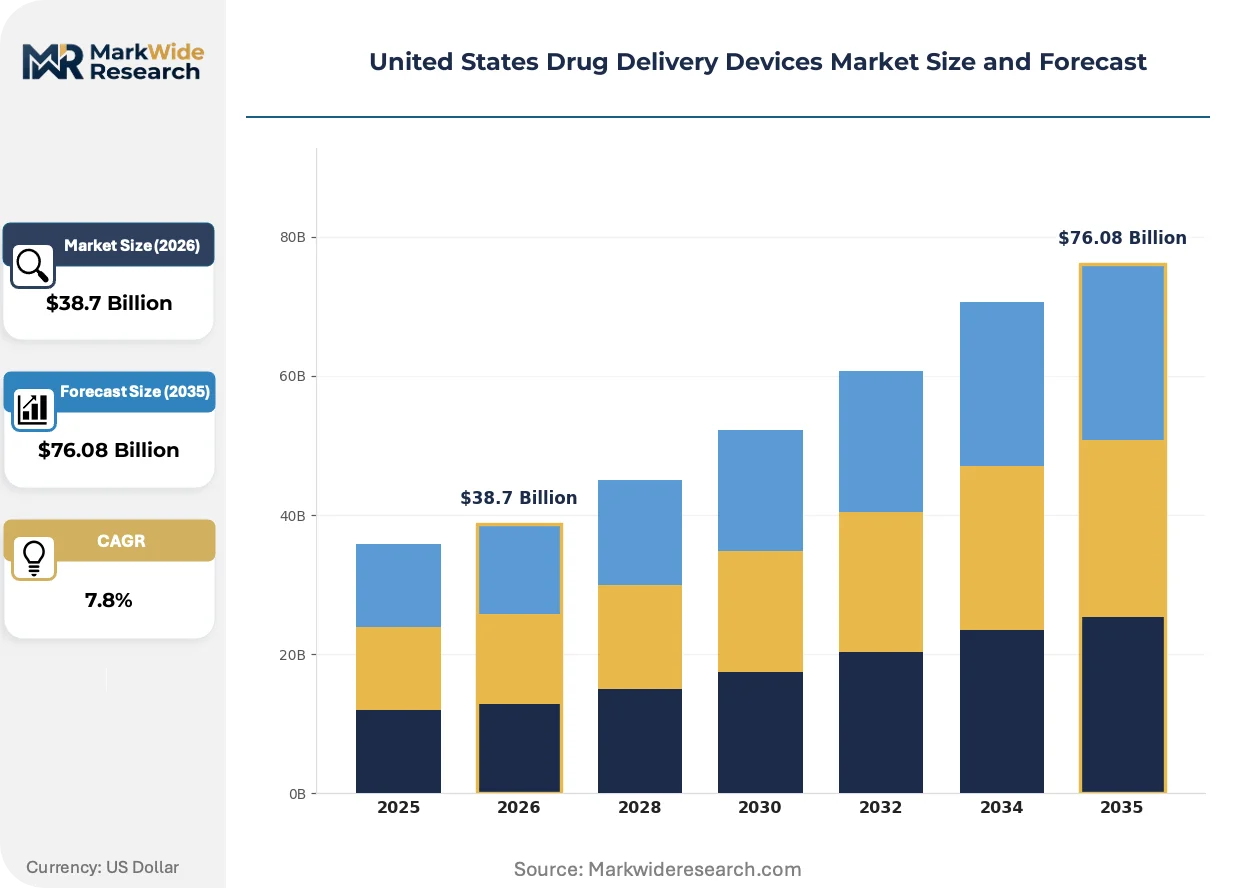
FDA 510(k) clearance pathways for combination products and wearable injectors are compressing innovation cycles, while homecare demand reconfigures procurement toward patient-administered platforms. This regulatory acceleration intersects with biopharma clustering in California and Massachusetts to reshape competitive positioning.
Growth Catalysts
- Biologics proliferation:Complex therapeutic proteins require precision injectable systems, pulling demand toward advanced pen injectors and autoinjectors in chronic disease management.
- ISO 13485 harmonization:Quality management standardization reduces supplier qualification friction, accelerating device commercialization timelines for domestic manufacturers.
- Homecare migration:Patient-administered therapies in diabetes and rheumatology are displacing hospital-centric infusion models, expanding addressable device volumes.
Market Restraints
- Silicone elastomer supply concentration:West Pharmaceutical Services and limited alternative suppliers create input vulnerability for containment solutions serving biologics.
- FDA combination product review extension:Drug-device pairing regulations add 6-18 month timeline uncertainty, constraining capital deployment for novel platform development.
- Metal-polymer substitution limits:Stainless steel prefilled syringes retain cost advantage over polymer alternatives in high-volume generic applications, capping material transition speed.
Strategic Opportunities
- Telehealth reimbursement expansion:State-level policies determining homecare device economics create white space for connected pump platforms with embedded dosing analytics.
- AI-enabled dosing algorithm guidance:Evolving FDA frameworks on artificial intelligence in delivery systems offer first-mover advantage for algorithm-integrated wearable injectors.
- Texas and North Carolina biopharma growth:Emerging manufacturing clusters beyond California-Massachusetts corridor present underpenetrated demand for regional device supply partnerships.
Industry Challenges
- Connected platform cybersecurity certification:HIPAA compliance for patient dosing data transmission requires specialized engineering talent scarce in traditional device manufacturing.
- Biocompatibility testing backlog:ISO 10993 standard evolution creates timeline compression for material qualification, straining regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Drug Delivery Devices Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $76.08 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Syringes, Pumps, Transdermal Patches Delivery Mode: Injectable, Oral, Topical, Inhalation End User: Hospitals, Homecare, Clinics, Ambulatory Surgical Centers Technology: Smart Devices, Microneedle Technology, Bioadhesive Systems, Nanotechnology |
| Companies Covered | Becton, Dickinson and Company, West Pharmaceutical Services, Inc., Medtronic plc, Johnson & Johnson, Baxter, Insulet Corporation, Tandem Diabetes Care, Cardinal Health, 3M, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Drug Delivery Devices Market Evolving Landscape
Wearable injector platforms with embedded connectivity are reshaping reimbursement logic and competitive differentiation. Three convergent developments are restructuring how devices capture value and integrate into care delivery.
Smart delivery systems incorporating Bluetooth-enabled dose tracking and cloud-based adherence monitoring are expanding into diabetes and multiple sclerosis patient populations. Endocrinology practices and specialty pharmacies are adopting these platforms at accelerating pace to demonstrate outcomes for payor contracts. The technology is expanding into premium pricing tiers as connectivity becomes a reimbursement prerequisite rather than optional feature.
FDA guidance evolution on artificial intelligence-enabled dosing algorithms is creating compliance complexity for algorithm-integrated devices. Manufacturers must demonstrate algorithm validation and real-world performance monitoring, extending development timelines for next-generation platforms. The infusion pump segment is most affected, with Medtronic and emerging competitors restructuring quality systems to accommodate adaptive software review pathways.
Specialty pharmacy direct-to-patient distribution is compressing traditional hospital purchasing committee influence over device selection. Diabetes and autoimmune therapy prescribers are routing patients toward home delivery platforms that bundle device training with medication shipment. This channel rotation is most visible in California and Florida, where consolidated specialty pharmacy networks anchor patient onboarding workflows.
United States Drug Delivery Devices Market Segmentation
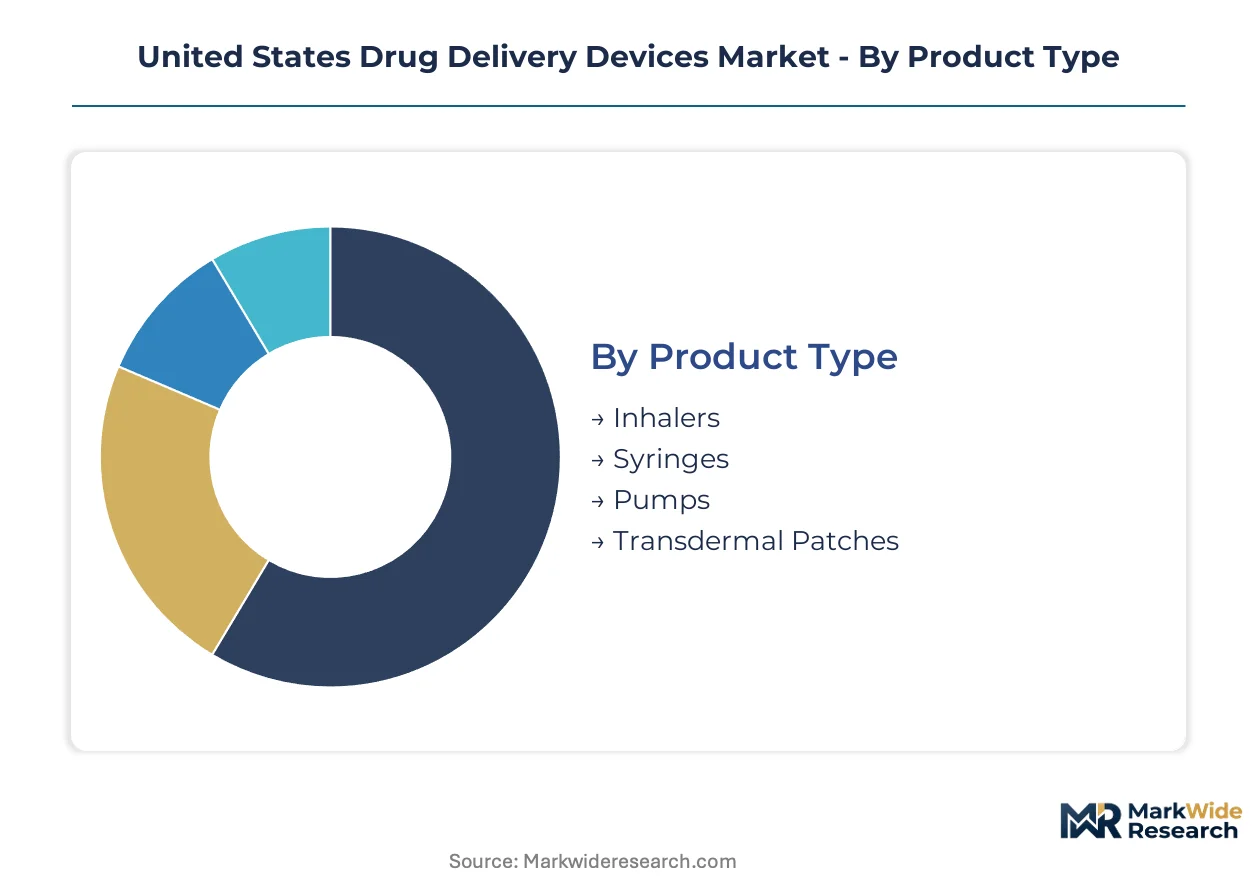
Device segmentation in the United States market reveals how reimbursement pathways and patient-administration trends reshape procurement priorities across delivery platforms. Understanding category boundaries helps stakeholders align R&D investment with the fastest-expanding margin pools.
Product Type:
Replacement cycles vary dramatically across product categories, with legacy hospital equipment facing accelerated obsolescence as homecare platforms capture preference.
- Syringes:Prefilled and safety-engineered designs dominate chronic disease administration, with flow-rate precision specifications meeting ISO 13485 quality benchmarks. Demand concentrates in California and Massachusetts biopharma clusters where biologics manufacturing anchors device procurement volumes.
- Pumps:Infusion and wearable injector platforms incorporate Bluetooth connectivity and cloud-based dose tracking, commanding premium positioning in diabetes and multiple sclerosis therapy protocols. Texas and Florida specialty pharmacy networks are driving fastest adoption for patient-administered infusion alternatives.
- Inhalers:Metered-dose and dry-powder systems serve respiratory therapy protocols with established Medicare reimbursement codes.
- Transdermal Patches:Matrix and reservoir designs occupy stable hospital niches but face limited homecare traction against pump alternatives.
Syringes sit at the top of the volume ranking, with pumps climbing the fastest.
Delivery Mode:
Cost tier differentiation separates precision-engineered platforms from commodity alternatives, with reimbursement logic favoring demonstrable adherence outcomes.
- Injectable:Autoinjectors, pen injectors, and prefilled syringes administer biologics with controlled release kinetics and five percent flow-rate tolerance specifications. Massachusetts and North Carolina manufacturing hubs are expanding capacity to serve rheumatology and endocrinology patient populations migrating to self-administration.
- Inhalation:Nebulizers and dry-powder inhalers deliver respiratory agents with particle size optimization for pulmonary deposition. CMS reimbursement policies in Florida and California are reshaping prescribing patterns toward connected platforms with adherence documentation.
- Oral:Sustained-release formulations and novel dosage forms address gastrointestinal absorption variability.
- Topical:Creams, gels, and ointment applicators serve dermatology and localized pain management with limited device complexity.
Injectable delivery commands the largest revenue share, with inhalation gaining share fastest as respiratory connectivity platforms penetrate Medicare Advantage contracts.
End User:
Customer type determines procurement authority, with consolidated specialty pharmacy networks displacing traditional hospital purchasing committee influence.
- Homecare:Patient-administered platforms bundle device training with medication shipment through specialty pharmacy direct-to-patient distribution. California and Florida consolidated networks anchor onboarding workflows for diabetes and autoimmune therapies.
- Hospitals:Acute care settings retain preference for infusion pumps with embedded connectivity and centralized dosing analytics, though procurement volumes face displacement from homecare migration.
- Clinics:Outpatient infusion centers serve as transition points between hospital and home administration, with device selection increasingly influenced by specialty pharmacy partnership terms.
- Ambulatory Surgical Centers:Same-day procedure settings demand compact, single-use delivery platforms with minimal training requirements.
Homecare sits at the top of the volume ranking, with ambulatory surgical centers climbing the fastest as procedure migration accelerates.
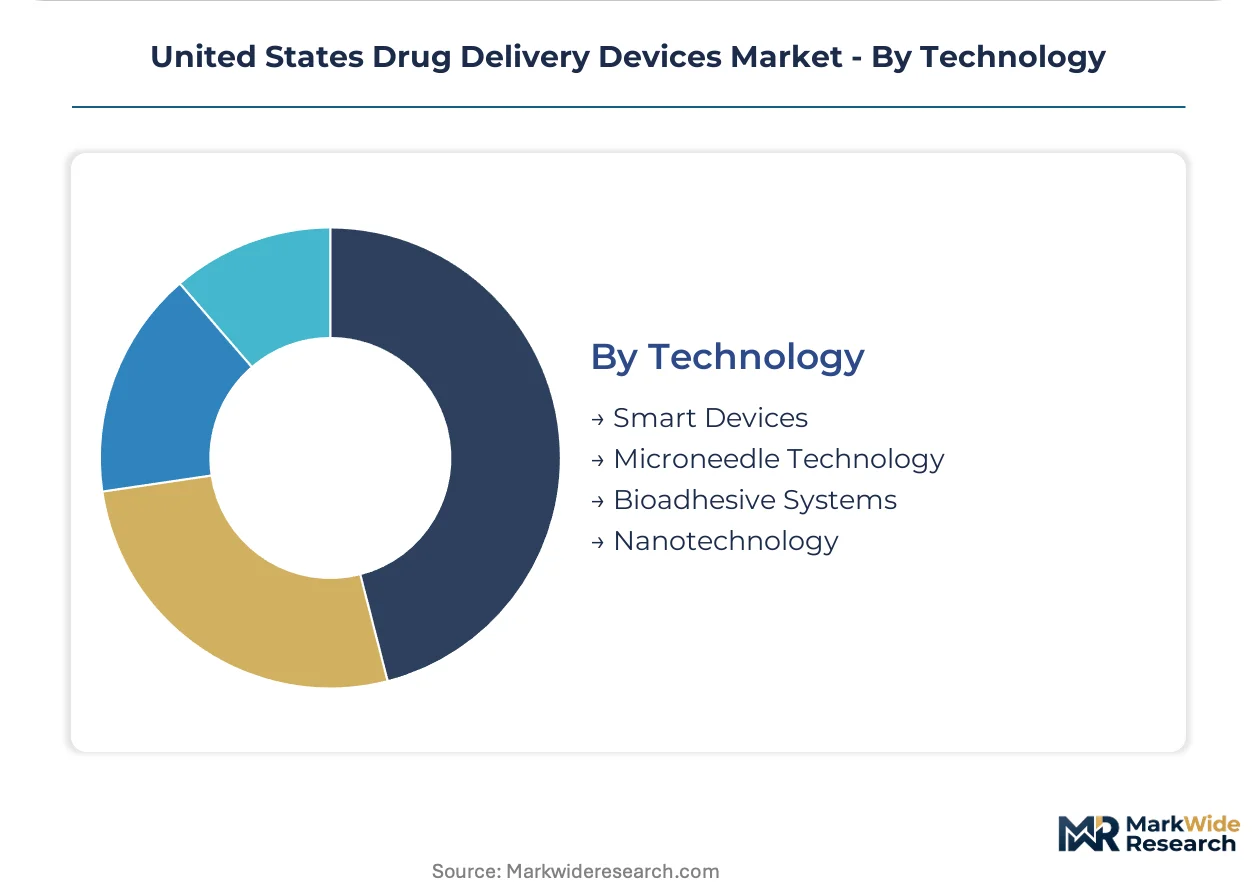
Technology:
Margin concentration follows connectivity capabilities, with dose-tracking and adherence monitoring reshaping reimbursement prerequisites.
- Smart Devices:Bluetooth-enabled pumps and injectors transmit dosing data to cloud platforms, satisfying HIPAA compliance requirements for patient data transmission. FDA guidance evolution on algorithm validation is extending development timelines for adaptive software-integrated platforms.
- Microneedle Technology:Dissolvable and hollow microarray designs enable transdermal biologics delivery with reduced immunogenicity risk. Massachusetts research institutions are anchoring commercialization partnerships for next-generation vaccine and insulin applications.
- Bioadhesive Systems:Mucoadhesive and tissue-adhesive formulations extend gastrointestinal or topical residence time for enhanced absorption profiles.
- Nanotechnology:Liposomal and polymeric nanoparticle carriers address solubility and targeting challenges for oncology and neurology payloads.
Smart devices sit at the top of the volume ranking, with microneedle technology climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The California-Massachusetts biopharma corridor anchors device demand through concentrated biologics manufacturing and medtech R&D infrastructure. FDA 510(k) clearance pathways and state-level telehealth reimbursement policies are redistributing procurement authority across sub-national markets.
California
San Francisco Bay Area and San Diego clusters drive demand for connected insulin pumps and autoinjectors serving diabetes and autoimmune patient populations. FDA breakthrough device designation programs accelerate local commercialization timelines for wearable injector platforms. Specialty pharmacy networks in Los Angeles and Orange County are compressing traditional hospital purchasing influence through direct-to-patient distribution models.
Massachusetts
Greater Boston's biopharma concentration generates procurement volumes for containment solutions and precision syringes serving biologics manufacturing. ISO 13485 quality management compliance requirements shape supplier qualification protocols among Cambridge-area device developers. Worcester County manufacturing expansion is absorbing overflow demand from constrained silicone elastomer supply chains.
Texas
Houston and Dallas-Fort Worth medical center complexes are expanding ambulatory infusion capacity for patient-administered therapies transitioning from hospital settings. State Medicaid reimbursement policies for homecare devices are attracting specialty pharmacy distribution investment. Austin's emerging health tech corridor is incubating connected pump startups targeting Medicare Advantage adherence contracts.
North Carolina
Research Triangle Park pharmaceutical manufacturing is pulling demand for prefilled syringes and safety-engineered injection systems. FDA combination product review timelines are influencing local device developer capital deployment decisions. Durham and Raleigh biotech incubators are anchoring regional partnerships with West Pharmaceutical Services for elastomer containment supply.
Florida
Miami and Tampa specialty pharmacy consolidation is driving fastest adoption of Bluetooth-enabled adherence tracking platforms for diabetes management. CMS Medicare Advantage penetration rates in the state are reshaping prescriber routing toward connected devices with documented outcomes data. Orlando medical device distribution hubs are serving southeastern homecare migration demand.
United States Drug Delivery Devices Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers respond to biologics proliferation and homecare procurement reconfiguration. The vendor base stratifies across three tiers: diversified medtech conglomerates with pump and injector portfolios, specialized containment and elastomer suppliers, and connected device pure-plays. Strategic archetypes include vertical integrators controlling prefilled syringe supply chains, platform specialists embedding connectivity for reimbursement advantage, and regional fabricators serving emerging biopharma clusters. M&A activity and FDA 510(k) pathway exploitation represent the dominant competitive moves reshaping positioning.
Among diversified portfolio holders, Becton, Dickinson and Company and Johnson & Johnson exemplify scale-driven archetypes with cross-category presence spanning safety-engineered syringes and infusion systems. Medtronic plc occupies a position within the connected platform tier, representing pump manufacturers embedding cloud-based dose analytics for payor contract differentiation. Insulet Corporation and Tandem Diabetes Care sit within the diabetes-focused pure-play segment, anchoring wearable insulin delivery specialization against broader portfolio competitors. West Pharmaceutical Services, Inc. represents the containment specialist archetype, with elastomer and closure system focus serving biologics manufacturing demand concentration in California and Massachusetts clusters.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| West Pharmaceutical Services, Inc. |
| Medtronic plc |
| Johnson & Johnson |
| Baxter |
| Insulet Corporation |
| Tandem Diabetes Care |
| Cardinal Health |
| 3M |
| Others |
Value Network & Pricing Analysis
Silicone elastomer price indices cascade through United States drug delivery device supply chains, compressing margins for containment-dependent manufacturers while amplifying pricing power among vertically integrated syringe producers serving biopharma clusters.
Pricing Analysis
Input-cost pass-through from medical-grade polymers and stainless steel alloys stratifies pricing across three tiers: premium connectivity-enabled pumps, standard prefilled syringes, and economy generic alternatives. ISO 13485 certification grade and embedded Bluetooth adherence tracking represent the primary differentiation drivers. Cost compression in the economy tier intensifies as high-volume generic manufacturers prioritize stainless steel over polymer alternatives. Hospital purchasing committees exhibit highest price sensitivity, while specialty pharmacy networks securing Medicare Advantage contracts demonstrate lowest sensitivity to upfront device costs.
Supply Chain Analysis
Medical-grade silicone elastomer supply rests on concentrated domestic production anchored in Massachusetts and Pennsylvania, with limited qualified alternative sources for biologics containment applications. Stainless steel tubing for prefilled syringes draws from Minnesota and Ohio manufacturing hubs, while polymer resins feed from Texas petrochemical corridors. Single-source vulnerability in silicone elastomer qualification creates procurement risk for wearable injector platforms. Distribution runs through consolidated specialty pharmacy networks in California and Florida, displacing traditional hospital purchasing committee influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States drug delivery device manufacturing offers geographic-arbitrage advantages through FDA 510(k) pathway acceleration relative to European MDR timelines, reducing time-to-revenue for domestic developers by twelve to eighteen months.
For Market Incumbents: To counter emerging connected pump competitors from Austin and Research Triangle Park, Becton Dickinson and Medtronic should deepen backward integration into silicone elastomer production and expand Massachusetts manufacturing capacity for containment solutions. FDA breakthrough device designation pursuit represents a critical certification lever for maintaining premium positioning against algorithm-integrated challengers. For New Entrants and Emerging Players: Direct-to-patient digital channels through consolidated specialty pharmacy networks in Florida and Texas offer the most penetrable route for microneedle technology platforms targeting diabetes adherence contracts. Texas Medicaid reimbursement expansion for homecare devices creates immediate white-space opportunity for connected insulin pump alternatives, with Austin health tech incubators providing regional partnership access. For Investors and Strategic Acquirers: Consolidation pressure builds where silicone elastomer supply concentration intersects with biologics manufacturing expansion in California and Massachusetts. Long-term viability favors acquisition targets with FDA 510(k) clearance momentum and embedded connectivity architectures serving Medicare Advantage outcomes contracts. Algorithm validation guidance evolution from FDA represents the critical inflection signal for adaptive dosing platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Accelerates commercialization timelines for wearable injector platforms in California clusters. |
| Silicone Elastomer Backward Integration | Captures supply chain margin and reduces input vulnerability for biologics containment solutions. |
| Specialty Pharmacy Network Partnership | Secures patient onboarding workflows for diabetes and autoimmune therapy device bundling. |
| AI-Enabled Dosing Algorithm Development | Positions for evolving FDA guidance on adaptive software validation in infusion pumps. |
| Texas Manufacturing Footprint Expansion | Captures Medicaid reimbursement-driven demand for homecare device regional supply partnerships. |
Research Methodology
Direct dialogue with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and specialty pharmacy distribution executives grounded the qualitative foundation, cross-referenced with FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up and top-down triangulation validated segment-level demand estimates across product categories.
Bottom-up modeling aggregated device shipment volumes by delivery mode and technology tier, while top-down analysis calibrated aggregate market expansion against biologics pipeline growth and homecare migration trends. Segmentation dimensions included product type, delivery mode, end-user setting, and connectivity capability. CAGRs were derived from regression analysis against FDA approval velocity and specialty pharmacy network expansion rates.
The model assumes a particular technology adoption path; alternative pathways for microneedle transdermal delivery would alter the outlook for injectable device demand concentration. Forecasts reflect assumptions regarding FDA guidance evolution on AI-enabled dosing and state-level telehealth reimbursement stability. Material deviation in silicone elastomer supply availability or breakthrough device designation denial rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Endoprosthesis Market
Medical Devices
Radiolucent Wrist Fixator Market
Medical Devices
Kirschner Wires Market
Medical Devices
Global Advanced Bipolar Direct Energy Device Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
Ophthalmic Microscopes Market
Medical Devices
Carotid Stenting Systems Market
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
Powered Wheelchair Market
Medical Devices
Portable Ultrasonic Skin Scrubber Market
Medical Devices
Global Microscopy Device Market
Medical Devices
High Pressure Contrast Media Injectors Market
Medical Devices
Neurostimulation Devices Market
Medical Devices
Veterinary Ultrasound Devices Market
Medical Devices
China Aesthetic Devices Market
Medical Devices
Wearable Breast Pumps Market