
 Europe Scar Treatment Market | 2026-2036
Europe Scar Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Scar Treatment Market Analytics
CE marking under the EU Medical Device Regulation is redrawing competitive boundaries for laser and silicone-based scar devices. Smith & Nephew PLC leverages its wound care heritage to sustain hospital channel dominance across Western Europe. Merz Pharma GmbH & Co. KGaA anchors its position through specialized injectable scar therapies, while Molnlycke Health Care AB dominates silicone sheet supply to post-surgical units.
Scar treatment encompasses topical formulations, mechanical sheeting, energy-based devices, and intralesional interventions designed to remodel collagen architecture and reduce fibrotic tissue visibility. Silicone gel sheets operate through occlusive hydration and static pressure mechanisms, while fractional laser systems target scar vasculature and collagen redistribution at precise dermal depths. Laser devices capture premium margin pools in clinic settings, whereas silicone sheets and gels drive volume through pharmacy and home care channels. Post-surgical applications lead therapy area demand, with hypertrophic scar management representing the fastest-growing segment as procedural volumes expand.
EMA oversight of combination drug-device products and the EU MDR's stricter clinical evidence requirements are elevating compliance costs for manufacturers seeking European market access. REACH regulations governing silicone polymer chemistry and the F-Gas Regulation's restrictions on certain laser cooling agents further constrain formulation and equipment design choices. Stakeholders must monitor evolving notified body capacity bottlenecks and national reimbursement decisions that will determine which modalities achieve sustainable adoption across European healthcare systems.
Market Dynamics
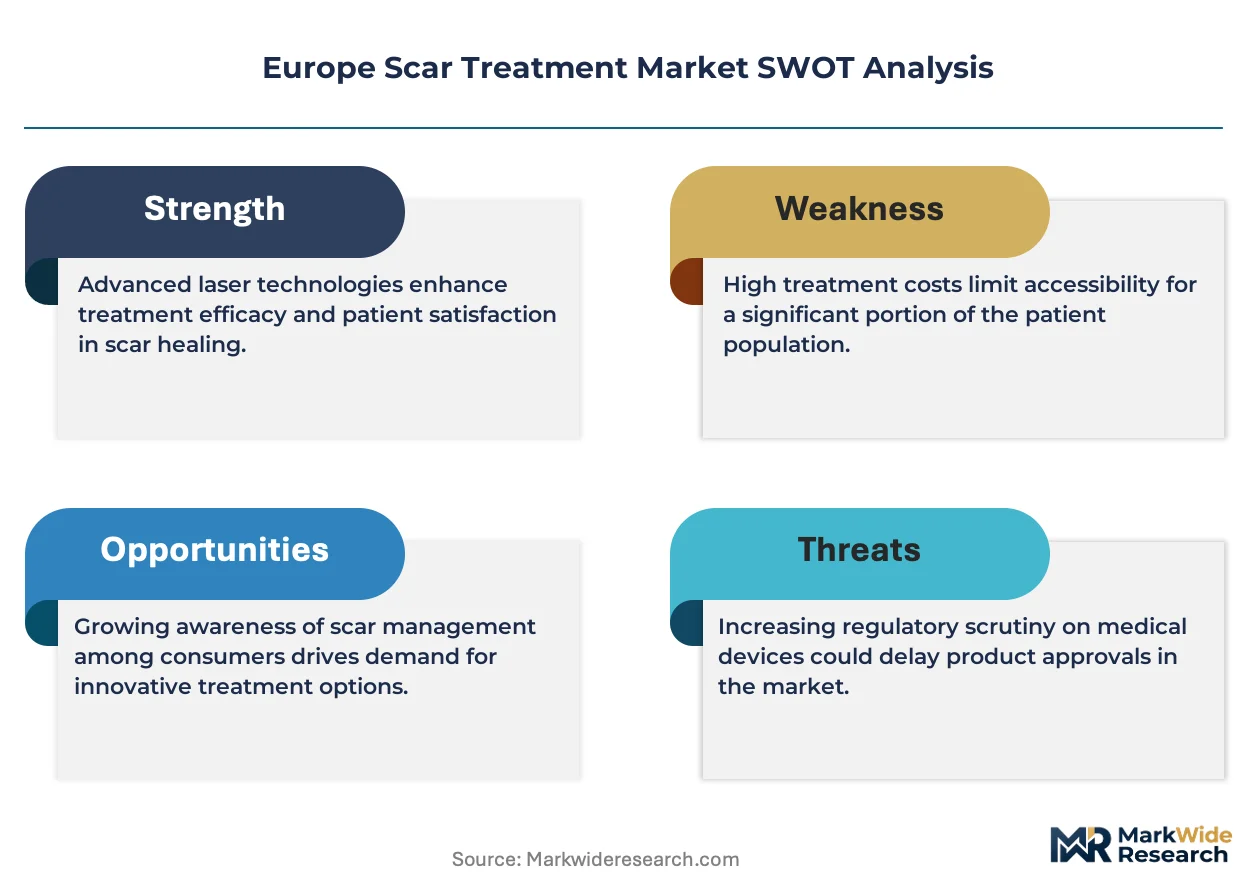
EU Medical Device Regulation compliance costs are compressing vendor margins while fragmenting competitive positioning across energy-based and mechanical scar treatment modalities. The CE marking transition is forcing portfolio rationalization among mid-tier device manufacturers serving dermatology and plastic surgery channels.
Growth Catalysts
- Post-surgical procedural volumes:Rising aesthetic and reconstructive surgery rates across Germany, France, and the United Kingdom are expanding the addressable patient pool for hypertrophic and keloid scar interventions.
- EU MDR compliance differentiation:Manufacturers that have secured notified body certification under the tightened medical device framework are capturing hospital procurement contracts from non-compliant competitors.
- Silicone polymer chemistry advances:Next-generation self-drying gel formulations with improved wear-time properties are displacing traditional sheet products in outpatient settings.
Market Restraints
- Notified body capacity bottlenecks:Concentrated certification infrastructure in Germany and the Netherlands is extending time-to-market for laser device manufacturers by 12-18 months.
- F-Gas Regulation constraints:Restrictions on hydrofluorocarbon cooling agents are forcing redesign of fractional laser systems, elevating R&D costs for equipment producers.
- Reimbursement fragmentation:Inconsistent national health technology assessment outcomes across EU member states limit cross-border commercial scalability for novel scar therapies.
Strategic Opportunities
- Eastern European clinic expansion:Poland and Romania present underpenetrated demand for laser-based scar revision as private dermatology networks expand beyond capital cities.
- Combination drug-device positioning:Convergence of corticosteroid-eluting silicone sheeting with sustained-release kinetics offers pathway to premium pricing in hospital burn units.
- Telemedicine-integrated home care:Remote monitoring platforms for post-operative scar management are opening direct-to-patient channels previously controlled by pharmacy retail.
Industry Challenges
- Laser technician certification scarcity:Specialized training requirements for fractional and vascular laser operation are constraining clinic capacity expansion across Nordic markets.
- Clinical evidence generation timelines:EU MDR's strengthened post-market surveillance obligations are extending study durations for comparative effectiveness claims against standard-of-care silicone.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Scar Treatment Market |
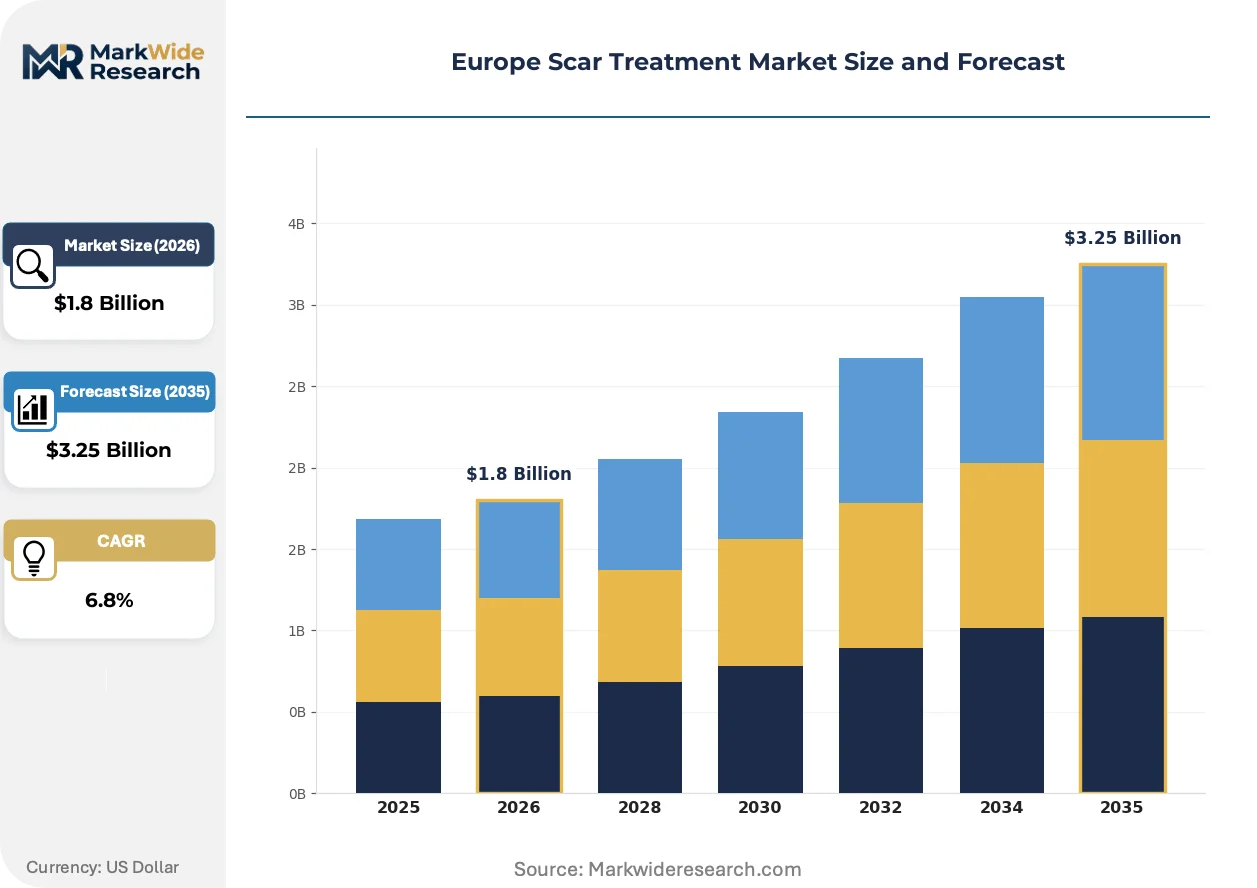
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Gels, Silicone Sheets, Laser Devices Therapy Area: Post-Surgical, Dermal, Hypertrophic, Keloid End User: Clinics, Hospitals, Home Care, Ambulatory Surgery Centers Distribution Channel: Online, Pharmacies, Specialty Stores, Direct Sales |
| Companies Covered | Smith & Nephew PLC, Merz Pharma GmbH & Co. KGaA, Molnlycke Health Care AB, Lumenis Be Ltd, Cynosure LLC, Perrigo Company PLC, Suneva Medical Inc, Alma Lasers, Sientra Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Scar Treatment Market Evolving Landscape
Scar treatment technology is converging around precision energy delivery and patient-controlled home-based modalities, compressing the traditional clinic-centric care model. These shifts are redrawing competitive boundaries between device manufacturers, pharmaceutical formulators, and digital health platforms.
Fractional laser systems are miniaturizing into handheld, lower-power devices suitable for ambulatory and select home-use applications under remote physician supervision. Dermatology clinics in Germany and the United Kingdom are piloting these portable units for patient self-administration between in-office sessions. This portability is compressing the addressable market for full-scale clinic installations while creating recurring revenue streams through consumable coupling gels and treatment plan subscriptions.
REACH regulations governing silicone monomer purity and polymer cross-linking density are elevating formulation standards for topical scar products entering the European market. Manufacturers must now document full supply chain chemistry compliance, favoring integrated producers with captive silicone synthesis capabilities. The regulatory burden falls most heavily on contract manufacturers serving private-label pharmacy brands, accelerating consolidation among gel and sheet suppliers.
Patient acquisition patterns are fragmenting across social media-influenced self-referral and general practitioner-mediated pathways. Aesthetic clinics in France and Spain are redirecting marketing spend toward Instagram and TikTok education content, bypassing traditional dermatologist referral networks. This channel disintermediation is most pronounced among patients under 35 seeking acne scar revision, compressing the role of primary care gatekeepers in treatment decisions.
Europe Scar Treatment Market Segmentation
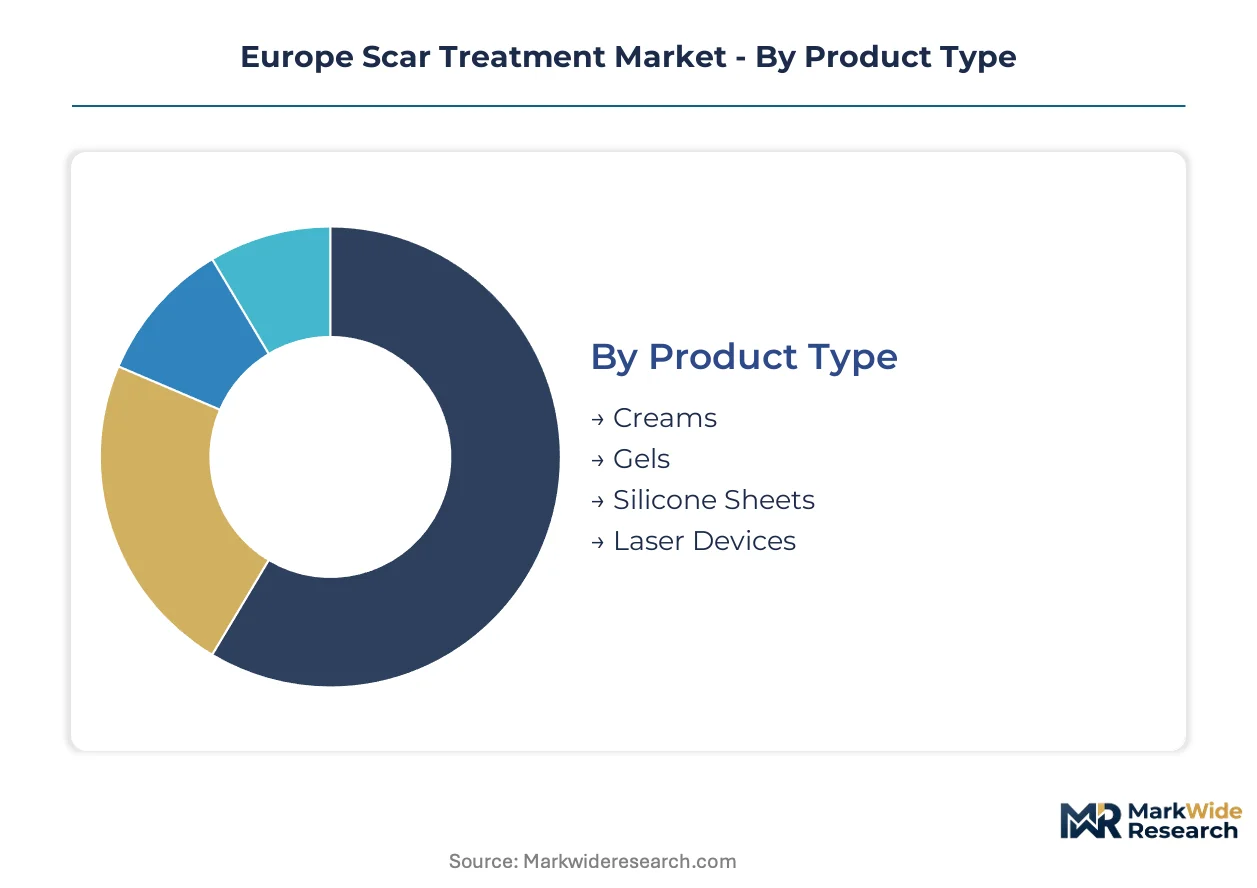
Channel economics and regulatory pathways diverge sharply across scar treatment modalities. Silicone-based products flow through pharmacy retail and home care channels, while laser devices concentrate in clinic procurement networks governed by EU MDR certification requirements.
Product Type:
Pharmacy and home care channels dominate mass-market formulations, whereas hospital procurement contracts govern energy-based device placement.
- Silicone Sheets:Occlusive polymer dressings deliver static pressure and hydration to remodeling scar tissue. German hospital burn units and post-surgical wards in France drive institutional procurement volumes, with REACH compliance on monomer purity elevating supplier qualification barriers.
- Laser Devices:Fractional and vascular laser systems target collagen redistribution at precise dermal depths through thermal injury patterns. Clinic networks in the United Kingdom and Germany capture premium placement, though F-Gas Regulation constraints on hydrofluorocarbon coolants are forcing equipment redesign cycles.
- Creams:Emulsion-based topical formulations containing onion extract or allantoin serve early-stage scar management in outpatient settings.
- Gels:Self-drying silicone gel variants with extended wear-time properties are displacing traditional sheet formats in Spanish and Italian pharmacy channels.
By volume, silicone sheets lead. By expansion trajectory, laser devices are climbing fastest as ambulatory clinic networks proliferate.
Therapy Area:
Procedure volume trends and reimbursement eligibility create distinct demand profiles across scar etiologies.
- Post-Surgical:Scar management following aesthetic and reconstructive procedures represents the foundational revenue pool. Hypertrophic intervention protocols in German and French hospital systems anchor standardized care pathways with defined reimbursement codes.
- Hypertrophic:Raised, erythematous scars with contained growth patterns respond to silicone occlusion and intralesional corticosteroid protocols. United Kingdom dermatology clinics report strongest patient self-referral volumes for this indication, driven by social media visibility of treatment outcomes.
- Dermal:Superficial scar categories including acne and minor trauma markings concentrate in private aesthetic clinic channels across Spain and Italy.
- Keloid:Aggressive fibroproliferative scarring with extension beyond wound boundaries requires multimodal intervention combining silicone sheeting, corticosteroid injection, and laser therapy.
Post-surgical applications command the largest patient base. Hypertrophic management is gaining share fastest as procedural aesthetics expand.
End User:
Capital intensity and regulatory oversight stratify access across care settings.
- Clinics:Private dermatology and aesthetic medicine practices concentrate laser device utilization and combination therapy protocols. German clinic chains are consolidating procurement power through group purchasing organizations.
- Hospitals:Acute care settings dominate post-surgical and burn scar management with institutional formulary control over silicone sheeting and injectable therapies.
- Home Care:Patient-directed topical application of gels and sheets bypasses clinical gatekeepers, with e-commerce platforms capturing growing share in Nordic markets.
- Ambulatory Surgery Centers:Same-day procedural facilities in France and the Netherlands are expanding scar treatment service lines as part of bundled aesthetic packages.
Clinics lead by procedure volume. Home care is expanding most quickly as self-treatment protocols proliferate.
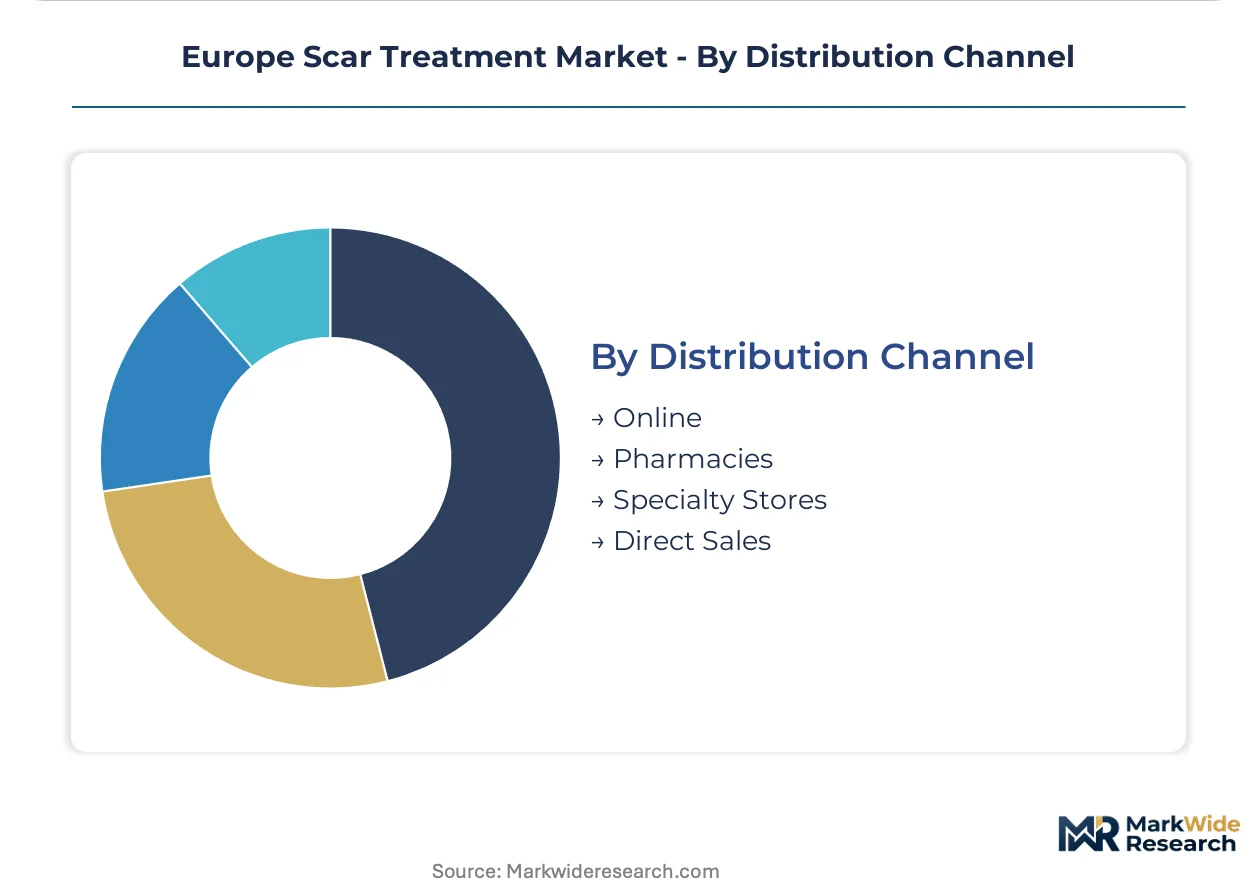
Distribution Channel:
Patient acquisition patterns are fragmenting across digital and traditional retail pathways.
- Pharmacies:Community and hospital pharmacy networks retain dominance for silicone gel and sheet distribution, with pharmacist counseling influencing product selection in France and Germany.
- Online:Direct-to-patient e-commerce is compressing traditional retail margins, with specialized scar care platforms capturing subscription-based recurring revenue in the United Kingdom.
- Specialty Stores:Medical supply retailers and aesthetic clinic retail extensions serve patient populations seeking professional-grade home care products.
- Direct Sales:Device manufacturers maintain field sales organizations for laser system placement and service contract negotiation with hospital procurement departments.
Pharmacies retain volume leadership. Online channels are gaining share fastest as telemedicine-integrated care models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments and private clinic chains concentrate purchasing power across Western Europe, with reimbursement pathways and EU MDR compliance timelines determining vendor access. Germany, France, and the United Kingdom anchor device placement volumes, while Eastern European markets present expansion vectors for ambulatory service networks.
Germany
Aesthetic medicine adoption and post-surgical scar management reimbursement outpace European peers, with statutory health insurance covering hypertrophic interventions in hospital burn units. BfArM oversight of laser device classification under EU MDR has concentrated notified body capacity in Berlin and Munich. The Rhine-Ruhr corridor hosts consolidated dermatology clinic chains that negotiate group purchasing contracts for fractional laser systems.
France
Social media-influenced self-referral for acne scar revision is compressing traditional GP gatekeeper roles, particularly among patients under 35. ANSM pharmacovigilance requirements for silicone gel formulations exceed baseline EU standards, elevating documentation burdens for pharmacy channel entrants. The Île-de-France region concentrates aesthetic clinic density, with Paris-based practices capturing premium positioning for combination laser-injectable protocols.
United Kingdom
NICE technology appraisal pathways determine NHS reimbursement eligibility for novel scar therapies, creating a two-tier market alongside private aesthetic channels. MHRA recognition of EU MDR certificates post-Brexit has streamlined continued market access for CE-marked devices. London and Manchester dermatology networks are piloting telemedicine-integrated home care models that bypass traditional pharmacy retail.
Italy
Self-drying silicone gel variants are displacing traditional sheet formats in pharmacy channels, driven by patient preference for discrete daytime wear. AIFA pricing negotiations for hospital-procured laser equipment extend procurement cycles by 6-9 months versus Northern European benchmarks. Lombardy and Emilia-Romagna host the densest concentrations of private aesthetic clinics offering bundled post-surgical scar packages.
Poland
Private dermatology networks are expanding laser-based scar revision services beyond Warsaw and Kraków into secondary cities with limited historical access. The national pharmaceutical regulator enforces REACH documentation requirements for silicone imports that favor established EU suppliers over Asian manufacturers. The Silesian metropolitan area is emerging as a regional hub for medical tourism-driven aesthetic procedures.
Europe Scar Treatment Market Competitive Landscape
Player mix skews toward diversified wound care conglomerates and specialized aesthetic device manufacturers. Three tiers structure competitive positioning: hospital channel incumbents with institutional procurement relationships, clinic-focused laser system vendors with service-dependent revenue models, and pharmacy channel formulators competing on formulation wear-time properties. Consolidation pressure is elevating as EU MDR compliance costs force portfolio rationalization among mid-tier device manufacturers.
Within the hospital channel tier, Smith & Nephew PLC and Molnlycke Health Care AB occupy positions reflecting wound care heritage extension into post-surgical scar management. Among specialized aesthetic device manufacturers, Lumenis Be Ltd and Alma Lasers exemplify the laser system archetype facing F-Gas Regulation redesign constraints. Merz Pharma GmbH & Co. KGaA represents the injectable therapy specialization vector, anchoring a position through corticosteroid and filler-based scar interventions.
| Leading Market Players |
|---|
| Smith & Nephew PLC |
| Merz Pharma GmbH & Co. KGaA |
| Molnlycke Health Care AB |
| Lumenis Be Ltd |
| Cynosure LLC |
| Perrigo Company PLC |
| Suneva Medical Inc |
| Alma Lasers |
| Sientra Inc |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with German notified bodies lock in CE marking access and price visibility for laser device manufacturers navigating EU MDR transition bottlenecks. These arrangements tether procurement costs to certification queue position while insulating compliant vendors from spot-market volatility for silicone polymer feedstock.
Pricing Analysis
Cost-plus contracts indexed to medical-grade silicone monomer spot prices dominate raw material procurement for gel and sheet manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified hospital-grade supply from pharmacy-channel formulations and private-label economy variants. Pricing pressure stems from F-Gas Regulation compliance redesign costs for laser cooling systems. Home care channels exhibit highest price sensitivity, while hospital burn units prioritize certification grade over unit cost.
Supply Chain Analysis
Notified body certification queues in Germany and the Netherlands constitute the primary regulatory chokepoint for laser device market entry. Silicone polymer supply draws from Germany, Belgium, and France for medical-grade formulations, with Asian contract manufacturers feeding economy-tier pharmacy products. Raw material dependencies center on chlorosilane precursors, platinum catalysts, and hydrofluorocarbon cooling agents. Single-source vulnerability concentrates in platinum-group metal supply for catalytic cross-linking. Distribution runs through hospital procurement consortia, pharmacy wholesale networks, and direct-to-patient e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face acute substitution pressure from next-generation self-drying gel formulations displacing traditional silicone sheet protocols in outpatient settings. Defense requires preemptive portfolio repositioning before formulation chemistry advantages erode mechanical sheeting's hospital formulary lock.
For Market Incumbents: Fortify hospital channel dominance through backward integration into REACH-compliant silicone synthesis, eliminating contract manufacturer dependency. Secure multi-year GPO contracts with German clinic chains before notified body bottlenecks ease and new laser vendors achieve CE marking. Prioritize corticosteroid-eluting combination product R&D to defend against standalone gel formulation substitution.
For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Eastern Europe offers lowest-barrier entry for laser device manufacturers lacking legacy certification. Poland's expanding private dermatology networks present underpenetrated demand for fractional scar revision systems. Target ambulatory surgery centers in France and the Netherlands with bundled aesthetic package positioning, bypassing hospital procurement complexity.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier device manufacturers with notified body certification already secured but lacking capital for F-Gas Regulation redesign completion. Long-term viability hinges on convergence capability across energy-based, mechanical, and pharmaceutical modalities. Monitor national health technology assessment outcomes in France and the United Kingdom as inflection signals for reimbursement-driven demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Notified body certification under EU MDR unlocks hospital procurement contracts across Germany and France. |
| Backward Integration | In-house silicone polymer synthesis insulates margin from REACH compliance cost escalation in feedstock supply. |
| Combination Product Development | Corticosteroid-eluting sheeting commands premium positioning in burn unit formularies versus standalone mechanical devices. |
| Telemedicine Platform Launch | Remote monitoring subscriptions capture recurring revenue from home care patients bypassing pharmacy retail channels. |
| Eastern European Clinic Partnership | Poland and Romania networks expand addressable market for laser-based revision beyond saturated Western European capitals. |
Research Methodology
Desk research of EU MDR guidance documents, REACH substance dossiers, and national reimbursement databases preceded structured interviews with hospital procurement managers, dermatology clinic directors, notified body certification officers, and silicone polymer suppliers. Primary fieldwork with biomedical engineers and GPO contracts managers validated secondary findings from EMA combination product filings and hospital tender records. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data.
Variance decomposition across product type, therapy area, end user, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segmented procedure volume trajectories, price index movements, and channel mix evolution. Forecast inputs incorporated EU MDR transition timelines, F-Gas Regulation implementation phases, and national health technology assessment pipeline status.
Decision-makers should treat outputs as directional under assumptions of stable notified body capacity and unchanged REACH polymer standards; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as reimbursement fragmentation patterns and laser technician certification scalability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Global Dermatology Cro Market
Dermatology
Atopic Dermatitis Treatment Market
Dermatology
Darier Disease Drugs Market
Dermatology
Keratoacanthoma Market
Dermatology
Immunodermatology Market
Dermatology
Acne Vulgaris Treatment Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Hyperpigmentation Treatment Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Microneedling Market
Dermatology
Global Radiodermatitis Market
Dermatology
Japan Scar Treatment Market
Dermatology
Global Onychomycosis Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Global Dermatological Therapeutics Market
Dermatology
Global Veterinary Dermatology Drugs Market