
 North America Traumatic Brain Injuries Assessment Market | 2026-2036
North America Traumatic Brain Injuries Assessment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Traumatic Brain Injuries Assessment Market Insights
The FDA's breakthrough device designation pathway is recalibrating how developers prioritize portable neurodiagnostic submissions. Abbott Laboratories leverages its cardiac monitoring infrastructure to extend into wearable brain injury detection. BrainScope, Inc. specializes in handheld electroencephalography for emergency department triage. InfraScan, Inc. anchors its position with near-infrared spectroscopy devices for hematoma detection.
Traumatic brain injuries assessment encompasses the clinical evaluation, imaging, and cognitive testing protocols used to diagnose and monitor structural and functional brain damage following head trauma. Computed tomography scanning remains the first-line imaging modality for detecting intracranial hemorrhage, while magnetic resonance imaging provides superior soft-tissue resolution for diffuse axonal injury. Neuropsychological testing captures the largest margin pool due to repeat-billing potential across recovery timelines. Biomarker-based assessment represents the fastest-growing technology segment as blood-based glial fibrillary acidic protein assays near clinical integration. Wearable devices in home care settings are displacing some rehabilitation facility volumes as remote monitoring protocols mature.
The FDA governs premarket clearance for all diagnostic devices, while the Centers for Medicare and Medicaid Services determines reimbursement codes that shape provider adoption economics. State-level concussion legislation in Texas and California mandates scholastic athletic screening, creating institutional demand for baseline cognitive assessment platforms. Trauma center designation requirements from the American College of Surgeons drive capital equipment decisions. Stakeholders must monitor how the FDA's evolving software-as-a-medical-device framework reclassifies algorithm-driven interpretation tools.
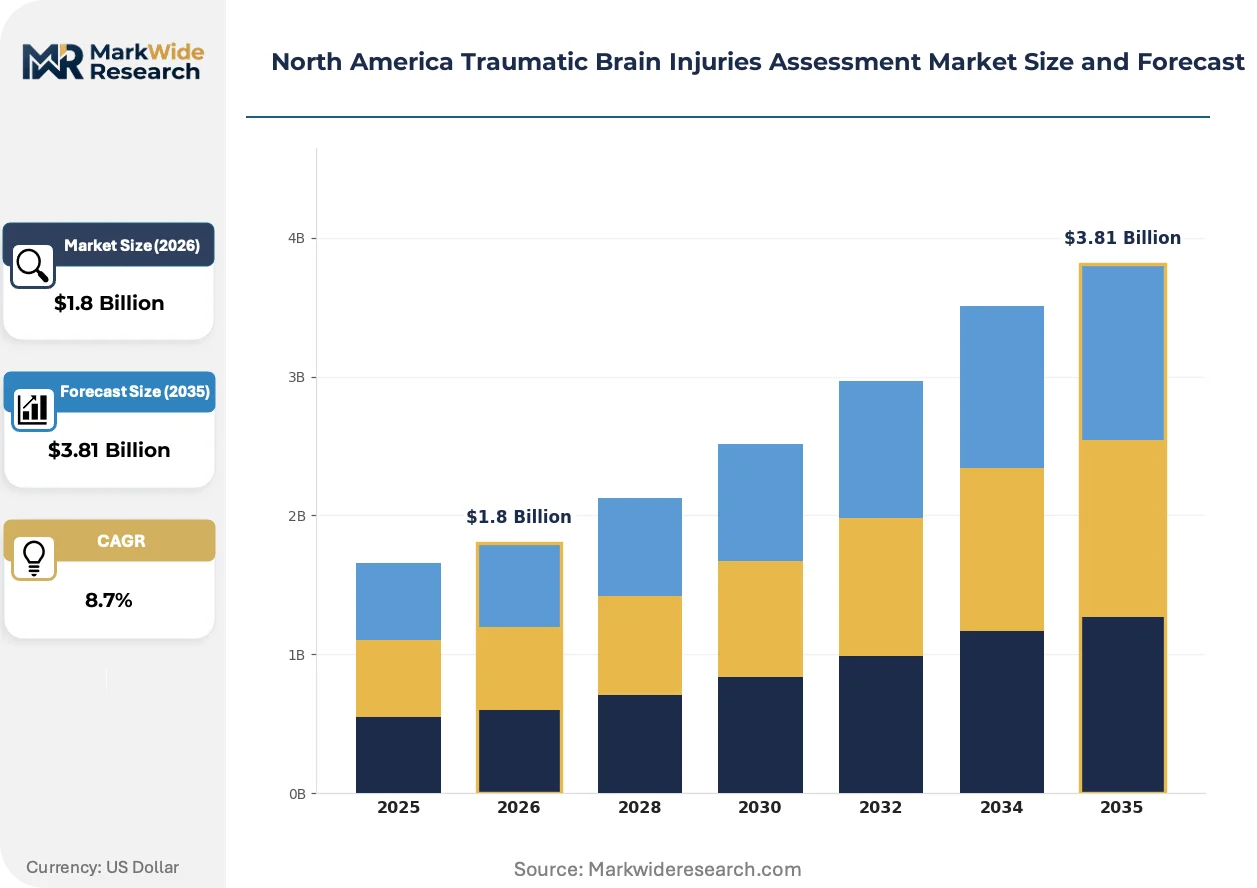
Market Dynamics
The FDA's breakthrough device designation pathway is compressing clearance timelines for portable neurodiagnostic tools, while state concussion mandates in Texas and California institutionalize baseline cognitive testing across scholastic athletics.
Growth Catalysts
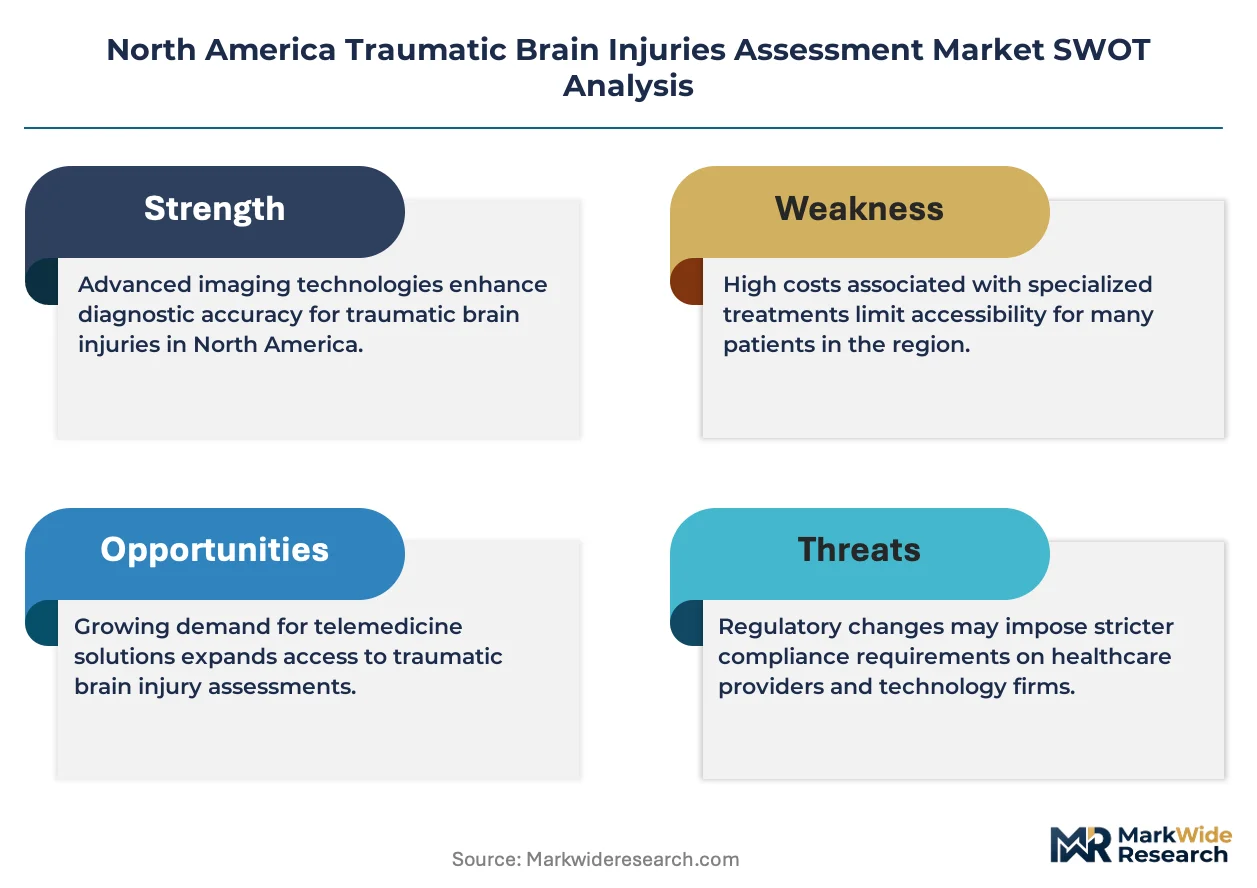
- State Legislative Mandates:Texas and California laws require scholastic athletic concussion screening, creating institutional demand for baseline cognitive assessment platforms across school districts.
- Biomarker Assay Integration:Blood-based glial fibrillary acidic protein tests are nearing clinical validation, expanding diagnostic capabilities beyond imaging-dependent protocols.
- Trauma Center Designation Standards:American College of Surgeons requirements drive capital equipment procurement across California's trauma center network and Texas Medical Center cluster.
Market Restraints
- Reimbursement Code Fragmentation:Centers for Medicare and Medicaid Services coverage determinations for novel biomarker tests create payment uncertainty that slows provider adoption.
- Technical Limitation of Wearables:Current portable electroencephalography devices lack sensitivity for diffuse axonal injury detection, restricting their utility to emergency department triage.
- Specialized Workforce Scarcity:Neuropsychological testing requires certified practitioners, creating service delivery bottlenecks in rural markets across the US and Canada.
Strategic Opportunities
- Home Care Monitoring Expansion:Remote patient monitoring protocols for post-acute TBI recovery are displacing rehabilitation facility volumes in suburban US markets.
- Software-as-Medical-Device Reclassification:FDA's evolving algorithm interpretation framework creates pathways for AI-driven diagnostic tools to secure standalone regulatory status.
- Sports Medicine Program Expansion:Collegiate athletic departments are broadening concussion baseline testing protocols, generating recurring revenue streams for cognitive assessment platforms.
Industry Challenges
- Integration Complexity with Legacy PACS:Portable neurodiagnostic tools face interoperability hurdles with hospital picture archiving and communication systems, delaying deployment timelines.
- Neuropsychologist Certification Bottlenecks:The limited pipeline of board-certified specialists constrains scaling of repeat-billing assessment services across recovery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Traumatic Brain Injuries Assessment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Assessment Type: CT Scan, MRI, Neuropsychological Testing, Cognitive Assessment Patient Category: Pediatric, Adolescent, Adult, Geriatric Care Setting: Emergency Room, Outpatient Clinic, Rehabilitation Facility, Home Care Technology: Digital Imaging, Telemedicine, Biomarkers, Wearable Devices |
| Companies Covered | Abbott Laboratories, BrainScope, Inc., InfraScan, Inc., Oculogica, Integra LifeSciences, Nihon Kohden Corp., Raumedic AG, Natus Medical, Inc., Compumedics Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Traumatic Brain Injuries Assessment Market Trends and Innovations
Portable diagnostic modalities are converging with biomarker science to challenge imaging-centric assessment paradigms. Regulatory acceleration and remote care protocols are reshaping where and how traumatic brain injuries are evaluated.
Handheld electroencephalography combined with near-infrared spectroscopy is consolidating emergency department triage workflows into single-device protocols. California trauma centers and Texas Medical Center emergency departments are piloting these integrated platforms. This convergence is consolidating vendor relationships and compressing procurement cycles around multifunction systems rather than discrete imaging and laboratory workflows.
FDA's breakthrough device designation pathway is accelerating premarket review timelines for algorithm-driven interpretation tools. The agency's software-as-a-medical-device framework is reclassifying standalone diagnostic algorithms, enabling faster clearance for blood-based biomarker integration. Portable neurodiagnostic developers are restructuring submissions to leverage this pathway, with hematoma detection and concussion assessment tools receiving priority review status.
Collegiate athletic departments and professional sports franchises are unbundling baseline cognitive testing from traditional healthcare procurement channels. Direct vendor relationships with sports medicine programs are displacing hospital-contracted neuropsychology services. This channel shift is most visible across California's Pac-12 conference institutions and Texas Big 12 athletic departments, where dedicated concussion protocols now operate outside standard referral networks.
North America Traumatic Brain Injuries Assessment Market Segmentation
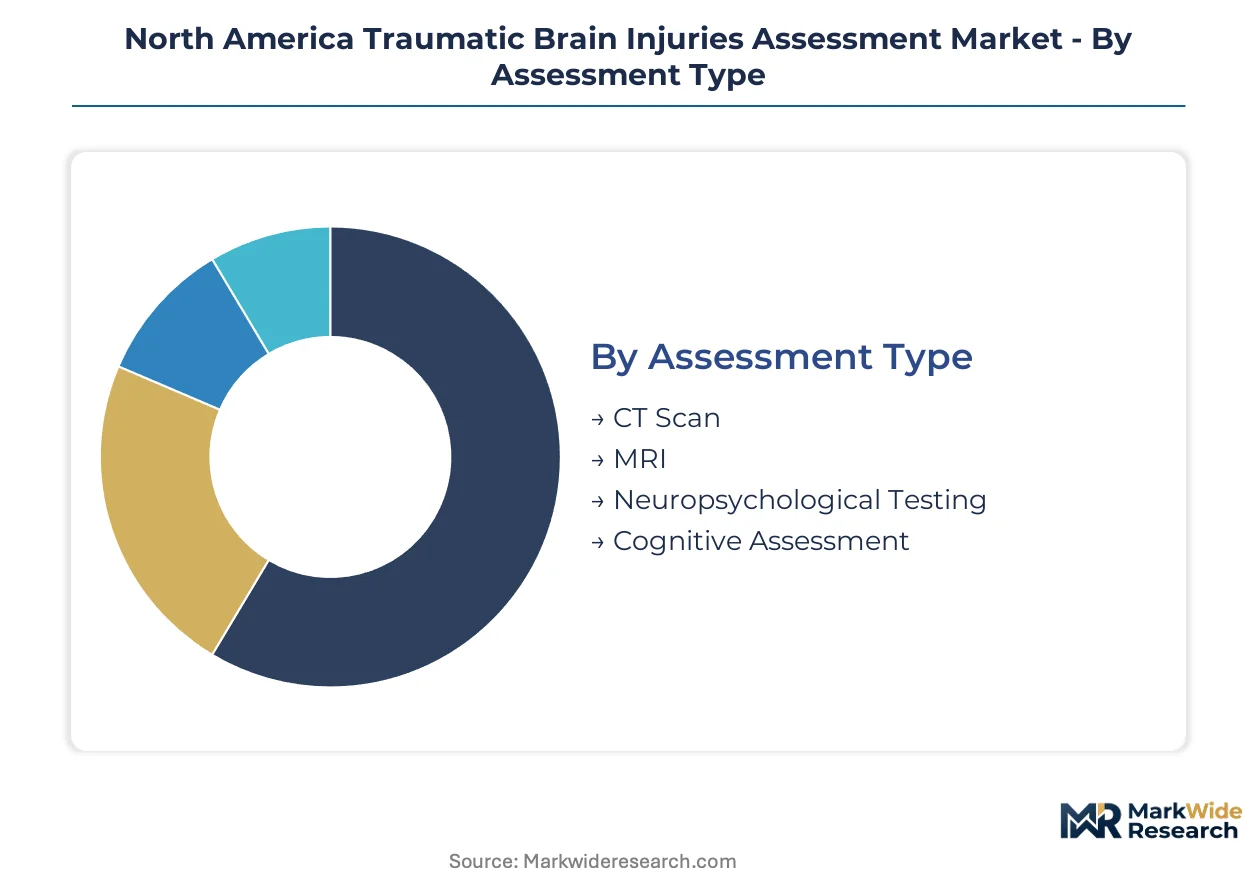
Segmentation in traumatic brain injuries assessment reveals how diagnostic workflows fragment across clinical environments, patient risk profiles, and technology maturation curves. Understanding these divisions exposes where procurement budgets concentrate and where regulatory acceleration is reshaping competitive entry points.
Assessment Type:
Technical sophistication and reimbursement density separate acute diagnostic modalities from longitudinal monitoring protocols across North American trauma networks.
- CT Scan:Computed tomography delivers rapid intracranial hemorrhage detection through ionizing radiation-based cross-sectional imaging. Demand concentrates in California's Level I trauma centers and Texas Medical Center emergency departments where ACS designation mandates 24-hour neuroradiology availability.
- Neuropsychological Testing:Standardized cognitive batteries measure attention, memory, and executive function through repeat-administration protocols. Texas and California scholastic athletic programs drive institutional procurement as state concussion mandates require baseline and post-injury comparison testing across school districts.
- MRI:Magnetic resonance imaging provides superior soft-tissue resolution for diffuse axonal injury without radiation exposure.
- Cognitive Assessment:Computerized platforms deliver rapid screening through automated scoring algorithms for emergency triage and sports medicine applications.
Mature deployment sits with CT Scan. Newer deployment is concentrated in Cognitive Assessment.
Patient Category:
Risk stratification and recovery trajectory variation create distinct service delivery requirements across age cohorts.
- Adolescent:Scholastic and collegiate athletic participation drives baseline testing volume through mandatory screening protocols. Texas and California state laws institutionalize cognitive assessment requirements across high school and university sports programs, creating recurring revenue streams for platform vendors.
- Geriatric:Fall-related TBI incidence and polypharmacy complications elevate diagnostic complexity in Medicare populations. Demand clusters in Florida retirement communities and Arizona senior care networks where remote monitoring protocols are displacing facility-based rehabilitation.
- Pediatric:Developing neural plasticity requires specialized normative databases and family-centered intervention protocols.
- Adult:Occupational injury and motor vehicle accident cases dominate acute presentation patterns.
Volume concentration favors Adolescent. Margin expansion is strongest in Geriatric.
Care Setting:
Site-of-care economics and reimbursement differentials are redistributing assessment volume across institutional and ambulatory environments.
- Emergency Room:Acute triage protocols demand rapid hemorrhage exclusion through CT imaging and emerging handheld EEG devices. California trauma centers and Texas Medical Center emergency departments pilot integrated portable diagnostic platforms that consolidate multiple assessment modalities.
- Home Care:Remote patient monitoring protocols for post-acute TBI recovery leverage wearable devices and telemedicine platforms. Suburban US markets see rehabilitation facility volumes displaced as CMS reimbursement shifts favor home-based care models.
- Outpatient Clinic:Scheduled follow-up and concussion management occur through neurology and sports medicine practices.
- Rehabilitation Facility:Intensive cognitive and physical therapy protocols address moderate-to-severe injury recovery.
Capital intensity peaks in Emergency Room. Growth velocity is climbing fastest in Home Care.
Technology:
Regulatory pathway acceleration and algorithm maturation are reordering competitive positioning across diagnostic technology platforms.
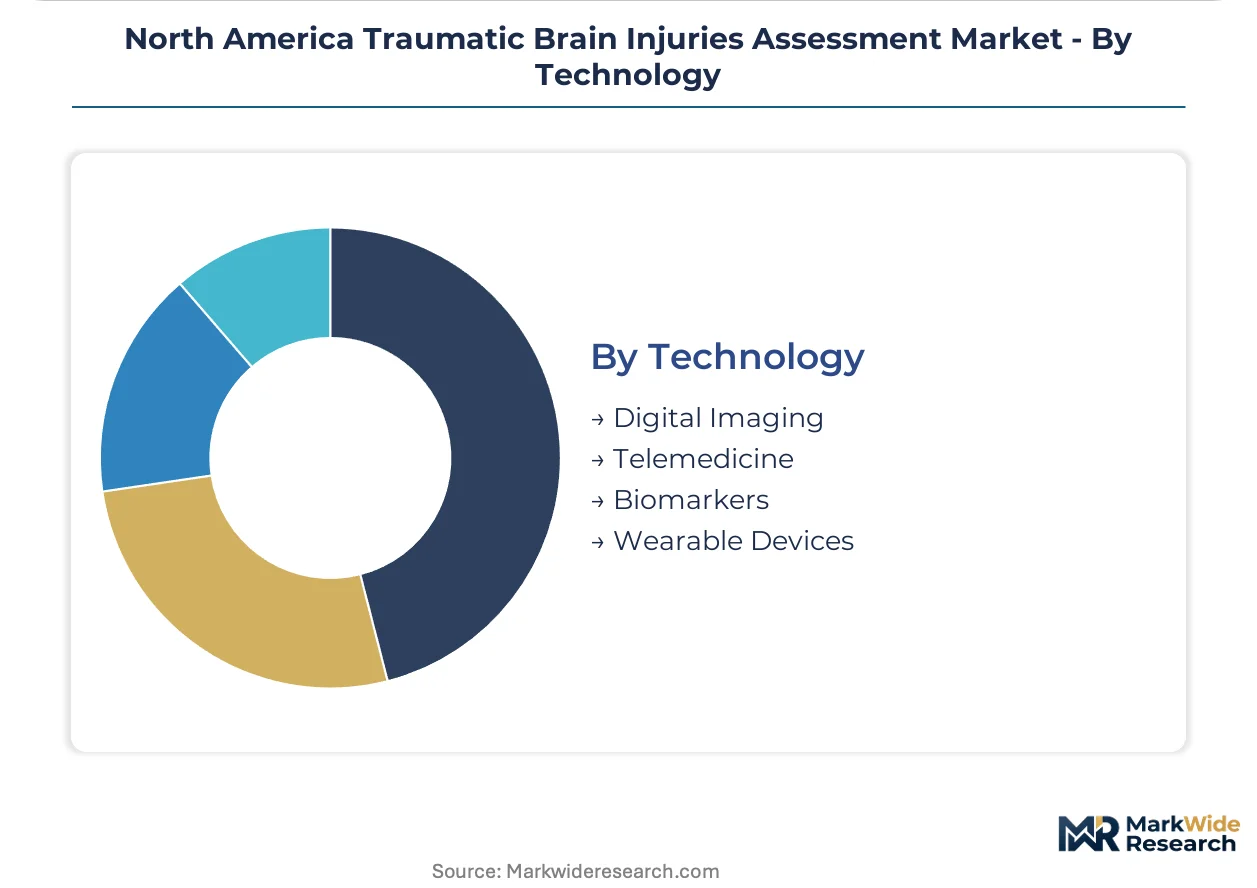
- Biomarkers:Blood-based glial fibrillary acidic protein assays enable rapid hematoma risk stratification without imaging radiation exposure. FDA breakthrough device designation is compressing premarket review timelines for developers integrating biomarker interpretation into emergency triage workflows.
- Wearable Devices:Portable electroencephalography and near-infrared spectroscopy systems deliver point-of-care neurological monitoring. Texas and California sports medicine programs adopt direct vendor relationships for concussion baseline testing outside traditional hospital procurement channels.
- Digital Imaging:Picture archiving and communication system integration remains the backbone of trauma center diagnostic infrastructure.
- Telemedicine:Virtual consultation platforms extend specialist access to rural markets with neuropsychologist certification bottlenecks.
Installed base dominance rests with Digital Imaging. Steepest expansion trajectory belongs to Biomarkers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of portable neurodiagnostic devices concentrates in California and Massachusetts manufacturing corridors, while clinical consumption spreads across trauma center networks in Texas, Florida, and the US Northeast. Canada imports the majority of advanced assessment platforms from US suppliers. Mexico's market remains nascent, with demand confined to border state medical centers serving cross-border patient flows.
United States
California's trauma center network and Texas Medical Center cluster absorb the highest equipment procurement volumes under American College of Surgeons designation requirements. FDA breakthrough device designation accelerates premarket review for developers targeting these hubs. The Southeast sees expanding adoption as Florida retirement communities pilot remote monitoring protocols for geriatric fall-related TBI.
Canada
Provincial health authorities in Ontario and Quebec drive institutional purchasing through centralized procurement frameworks. Health Canada regulates premarket approval for diagnostic devices entering the Canadian market. Toronto's academic medical centers and Vancouver's trauma networks concentrate adoption of biomarker-integrated assessment platforms.
Mexico
Border state medical centers in Tijuana and Ciudad Juárez serve cross-border patient flows from California and Texas trauma networks. COFEPRIS, the country's national health regulator, oversees device registration timelines that lag US FDA pathways. Private hospital chains in Mexico City represent the primary domestic demand concentration for advanced neurodiagnostic equipment.
North America Traumatic Brain Injuries Assessment Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with established cardiac and neurological monitoring infrastructure. Tier-one participants leverage existing hospital procurement relationships to bundle brain injury assessment tools with broader neurocritical care portfolios. Mid-tier specialists concentrate on single-modality innovation—handheld electroencephalography, near-infrared spectroscopy, or blood-based biomarker platforms. Dominant competitive moves include FDA breakthrough pathway navigation for accelerated clearance and direct contracting with collegiate athletic departments outside traditional hospital supply chains.
Among US-based diversified manufacturers, Abbott Laboratories anchors the conglomerate tier with monitoring infrastructure extending into wearable detection formats. BrainScope, Inc. and InfraScan, Inc. exemplify the specialist archetype, occupying positions in handheld electroencephalography and near-infrared hematoma detection respectively. These three represent contrasting strategic postures: backward integration into established distribution versus focused modality innovation targeting emergency department triage workflows.
| Leading Market Players |
|---|
| Abbott Laboratories |
| BrainScope, Inc. |
| InfraScan, Inc. |
| Oculogica |
| Integra LifeSciences |
| Nihon Kohden Corp. |
| Raumedic AG |
| Natus Medical, Inc. |
| Compumedics Ltd. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FDA breakthrough pathway devices and legacy imaging platforms manifests in both procurement premiums and supply chain configurations across California and Texas trauma networks. Premium-tier portable neurodiagnostic tools command higher unit economics through accelerated regulatory clearance timelines, while standard-tier CT and MRI systems compete on capital lease structures and maintenance bundling.
Pricing Analysis
Margin tightening in portable device tiers reflects CMS reimbursement code fragmentation for novel biomarker tests. Three-tier pricing structure across premium breakthrough-designated devices, standard FDA-cleared platforms, and economy refurbished imaging systems dominates procurement. Price differentiation hinges on FDA clearance tier and after-sales algorithm update subscriptions. Hospital purchasing committees show highest price sensitivity, while collegiate athletic departments demonstrate lower sensitivity due to dedicated concussion protocol budgets.
Supply Chain Analysis
Freight cost escalation for precision optical components and semiconductor sensors from East Asian manufacturing hubs elevates landed costs for wearable EEG manufacturers. Component supply concentrates in Taiwan, South Korea, and Japan for microelectromechanical systems and near-infrared spectroscopy modules. Raw material dependencies include germanium substrates, indium gallium arsenide detectors, and medical-grade lithium polymer cells. Single-source vulnerability in MEMS foundry capacity represents the dominant structural risk. Distribution runs through GPO contracts with Vizient and Premier for hospital systems, alongside direct vendor relationships with collegiate athletic departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The traumatic brain injuries assessment market sits in a technology-transition phase as blood-based biomarker platforms displace imaging-dependent protocols for emergency triage workflows.
For Market Incumbents: Hedge against biomarker assay commoditization by securing exclusive GPO contracts with California's trauma center network and Texas Medical Center cluster. Deepen backward integration into algorithm interpretation software to capture recurring revenue from SaaS-tiered diagnostic platforms. Prioritize FDA breakthrough pathway submissions for hematoma detection tools to maintain pricing power against emerging blood-test competitors. For New Entrants and Emerging Players: Direct-to-collegiate athletic department channels offer the most penetrable white-space target, bypassing hospital procurement bottlenecks entirely. Remote patient monitoring protocols for post-acute TBI recovery in suburban Florida and Arizona senior care networks represent a second underdefended segment. Pursue software-as-medical-device standalone clearance to enable rapid deployment without hardware manufacturing scale. For Investors and Strategic Acquirers: Re-rating potential sits with biomarker-integrated platform developers given FDA breakthrough designation acceleration and CMS reimbursement pathway maturation. Long-term viability favors companies with dual capability in portable hardware and algorithm-driven interpretation software. Watch for Health Canada approval decisions as early inflection indicators for North American regulatory harmonization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Submission | Abbott Laboratories and BrainScope leverage accelerated review timelines for portable neurodiagnostic clearance. |
| Hospital System Partnership | InfraScan anchors near-infrared spectroscopy placement across California Level I trauma centers. |
| Software Companion Development | Biomarker assay developers build algorithm interpretation tools for emergency department triage workflows. |
| Reimbursement Strategy | CMS coverage determination lobbying shapes provider adoption economics for blood-based GFAP tests. |
| CE Marking Pathway | Canadian and Mexican market entry requires Health Canada and COFEPRIS alignment with FDA predicate devices. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with emergency medicine physicians, hospital procurement managers, biomedical engineers, and sports medicine directors combined with FDA 510(k) databases, CMS Medicare claims data, and GPO contract repositories. Bottom-up equipment procurement modeling triangulated against top-down trauma center capacity estimates.
Segment-level granularity modeled assessment type, patient category, care setting, and technology platform dimensions across the projection horizon. CAGRs derived from equipment replacement cycles, state legislative mandate implementation timelines, and biomarker assay clinical validation trajectories. Forecast inputs incorporated American College of Surgeons trauma designation requirements and collegiate athletic department concussion protocol expansion rates.
The model holds under stable FDA regulatory frameworks and CMS reimbursement continuity; deviation in biomarker coverage determinations or state mandate enforcement would shift volume projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Multiple Sclerosis Therapies Market
Neurology
Movement Disorder Market
Neurology
Brain Aneurysm Treatment Market
Neurology
Global Neuroblastoma Market
Neurology
Frontotemporal Disorders Treatment Market
Neurology
Argentina Neurology Devices Market
Neurology
Saudi Arabia Neurology Devices Market
Neurology
Tourette Syndrome Market
Neurology
Neurocognitive Assessment and Rehabilitation Market
Neurology
3D Neuroscience Market
Neurology
Neurology Devices Market
Neurology
Nerve Repair Market
Neurology
Neurological Biomarkers Market
Neurology
Demyelinating Diseases Therapeutics Market
Neurology
Pediatric Neurology Device Market
Neurology
Interventional Neurology Market