
 Modular Battery Pack Platforms for Skateboard EVs Market | 2026-2036
Modular Battery Pack Platforms for Skateboard EVs Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Battery Pack Platforms for Skateboard EVs Market Insights
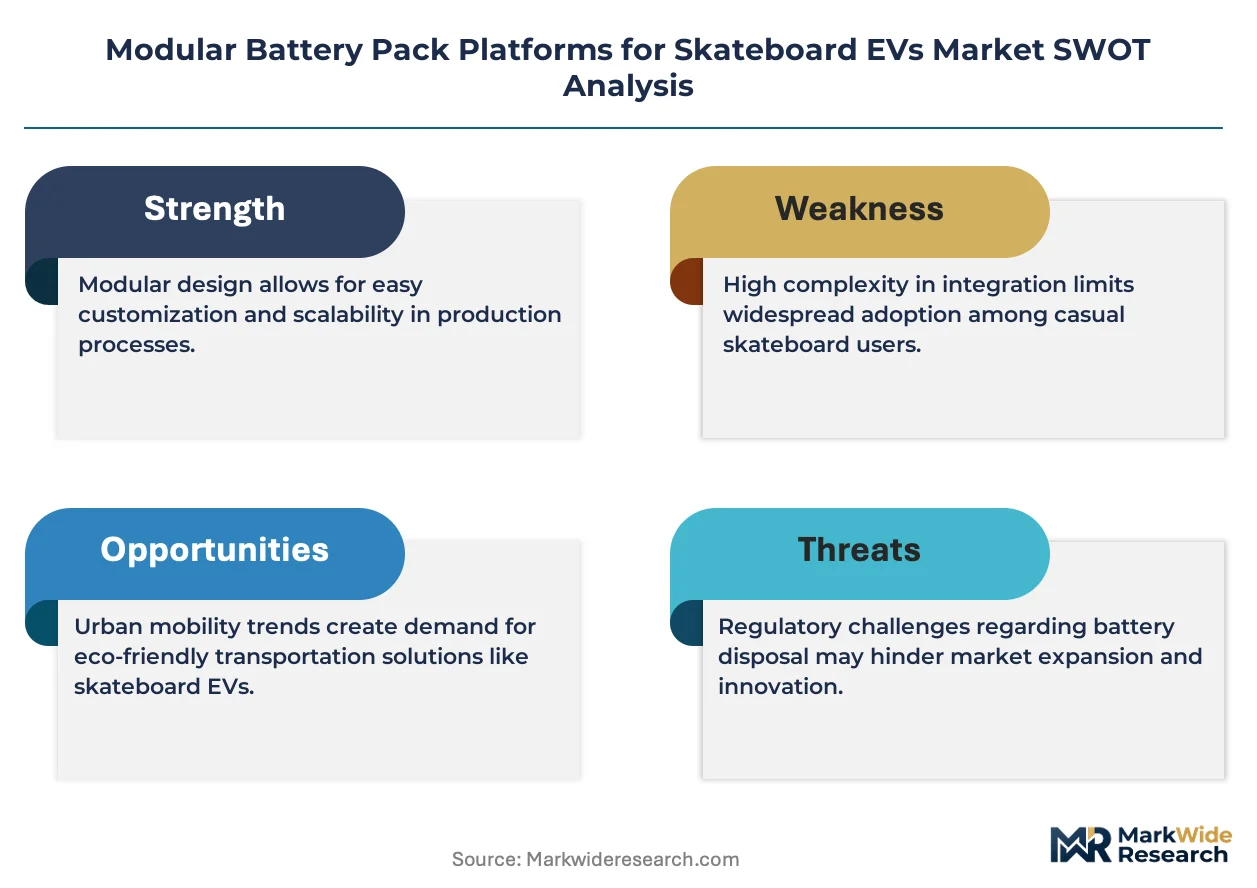
Cell-to-pack energy density above 200 Wh/kg is collapsing the cost-per-kilometer calculus for urban delivery fleets. Tesla leverages its 4680 cell architecture to sustain vertical control over thermal interfaces. Foxconn anchors contract manufacturing capacity across multiple OEM programs in Taiwan and Mexico. Hyundai Motor differentiates through integrated motor-battery-thermal modules that reduce assembly steps.
Modular battery pack platforms for skateboard EVs are structural chassis-integrated energy systems where standardized cell modules mount below the passenger cabin floor, typically achieving 400-800 V nominal voltage with liquid-cooled aluminum housings; their primary purpose is to decouple battery engineering from vehicle body design, enabling single-platform sourcing for multiple vehicle top-hats. Lithium-Ion chemistry dominates installed base owing to mature supply chains and recyclability infrastructure, while Solid-State formats represent the fastest-growing technology segment as manufacturers target elimination of thermal propagation barriers. Last-Mile Logistics applications command the deepest margin pools because fleet operators prioritize total-cost-of-ownership contracts over upfront hardware pricing.
China's MIIT enforces GB/T battery-swap interoperability standards that dictate connector geometry and communication protocols, while the EU F-Gas Regulation restricts refrigerant selection in thermal regulation systems, directly conditioning platform design choices for European-market vehicles. The US NHTSA crashworthiness standards for underbody battery protection create divergent reinforcement requirements that fragment common-platform economics. Stakeholders must monitor regulatory divergence between major automotive markets as a primary determinant of platform architecture fungibility.
Market Dynamics
Cell-to-pack integration is compressing platform engineering cycles by eliminating module-level redundancy, forcing suppliers to retool aluminum casting and thermal interface lines simultaneously.
Growth Catalysts
- Last-Mile Fleet Electrification:Urban delivery operators in China's Yangtze River Delta are consolidating orders for swappable-pack vans under MIIT GB/T interoperability mandates.
- F-Gas Thermal Regulation:The EU's F-Gas Regulation on refrigerant selection is accelerating liquid-cooled aluminum housing adoption across European-market platform designs.
- Cell Chemistry Maturation:Solid-state electrolyte research is eliminating thermal propagation barriers that previously required redundant module compartmentalization.
Market Restraints
- Cathode Material Volatility:Nickel and lithium carbonate spot price swings destabilize pack cost forecasting for contract manufacturers.
- Single-Source Tooling Concentration:Large-format cell winding equipment suppliers cluster in South Korea and Japan, creating procurement bottlenecks.
- Crashworthiness Fragmentation:Divergent NHTSA underbody protection standards versus UN ECE requirements prevent true global platform fungibility.
Strategic Opportunities
- Indian Commercial Vehicle Electrification:The country's PLI scheme for advanced chemistry cell manufacturing is opening localized pack assembly capacity near Chennai and Pune.
- Battery-as-a-Service Channel Models:Fleet operators are unbundling pack ownership from vehicle acquisition, creating recurring revenue streams for thermal management specialists.
- Silicon-Carbide Inverter Convergence:800V architectures paired with SiC power electronics are enabling faster charging protocols that differentiate premium platform tiers.
Industry Challenges
- Thermal Interface Engineering Talent Scarcity:Pack manufacturers compete for finite pools of phase-change material and cold-plate design specialists.
- Homologation Timeline Compression:UN ECE R100 revision cycles and regional crash-test protocols extend platform validation schedules beyond vehicle program deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Battery Pack Platforms for Skateboard EVs Market |
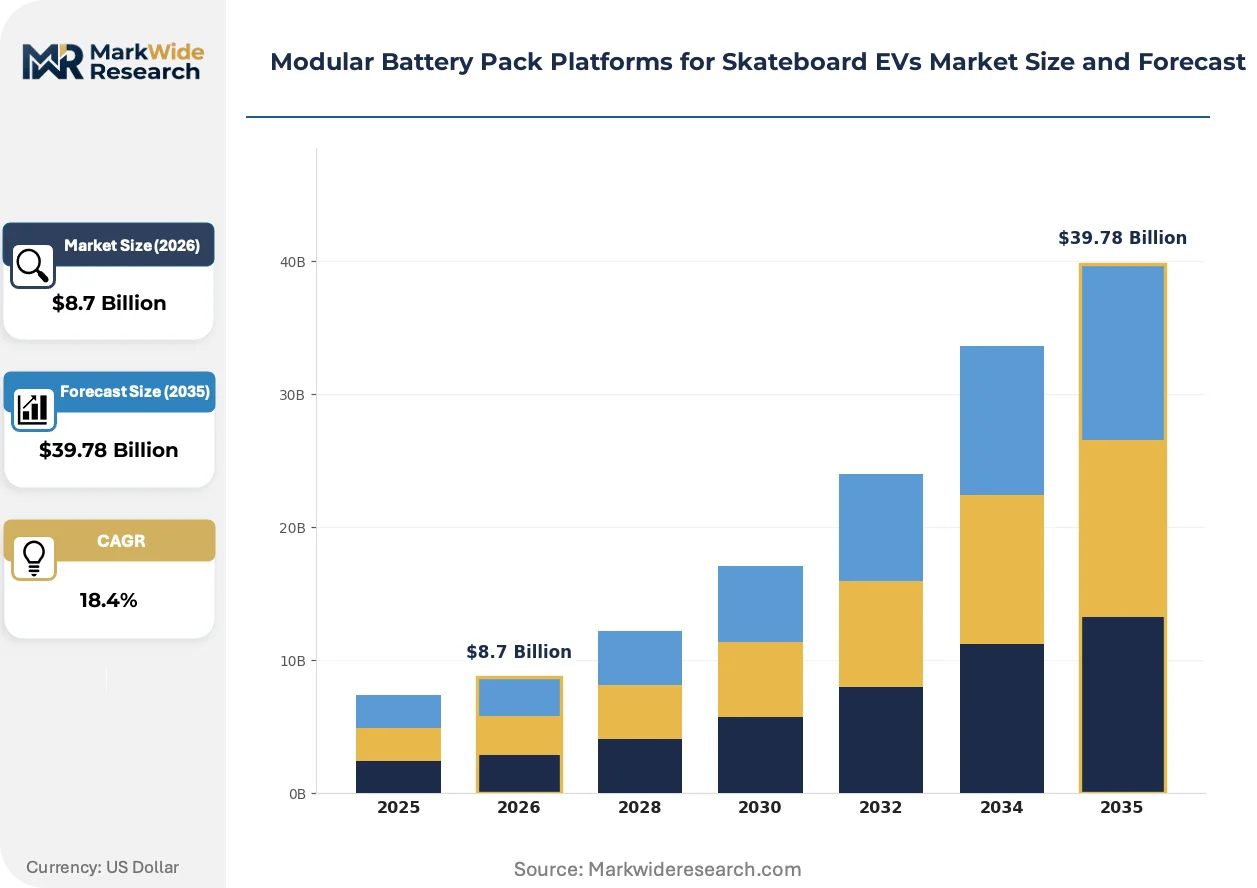
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lithium-Polymer, Zinc-Air Technology: Battery Management System, Thermal Regulation, Wireless Charging, Fast Charging, Cell Balancing Application: Personal Mobility Devices, Electric Motorcycles, Light Delivery Vehicles, Autonomous Transporters, Last-Mile Logistics End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers, Rental Operators |
| Companies Covered | Tesla, Foxconn, Hyundai Motor, General Motors, Rivian, Audi, Toyota, Volkswagen, REE Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Battery Pack Platforms for Skateboard EVs Market Trends and Innovations
Platform architectures are converging around standardized cell formats that sacrifice some customization latitude for manufacturing velocity and supplier interchangeability.
Cell-to-pack structural batteries are supplanting traditional module-and-frame assemblies by bonding cells directly to the skateboard floorpan, eliminating steel reinforcements. Last-mile logistics operators are specifying these architectures for delivery van programs where payload density determines route economics. The shift is compressing pack height by 30-40 millimeters, enabling lower step-in heights that reduce driver injury claims.
China's MIIT GB/T battery-swap standards are mandating connector geometry and CAN communication protocols that lock out non-compliant platform designs. Domestic OEMs are pre-certifying packs to these specifications before export, while European entrants must maintain dual-stack software to serve both markets. The regulation is fragmenting thermal management strategies as swap-compatible packs require quick-disconnect cooling loops.
Fleet procurement departments are consolidating vendor relationships around total-cost-of-ownership metrics rather than upfront pack pricing. Third-party battery lifecycle managers are inserting themselves between OEMs and operators, underwriting residual value risk. This restructuring is most visible in Germany's urban freight corridors where logistics cooperatives pool charging infrastructure and swap station access.
Modular Battery Pack Platforms for Skateboard EVs Market Segmentation
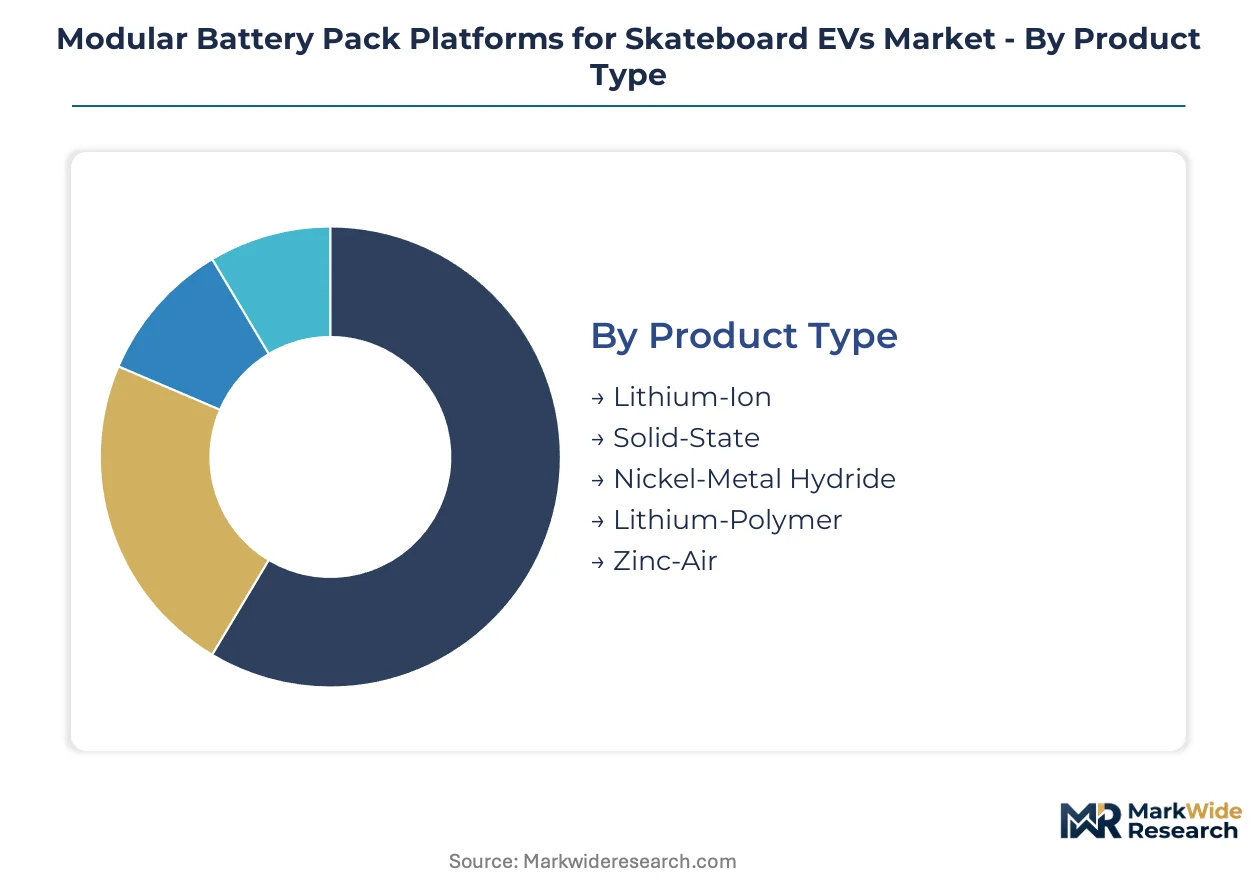
Segmentation in modular battery pack platforms reveals how technical specifications, regulatory requirements, and procurement economics fragment the addressable market. Each dimension carries distinct margin structures and homologation burdens that reshape supplier positioning.
Product Type:
The EU F-Gas Regulation on thermal management refrigerants and China's MIIT battery-swap standards create divergent chemistry certification pathways that segment manufacturing investment.
- Lithium-Ion:Mature supply chains and established recyclability infrastructure dominate installed base economics. Demand concentrates in China's Yangtze River Delta manufacturing corridor where cell-to-pack integration factories cluster near vehicle assembly plants, constrained by nickel and lithium carbonate spot price volatility.
- Solid-State:Elimination of thermal propagation barriers enables structural battery designs without redundant module compartmentalization. European-market platform designs are accelerating adoption under pressure from UN ECE R100 revision cycles and F-Gas thermal regulation mandates.
- Nickel-Metal Hydride:Legacy chemistry persists in cost-sensitive personal mobility applications with limited thermal management requirements.
- Lithium-Polymer:Flexible form factors serve niche autonomous transporter designs requiring non-rectangular pack geometries.
- Zinc-Air:Experimental chemistry targets ultra-low-cost segments in emerging markets with minimal infrastructure requirements.
Lithium-Ion handles the majority of throughput; Solid-State is gaining share fastest on the back of European regulatory pressure.
Technology:
Cost tier differentiation separates premium 800V architectures from commodity 400V systems, with silicon-carbide inverter convergence reshaping thermal management investment priorities.
- Battery Management System:Software-defined state-of-charge algorithms and predictive thermal modeling differentiate fleet operator contracts. Last-mile logistics procurement departments prioritize total-cost-of-ownership underwriting from third-party lifecycle managers over hardware specifications.
- Thermal Regulation:Liquid-cooled aluminum housings with phase-change material interfaces dominate European-market designs under F-Gas refrigerant restrictions. Talent scarcity for cold-plate engineering specialists constrains supplier expansion timelines.
- Wireless Charging:Inductive pad integration requires standardized ground clearance protocols that conflict with cell-to-pack height compression targets.
- Fast Charging:800V architectures paired with SiC power electronics enable premium platform tier differentiation.
- Cell Balancing:Active balancing circuits extend pack longevity for battery-as-a-service revenue models.
Thermal Regulation commands the deepest engineering investment; Fast Charging shows the steepest expansion trajectory among premium tier deployments.
Application:
Volume concentration in commercial fleet procurement is displacing consumer-driven demand patterns, with route economics dictating payload density specifications.
- Last-Mile Logistics:Urban delivery operators consolidate orders for swappable-pack vans under MIIT GB/T interoperability mandates. China's Yangtze River Delta logistics cooperatives pool charging infrastructure and swap station access, compressing total-cost-of-ownership calculations.
- Light Delivery Vehicles:Payload density determines route economics for cell-to-pack structural batteries that eliminate 30-40 millimeters of pack height. German urban freight corridors drive specification convergence.
- Personal Mobility Devices:Price-sensitive consumer segments prioritize upfront hardware pricing over lifecycle contracts.
- Electric Motorcycles:Two-wheeler platforms require compact thermal interfaces with limited liquid cooling capacity.
- Autonomous Transporters:Unmanned operation demands predictive battery health monitoring with minimal human intervention protocols.
Last-Mile Logistics anchors procurement volume; Light Delivery Vehicles are climbing the fastest on fleet electrification mandates.
End User:
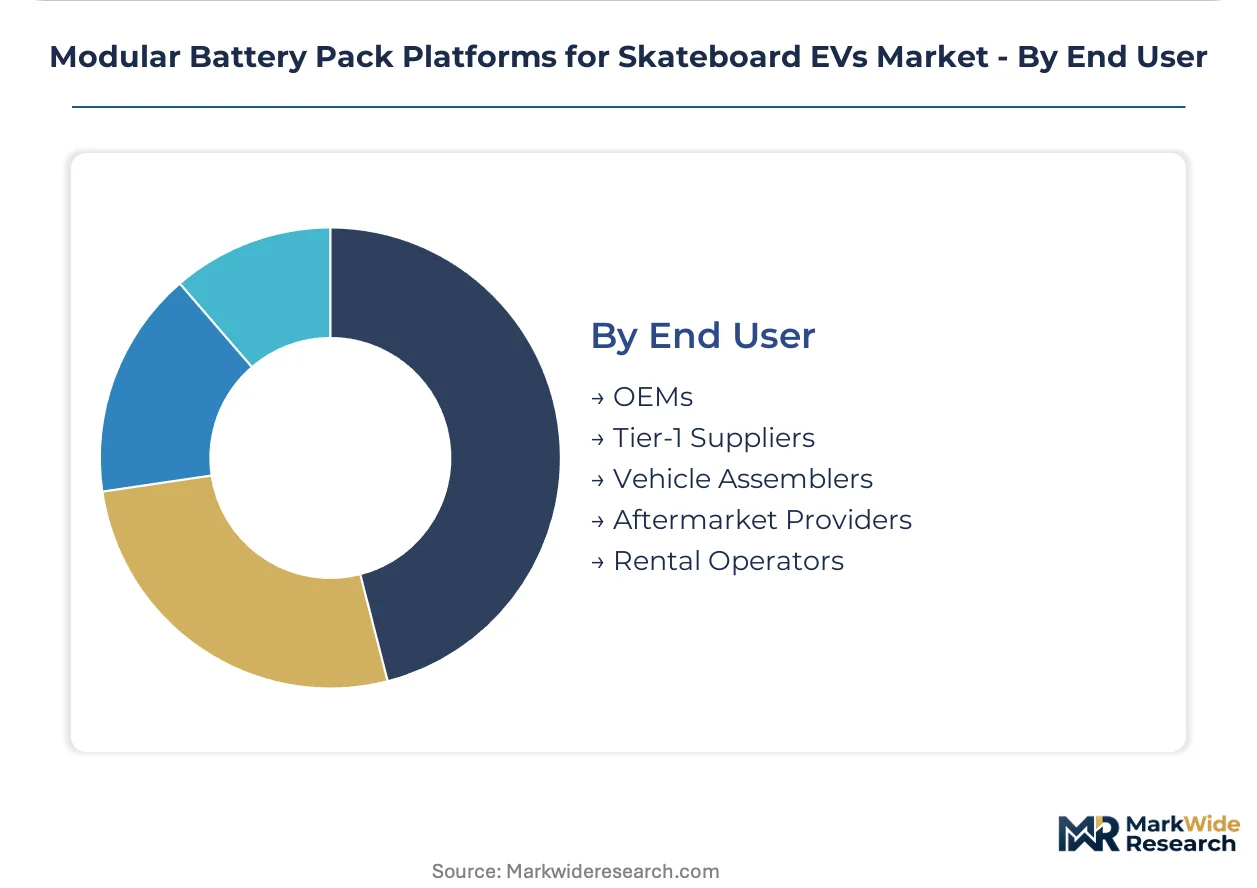
Customer type fragmentation separates captive OEM programs from open supplier markets, with contract manufacturing concentration reshaping margin capture.
- OEMs:Vertical control over thermal interfaces sustains differentiation through integrated motor-battery-thermal modules that reduce assembly steps. Tesla's 4680 cell architecture exemplifies in-house production strategies.
- Tier-1 Suppliers:Foxconn anchors contract manufacturing capacity across multiple OEM programs in Taiwan and Mexico, consolidating procurement bottlenecks from South Korean and Japanese winding equipment suppliers.
- Vehicle Assemblers:Final integration points face homologation timeline compression from UN ECE R100 revisions.
- Aftermarket Providers:Swap-compatible pack retrofits require quick-disconnect cooling loop engineering.
- Rental Operators:Battery-as-a-service channel models unbundle pack ownership from vehicle acquisition, creating recurring revenue streams.
Tier-1 Suppliers handle the majority of outsourced throughput; Rental Operators are expanding most quickly on unbundled ownership models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell-to-pack integration factories cluster along China's Yangtze River Delta, where suppliers retool aluminum casting lines to serve multiple OEM programs simultaneously. This concentration is compressing engineering cycles and forcing regional specialization in thermal interface manufacturing.
China
Urban delivery operators in Shanghai and Suzhou are consolidating orders for swappable-pack vans under MIIT GB/T interoperability mandates. The country's MIIT enforces connector geometry and CAN communication protocols that lock out non-compliant platform designs. Cell-to-pack integration factories in the Yangtze River Delta cluster near vehicle assembly plants, eliminating steel reinforcements through structural battery bonding.
Germany
Logistics cooperatives in urban freight corridors pool charging infrastructure and swap station access, compressing total-cost-of-ownership calculations. The EU's F-Gas Regulation restricts refrigerant selection in thermal regulation systems, accelerating liquid-cooled aluminum housing adoption. Cold-plate engineering specialists in Baden-Württemberg face talent scarcity as pack manufacturers compete for finite design pools.
United States
Fleet operators prioritize total-cost-of-ownership contracts over upfront hardware pricing for last-mile electrification programs. The US NHTSA crashworthiness standards for underbody battery protection create divergent reinforcement requirements that fragment common-platform economics. Michigan and California anchor rival engineering approaches to thermal management and pack structural integration.
South Korea
Large-format cell winding equipment suppliers cluster in Seoul and Busan, creating procurement bottlenecks for contract manufacturers. The country's national industrial regulator supports advanced chemistry cell manufacturing through targeted investment programs. Battery management system software firms in the Seoul Capital Area differentiate through predictive thermal modeling for fleet operator contracts.
India
The country's PLI scheme for advanced chemistry cell manufacturing is opening localized pack assembly capacity near Chennai and Pune. Commercial vehicle electrification is accelerating as logistics operators seek payload density advantages from compressed pack heights. Tamil Nadu manufacturing corridors are attracting thermal interface specialists to serve domestic and export markets.
Modular Battery Pack Platforms for Skateboard EVs Market Competitive Landscape
Concentration sits with vertically integrated OEMs and contract manufacturing specialists that anchor multi-program production capacity. The market structure splits between captive in-house production strategies and open supplier markets where tier-1 fabricators consolidate procurement leverage. Two strategic archetypes dominate: integrated motor-battery-thermal module suppliers and pure-play battery-as-a-service platform operators. Competitive moves center on backward integration into cell winding capacity and geographic expansion of aluminum casting footprints.
Within the integrated OEM tier, Tesla and Hyundai Motor exemplify in-house thermal interface control strategies. Foxconn anchors the contract manufacturing archetype across Taiwan and Mexico production nodes. These three entities represent divergent approaches to platform architecture fungibility—captive cell-to-pack engineering versus outsourced multi-program capacity.
| Leading Market Players |
|---|
| Tesla |
| Foxconn |
| Hyundai Motor |
| General Motors |
| Rivian |
| Audi |
| Toyota |
| Volkswagen |
| REE Automotive |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts with South Korean and Japanese cell suppliers lock in both cathode material access and price visibility for European platform manufacturers facing F-Gas thermal regulation compliance costs. These arrangements tether pack economics to nickel and lithium carbonate spot volatility while insulating tier-1 assemblers from procurement bottlenecks in winding equipment.
Pricing Analysis
China's MIIT GB/T battery-swap standards dictate the pricing tier structure across Asian-market platforms, separating swap-certified architectures from non-compliant designs. Three-tier pricing stratifies across premium 800V SiC-enabled systems, standard liquid-cooled aluminum configurations, and economy-grade air-cooled packs. Cost compression in the standard tier intensifies as Foxconn's contract manufacturing scale in Taiwan and Mexico squeezes margin capture for independent thermal specialists. Fleet operators in last-mile logistics show least price sensitivity, prioritizing total-cost-of-ownership underwriting from battery-as-a-service providers over upfront hardware expenditure.
Supply Chain Analysis
China and South Korea anchor cathode active material and large-format cell winding capacity, with Japan supplying precision thermal interface components. The supply chain draws from Chilean lithium brine operations, Indonesian nickel laterite processing, and Australian spodumene concentrate. Single-source vulnerability concentrates in Seoul and Busan equipment suppliers, where order backlogs for winding machinery extend procurement timelines. Distribution runs through Yangtze River Delta integration factories that co-locate cell-to-pack assembly with vehicle final assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-as-a-service revenue streams expand faster than hardware sales as fleet operators unbundle pack ownership from vehicle acquisition, creating attach opportunities for thermal lifecycle management and predictive state-of-charge software.
For Market Incumbents: Shield integrated motor-battery-thermal module positions by accelerating in-house phase-change material engineering before talent scarcity in Baden-Württemberg and Tamil Nadu worsens. Defensive patent filings around quick-disconnect cooling loop architectures for swap-compatible packs will raise barriers against contract manufacturing specialists expanding from Taiwan into Mexico. Vertical integration into cell winding capacity, though capital-intensive, secures supply priority when South Korean equipment suppliers ration output. For New Entrants and Emerging Players: UN ECE R100 fast-track certification opens European last-mile logistics procurement channels before incumbents complete homologation timeline compression. White-space sits in Indian commercial vehicle electrification, where PLI scheme incentives for advanced chemistry cell manufacturing near Chennai and Pune outpace established supplier footprint. Go-to-market leverage targets battery lifecycle management software for German logistics cooperatives pooling swap station infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward thermal interface engineering specialists with captive relationships to Yangtze River Delta integration factories. Long-term viability over the projection horizon rests on platform architecture fungibility across divergent NHTSA and UN ECE crashworthiness requirements. The signal to watch is consolidation in cold-plate design talent pools as European F-Gas compliance deadlines accelerate.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Integration Investment | Eliminates module-level redundancy, compressing pack height for last-mile payload density gains. |
| Battery-as-a-Service Platform Launch | Unbundles ownership for fleet operators, creating recurring thermal management revenue streams. |
| Dual-Certification Homologation Pathway | Secures access to both China's MIIT GB/T swap standards and EU F-Gas thermal regulation markets. |
| Silicon-Carbide Inverter Convergence | Enables 800V fast-charging differentiation for premium platform tiers in German logistics corridors. |
| Regional Aluminum Casting Expansion | Co-locates thermal housing capacity with Yangtze River Delta vehicle assembly clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, tier-1 thermal management specialists, fleet procurement directors at last-mile logistics cooperatives, and cell-to-pack integration factory operations managers. Secondary validation drew from MIIT GB/T standard filings, EU F-Gas Regulation compliance disclosures, NHTSA crashworthiness test protocols, UN ECE R100 revision documentation, and vehicle production databases. Bottom-up volume estimates triangulated against top-down market sizing across chemistry, voltage architecture, and application segments.
Across the analysis window, forecasts model cell chemistry evolution, thermal regulation compliance cost trajectories, and fleet electrification procurement patterns. Segmentation dimensions include product type, technology tier, application use case, and end-user archetype. CAGRs derive from elasticity modeling against cathode material spot prices and contract manufacturing capacity expansion timelines. Industry-specific inputs incorporate F-Gas refrigerant phase-out schedules and PLI scheme incentive disbursement velocity.
Underlying assumptions cover sustained nickel and lithium carbonate price volatility, with deviation risk concentrated in NHTSA-UN ECE regulatory divergence and single-source winding equipment procurement bottlenecks. Recalibration cycles align with material shifts in battery-swap infrastructure deployment and solid-state electrolyte commercialization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Global Zinc Air Batteries Market
Batteries
Nimh Battery Market
Batteries
South and Central America Battery Market
Batteries
Rear Rack Battery Market
Batteries
Aluminum Wire Battery Market
Batteries
China Rechargeable Battery Market
Batteries
Indonesia Battery Market
Batteries
Global Electric Scooter Batteries Market
Batteries
Smart Battery Charger Market
Batteries
Global Lithium Titanate (LTO) Batteries Market
Batteries
Italy Rechargeable Battery Market
Batteries
Battery Diagnostics and Repair Market
Batteries
West Europe Battery Market
Batteries
South Asia Battery Market
Batteries
Micro Battery Market
Batteries
Lithium Pouch Cell Market