
 Global Electric Scooter Batteries Market | 2026-2036
Global Electric Scooter Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Scooter Batteries Market Analysis
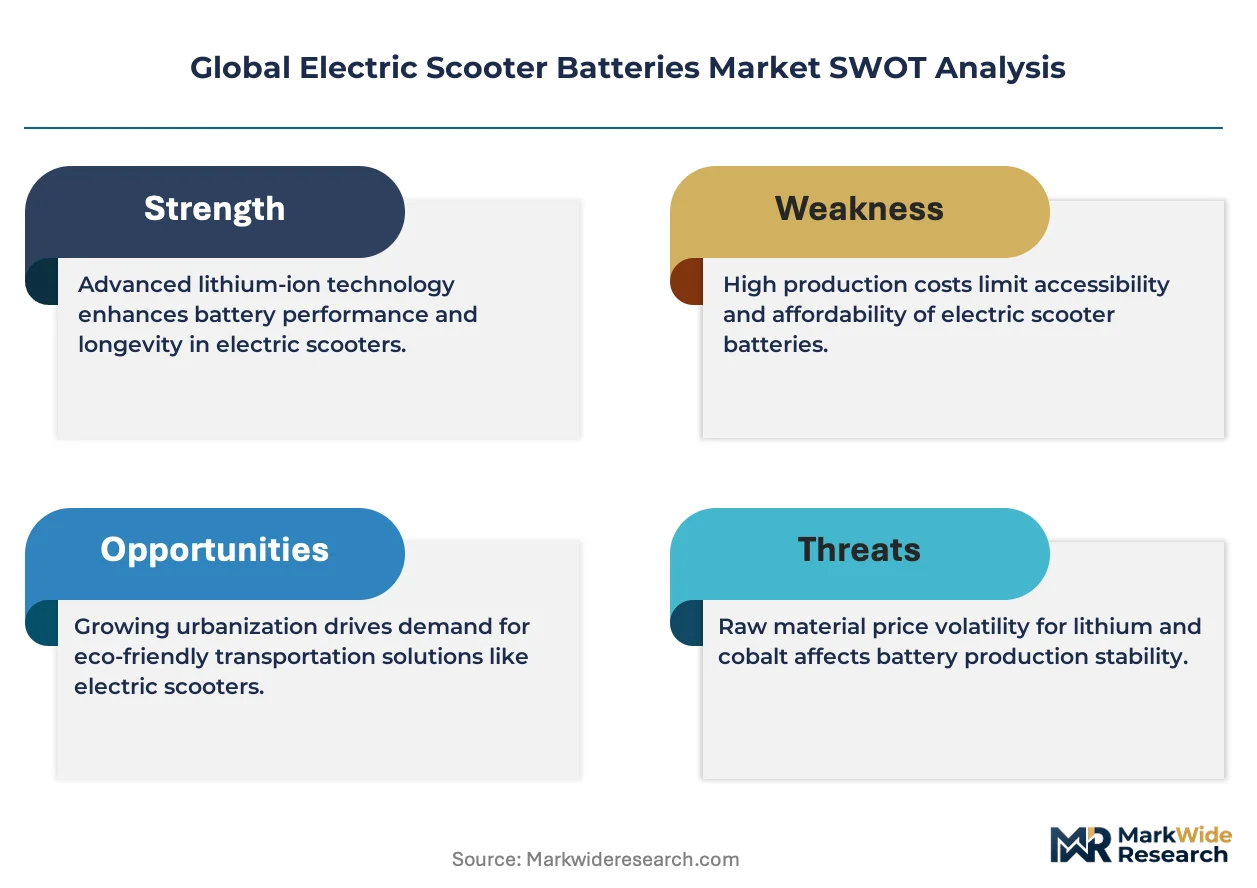
The EU Green Deal is broadening the addressable market for high-density scooter battery packs across European urban fleets. LG Chem leverages its cylindrical cell expertise to sustain supply relationships with premium European OEMs. Samsung SDI anchors its position through rigorous thermal management systems that meet stringent EU safety certifications. CATL competes aggressively on manufacturing scale, operating giga-scale facilities that dominate cost curves for lithium-iron-phosphate variants.
Electric scooter batteries are rechargeable electrochemical storage systems, typically rated between 36V and 72V with capacities spanning 10Ah to 40Ah, engineered to deliver sustained discharge currents for brushless DC hub motors in micromobility platforms. Lithium-ion chemistry retains the dominant share due to superior energy density and cycle life, while lead-acid continues to occupy the economy tier where upfront cost sensitivity governs procurement. Fast charging infrastructure is displacing standard charging in commercial fleet deployments where vehicle utilization rates dictate revenue per asset. Delivery services represent the fastest-growing end-user segment as logistics operators electrify last-mile operations.
The EU AI Act and F-Gas Regulation are reshaping product standards for battery management systems and thermal materials across European markets. China's MIIT enforces GB standards that mandate cell-level traceability and recycling accountability for domestic manufacturers. India's BIS certification requirements for lithium-ion cells are tightening import compliance for aftermarket battery suppliers. Stakeholders must monitor how divergent recycling mandates across Brussels, Beijing, and New Delhi reshape cost structures and supply chain geography.
Market Dynamics
Cell-to-pack integration is compressing manufacturing costs while tightening performance tolerances across the lithium-ion supply base. This structural shift is redrawing competitive boundaries between cylindrical, prismatic, and pouch cell architectures.
Growth Catalysts
- EU Green Deal emissions thresholds:Metropolitan fleet operators across Germany, France, and the Netherlands face accelerating procurement deadlines for zero-emission last-mile vehicles.
- China's NEV subsidy framework:Domestic manufacturers in the Yangtze River Delta cluster receive tiered incentives for high-density pack architectures that exceed 180 Wh/kg.
- Fast charging infrastructure:Commercial delivery services operating 24-hour logistics networks demand sub-45-minute charge cycles to maximize vehicle utilization rates.
Market Restraints
- Lithium carbonate price volatility:Raw material input costs for cathode active materials fluctuate with South American brine extraction rates and Australian spodumene contract terms.
- Nickel supply concentration:Indonesian laterite processing and Philippine ore exports dominate the Class 1 nickel supply chain for high-nickel cathode chemistries.
- Cell-level thermal runaway:Energy density gains in NMC 811 formulations confront fundamental electrochemical stability limits under sustained high-rate discharge conditions.
Strategic Opportunities
- India's BIS certification expansion:Domestic cell manufacturing capacity under the PLI scheme creates first-mover advantages for localized pack assembly operations.
- Solid-state electrolyte convergence:Sulfide-based ceramic separators paired with lithium-metal anodes promise 400+ Wh/kg pack-level densities within commercialization timelines.
- Battery-as-a-service channels:Subscription-based ownership models decouple upfront capital requirements from fleet cash flow management for urban mobility operators.
Industry Challenges
- GB standard traceability mandates:China's MIIT requires cell-level serialization and blockchain-verified provenance documentation that extends compliance timelines for imported components.
- Thermal management engineering scarcity:Pack designers with expertise in phase-change materials and liquid cooling manifold integration command premium compensation in competitive labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Scooter Batteries Market |
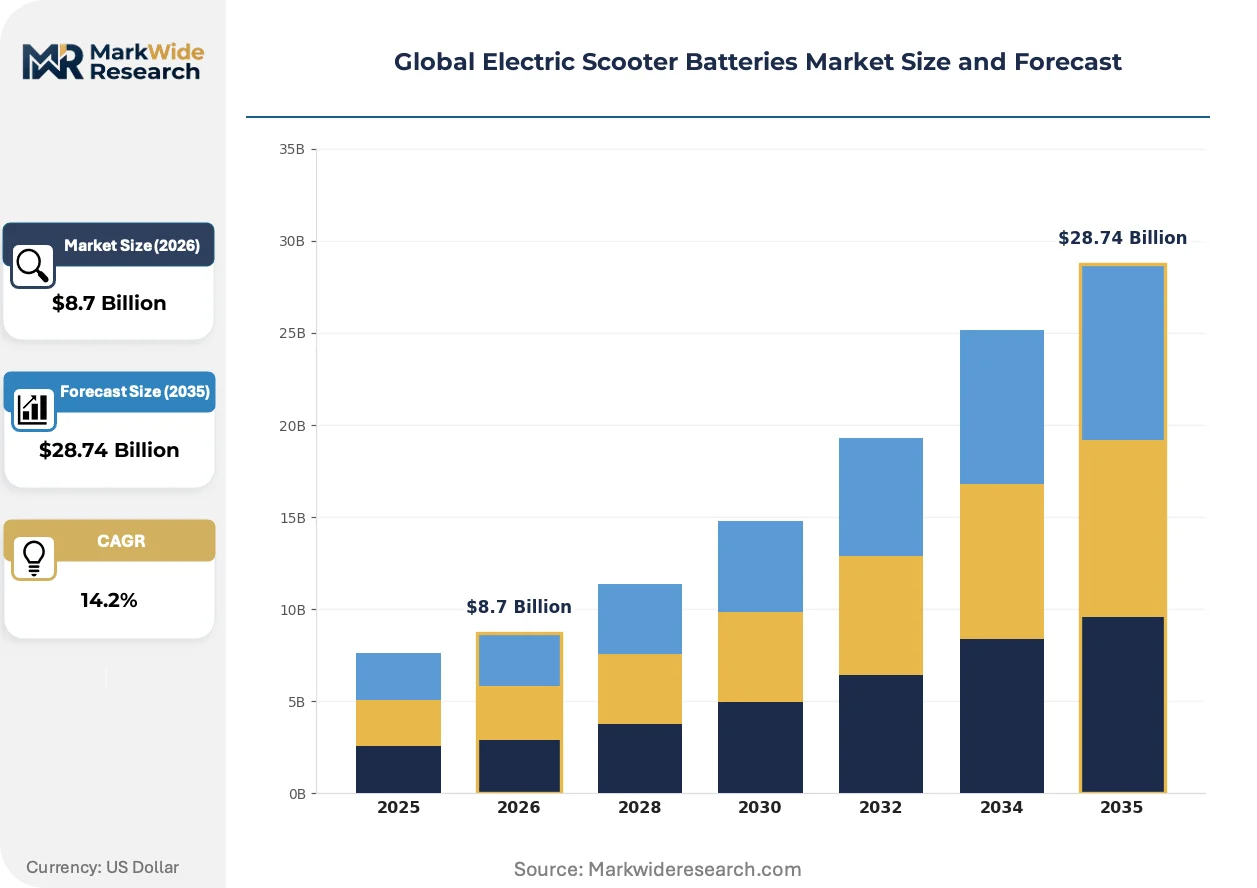
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Lithium Polymer Charging Technology: Fast Charging, Standard Charging, Wireless Charging, Regenerative Charging End User: Commuters, Delivery Services, Hobbyists, Rental Services Application: Urban Transport, Leisure Use, Food Delivery, Environmental Initiatives |
| Companies Covered | LG Chem, Samsung SDI, Panasonic Corporation, Contemporary Amperex Technology Co. Limited (CATL), BYD Co. Ltd., ENVISION AESC GROUP LTD., Guoxuan Hi-Tech, CBAK Energy Technology, China Aviation Lithium Battery Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Scooter Batteries Market Emerging Trajectories
Silicon-anode chemistries and intelligent battery management systems are converging to extend cycle life while enabling predictive maintenance capabilities. These advances are compressing total cost of ownership calculations for high-utilization commercial fleets.
Lithium-iron-phosphate cathode formulations are consolidating market share in the economy and mid-tier scooter segments where safety tolerance outweighs gravimetric energy density requirements. Fleet procurement managers in Southeast Asian markets are specifying LFP packs for their superior thermal stability during tropical ambient temperature operation. This chemistry shift is consolidating supplier relationships around giga-scale manufacturers with captive phosphate supply agreements.
The EU F-Gas Regulation is phasing down hydrofluorocarbon-based thermal interface materials in favor of natural refrigerant alternatives and phase-change compounds. Pack assemblers serving European OEMs must reformulate thermal management architectures to maintain safety certifications under revised material restrictions. German and Italian engineering houses are accelerating validation programs for graphite-based gap fillers and paraffin wax phase-change materials.
Delivery service operators are unbundling battery ownership from vehicle procurement through third-party leasing arrangements and swap-station networks. This asset-light model shifts capital burden to specialized infrastructure providers while enabling fleet managers to match battery capacity to route requirements. Dense urban corridors in São Paulo, Mexico City, and Jakarta display the fastest penetration of subscription-based energy services for two-wheel logistics platforms.
Global Electric Scooter Batteries Market Segmentation
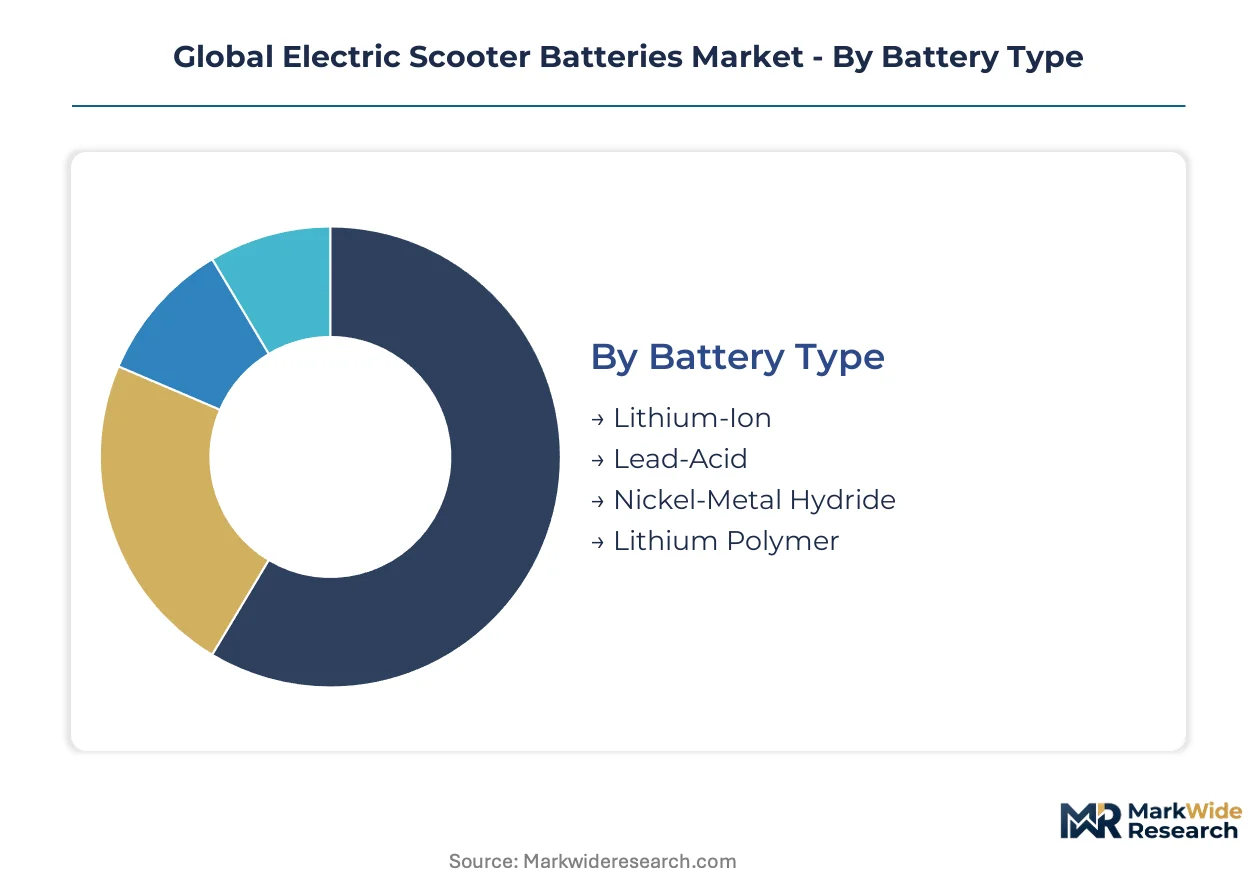
Segmentation in electric scooter batteries reveals how certification requirements, thermal performance thresholds, and duty-cycle intensity fragment procurement patterns across chemistry types and charging modalities. Fleet operators, commuter platforms, and logistics networks each impose distinct validation protocols that reshape supplier qualification timelines and geographic sourcing strategies.
Battery Type:
Lithium-ion and LFP variants require UN 38.3 transport certification and IEC 62133 safety validation for EU market entry, while lead-acid chemistry faces less stringent documentation but confronts REACH substance restrictions on sulfuric acid handling.
- Lithium-Ion:Cylindrical and prismatic cell configurations dominate premium scooter architectures with energy densities exceeding 250 Wh/kg. Demand concentrates in European urban fleet deployments where operators specify NMC 811 cathodes for maximum range-per-charge under EU Green Deal procurement mandates.
- Lead-Acid:Flooded and AGM constructions retain cost advantages in price-sensitive South Asian and African markets. Volume clusters in India's aftermarket replacement segment where BIS certification compliance remains less rigorous than lithium-ion import standards.
- Nickel-Metal Hydride:Legacy chemistry with moderate energy density finds residual demand in Japanese domestic scooters adhering to METI recycling directives.
- Lithium Polymer:Pouch-cell formats enable flexible pack geometries for compact folding scooter designs popular in dense European city centers.
Leading the category by volume: Lithium-Ion. Expanding most quickly: Lithium Polymer in premium micromobility applications.
Charging Technology:
Fast charging infrastructure investment correlates directly with fleet utilization economics, while standard charging retains dominance in residential and small commercial settings where overnight dwell times accommodate longer cycles.
- Fast Charging:DC rapid protocols delivering 80% state-of-charge within 45 minutes are reshaping commercial fleet TCO calculations. Deployment concentrates in São Paulo and Jakarta swap-station networks where 24-hour logistics operators mandate sub-hour turnaround.
- Standard Charging:AC Level 1 and Level 2 hardware dominates commuter-owned scooters in European and North American residential contexts. Volume remains highest where overnight garage charging eliminates range anxiety without infrastructure capital expenditure.
- Wireless Charging:Inductive pad systems are piloting in corporate campus and municipal parking integrations across Germany and the Netherlands.
- Regenerative Charging:Kinetic recovery systems add 8-15% range extension in stop-and-go urban corridors, gaining specification in premium commuter models.
Dominant by installed base: Standard Charging. Steepest expansion trajectory: Fast Charging in commercial fleet channels.
End User:
Delivery services impose the most severe cycle-life and thermal management requirements, while rental services prioritize vandal-resistant pack enclosures and standardized swap compatibility.
- Delivery Services:Last-mile logistics operators in Mexico City and Bangkok specify high-cycle LFP packs rated for 2,000+ deep discharges annually. Procurement volumes track e-commerce penetration and quick-commerce grocery expansion.
- Commuters:Individual ownership segments in German and French metropolitan areas favor mid-capacity packs balancing purchase price against daily range requirements.
- Hobbyists:Enthusiast modifiers in US and Australian markets drive aftermarket demand for high-discharge-rate cells and custom BMS configurations.
- Rental Services:Shared micromobility platforms in Barcelona and Singapore mandate IP67-rated enclosures and CAN-bus telemetry integration for remote diagnostics.
Highest absolute consumption: Commuters. Gaining share fastest: Delivery Services as logistics electrification accelerates.
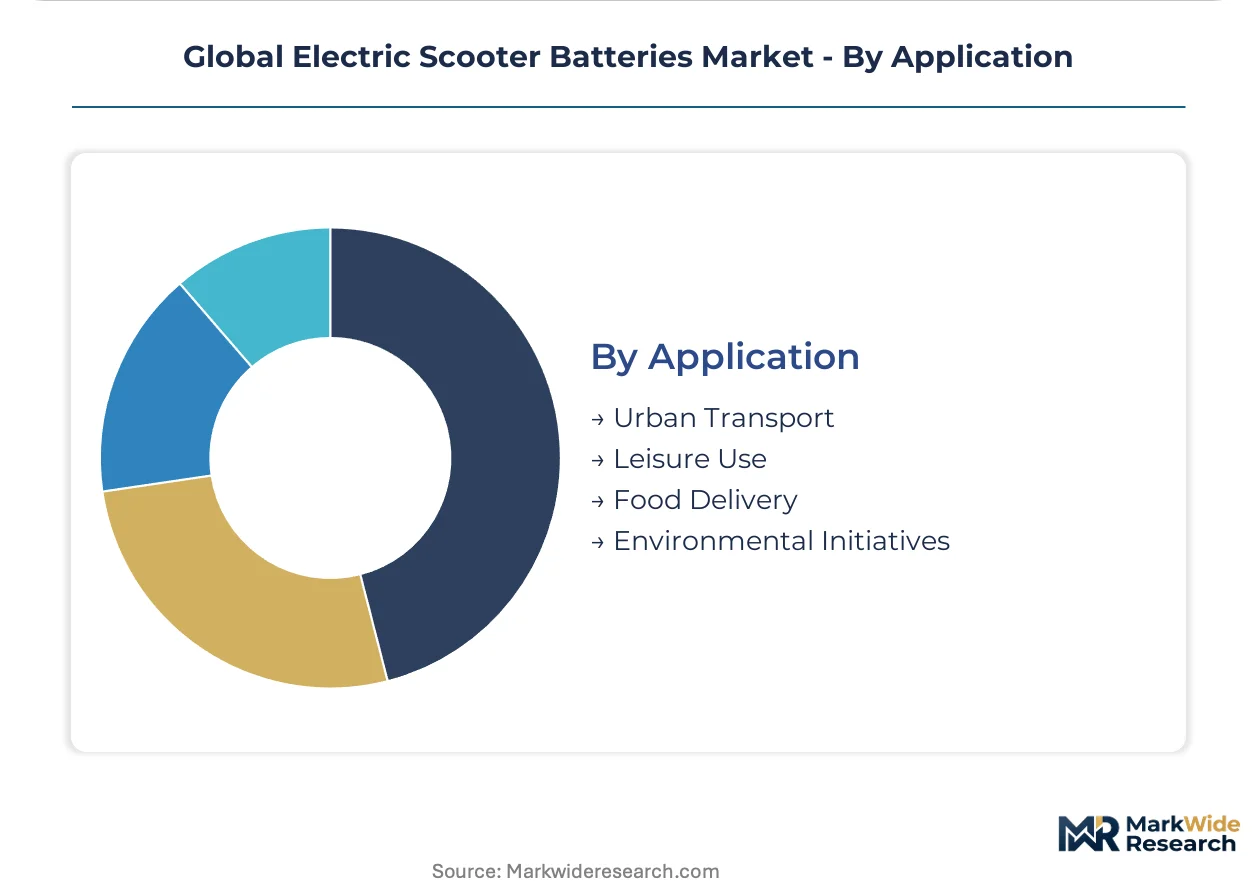
Application:
Urban transport applications face the strictest regulatory scrutiny for fire safety and electromagnetic compatibility, while food delivery sub-segments prioritize rapid swap capability over maximum energy density.
- Urban Transport:Municipal fleet procurement across Amsterdam, Copenhagen, and Milan specifies packs meeting ECE R136 electric powertrain standards. Volume concentrates where congestion charging and low-emission zones mandate zero-tailpipe operation.
- Food Delivery:Thermal stability during sustained high-rate discharge distinguishes this segment, with operators in tropical markets favoring LFP chemistries for ambient temperature resilience.
- Leisure Use:Recreational scooters in coastal Mediterranean and Southeast Asian tourist corridors emphasize lightweight pack designs for portability.
- Environmental Initiatives:Corporate and municipal sustainability programs in Sweden and California drive small-volume procurement of second-life automotive cells repurposed for scooter applications.
Category leader by unit volume: Urban Transport. Climbing the fastest: Food Delivery as quick-commerce platforms scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta manufacturing cluster anchors global cell-to-pack integration, with Suzhou and Ningbo facilities setting the pace for lithium-ion density improvements. Metropolitan procurement mandates across three continents are reshaping regional competitive positioning.
China
Fleet electrification in Shenzhen and Hangzhou drives procurement volumes for high-density NMC packs. MIIT enforces GB standards mandating cell-level traceability and recycling accountability. The Yangtze River Delta cluster dominates giga-scale LFP production for domestic and export markets.
Germany
Berlin and Munich fleet operators face accelerating deadlines under EU Green Deal emissions thresholds for zero-emission last-mile vehicles. The F-Gas Regulation phases down hydrofluorocarbon thermal materials, forcing pack redesigns. Engineering houses in Stuttgart validate graphite-based gap fillers for revised safety certifications.
United States
Delivery services in Los Angeles and New York electrify last-mile logistics, specifying high-cycle packs for 24-hour utilization. EPA tailpipe regulations tighten indirectly through state-level zero-emission vehicle mandates. The Pacific Northwest hosts pilot wireless charging integrations for corporate campus deployments.
India
Quick-commerce expansion in Mumbai and Bangalore drives LFP procurement for thermal stability in tropical ambient conditions. BIS certification requirements tighten import compliance for aftermarket lithium-ion suppliers. Domestic cell manufacturing under the PLI scheme concentrates in Gujarat and Tamil Nadu.
Indonesia
Motorcycle-to-electric conversion programs in Jakarta and Surabaya accelerate demand for affordable pack architectures. The country's national industrial regulator coordinates nickel laterite processing integration with cathode material supply. Processing facilities in Sulawesi and Halmahera feed Class 1 nickel into regional battery supply chains.
Global Electric Scooter Batteries Market Vendor Landscape
Premium-margin players sit above commodity-margin players across energy density and thermal management certification tiers. The vendor base stratifies between cylindrical cell specialists, prismatic format manufacturers, and pouch-cell integrators serving distinct OEM specifications. Three archetypes dominate: giga-scale chemistry producers, thermal engineering specialists, and swap-station infrastructure operators. Capacity expansion and backward integration into cathode active materials represent the dominant competitive moves.
Within the chemistry-producer tier, LG Chem and Samsung SDI exemplify premium-tier positioning through cylindrical cell expertise and rigorous thermal management validation. Contemporary Amperex Technology Co. Limited anchors the scale-driven segment with giga-manufacturing footprints. These three occupy positions that reflect divergent strategic bets on format standardization versus chemistry flexibility.
| Leading Market Players |
|---|
| LG Chem |
| Samsung SDI |
| Panasonic Corporation |
| Contemporary Amperex Technology Co. Limited (CATL) |
| BYD Co. Ltd. |
| ENVISION AESC GROUP LTD. |
| Guoxuan Hi-Tech |
| CBAK Energy Technology |
| China Aviation Lithium Battery Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate contract terms from South American brine operations and Australian spodumene offtake agreements cascade through cathode active material pricing tiers, compressing margins for mid-tier pack assemblers while giga-scale producers in China's Yangtze River Delta absorb volatility through captive mining stakes and long-term supply anchors.
Pricing Analysis
Vehicle utilization rates per charge cycle anchor value-based pricing for commercial fleet procurement, with subscription models decoupling upfront capital from operating expenditure. Pricing stratifies across premium cylindrical cell formats with UN 38.3 certification, standard prismatic architectures for commuter segments, and economy lead-acid replacements in price-sensitive South Asian markets. Cost compression in the mid-tier intensifies because Indonesian nickel laterite processing bottlenecks tighten cathode input availability. Delivery service operators exhibit highest price sensitivity due to thin logistics margins, while European OEMs prioritize certification-grade packs with reduced elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian Class 1 nickel laterite processing for high-nickel NMC cathodes, Chinese giga-scale LFP cell manufacturing, and South Korean cylindrical cell expertise. The supply chain draws from lithium brine extraction in Chile and Argentina, graphite anode processing in China, and electrolyte salt production in Japan. Tariff exposure on cells crossing the EU-China trade corridor elevates landed cost unpredictability for pack assemblers. Distribution runs through Yangtze River Delta export hubs to European port clusters and Southeast Asian assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-to-pack integration capacity in the Yangtze River Delta and South Korean cathode material plants operates at effective saturation, propping pricing power for qualified suppliers against unmet fleet procurement deadlines.
For Market Incumbents: To counter emerging solid-state electrolyte patent holders from Japan and South Korea, secure backward integration into phosphate mining concessions and expand giga-scale LFP capacity in Gujarat under India's PLI scheme. Thermal management engineering talent scarcity demands premium compensation structures and targeted university partnerships in Stuttgart and Milan. For New Entrants and Emerging Players: Direct-to-fleet digital procurement platforms offer the lowest friction route to bypass incumbent distributor networks. White-space concentrates in India's BIS-certified aftermarket replacement segment and Indonesia's motorcycle-to-electric conversion programs. Battery-as-a-service subscription models for quick-commerce operators in São Paulo and Jakarta provide the most penetrable entry vector. For Investors and Strategic Acquirers: MIIT enforcement of GB standard blockchain traceability mandates is the leading indicator that compliance-technology providers will command acquisition premiums. Long-term viability rests on exposure to swap-station infrastructure operators and phase-change thermal material specialists rather than commodity cell manufacturing. Acquisition targets should display captive cathode supply agreements and validated EU F-Gas Regulation thermal architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Integration Scale-Up | CATL and BYD giga-facilities compress cost curves below prismatic competitors in Suzhou. |
| Solid-State Electrolyte R&D Partnership | Sulfide-based ceramic separator development promises 400+ Wh/kg densities for premium fleets. |
| Battery-as-a-Service Platform Launch | Subscription ownership decouples capital burden from cash flow for 24-hour logistics operators. |
| Thermal Management Certification Investment | Graphite gap filler validation under EU F-Gas Regulation secures European OEM supply relationships. |
| Backward Integration into Phosphate Mining | Captive LFP cathode supply agreements insulate margin structures from lithium carbonate volatility. |
Methodological Framework
UN Comtrade customs records, MIIT production filings, and EU F-Gas Regulation implementation documents formed the secondary backbone, cross-referenced with primary interviews across pack design engineers at Tier 1 suppliers, fleet procurement managers at quick-commerce platforms, thermal management specialists at German engineering houses, and cathode material procurement leads at giga-scale manufacturers. Bottom-up cell shipment aggregation and top-down fleet deployment modeling were triangulated against BIS import certification databases and Yangtze River Delta facility utilization reports.
Historical trendline analysis of lithium-ion cell pricing, LFP chemistry adoption curves, and fast charging infrastructure deployment informed the projection framework. Segmentation dimensions spanned battery chemistry tier, charging protocol, end-user archetype, and regional regulatory cluster. CAGRs were derived from fitted growth curves against fleet electrification mandates and e-commerce logistics expansion rates, with sensitivity testing on nickel laterite supply constraints and solid-state commercialization timelines.
Inputs from Chinese MIIT production statistics and Indonesian mineral processing disclosures were available through the study window; gaps in swap-station utilization data and second-life automotive cell repurposing volumes introduce uncertainty bands around commercial fleet TCO assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Automotive Starting Battery Market
Batteries
Thin Film and Printed Battery Market
Batteries
Japan Rechargeable Battery Market
Batteries
India Electric Vehicle Battery Electrolyte Market
Batteries
Malaysia Battery Market
Batteries
Portable Battery Pack Market
Batteries
Residential Battery Market
Batteries
South and Central America Battery Market
Batteries
Deep Cycle Battery Market
Batteries
Heavy-Duty Truck Megapack Battery Systems Market
Batteries
Behind-The-Meter (BTM) Battery Market
Batteries
India Micro Batteries Market
Batteries
Alkaline Battery Market
Batteries
Battery Separators Market
Batteries
Battery Binders Market
Batteries
Global Cylindrical Lithium Battery Pack Market