
 Rear Rack Battery Market | 2026-2036
Rear Rack Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Rear Rack Battery Market Insights
Chinese cylindrical cell producers is rebalancing supply toward e-mobility formats as electric two-wheeler volumes climb. Bosch leverages its Stuttgart engineering base to sustain premium positioning in European OEM channels. Panasonic anchors North American demand through partnerships with mid-tier bike assemblers. Samsung SDI competes on energy density leadership for high-torque cargo applications.
A rear rack battery is a removable electrochemical energy storage unit mounted on the rear carrier of a bicycle or light electric vehicle, typically employing lithium-ion cells with nominal voltages between 36 V and 48 V and capacities spanning 10 Ah to 30 Ah to deliver 360–1,440 Wh of usable energy. The device powers hub or mid-drive motors for pedal-assist propulsion, with thermal management and battery management systems ensuring cycle life across temperature extremes. Lithium-ion chemistry dominates value capture due to superior gravimetric energy density, while lead-acid retains residual share in price-sensitive replacement markets. Removable installation formats command margin premiums by enabling off-bike charging and theft deterrence, whereas integrated designs appeal to OEMs pursuing frame aesthetics and weather sealing.
The EU Green Deal and REACH chemical frameworks mandate recycled content thresholds and restricted substance controls for batteries sold across member states. China's GB standards and MIIT technical rules govern cell safety testing and pack labeling for domestic and export-bound production. The US Consumer Product Safety Commission and state-level fire codes in California and New York shape import compliance and retailer liability. Stakeholders must track evolving certification reciprocity between jurisdictions to avoid market access friction as regulatory divergence widens.
Market Dynamics
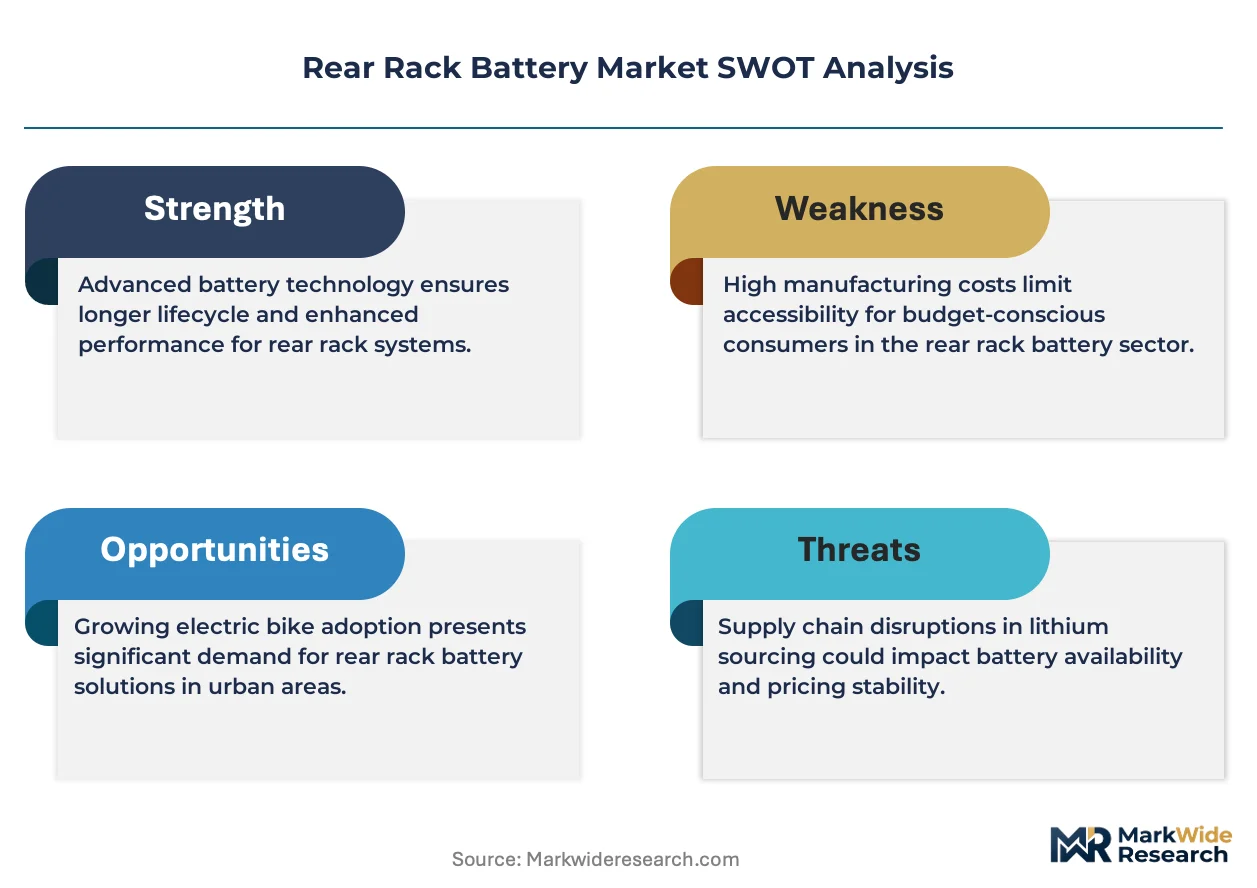
EU battery sustainability mandates under the EU Green Deal are forcing cell chemistry upgrades and modular pack architectures across the rear rack battery supply base, compressing legacy lead-acid replacement cycles and accelerating lithium-ion format transitions.
Growth Catalysts
- Urban micromobility maturation:Municipal bike-share networks in Germany and the Netherlands are standardizing rear rack formats for fleet interoperability and rapid battery swapping.
- REACH chemical compliance:Restricted substance controls are pushing OEMs toward certified cell suppliers with documented supply chain transparency.
- Jiangsu-Zhejiang manufacturing scale:Pack assembly capacity concentration in these coastal provinces is reducing unit costs for export-bound production.
Market Restraints
- Lithium carbonate volatility:Raw material price swings compress margin stability for pack assemblers locked into annual OEM contracts.
- Cell supplier concentration:Dependence on a limited pool of cylindrical cell producers creates single-source vulnerability for mid-tier battery brands.
- Lead-acid residual demand:Price-sensitive replacement markets in developing economies delay full lithium-ion penetration.
Strategic Opportunities
- Swappable battery standards:Interoperability protocols emerging from Chinese MIIT technical rules could unlock cross-brand fleet adoption.
- Cargo bike torque demands:High-capacity 48 V formats for commercial delivery applications represent an underserved premium segment.
- Second-life stationary storage:Retired e-bike cells are finding reuse in residential energy systems through dedicated refurbishment channels.
Industry Challenges
- BMS firmware certification:Multi-junction safety testing across EU, US, and Chinese standards extends product launch timelines by 8-14 months.
- Thermal engineering talent:Pack-level thermal management expertise remains concentrated among automotive battery veterans, creating hiring bottlenecks for bike-specific developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rear Rack Battery Market |
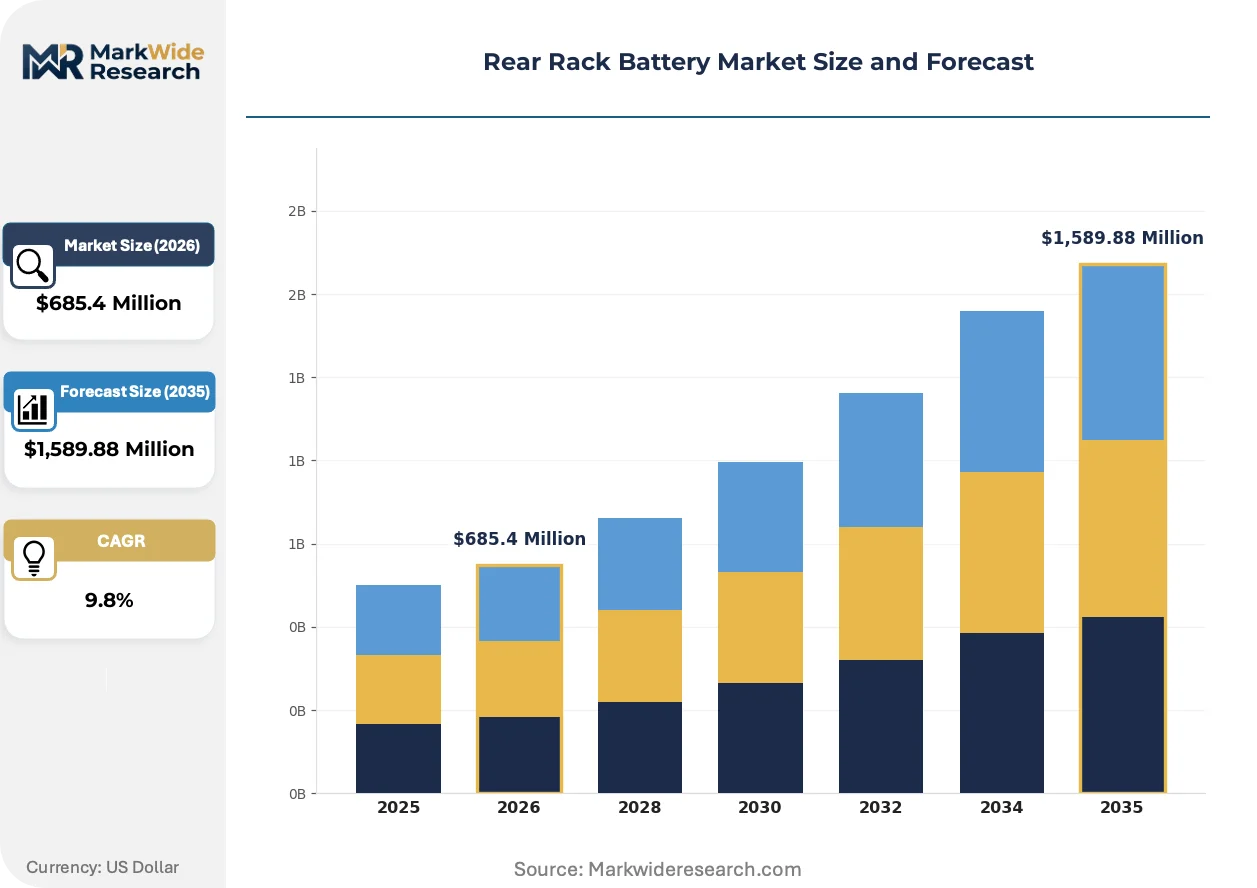
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,589.88 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Flow Batteries End User: E-Bike Manufacturers, Electric Scooters, Recreational Segments, Delivery Services Capacity: 10 Ah, 20 Ah, 30 Ah, 40 Ah Installation: Integrated, Removable, Built-in, Plug-and-play |
| Companies Covered | Bosch, Shimano, Yamaha Motor Co. Ltd., Panasonic Corporation, LG Chem Ltd., Samsung SDI, Contemporary Amperex Technology Co. Limited (CATL), Toshiba Corporation, Bafang Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rear Rack Battery Market Trends and Innovations
Cell-to-pack architectures and smart battery management systems are compressing the traditional boundaries between component supplier and system integrator, reshaping how rear rack batteries are specified, priced, and serviced across OEM and aftermarket channels.
Solid-state electrolyte research is absorbing development resources from tier-one cell producers targeting e-mobility formats. Automotive spillover programs at Samsung SDI and Panasonic are accelerating prototype cycles for bicycle-scale applications. This chemistry transition is absorbing margin pressure from cobalt reduction mandates while enabling higher volumetric density in constrained rack geometries.
EU Green Deal recycled content thresholds are mandating closed-loop material recovery for batteries sold across member states. Pack assemblers must now document post-consumer lithium sourcing or face market exclusion. Germany's KBA and France's environmental agency are conducting the strictest enforcement, pushing suppliers toward certified recycling partnerships before 2027 compliance deadlines.
Fleet procurement managers are consolidating vendor relationships around single-source service agreements that bundle hardware, firmware updates, and predictive maintenance. This model displaces the traditional spot-buy replacement market for independent bike shops. The shift is most visible in Dutch commercial delivery networks, where total-cost-of-ownership contracts now dominate new rack battery acquisitions.
Rear Rack Battery Market Segmentation
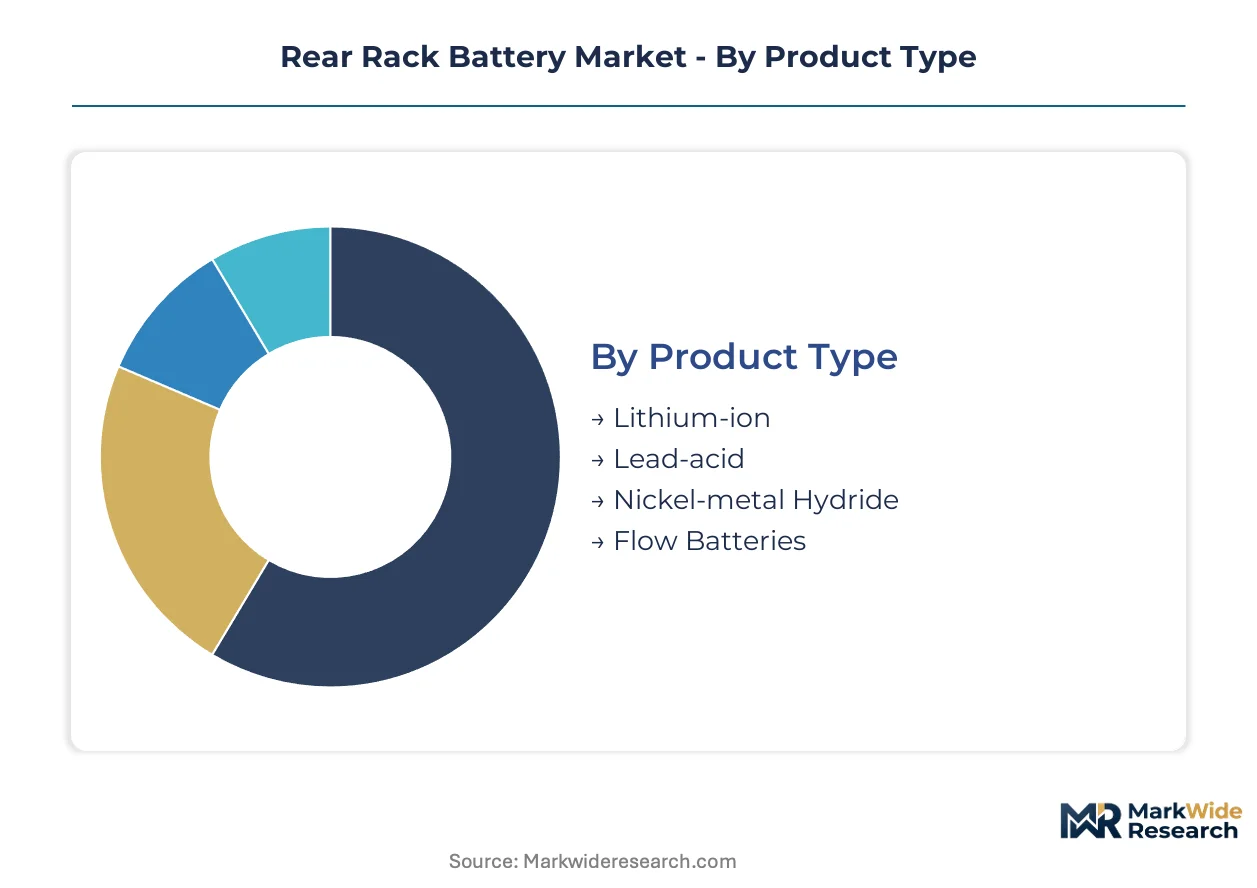
Rear rack battery procurement decisions split across chemistry trade-offs, fleet versus consumer use cases, and the serviceability requirements of commercial operators. Understanding these segment boundaries clarifies where margin concentrates and which technical specifications command premium positioning.
Product Type:
Cell chemistry dictates energy density, cycle life, and compliance pathways for pack assemblers serving OEM and aftermarket channels.
- Lithium-ion:Dominant format employing NMC or LFP cell architectures delivering 150-250 Wh/kg gravimetric density. Demand concentrates in German and Dutch e-bike OEM channels where EU Green Deal recycled content mandates favor suppliers with documented closed-loop partnerships.
- Lead-acid:Flooded and AGM variants persist in price-sensitive replacement markets across South Asian and African aftermarket channels. Cost-driven fleet operators in developing economies delay lithium-ion migration despite weight and cycle-life penalties.
- Nickel-metal Hydride:Legacy chemistry retaining niche presence in early-generation e-bike refurbishment programs and specialty recreational applications requiring thermal stability over energy density.
- Flow Batteries:Experimental zinc-bromine and vanadium redox formats under evaluation for stationary-swappable cargo bike depots where extended cycle tolerance outweighs volumetric constraints.
Lithium-ion leads on scale; lead-acid retains residual volume in price-tiered replacement segments.
End User:
Customer archetypes diverge sharply on total-cost-of-ownership calculations, warranty expectations, and charging infrastructure access.
- E-Bike Manufacturers:Frame-integrated procurement specifications from Bosch, Panasonic, and Samsung SDI dominate European OEM supply agreements. Volume commitments lock in annual cell allocation through multi-year contracts with cylindrical producers.
- Electric Scooters:Shared micromobility operators in Paris and Barcelona specify swappable rear rack formats for rapid turnaround. Interoperability pressures from Chinese MIIT technical rules are reshaping connector and communication protocol standards.
- Recreational Segments:Weekend cyclists and touring enthusiasts prioritize removable installation formats enabling off-bike charging in residential settings. Retail channel distribution through independent bike shops sustains aftermarket margin.
- Delivery Services:Commercial last-mile operators in Dutch urban centers negotiate predictive maintenance bundles and guaranteed swap availability. High-torque cargo applications demand 48 V high-capacity configurations with reinforced thermal management.
E-bike manufacturers capture the largest revenue pool; delivery services are expanding most quickly through fleet electrification mandates.
Capacity:
Energy storage specifications align directly with range requirements, motor torque demands, and regulatory classification thresholds for vehicle registration.
- 10 Ah:Entry-level format for pedal-assist commuters in flat urban environments. German KBA regulations classify these configurations as standard bicycles exempt from insurance and registration requirements.
- 20 Ah:Mid-range specification balancing weight and range for mixed-terrain recreational use. Chinese Jiangsu assembly lines scale this format most aggressively for export-bound production.
- 30 Ah:Extended-range configuration gaining share in suburban commuter segments and light cargo applications. REACH compliance documentation from certified cell suppliers commands premium pricing.
- 40 Ah:Maximum-capacity tier for commercial delivery and heavy cargo bikes requiring sustained high-torque output. Thermal engineering complexity limits supplier pool to automotive-spillover battery veterans.
20 Ah configurations dominate unit volume; 40 Ah formats show steepest expansion trajectory in commercial fleet procurement.
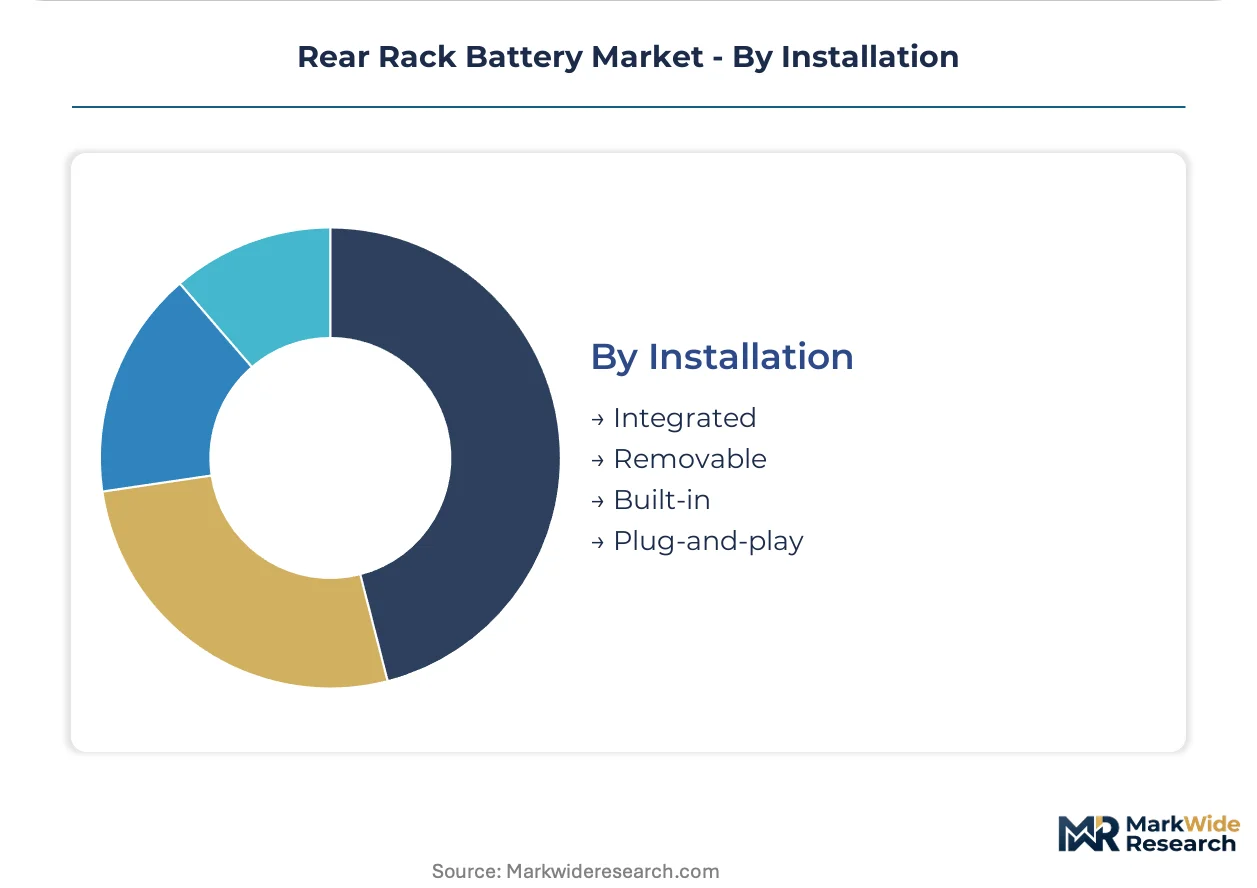
Installation:
Mounting architecture determines theft exposure, weather sealing, and the serviceability economics of fleet operators versus individual owners.
- Integrated:Frame-embedded designs with proprietary connector systems. OEMs in Stuttgart and Munich favor this format for aesthetic differentiation and controlled service revenue.
- Removable:Key-locked carrier mounting enabling off-bike charging and theft deterrence. Dutch bike-share networks standardize on this format for rapid battery swapping protocols.
- Built-in:Semi-permanent rack attachment with tool-required removal. Balances weather protection with field-service accessibility for municipal fleet maintenance teams.
- Plug-and-play:Universal connector systems emerging from Chinese MIIT standardization efforts. Cross-brand interoperability promises to unlock third-party battery supply for fleet operators.
Removable formats command the widest adoption across consumer and commercial channels; plug-and-play specifications are gaining regulatory momentum through Chinese technical rule harmonization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's procurement volumes for rear rack batteries outpace those of France by a factor of three, yet both markets operate under identical EU Green Deal compliance deadlines that reshape supplier qualification criteria.
Germany
KBA vehicle classification rules and fleet electrification mandates drive OEM demand for certified 48 V formats. REACH documentation requirements from ECHA force cell suppliers to disclose full material provenance. Stuttgart and Munich engineering clusters concentrate Bosch and premium-tier pack development activity.
Netherlands
Commercial delivery networks standardize swappable rear rack protocols for rapid turnaround logistics. National subsidies for cargo bike procurement accelerate 40 Ah high-capacity adoption. Randstad urban hubs host Europe's densest battery swapping infrastructure deployment.
China
Domestic e-bike replacement cycles and export manufacturing scale sustain Jiangsu-Zhejiang assembly corridor dominance. MIIT technical rules on cell safety testing and pack labeling govern both domestic sales and export-bound production. Suzhou and Hangzhou facilities scale cylindrical cell-to-pack automation fastest.
United States
State-level fire codes in California and New York shape import compliance and retailer liability frameworks for lithium-ion rack formats. Consumer Product Safety Commission guidelines influence aftermarket distribution channel requirements. Pacific Northwest recreational cycling demand sustains removable-format premium positioning.
Japan
METI efficiency standards and domestic quality certification protocols sustain niche demand for high-cycle-life configurations. Aging demographic pedal-assist adoption concentrates in suburban Kanto and Kansai corridors. Panasonic anchors domestic OEM supply relationships through automotive battery technology spillover.
Rear Rack Battery Market Competitive Landscape
Chinese producers anchor the volume tier; German and Japanese specialists hold premium positioning through automotive battery heritage. The market structures around three strategic archetypes: automotive-spillover cell suppliers, dedicated e-mobility pack integrators, and cylindrical cell specialists pivoting from consumer electronics. Competitive moves concentrate on backward integration into cell supply and geographic expansion through certified recycling partnerships.
Among automotive-spillover specialists, Bosch and Panasonic exemplify the premium-tier archetype, leveraging Stuttgart and Osaka engineering bases to sustain OEM channel dominance. Samsung SDI occupies a position within the energy density leadership segment, serving high-torque cargo applications where volumetric constraints demand advanced cell architectures. Contemporary Amperex Technology Co. Limited anchors the scale-driven tier, representing the manufacturing concentration that defines export-bound supply from Chinese coastal provinces.
| Leading Market Players |
|---|
| Bosch |
| Shimano |
| Yamaha Motor Co. Ltd. |
| Panasonic Corporation |
| LG Chem Ltd. |
| Samsung SDI |
| Contemporary Amperex Technology Co. Limited (CATL) |
| Toshiba Corporation |
| Bafang Electric |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate spot volatility flows through cylindrical cell pricing into tiered pack assembler margins, compressing mid-tier suppliers locked into annual OEM contracts while premium automotive-spillover brands absorb shocks through captive cathode supply.
Pricing Analysis
Distributor margin layers compress most acutely in the 20 Ah standard tier where Jiangsu-Zhejiang pack assemblers compete on export volume. Pricing stratifies across premium, standard, and economy tiers driven by REACH certification documentation and volume scale commitments. Pricing pressure stems from raw material pass-through clauses in cell supply agreements. Fleet procurement managers show lowest price sensitivity through total-cost-of-ownership contracts, while independent bike shops in replacement channels face acute margin squeeze.
Supply Chain Analysis
Reverse-logistics flows for end-of-life rack batteries are consolidating around certified recycling partnerships in Germany and France ahead of EU Green Deal recycled content mandates. Manufacturing concentrates in China, South Korea, and Japan through cylindrical cell and pack assembly specialization. The supply chain draws from lithium carbonate, nickel sulfate, and electrolyte solvent feedstocks. Single-source vulnerability runs through concentrated cathode precursor supply. Distribution runs through OEM direct contracts and fleet service agreements displacing traditional aftermarket wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rear rack battery market has entered a late-cycle quality phase where EU Green Deal compliance documentation and automotive-grade BMS firmware separate viable suppliers from margin-compressed commodity assemblers.
For Market Incumbents: Cement channel control through multi-year cell allocation contracts with cylindrical producers in Jiangsu and Zhejiang. Deepen backward integration into certified recycling partnerships before France and Germany enforce 2027 compliance deadlines. Defend against emerging Chinese pack integrators by locking fleet procurement managers into predictive maintenance bundles that bundle hardware, firmware, and swap logistics. For New Entrants and Emerging Players: Launch via plug-and-play interoperability protocols emerging from Chinese MIIT technical rules to bypass Bosch and Panasonic OEM channel dominance. Target Dutch commercial delivery networks where total-cost-of-ownership contracts are displacing spot-buy replacement markets. Enter through 48 V high-capacity cargo configurations where thermal engineering complexity limits incumbent supplier pools. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH documentation gaps and BMS firmware certification bottlenecks strand sub-scale pack assemblers without automotive battery heritage. Long-term viability favors automotive-spillover specialists with captive cell supply and closed-loop recycling infrastructure. Watch for EU member state enforcement divergence between Germany's KBA and France's environmental agency as early signals of supplier qualification tiering.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Supply | Captive lithium-nickel sourcing insulates margin from carbonate volatility through Jiangsu refining partnerships. |
| Certified Recycling Partnership Establishment | Documented closed-loop material recovery satisfies EU Green Deal thresholds for German and French market access. |
| Plug-and-Play Interoperability Certification | Chinese MIIT protocol compliance unlocks cross-brand fleet procurement from Dutch delivery network consolidators. |
| Predictive Maintenance Service Bundling | Total-cost-of-ownership contracts displace independent bike shop spot-buy replacement channels in commercial segments. |
| 48 V High-Capacity Thermal Engineering Investment | Automotive battery veteran expertise concentrates margin in cargo bike torque applications underserved by standard tier suppliers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with e-bike OEM procurement directors, fleet operations managers at Dutch delivery networks, pack assembly engineers in Jiangsu-Zhejiang manufacturing clusters, and certified recycling facility operators in Germany and France. Secondary validation drew from EU ECHA REACH substance databases, Chinese MIIT technical rule filings, US Consumer Product Safety Commission guidance documents, and customs trade flow records for lithium-ion battery exports. Bottom-up cell production estimates and top-down e-bike registration data were triangulated to anchor volume assumptions.
Segment-weighting approaches modeled chemistry format splits, installation architecture preferences, and capacity tier demand across the projection horizon. The analytical framework incorporated end-user procurement patterns, fleet electrification mandate timelines, and regulatory compliance deadline phasing. CAGRs were derived from logistic diffusion curves fitted to historical e-bike adoption rates and adjusted for cell chemistry transition velocity. Industry-specific inputs included lithium carbonate price elasticity coefficients and BMS firmware certification timeline distributions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium supply disruption or EU enforcement divergence scenarios. Practitioners should monitor KBA and French environmental agency audit announcement calendars for early signals of supplier qualification tiering.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
North America Consumer Battery Market
Batteries
Asia-Pacific Industrial Battery Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
Asia-Pacific Battery Market
Batteries
North Europe Battery Market
Batteries
Modular Battery Pack Market
Batteries
Aluminum Wire Battery Market
Batteries
Portable Battery Powered Products Market
Batteries
PVT Battery Panel Market
Batteries
Zinc-Manganese Oxide Batteries Market
Batteries
Grid-Scale Flow Battery Stack Endurance Test Benches Market
Batteries
South America Micro Battery Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
United States Household Battery Market
Batteries
Aluminum-Air Battery Market
Batteries
Battery Light Towers Market