
 Battery Diagnostics and Repair Market | 2026-2036
Battery Diagnostics and Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Diagnostics and Repair Market Analytics
Aftermarket service revenue is narrowing toward high-margin diagnostic software and cell-level refurbishment as battery complexity outpaces traditional repair economics. Midtronics, Inc. anchors its position through deep channel control in automotive workshop networks across North America. Bosch Automotive Service Solutions Inc. leverages integrated tool-to-cloud platforms that link diagnostic hardware with service management systems. DV Power specializes in electrochemical testing rigs for industrial battery banks, occupying a defensible niche in utility-scale storage maintenance.
Battery diagnostics and repair encompasses the systematic assessment of electrochemical storage system health through voltage mapping, impedance spectroscopy, and thermal profiling, followed by targeted remediation ranging from module balancing to full cell replacement. The primary purpose is to extend operational life, prevent catastrophic failure, and recover residual value from lithium-ion and emerging solid-state systems. Testing Services commands the largest revenue pool today because fleet operators and OEMs mandate periodic state-of-health certification for warranty compliance and residual value guarantees. Smart Diagnostics is gaining share fastest as embedded sensors and edge-computing algorithms enable real-time degradation tracking without full discharge cycles. Repair Services remains structurally constrained by OEM software locks and proprietary battery management system architectures, concentrating margin in authorized networks while independent shops capture simpler thermal management and connector servicing.
FDA oversight applies to diagnostic equipment used in medical device battery systems, while EPA rules govern hazardous waste classification for damaged lithium-ion cells and recycling chain accountability. The EU Battery Regulation and CE marking requirements are forcing OEMs to design for disassembly and mandate state-of-health transparency at point of resale. Stakeholders must monitor whether right-to-repair legislation in multiple jurisdictions cracks open proprietary diagnostic interfaces or reinforces manufacturer-controlled service ecosystems.
Market Dynamics
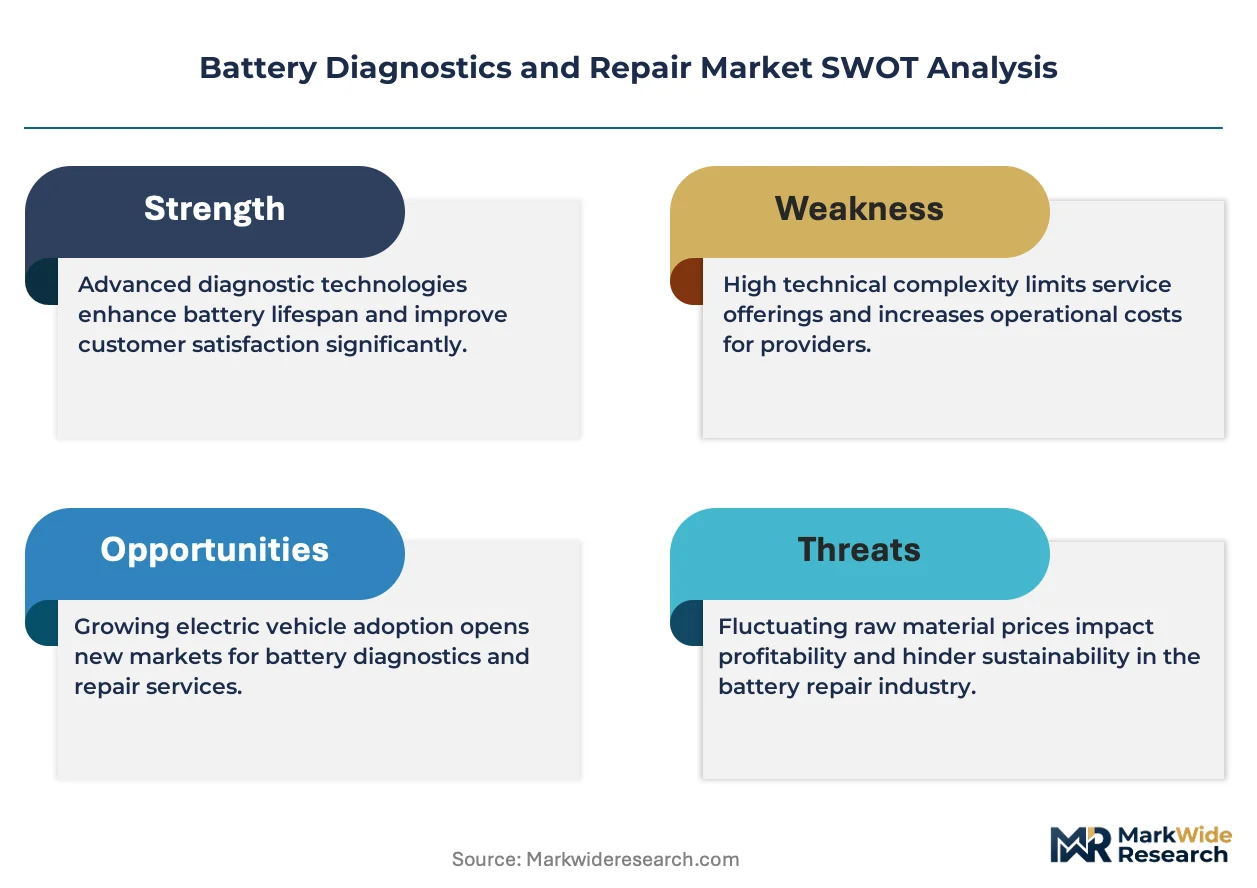
The Battery Diagnostics and Repair Market is being fundamentally restructured by the EU Battery Regulation's right-to-repair mandates and state-of-health disclosure requirements, which are forcing OEMs to open proprietary diagnostic interfaces and create certified refurbishment networks.
Growth Catalysts
- Fleet predictive maintenance contracts:Commercial vehicle operators in Germany and the Netherlands are mandating real-time battery health monitoring to optimize total cost of ownership and warranty compliance.
- CE marking and EU Battery Regulation:Extended producer responsibility rules require manufacturers to design for disassembly, creating downstream demand for authorized repair capacity and diagnostic tooling.
- Solid-state battery pilot programs:Early-stage manufacturing of next-generation cells in Japan and South Korea is generating specialized testing protocol development and technician certification needs.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings compress margins for independent refurbishers who cannot pass through input costs to fleet customers locked into long-term service agreements.
- OEM software lock architecture:Proprietary battery management system encryption prevents independent workshops from accessing cell-level diagnostics, concentrating repair revenue in manufacturer-authorized channels.
- Cobalt supply concentration:Dependence on Democratic Republic of Congo mining for cathode materials creates geopolitical risk that disrupts cell replacement part availability for high-nickel battery chemistries.
Strategic Opportunities
- Second-life stationary storage:Retired EV batteries with residual capacity are being redeployed for grid-scale buffering in California and Texas, requiring specialized grading and reconditioning services.
- India BIS certification expansion:The Bureau of Indian Standards is developing battery testing protocols for electric two-wheelers and three-wheelers, opening diagnostic service demand in a nascent but high-volume market.
- Cloud-integrated diagnostic hardware:Edge-computing tools that stream impedance data directly to fleet management platforms are creating recurring software revenue streams alongside hardware sales.
Industry Challenges
- Electrochemical engineer scarcity:The specialized skill set required for lithium-ion failure mode analysis and thermal runaway mitigation outpaces vocational training program output in all major markets.
- ISO 17025 accreditation timelines:Independent testing laboratories face 18-24 month certification cycles for state-of-health validation, delaying market entry for new service providers.
- Legacy lead-acid infrastructure:Existing workshop equipment and technician training programs require complete retooling to handle high-voltage lithium systems safely.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Diagnostics and Repair Market |
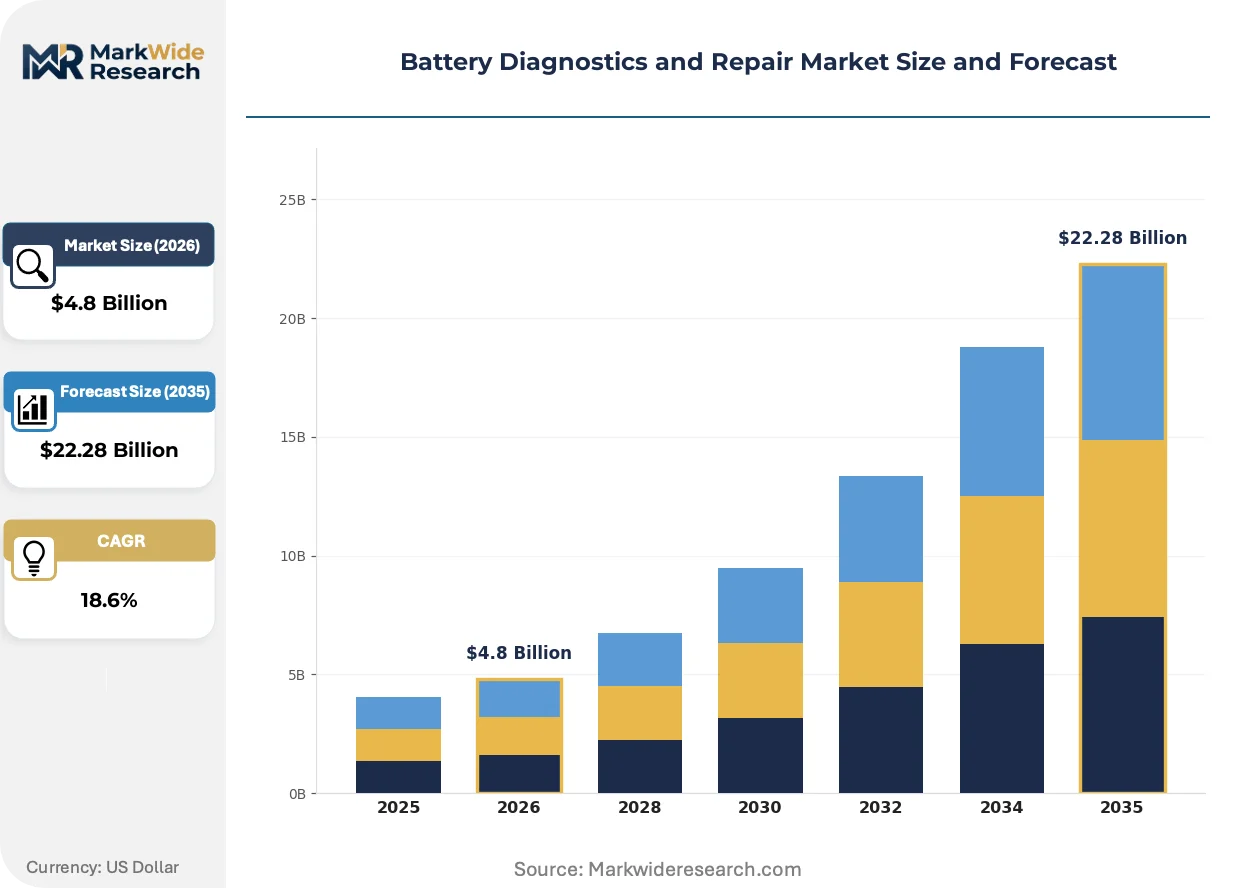
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Testing Services, Repair Services, Maintenance Services, Replacement Services Technology: Smart Diagnostics, Electrochemical Impedance Spectroscopy, Thermal Imaging, Data Analytics End User: Automotive Manufacturers, Fleet Operators, Repair Shops, Consumers Application: Electric Vehicles, Industrial Equipment, Consumer Electronics, Renewable Energy Systems |
| Companies Covered | AVILOO GmbH, Midtronics, Inc., DV Power, ENERSYS, Bosch Automotive Service Solutions Inc., Keysight Technologies, CycloChrome, Saft, Exponential Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Diagnostics and Repair Market Evolving Landscape
Diagnostic methodology is migrating from destructive full-discharge testing toward non-invasive electrochemical fingerprinting, enabled by embedded sensors and machine learning inference at the edge.
Electrochemical impedance spectroscopy is migrating from laboratory benchtops to handheld workshop devices. Automotive service networks in Germany and Japan are deploying these units for 15-minute state-of-health assessments. The technology is migrating from centralized testing facilities toward distributed point-of-service locations, compressing turnaround times and reducing logistics costs for fleet operators.
The EU Battery Regulation's digital battery passport requirement is mandating standardized data formats for state-of-health documentation. OEMs must now provide accessible diagnostic interfaces or face market access restrictions. European leasing companies and residual value guarantors are the most affected, responding by building captive refurbishment capacity to control asset lifecycles.
Service contract unbundling is separating diagnostic software subscriptions from hardware purchases and technician labor. Fleet managers in California and Texas are procuring cloud-based degradation monitoring as standalone SaaS offerings. This shift is most visible in commercial vehicle electrification programs where total cost of ownership modeling drives procurement decisions.
Battery Diagnostics and Repair Market Segmentation
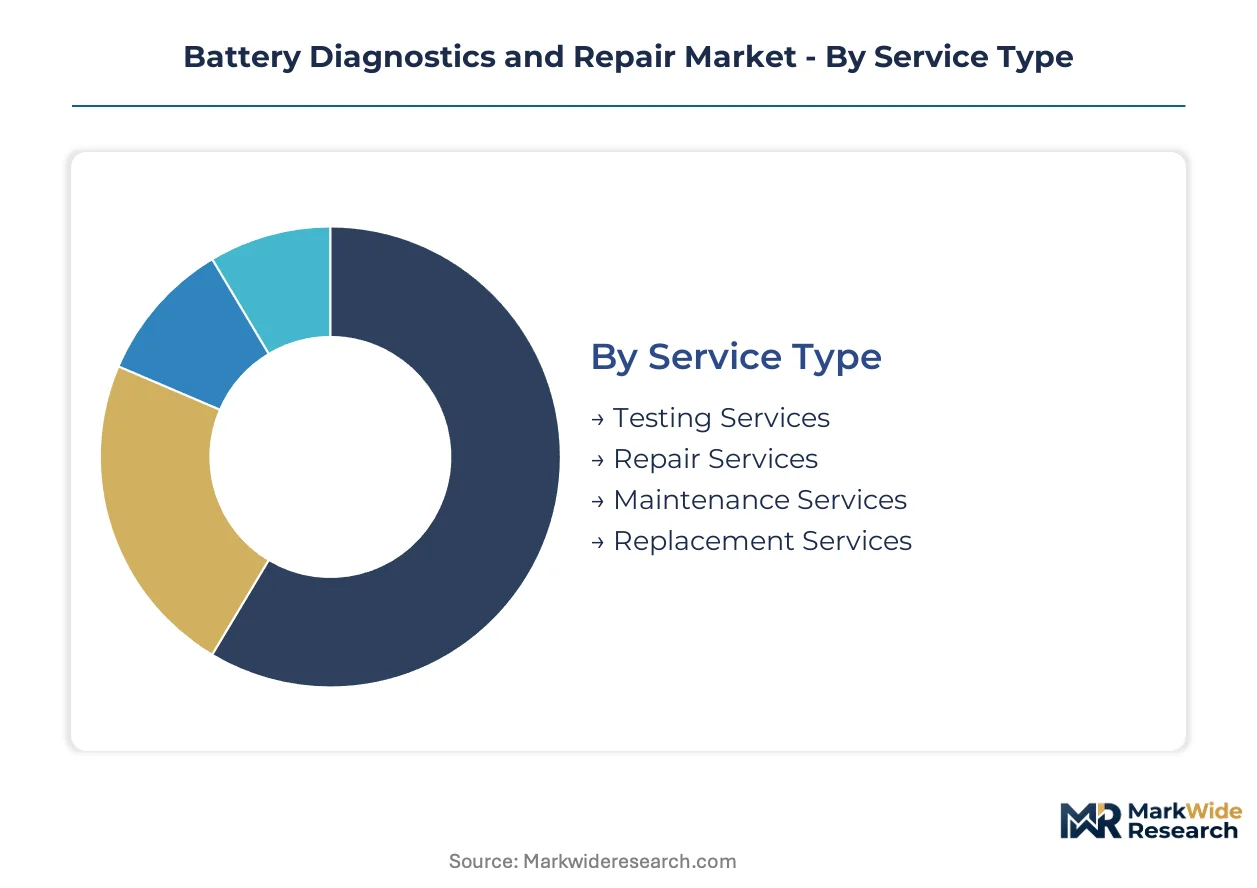
Service intensity varies dramatically across battery diagnostics segments, with predictive maintenance contracts reshaping how revenue flows between testing, repair, and replacement activities. Fleet operators now demand integrated service bundles that combine real-time monitoring with guaranteed turnaround times. Understanding these segment boundaries clarifies where margin concentrates versus where volume commoditizes.
Service Type:
After-sales service intensity peaks in recurring maintenance contracts rather than one-time interventions, shifting vendor economics toward subscription-based revenue models.
- Testing Services:Systematic assessment of electrochemical storage health through voltage mapping, impedance spectroscopy, and thermal profiling to certify state-of-health for warranty compliance. German fleet operators and residual value guarantors mandate periodic certification, creating recurring revenue pools for authorized diagnostic networks.
- Repair Services:Targeted remediation ranging from module balancing to full cell replacement, constrained by OEM software locks and proprietary battery management system architectures. Independent workshops capture simpler thermal management and connector servicing while authorized networks monopolize cell-level interventions.
- Maintenance Services:Preventive care protocols including thermal management system cleaning, firmware updates, and connector integrity checks. California commercial vehicle electrification programs bundle these into total cost of ownership contracts.
- Replacement Services:Full pack swap operations for end-of-life or catastrophic failure scenarios, dominated by OEM-controlled supply chains for proprietary form factors.
Testing Services commands the largest revenue pool today; momentum sits with Maintenance Services as predictive contracts displace reactive repair models.
Technology:
Diagnostic technology investment tracks directly with battery chemistry complexity, with solid-state pilot programs demanding entirely new testing protocols.
- Smart Diagnostics:Embedded sensors and edge-computing algorithms enable real-time degradation tracking without full discharge cycles. Fleet management platforms in the Netherlands stream impedance data continuously to optimize charging schedules and residual value forecasting.
- Electrochemical Impedance Spectroscopy:Laboratory-grade frequency response analysis now migrating to handheld workshop devices for 15-minute health assessments. Japanese automotive service networks deploy these units at distributed point-of-service locations.
- Thermal Imaging:Non-contact detection of cell-level hot spots and thermal runaway precursors using infrared cameras. Texas grid-scale storage operators use these for utility-scale battery bank monitoring.
- Data Analytics:Cloud-based degradation modeling and predictive failure algorithms trained on fleet-wide operational datasets. California leasing companies procure these as standalone SaaS offerings separate from hardware.
Electrochemical Impedance Spectroscopy anchors current diagnostic hardware revenue; Smart Diagnostics climbs fastest as embedded sensor costs decline.
End User:
Procurement sophistication diverges sharply between captive OEM networks and fragmented independent channels, with fleet operators driving standardization demands.
- Fleet Operators:Commercial vehicle and logistics companies mandating real-time battery health monitoring to optimize total cost of ownership. German and Dutch operators lock in long-term predictive maintenance contracts with guaranteed uptime clauses.
- Automotive Manufacturers:OEMs building certified refurbishment capacity to control asset lifecycles under EU Battery Regulation extended producer responsibility. European leasing companies respond by developing captive repair networks.
- Repair Shops:Independent and authorized service networks competing for simpler thermal and connector work while excluded from cell-level diagnostics by encryption protocols.
- Consumers:Individual EV owners seeking warranty-preserving service at lowest cost, price-sensitive and geographically dispersed.
Fleet Operators concentrate the highest service contract value; Automotive Manufacturers are expanding most quickly into vertical refurbishment integration.
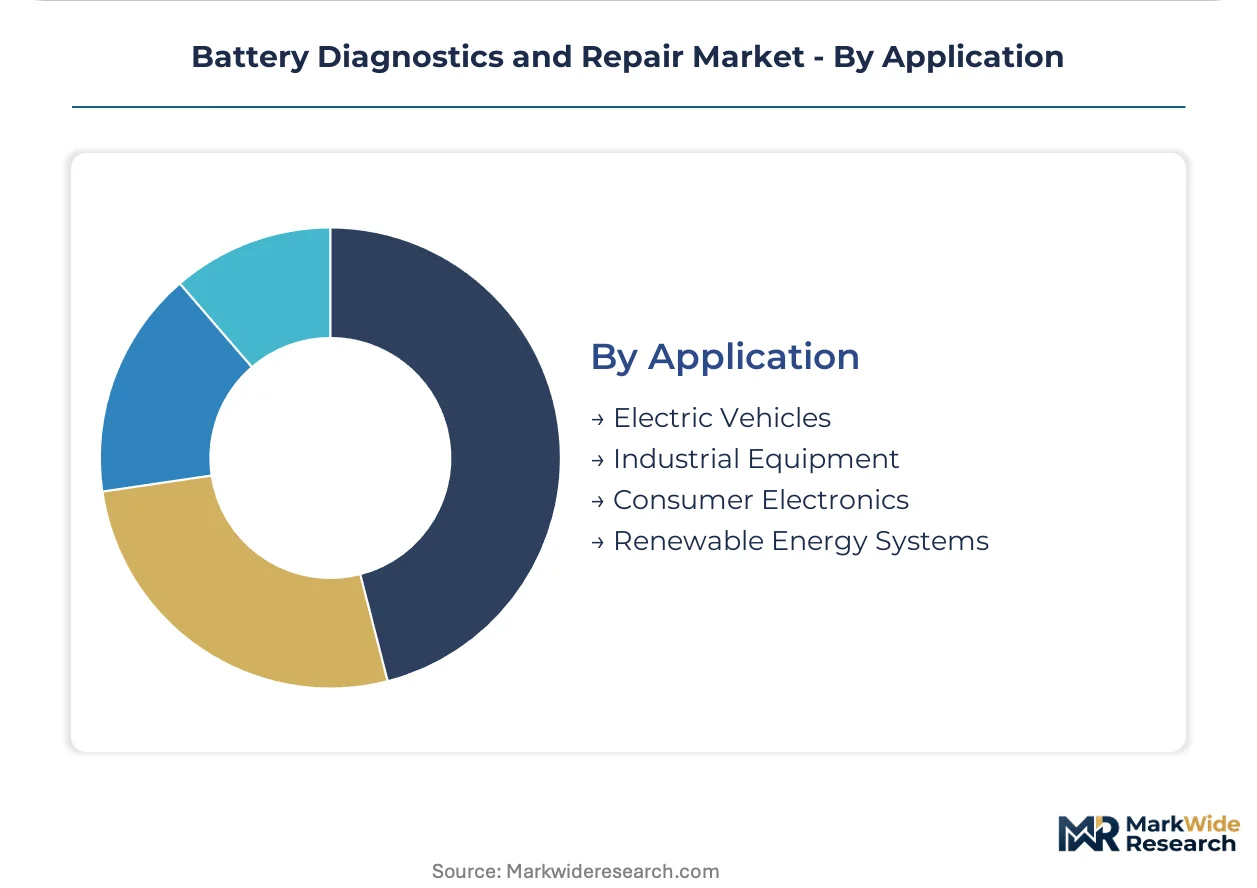
Application:
Application-specific failure modes dictate diagnostic tooling requirements, with stationary storage presenting distinct degradation signatures versus mobile applications.
- Electric Vehicles:High-cycle, vibration-exposed systems requiring dynamic state-of-health assessment under variable load profiles. Second-life redeployment to California and Texas grid storage creates downstream grading demand.
- Renewable Energy Systems:Stationary storage installations with deep discharge cycles and temperature-stressed thermal management. Utility-scale operators in Texas require specialized testing rigs for industrial battery bank maintenance.
- Industrial Equipment:Forklifts, material handling, and heavy machinery with high-utilization duty cycles and standardized pack geometries.
- Consumer Electronics:Low-voltage, high-volume devices with limited repair economics and dominant replacement preference.
Electric Vehicles holds the dominant installed base; Renewable Energy Systems gain share fastest as retired EV batteries flow into grid-scale buffering applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic equipment manufacturing clusters in Germany, the United States, Japan, and South Korea supply the majority of advanced testing hardware. Service network expansion concentrates in markets with high EV penetration and regulatory mandates for battery health transparency.
Germany
KBA enforcement of EU Battery Regulation state-of-health disclosure rules drives fleet operator demand for certified diagnostic networks. The country's extended producer responsibility framework compels OEMs to build authorized refurbishment capacity. Stuttgart and Munich host concentrated automotive service engineering clusters where Bosch and independent networks deploy electrochemical testing rigs.
United States
EPA hazardous waste classification rules for damaged lithium-ion cells shape recycling chain accountability requirements. California and Texas grid operators deploy specialized grading services for second-life stationary storage applications. The NHTSA maintains oversight of diagnostic equipment used in vehicle safety systems.
Japan
METI solid-state battery pilot programs generate specialized testing protocol development needs. Automotive service networks in Nagoya and Osaka deploy handheld electrochemical impedance spectroscopy devices for distributed point-of-service health assessments. JIS standards govern diagnostic equipment certification.
South Korea
MFDS and METI-aligned standards for next-generation cell manufacturing drive technician certification program expansion. Seoul-based battery makers fund captive diagnostic tooling development for internal quality control. The country's utility-scale storage operators import industrial testing rigs for lithium-ion bank maintenance.
India
BIS certification expansion for electric two-wheeler and three-wheeler batteries opens diagnostic service demand in high-volume segments. Maharashtra and Gujarat manufacturing corridors attract testing equipment distributors serving nascent OEM service networks. Central Electricity Authority guidelines for energy storage safety create compliance-driven inspection requirements.
Battery Diagnostics and Repair Market Competitive Landscape
Integrated tool-to-cloud platform providers and specialized electrochemical testing rig manufacturers split the market along service intensity lines. The vendor base concentrates in three strategic archetypes: automotive workshop network suppliers, industrial battery bank specialists, and emerging cloud-integrated diagnostic software vendors. Dominant competitive moves include strategic partnerships linking hardware OEMs with fleet management platforms and geographic expansion into regulatory-mandated certification markets.
Within the automotive workshop network tier, Midtronics, Inc. and Bosch Automotive Service Solutions Inc. exemplify integrated platform strategies. DV Power occupies a position among industrial-scale testing specialists serving utility storage operators. These three anchors represent divergent approaches to channel control, with workshop-focused players leveraging existing service relationships while industrial specialists target direct procurement from grid operators and fleet managers.
| Leading Market Players |
|---|
| AVILOO GmbH |
| Midtronics, Inc. |
| DV Power |
| ENERSYS |
| Bosch Automotive Service Solutions Inc. |
| Keysight Technologies |
| CycloChrome |
| Saft |
| Exponential Power |
| Others |
Value Network & Pricing Analysis
Overcapacity in South Korean electrochemical testing rig manufacturing is compressing hardware margins while simultaneously enabling aggressive SaaS bundling strategies that lock fleet operators into long-term diagnostic subscriptions. This utilization imbalance feeds directly into supplier behavior: foundries with idle capacity absorb upfront equipment costs to capture recurring software revenue streams, shifting pricing power toward integrated platform providers and away from standalone hardware vendors.
Pricing Analysis
The EU Battery Regulation dictates the pricing tier structure across the diagnostic services landscape. Three-tier pricing stratifies across authorized certification networks, independent workshops with limited cell access, and commodity connector servicing. Price differentiation rests on ISO 17025 accreditation status and proprietary interface licensing from automotive OEMs. Pricing pressure stems from lithium carbonate volatility squeezing independent refurbisher margins. Fleet operators locked into predictive maintenance contracts exhibit the lowest price sensitivity, while individual consumers seeking warranty-preserving service drive aggressive cost competition at the economy tier.
Supply Chain Analysis
Contract manufacturing for handheld diagnostic devices concentrates in Taiwan and South Korea, with industrial-scale testing rigs assembled in Germany and Japan. Raw material dependencies span lithium carbonate from Chile and Australia, cobalt cathode precursors from the Democratic Republic of Congo, and specialized semiconductor components from Taiwanese foundries. Single-source vulnerability around BMS encryption chip supply creates bottlenecks for independent diagnostic tool developers. Distribution runs through automotive service equipment distributors in Europe and direct procurement channels for utility-scale operators in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across service intensity levels creates multiple viable entry points, as the shift from reactive repair toward predictive maintenance contracts splinters demand across embedded sensor providers, cloud analytics platforms, and specialized electrochemical testing hardware.
For Market Incumbents: Entrench channel control through exclusive predictive maintenance contracts with German and Dutch fleet operators facing EU Battery Regulation compliance deadlines. Deepen backward integration into proprietary BMS interface licensing to defend against emerging cloud-integrated diagnostic software vendors eroding hardware attach rates. Prioritize ISO 17025 accreditation investments that independent competitors cannot replicate within 18-24 month certification windows. For New Entrants and Emerging Players: Establish a beachhead in second-life stationary storage grading services for California and Texas grid operators retiring EV batteries into grid-scale buffering applications. Target the India BIS certification expansion for electric two-wheeler and three-wheeler diagnostic protocols, where nascent OEM service networks lack captive testing capacity. Deploy cloud-native degradation monitoring as standalone SaaS offerings unbundled from hardware sales, mirroring procurement patterns visible in California commercial vehicle electrification programs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-integrated diagnostic platform providers with fleet management system integrations, positioning these archetypes for superior cash flow quality across a multi-year electrification investment cycle. Prioritize acquisition targets with embedded sensor-to-edge-computing technology stacks and existing technician certification program infrastructure. Watch for inflection signals in right-to-repair legislation progression across multiple jurisdictions, which would abruptly revalue proprietary diagnostic interface assets.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Integrated Diagnostic Platform Launch | Enables recurring SaaS revenue streams alongside hardware sales for fleet operators. |
| ISO 17025 Laboratory Accreditation Investment | Creates 18-24 month competitive moats against independent testing service entrants. |
| Second-Life Battery Grading Service Expansion | Captures downstream demand from California and Texas grid-scale storage operators. |
| Technician Certification Program Development | Addresses electrochemical engineer scarcity constraining service network expansion. |
| Proprietary BMS Interface Licensing Agreement | Secures cell-level diagnostic access against right-to-repair regulatory uncertainty. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with fleet operations managers, automotive service network directors, electrochemical testing equipment procurement leads, and independent refurbishment facility owners. Secondary validation drew from EU Battery Regulation implementation documents, KBA enforcement guidance, EPA hazardous waste classification rulings, BIS certification draft protocols, and automotive OEM service bulletins. Bottom-up segment sizing triangulated against top-down market envelope estimates from production and import data.
Calibration against historical adoption curves for comparable predictive maintenance technologies anchored growth assumptions across the projection horizon. Segmentation dimensions modeled include service type intensity, diagnostic technology architecture, end-user procurement sophistication, and application-specific failure mode signatures. CAGRs were derived from installed base expansion rates coupled with service contract penetration assumptions. Industry-specific forecast inputs incorporated solid-state battery pilot program timelines and right-to-repair legislative tracking across multiple jurisdictions.
Stress conditions across lithium carbonate price bands, OEM software lock persistence, and electrochemical engineer training program output were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and fleet electrification commitment durability. Quarterly review of EU Battery Regulation implementation pace, India BIS certification rollout timing, and second-life storage deployment volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Advanced Batteries Market
Batteries
Nickel-Metal Hydride (Ni-MH) Battery Market
Batteries
Norway Rechargeable Battery Market
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market
Batteries
North America Rechargeable Battery Market
Batteries
Lithium Battery Testing System Market
Batteries
Consumer Battery Market
Batteries
Global Coke Oven Batteries Market
Batteries
Zinc Ion Batteries Market
Batteries
Myanmar Battery Market
Batteries
Water-Based Zinc-Ion Battery Market
Batteries
Iron-Chromium Flow Battery Market
Batteries
Micro Battery Market
Batteries
PVT Battery Panel Market
Batteries
Aluminium-Sulfur Battery Market
Batteries
Second-Life EV Battery Module Qualification Test Systems Market