
 Global Lithium Titanate (LTO) Batteries Market | 2026-2036
Global Lithium Titanate (LTO) Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lithium Titanate (LTO) Batteries Market Foresight
The EU Green Deal is pivoting commercial vehicle procurement standards across European transportation fleets toward chemistries with extended cycle durability. Toshiba Corporation leverages its proprietary SCiB technology to anchor premium positioning in fast-charging industrial applications. Yinlong Energy International Pte Ltd. competes on aggressive manufacturing scale across China's electric bus supply chain. Microvast Holdings, Inc. specializes in modular pack architectures for North American transit operators seeking rapid depot turnaround.
Lithium titanate batteries employ Li4Ti5O12 as the anode active material, enabling charge rates exceeding 6C without lithium plating damage while delivering over 15,000 cycles at 80% depth of discharge. Their primary commercial purpose centers on applications demanding extreme longevity and rapid energy replenishment where downtime carries disproportionate cost. Prismatic formats dominate grid energy storage deployments due to superior thermal stacking density and structural rigidity in containerized installations. Fast charging technology leads electric bus adoption where route schedules mandate sub-ten-minute opportunity charging. Cylindrical cells sustain niche demand in autonomous robots requiring standardized form factors for rapid field swap protocols.
China's MIIT enforces GB standards for battery safety testing that LTO chemistries satisfy more readily than conventional lithium-ion variants due to inherent thermal stability. The EU AI Act and CSRD disclosure frameworks compel European renewable energy firms to document supply chain provenance, favoring cells with verifiable low-carbon production trails. Japan's METI subsidizes domestic battery material independence, reinforcing Toshiba and NICHICON Corporation's captive anode supply positions. Stakeholders must monitor how F-Gas Regulation phase-downs affect thermal management system costs in European grid installations.
Market Dynamics
The convergence of extreme fast-charging requirements in commercial electric fleets and tightening carbon disclosure mandates is compressing supplier qualification timelines while favoring chemistries with demonstrable cycle longevity.
Growth Catalysts
- EU Battery Regulation carbon footprint rules:Mandatory disclosure of embedded emissions across cell production favors LTO's inherently stable manufacturing profile and extended service life metrics.
- Electric bus opportunity charging infrastructure:Transit agencies in China and European metropolitan networks are mandating sub-ten-minute depot turnaround protocols that only lithium titanate chemistries reliably deliver.
- Grid-scale frequency regulation contracts:Independent power producers value the chemistry's 15,000-plus cycle durability for daily cycling revenue streams in ancillary services markets.
Market Restraints
- Vanadium and titanium feedstock cost volatility:LTO anode production depends on titanium dioxide supply chains concentrated in Chinese pigment manufacturing, exposing cell producers to input price swings.
- Energy density penalty versus NMC alternatives:The 70-80 Wh/kg gravimetric performance limits deployment in weight-constrained applications such as long-haul aviation or premium passenger electric vehicles.
- REACH substance authorization complexity:European chemical registration requirements for novel electrolyte additives create compliance friction for LTO pack assemblers importing cells from non-EU manufacturing bases.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic manufacturing incentives targeting 50 GWh annual capacity create first-mover positioning for LTO specialists establishing local anode production.
- Autonomous mobile robot fleet charging:Warehouse automation deployers seek standardized cylindrical formats enabling sub-two-minute battery swap protocols without thermal management complexity.
- Japan METI battery material independence subsidies:Government funding for domestic anode supply chain development reinforces captive production advantages for established Japanese LTO producers.
Industry Challenges
- Electrolyte formulation expertise scarcity:The specialized knowledge required for high-rate electrolyte stability at low temperatures remains concentrated among a limited pool of electrochemists in Japanese and South Korean R&D centers.
- Pack-level thermal management integration:System engineers face complexity harmonizing LTO's flat voltage profile with legacy battery management architectures designed for conventional lithium-ion charge curves.
- UN 38.3 transport certification timelines:Extended testing protocols for high-capacity prismatic cells delay market entry for new product variants targeting maritime and aviation freight applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lithium Titanate (LTO) Batteries Market |
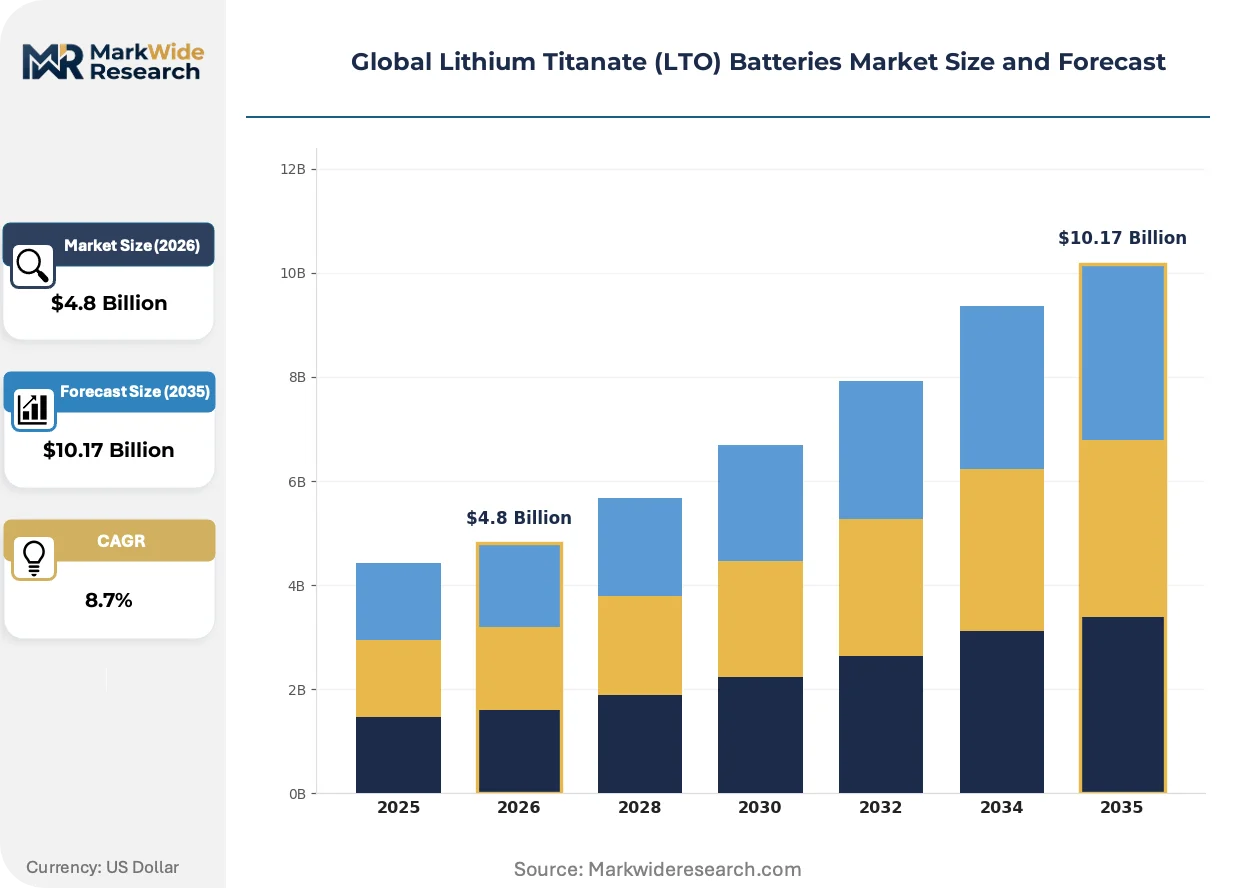
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Pouch, Module Technology: Fast Charging, High Power Density, Long Cycle Life, Low Temperature Performance Application: Grid Energy Storage, Electric Buses, Military Vehicles, Autonomous Robots End User: Telecommunication Providers, Renewable Energy Firms, Transportation Fleets, Defense Organizations |
| Companies Covered | Altair Nanotechnologies Inc., XALT Energy, Toshiba Corporation, NICHICON Corporation, Dongturbo Electric Company Ltd., Microvast Holdings, Inc., Yinlong Energy International Pte Ltd., ELB Energy Group, Leclanché SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lithium Titanate (LTO) Batteries Market Shifts & Advancements
Active materials engineering and regulatory disclosure frameworks are simultaneously pulling LTO technology toward higher energy density variants and verifiable low-carbon supply chains. These pressures are reshaping competitive differentiation beyond cycle life metrics alone.
Silicon-doped lithium titanate composites are electrifying next-generation anode formulations by boosting reversible capacity above 200 mAh/g while preserving structural integrity. Chinese electric bus manufacturers are piloting these materials in 2024 fleet trials. The technology is electrifying procurement specifications toward energy-density-adjusted total cost of ownership rather than upfront cell pricing.
CSRD disclosure mandates are compelling European renewable energy storage developers to document scope three emissions across cell supply chains. Asset managers now require battery procurement teams to secure production trail documentation from anode precursor through final pack assembly. Grid-scale storage tenders in Germany and the Netherlands are increasingly weighting carbon intensity scores at 15-20% of technical evaluation criteria.
Chinese transit operators are consolidating procurement authority under provincial fleet management entities, displacing fragmented municipal purchasing. These aggregated buyers negotiate multi-year supply agreements directly with cell manufacturers, bypassing traditional distributor networks. The concentration is most visible in Guangdong and Jiangsu provinces, where electric bus fleets exceed 10,000 vehicles per operator group.
Global Lithium Titanate (LTO) Batteries Market Segmentation
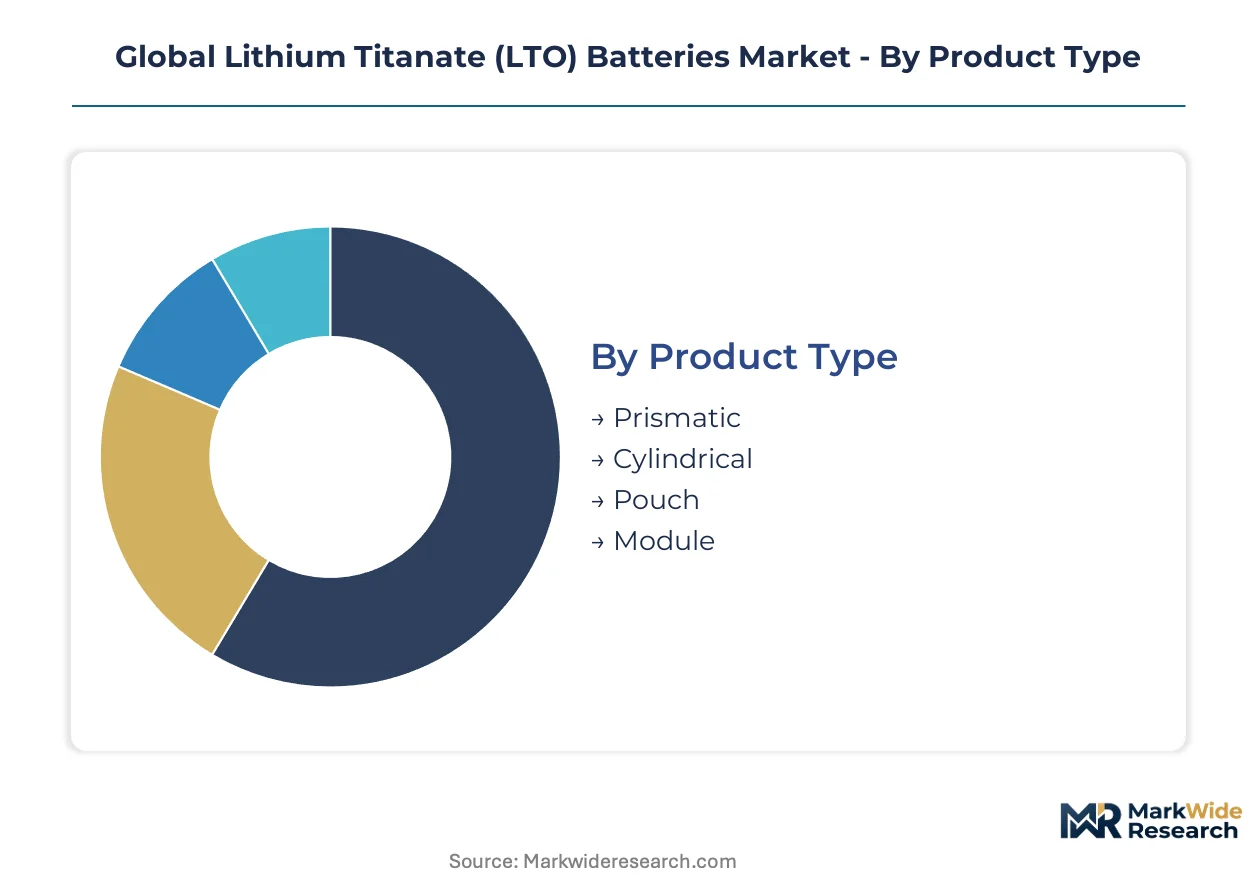
Segmentation in the LTO battery market reflects divergent capital requirements across form factors, performance tiers, and end-use certifications. Procurement patterns cluster around applications where cycle durability justifies premium pricing over energy density trade-offs.
Product Type:
Prismatic formats demand the heaviest upfront tooling investment due to precision aluminum housing fabrication and laser welding infrastructure. Cylindrical production lines achieve faster amortization through standardized winding equipment.
- Prismatic:Rectangular aluminum-cased cells stack efficiently in containerized grid installations. China's State Grid Corporation specifications favor this format for 100 MWh-plus frequency regulation projects in Jiangsu and Guangdong provinces. Thermal stacking density and structural rigidity offset higher cell-level costs.
- Cylindrical:Standardized 18650 and 21700 formats enable rapid field swap protocols in warehouse automation fleets. Japanese robotics manufacturers specify cylindrical LTO packs for autonomous mobile robots requiring sub-two-minute battery exchanges without thermal management complexity.
- Pouch:Flexible polymer-housed cells serve weight-sensitive military applications where conformal packing maximizes volumetric efficiency in vehicle hull compartments.
- Module:Pre-integrated pack architectures reduce system integration labor for North American transit operators seeking rapid depot deployment.
Most installed capacity flows through Prismatic formats. Expansion is steepest in Module configurations as transit agencies consolidate procurement under fleet management entities.
Technology:
Performance differentiation separates premium pricing tiers from commodity positioning, with fast-charging commanding the steepest R&D investment recovery.
- Fast Charging:Electrolyte formulations enabling 6C-plus charge rates without lithium plating require fluorinated additive packages and precision formation protocols. European metropolitan bus networks in Germany and the Netherlands mandate sub-ten-minute opportunity charging that only this technology reliably delivers.
- High Power Density:Optimized electrode architectures prioritize discharge rate capability over absolute capacity. Japanese industrial equipment manufacturers specify these cells for automated guided vehicles in just-in-time manufacturing lines.
- Long Cycle Life:Conservative depth-of-discharge algorithms and ceramic-coated separators target 20,000-plus cycle performance. German renewable energy storage developers weight this specification heavily in CSRD-compliant procurement tenders.
- Low Temperature Performance:Propylene carbonate electrolyte blends maintain ionic conductivity below minus 20 degrees Celsius. Scandinavian grid operators specify these variants for frequency regulation contracts in subarctic climates.
Fast Charging captures the dominant share of new patent filings. Low Temperature Performance is gaining share fastest as Nordic markets accelerate battery storage deployment.
Application:
Application segmentation tracks divergent duty cycles and certification burdens, with military specifications imposing the most stringent qualification timelines.
- Grid Energy Storage:Daily cycling revenue streams in ancillary services markets exploit the chemistry's 15,000-plus cycle durability. Independent power producers in Germany and the Netherlands value flat degradation curves for 20-year asset financing.
- Electric Buses:Route schedules mandating opportunity charging at terminus points concentrate demand in Chinese provincial fleet operators. Guangdong and Jiangsu province procurement entities negotiate multi-year supply agreements directly with cell manufacturers.
- Military Vehicles:MIL-STD-810G vibration and ballistic tolerance requirements filter supplier pools to established defense contractors. Thermal runaway containment specifications exceed commercial standards.
- Autonomous Robots:Standardized cylindrical formats and rapid swap protocols prioritize operational uptime over absolute range. Warehouse automation deployers in Japan and South Korea specify these packs.
Grid Energy Storage accounts for the largest cumulative installed base. Electric Buses are expanding most quickly as Chinese transit electrification accelerates.
End User:
End user categories reflect distinct procurement authority structures, with defense organizations maintaining the most centralized purchasing processes.
- Telecommunication Providers:Base station backup power applications prioritize 20-year service life over energy density. India's Reliance Jio and Bharti Airtel specify LTO for rural tower installations with limited maintenance access.
- Renewable Energy Firms:CSRD disclosure mandates compel European developers to document scope three emissions across cell supply chains. Asset managers now require production trail documentation from anode precursor through final pack assembly.
- Transportation Fleets:Consolidated provincial procurement in China displaces fragmented municipal purchasing. Aggregated buyers in Guangdong province negotiate directly with manufacturers.
- Defense Organizations:National security supply chain requirements favor domestic or allied-nation cell production. Japan's Acquisition, Technology and Logistics Agency specifies METI-subsidized domestic sources.
Transportation Fleets channel the greatest procurement volume. Renewable Energy Firms are climbing the fastest as European carbon disclosure rules tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium titanate battery manufacturing originated in Japanese industrial laboratories during the early 2000s, with Toshiba Corporation's SCiB technology establishing the foundational production protocols that Chinese and South Korean competitors later adapted at scale.
China
Provincial fleet operators in Guangdong and Jiangsu provinces negotiate multi-year supply agreements directly with cell manufacturers, bypassing traditional distributor networks. MIIT enforces GB standards for battery safety testing that LTO chemistries satisfy more readily than conventional lithium-ion variants. The Pearl River Delta manufacturing cluster hosts integrated anode precursor facilities feeding dedicated LTO cell assembly lines.
Japan
METI subsidizes domestic battery material independence, reinforcing captive anode supply positions for established producers. The Kanto region around Tokyo maintains concentrated electrochemist expertise for high-rate electrolyte formulation at low temperatures. Japanese robotics manufacturers in the Chubu industrial corridor specify cylindrical LTO packs for autonomous mobile robots requiring rapid field swap protocols.
Germany
Independent power producers value LTO chemistry's flat degradation curves for 20-year asset financing of grid-scale frequency regulation projects. The EU Battery Regulation and CSRD disclosure frameworks compel renewable energy developers to document scope three emissions across cell supply chains. Grid storage tenders in North Rhine-Westphalia weight carbon intensity scores at 15-20% of technical evaluation criteria.
United States
North American transit operators seek modular pack architectures enabling rapid depot turnaround without extensive thermal management infrastructure. The FERC regulatory environment shapes revenue stacking strategies for battery storage assets participating in ancillary services markets. California's aggressive fleet electrification mandates drive procurement specifications emphasizing cycle durability over energy density metrics.
India
The PLI scheme for advanced chemistry cells targets 50 GWh annual domestic manufacturing capacity, creating first-mover positioning for LTO specialists establishing local anode production. Reliance Jio and Bharti Airtel specify LTO for rural telecommunications base stations prioritizing 20-year service life over maintenance access. Tamil Nadu and Gujarat industrial corridors attract cell assembly investments through production-linked incentive structures.
Global Lithium Titanate (LTO) Batteries Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the LTO battery landscape. Japanese and South Korean incumbents maintain captive anode supply chains and proprietary electrolyte formulations, while Chinese fabricators exploit manufacturing scale advantages in electric bus procurement. Three archetypes dominate: technology originators with decades of materials science IP, scale-driven volume producers serving consolidated transit fleets, and system integrators specializing in modular pack architectures for rapid deployment. Competitive dynamics center on backward integration into titanium dioxide precursor supply and geographic expansion through local manufacturing incentives.
Among technology originators, Toshiba Corporation and NICHICON Corporation exemplify the premium-tier positioning built on proprietary SCiB formulations and METI-subsidized domestic supply chain control. Yinlong Energy International Pte Ltd. and Microvast Holdings, Inc. represent contrasting scale strategies—Chinese manufacturing concentration versus North American system integration focus. Altair Nanotechnologies Inc. occupies a specialist position within the materials science tier, while XALT Energy and Leclanché SA anchor European manufacturing presence for CSRD-compliant procurement channels.
| Leading Market Players |
|---|
| Altair Nanotechnologies Inc. |
| XALT Energy |
| Toshiba Corporation |
| NICHICON Corporation |
| Dongturbo Electric Company Ltd. |
| Microvast Holdings, Inc. |
| Yinlong Energy International Pte Ltd. |
| ELB Energy Group |
| Leclanché SA |
| Others |
Supply & Pricing Matrix
Consolidated provincial fleet operators in Guangdong and Jiangsu provinces negotiate multi-year offtake agreements directly with cell manufacturers, compressing margin capture for intermediaries and anchoring contract-based long-term pricing as the dominant commercial model. This buyer concentration enables volume-scaled procurement that displaces spot-market transactions across China's electric bus supply chain.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates METI-subsidized Japanese producers with captive anode supply from Chinese scale fabricators and modular pack assemblers serving North American transit operators. Price differentiation rests on certification grade for EU Battery Regulation carbon disclosure compliance and after-sales service bundling for depot infrastructure support. Cost compression in the economy tier is intensifying because titanium dioxide feedstock volatility exposes non-integrated producers to margin erosion. Transportation fleets exhibit the sharpest price sensitivity, while grid-scale independent power producers prioritize flat degradation curves over upfront cell cost.
Supply Chain Analysis
End-of-life cell recovery flows remain underdeveloped, with limited refurbishment infrastructure for LTO's 15,000-plus cycle assets creating stranded value in early-deployment bus fleets. Manufacturing concentrates in China, Japan, and South Korea, with the Pearl River Delta hosting integrated titanium dioxide precursor facilities feeding dedicated cell assembly lines. Raw material dependencies draw from Chinese pigment manufacturing for titanium dioxide, Japanese electrochemist expertise for high-rate electrolyte additives, and South Korean separator technology. Single-source vulnerability in titanium dioxide supply chains concentrated in Chinese pigment manufacturing exposes cell producers to input price swings. Distribution runs through direct manufacturer relationships with consolidated provincial fleet operators, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI scheme production-linked incentives for domestic cell manufacturing create cost positioning unavailable in European markets burdened by REACH substance authorization complexity and CSRD disclosure compliance costs.
For Market Incumbents: To counter silicon-doped lithium titanate composite formulations threatening energy-density advantages, Toshiba Corporation and NICHICON Corporation should deepen backward integration into titanium dioxide precursor supply chains and expand METI-subsidized domestic anode production capacity. Capacity addition in India's Tamil Nadu and Gujarat industrial corridors captures PLI scheme benefits before incentive windows narrow. For New Entrants and Emerging Players: The mid-tier price-point gap between premium Japanese SCiB technology and economy-tier Chinese bus fleet cells creates entry space for specialists offering CSRD-compliant documentation without METI-level R&D overhead. India's telecommunications base station backup power segment presents the most penetrable geography, with Reliance Jio and Bharti Airtel specifications prioritizing 20-year service life over energy density. A go-to-market angle anchored in modular pack architectures for rapid depot deployment without extensive thermal management infrastructure differentiates against integrated cell producers. For Investors and Strategic Acquirers: Electric vehicle platform developers are the most active acquirer in this space, seeking captive battery supply for commercial fleet electrification roadmaps. Long-term viability over a multi-year horizon hinges on chemistry cost convergence with NMC alternatives in grid-scale applications. Acquisition targets should display backward integration into titanium dioxide precursor supply or established CSRD-compliant production trail documentation. Practitioners should monitor F-Gas Regulation phase-down impacts on thermal management system costs in European grid installations for early signals of competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Dioxide Precursor Supply | Captive anode material sourcing insulates Toshiba and NICHICON from Chinese pigment manufacturing price volatility. |
| CSRD-Compliant Production Trail Documentation | Verifiable scope three emissions data secures German and Dutch grid storage tender evaluation criteria weighting. |
| Modular Pack Architecture Development | Pre-integrated systems reduce North American transit operator depot deployment labor and thermal management complexity. |
| Silicon-Doped Anode Formulation Investment | Reversible capacity above 200 mAh/g preserves structural integrity while narrowing energy-density gaps with NMC alternatives. |
| India PLI Scheme Manufacturing Localization | Domestic cell assembly in Tamil Nadu and Gujarat corridors captures 50 GWh incentive-targeted capacity allocation. |
Research Methodology
Direct dialogue with cell manufacturing executives, transit fleet procurement directors, grid-scale project developers, and electrochemist specialists in Japanese and South Korean R&D centers grounded qualitative assessment in operational reality. Secondary validation drew from MIIT GB standards documentation, EU Battery Regulation implementation guidance, METI subsidy program disclosures, and FERC ancillary services market filings. Bottom-up cell production capacity estimates and top-down application demand projections were cross-referenced to establish market sizing boundaries.
Installed base and revenue projections across the analysis window reflect segment-level modeling of prismatic, cylindrical, pouch, and module form factors intersecting with fast charging, high power density, long cycle life, and low temperature performance technology tiers. CAGRs were derived from regression analysis of historical procurement patterns in Chinese provincial fleet operators and German frequency regulation contract awards. Forecast inputs incorporated titanium dioxide feedstock price indices, GB standards testing timeline assumptions, and CSRD disclosure framework implementation schedules.
Caveats apply where electrolyte formulation expertise scarcity concentration, UN 38.3 transport certification timeline extensions, or F-Gas Regulation thermal management cost impacts could materially shift the outlook. Forecasts reflect assumptions regarding sustained electric bus procurement acceleration in Guangdong and Jiangsu provinces and continued METI material independence subsidy continuity. Practitioners should monitor silicon-doped lithium titanate composite pilot fleet trial outcomes and India PLI scheme capacity allocation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Deep Cycle Battery Market
Batteries
Lithium Battery Testing System Market
Batteries
Denmark Rechargeable Battery Market
Batteries
Lithium Pouch Cell Market
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
High Temperature NiMH Battery Market
Batteries
Latin America Automotive Lead-Acid Battery Market
Batteries
Europe Automotive Lead-Acid Battery Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
North America NMC Battery Pack Market
Batteries
Global Industrial Lead Acid Battery Market
Batteries
Cylindrical Lithium Battery Winding Machine Market
Batteries
Coin Cell Lithium Batteries Market
Batteries
Battery Cell Market
Batteries
Norway Rechargeable Battery Market