
 Lithium Pouch Cell Market | 2026-2036
Lithium Pouch Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Pouch Cell Market Insights
A shortage of electrochemical engineers with solid-state electrolyte experience is unwinding planned capacity ramps at several gigafactories. LG Energy Solution leverages its Korean cathode supply chain to sustain high-nickel pouch output for European automotive programs. Farasis Energy anchors its position through direct OEM partnerships in China's premium EV segment. Great Power competes on cost-optimized lithium-polymer lines for consumer electronics, while EVE Energy specializes in energy storage system formats with extended cycle-life specifications.
Lithium pouch cells are sealed flexible-format electrochemical cells constructed with aluminum-laminate film outer packaging rather than rigid metal cans, typically achieving energy densities above 250 Wh/kg through stacked or Z-fold electrode architectures. These cells serve applications where weight minimization and form-factor adaptability outweigh structural robustness, particularly in electric vehicle battery packs and slim consumer electronics. The high energy density product tier leads automotive powertrain procurement, while flexible-format variants capture wearable and foldable device demand. Solid-state technology represents the fastest-growing development trajectory, though lithium-polymer formulations still occupy the majority of current manufacturing capacity. Grid storage applications concentrate margin pools in long-cycle-life configurations with enhanced thermal management requirements.
China's SAMR enforces GB standards on cell thermal runaway propagation, while South Korea's MFDS mandates traceability protocols for automotive-grade pouch supply. The EU's Battery Regulation imposes recycled content thresholds and carbon footprint declarations that reshape import competitiveness. REACH compliance for electrolyte solvents and binder chemistries adds formulation constraints for European market access. Stakeholders must monitor solid-state pilot-line yields and regional subsidy recalibrations as the primary variables determining which manufacturing footprints achieve scale economics first.
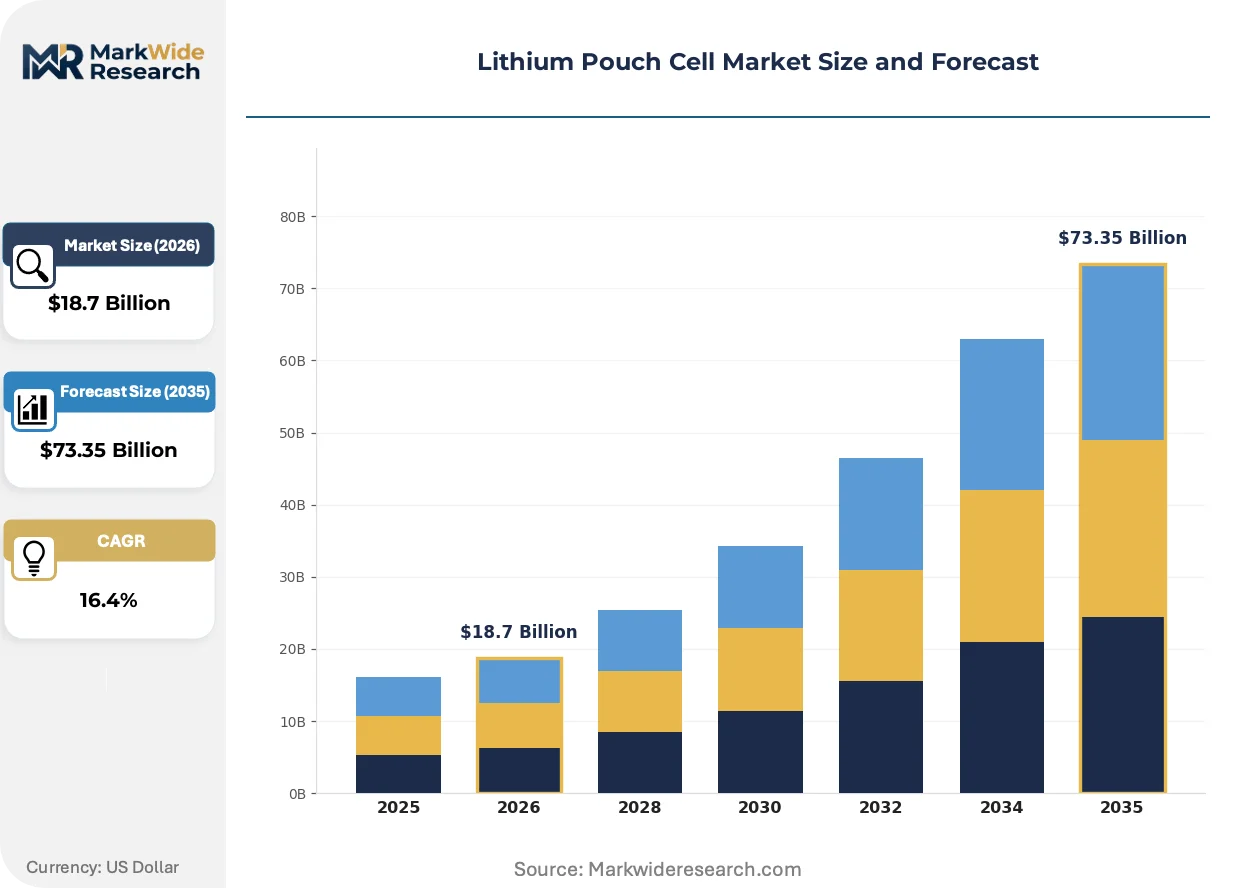
Market Dynamics
Solid-state electrolyte maturation is compressing development timelines across automotive battery programs while simultaneously straining electrochemical engineering capacity. This technology transition is redrawing competitive boundaries between incumbent lithium-polymer manufacturers and next-generation solid-state entrants.
Growth Catalysts
- EU Battery Regulation recycled content mandates:Automotive OEMs are accelerating pouch cell procurement to secure supply chains compliant with carbon footprint declarations and recycled material thresholds. This regulatory pressure concentrates demand among pre-certified suppliers.
- South Korean cathode material ecosystem:Vertical integration from precursor chemicals through finished cathode active material reduces lead times for high-nickel pouch formulations serving European electric vehicle platforms.
- Silicon-anode chemistry advances:Energy density improvements above 300 Wh/kg are opening design flexibility for premium electric vehicle powertrains previously constrained by cobalt-dependent cathode systems.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings between contract and spot markets compress margin predictability for cell manufacturers without captive mining offtake agreements.
- Single-region electrolyte solvent concentration:Dependence on Chinese production of dimethyl carbonate and ethylene carbonate creates supply vulnerability amplified by REACH compliance costs for European market entry.
- Solid-state manufacturing yield gaps:Ceramic electrolyte processing remains below commercial viability thresholds, delaying volume scale-up and extending payback periods for pilot line investments.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Subsidy tiers for gigafactory establishment attract pouch cell producers seeking geographic diversification beyond China-dependent supply chains.
- Grid-scale energy storage system integration:Long-cycle-life pouch configurations with enhanced thermal management capture margin pools in utility procurement programs requiring 15-year performance guarantees.
- Foldable consumer electronics form factors:Z-fold electrode architectures enable battery designs conforming to hinge mechanics in next-generation smartphones and wearable devices.
Industry Challenges
- Electrochemical engineer scarcity:Solid-state electrolyte expertise shortages are forcing delays at multiple gigafactory ramp schedules, particularly for sulfide-based ceramic processing.
- Dual certification timeline compression:Simultaneous compliance with China's GB thermal runaway standards and EU Battery Regulation carbon accounting extends product qualification cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Pouch Cell Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Energy Density, Ultra-Light, Flexible, Standard End User: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Aerospace Technology: Solid-State, Lithium-Ion, Lithium-Polymer, Conventional Application: Portable Devices, Renewable Energy, Automotive Powertrains, Grid Storage |
| Companies Covered | Farasis Energy, EV Energies, LG Energy Solution, Teamgiant, Great Power, AESC, CENAT, EVE Energy, Beijing National Battery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Pouch Cell Market Trends and Innovations
Manufacturing process intensification and regulatory disclosure requirements are converging to reshape how pouch cell producers compete on traceability and energy density simultaneously. These forces are elevating technical specifications from procurement checklists to strategic differentiators.
Stacked electrode architectures with ultra-thin separators are miniaturizing internal resistance pathways while maintaining mechanical flexibility. Automotive battery pack designers are adopting these configurations for premium electric vehicle segments where volumetric energy density determines platform competitiveness. This miniaturization is compressing the performance gap between pouch and prismatic formats in high-voltage applications.
REACH compliance for electrolyte solvents and binder chemistries is constraining formulation flexibility for European market access. ECHA substance restrictions on N-methyl-2-pyrrolidone and selected fluorinated compounds are forcing reformulation investments across mid-tier manufacturers. High-nickel cathode pouch suppliers with pre-validated solvent systems are capturing displaced volume from competitors facing extended requalification timelines.
Fleet operators and energy storage developers are consolidating procurement around suppliers offering 15-year cycle-life warranties with degradation guarantees. This contractual evolution is displacing transactional spot purchasing in utility-scale deployments. Germany's automotive integration corridors and South Korea's cathode material clusters are the primary geographies where these long-term offtake structures are standardizing first.
Lithium Pouch Cell Market Segmentation
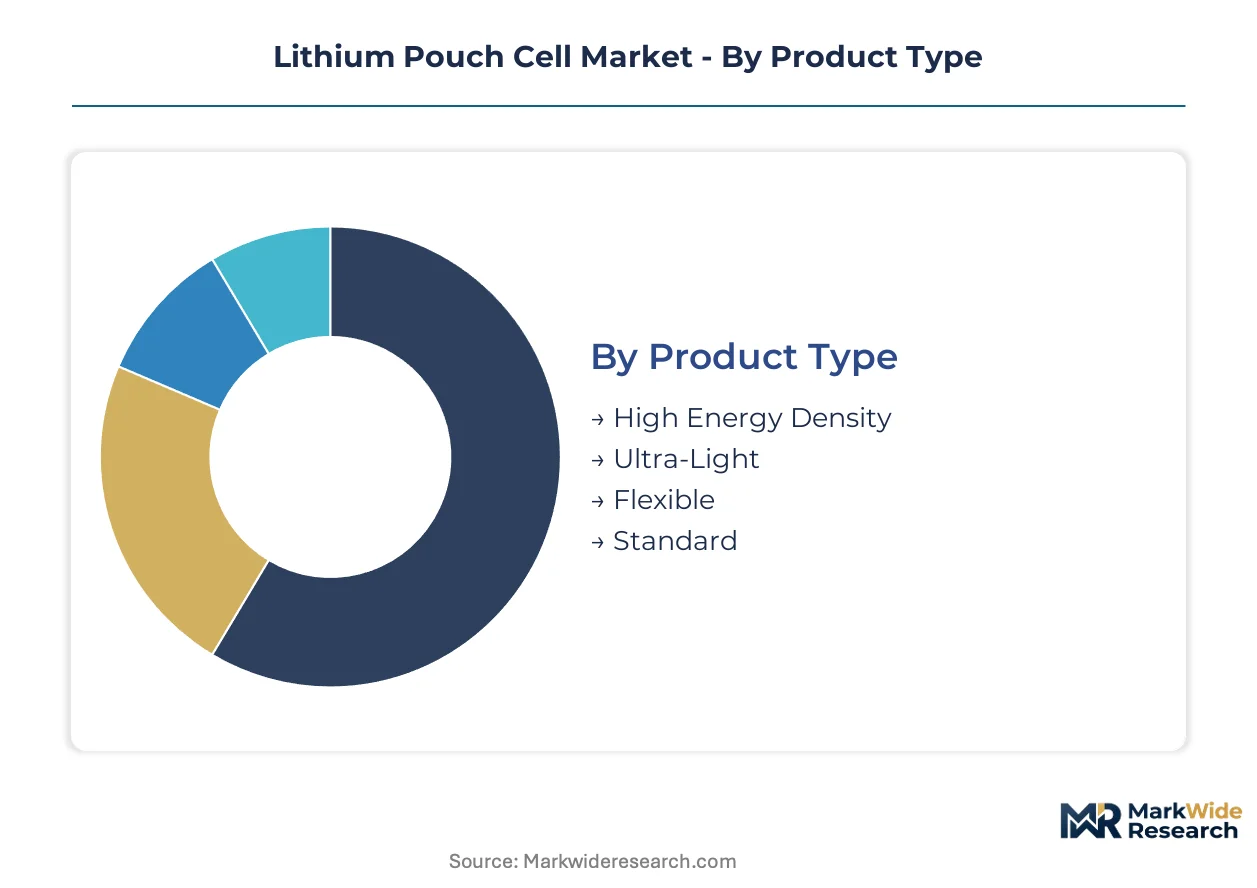
Pouch cell procurement patterns diverge sharply across energy density tiers and thermal management requirements. Automotive powertrain designers prioritize volumetric performance while consumer electronics manufacturers chase form-factor adaptability.
Product Type:
High energy density variants dominate export flows to European automotive corridors, while flexible-format lines serve domestic Asian electronics assembly.
- High Energy Density:Stacked electrode architectures with nickel-rich cathodes achieve gravimetric performance above 250 Wh/kg. German automotive integration corridors concentrate procurement for premium EV platforms where volumetric efficiency determines pack competitiveness.
- Flexible:Z-fold electrode configurations conform to hinge mechanics in foldable smartphones and wearable devices. South Korean display manufacturers anchor demand through direct OEM partnerships requiring mechanical compliance across repeated bending cycles.
- Ultra-Light:Thinned aluminum-laminate housings and reduced electrolyte loading serve aerospace satellite applications with strict mass budgets.
- Standard:Cost-optimized lithium-polymer formulations retain majority manufacturing capacity for mid-tier consumer electronics.
High energy density holds the largest share; momentum sits with flexible formats.
End User:
Customer procurement patterns split between long-cycle-life contractual structures and transactional spot purchasing.
- Electric Vehicles:High-nickel pouch configurations with silicon-anode compatibility command 15-year performance guarantees. EU Battery Regulation carbon footprint declarations are concentrating demand among pre-certified suppliers serving German and French automotive platforms.
- Energy Storage Systems:Extended cycle-life specifications with enhanced thermal management capture utility procurement requiring degradation warranties. Grid-scale developers in Texas and California are standardizing long-term offtake structures.
- Consumer Electronics:Slim-format lithium-polymer cells serve smartphone and laptop manufacturers with compressed lead-time requirements.
- Aerospace:Radiation-hardened pouch configurations with ceramic separator layers serve satellite power subsystems.
Electric vehicles command the dominant revenue pool; energy storage systems are expanding most quickly.
Technology:
Manufacturing yield gaps separate pilot-line demonstrators from commercial-scale production.
- Solid-State:Ceramic electrolyte processing with sulfide or oxide ionic conductors eliminates thermal runaway risks. Japanese pilot lines are advancing toward automotive qualification timelines.
- Lithium-Polymer:Gel electrolyte formulations with polymer binder matrices retain cost advantages for consumer electronics.
- Lithium-Ion:Liquid electrolyte systems with graphite anodes dominate current gigafactory output.
- Conventional:Cobalt-dependent cathode chemistries face displacement from high-nickel alternatives.
Lithium-polymer retains installed capacity leadership; solid-state is climbing the fastest.
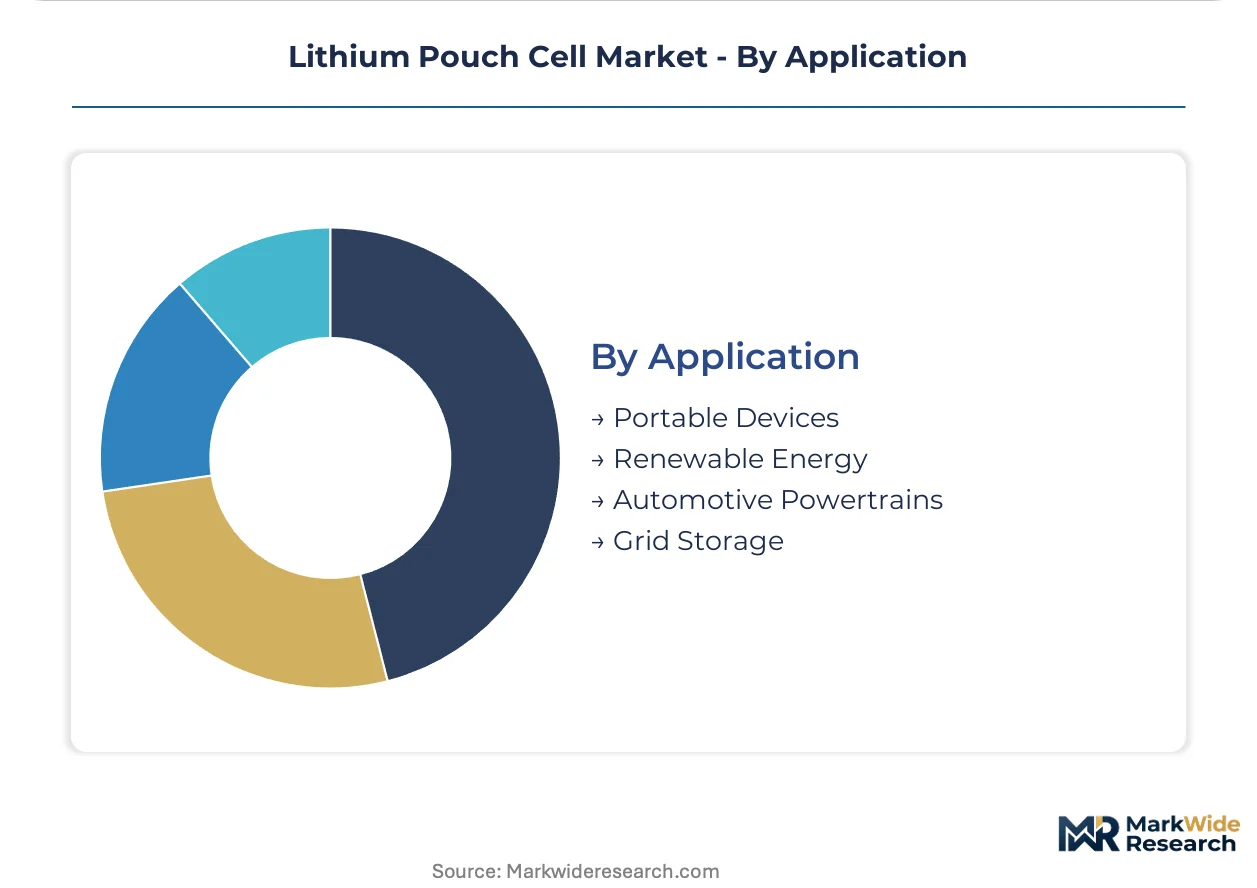
Application:
Performance specifications diverge between mobile power requirements and stationary infrastructure demands.
- Automotive Powertrains:High-voltage pouch modules with integrated cell-to-pack architectures reduce structural mass. South Korean cathode material ecosystems supply precursor chemicals for European EV platforms.
- Grid Storage:Containerized pouch arrays with liquid cooling loops serve utility-scale renewable integration projects.
- Portable Devices:Slim-format cells with aluminum-laminate flexibility enable wearable and foldable form factors.
- Renewable Energy:Behind-the-meter residential storage systems with 10-year cycle-life specifications.
Automotive powertrains generate the dominant volume; grid storage is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR enforces GB thermal runaway standards that reshape cell-level accountability across the dominant manufacturing geography. South Korea's MFDS traceability protocols and the EU's Battery Regulation recycled content mandates create a three-pole regulatory framework. German automotive integration corridors and Texas utility procurement programs concentrate demand validation for next-generation chemistries.
China
Domestic EV manufacturers drive volume commitments for silicon-anode pouch configurations. SAMR's GB standards on thermal runaway propagation force reformulation investments across mid-tier suppliers. The Yangtze River Delta cluster anchors cathode precursor chemical production for export-oriented cell lines.
South Korea
High-nickel cathode ecosystems supply European automotive platforms with reduced lead times. MFDS mandates traceability protocols that extend qualification cycles for automotive-grade pouch exports. The Seoul Capital Area concentrates pilot-line development for solid-state electrolyte processing.
Germany
Premium EV powertrain procurement concentrates demand for volumetric energy density above 250 Wh/kg. EU Battery Regulation carbon footprint declarations reshape import competitiveness for non-compliant suppliers. Stuttgart and Munich automotive corridors standardize 15-year performance guarantee structures.
United States
Texas and California utility-scale developers consolidate procurement around long-cycle-life configurations. FERC grid interconnection standards amplify thermal management requirements for containerized pouch arrays. The Pacific Northwest hosts validation programs for aerospace satellite power subsystems.
India
PLI scheme subsidy tiers attract gigafactory proposals seeking geographic diversification beyond China-dependent supply chains. BIS standards on cell safety create dual certification burdens for imported pouch configurations. Gujarat and Tamil Nadu industrial corridors concentrate early-phase cathode material partnerships.
Lithium Pouch Cell Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the lithium pouch cell market. Korean and Chinese manufacturers dominate high-nickel automotive supply through captive cathode material access. Three archetypes define competitive positioning: vertically integrated chemistry developers, cost-optimized polymer specialists, and solid-state pilot-line operators. Capacity expansion and strategic OEM partnerships represent the dominant competitive moves as electrochemical engineering scarcity compresses ramp timelines.
Among Korean integrated producers, LG Energy Solution exemplifies the cathode-captive archetype serving European automotive programs. Farasis Energy and EVE Energy represent Chinese specialists anchoring distinct market vectors—premium EV partnerships and energy storage system formats respectively. Great Power occupies a position within cost-optimized consumer electronics supply. These three named companies illustrate how geographic origin and customer-type focus stratify competitive positioning without requiring uniform technology strategies.
| Leading Market Players |
|---|
| Farasis Energy |
| EV Energies |
| LG Energy Solution |
| Teamgiant |
| Great Power |
| AESC |
| CENAT |
| EVE Energy |
| Beijing National Battery |
| Others |
Pricing and Supply Chain Analysis
Gigafactory scale economics above 20 GWh annual output compress unit costs for high-nickel pouch configurations while simultaneously concentrating bargaining power among cathode-captive producers. This scale threshold shapes both regional price floors and supplier consolidation dynamics across automotive procurement programs.
Pricing Analysis
Contract-to-spot spreads between Chinese and European delivery terms exceed 15% for automotive-grade pouch cells, reflecting carbon footprint certification premiums and REACH compliance costs. Three-tier pricing structure across automotive-certified, industrial-standard, and consumer-economy levels separates suppliers by thermal runaway test documentation and recycled content thresholds. Cost compression in consumer lithium-polymer tiers is intensifying because of spot-market lithium carbonate volatility and oversupply from converted cylindrical lines. Energy storage developers exhibit highest price sensitivity due to project-financing constraints, while premium EV platforms prioritize energy density guarantees over unit cost.
Supply Chain Analysis
China and South Korea anchor cathode active material production, with the Yangtze River Delta and Gyeonggi Province concentrating precursor chemical capacity for export-oriented cell lines. Dimethyl carbonate and ethylene carbonate solvents draw from Sichuan and Shandong petrochemical complexes, while aluminum-laminate film feeds from Japanese and Taiwanese substrate specialists. Single-region electrolyte concentration creates tariff exposure amplified by EU Battery Regulation carbon border adjustments. Distribution runs through bonded warehouse networks serving Stuttgart and Munich automotive corridors, with direct OEM consignment replacing spot-market transactions for qualified suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state electrolyte maturation compresses technology adoption curves while EU recycled content mandates force supply chain restructuring. This dual inflection favors incumbents with cathode-captive positions and entrants with ceramic processing expertise.
For Market Incumbents: Compound defensive positioning through backward integration into high-nickel cathode precursor production and captive silicon-anode processing capacity. Solid-state pilot-line yield gaps threaten lithium-polymer margin pools, necessitating dual-technology R&D allocation. Pre-certification investments against China's GB thermal runaway standards and EU carbon footprint declarations extend qualification moats against mid-tier competitors lacking compliance infrastructure. For New Entrants and Emerging Players: EU Battery Regulation fast-track certification for recycled content compliance opens procurement access to German automotive platforms seeking qualified second-source suppliers. India's PLI scheme subsidy tiers offer the most penetrable geographic entry point, with Gujarat industrial corridor hosting early-phase cathode partnerships. Target utility-scale energy storage developers in Texas and California with long-cycle-life warranty structures as the primary go-to-market anchor. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors solid-state pilot-line operators with sulfide-based ceramic processing expertise and established OEM validation partnerships. Long-term viability over the next decade hinges on manufacturing yield achievement and regional subsidy capture. Monitor Japanese automotive qualification timelines for sulfide electrolyte configurations as the critical signal distinguishing pilot-line demonstrators from commercial-scale contenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursors | Captive nickel sulfate supply secures margin pools for European automotive programs facing EU recycled content mandates. |
| Solid-State Pilot-Line Scale-Up | Ceramic electrolyte yield improvements above commercial thresholds unlock qualification timelines for premium EV platforms. |
| Dual Certification Investment | Simultaneous GB standard and EU Battery Regulation compliance compresses competitor requalification windows by 12-18 months. |
| Geographic Diversification via India's PLI Scheme | Gujarat and Tamil Nadu gigafactory subsidies reduce China-dependent supply chain concentration for export-oriented cell lines. |
| Long-Cycle-Life Warranty Structuring | 15-year performance guarantees with degradation caps capture utility procurement programs in Texas and California grid storage markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SAMR regulatory filings, EU Battery Regulation implementation guidance, customs trade data, and cathode material supply disclosures. Electrochemical engineering directors at Korean and Chinese cell manufacturers, procurement leads at German automotive OEMs, and utility-scale storage developers in Texas and California provided operational validation. Bottom-up capacity buildout tracking triangulates against top-down demand segmentation across electric vehicle, energy storage, and consumer electronics end-uses.
Segmentation dimensions modeled include energy density tier, cathode chemistry composition, electrolyte formulation, and regional regulatory cluster across the analysis window. CAGRs derive from installed capacity forecasts, technology substitution curves for solid-state adoption, and OEM platform electrification commitments. Silicon-anode compatibility roadmaps and thermal runaway test certification timelines serve as industry-specific forecast inputs.
Underlying assumptions cover lithium carbonate price stabilization, solid-state yield achievement trajectories, and EU carbon border adjustment implementation, with deviation risk concentrated in raw material cost volatility and electrochemical engineering labor scarcity. Recalibration cycles align with material shifts in regulatory disclosure requirements and pilot-line yield announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Nickel Cadmium Battery Market
Batteries
China Battery Market
Batteries
Thin Film and Printed Battery Market
Batteries
Battery Maintainer Market
Batteries
Primary Lithium Battery Market
Batteries
Battery Wash System Market
Batteries
Sodium-Air Battery Market
Batteries
Aluminum-Air Battery Market
Batteries
Breathing Battery Market
Batteries
Heavy-Duty Truck Megapack Battery Systems Market
Batteries
Industrial Battery Charger Market
Batteries
Forklift Battery Market
Batteries
Battery Pack for Marine Hybrid and Full Electric Propulsion Market
Batteries
Global Bio Compatible Battery Market
Batteries
North America Industrial Battery Market
Batteries
Elastic Battery Binders Market