
 South and Central America Battery Market | 2026-2036
South and Central America Battery Market Size, Share, and Industry Trends Forecast 2026-2036
South and Central America Battery Market Analytics
Electric vehicle manufacturing is realigning procurement priorities across South and Central America. BYD Company leverages its integrated cell-to-pack architecture to secure fleet contracts in Brazil. Exide Industries anchors aftermarket demand through its established distribution network across Argentina and Colombia. Samsung SDI competes on energy density benchmarks for premium automotive programs.
South and Central America batteries encompass electrochemical storage devices ranging from lead-acid flooded cells to solid-state lithium-metal architectures, typically specified by nominal voltage, cycle life, and operating temperature bandwidth, serving to power vehicles, stabilize grids, and back up industrial loads. Lithium-ion chemistry captures the fastest expansion as declining cathode costs and regional assembly incentives shift procurement away from lead-acid dominance. Stationary installations for grid-connected energy storage accumulate margin pools where long-duration flow batteries and hybrid systems address intermittency in Chile's solar-rich northern regions.
Brazil's ANP biofuel blending mandates and Inova Energia local content requirements shape battery qualification for domestic automotive assembly. Argentina's SECRETARÍA DE ENERGÍA enforces import substitution rules that favor regional cell packaging over fully finished imports. Stakeholders must monitor how evolving solid-state technology readiness intersects with these national content frameworks to determine manufacturing investment timing.
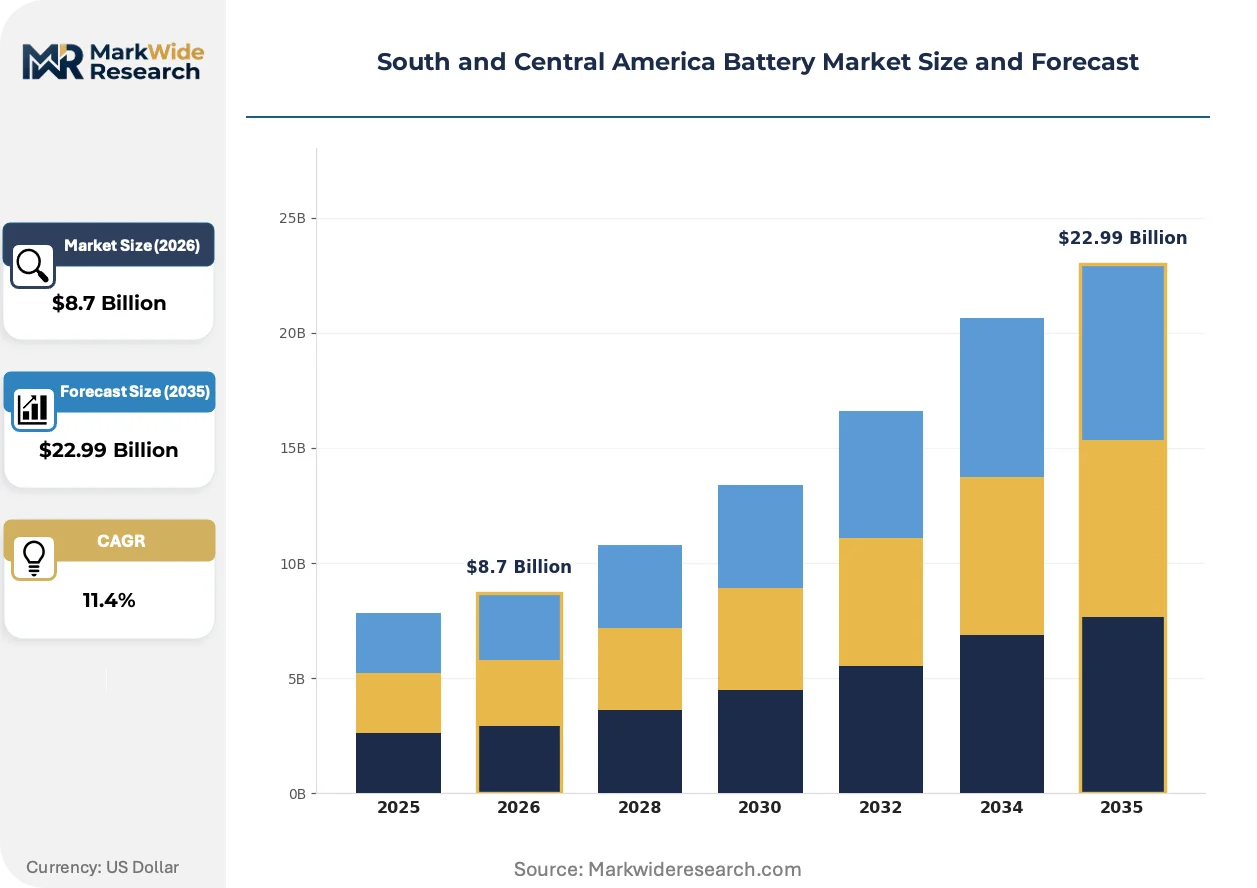
Market Dynamics
Lithium-ion cell-to-pack architectures are compressing module costs and forcing incumbent lead-acid suppliers across Brazil and Chile to accelerate cathode chemistry transitions or exit automotive qualification pipelines entirely.
Growth Catalysts
- Brazil's Inova Energia Program:Local content mandates for battery assembly are redirecting procurement toward domestic pack integrators in São Paulo state.
- Chilean Solar Intermittency:Grid operators in the Atacama Desert are procuring long-duration flow batteries to stabilize photovoltaic output during evening ramp events.
- Electric Fleet Electrification:Urban bus operators in Santiago and São Paulo are specifying lithium-iron-phosphate chemistries for route predictability and thermal safety.
Market Restraints
- Lithium Carbonate Volatility:Argentine salar brine processing delays and Chilean export quota uncertainty are transmitting price spikes to regional cathode manufacturers.
- Cell Import Concentration:Packagers in Colombia and Peru remain dependent on Chinese cylindrical cell shipments through the Port of Callao, creating single-point vulnerability.
- Lead-Acid Infrastructure Lock-In:Existing flooded battery recycling networks and technician training pools slow fleet operator migration to solid-state maintenance protocols.
Strategic Opportunities
- Colombia's Underserved Andean Corridor:Bogotá's altitude-sensitive commercial vehicle segment lacks qualified lithium pack service infrastructure, creating first-mover openings for technical service partnerships.
- Second-Life Stationary Storage:Retired electric bus batteries from Santiago's Transantiago fleet are being repurposed for industrial backup at copper concentrators in the Antofagasta Region.
- Argentina's Import Substitution Framework:SECRETARÍA DE ENERGÍA rules favor regional cell packaging investments over finished pack imports, rewarding Jujuy Province lithium conversion projects.
Industry Challenges
- Electrolyte Formulation Talent Scarcity:Regional universities lack graduate programs in non-aqueous electrochemistry, forcing packagers to import Chinese and Korean process engineers.
- UN 38.3 Certification Backlogs:Testing laboratory capacity in São Paulo and Buenos Aires cannot match submission volumes from new pack designs, delaying product launches by six to nine months.
- Legacy Charging Infrastructure Mismatch:Brazil's existing lead-acid forklift charging stations require voltage and communication protocol upgrades to accommodate lithium-ion opportunity charging cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South and Central America Battery Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Flow Batteries End User: Automotive, Consumer Electronics, Industrial, Energy Storage Technology: Rechargeable, Non-Rechargeable, Solid-State, Hybrid Installation: Portable, Stationary, Grid-Connected, Off-Grid |
| Companies Covered | Exide Industries, FIAMM Energy Technology, BYD Company, Duracell, Samsung SDI, Panasonic Holdings, Clarios International, Saft Groupe, EnerSys, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South and Central America Battery Market Evolving Landscape
Cell chemistry convergence with thermal management integration is eliminating discrete module boundaries, while regulatory pressure on carbon intensity is rewriting supply qualification criteria across the Andean lithium triangle.
Sodium-ion cathode formulations are rewriting the cost structure for grid-scale stationary storage in Brazil's northeastern wind corridors. Utility-scale developers in Ceará and Rio Grande do Norte are piloting sodium-ion arrays for four-to-eight-hour discharge durations. The technology is rewriting procurement benchmarks by eliminating lithium supply chain exposure and enabling direct procurement from emerging Brazilian electrode manufacturers.
Argentina's SECRETARÍA DE ENERGÍA import substitution enforcement is tightening local content verification for battery pack assembly. Industrial buyers in Buenos Aires and Córdoba provinces now face documentary requirements proving regional cell packaging rather than finished import acceptance. Automotive OEMs with assembly plants in Santa Isabel are restructuring supplier qualification to capture fiscal incentives tied to domestic value-added thresholds.
Fleet operators across São Paulo and Santiago are consolidating procurement through energy-as-a-service contracts rather than capital equipment purchases. Mining companies in Chile's Antofagasta Region are outsourcing battery ownership to specialized providers who guarantee cycle life and handle end-of-life recovery. This model is most visible in copper concentrator microgrid installations where operational expenditure treatment improves project finance terms.
South and Central America Battery Market Segmentation
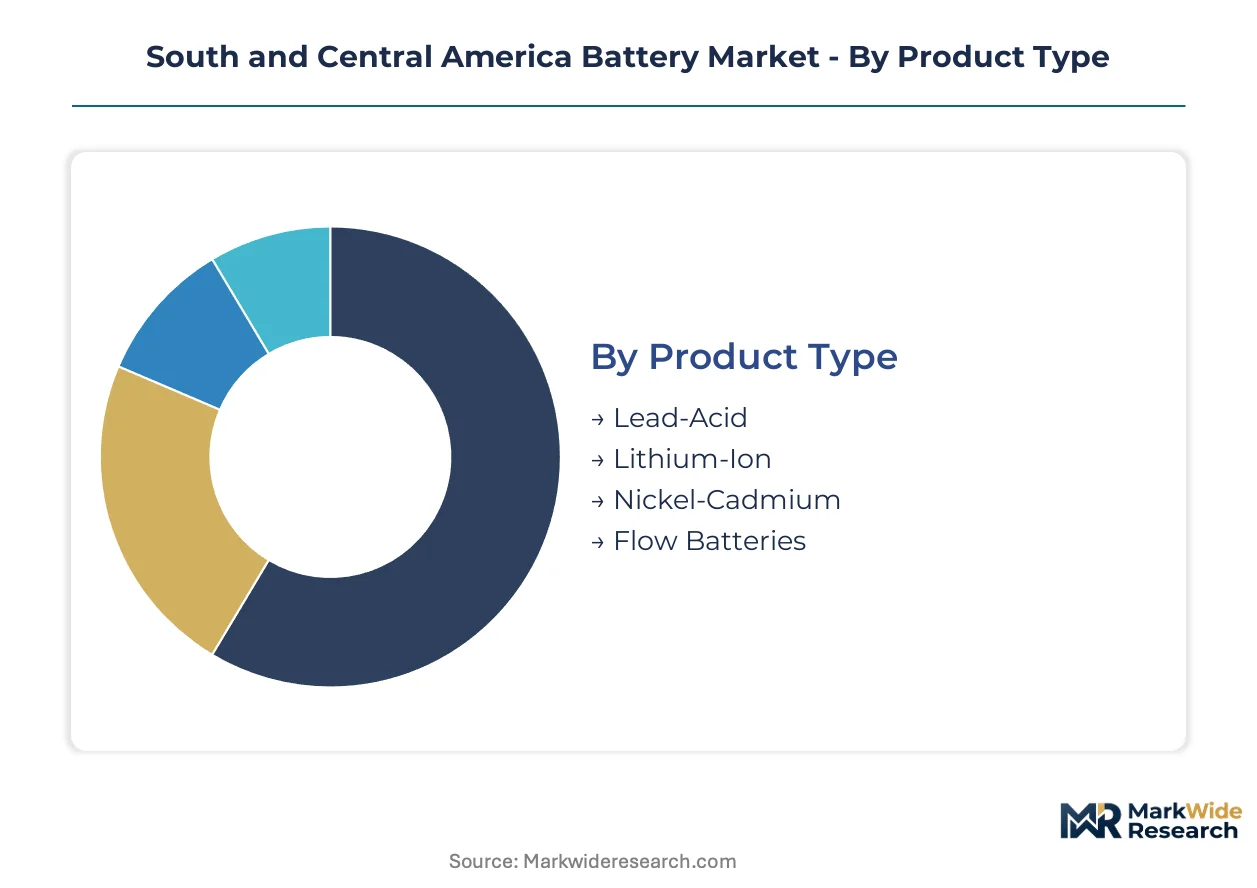
Battery procurement across South and Central America fragments along chemistry maturity, installation permanence, and end-use duty cycles. Each dimension carries distinct margin profiles, certification burdens, and localization incentives that reshape supplier qualification.
Product Type:
The customization-to-standardization spectrum runs from commodity flooded cells to engineered solid-state architectures requiring application-specific thermal management.
- Lithium-Ion:Cell-to-pack architectures compress module boundaries and eliminate discrete thermal interfaces. Demand concentrates in São Paulo's electric bus depots and Santiago's mining fleet electrification programs, where cathode cost declines and ANP local content rules accelerate procurement shifts from lead-acid.
- Lead-Acid:Flooded and absorbed glass mat constructions dominate aftermarket automotive starting-lighting-ignition applications. Brazil's southeastern industrial corridor still routes substantial volume through established recycling networks and technician training pools, though Inova Energia incentives are narrowing qualification windows for new automotive programs.
- Flow Batteries:Vanadium and zinc-bromine chemistries address long-duration grid stabilization in Chile's Atacama Desert solar corridors.
- Nickel-Cadmium:Sintered plate constructions persist in aviation ground support and emergency lighting where temperature tolerance outweighs energy density requirements.
Most installed capacity flows through Lead-Acid. Expansion is steepest in Lithium-Ion.
End User:
Margin capture varies sharply across customer types, from price-sensitive fleet operators to capital-rich miners seeking operational expenditure treatment.
- Automotive:Original equipment and aftermarket segments split between Brazil's Inova Energia-compliant domestic assembly and Argentina's import-substitution-driven cell packaging. OEM procurement specifies lithium-iron-phosphate for thermal safety in tropical climates.
- Energy Storage:Utility-scale developers in Ceará and Rio Grande do Norte pilot sodium-ion arrays for four-to-eight-hour discharge, while Chilean grid operators procure flow batteries for evening ramp stabilization. Mining companies in Antofagasta outsource battery ownership through energy-as-a-service contracts.
- Industrial:Forklift electrification and backup power for copper concentrators drive demand, constrained by legacy charging infrastructure requiring voltage and communication protocol upgrades.
- Consumer Electronics:Cylindrical and pouch cell demand concentrates through Colombian and Peruvian distributors dependent on Port of Callao shipments.
Automotive commands the largest revenue pool. Energy Storage is climbing the fastest as procurement shifts toward operational expenditure models.
Technology:
Architecture choices cascade through supply chain requirements, from commodity cell imports to captive electrode manufacturing.
- Rechargeable:Lithium-ion and sodium-ion chemistries dominate new procurement, with Brazilian northeastern wind developers piloting sodium-ion to eliminate lithium supply chain exposure.
- Solid-State:Lithium-metal anodes with ceramic or sulfide electrolytes remain pre-commercial for automotive, though SECRETARÍA DE ENERGÍA local content verification is already restructuring supplier qualification timelines.
- Non-Rechargeable:Primary lithium-manganese dioxide cells serve remote monitoring and medical device applications where charging infrastructure is absent.
- Hybrid:Lead-carbon and lithium-capacitor combinations address pulse power requirements in hybrid electric vehicle regenerative braking systems.
Rechargeable systems carry the bulk of installed base. Solid-State is gaining share fastest among technology categories as cathode cost trajectories intersect with regulatory pressure.
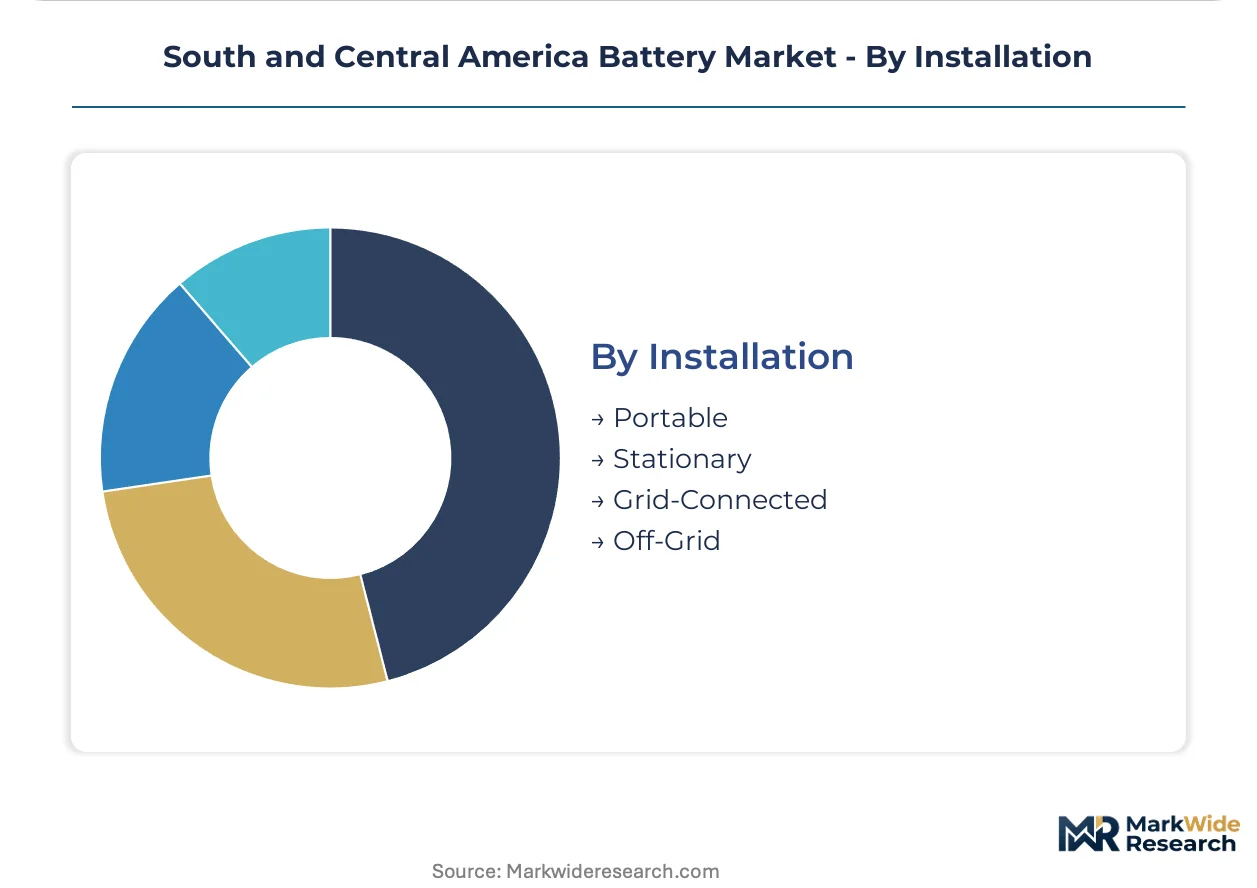
Installation:
Mobility requirements versus permanence dictate packaging density, cooling architecture, and service access design.
- Stationary:Grid-connected and off-grid systems accumulate margin in Chilean solar-rich regions and Brazilian wind corridors. Copper concentrators in Antofagasta repurpose retired electric bus batteries for industrial backup.
- Portable:Power tools, medical devices, and consumer electronics drive cylindrical and prismatic cell demand through established distribution networks across Argentina and Colombia.
- Grid-Connected:Utility-scale installations face UN 38.3 certification backlogs in São Paulo and Buenos Aires testing laboratories.
- Off-Grid:Rural electrification and telecom tower backup in Peru's Andean regions create altitude-sensitive service requirements.
Stationary installations represent the dominant revenue stream. Portable applications are expanding most quickly through consumer electronics distribution channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's southeastern industrial corridor anchors battery demand across South and Central America, with electric bus depots and automotive assembly plants driving lithium-ion procurement volumes.
Brazil
Electric fleet operators in São Paulo and Minas Gerais states are accelerating lithium-iron-phosphate procurement for route electrification. ANP biofuel blending mandates and Inova Energia local content requirements reshape supplier qualification for domestic automotive assembly. Pack integrators cluster in São Paulo state's industrial corridor to capture fiscal incentives tied to domestic value-added thresholds.
Chile
Grid operators in the Atacama Desert procure long-duration flow batteries to stabilize photovoltaic output during evening ramp events. Mining companies in the Antofagasta Region outsource battery ownership through energy-as-a-service contracts for copper concentrator microgrids. Santiago's Transantiago fleet retires electric bus batteries for industrial backup repurposing.
Argentina
Automotive OEMs with assembly plants in Santa Isabel restructure supplier qualification to capture SECRETARÍA DE ENERGÍA fiscal incentives. Import substitution rules favor regional cell packaging over finished pack imports for industrial buyers in Buenos Aires and Córdoba provinces. Jujuy Province lithium conversion projects attract investment to meet documentary verification requirements.
Colombia
Bogotá's altitude-sensitive commercial vehicle segment lacks qualified lithium pack service infrastructure, creating technical service partnership openings. Colombian distributors route cylindrical and pouch cell demand through established networks dependent on Port of Callao shipments. Andean corridor electrification programs drive pilot deployments for altitude-compensated battery management systems.
Peru
Rural electrification and telecom tower backup in Peru's Andean regions create altitude-sensitive service requirements for off-grid installations. Packagers remain dependent on Chinese cylindrical cell shipments through the Port of Callao, exposing procurement to single-point vulnerability. Mining logistics operators in the central highlands test hybrid energy storage configurations for remote site power.
South and Central America Battery Market Competitive Landscape
Capacity expansion dominates the current landscape as packagers respond to Inova Energia local content mandates and SECRETARÍA DE ENERGÍA import substitution enforcement. The vendor base stratifies across integrated cell-to-pack architects, established aftermarket distributors, and regional pack integrators. Three archetypes define positioning: chemistry-agnostic assemblers, vertically integrated cell producers, and service-specialized fleet operators. Geographic expansion and technology licensing represent the dominant competitive vectors for market access.
Among Asia-based integrated manufacturers, BYD Company exemplifies cell-to-pack architecture deployment for fleet electrification programs. Exide Industries anchors aftermarket demand through established distribution networks across Argentina and Colombia. Samsung SDI occupies a position emphasizing energy density benchmarks for premium automotive qualification pipelines.
| Leading Market Players |
|---|
| Exide Industries |
| FIAMM Energy Technology |
| BYD Company |
| Duracell |
| Samsung SDI |
| Panasonic Holdings |
| Clarios International |
| Saft Groupe |
| EnerSys |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between UN 38.3-qualified automotive packs and uncertified industrial assemblies manifests in parallel supply chain configurations, with São Paulo testing laboratory backlogs creating six-to-nine-month qualification premiums that compress margins for packagers lacking captive certification resources.
Pricing Analysis
Input-cost pass-through from Argentine salar brine processing delays and Chilean export quota uncertainty transmits lithium carbonate volatility directly to regional cathode manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates energy-density-specified automotive programs from forklift aftermarket replacements. Cost compression in lead-acid replacement segments is intensifying because Inova Energia local content thresholds disqualify import-dependent suppliers. Fleet operators in Santiago's Transantiago system demonstrate highest price sensitivity through energy-as-a-service procurement, while copper concentrators in Antofagasta accept premium positioning for operational expenditure treatment.
Supply Chain Analysis
UN 38.3 certification gating concentrates qualified cell sourcing from China, South Korea, and Japan, with São Paulo and Buenos Aires testing laboratories creating chokepoints for new pack designs. Cathode active material and electrolyte salt dependencies rest on Chilean lithium carbonate and Korean separator shipments. Single-source vulnerability runs through Port of Callao cylindrical cell imports serving Colombian and Peruvian packagers. Distribution runs through established aftermarket networks anchored by Exide Industries across Argentina and Colombia, supplemented by direct fleet contracting for electric bus electrification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's Inova Energia program compounds procurement demand through local content mandates, with ANP biofuel blending rules accelerating battery qualification timelines for domestic automotive assembly.
For Market Incumbents: Deploy backward integration into Jujuy Province lithium conversion to offset Argentine SECRETARÍA DE ENERGÍA import substitution enforcement. Capture São Paulo state fiscal incentives through domestic pack integration investments. Sodium-ion pilot deployments in Ceará threaten lithium-ion volume commitments; secure cathode chemistry diversification through Brazilian electrode manufacturer partnerships. For New Entrants and Emerging Players: Technical service partnerships in Bogotá's altitude-sensitive commercial vehicle segment open first-mover positioning where qualified lithium pack infrastructure remains absent. Target Andean corridor electrification programs requiring altitude-compensated battery management systems. Second-life stationary storage from Santiago's retired electric bus fleet offers asset-light entry into copper concentrator backup applications. For Investors and Strategic Acquirers: Consolidation pressure builds where electrolyte formulation talent scarcity forces packagers to import Chinese and Korean process engineers. Long-term viability favors vertically integrated cell-to-pack architects with captive electrode supply over chemistry-agnostic assemblers dependent on commodity cell imports. Watch sodium-ion utility-scale deployment in Brazil's northeastern wind corridors as inflection indicator for lithium demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Conversion | Jujuy Province projects capture SECRETARÍA DE ENERGÍA fiscal incentives for regional cell packaging. |
| Cell-to-Pack Architecture Deployment | BYD's integrated designs secure fleet contracts through module cost compression and thermal management consolidation. |
| Sodium-Ion Pilot Deployment | Ceará and Rio Grande do Norte utility developers eliminate lithium supply chain exposure through Brazilian electrode procurement. |
| Energy-as-a-Service Contract Structuring | Antofagasta mining companies improve project finance terms through operational expenditure treatment of battery ownership. |
| Second-Life Stationary Repurposing | Retired Santiago electric bus batteries supply industrial backup for copper concentrators with reduced capital requirements. |
Research Methodology
Coverage spans Brazil, Chile, Argentina, Colombia, and Peru, with primary inputs from each market's battery procurement decision-makers. Primary interviews with fleet electrification managers, grid operators in Atacama Desert solar corridors, mining company energy officers, automotive OEM procurement leads, and pack integration engineers combined with secondary validation from ANP regulatory filings, SECRETARÍA DE ENERGÍA import substitution documentation, Chilean central grid operator procurement records, and customs data through Port of Callao. Bottom-up cell shipment volumes and top-down energy storage deployment capacities were triangulated to establish market sizing.
Granularity-level modeling addressed chemistry type, installation permanence, end-use duty cycle, and regional regulatory cluster across the projection horizon. Segmentation dimensions included lithium-ion, lead-acid, flow battery, and sodium-ion chemistries; automotive, energy storage, industrial, and consumer electronics end users; and stationary, portable, grid-connected, and off-grid installations. CAGRs were derived from installation volume trajectories and cathode cost decline curves. Industry-specific forecast inputs incorporated Inova Energia local content compliance rates and SECRETARÍA DE ENERGÍA documentary verification timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state technology readiness intersecting with national content frameworks. Forecasts reflect assumptions regarding lithium carbonate price stabilization, UN 38.3 testing laboratory capacity expansion, and sodium-ion manufacturing scale-up in Brazilian northeastern wind corridors. A model refresh is warranted upon material change in Chilean lithium export quota policy or Brazilian Inova Energia local content threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Europe Battery Cell Market
Batteries
France Rechargeable Battery Market
Batteries
Aluminum Based Battery Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
India Electric Vehicle Battery Electrolyte Market
Batteries
Yacht Battery Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
US Solar Battery Market
Batteries
Indonesia and Malaysia Lead Acid Battery Market
Batteries
Alkaline Battery Market
Batteries
Lithium Starters Market
Batteries
Modular Battery Market
Batteries
Molten Salt Battery Market
Batteries
Breathing Battery Market
Batteries
Battery Plate Market
Batteries
Battery Wash System Market