
 West Europe Battery Market | 2026-2036
West Europe Battery Market Size, Share, and Industry Trends Forecast 2026-2036
West Europe Battery Market Analytics
Lithium iron phosphate is shifting from marginal to mainstream across West European EV battery supply contracts. Northvolt leverages its Swedish gigafactory complex to anchor regional cathode production. Saft Groupe S.A. specializes in high-cycle industrial lithium-ion systems for grid stabilization. LG Energy Solution extends its Polish manufacturing base to serve German automotive OEMs directly.
West Europe batteries are electrochemical storage devices comprising anode, cathode, electrolyte, and separator materials engineered for reversible ion transfer, typically operating at voltages from 1.2V to 4.2V depending on chemistry. These devices convert chemical energy to electrical energy for portable, motive, and stationary power applications. Lithium-ion chemistry dominates current manufacturing scale and investment flows across the region. Solid-state technology attracts the fastest-growing R&D allocation as manufacturers pursue energy density above 400 Wh/kg. Flow battery systems occupy niche but expanding roles in multi-hour grid storage deployments.
The EU Battery Regulation, ECHA REACH framework, and CE marking requirements collectively mandate recycled content verification, restricted substance limits, and performance durability standards across West European supply chains. EMA and national regulators in France and Germany enforce these rules through market surveillance and import controls. Stakeholders must monitor solid-state manufacturing readiness against evolving EU carbon footprint thresholds.
Market Dynamics
The EU Battery Regulation's recycled content mandates and carbon footprint declarations are forcing manufacturers to restructure cathode supply chains and localize production within West Europe's automotive corridor.
Growth Catalysts
- EU Battery Regulation mandates:Recycled lithium, cobalt, and nickel thresholds are compelling OEMs to secure regional refining capacity and closed-loop partnerships.
- German automotive procurement:Stuttgart, Munich, and Wolfsburg-based EV manufacturers are accelerating lithium-ion pack orders and qualifying second-source suppliers.
- Grid-scale storage deployment:Multi-hour flow battery installations for renewable integration are expanding across French and Spanish utility networks.
Market Restraints
- Cathode active material concentration:Chinese and Korean suppliers control over 80% of precursor chemical output, exposing West European cell makers to input cost volatility and geopolitical supply risk.
- REACH compliance friction:ECHA substance restrictions on fluorinated electrolyte additives are delaying product registrations and limiting formulation options for high-voltage chemistries.
- Solid-state manufacturing readiness:Ceramic electrolyte sintering yields remain below commercial viability thresholds, compressing timelines for 400 Wh/kg cell commercialization.
Strategic Opportunities
- Spanish and Portuguese lithium deposits:Iberian hard-rock and brine extraction projects offer captive raw material supply for cathode precursor plants serving regional cell factories.
- Second-life battery applications:Decommissioned EV packs are repurposing into stationary storage for commercial buildings and renewable microgrids across France and Italy.
- CE marking and carbon footprint differentiation:Verified low-carbon cell production is creating procurement preference among ESG-mandated fleet operators and corporate buyers.
Industry Challenges
- Electrochemical engineering talent scarcity:Solid-state and silicon-anode specialists command premium compensation, constraining R&D expansion at mid-scale manufacturers.
- Gigafactory capex intensity:Dry electrode coating and inert atmosphere assembly lines require billion-euro commitments with 6-8 year payback horizons.
- EU Battery Regulation certification timelines:Passport system integration and supply chain due diligence documentation are extending product launch cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Europe Battery Market |
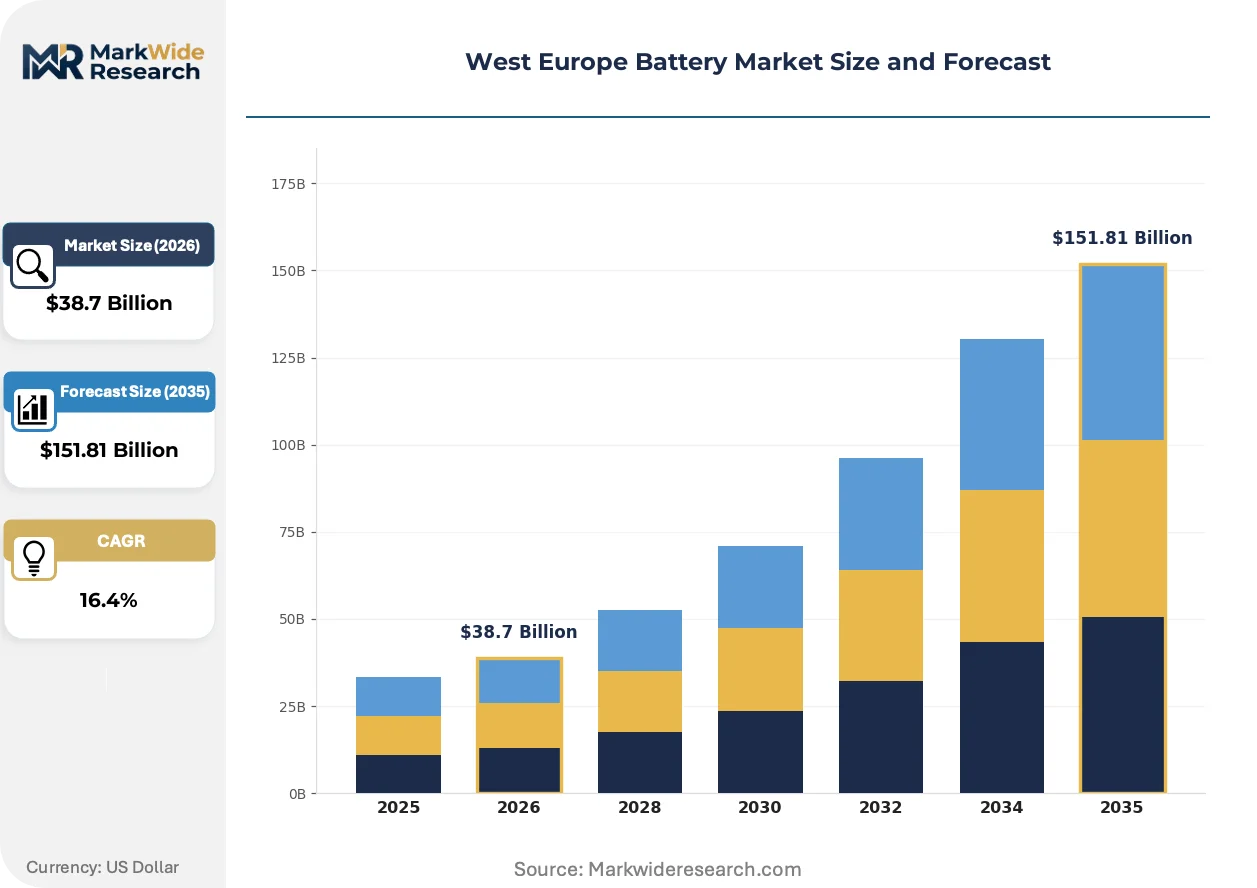
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel Metal Hydride, Lead Acid, Solid-state End User: Consumer Electronics, Automotive Manufacturers, Industrial Applications, Energy Storage Technology: Rechargeable, Primary, Flow, Thin Film Distribution Channel: Online Retail, Wholesalers, Direct Sales, Specialty Stores |
| Companies Covered | Contemporary Amperex Technology Co. Limited, BYD Company Ltd., Panasonic Corporation, VARTA Microbattery GmbH, Clarios LLC, Northvolt, LG Energy Solution, Saft Groupe S.A., Toshiba Corp, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Europe Battery Market Evolving Landscape
Solid-state electrolyte development, regulatory compliance automation, and direct OEM-supplier contracting models are compressing legacy supply chain structures across West Europe.
Lithium iron phosphate cathode chemistry is unifying entry and mid-segment EV supply contracts previously split between nickel-manganese-cobalt and nickel-cobalt-aluminum formulations. French and German OEMs are qualifying LFP packs for standard-range models, reducing cobalt exposure and simplifying thermal management. This chemistry convergence is unifying procurement specifications and compressing supplier qualification overhead across the region's tier-one cell contracts.
REACH framework amendments on persistent organic pollutants are restricting perfluorinated electrolyte additives and fluoropolymer binders in cell manufacturing. ECHA enforcement through import surveillance and market surveillance authorities in France and Germany is blocking non-compliant cells at ports. High-voltage cathode developers are responding by accelerating sulfone-based and nitrile-functionalized electrolyte formulations with equivalent ionic conductivity.
Fleet operators and energy storage developers are consolidating procurement through multi-year offtake agreements with cell makers, bypassing traditional distributor and trading house intermediaries. German municipal utilities and French renewable developers are negotiating direct volume commitments with Polish and Swedish gigafactories. This channel compression is most visible in stationary storage and commercial EV segments where buyers possess technical specification expertise and balance-sheet capacity for long-dated contracts.
West Europe Battery Market Segmentation
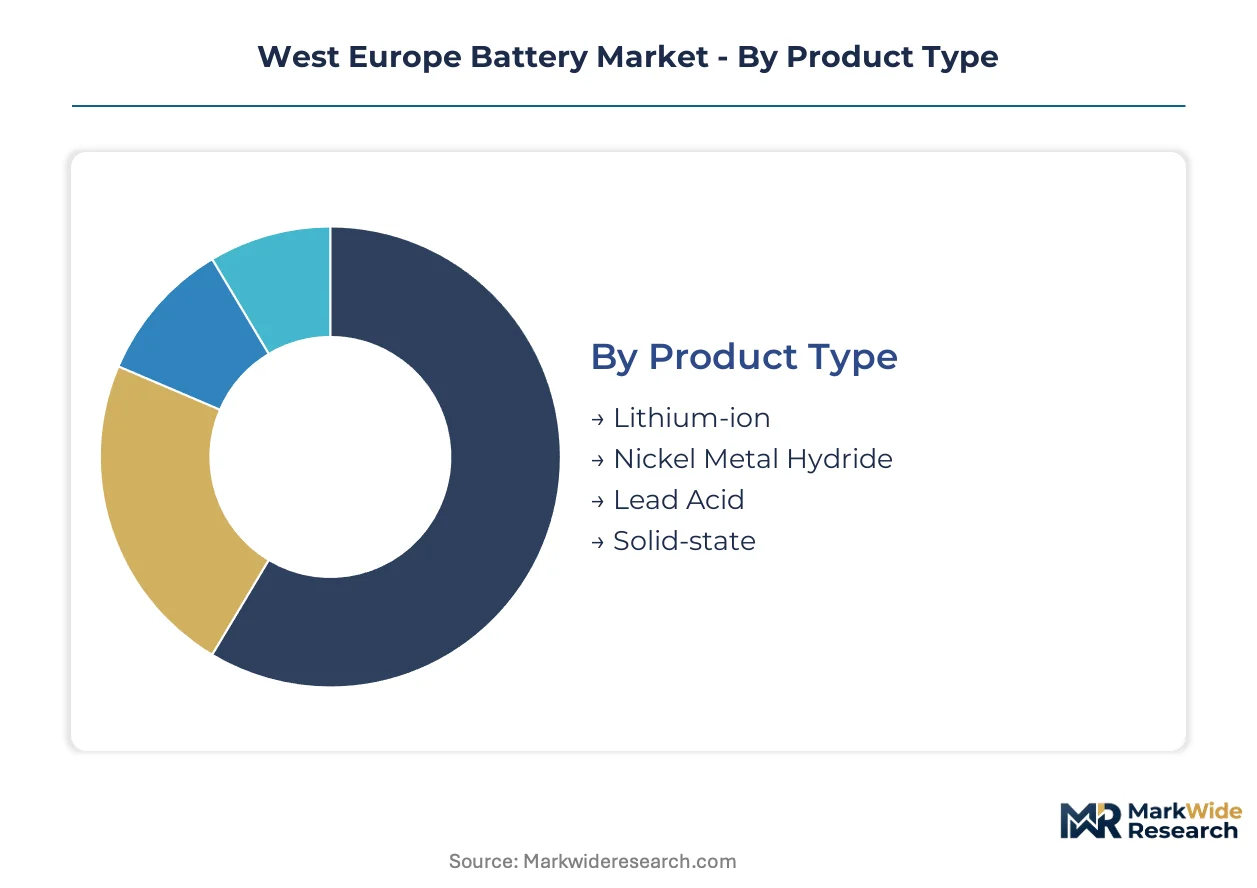
West Europe's battery market segments reflect divergent compliance burdens under EU Battery Regulation and REACH frameworks. Each category demands distinct certification pathways, carbon footprint documentation, and supply chain due diligence that reshape competitive positioning across the value chain.
Product Type:
Lithium-ion and solid-state chemistries carry the heaviest EU Battery Regulation certification loads, requiring passport documentation and recycled content verification. Lead acid and nickel metal hydride face lighter documentation thresholds but must still meet CE marking and substance restrictions under ECHA enforcement.
- Lithium-ion:Dominant chemistry for EV and grid applications, utilizing nickel-manganese-cobalt or lithium iron phosphate cathodes. German automotive OEMs in Stuttgart and Wolfsburg are consolidating procurement around standardized LFP packs for mid-range electric vehicles to simplify thermal management and reduce cobalt exposure.
- Solid-state:Ceramic or polymer electrolyte systems targeting energy density above 400 Wh/kg. Manufacturing readiness remains constrained by sintering yield challenges, though Swedish gigafactory investments are accelerating pilot production for premium EV contracts.
- Nickel Metal Hydride:Mature chemistry retaining niche roles in hybrid vehicle auxiliary systems and industrial backup power. Toyota and Honda legacy hybrid platforms in France and Spain sustain residual demand.
- Lead Acid:Flooded and valve-regulated designs for automotive starting-lighting-ignition and uninterruptible power supplies. ECHA substance restrictions on lead handling are compressing manufacturing footprints in Germany and Italy.
Lithium-ion sits at the top of the volume ranking, with solid-state climbing the fastest.
End User:
Automotive manufacturers and energy storage developers command direct contracting leverage, bypassing distributor intermediaries. Consumer electronics and industrial applications retain fragmented procurement through wholesale and retail channels.
- Automotive Manufacturers:OEMs across Germany's automotive corridor and French EV startups are negotiating multi-year offtake agreements with Polish and Swedish cell factories. Direct procurement is displacing traditional tiered supply structures.
- Energy Storage:French municipal utilities and Spanish renewable developers are deploying multi-hour flow battery and lithium-ion systems for grid stabilization. Procurement concentrates around verified low-carbon cell production to meet ESG mandates.
- Industrial Applications:Forklift fleets, mining equipment, and material handling systems across Belgium and the Netherlands. Second-life EV pack repurposing is gaining traction for warehouse energy arbitrage.
- Consumer Electronics:Smartphone, laptop, and power tool manufacturers. CE marking and REACH compliance dominate sourcing criteria, with limited differentiation beyond cycle life specifications.
Automotive manufacturers anchor revenue concentration, while energy storage is expanding most quickly.
Technology:
Rechargeable and flow technologies face divergent manufacturing scale economics. Primary and thin film chemistries occupy specialized niches with limited gigafactory investment overlap.
- Rechargeable:Lithium-ion and nickel metal hydride systems dominate cell manufacturing scale. Dry electrode coating and inert atmosphere assembly lines require billion-euro capital commitments with extended payback horizons.
- Flow:Vanadium and zinc-bromine systems for multi-hour grid storage. French utility networks are expanding installations for renewable integration, though system costs remain above lithium-ion for sub-four-hour durations.
- Primary:Non-rechargeable alkaline and lithium metal cells for medical devices and military applications. Limited West European manufacturing presence; import dependence from Asian suppliers.
- Thin Film:Solid-state micro-batteries for sensors and wearables. Swiss and German specialty manufacturers focus on medical and aerospace qualification pathways.
Rechargeable technology commands the volume base, with flow systems gaining share fastest in utility procurement.
Distribution Channel:
Direct sales and online retail are compressing wholesale margins as technical buyers consolidate procurement. Specialty stores retain relevance for replacement markets and technical advisory.
- Direct Sales:Cell makers negotiate volume commitments with automotive OEMs and energy developers. German municipal utilities and French renewable developers bypass trading house intermediaries through long-dated contracts.
- Wholesalers:Industrial and commercial buyers source standardized packs through regional distributors. REACH documentation and carbon footprint verification are becoming table stakes for channel access.
- Online Retail:Consumer and small commercial segments. E-commerce platforms are expanding private-label battery offerings with CE marking compliance as primary differentiation.
- Specialty Stores:Technical advisory and installation services for off-grid solar and marine applications. Italian and Greek island markets sustain localized retail footprints.
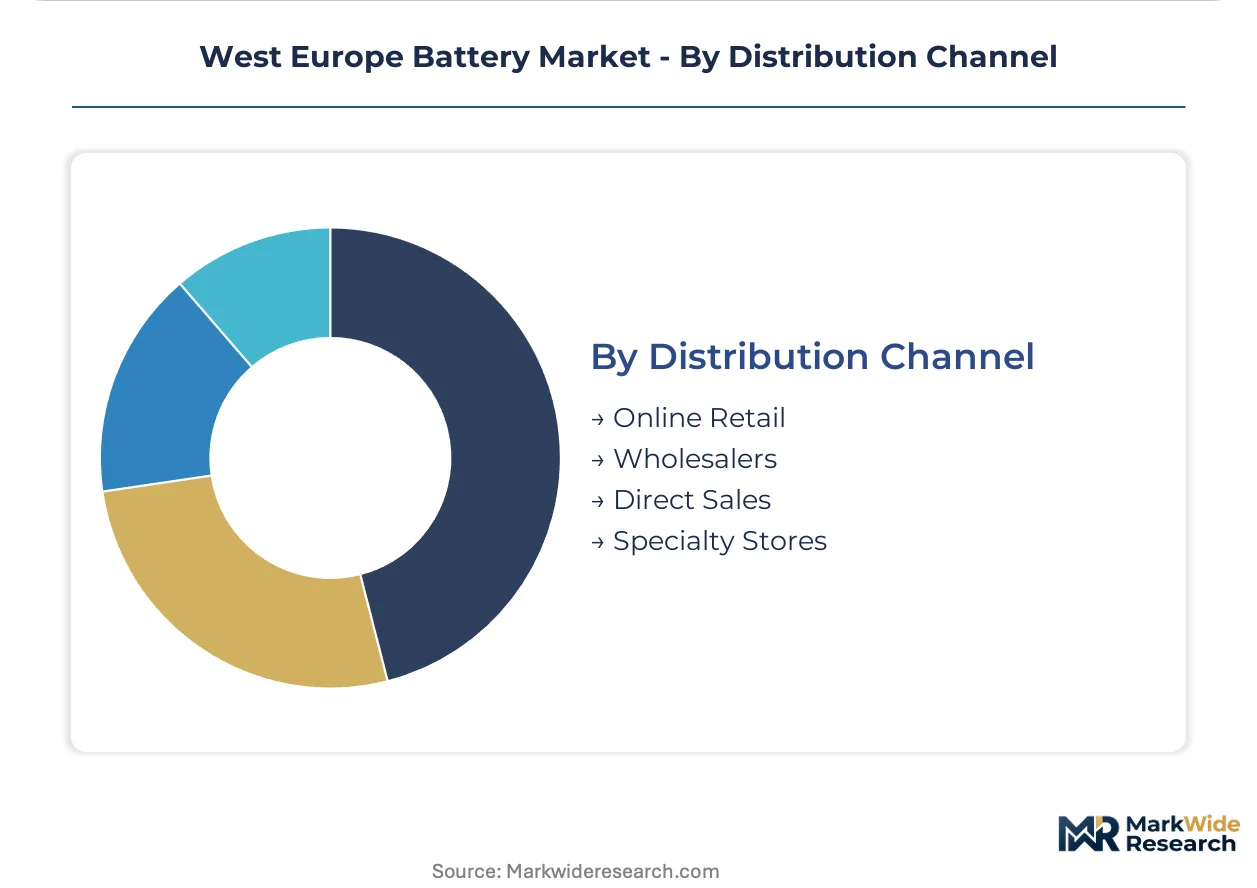
Direct sales leads volume concentration, with online retail climbing fastest in consumer and small commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive corridor spanning Stuttgart, Munich, and Wolfsburg anchors West European battery demand as EV manufacturers accelerate lithium-ion procurement and localize supply chains under EU regulatory pressure.
Germany
Stuttgart, Munich, and Wolfsburg-based OEMs are consolidating multi-year offtake agreements with Polish and Swedish cell factories. KBA enforces EU Battery Regulation compliance through vehicle type approval processes. Bavaria's Ingolstadt and Munich clusters host pilot solid-state production lines targeting premium EV contracts.
France
French EV startups and Renault's electrification programs are driving cathode active material demand. ANSM coordinates with ECHA on REACH substance restrictions for fluorinated electrolyte additives. The Dunkirk region is attracting precursor chemical investments to serve regional gigafactories.
Sweden
Northvolt's gigafactory complex in Västerås and Skellefteå anchors regional cathode production and closed-loop recycling infrastructure. Swedish environmental agencies enforce stringent carbon footprint verification for battery passport compliance. The Norrland region hosts Europe's largest lithium-ion cell manufacturing footprint.
Poland
LG Energy Solution's Wrocław manufacturing base serves German automotive OEMs directly, bypassing traditional distribution channels. Polish market surveillance authorities implement EU Battery Regulation import controls at Baltic ports. The Lower Silesia cluster concentrates cell assembly and module integration capacity.
Spain
Iberian hard-rock and brine extraction projects in Extremadura and Galicia offer captive lithium supply for cathode precursor plants. Spanish utility networks are expanding multi-hour flow battery installations for renewable integration. The Basque Country hosts automotive battery system integration facilities supplying French and German OEMs.
West Europe Battery Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and regulatory compliance capabilities. The vendor base stratifies into Asian conglomerates with integrated precursor supply, European specialists in industrial and grid applications, and emerging regional cell producers building captive recycling loops. Three archetypes dominate: chemistry-agnostic volume producers, high-cycle industrial specialists, and solid-state technology developers. Capacity expansion and strategic partnerships constitute the primary competitive moves as players secure raw material offtake and localize production within the EU regulatory perimeter.
Among Asian conglomerates, Contemporary Amperex Technology Co. Limited and BYD Company Ltd. exemplify integrated volume producers with upstream control over precursor chemicals. LG Energy Solution occupies a position bridging global scale and European regional presence through its Polish manufacturing base. These three anchors represent divergent approaches to EU market access: direct investment versus export qualification versus partnership structures.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited |
| BYD Company Ltd. |
| Panasonic Corporation |
| VARTA Microbattery GmbH |
| Clarios LLC |
| Northvolt |
| LG Energy Solution |
| Saft Groupe S.A. |
| Toshiba Corp |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers in Sweden and Poland anchor cathode supply expansion, translating state-supported financing into below-market capital costs that compress cell pricing for German automotive OEMs while forcing privately-funded competitors toward premium specialty chemistries.
Pricing Analysis
Input-cost pass-through from lithium carbonate and cobalt sulfate volatility dominates contract renegotiation cycles between Polish cell factories and Stuttgart-based OEMs. Three-tier pricing structure across premium solid-state, standard NMC, and economy LFP chemistries reflects certification grade and volume scale differentials. Cost compression in entry-tier packs is intensifying because Chinese precursor suppliers are absorbing margin erosion to maintain European market share. Fleet operators with ESG mandates show least price sensitivity, while aftermarket replacement buyers concentrate procurement around lowest CE-marked offerings.
Supply Chain Analysis
EU Battery Regulation passport certification gates access to German and French vehicle type approval pathways, filtering supplier pools before commercial negotiations commence. Cathode active material supply concentrates in China, South Korea, and Japan, with precursor chemical output drawing from Chilean brine and Australian spodumene. Single-source vulnerability runs through Chinese-controlled refining capacity for battery-grade lithium hydroxide. Distribution runs through direct long-term offtake agreements that displace spot-market intermediaries for automotive and utility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
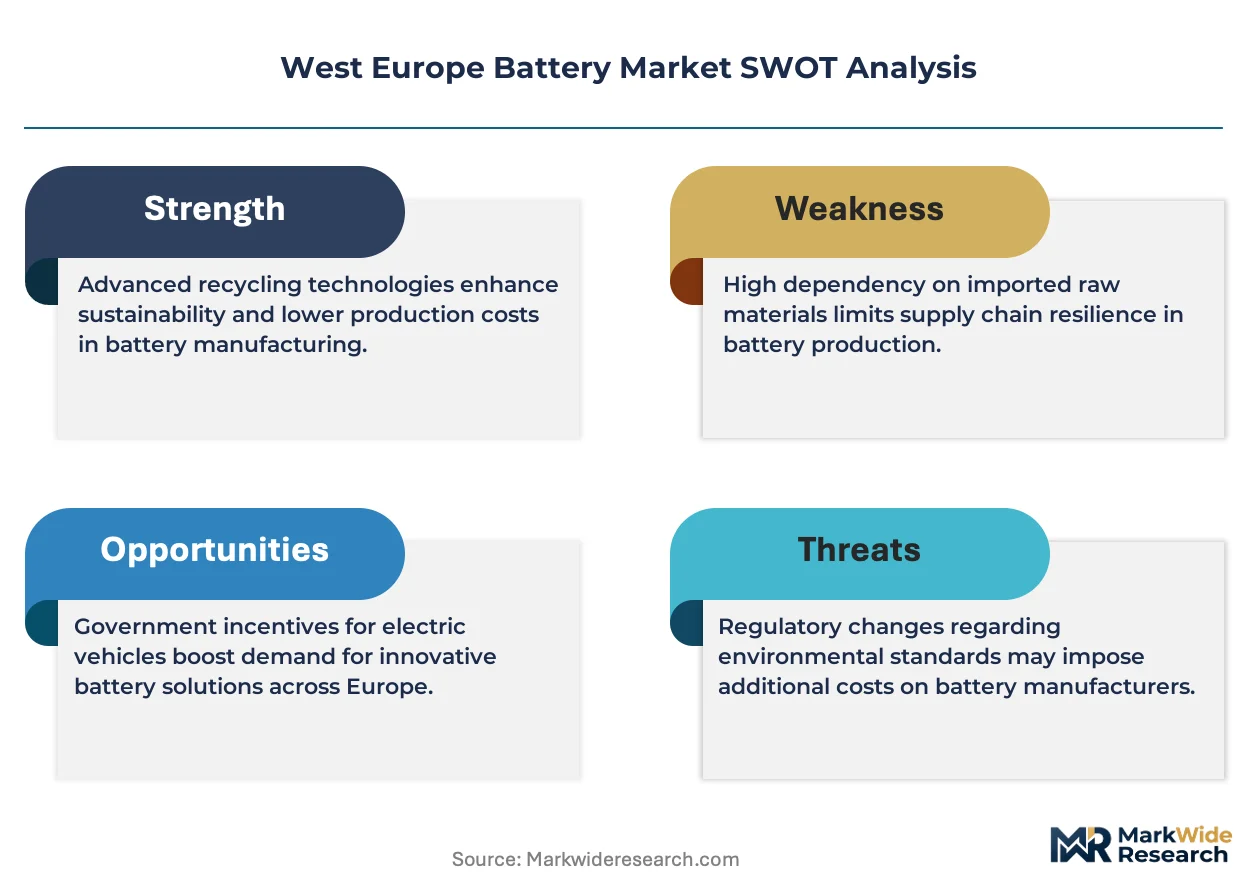
West Europe's battery market functions as a geographic-arbitrage play where ECHA REACH compliance costs in France and Germany exceed Iberian production economics, rewarding Spanish and Portuguese manufacturing investments with margin capture.
For Market Incumbents: Deploy backward integration into Iberian lithium extraction to secure captive raw material supply against Chinese precursor volatility. Incumbent cell makers must accelerate solid-state pilot lines before Swedish competitors achieve commercial yields, while locking German OEMs into multi-year LFP supply contracts that foreclose second-source qualification windows. For New Entrants and Emerging Players: Second-life battery aggregators represent the most penetrable channel partner type for warehouse energy arbitrage plays across Belgium and the Netherlands. White-space targets include flow battery system integration for French utility networks and silicon-anode R&D services for mid-tier automotive suppliers. A technical advisory go-to-market angle bypasses capital-intensive gigafactory competition. For Investors and Strategic Acquirers: Valuations sit cheapest among industrial lithium-ion specialists with established CE marking pathways and automotive qualification records. Long-term viability across the analysis window hinges on EU Battery Regulation compliance infrastructure rather than chemistry innovation alone. The signal to watch is passport system integration timelines extending product launch cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Plant Localization | Dunkirk and Västerås investments reduce Chinese supply exposure for German OEMs. |
| Solid-State Pilot Production Scale-Up | Swedish gigafactory output targets premium EV contracts from Munich-based manufacturers. |
| Closed-Loop Recycling Partnership | Northvolt's hydrometallurgical recovery meets EU recycled content mandates for French automakers. |
| Direct Utility offtake Agreements | Spanish renewable developers bypass distributors for multi-hour flow battery deployments. |
| REACH-Compliant Electrolyte Reformulation | Sulfone-based additives replace fluorinated compounds under ECHA enforcement. |
Research Methodology
Bottom-up automotive and utility procurement modeling reconciled against top-down cathode chemical production tracking forms the analytical core. Primary interviews with cell factory procurement directors, ECHA regulatory affairs leads, German OEM platform engineers, and Iberian mining project developers combined with secondary validation from EU Battery Regulation implementation reports, ECHA substance restriction databases, and KBA type approval filings. Bottom-up and top-down triangulation cross-checks volume assumptions against announced gigafactory capacity commitments.
Input-output matrices map lithium carbonate, cobalt sulfate, and nickel sulfate flows through precursor chemical plants to finished cell output across the projection horizon. Segmentation dimensions modeled include cathode chemistry, end-use application, and regional manufacturing cluster. CAGRs derive from installed capacity ramp schedules and OEM procurement contract visibility. Forecast inputs incorporate EU Battery Regulation compliance cost trajectories and solid-state manufacturing yield improvement curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese export restriction policies and ceramic electrolyte sintering breakthroughs. Forecasts reflect documented assumptions on raw material price normalization and regulatory enforcement intensity. A model refresh is warranted upon material change in EU Battery Regulation secondary legislation or Iberian lithium project commissioning timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
India Battery Cell Market
Batteries
PVT Battery Panel Market
Batteries
North America Lead Acid Battery Market
Batteries
Power Battery Sealant Market
Batteries
Electric Battery Market
Batteries
Southeast Asia Battery Market
Batteries
North Africa Battery Market
Batteries
Europe Rechargeable Battery Market
Batteries
VRLA Batteries Market
Batteries
Europe Industrial Battery Market
Batteries
GCC Rechargeable Battery Market
Batteries
France Rechargeable Battery Market
Batteries
Global Industrial Battery Market
Batteries
Asia Pacific Electric Vehicle Battery Electrolyte Market
Batteries
Iron Flow Battery Market
Batteries
Rear Rack Battery Market