
 Indonesia Battery Market | 2026-2036
Indonesia Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Battery Market Outlook
Aftermarket service revenue for battery diagnostics and second-life repurposing is tilting toward integrated cell-to-system providers. CATL anchors this shift through its joint venture with Indonesia Battery Corporation, which controls nickel-to-cathode refining corridors in Sulawesi. BYD competes via captive demand from its Wuling and GAC Aion automotive partnerships, while Zhejiang Huayou Cobalt extends upstream leverage through its Morowali smelter complex.
A battery for Indonesia's market comprises electrochemical cells engineered to store and deliver direct-current energy through reversible ion transfer between cathode and anode materials, with lithium-ion configurations typically achieving 150-300 Wh/kg energy density and cycle lives exceeding 2,000 charges. These systems power electric mobility, stabilize renewable intermittency, and sustain industrial operations across archipelago logistics. Lithium-ion chemistry leads product type segmentation due to nickel-rich cathode compatibility with domestic ore supply, while solid-state technology advances fastest among technology categories as Hyundai LG Indonesia Green Power tests next-generation formats for tropical thermal tolerance. Energy storage applications command expanding margin pools as PLN's renewable integration targets multiply grid-scale procurement.
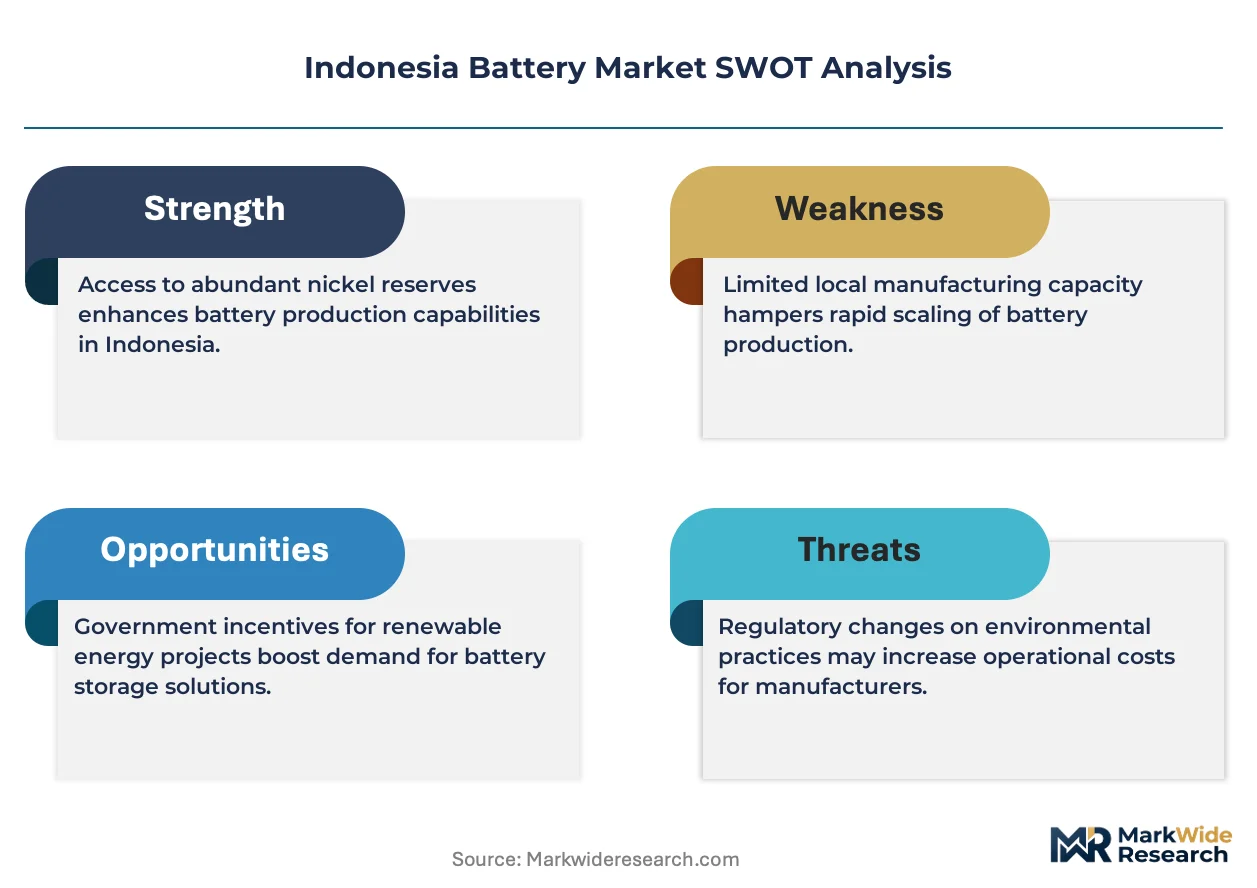
BIS-equivalent SNI certification, MEMR downstreaming regulations, and Ministry of Environment battery recycling directives collectively reshape product standards and foreign OEM market access. SNI mandates force import substitution toward domestic cell assembly, while recycling rules anticipate end-of-life liability for nickel and cobalt recovery. Stakeholders must weigh nickel price volatility against offtake commitments from integrated smelter-to-cell facilities before committing capital to new manufacturing footprints.
Market Dynamics
MEMR Regulation No. 11/2020 is redirecting cathode precursor supply chains toward domestic smelters, compressing lead times for nickel-rich lithium-ion cell production while locking foreign OEMs into local offtake partnerships.
Growth Catalysts
- Downstreaming mandates:MEMR Regulation No. 11/2020 requires nickel ore processing within Indonesian territory before export, forcing cathode precursor localization and attracting integrated cell manufacturing investments to Sulawesi smelter corridors.
- Two-wheeler electrification:Battery swapping networks for electric motorcycles are scaling across Greater Jakarta, creating standardized pack demand that favors domestic cell assembly over imported finished batteries.
- Grid-scale storage procurement:PLN's renewable integration targets are multiplying utility-scale battery energy storage system tenders, anchoring demand for containerized lithium-ion systems with tropical thermal management.
Market Restraints
- Nickel price volatility:London Metal Exchange nickel contract swings disrupt cathode cost modeling for cell producers committed to long-term offtake agreements with Morowali smelter complexes.
- Sulfuric acid supply concentration:Hydrometallurgical refining of laterite ore depends on acid imports concentrated through Southeast Asian chemical traders, exposing margin compression during shipping disruptions.
- Lithium raw material deficit:Indonesia possesses no economically viable spodumene or brine deposits, forcing cell manufacturers to import carbonate and hydroxide through Australian and Chilean suppliers.
Strategic Opportunities
- Eastern Indonesia logistics electrification:Archipelago shipping and island microgrids present underpenetrated demand for ruggedized battery systems with salt-corrosion resistance specifications absent from Java-centric product portfolios.
- Second-life repurposing:Retired electric motorcycle packs from Gojek and Grab fleets offer feedstock for stationary energy storage in off-grid Sulawesi mining camps, creating circular revenue streams.
- SNI certification acceleration:Mandatory national standard compliance for imported cells is forcing quality upgrades that position domestic assemblers to capture ASEAN re-export markets.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design and thermal management expertise concentrates in Greater Jakarta, constraining smelter-to-cell facility staffing in remote Sulawesi industrial zones.
- Battery recycling infrastructure capex:Ministry of Environment directives mandate nickel and cobalt recovery liability without established hydrometallurgical recycling capacity, requiring greenfield facility investments ahead of end-of-life volume arrival.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Battery Market |
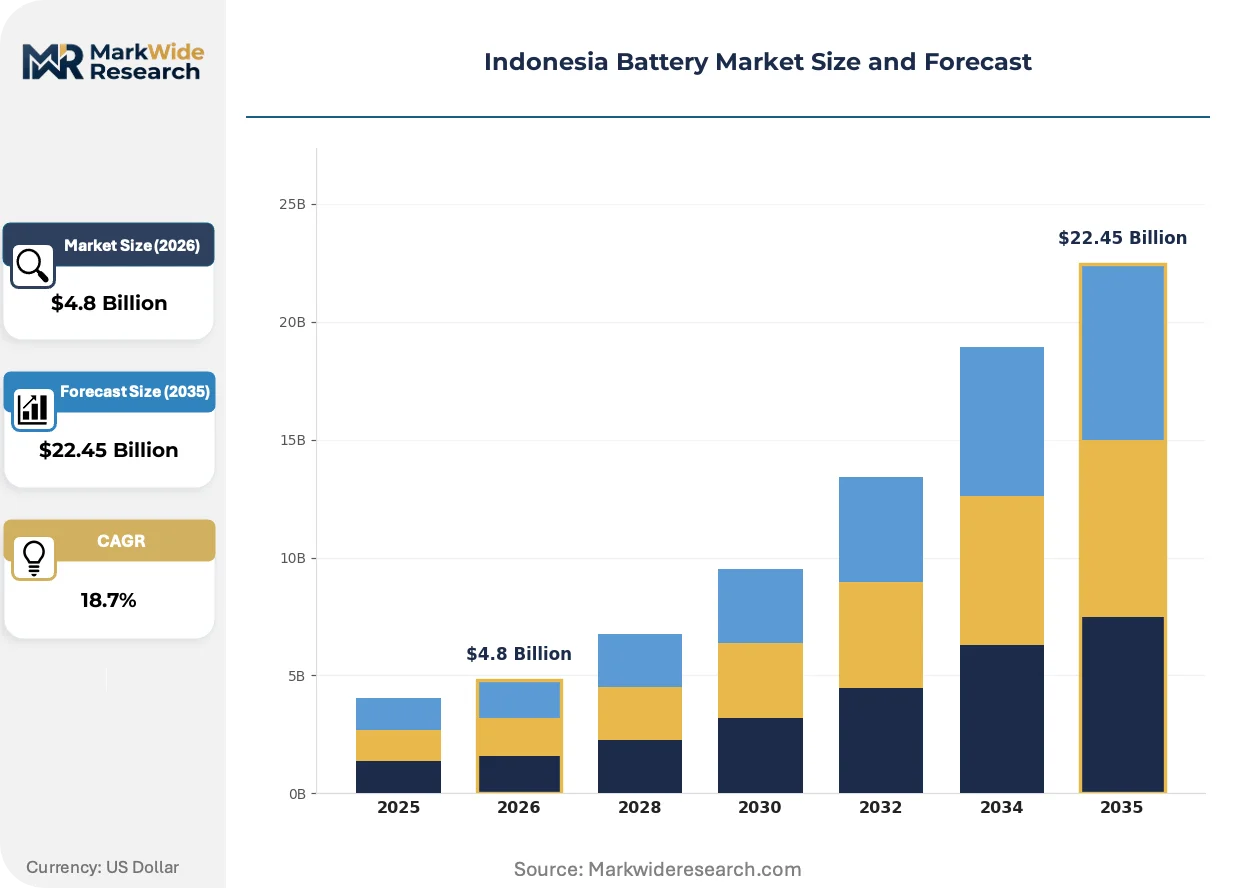
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Flow Battery Technology: Rechargeable, Solid-state, Nanotechnology, Advanced Chemistry End User: Automotive, Consumer Electronics, Industrial Equipment, Energy Storage Application: Electric Vehicles, Portable Devices, Renewable Energy, Backup Power |
| Companies Covered | PT Aneka Tambang, BYD, CATL (Contemporary Amperex Technology Co., Limited), Wuling, GAC Aion, Hyundai LG Indonesia Green Power, Zhejiang Huayou Cobalt, Chery, Indonesia Battery Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Battery Market Strategic Shifts
Solid-state electrolyte formats and digital battery management systems are compressing the competitive window for conventional lithium-ion architectures while MEMR downstreaming rules reshape who controls cathode supply.
Silicon nanowire anode additives are virtualizing energy density improvements in nickel-rich NMC cells by replacing graphite intercalation chemistry. Hyundai LG Indonesia Green Power is piloting these formats for tropical thermal tolerance in Java electric bus fleets. The technology is virtualizing the traditional trade-off between cycle life and gravimetric capacity that has constrained fast-charging two-wheeler applications.
Ministry of Environment battery recycling directives are mandating extended producer liability frameworks that force OEMs to pre-fund end-of-life collection infrastructure. Cell importers must now demonstrate recovery pathway partnerships before SNI certification approval. The regulations are accelerating domestic hydrometallurgical recycling joint ventures, particularly for nickel and cobalt streams from Morowali smelter offcuts.
Fleet operators are consolidating procurement through cell-to-system integrators rather than trading house intermediaries. Gojek and Grab are negotiating direct cathode supply agreements with IBC-linked producers, bypassing traditional battery distributor networks. This concentration is most visible in Greater Jakarta, where integrated service contracts now bundle diagnostics, thermal management, and second-life repurposing into per-kilometer pricing structures.
Indonesia Battery Market Segmentation
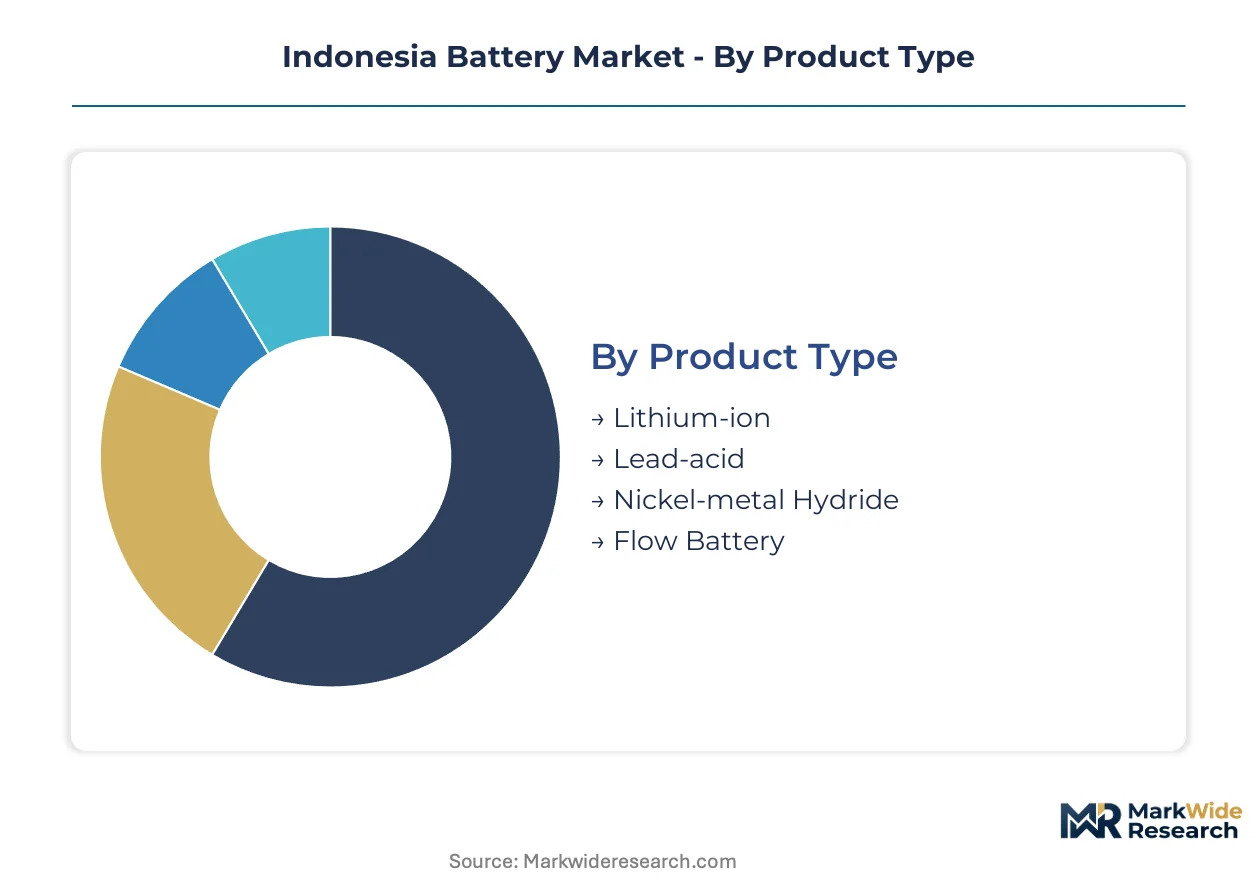
Segmentation in Indonesia's battery market reveals how MEMR downstreaming mandates and SNI certification requirements are concentrating procurement around specific chemistries and integrated supply chain configurations. Each dimension exposes different pressure points for foreign OEMs versus domestic assemblers.
Product Type:
Mature formats dominate installed base while emerging chemistries capture capital deployment.
- Lithium-ion:Nickel-rich NMC and LFP cells achieve 150-300 Wh/kg energy density with cycle lives exceeding 2,000 charges. Demand concentrates in Greater Jakarta electric bus depots and Gojek two-wheeler swapping stations, driven by cathode precursor compatibility with Morowali smelter output.
- Lead-acid:Flooded and AGM configurations deliver 30-50 Wh/kg with established recycling infrastructure. Industrial UPS and telecom backup systems across Java manufacturing zones sustain procurement volumes despite lithium substitution in mobility applications.
- Nickel-metal Hydride:Toyota hybrid vehicle production in Karawang anchors residual demand for this chemistry as legacy powertrain configurations phase out gradually.
- Flow Battery:Vanadium redox systems scale in PLN grid-scale tenders where 4-6 hour discharge durations exceed lithium-ion economic viability.
Lithium-ion handles the majority of throughput; flow battery is the fastest mover on share.
Technology:
Cost tier stratification separates mass-market rechargeable formats from premium solid-state development programs.
- Rechargeable:Conventional lithium-ion with liquid electrolyte dominates pack assembly lines in Bekasi and Karawang industrial corridors. PLN utility tenders and Wuling Airev procurement anchor volume.
- Solid-state:Sulfide and oxide electrolyte formats eliminate thermal runaway risk while targeting 400+ Wh/kg density. Hyundai LG Indonesia Green Power pilots these systems for tropical climate tolerance in Java electric bus fleets.
- Nanotechnology:Silicon nanowire anode additives from domestic material suppliers boost gravimetric capacity without sacrificing cycle stability in fast-charging two-wheeler applications.
- Advanced Chemistry:Sodium-ion and lithium-sulfur prototypes target cost reduction for archipelago microgrid storage where nickel price volatility disrupts NMC economics.
Rechargeable technology commands current manufacturing capacity; solid-state is gaining share fastest among new capital commitments.
End User:
Application volume separates automotive scale from industrial margin pools.
- Automotive:Passenger EV, electric bus, and two-wheeler OEMs specify pack formats with integrated battery management systems and thermal runaway containment. IBC-CATL joint venture and BYD-Wuling partnerships control cathode-to-module supply.
- Consumer Electronics:Smartphone and laptop assemblers in Batam free trade zone import cylindrical and prismatic cells under bonded warehouse schemes, bypassing SNI mandates for re-export markets.
- Industrial Equipment:Forklift and mining vehicle electrification in Kalimantan and Papua drives demand for ruggedized IP67-rated packs with salt-corrosion resistance.
- Energy Storage:PLN's 35 GW renewable integration target multiplies containerized BESS procurement across Sulawesi and Sumatra interconnection nodes.
Automotive end users absorb the largest cell volumes; energy storage is expanding most quickly on capacity additions.
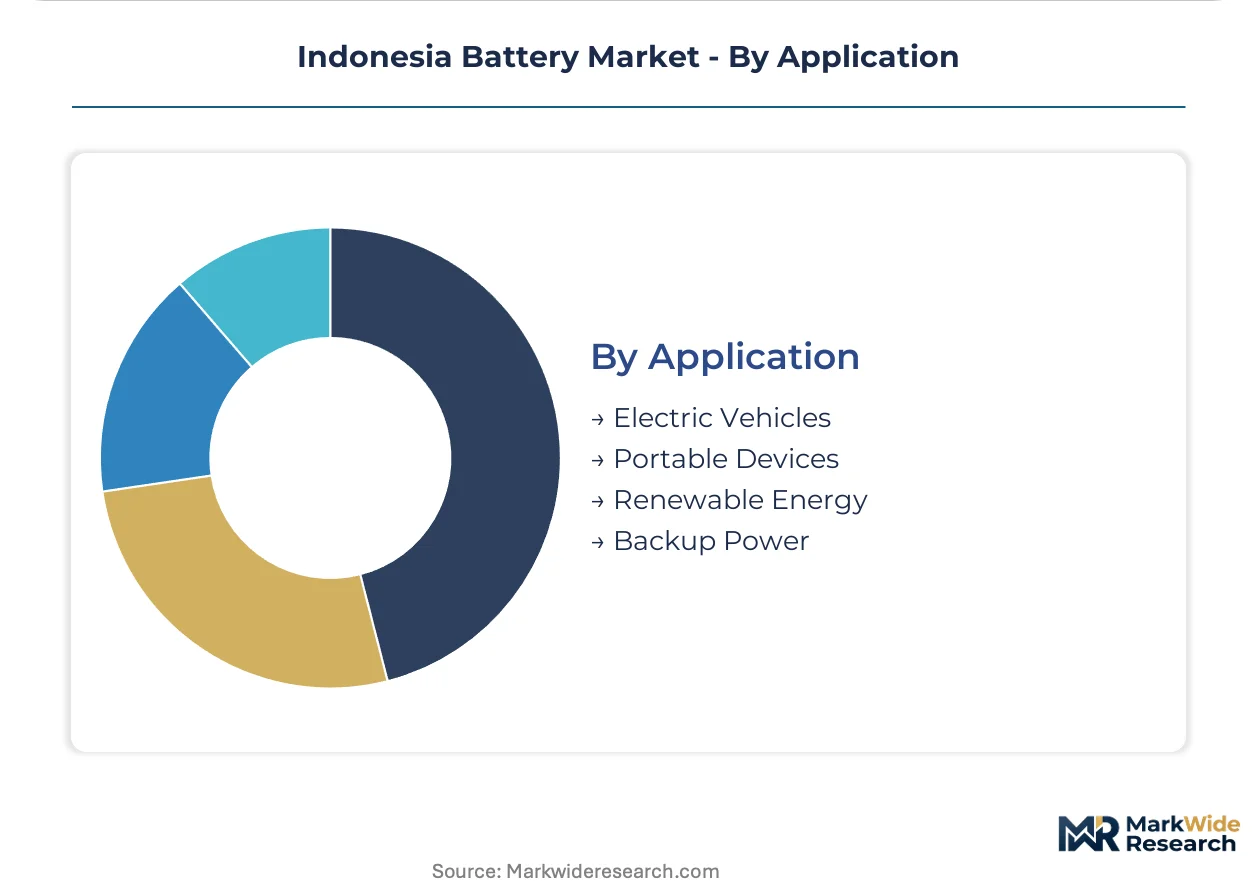
Application:
Customer type bifurcation separates fleet procurement standardization from distributed residential demand.
- Electric Vehicles:Four-wheel passenger cars, electric buses, and two-wheelers specify pack architectures with standardized swapping interfaces. Gojek and Grab fleet operators negotiate direct cathode supply agreements bypassing distributor networks.
- Portable Devices:Power tools, medical equipment, and consumer electronics require compact 18650 and 21700 cylindrical formats with UN38.3 transport certification for archipelago logistics.
- Renewable Energy:Solar-plus-storage hybrid systems in Eastern Indonesia microgrids demand cycle stability under high-temperature operating conditions absent from temperate-zone product specifications.
- Backup Power:Data centers, hospitals, and telecom towers specify 4-hour to 8-hour discharge duration with diesel generator integration protocols.
Electric vehicle applications drive the dominant share of cathode consumption; renewable energy pairing is climbing the fastest on project pipeline growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Greater Jakarta exhibit the highest price sensitivity due to fragmented fleet procurement, while Sulawesi smelter-linked customers accept premium pricing for integrated cathode supply security.
Java
Electric bus depots and two-wheeler swapping networks for Gojek and Grab fleets absorb the majority of lithium-ion cell throughput. MEMR downstreaming mandates under Regulation No. 11/2020 require nickel ore processing within Indonesian territory, redirecting cathode precursor supply toward domestic facilities. The Bekasi-Karawang industrial corridor hosts pack assembly lines serving Wuling and GAC Aion automotive partnerships.
Sulawesi
Morowali smelter complexes anchor nickel-to-cathode refining corridors for integrated cell manufacturing investments. Indonesia Battery Corporation's joint venture with CATL controls critical upstream capacity, locking foreign OEMs into local offtake partnerships. Remote industrial zones face electrochemical engineering talent scarcity, constraining staffing for smelter-to-cell facilities.
Sumatra
Grid-scale battery energy storage system tenders from PLN multiply across interconnection nodes supporting renewable integration targets. Containerized lithium-ion systems with tropical thermal management specifications dominate procurement. Medan and Palembang clusters concentrate engineering services for utility-scale installation and maintenance.
Kalimantan
Mining vehicle electrification and industrial logistics drive demand for ruggedized IP67-rated packs with salt-corrosion resistance. Ministry of Environment battery recycling directives mandate nickel and cobalt recovery liability, anticipating end-of-life volume from heavy-duty applications. Samarinda and Balikpapan serve as distribution hubs for archipelago shipping electrification.
Eastern Indonesia
Archipelago shipping and island microgrids present underpenetrated demand for battery systems with specifications absent from Java-centric product portfolios. Solar-plus-storage hybrid systems in remote locations demand cycle stability under high-temperature operating conditions. Makassar anchors logistics for second-life repurposing of retired electric motorcycle packs into stationary storage for off-grid mining camps.
Indonesia Battery Market Competitive Environment
Integrated cell-to-system providers and upstream material specialists split the market between cathode supply control and pack assembly dominance. The vendor base concentrates around smelter-linked joint ventures and automotive captive demand arrangements. Three archetypes define competitive positioning: nickel-cathode integrators, fleet-direct suppliers, and technology licensors. Capacity expansion into Sulawesi refining corridors and strategic partnerships for SNI certification compliance represent the dominant competitive moves.
Among nickel-cathode integrators, Indonesia Battery Corporation and Zhejiang Huayou Cobalt occupy positions exemplifying upstream-to-cell verticalization, while CATL anchors the technology-licensor archetype through its joint venture structure. BYD represents the fleet-direct supplier model via captive demand from automotive partnerships. Hyundai LG Indonesia Green Power sits within the advanced-technology tier, piloting next-generation formats for tropical climate applications. These groupings illustrate how MEMR downstreaming rules and SNI mandates reshape foreign OEM market access toward integrated local production.
| Leading Market Players |
|---|
| PT Aneka Tambang |
| BYD |
| CATL (Contemporary Amperex Technology Co., Limited) |
| Wuling |
| GAC Aion |
| Hyundai LG Indonesia Green Power |
| Zhejiang Huayou Cobalt |
| Chery |
| Indonesia Battery Corporation |
| Others |
Value Chain & Pricing Dynamics
Morowali smelter corridors concentrate nickel-to-cathode refining capacity, anchoring margin pools in integrated cell assembly rather than raw ore export. MEMR downstreaming mandates force foreign OEMs into local offtake partnerships, compressing procurement options while elevating domestic pack assemblers to price-setting positions.
Pricing Analysis
Aftermarket service revenue for battery diagnostics and second-life repurposing drives lifetime value capture for integrated cell-to-system providers. Three-tier pricing structure across premium, standard, and economy levels separates SNI-certified domestic packs from import substitutes and grey-market cells. Cost compression in standard-tier lithium-ion modules intensifies because Gojek and Grab fleet operators negotiate direct cathode supply agreements, bypassing distributor markups. Two-wheeler swapping networks in Greater Jakarta exhibit highest price sensitivity, while Sulawesi smelter-linked utility buyers accept premium pricing for integrated supply security.
Supply Chain Analysis
Upstream feedstock for Indonesian cell manufacturing draws from Philippine laterite ore, Australian spodumene concentrate, and Chilean lithium carbonate. Hydrometallurgical refining rests on sulfuric acid imports concentrated through Southeast Asian chemical traders, creating single-source vulnerability during shipping disruptions. Distribution runs through bonded warehouse schemes in Batam free trade zone for consumer electronics re-export, while automotive and energy storage procurement channels direct through Bekasi-Karawang pack assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's battery market demands substitution defense against sodium-ion chemistry for archipelago microgrids, where nickel price volatility threatens NMC economics. Incumbents must navigate this threat while locking in cathode supply through integrated smelter partnerships.
For Market Incumbents: Insulate cathode cost positions through backward integration into Morowali refining corridors and captive offtake agreements with IBC-linked producers. Accelerate SNI certification investments to block import substitutes from grey-market channels. Sodium-ion prototypes for stationary storage represent the looming substitute threat requiring pre-emptive R&D hedging. For New Entrants and Emerging Players: Eastern Indonesia island microgrids and archipelago shipping electrification represent the most penetrable entry point for ruggedized battery systems with salt-corrosion resistance specifications absent from Java-centric portfolios. Second-life repurposing of retired Gojek motorcycle packs into off-grid mining camp storage offers circular revenue stream entry. Direct procurement relationships with PLN utility planning officers bypass established distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward smelter-to-cell verticalization specialists with locked nickel offtake and SNI compliance pathways. Long-term viability over the next decade hinges on positioning ahead of Ministry of Environment recycling liability enforcement. Watch for inflection in PLN renewable integration tender awards as capacity commitment signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Localization | MEMR Regulation No. 11/2020 mandates domestic processing, attracting integrated manufacturing to Sulawesi corridors. |
| SNI Certification Acceleration | Mandatory national standards force quality upgrades that position domestic assemblers for ASEAN re-export markets. |
| Second-Life Repurposing Infrastructure | Retired Gojek and Grab fleet packs create circular revenue streams for off-grid Sulawesi mining camp storage. |
| Grid-Scale BESS Procurement | PLN's renewable integration targets multiply containerized lithium-ion tenders across Sumatra interconnection nodes. |
| Solid-State Technology Piloting | Hyundai LG Indonesia Green Power tests next-generation formats for tropical thermal tolerance in Java electric bus fleets. |
Study Parameters
A standing panel of PLN utility planning officers, smelter operations managers, Gojek fleet procurement leads, and SNI certification auditors provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from MEMR regulatory filings, Indonesian customs trade data, PLN tender announcements, and IEA energy storage deployment reports. Bottom-up cell shipment tracking and top-down cathode precursor production estimates were triangulated to anchor volume figures.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation modeled by product type, technology tier, end-use application, and regional industrial cluster. CAGRs were derived from installed base evolution and replacement cycle analysis. Forecast inputs incorporated PLN renewable integration pipeline visibility, MEMR downstreaming compliance timelines, and two-wheeler electrification subsidy trajectories.
Macroeconomic conditions sit as an overlay; deviation in nickel LME contract volatility, rupiah-dollar exchange rates, or sulfuric acid shipping costs would shift the trajectory. Forecasts reflect documented assumptions about SNI enforcement stringency and recycling liability implementation pace. Cross-checking against ASEAN battery trade flow data and regional smelter capacity announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Japan Battery Market
Batteries
Utility Battery Market
Batteries
United Kingdom SLI Battery Market
Batteries
United Kingdom Electric Vehicle Battery Electrolyte Market
Batteries
Battery Pack Balancer Market
Batteries
Thin Film and Printed Battery Market
Batteries
North America Consumer Battery Market
Batteries
Vanadium Redox Flow Batteries (VRFB) Market
Batteries
Global Coke Oven Batteries Market
Batteries
South Asia Battery Market
Batteries
48 Volt Battery System Market
Batteries
Wood-Based Batteries Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
Europe Battery Market
Batteries
High Temperature NiMH Battery Market
Batteries
Atomic Battery Market