
 China Rechargeable Battery Market | 2026-2036
China Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
China Rechargeable Battery Market Insights
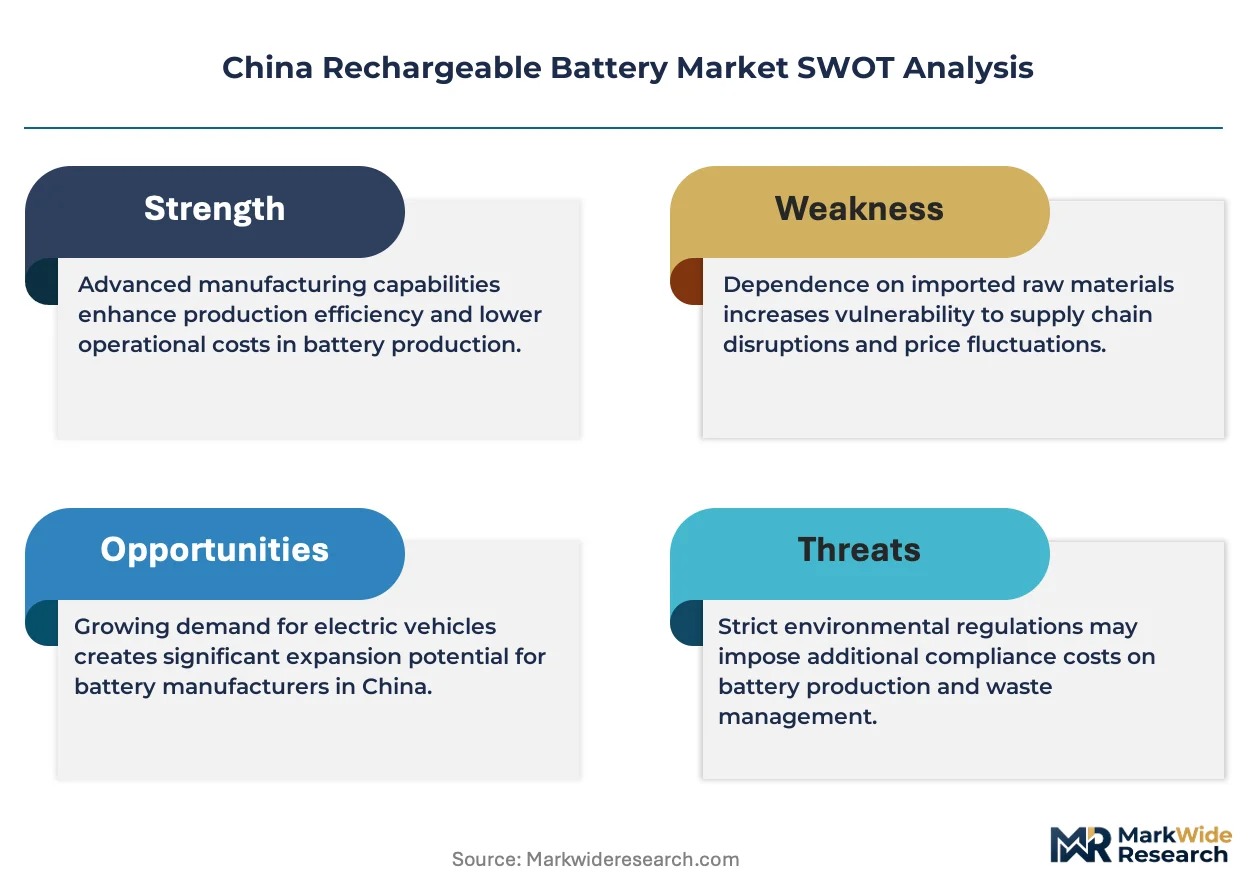
GB/T certification for lithium-ion traction batteries is collapsing the supplier base to manufacturers with testing infrastructure and capital reserves. CATL leverages its vertical integration into cathode materials and cell production to sustain cost leadership across automotive contracts. BYD Company anchors its position through in-house vehicle demand and blade cell architecture. Gotion High-Tech competes on LFP chemistry specialization and provincial government partnerships in Anhui.
China rechargeable batteries are electrochemical storage devices with rated voltages typically spanning 3.2V to 4.3V per cell, utilizing layered oxide or olivine cathode structures paired with graphite or silicon-composite anodes, manufactured through slurry coating, calendering, and formation cycling processes designed to deliver cyclable energy for mobility and grid applications. Lithium-ion chemistry dominates installed capacity due to energy density thresholds demanded by electric vehicle platforms, while solid-state technology attracts R&D capital for its potential to eliminate thermal runaway risks. Energy Storage applications are expanding fastest behind utility-scale procurement mandates, though consumer electronics retains the most mature margin pool.
MIIT battery whitelist requirements and GB standards enforced by SAMR dictate cell format, cycle life, and safety testing protocols for domestic sale and export eligibility. The country's dual carbon goals are accelerating demand for grid-tied storage systems that must comply with CEA interconnection rules. Stakeholders must monitor how provincial capacity licensing and lithium raw material import policies reshape manufacturing location decisions.
Market Dynamics
MIIT battery whitelist enforcement and GB/T certification requirements are compressing the supplier base toward manufacturers with captive testing infrastructure and provincial licensing access, reshaping competitive entry barriers across China's rechargeable battery sector.
Growth Catalysts
- Dual carbon policy mandates:China's 2030 carbon peak and 2060 neutrality targets under MEE oversight are mandating grid-tied energy storage procurement across provincial power grids, directly expanding LFP and NMC cell demand.
- Electric vehicle platform electrification:Automotive OEMs are localizing cell sourcing within the Yangtze River Delta cluster to secure supply chain resilience and qualify for NEV subsidy programs administered by MIIT.
- Solid-state R&D capital deployment:Sulfide-based electrolyte research programs at CAS institutes and Tsinghua University are advancing toward pilot production lines targeting thermal runaway elimination in high-energy density applications.
Market Restraints
- Lithium carbonate price volatility:Qinghai and Sichuan domestic brine extraction capacity constraints and Chilean-Argentine import dependency are creating margin compression for cathode material producers without long-term offtake agreements.
- Graphite anode supply concentration:Heilongjiang and Shandong provinces control over 80% of spherical graphite processing capacity, creating geographic bottleneck risk for cell manufacturers outside northern China.
- Electrolyte formulation IP fragmentation:Japanese and Korean patent thickets around lithium hexafluorophosphate additive combinations are restricting domestic electrolyte producers from accessing high-voltage cathode matching technologies.
Strategic Opportunities
- Anhui and Hubei manufacturing expansion:Provincial governments in central China are offering discounted industrial land and power tariffs to attract cell plants outside the saturated Yangtze River Delta corridor.
- Industrial ESS behind-the-meter deployment:Steel and chemical facilities under provincial dual-control energy intensity rules are procuring containerized battery systems to manage peak demand charges and avoid production curtailments.
- Sodium-ion chemistry commercialization:CATL and other producers are scaling prismatic sodium-ion cells for two-wheeler and A00-class vehicle applications where energy density requirements are relaxed and cost sensitivity dominates.
Industry Challenges
- Formation cycling technician scarcity:The electrochemical engineering talent pipeline from university programs in Hunan and Fujian is insufficient to staff the expanding base of giga-scale cell plants coming online through 2027.
- GB/T 31485 certification timeline compression:Third-party testing laboratory capacity at CATARC and CQC is creating 4-6 month queue delays for new cell format approvals, slowing product launch cycles for mid-tier manufacturers.
- Separator film coating equipment lead times:Japanese and German extrusion line manufacturers are extending delivery schedules to 18-24 months, constraining domestic wet-process separator capacity expansion plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Rechargeable Battery Market |
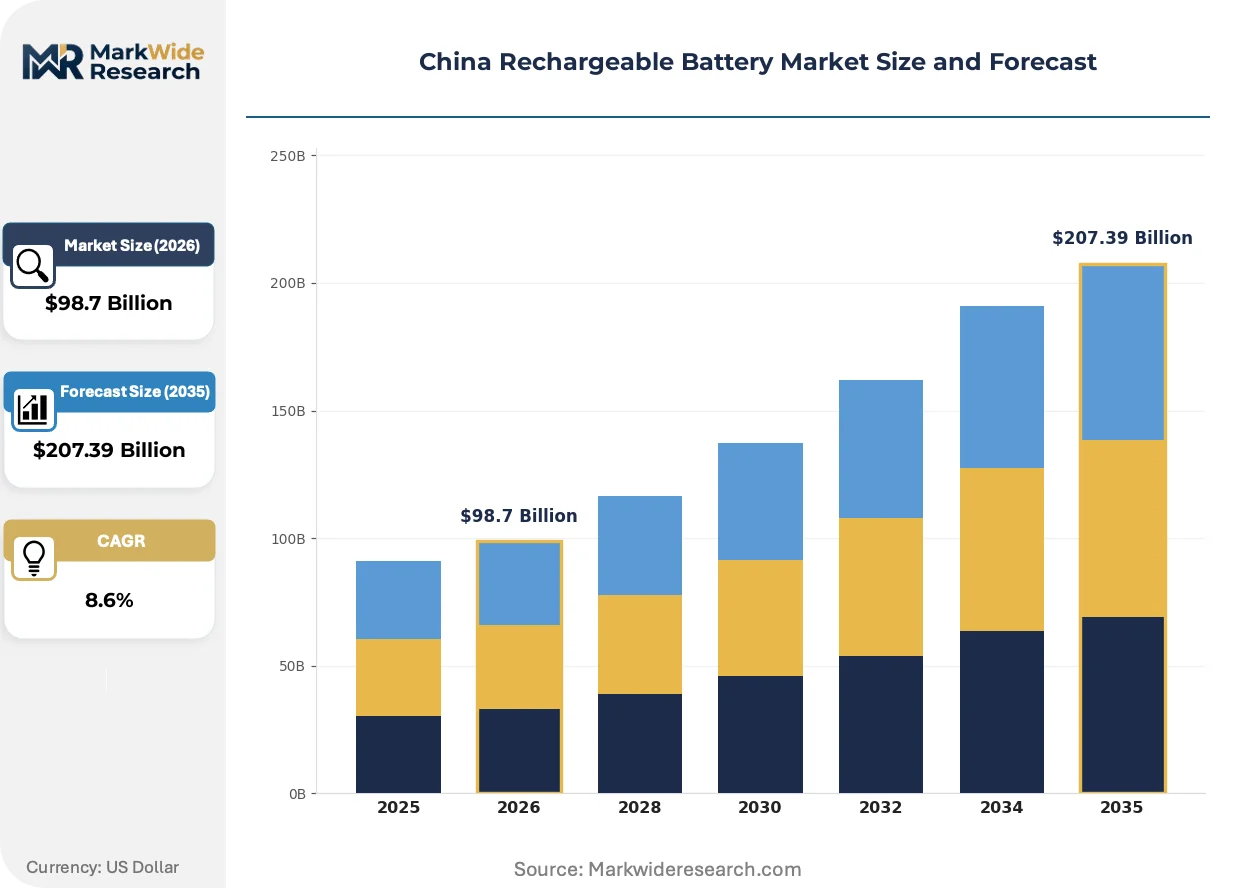
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $207.39 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-cadmium, Nickel-metal Hydride, Lead-acid End User: Consumer Electronics, Automotive, Industrial, Energy Storage Application: Electric Vehicles, Power Tools, Uninterruptible Power Supply, Portable Devices Technology: Fast Charging, Wireless Charging, Solid-state, Eco-friendly |
| Companies Covered | CATL (Contemporary Amperex Technology Co. Limited), BYD Company, EVE Energy Co., Ltd., Gotion High-Tech, CALB, Ganfeng Lithium, Farasis Energy, Lishen Battery, Fujian Minhua Power Source Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Rechargeable Battery Market Trends and Innovations
Electrochemical system architecture and manufacturing process control are converging around safety-first design principles that prioritize thermal stability over incremental energy density gains in China's rechargeable battery sector.
Lithium iron phosphate chemistry is displacing ternary NMC formulations in passenger vehicle traction applications below 600 km range targets. BYD and Tesla Shanghai are expanding LFP procurement for standard-range models, compressing cobalt and nickel demand trajectories while extending cycle life warranties toward 1.6 million kilometers. This chemistry migration is enabling cell producers to bypass constrained Class 1 nickel supply chains and qualify for simplified GB/T thermal abuse testing protocols.
GB standards enforced by SAMR are mandating nail penetration and overcharge abuse testing at the cell level for all domestic sale and export eligibility. The 2024 revision to GB/T 31485 tightened cycle life verification requirements from 500 to 1,000 full equivalent cycles, forcing manufacturers to extend formation cycling protocols and invest in predictive aging models. Energy storage system integrators face the most acute compliance burden as CEA interconnection rules now require module-level fire suppression documentation.
Automotive OEMs are consolidating cell procurement around direct long-term agreements rather than multi-tier supplier hierarchies. SAIC, GAC, and NIO are negotiating annual volume commitments with CATL and CALB that displace traditional trading company intermediaries, compressing price discovery transparency but securing allocation priority during raw material tightness. This channel restructuring is most visible in Guangdong province where vehicle assembly concentration has attracted dedicated cell plant investments from mid-tier producers seeking captive demand anchors.
China Rechargeable Battery Market Segmentation
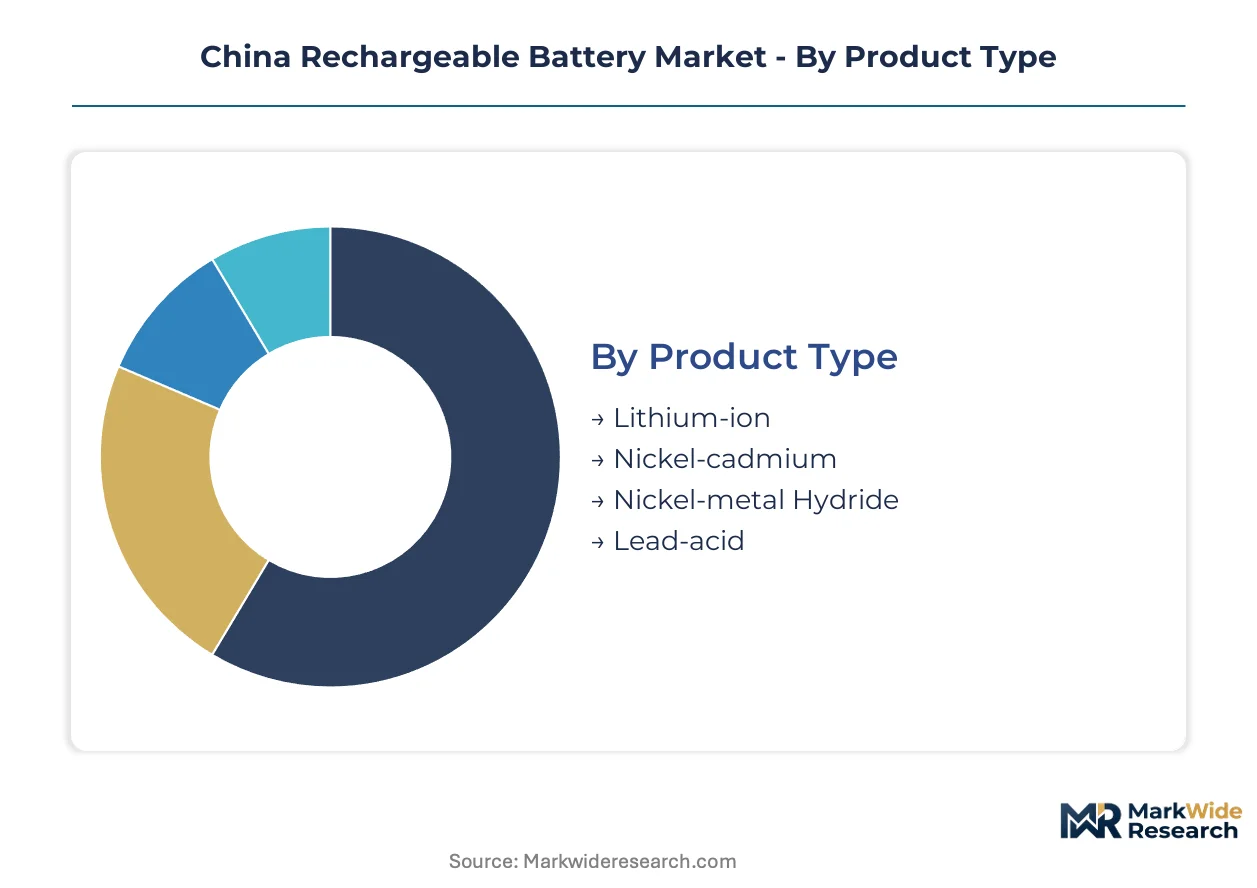
Segmentation in China's rechargeable battery sector reveals how procurement channels diverge across chemistry types and end-use requirements. MIIT whitelist compliance and GB/T certification create distinct qualification tiers that determine which manufacturers can supply automotive OEMs versus consumer electronics distributors.
Product Type:
Lithium-ion cells dominate automotive procurement channels through direct OEM contracts, while lead-acid and nickel-based chemistries flow through aftermarket distributors and industrial supply houses.
- Lithium-ion:Layered oxide and olivine cathode structures paired with graphite anodes deliver energy densities above 250 Wh/kg. Automotive OEMs in the Yangtze River Delta cluster source these through annual volume commitments with CATL and CALB to secure allocation priority during raw material tightness.
- Lead-acid:Flooded and valve-regulated designs utilizing lead dioxide cathodes and sponge lead anodes remain cost-competitive for starter battery replacement cycles. Demand concentrates in Shandong and Hebei aftermarket distribution networks serving commercial vehicle fleets under provincial emissions retrofit mandates.
- Nickel-cadmium:Pocket-plate and sintered electrode designs tolerate extreme temperature cycling for railway signaling and aviation ground support equipment.
- Nickel-metal Hydride:Rare earth hydride anode chemistry persists in hybrid vehicle auxiliary systems and cordless power tools where established supply chains resist lithium-ion conversion costs.
By volume, Lithium-ion leads. By growth pace, solid-state lithium-ion derivatives within this category are climbing the fastest.
End User:
Cost tier stratification separates premium automotive contracts from standardized industrial procurement, with energy storage emerging as a distinct margin pool requiring CEA interconnection compliance.
- Automotive:Traction battery demand from NEV platforms spans LFP and NMC chemistries with GB/T 31485 certification mandatory for MIIT subsidy eligibility. CATL and BYD anchor supply through dedicated Yangtze River Delta plant investments aligned with SAIC, GAC, and NIO assembly footprints.
- Energy Storage:Containerized LFP systems for utility-scale procurement under MEE dual carbon mandates require module-level fire suppression documentation and CEA grid connection approval. Provincial power grids in Jiangsu and Zhejiang are issuing mandatory storage procurement quotas.
- Consumer Electronics:Cylindrical and pouch cell formats for smartphones and laptops flow through established trading company channels with mature margin compression.
- Industrial:Forklift motive power and telecom backup systems source through regional distributors with less stringent certification requirements than automotive tiers.
Automotive commands the premium pricing tier. Energy Storage is gaining share fastest as provincial procurement mandates expand.
Application:
Application-specific performance thresholds create divergent supply chains, with electric vehicles requiring formation cycling infrastructure that portable device manufacturers need not maintain.
- Electric Vehicles:Prismatic and blade cell architectures demand giga-scale formation cycling lines and predictive aging models to meet extended warranty terms. BYD's vertical integration of blade cell production for standard-range models compresses cobalt demand while qualifying for simplified GB/T thermal abuse protocols.
- Portable Devices:High-rate cylindrical cells for power tools and consumer electronics utilize established coating and winding equipment with shorter qualification cycles than automotive applications.
- Uninterruptible Power Supply:Valve-regulated lead-acid dominates data center backup where cycle life requirements remain below deep-discharge traction standards.
- Power Tools:Brushless motor compatibility drives 18650 and 21700 cylindrical cell demand through professional tool rental channels.
Electric Vehicles absorbs the largest capital deployment. Portable Devices offers the shortest product development cycles.
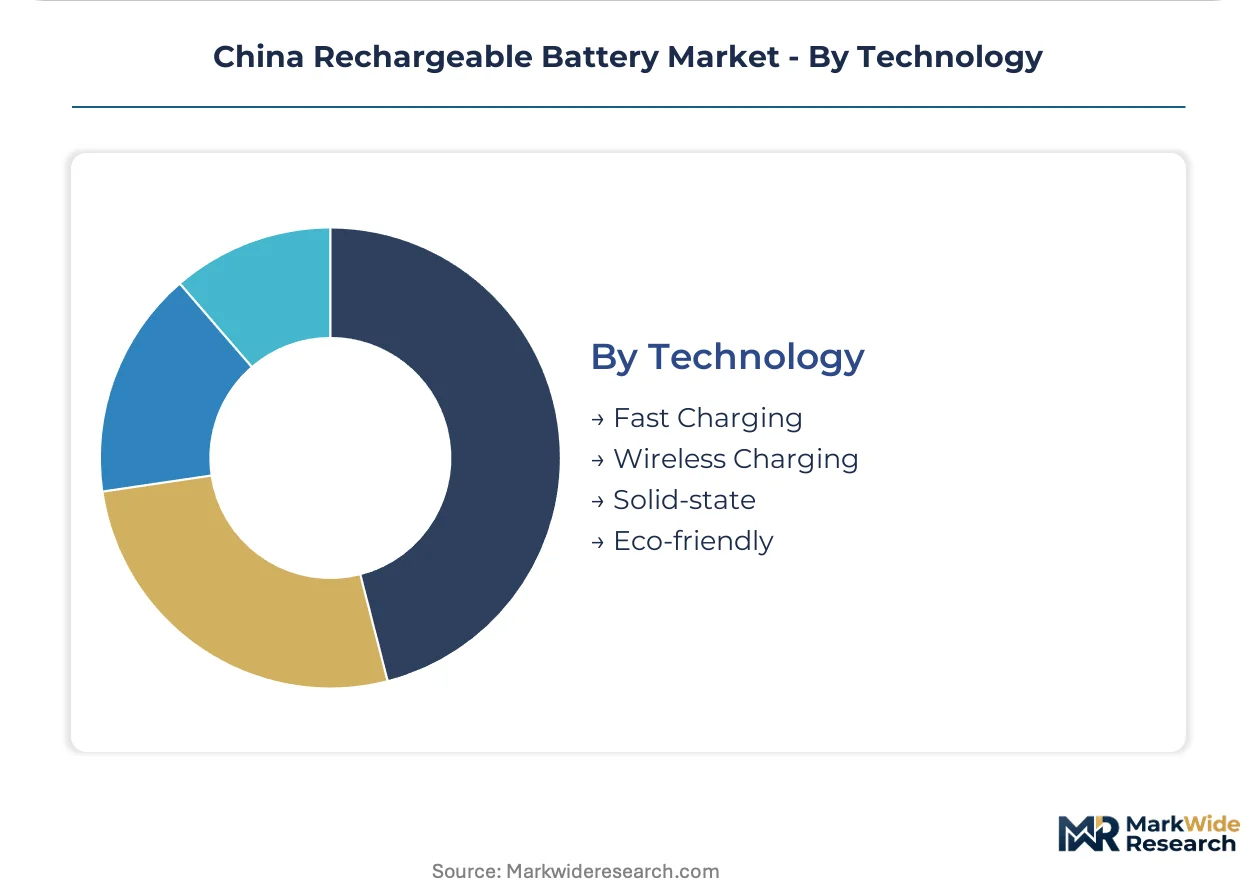
Technology:
Technology maturity curves separate near-term deployable solutions from R&D-stage architectures, with fast charging representing immediate commercial traction versus solid-state pilot lines.
- Fast Charging:Silicon-composite anode and high-voltage electrolyte formulations enable 10-80% state-of-charge cycles. CATL's 4C charging cells for premium automotive platforms are penetrating Guangdong province where vehicle assembly concentration supports dedicated cell plant investments.
- Solid-state:Sulfide-based electrolyte research at CAS institutes and Tsinghua University targets thermal runaway elimination through pilot production lines, though separator-electrolyte interface stability remains unresolved.
- Wireless Charging:Inductive pad systems for consumer electronics and autonomous logistics vehicles face efficiency penalties that limit adoption beyond convenience-focused applications.
- Eco-friendly:Sodium-ion chemistry commercialization by CATL and others targets two-wheeler and A00-class vehicle segments where energy density requirements relax and cost sensitivity dominates.
Fast Charging leads current revenue contribution. Solid-state R&D is expanding most quickly as CAS and Tsinghua programs advance toward pilot scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT subsidy eligibility and provincial dual carbon procurement mandates are redistributing manufacturing investment across China's sub-regional corridors, with cell plants migrating toward lower-cost central provinces while R&D concentration persists in coastal technology clusters.
Yangtze River Delta
Shanghai, Jiangsu, and Zhejiang provinces anchor automotive cell demand through SAIC, NIO, and Tesla Shanghai assembly footprints. GB/T 31485 certification requirements enforced by SAMR concentrate testing infrastructure in this corridor. CATL and CALB maintain dedicated giga-scale plants in Ningde and Changzhou to secure MIIT whitelist compliance for NEV subsidy programs.
Pearl River Delta
Guangdong province's vehicle assembly concentration in Guangzhou and Shenzhen attracts mid-tier producers seeking captive demand anchors. CEA interconnection rules for grid-tied storage systems are expanding procurement quotas across provincial power grids. BYD anchors cell production in Shenzhen through vertical integration with automotive and energy storage divisions.
Anhui Province
Hefei and surrounding industrial zones offer discounted land and power tariffs to cell manufacturers outside the saturated coastal corridor. Provincial government partnerships under Anhui's new energy vehicle industrial policy are accelerating LFP chemistry specialization. Gotion High-Tech leverages these incentives to expand formation cycling capacity for regional automotive contracts.
Sichuan-Chongqing
Domestic lithium brine extraction in Qinghai and Sichuan is reducing import dependency for cathode material producers. MEE oversight of dual carbon implementation is mandating grid-tied storage procurement across western provincial power grids. Local producers are negotiating long-term offtake agreements to bypass Chilean-Argentine supply volatility.
Shandong Peninsula
Spherical graphite processing capacity in Heilongjiang and Shandong creates geographic concentration for anode material supply. SAMR enforcement of GB standards is compressing lead-acid aftermarket distribution networks serving commercial vehicle fleets. Qingdao and Yantai industrial zones host separator film coating equipment dependent on Japanese and German extrusion line manufacturers.
China Rechargeable Battery Market Competitive Landscape
Player mix skews toward vertically integrated conglomerates with captive automotive demand and standalone cell specialists competing on chemistry certification. Market structure concentrates around three tiers: premium automotive contract holders with MIIT whitelist status, mid-tier industrial suppliers serving energy storage and consumer electronics, and regional assemblers dependent on trading company distribution. Strategic archetypes include chemistry specialists leveraging provincial licensing access, scale-driven producers with giga-plant formation cycling infrastructure, and diversified conglomerates with in-house vehicle demand anchors. Competitive moves center on backward integration into cathode materials and direct long-term procurement agreements displacing multi-tier supplier hierarchies.
Among the vertically integrated conglomerates, CATL (Contemporary Amperex Technology Co. Limited) and BYD Company occupy positions defined by captive demand anchors and upstream control over material supply chains. CATL represents the scale-driven archetype with giga-scale manufacturing footprints across multiple provincial corridors. BYD exemplifies the diversified conglomerate model with in-house vehicle demand anchoring cell production decisions. EVE Energy Co., Ltd. sits within the specialist tier, competing through chemistry certification and provincial government partnerships rather than vertical integration depth.
| Leading Market Players |
|---|
| CATL (Contemporary Amperex Technology Co. Limited) |
| BYD Company |
| EVE Energy Co., Ltd. |
| Gotion High-Tech |
| CALB |
| Ganfeng Lithium |
| Farasis Energy |
| Lishen Battery |
| Fujian Minhua Power Source Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Giga-scale formation cycling infrastructure concentrates among three manufacturers with MIIT whitelist status, compressing price floors for automotive-grade cells while elevating margins for certified suppliers serving provincial dual carbon procurement mandates. This scale asymmetry rewards CATL and BYD with cost advantages that mid-tier producers cannot replicate without provincial licensing partnerships.
Pricing Analysis
GB/T certification tier creates the primary spread between premium automotive contracts and industrial aftermarket sales. Contract-based long-term offtage agreements dominate automotive procurement, with volume scale and MIIT whitelist status as the key price differentiation drivers. Cost compression in standard-range LFP cells is intensifying because BYD's blade cell architecture eliminates cobalt content. Aftermarket distributors serving Shandong commercial vehicle fleets exhibit the highest price sensitivity, while Yangtze River Delta OEMs prioritize allocation security over unit cost.
Supply Chain Analysis
Chilean-Argentine lithium carbonate shipments through Shanghai port congestion create inbound logistics volatility for cathode material producers without Qinghai brine offtake agreements. China's spherical graphite processing in Heilongjiang and Shandong, plus South Korean separator film coating equipment, anchors geographic supply concentration. The supply chain rests on lithium brine extraction, cathode precursor chemicals, and Japanese extrusion line equipment. Single-source vulnerability from 18-24 month equipment lead times constrains domestic wet-process separator expansion. Distribution runs through direct OEM contracts displacing multi-tier trading company hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM consolidation around CATL and CALB long-term agreements has shifted buyer power toward vehicle assemblers, fragmenting price discovery transparency while securing allocation priority for whitelist-compliant cell producers.
For Market Incumbents: Fortify backward integration into cathode materials to bypass Chilean-Argentine lithium carbonate volatility. Expand formation cycling capacity in Anhui and Hubei provinces where discounted power tariffs offset Yangtze River Delta saturation. Sodium-ion chemistry R&D investment defends against cost-sensitive two-wheeler segment erosion. For New Entrants and Emerging Players: Anchor in industrial behind-the-meter ESS deployment for steel and chemical facilities under provincial dual-control energy intensity rules. Containerized LFP systems for Jiangsu and Zhejiang grid procurement quotas represent the most penetrable segment. Pursue provincial government partnerships in central China manufacturing zones as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors chemistry specialists with GB/T 31485 certification infrastructure over undifferentiated scale plays. Long-term viability hinges on solid-state pilot line execution and CEA interconnection compliance capability. Acquisition targets should demonstrate module-level fire suppression documentation for utility-scale storage. Monitor separator-electrolyte interface stability resolution as the inflection signal for solid-state commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Material Backward Integration | Captive lithium carbonate supply from Qinghai brine extraction reduces Argentine import dependency. |
| Provincial Manufacturing Expansion | Anhui and Hubei discounted power tariffs attract cell plants outside saturated coastal corridors. |
| Sodium-Ion Chemistry Commercialization | Prismatic cell production for two-wheeler segments bypasses constrained Class 1 nickel supply chains. |
| GB/T 31485 Certification Investment | Extended cycle life verification from 500 to 1,000 cycles qualifies for MIIT NEV subsidy programs. |
| Industrial ESS Partnership Development | Containerized systems for steel facilities under dual-control rules secure behind-the-meter demand anchors. |
Research Methodology
The analysis maps lithium-ion traction batteries, lead-acid starter batteries, and solid-state R&D pipelines, each validated through cell plant operations directors, automotive OEM procurement managers, and CEA grid interconnection officers. Primary interviews with cathode material procurement leads and separator film equipment suppliers combined with secondary validation from MIIT whitelist publications, SAMR GB standard revisions, and provincial dual carbon implementation notices. Bottom-up cell capacity modeling and top-down automotive production forecasts were triangulated against MEE energy storage procurement quota disclosures.
Consistency checks against utility-scale ESS deployment databases and NEV registration data validated volume and value outputs across the projection horizon. The analytical framework modeled chemistry type, end-use application, and provincial regulatory cluster as core segmentation dimensions. CAGRs were derived from production capacity buildout schedules and raw material offtake agreement trajectories. Forecast inputs included lithium carbonate spot price volatility bands and separator film coating equipment delivery schedules.
Material uncertainties — lithium brine extraction capacity constraints, GB/T certification timeline compression at CATARC, and sulfide-based electrolyte interface stability — sit outside the modeled envelope. Forecasts reflect assumptions about provincial licensing access and MIIT whitelist maintenance. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Home Inverter Battery Market
Batteries
Iron Salt Battery Market
Batteries
India Battery Cell Market
Batteries
Lead Acid Battery Market
Batteries
Asia Power Tool Batteries Market
Batteries
Automotive Starting Battery Market
Batteries
Aluminum-Air Battery Market
Batteries
Low Temperature Battery Market
Batteries
VRLA Batteries Market
Batteries
Iron-Chromium Flow Battery Market
Batteries
India Battery Market
Batteries
Lithium Battery Testing System Market
Batteries
Dry Cell Battery Market
Batteries
Zinc Ion Batteries Market
Batteries
Rechargeable Battery Market
Batteries
Global Industrial Lead Acid Battery Market