
 Nimh Battery Market | 2026-2036
Nimh Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Nimh Battery Market Analytics
UN 38.3 lithium battery transport certification is redrawing competitive boundaries for NiMH suppliers serving cross-border OEM contracts. Panasonic Holdings Corporation leverages its vertical integration from cathode materials to finished cells, sustaining cost advantages in cylindrical formats for power tool OEMs. Energizer Holdings Inc. dominates North American retail channels for consumer replacement packs, while Primearth EV Energy Co., Ltd. anchors Toyota's hybrid vehicle supply chain with prismatic cell production.
Nickel metal hydride batteries store energy through hydrogen absorption in a rare earth-based alloy anode, delivering nominal voltages of 1.2V with tolerance for high discharge rates across temperature extremes from minus twenty to plus sixty degrees Celsius. The cylindrical cell segment occupies the largest revenue share due to mature tooling and economies of scale in high-volume manufacturing. Portable Devices applications face margin compression as lithium-ion alternatives penetrate consumer electronics, whereas Energy Storage Systems represent an emerging outlet for repurposed automotive NiMH packs in stationary backup configurations.
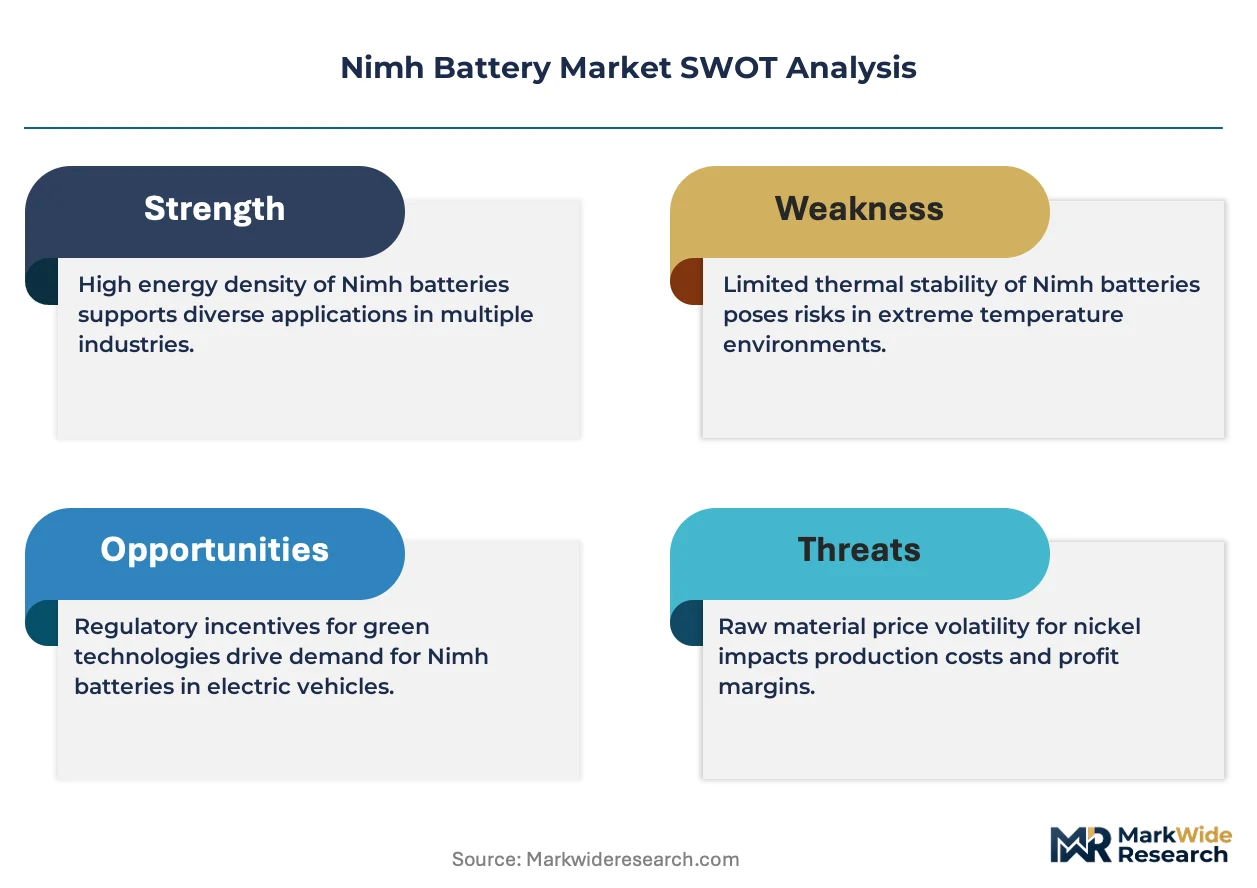
Japan's METI enforces JIS C 8712 safety standards for sealed rechargeable cells, while China's SAMR mandates GB/T certification for domestic battery sales, collectively shaping product design and testing burdens for multi-regional suppliers. The EU Battery Regulation imposes carbon footprint disclosure and recycled content thresholds that NiMH producers must address for European market access. Stakeholders should monitor chemistry-specific recycling infrastructure buildout and rare earth supply chain concentration as determinants of long-term cost competitiveness.
Market Dynamics
China's MIIT battery recycling mandates are forcing nickel recovery infrastructure buildout, while Japanese automakers expand NiMH procurement for hybrid drivetrains as a cost hedge against lithium-ion volatility. The market structure hinges on rare earth supply concentration and chemistry-specific circular economy compliance.
Growth Catalysts
- Japan's hybrid vehicle procurement:Toyota and Honda anchor demand through prismatic cell contracts for hybrid electric drivetrains, sustaining volume commitments despite lithium-ion alternatives.
- MIIT recycling mandates:China's Ministry of Industry and Information Technology tightens material recovery requirements for nickel-based chemistries, creating compliant recycling infrastructure demand.
- Rare earth processing co-location:East Asian production clusters integrate cell fabrication with lanthanide refining, reducing alloy anode input costs through geographic concentration.
Market Restraints
- Energy density ceiling:NiMH chemistry's theoretical capacity limits prevent penetration into battery electric vehicle powertrains where lithium-ion dominates.
- Nickel price volatility:London Metal Exchange nickel contract swings disrupt cathode material cost planning for cylindrical cell manufacturers.
- Lithium-ion substitution:LFP and NMC chemistries displace NiMH in consumer electronics and power tools through superior gravimetric performance.
Strategic Opportunities
- Second-life stationary storage:Repurposed automotive NiMH packs enter backup power configurations for telecom and industrial uninterruptible power supply installations.
- India BIS certification pathway:India's Bureau of Indian Standards creates compliant market entry for cylindrical formats in unorganized power tool and lighting segments.
- EU Battery Regulation tailwinds:Carbon footprint disclosure thresholds and recycled content mandates favor established NiMH producers with existing hydrometallurgical recovery networks.
Industry Challenges
- UN 38.3 certification timelines:Cross-border OEM contracts require lithium-equivalent transport safety documentation, extending qualification cycles for new cell formats.
- Rare earth supply concentration:Lanthanum and cerium alloy anode production depends on Chinese separation capacity, creating single-source vulnerability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nimh Battery Market |
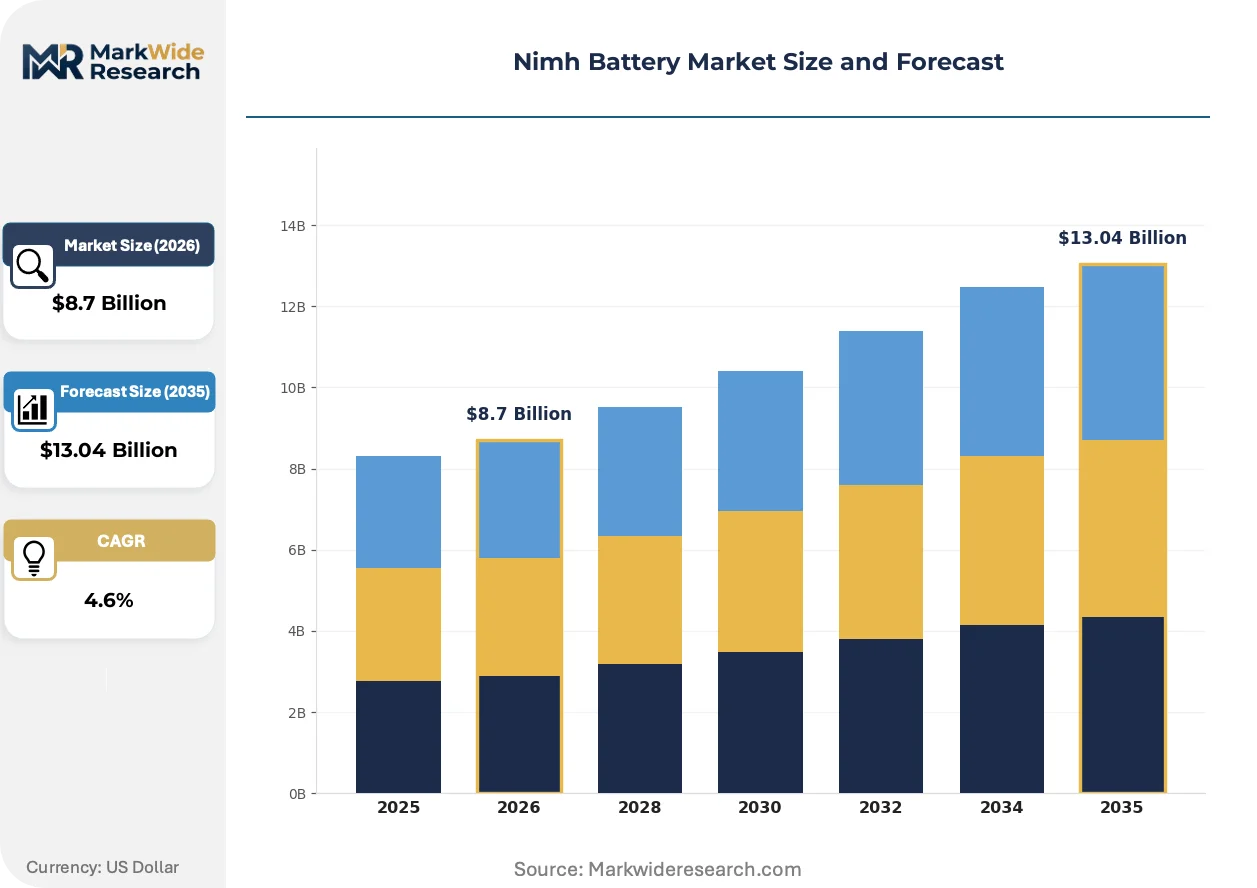
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Button Cell, Cylindrical Cell, Prismatic Cell, Pack End User: Consumer Electronics, Automotive, Industrial, Telecommunications Application: Portable Devices, Electric Vehicles, Energy Storage Systems, Power Tools Technology: Nickel Metal Hydride, Rechargeable, High Capacity, Fast Charge |
| Companies Covered | Panasonic Holdings Corporation, Energizer Holdings Inc., Primearth EV Energy Co., Ltd., FDK Corporation, Duracell Inc., GP Batteries International Limited, VARTA AG, GS Yuasa Corporation, Shenzhen Grepow Battery Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nimh Battery Market Evolving Landscape
Active materials research and regulatory disclosure requirements are reshaping competitive boundaries. Chemistry optimization, compliance architecture, and procurement model evolution define the current innovation frontier.
Low-cobalt AB5 alloy formulations are bifurcating the anode material landscape. Power tool OEMs in North America and Europe adopt these variants for improved cycle stability in high-drain applications. The technology is compressing cost differentials with entry-level lithium-ion packs in price-sensitive consumer segments.
EU Battery Regulation carbon footprint disclosure mandates are forcing supply chain visibility investments. Producers must document upstream emissions from nickel mining through cell assembly for European market access. Cylindrical formats face the steepest compliance burden due to fragmented supplier bases across multiple jurisdictions.
Long-term service contracts are displacing spot procurement in hybrid vehicle supply chains. Toyota and Honda negotiate decade-spanning cell supply agreements with fixed volume floors and price adjustment clauses. Japan anchors this shift, with similar structures emerging in South Korean industrial battery procurement.
Nimh Battery Market Segmentation
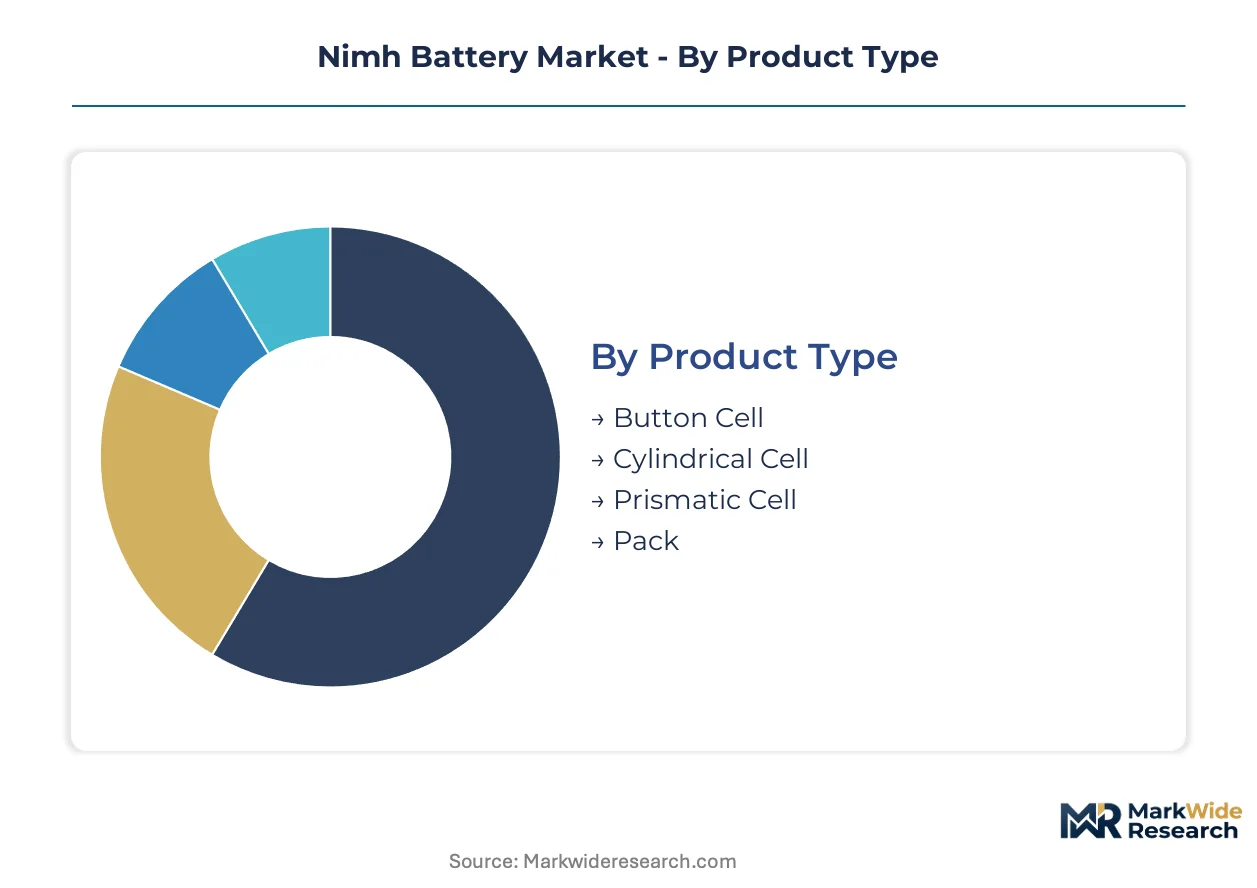
NiMH battery segmentation reveals distinct procurement patterns across cylindrical formats for power tools, prismatic cells for Toyota's hybrid drivetrains, and repurposed automotive packs entering stationary backup installations. Understanding these segment boundaries clarifies where chemistry-specific advantages persist against lithium-ion displacement.
Product Type:
Domestic production in Japan and China supplies cylindrical and prismatic formats for regional automotive contracts, while button cells and packs serve export-heavy consumer replacement channels across North America and Europe.
- Cylindrical Cell:Standardized 18650 and AA/AAA formats dominate high-volume manufacturing with mature tooling economics. Demand concentrates in North American and European power tool OEM procurement where Panasonic's captive cathode production sustains cost advantages.
- Prismatic Cell:Flat rectangular housings optimize volumetric efficiency for hybrid vehicle battery packs. Toyota and Honda anchor procurement through Primearth EV Energy's Japan-based production, with volume commitments spanning decade-long service contracts.
- Button Cell:Compact disc-shaped formats serve medical devices and small electronics requiring minimal footprint. Swiss and German industrial sensor manufacturers represent key export destinations.
- Pack:Pre-assembled multi-cell configurations integrate battery management circuitry for plug-and-play industrial applications. Warehouse equipment and material handling OEMs in the US Midwest drive replacement demand.
Cylindrical formats command the established base. The steepest expansion runs through prismatic cells tied to hybrid vehicle procurement.
End User:
Cost tier stratification separates premium automotive contracts with fixed-volume floors from price-sensitive consumer electronics exposed to lithium-ion substitution.
- Automotive:Hybrid electric drivetrains sustain the only growing NiMH demand within transportation, as Toyota's Prius and Honda's Insight platforms maintain chemistry-specific pack designs. Japanese METI safety standards and UN 38.3 transport certification create qualification barriers protecting incumbent suppliers.
- Industrial:Uninterruptible power supply and forklift applications value NiMH's temperature tolerance and abuse resistance over energy density. German and US manufacturing clusters specify cylindrical packs for factory-floor reliability.
- Consumer Electronics:Digital cameras and portable gaming devices represent residual demand as smartphones and laptops completed lithium-ion transition. Retail replacement channels concentrate in North American big-box and online marketplaces.
- Telecommunications:Base station backup power and rural network infrastructure specify NiMH for operational temperature range. India's Bharat Sanchar Nigam and tower companies drive procurement in price-sensitive emerging markets.
Industrial applications command the established base. The steepest expansion runs through automotive hybrid contracts.
Application:
Volume concentration in mature segments contrasts with emerging second-life outlets where repurposed automotive packs enter stationary configurations.
- Power Tools:Cordless drills, impact drivers, and lawn equipment sustain cylindrical cell demand through professional-grade durability requirements. Milwaukee, DeWalt, and Makita specify NiMH for contractor segments where runtime predictability outweighs weight penalties.
- Energy Storage Systems:Repurposed automotive NiMH packs enter telecom backup and industrial UPS installations at degraded capacity. China's State Grid and European distribution network operators pilot second-life configurations for cost-sensitive stationary applications.
- Portable Devices:Digital cameras, handheld GPS, and portable audio face accelerating lithium-ion substitution. Japanese consumer electronics OEMs have largely exited NiMH procurement.
- Electric Vehicles:Battery electric vehicle powertrains exclude NiMH due to energy density ceilings, limiting chemistry to hybrid assist applications where discharge rate tolerance matters more than range.
Power tools command the established base. The steepest expansion runs through energy storage systems.
Technology:
Supply concentration in East Asian rare earth processing determines cost competitiveness across alloy anode formulations and charging protocols.
- Nickel Metal Hydride:The baseline chemistry employs hydrogen-absorbing AB5 alloy anodes with lanthanum and cerium from Chinese separation capacity. Cell fabrication clusters in Japan's Osaka-Kobe corridor and China's Guangdong province.
- High Capacity:Advanced alloy formulations and electrode loading techniques extend specific energy toward theoretical limits. Japanese materials suppliers lead patent positions, licensing to Korean and Chinese cell manufacturers.
- Rechargeable:Standard sealed cell construction dominates consumer replacement markets with established JIS C 8712 and GB/T certification pathways. Retail shelf life and self-discharge rates determine channel economics.
- Fast Charge:Modified electrolyte compositions and thermal management enable one-hour recharge cycles for industrial fleet applications. Airport ground support equipment and automated guided vehicles specify these variants.
Standard rechargeable formats command the established base. The steepest expansion runs through high capacity variants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hybrid vehicle manufacturers and power tool OEMs drive procurement concentration across East Asian production clusters and North American retail channels. Japanese automakers sustain prismatic cell demand through decade-spanning supply contracts. Chinese rare earth processing capacity underpins alloy anode cost structures for cylindrical formats.
Japan
Toyota and Honda anchor prismatic cell demand through Primearth EV Energy's production commitments for hybrid drivetrains. METI enforces JIS C 8712 safety standards for sealed rechargeable cells, creating qualification barriers for new entrants. The Osaka-Kobe corridor hosts concentrated cell fabrication clusters integrated with rare earth alloy suppliers.
China
Guangdong province cell manufacturers serve domestic power tool OEMs and export-heavy consumer replacement channels. MIIT battery recycling mandates tighten material recovery requirements for nickel-based chemistries, forcing hydrometallurgical infrastructure buildout. Shenzhen and Dongguan concentrate cylindrical cell production alongside lanthanide separation capacity.
United States
Milwaukee, DeWalt, and Makita specify NiMH packs for professional-grade cordless equipment through distributor networks. EPA and OSHA regulations govern industrial battery handling in manufacturing facilities. The US Midwest warehouse equipment corridor drives replacement demand for pre-assembled multi-cell configurations.
Germany
Industrial UPS and forklift OEMs specify cylindrical formats for factory-floor reliability in Baden-Württemberg manufacturing clusters. ECHA REACH compliance and EU Battery Regulation carbon footprint disclosure requirements shape procurement specifications. Bavarian automotive suppliers pilot second-life automotive pack configurations for stationary backup.
India
Bharat Sanchar Nigam and tower companies drive telecommunications backup power procurement in price-sensitive rural network infrastructure. BIS certification creates compliant market entry pathways for cylindrical formats in unorganized power tool segments. Tamil Nadu and Karnataka industrial corridors concentrate assembly operations for export-oriented consumer packs.
Nimh Battery Market Competitive Landscape
Player mix skews toward vertically integrated Japanese conglomerates with captive cathode material production and rare earth alloy supply chains. The structure concentrates around three strategic archetypes: automotive-tier suppliers with decade-long service contracts, retail-channel dominators with North American shelf space control, and regional fabricators serving price-sensitive industrial segments. Competitive moves center on backward integration into rare earth processing and strategic partnerships for recycling infrastructure access.
Among Japan-based integrated producers, Panasonic Holdings Corporation and Primearth EV Energy Co., Ltd. exemplify the automotive-tier archetype through hybrid vehicle supply chain anchoring. Energizer Holdings Inc. occupies the retail-channel position for North American consumer replacement markets. Chinese fabricators including Shenzhen Grepow Battery Co., Ltd. represent the regional specialist tier serving industrial and export segments.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| Energizer Holdings Inc. |
| Primearth EV Energy Co., Ltd. |
| FDK Corporation |
| Duracell Inc. |
| GP Batteries International Limited |
| VARTA AG |
| GS Yuasa Corporation |
| Shenzhen Grepow Battery Co., Ltd. |
| Others |
Value Network & Pricing Analysis
High-volume cylindrical cell tooling in China's Guangdong province and Japan's Osaka-Kobe corridor establishes minimum efficient scale thresholds that compress price floors for entry-level formats while elevating margins for prismatic hybrid vehicle contracts. This scale asymmetry concentrates supply-side power among integrated producers with captive cathode production, forcing smaller fabricators into commodity consumer replacement segments where London Metal Exchange nickel volatility erodes pricing control.
Pricing Analysis
Cost-plus contracts with London Metal Exchange nickel indexation dominate cathode material procurement, creating direct pass-through exposure for cylindrical cell manufacturers serving power tool OEMs. Price differentiation separates UN 38.3-certified automotive-tier cells from uncertified consumer replacement packs, with Toyota and Honda's decade-long service contracts exhibiting lowest price sensitivity due to switching costs embedded in pack architecture. Cost compression in consumer electronics tiers intensifies because lithium-ion substitution has eliminated premium positioning, while industrial UPS buyers demonstrate moderate sensitivity valuing temperature tolerance over marginal cost savings.
Supply Chain Analysis
Strategic stockpiling of lanthanum and cerium separates Japanese hybrid cell producers from just-in-time cylindrical fabricators exposed to Chinese rare earth separation volatility. Supply concentrates in Japan, China, and South Korea, with alloy anode production drawing from Chinese lanthanide separation capacity and cathode materials sourcing from Korean nickel refining. Single-source vulnerability in rare earth processing creates structural risk, as Japanese automotive cell production rests on Chinese separation infrastructure. Distribution runs through captive automotive supply chains for prismatic formats and distributor networks for North American power tool replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat structure where METI JIS C 8712 certification and UN 38.3 transport documentation create regulatory entrenchment protecting incumbent hybrid vehicle suppliers from displacement. Toyota and Honda's pack architecture switching costs reinforce this moat.
For Market Incumbents: Secure backward integration into rare earth alloy processing to reduce Chinese separation exposure, and extend service contract durations with price-adjustment clauses indexed to nickel volatility. Lithium-ion substitution in power tools threatens cylindrical margins, making captive cathode production the priority lever for cost defense. For New Entrants and Emerging Players: Second-life stationary storage configuration services represent an underserved layer where incumbents lack dedicated engineering teams for degraded-capacity pack repurposing. India's BIS-certified unorganized power tool segment offers the most penetrable geography, with cylindrical format assembly partnerships providing lowest-capital entry. Target telecom tower operators with pay-per-backup-hour financing models. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automotive-tier cell suppliers with decade-spanning Toyota and Honda contracts, supporting premium valuation multiples against spot-market-exposed consumer replacement players. Acquisition focus should center on Japanese producers with METI certification and existing rare earth alloy supply relationships. Revision becomes warranted when Chinese rare earth export licensing crosses threshold tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Alloy Backward Integration | Captive lanthanum-cerium supply reduces Chinese separation dependency for Japanese automotive cell producers. |
| Second-Life Storage Service Launch | Degraded hybrid pack configuration for telecom backup opens margin accretive outlet beyond automotive retirement. |
| India BIS Certification Investment | Compliant market entry enables cylindrical cell penetration in price-sensitive unorganized power tool segments. |
| Long-Term Nickel Supply Agreement | Fixed-price cathode material contracts hedge London Metal Exchange volatility for cylindrical format margins. |
| Hydrometallurgical Recycling Partnership | MIIT-compliant nickel recovery infrastructure secures Chinese market access under tightening circular economy mandates. |
Research Methodology
Operator-level perspectives from cell fabrication plant managers, Toyota and Honda procurement officers, power tool OEM sourcing leads, and rare earth separation facility engineers anchored the qualitative base for this analysis. Primary interview findings triangulated against secondary sources including METI regulatory filings, MIIT circular economy directives, London Metal Exchange nickel contract data, and UN 38.3 transport certification documentation. Bottom-up cell shipment estimates by format and end-use reconciled with top-down hybrid vehicle production forecasts.
Sensitivity analysis tested forecast robustness across nickel price scenarios, rare earth export restriction cases, and lithium-ion substitution acceleration assumptions across the analysis window. Segmentation modeling incorporated product type, end-user industry, application, and technology tier dimensions. CAGRs derived from volume trajectory analysis calibrated to automotive contract commitments and industrial replacement cycle patterns, with nickel alloy input cost curves and certification timeline assumptions as key inputs.
Forecasts assume regulatory continuity in Japanese METI safety standards, Chinese MIIT recycling mandates, and EU Battery Regulation carbon disclosure regimes; material policy shifts would require re-modeling. Revision becomes warranted when Chinese rare earth separation capacity utilization crosses thresholds affecting alloy anode input availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Middle East and Africa SLI Battery Market
Batteries
High Voltage Battery Market
Batteries
Middle East and Africa Solar and Motorcycle Battery Market
Batteries
Lithium Pouch Cell Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
Asia-Pacific Primary Battery Market
Batteries
Rechargeable Coin Cell Market
Batteries
GCC Rechargeable Battery Market
Batteries
Europe Consumer Battery Market
Batteries
Printed Batteries Market
Batteries
Redox Flow Battery Market
Batteries
Low Temperature Battery Market
Batteries
Wide Temperature Battery Market
Batteries
Solid-State Car Battery Market
Batteries
Heavy-Duty Truck Megapack Battery Systems Market
Batteries
Inverter Battery Market