
 Smart Battery Charger Market | 2026-2036
Smart Battery Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Battery Charger Market Analysis
Buyer concentration in the smart battery charger space is broadening as automotive OEMs and industrial fleet operators diversify supplier rosters beyond legacy vendors. Panasonic leverages its vertical integration into battery cell manufacturing to anchor premium charger development for electric vehicle platforms. EnerSys competes through specialized industrial charger lines serving material handling and telecommunications backup power. Delta-Q Technologies sustains technology leadership in lithium-ion charging algorithms for electric mobility applications.
A smart battery charger is an electronically controlled device that applies adaptive voltage and current profiles based on battery chemistry, state of charge, and temperature feedback to optimize charging cycles and extend cell longevity. These systems typically incorporate microprocessor-based management, multi-stage charging protocols, and communication interfaces such as CAN bus or Bluetooth for real-time monitoring and diagnostics. Fast chargers command the highest margin pools in the product type dimension due to thermal management complexity and semiconductor content, while solar chargers represent the fastest-expanding category as off-grid renewable installations proliferate. Lithium-ion technology dominates charger design roadmaps, though lead acid retains substantial volume in industrial backup and automotive starter applications where replacement cycles remain frequent.
The EU Battery Directive and CE marking requirements shape product standards for chargers sold across European member states, mandating efficiency benchmarks and recyclability disclosures. In the United States, the Department of Energy enforces minimum efficiency standards under EPCA while California's CEC regulations impose supplemental standby power limits. China's GB standards and MIIT circular economy directives govern domestic charger certification and materials recovery protocols. Stakeholders must monitor divergence between regional efficiency test methodologies and emerging interoperability mandates for vehicle-to-grid charging interfaces.
Market Dynamics
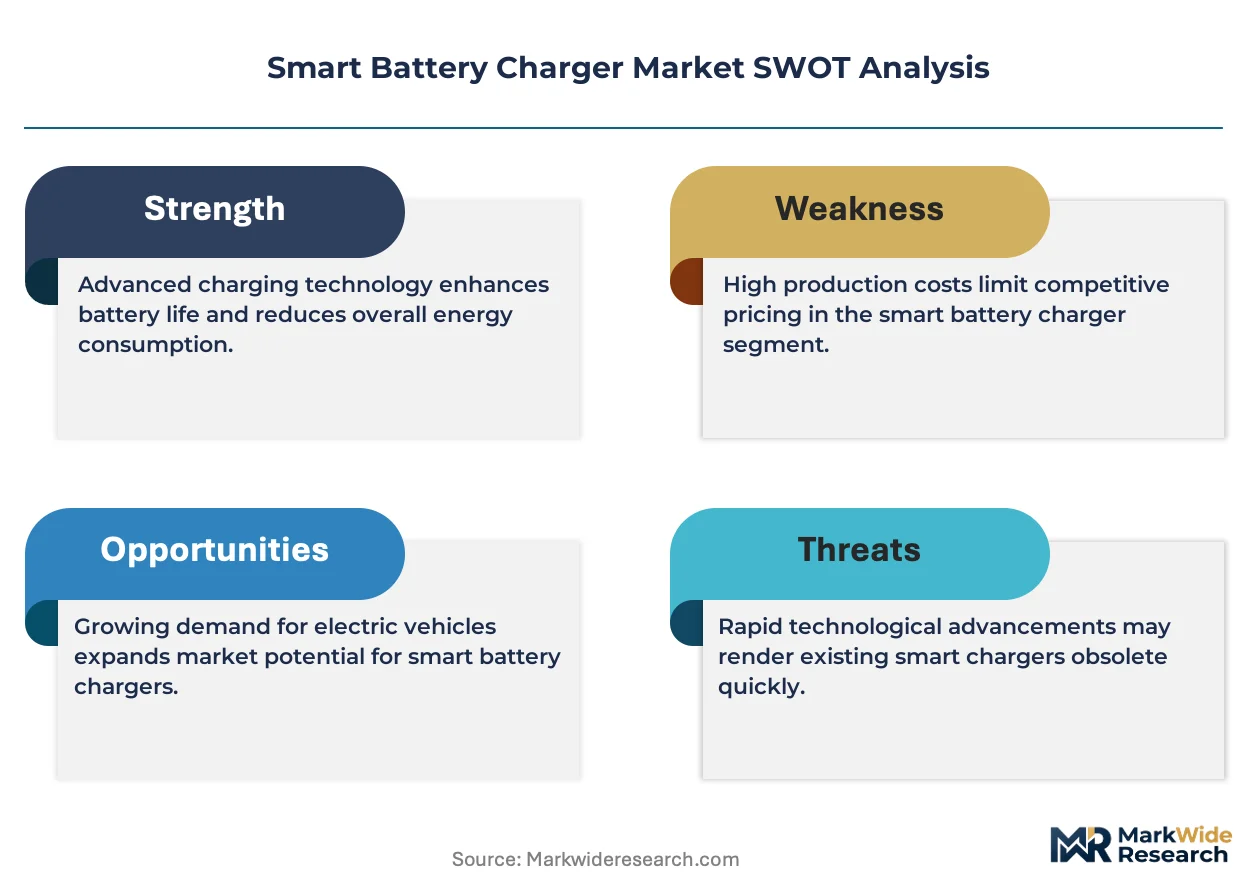
The EU F-Gas Regulation and Battery Directive are compressing design cycles for charging equipment manufacturers while forcing rapid semiconductor upgrades to meet efficiency mandates.
Growth Catalysts
- Electric mobility fleets:Commercial vehicle operators in Germany are mandating intelligent charging infrastructure to optimize battery lifecycle costs and reduce downtime.
- MIIT circular economy directives:China's domestic manufacturing incentives are accelerating localized production of high-efficiency chargers with materials recovery protocols.
- Lithium-ion algorithm advancement:Adaptive charging protocols are extending cell longevity in material handling and telecommunications backup applications.
Market Restraints
- Semiconductor supply concentration:Power management IC sourcing remains concentrated among Taiwan-based foundries, creating input volatility for charger OEMs.
- CE marking complexity:Divergent efficiency test methodologies across EU member states are extending product certification timelines.
- Lead acid substitution ceiling:Industrial starter and backup power applications retain frequent replacement cycles that limit lithium-ion charger penetration.
Strategic Opportunities
- Vehicle-to-grid interoperability:California's CEC regulations are mandating bidirectional charging standards that create white space for interface technology providers.
- Solar off-grid installations:Renewable energy developers in Australia are deploying smart chargers with integrated MPPT controllers for remote telecommunications infrastructure.
- Telematics convergence:Bluetooth and CAN bus integration with fleet management platforms is opening subscription revenue models for charging diagnostics.
Industry Challenges
- Thermal engineering talent scarcity:Fast charger development requires specialized expertise in liquid cooling design and power density optimization that outpaces workforce supply.
- Legacy system integration:Industrial battery rooms with mixed chemistries face firmware complexity when retrofitting microprocessor-based management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Battery Charger Market |
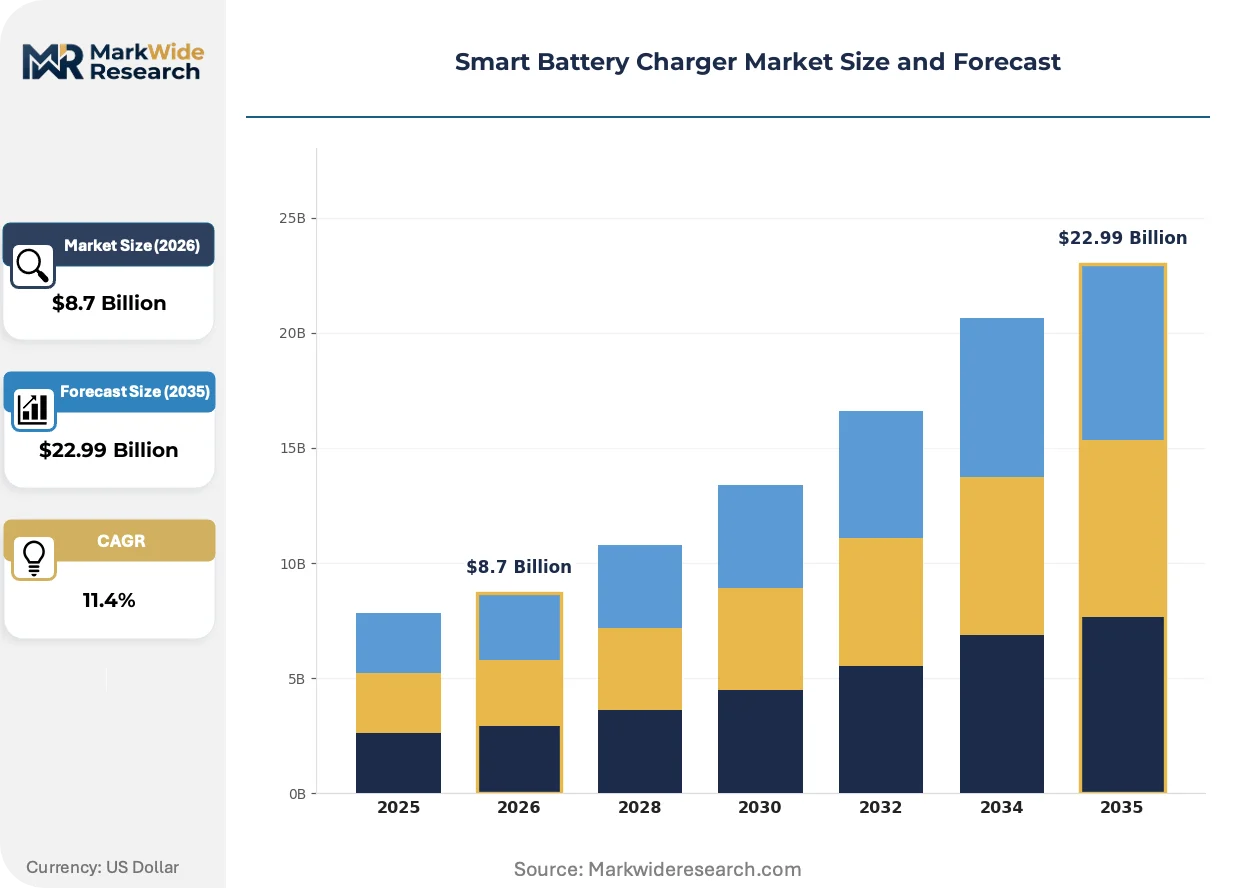
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Chargers, Fast Chargers, Solar Chargers, Multi-Channel Chargers Technology: Lead Acid, Lithium-Ion, Nickel Metal Hydride, Constant Current Application: Automotive, Consumer Electronics, Industrial Equipment, Renewable Energy End User: Retail Consumers, Automotive OEMs, Industrial Users, Service Providers |
| Companies Covered | Accutronics Ltd, Delta-Q Technologies, Exide Technologies, Panasonic, CTEK Sweden AB, EnerSys, NOCO, Schumacher Electric Corp, Anker Innovations Technology Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Battery Charger Market Emerging Trajectories
Silicon carbide semiconductors and adaptive charging algorithms are compressing power conversion losses while enabling new form factors for mobile and stationary applications.
Gallium nitride power stages are decentralizing thermal management architectures in fast charger designs by reducing switching losses and enabling higher frequency operation. Electric vehicle fleet operators are adopting GaN-based units for depot installations to minimize cooling infrastructure. This semiconductor transition is decentralizing manufacturing footprints by reducing heat sink mass and enabling compact wall-mounted configurations.
The EU Battery Directive's recyclability disclosure mandates are forcing redesign of enclosure materials and connector assemblies for European market entry. Manufacturers must now document end-of-life disassembly procedures and rare earth recovery pathways. Charger lines destined for Germany and France are prioritizing modular architectures that simplify component separation.
Telematics-enabled predictive maintenance contracts are displacing traditional hardware-only sales in material handling and telecommunications verticals. Hyster-Yale and Crown Equipment are bundling charging analytics with fleet management subscriptions. This service unbundling is most advanced in the United States where EPCA efficiency standards have already commoditized baseline hardware margins.
Smart Battery Charger Market Segmentation
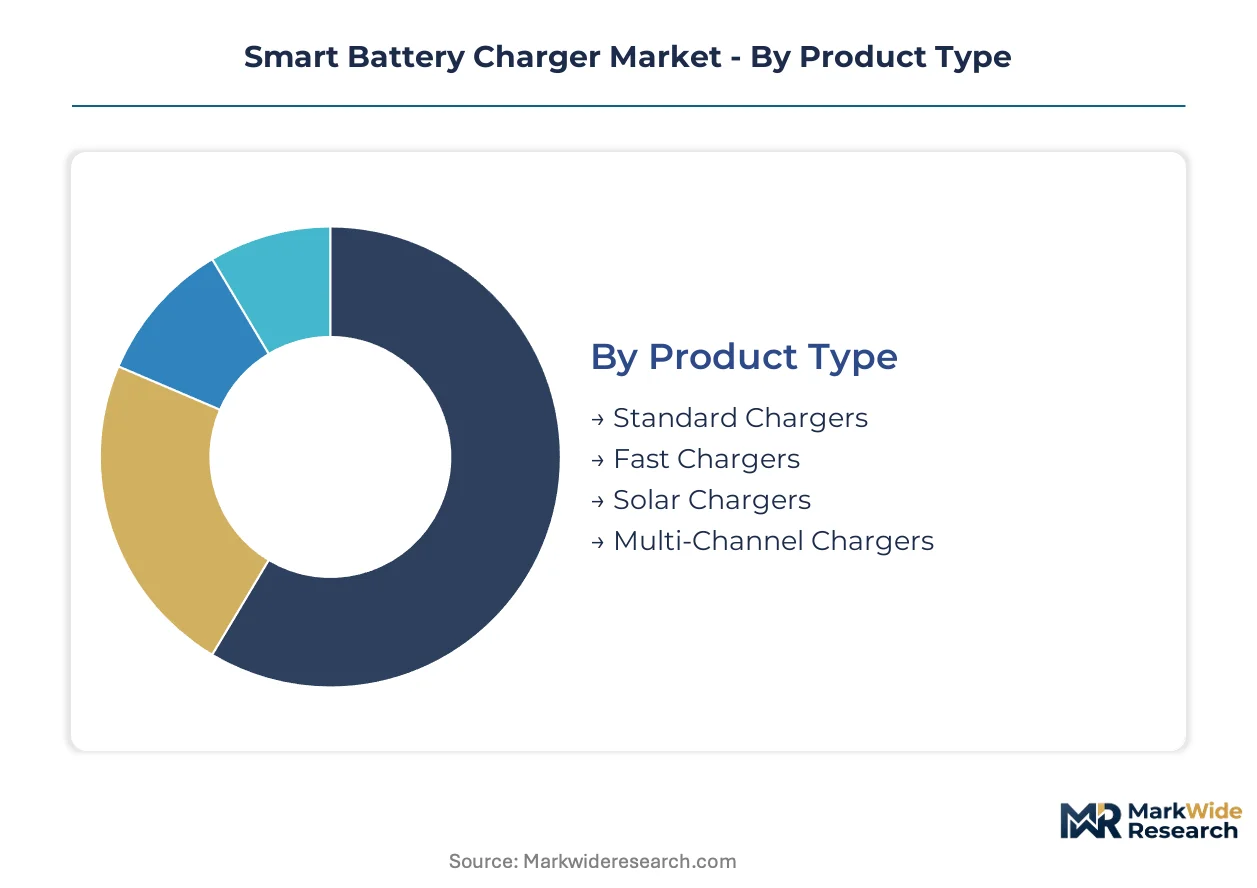
Segmentation in the smart battery charger market reveals distinct margin profiles and supply chain configurations across product architectures. Charger OEMs configure production lines differently for each category, with semiconductor sourcing strategies and thermal engineering talent allocation varying significantly by segment.
Product Type:
Supply concentration in fast chargers centers on Taiwan-based foundries for GaN power stages, while solar charger assembly disperses across Southeast Asian contract manufacturers.
- Fast Chargers:These systems deploy liquid cooling architectures and silicon carbide semiconductors to manage thermal loads above 50kW. Demand concentrates in Germany and California depot installations for electric bus and delivery van fleets where downtime minimization justifies premium hardware costs.
- Solar Chargers:Integrated MPPT controllers and bidirectional power conversion enable off-grid renewable installations. Australian telecommunications infrastructure developers represent the most active procurement segment as remote tower electrification accelerates.
- Standard Chargers:Microprocessor-based multi-stage protocols serve residential and light commercial applications with moderate power requirements.
- Multi-Channel Chargers:Parallel charging architectures support industrial battery rooms with mixed cell configurations.
Today's leader: Fast Chargers. Tomorrow's challenger: Solar Chargers.
Technology:
Cost tier differentiation separates lithium-ion algorithm development from legacy lead acid hardware margins.
- Lithium-Ion:Adaptive voltage profiling and real-time impedance tracking extend cell cycle life through machine learning-enhanced charge termination. Material handling fleets in the United States and Germany are mandating these systems to optimize total cost of ownership calculations.
- Lead Acid:Three-stage constant current-voltage-float protocols dominate automotive starter and industrial backup applications. China's domestic manufacturing base sustains volume production for price-sensitive replacement markets.
- Nickel Metal Hydride:Legacy traction battery support persists in hybrid vehicle service applications and specific industrial niches.
- Constant Current:Simplified architectures serve low-cost consumer electronics and emergency lighting systems with minimal monitoring requirements.
Volume concentrates in Lead Acid. Margin expansion concentrates in Lithium-Ion.
Application:
Customer type segmentation aligns procurement sophistication with technical specification complexity.
- Automotive:Vehicle-to-grid interoperability requirements and CAN bus integration dominate OEM procurement specifications. California's CEC bidirectional charging mandates are reshaping supplier qualification criteria.
- Industrial Equipment:Telematics-enabled predictive maintenance contracts are displacing hardware-only sales in material handling verticals. Hyster-Yale and Crown Equipment bundle charging analytics with fleet management subscriptions.
- Consumer Electronics:Compact form factors and USB-C power delivery standards drive commodity pricing dynamics.
- Renewable Energy:Grid-tie inverters with integrated charge control serve residential solar-plus-storage installations.
Maturity favors Industrial Equipment. Steepest expansion trajectory favors Automotive.
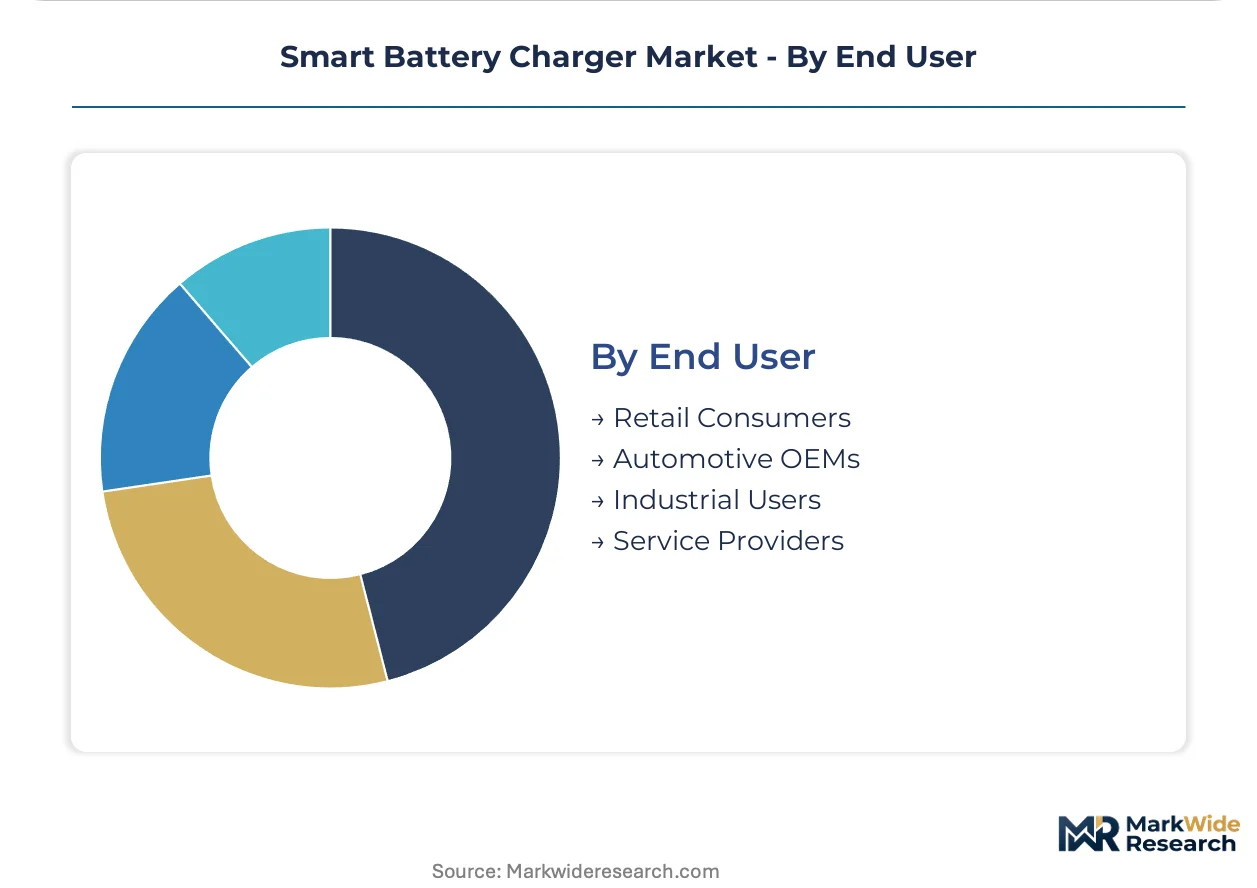
End User:
Geography shapes procurement patterns as regional efficiency regulations and domestic manufacturing incentives reconfigure supplier access.
- Automotive OEMs:Vertical integration strategies at Panasonic and BYD are capturing captive charger supply for electric vehicle platforms. These manufacturers specify proprietary communication protocols that lock out third-party alternatives.
- Industrial Users:Telecommunications backup power and material handling fleets in Germany prioritize CE-marked efficiency compliance and modular serviceability.
- Service Providers:Independent repair networks and battery service specialists source multi-chemistry universal chargers to reduce inventory complexity.
- Retail Consumers:E-commerce channel concentration in the United States and China drives price transparency and brand fragmentation.
Backward integration dominates Automotive OEMs. Channel expansion dominates Retail Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT circular economy directives are accelerating domestic charger production faster than Germany's EU F-Gas Regulation compliance timelines are reshaping European equipment procurement.
United States
Commercial vehicle fleet operators in California are mandating bidirectional charging infrastructure under CEC regulations to optimize battery lifecycle costs. The Department of Energy enforces EPCA minimum efficiency standards while supplemental standby power limits apply in California. Detroit-area automotive OEMs are integrating CAN bus communication protocols into captive charger development for electric vehicle platforms.
Germany
Industrial material handling fleets prioritize CE-marked efficiency compliance and modular serviceability for battery room retrofits. The EU Battery Directive and F-Gas Regulation mandate recyclability disclosures and efficiency benchmarks for charging equipment. Stuttgart and Munich manufacturing clusters are scaling domestic battery recycling infrastructure alongside charger production lines.
China
Domestic manufacturing incentives under MIIT directives are localizing high-efficiency charger production with materials recovery protocols. GB standards and circular economy regulations govern certification and rare earth recovery pathways. Shenzhen and Shanghai industrial zones are concentrating lithium-ion algorithm development for electric mobility applications.
Japan
Hybrid vehicle service networks sustain demand for legacy chemistry charger support alongside lithium-ion advancement. METI efficiency guidelines and JIS standards shape domestic product certification requirements. Nagoya and Osaka manufacturing bases are specializing in compact form factor designs for consumer electronics and industrial backup power.
Australia
Remote telecommunications infrastructure developers are deploying solar chargers with integrated MPPT controllers for off-grid tower electrification. The country's national energy regulator oversees grid interconnection standards for renewable-plus-storage installations. Western Australia and Queensland mining regions are procuring ruggedized charging systems for heavy equipment battery maintenance.
Smart Battery Charger Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered technology segments. The vendor base organizes around three strategic archetypes: battery cell manufacturers with captive charger supply, industrial power specialists serving material handling verticals, and consumer electronics brands driving commoditized volume. M&A activity concentrates on semiconductor and thermal management capability acquisition, while strategic partnerships target vehicle-to-grid interoperability certification.
Among battery-integrated conglomerates, Panasonic exemplifies backward integration into charger development for electric vehicle platforms. EnerSys occupies a position within the industrial power specialist archetype, serving material handling and telecommunications backup applications. Delta-Q Technologies represents the pure-play mobility charging segment, with algorithm specialization for lithium-ion applications.
| Leading Market Players |
|---|
| Accutronics Ltd |
| Delta-Q Technologies |
| Exide Technologies |
| Panasonic |
| CTEK Sweden AB |
| EnerSys |
| NOCO |
| Schumacher Electric Corp |
| Anker Innovations Technology Co., Ltd |
| Others |
Supply Flow & Price Mechanics
Silicon carbide wafer price indices cascade through Taiwan-based foundry contracts into three-tier pricing structure across premium, standard, and economy levels for smart battery charger OEMs. German fleet operators absorb premium fast-charger costs while Chinese manufacturers compress standard-tier margins through localized GaN sourcing.
Pricing Analysis
Capacity additions in China's Shenzhen industrial zone are reshaping price floors for standard-tier chargers serving consumer electronics and light commercial applications. Pricing stratifies across premium, standard, and economy tiers based on thermal management complexity and CE certification grade. Cost compression in the economy tier is intensifying because Southeast Asian contract manufacturers are scaling MPPT controller assembly for solar charger exports. Industrial fleet operators in Germany demonstrate lowest price sensitivity due to lifecycle cost optimization mandates, while retail consumers in the United States drive commodity pricing dynamics through e-commerce channel transparency.
Supply Chain Analysis
MIIT circular economy directives and California's CEC domestic-content preferences are reshaping sourcing footprints for power management ICs and rare earth magnet assemblies. Semiconductor fabrication draws from Taiwan, South Korea, and the United States for GaN power stages and silicon carbide substrates. Lithium-ion cell production rests on cathode precursor supply from China, electrolyte formulation from Japan, and separator membrane technology from South Korea. Single-source vulnerability concentrates in Taiwan-based foundry capacity for high-frequency power conversion chips. Distribution runs through captive supply agreements for automotive OEMs, industrial distributor networks for material handling fleets, and direct e-commerce for retail consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart battery charger market functions as a stable compounder anchored by electric vehicle fleet electrification mandates across Germany, China, and California that sustain procurement velocity through regulatory compliance cycles.
For Market Incumbents: Deploy thermal engineering talent acquisition as the primary defensive lever against fast-charger development bottlenecks. Incumbents should consolidate algorithm IP for lithium-ion adaptive charging to preempt emerging pure-play mobility specialists, while expanding modular service architectures that simplify EU Battery Directive recyclability compliance for German industrial customers. For New Entrants and Emerging Players: Enter via solar charger integration for Australian telecommunications infrastructure, where remote tower electrification demand outpaces incumbent supply capacity. White-space targets include bidirectional vehicle-to-grid interface technology for California CEC compliance and predictive maintenance SaaS bundling for United States material handling fleets. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor-thermal management capability hybrids that can compress power conversion losses for next-generation fast chargers. Acquisition targets should demonstrate 5-10 year viability through GaN power stage design IP and California CEC certification progress. The signal to watch is MIIT domestic-content quota enforcement accelerating localization timelines for foreign charger OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Power Stage Integration | Reduces switching losses for California depot fast-charger deployments requiring compact wall-mounted configurations. |
| Vehicle-to-Grid Certification | Unlocks bidirectional charging revenue streams under CEC regulations reshaping automotive OEM procurement criteria. |
| Thermal Management Talent Acquisition | Addresses liquid cooling design scarcity constraining fast-charger development timelines for German electric bus fleets. |
| Modular Enclosure Redesign | Enables EU Battery Directive recyclability compliance through simplified component separation for France and Germany markets. |
| Predictive Maintenance SaaS Launch | Captures subscription revenue from Hyster-Yale and Crown Equipment fleet management platform integrations. |
Methodological Framework
Multiple input streams — primary interviews with charger OEM procurement directors, thermal engineering leads, and fleet management platform executives; secondary validation through SEC filings, MIIT circular economy directive texts, and CEC regulatory dockets; plus customs trade data for semiconductor import flows — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations encompassed automotive Tier 1 supplier procurement teams, industrial battery room maintenance directors, renewable energy EPC contractors, and telecommunications infrastructure developers.
Historical shipment data was cross-referenced against expert panel inputs to construct projection frameworks across the analysis window. Segmentation dimensions modeled include product architecture (fast, solar, standard, multi-channel), battery chemistry protocol (lithium-ion, lead acid, nickel metal hydride), and end-use application (automotive, industrial equipment, consumer electronics, renewable energy). CAGRs were derived from curve-fitting approaches applied to technology adoption S-cycles and regulatory compliance deadline clustering.
Inputs from GB standards certification databases and EU F-Gas Regulation implementation guidance were available through the study window; gaps in real-time foundry capacity utilization data introduce uncertainty bands around semiconductor cost assumptions. Forecasts reflect documented assumptions regarding MIIT localization incentive intensity and California CEC bidirectional mandate enforcement timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Semi-Solid Flow Battery Market
Batteries
Dry Cell Battery Market
Batteries
PERC Battery Market
Batteries
Lithium-Fluorinated Graphite Batteries Market
Batteries
Nickel Cadmium Battery Market
Batteries
Advanced Batteries Market
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market
Batteries
Two Wheeler Lead Acid Batteries Market
Batteries
Iron Salt Battery Market
Batteries
South Korea Rechargeable Battery Market
Batteries
Global Industrial Battery Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Portable Battery Pack Market
Batteries
East Asia Battery Market
Batteries
Li-Ion Pouch Battery Market
Batteries
18650 And 21700 Battery Market