
 Italy Rechargeable Battery Market | 2026-2036
Italy Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Rechargeable Battery Market Insights
Automotive-grade cell certification is unwinding legacy cost structures across the Italian supply base. FIAMM SpA leverages its historic industrial battery expertise to anchor utility-scale storage contracts in the Po Valley. LG Energy Solution competes through high-nickel cathode specialization aimed at premium electric vehicle platforms. Enel Green Power extends its vertical reach into grid-tied battery installations through controlled development pipelines.
Italy rechargeable batteries are electrochemical storage devices with rated capacities from 2 Ah to 100+ kWh, engineered for repeated charge-discharge cycles exceeding 500–8,000 iterations depending on chemistry. These systems buffer intermittent renewable generation and propel electrified transport across Mediterranean climate zones. Lithium-ion chemistry dominates current procurement volumes due to energy density advantages in automotive and grid storage deployments. Lead acid retains residual share in backup power applications where capital cost sensitivity outweighs cycle-life requirements. Electric mobility applications within the technology dimension are absorbing the fastest capacity expansion as domestic bus and two-wheeler electrification targets tighten.
CE marking under the EU Battery Regulation shapes product compliance obligations for all manufacturers distributing within Italy. The national fire corps and civil protection standards enforce installation protocols for stationary energy storage systems above threshold capacities. Italy's transposition of EU Green Deal industrial policy channels state aid toward gigafactory development in Piedmont and Sicily. Stakeholders must monitor how upcoming delegated acts on recycled content mandates reshape feedstock sourcing economics for domestic cell producers.
Market Dynamics
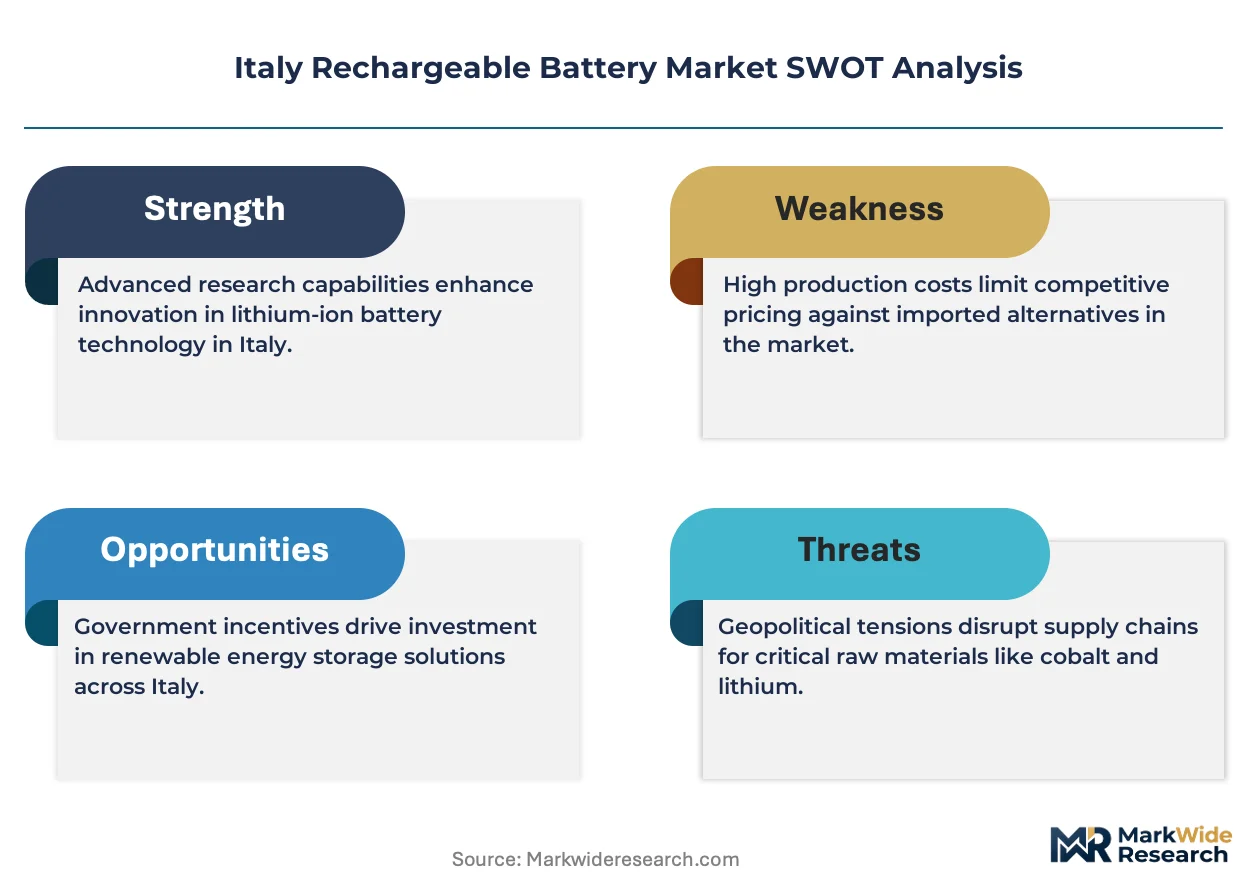
Italy's rechargeable battery sector faces a structural squeeze between EU Battery Regulation compliance deadlines and the absence of domestic cathode active material production, forcing assemblers to absorb certification costs while competing with imported cells from Poland and Hungary.
Growth Catalysts
- EU Green Deal state aid:Italy's National Recovery and Resilience Plan channels capital toward gigafactory development in Piedmont and Sicily, reducing import dependency for automotive OEMs.
- Electric bus procurement mandates:Municipal fleets in Milan and Turin now specify lithium-ion traction batteries above 100 kWh, creating guaranteed offtake for certified cell suppliers.
- Grid-scale storage auctions:Enel Green Power's controlled development pipelines for utility-scale installations in the Po Valley lock in multi-year supply contracts for domestic integrators.
Market Restraints
- Cathode precursor import concentration:Ninety percent of nickel sulfate and lithium hydroxide feedstock arrives through Rotterdam, exposing Italian cell plants to EU-wide port congestion and Dutch transshipment bottlenecks.
- CE marking compliance friction:Delegated acts on recycled content mandates under the EU Battery Regulation remain unpublished, freezing long-term feedstock sourcing decisions for domestic producers.
- Lead acid residual substitution:Backup power applications in telecommunications and healthcare retain lead acid systems where capital cost sensitivity outweighs cycle-life requirements, capping lithium-ion penetration in price-driven segments.
Strategic Opportunities
- Sicily renewable buffering:Island grid instability and high solar irradiance create demand for stationary storage installations that domestic assemblers can serve without mainland logistics costs.
- Second-life automotive packs:Retired electric bus batteries from Turin's GTT fleet offer 70-80 percent residual capacity for industrial forklift and stationary applications, unlocking circular revenue streams.
- Two-wheeler electrification subsidies:Regional incentives in Lombardy and Veneto for electric motorcycle adoption accelerate demand for compact lithium-ion formats below 5 kWh.
Industry Challenges
- Fire safety certification timelines:Italy's national fire corps and civil protection standards for stationary energy storage above threshold capacities impose multi-month approval delays that compress project delivery windows.
- Electrochemical engineering talent scarcity:Domestic universities produce fewer than 200 specialized battery researchers annually, forcing manufacturers to recruit from German and French programs at premium compensation.
- Legacy industrial site remediation:Former lead acid production facilities in Milan's hinterland require environmental liability clearance before battery-grade cleanroom construction can commence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Rechargeable Battery Market |
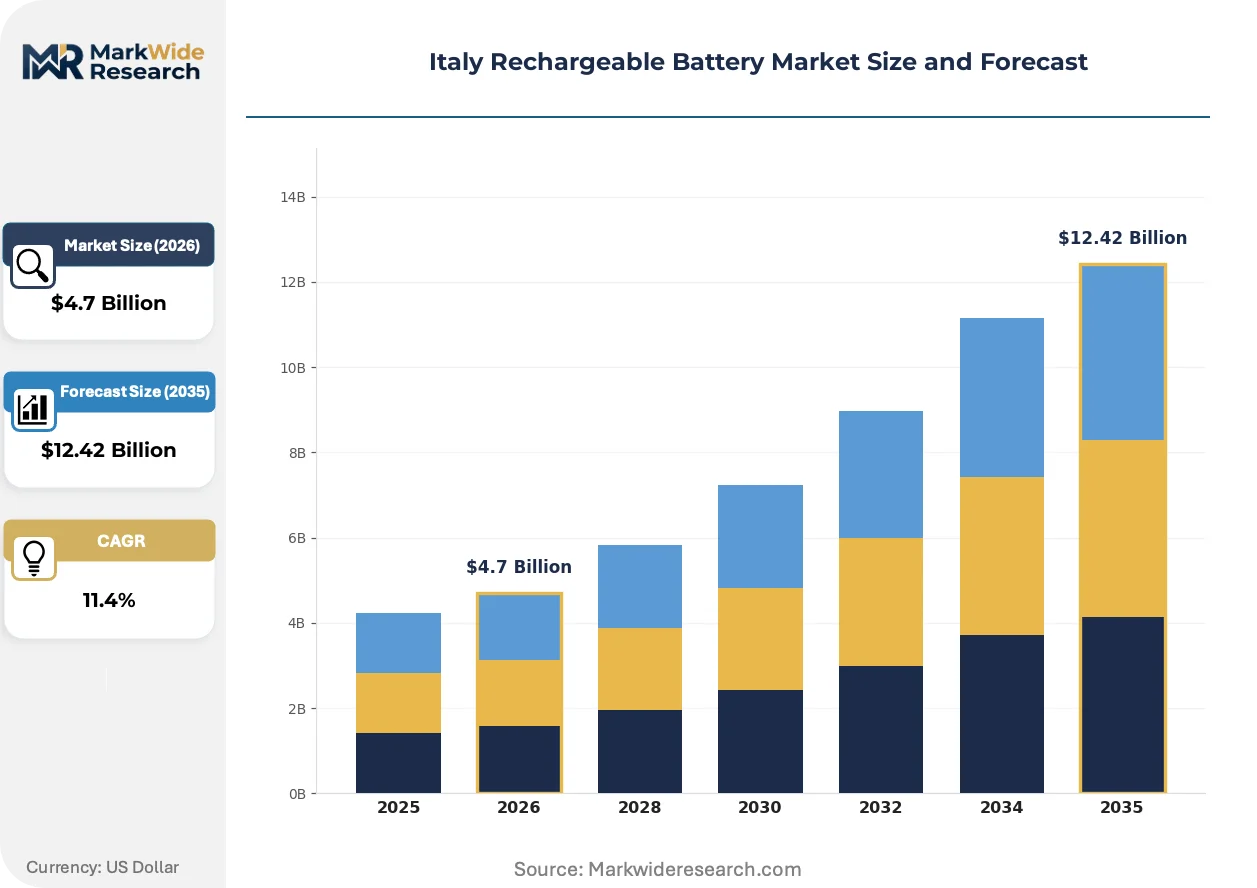
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-Metal Hydride, Lead Acid, Lithium Polymer End User: Consumer Electronics, Automotive, Industrial, Renewable Energy Technology: Energy Storage Systems, Electric Vehicles, Portable Devices, Power Tools Application: Grid Storage, Hybrid Systems, Backup Power, Electric Mobility |
| Companies Covered | Duracell Inc., BYD Company Ltd, Exide Industries Ltd, EnerSys, Panasonic Holdings Corporation, FIAMM SpA, Saft Groupe SA, LG Energy Solution, Enel Green Power, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Rechargeable Battery Market Trends and Innovations
Cell chemistry selection is fragmenting across end-use requirements, with automotive and grid applications diverging toward incompatible performance specifications that reshape supplier specialization.
High-nickel cathode formulations, specifically NMC 811 and NCA variants, are bifurcating the Italian supply base. Premium electric vehicle platforms from Turin-based OEMs specify these chemistries for energy density above 250 Wh/kg. Grid storage developers in the Po Valley reject the same materials due to thermal runaway risks, opting instead for lithium iron phosphate. This chemistry split forces domestic assemblers to maintain dual qualification lines, compressing margin structures for mid-volume producers unable to achieve scale in either camp.
The EU Battery Regulation's carbon footprint declaration requirements are tightening product compliance obligations for all manufacturers distributing within Italy. Industrial consequence: cell importers must now trace and document upstream emissions from mining through refining, adding 8-12 percent to administrative overhead. The segment most affected is the mid-tier automotive supply chain, where Tier 2 integrators lack the data systems to satisfy due diligence mandates and are consolidating around larger trading partners with established audit trails.
Fleet procurement offices are consolidating supplier relationships around integrated cell-to-pack providers, displacing modular component sourcing. Milan's ATM transport authority now issues single-source tenders covering cells, battery management systems, and thermal management. Channel disruption concentrates volume with Korean and Chinese integrators possessing in-house production of all three subsystems. This pattern is most visible in northern Italy's electric bus segment, where procurement teams prioritize warranty uniformity over component-level cost optimization.
Italy Rechargeable Battery Market Segmentation
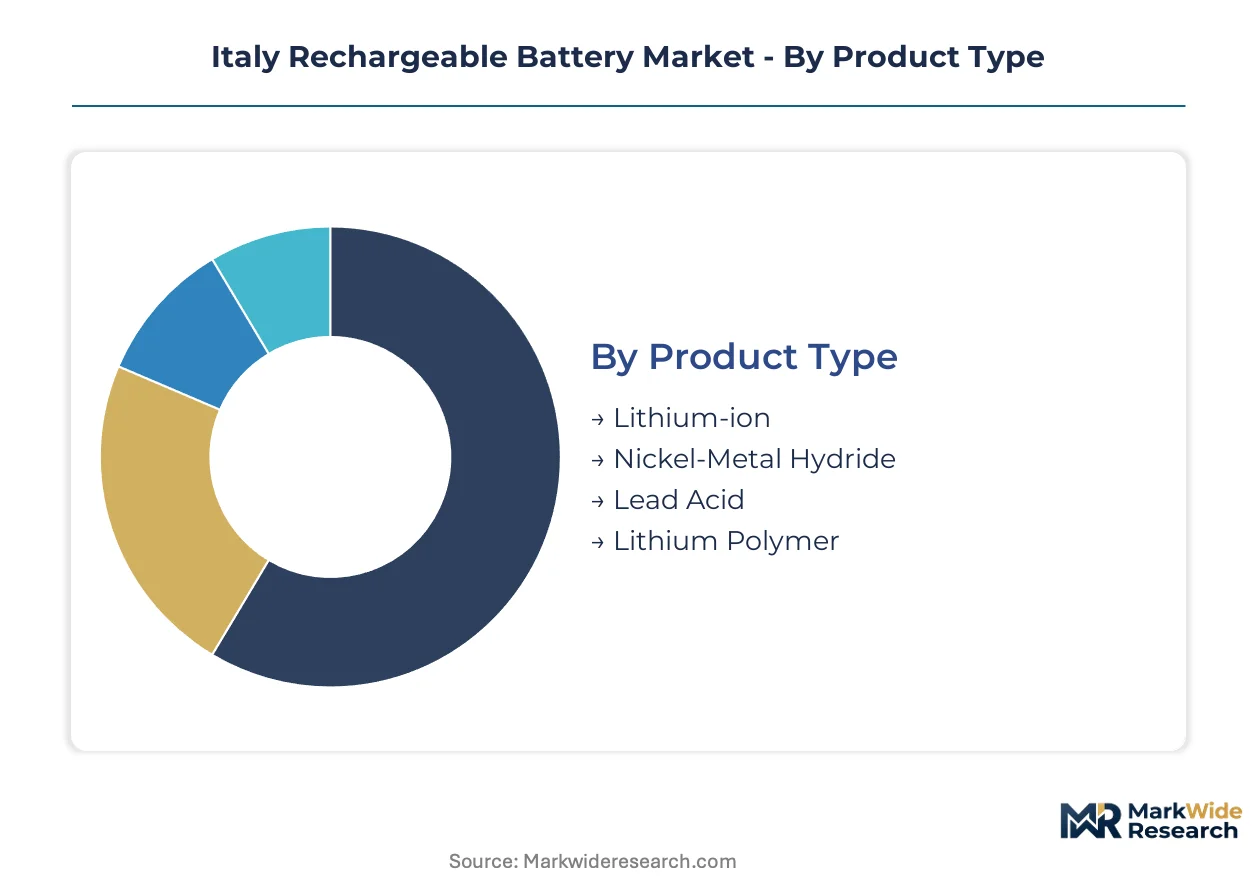
Segmentation in Italy's rechargeable battery market reveals how procurement patterns diverge between export-oriented automotive supply chains and domestically anchored grid storage installations. Understanding these splits helps suppliers calibrate certification investments and capacity allocation across diverging customer requirements.
Product Type:
Lithium-ion chemistries dominate export-linked contracts to German and French automotive OEMs, while lead acid retains strongholds in price-sensitive domestic backup power applications.
- Lithium-ion:NMC and LFP variants deliver 250+ Wh/kg energy density for electric vehicle platforms. Turin-based OEM procurement concentrates demand in the northern industrial corridor, though cathode precursor import bottlenecks through Rotterdam constrain margin expansion for domestic assemblers.
- Lead Acid:Flooded and VRLA configurations persist in telecommunications and healthcare backup systems where capital cost sensitivity outweighs cycle-life requirements. Demand clusters in Milan's metropolitan infrastructure and legacy industrial sites requiring minimal upfront investment.
- Nickel-Metal Hydride:Hybrid vehicle auxiliary power units in Bologna's automotive supplier network sustain residual demand for this chemistry.
- Lithium Polymer:Compact formats below 5 kWh serve Lombardy and Veneto electric two-wheeler subsidies with flexible form factors.
Lithium-ion holds the largest share; momentum sits with LFP variants as grid storage developers reject high-nickel thermal risks.
End User:
Cost tier stratification separates premium automotive-grade certification from standard industrial procurement, with renewable energy applications commanding mid-tier pricing.
- Automotive:OEM demand concentrates in the Turin-Bologna corridor for traction batteries above 100 kWh. CE marking under the EU Battery Regulation and carbon footprint declaration requirements add 8-12 percent administrative overhead, consolidating procurement around integrated cell-to-pack providers with established audit trails.
- Renewable Energy:Enel Green Power's controlled development pipelines in the Po Valley lock in multi-year supply contracts for utility-scale installations. Sicily's island grid instability and high solar irradiance create additional demand that domestic assemblers serve without mainland logistics costs.
- Consumer Electronics:Compact portable device demand flows through Milan's distribution networks with limited domestic manufacturing value capture.
- Industrial:Forklift and material handling equipment in Lombardy logistics hubs absorb second-life automotive packs with 70-80 percent residual capacity.
Automotive commands premium pricing tiers; renewable energy applications are climbing the fastest as auction mechanisms standardize procurement.
Technology:
Volume concentration favors electric vehicle platforms, though energy storage systems are gaining share through utility procurement mandates.
- Electric Vehicles:Bus electrification targets in Milan and Turin specify lithium-ion traction batteries, with ATM transport authority issuing single-source tenders covering cells, battery management systems, and thermal management. Korean and Chinese integrators capture volume through in-house subsystem production.
- Energy Storage Systems:Stationary installations above threshold capacities face multi-month approval delays from Italy's national fire corps and civil protection standards, compressing project delivery windows for domestic integrators.
- Portable Devices:Consumer electronics demand relies on imported cells with limited local value addition.
- Power Tools:Professional construction equipment in northern Italy specifies compact lithium-ion formats with rapid charge capabilities.
Electric vehicles retain volume leadership; energy storage systems are expanding most quickly as grid-scale auctions proliferate.
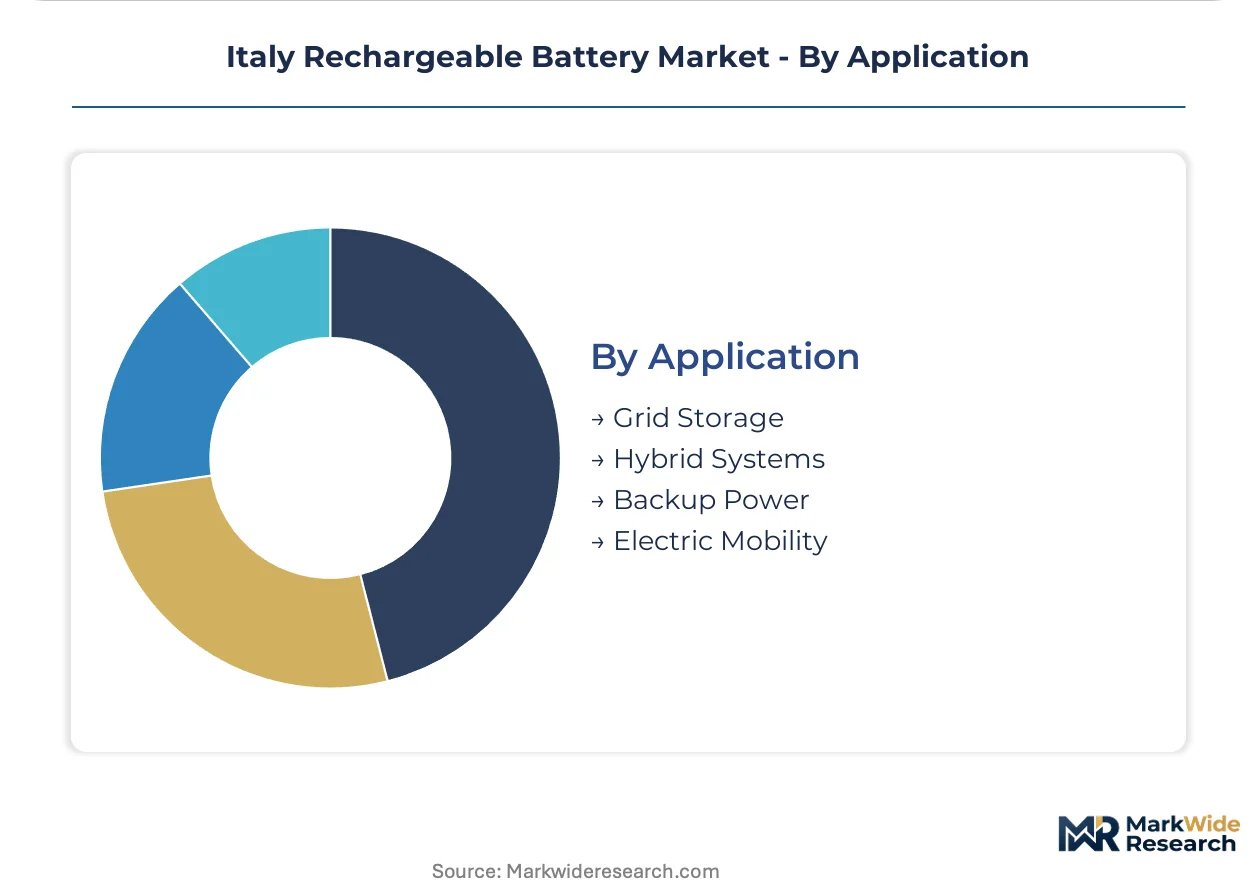
Application:
Customer type bifurcation separates municipal fleet procurement from private industrial offtake, with distinct contracting mechanisms and warranty structures.
- Electric Mobility:Municipal bus fleets in Milan and Turin now mandate lithium-ion specifications above 100 kWh, creating guaranteed offtake for certified cell suppliers. Regional two-wheeler electrification subsidies in Lombardy and Veneto accelerate demand for compact formats below 5 kWh.
- Grid Storage:Utility-scale developers in the Po Valley reject high-nickel cathodes due to thermal runaway risks, opting instead for lithium iron phosphate. This chemistry split forces domestic assemblers to maintain dual qualification lines.
- Backup Power:Telecommunications and healthcare facilities retain lead acid systems where capital cost sensitivity dominates procurement decisions.
- Hybrid Systems:Industrial microgrids in Sicily combine solar generation with battery buffering to address island grid instability.
Electric mobility holds the largest share; momentum sits with grid storage as Enel Green Power's pipeline matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic assembly capacity clusters in Italy's northern industrial corridor, with cathode precursor import bottlenecks through Rotterdam exposing the entire Po Valley supply base to transshipment risk.
Piedmont
Turin-based automotive OEMs specify lithium-ion traction batteries above 100 kWh for electric bus fleets. Italy's National Recovery and Resilience Plan channels state aid toward gigafactory development here. The Stellantis supply corridor anchors cell-to-pack procurement for premium electric vehicle platforms.
Lombardy
Milan's ATM transport authority issues single-source tenders covering cells, battery management systems, and thermal management. Regional two-wheeler electrification subsidies accelerate demand for compact lithium-ion formats below 5 kWh. Logistics hubs around Brescia absorb second-life automotive packs for industrial forklift applications.
Veneto
Electric motorcycle adoption incentives in Verona and Padua drive procurement of lithium polymer formats with flexible form factors. The region's manufacturing base lacks domestic cathode active material production, forcing assemblers to compete with imported cells from Poland and Hungary.
Sicily
Island grid instability and high solar irradiance create demand for stationary storage installations that domestic assemblers serve without mainland logistics costs. Former industrial sites require environmental liability clearance before battery-grade cleanroom construction can commence near Catania.
Emilia-Romagna
Bologna's automotive supplier network sustains residual demand for nickel-metal hydride in hybrid vehicle auxiliary power units. The region connects the Turin-Milan corridor to Adriatic port infrastructure, though EU Battery Regulation compliance deadlines freeze long-term feedstock sourcing decisions.
Italy Rechargeable Battery Market Competitive Landscape
Concentration sits with integrated cell-to-pack providers possessing in-house subsystem production. Korean and Chinese fabricators capture volume through warranty uniformity advantages over modular component sourcing. Three archetypes dominate: automotive-grade specialists, utility-scale integrators, and industrial battery legacy players. Competitive moves center on strategic partnerships for cathode precursor supply security and capacity expansion to serve Enel Green Power's controlled development pipelines.
Among Asia-based manufacturers, BYD Company Ltd and LG Energy Solution exemplify the integrated archetype with captive cell and pack capabilities. FIAMM SpA represents the European legacy industrial battery specialist pivoting toward utility-scale storage contracts. Duracell Inc. occupies a position in consumer-facing branded segments with limited exposure to automotive certification requirements. Panasonic Holdings Corporation anchors the premium-tier vector through established relationships with Turin-based OEM procurement offices.
| Leading Market Players |
|---|
| Duracell Inc. |
| BYD Company Ltd |
| Exide Industries Ltd |
| EnerSys |
| Panasonic Holdings Corporation |
| FIAMM SpA |
| Saft Groupe SA |
| LG Energy Solution |
| Enel Green Power |
| Others |
Pricing and Supply Chain Analysis
Ninety-day cathode precursor lead times from Rotterdam transshipment hubs compress margin structures for Italian assemblers while amplifying pricing power for integrated cell-to-pack providers with captive supply agreements. This inventory-to-pricing nexus forces mid-tier domestic producers into unfavorable contract terms as they compete with Polish and Hungarian imports benefiting from shorter logistics loops.
Pricing Analysis
CE marking under the EU Battery Regulation dictates the pricing tier structure across the Italian supply base. Three-tier pricing separates automotive-grade certified cells from industrial standard packs and uncertified economy imports. Price differentiation hinges on carbon footprint declaration compliance and fire safety certification from Italy's national fire corps. Cost compression in the mid-tier automotive segment is intensifying because Tier 2 integrators lack data systems to satisfy due diligence mandates. Municipal fleet procurement offices exhibit lowest price sensitivity, while telecommunications backup buyers retain lead acid systems where capital cost dominates.
Supply Chain Analysis
Ninety-day cathode precursor inventories at Rotterdam expose Italian cell plants to EU-wide port congestion and Dutch transshipment bottlenecks. Active material supply draws from China, South Korea, and Japan for lithium hydroxide, nickel sulfate, and cobalt refining. Raw material dependencies rest on Australian spodumene concentrate, Chilean brine lithium, and Indonesian nickel matte. Single-source vulnerability concentrates in cathode precursor feedstock arriving through Rotterdam. Distribution runs through controlled development pipelines anchored by Enel Green Power's utility-scale procurement and Stellantis supply corridor offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italian rechargeable battery incumbents face a substitution defense against imported cells from Polish and Hungarian gigafactories that benefit from shorter logistics loops and established EU Battery Regulation compliance pathways.
For Market Incumbents: Shield market position by securing backward integration into cathode precursor supply through long-term offtake agreements with Australian and Chilean mining operations. Invest in dual chemistry qualification lines for NMC and LFP variants to serve diverging automotive and grid storage specifications. Counter the threat of Korean and Chinese integrated cell-to-pack providers by accelerating fire safety certification timelines with Italy's national fire corps. For New Entrants and Emerging Players: Differentiate on second-life automotive pack refurbishment for industrial forklift and stationary applications in Lombardy logistics hubs. Target Sicily's island grid instability with lithium iron phosphate installations that domestic assemblers can serve without mainland logistics costs. Penetrate the two-wheeler electrification subsidy channel in Lombardy and Veneto with compact lithium polymer formats below 5 kWh. Go-to-market angle: circular economy certification aligned with upcoming EU Battery Regulation recycled content mandates. For Investors and Strategic Acquirers: Carve-out targets emerge from European legacy industrial battery specialists with historic utility-scale storage expertise and established Po Valley customer relationships. Long-term viability over the next decade hinges on cathode active material production localization within EU regulatory boundaries. Target acquisition archetype: mid-volume assemblers with dual NMC-LFP qualification lines and Enel Green Power pipeline exposure. Signal to watch: publication of delegated acts on recycled content mandates that will unfreeze feedstock sourcing decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Supply Security | Long-term offtake agreements with Australian miners reduce Rotterdam port congestion exposure for Italian assemblers. |
| Dual Chemistry Qualification | Parallel NMC and LFP certification lines capture diverging automotive and grid storage procurement specifications. |
| Second-Life Pack Refurbishment | Circular revenue streams from retired Turin bus batteries unlock industrial forklift demand in Lombardy logistics hubs. |
| Sicily Grid Storage Deployment | Island installations bypass mainland logistics costs while addressing renewable buffering needs from high solar irradiance. |
| Fire Safety Certification Acceleration | Compressed approval timelines with Italy's national fire corps defend against Korean integrators with established audit trails. |
Research Methodology
Desk research of EU Battery Regulation delegated acts, Enel Green Power development pipeline disclosures, and Italian National Recovery and Resilience Plan funding allocations preceded structured interviews with cell plant engineering directors, OEM procurement leads at Stellantis, utility-scale storage developers, cathode precursor traders, and fire safety certification officers. Secondary validation drew from Terna grid interconnection data, customs records of lithium compound imports through Rotterdam, and automotive production databases. Bottom-up capacity installation tracking and top-down policy flow analysis were triangulated against procurement contract announcements.
Variance decomposition across chemistry type, end-use application, and regional production cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include lithium-ion chemistry variant, automotive versus grid storage deployment, and northern industrial corridor versus island geography. CAGRs were derived from capacity expansion announcements, policy funding trajectories, and substitution elasticity estimates for lead acid displacement. Industry-specific forecast inputs incorporated Enel Green Power's controlled pipeline maturation and municipal fleet electrification mandates in Milan and Turin.
Material uncertainties — publication timing of EU Battery Regulation recycled content mandates, Rotterdam port congestion persistence, and cathode active material production localization decisions — sit outside the modeled envelope. Forecasts reflect assumptions about state aid disbursement schedules and fire safety certification processing rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Bangladesh Lead Acid Battery Market
Batteries
Italy SLI Battery Market
Batteries
Solid-State Batteries for Electric Vehicles Market
Batteries
Second-Life Automotive Battery Module Systems Market
Batteries
South Europe Battery Market
Batteries
Australia Battery Market
Batteries
India Lead-Acid Battery Market
Batteries
Grid-Scale Lead-Acid Battery Market
Batteries
Silicon Battery Market
Batteries
United Kingdom Rechargeable Battery Market
Batteries
Tubular GEL Battery Market
Batteries
United States SLI Battery Market
Batteries
Marine Powerboat Battery Market
Batteries
FORTELION Battery Module Market
Batteries
Indonesia and Malaysia Lead Acid Battery Market
Batteries
Drone Power Sources Market