
 Micro Battery Market | 2026-2036
Micro Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Battery Market Intelligence
Customized power module integration for medical devices is reconfiguring the value chain away from standardized component sales. This shift favors suppliers with deep application engineering capabilities. VARTA AG specializes in high-performance, miniaturized cells for premium hearing aids and medical wearables. Murata Manufacturing Co. Ltd. leverages its extensive background in passive electronic components to produce ultra-small silver-oxide and lithium-ion batteries. Meanwhile, STMicroelectronics N.V. positions its products by bundling micro batteries with its own microcontrollers and sensors for IoT applications.
A micro battery is a miniaturized electrochemical power source, typically characterized by a capacity under 100 mAh and a form factor designed for integration into space-constrained electronic devices. Manufacturing often involves advanced techniques like thin-film deposition to achieve minimal thickness. Its primary purpose is to provide autonomous power for products such as medical implants, smart cards, and wireless sensor nodes. Lithium-ion chemistries currently dominate the market due to superior energy density, while emerging solid-state batteries represent the fastest-growing technology segment. Demand from wearable electronics and IoT devices constitutes the largest application areas.
The regulatory environment imposes strict performance and safety mandates on manufacturers. In the United States, the FDA sets rigorous standards for batteries used in implantable and life-sustaining medical devices. Similarly, the EU's Medical Device Regulation (MDR) requires extensive documentation and testing for power components. Global market access often depends on compliance with IEC 62133 safety standards for portable lithium systems. The critical decision for suppliers involves allocating R&D capital between enhancing current lithium-ion performance and accelerating the commercialization of next-generation solid-state technologies.
Market Dynamics
The central dynamic shaping the micro battery market is the conflict between the pull for extreme miniaturization from the wearable electronics sector and the push for uncompromising reliability and safety from medical device regulators, creating a complex innovation and manufacturing landscape.
Growth Catalysts
- Miniaturization in Electronics:The continuous reduction in the size of components for IoT devices, particularly wireless sensor nodes and smart cards, requires correspondingly smaller and more integrated power sources to enable autonomous operation.
- Medical Device Regulation:The European Union's MDR establishes stringent safety and performance criteria, compelling medical device manufacturers to adopt high-reliability micro batteries for products like connected health monitors and diagnostic wearables.
- Wearable Technology Expansion:Proliferation of consumer and medical wearables, from premium hearing aids to fitness trackers, fuels demand for power sources that offer high energy density within a minimal footprint and weight.
Market Restraints
- High Manufacturing Costs:Advanced fabrication processes like thin-film deposition are capital-intensive and result in higher per-unit costs compared to conventional battery manufacturing, limiting adoption in price-sensitive applications.
- Energy Density Trade-offs:The physics of miniaturization imposes inherent limits on battery capacity and cycle life, creating performance trade-offs that can restrict functionality in power-intensive smart devices.
- Material Supply Concentration:The supply chain for high-purity lithium and specialized electrolyte materials is concentrated among a few global suppliers, exposing battery manufacturers to price volatility and potential sourcing risks.
Strategic Opportunities
- Smart Textiles Integration:The emergence of electronic textiles and flexible electronics for on-body monitoring presents a significant opportunity for developing conformable and stretchable micro batteries that can be woven into fabrics.
- Bundled IoT Solutions:Suppliers can create value by offering integrated platforms that bundle micro batteries with microcontrollers and sensors, simplifying the design process for IoT device manufacturers in sectors like industrial automation.
- Solid-State Technology Commercialization:Accelerating the development and scaling of solid-state micro batteries offers a path to capture the premium market segment for ultra-safe, high-density power in medical implants and critical sensors.
Industry Challenges
- Regulatory Certification Hurdles:Navigating the extensive and time-consuming testing and documentation required for compliance with both the FDA's requirements for medical devices and the EU's MDR creates significant barriers to entry.
- Lack of Form Factor Standardization:The absence of standard sizes and interconnects for micro batteries across different applications complicates automated assembly for device OEMs and limits economies of scale for battery producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Battery Market |
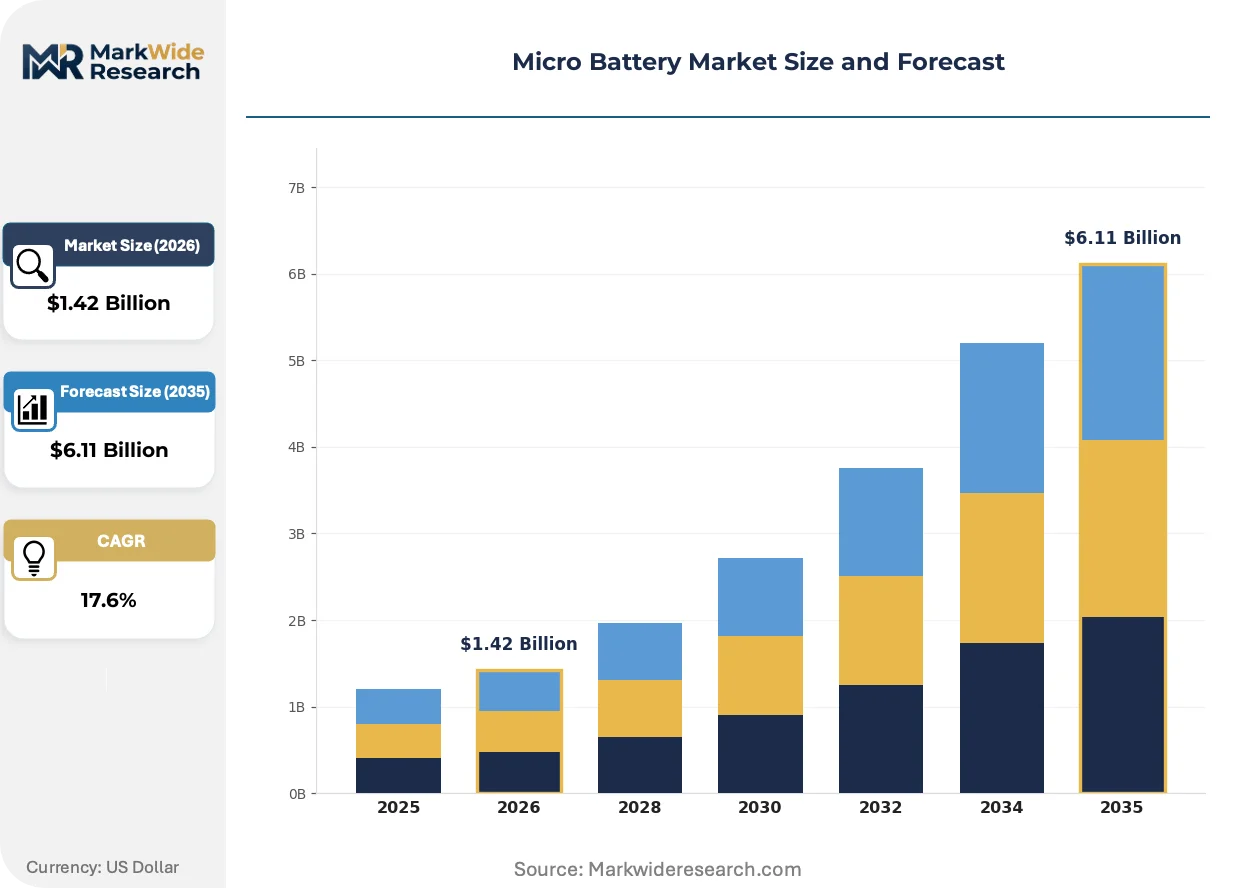
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $6.11 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Lithium-ion, Zinc-air, Nickel-metal Hydride, Solid-state, Silver-oxide Application: Wearable Electronics, Medical Devices, Smart Cards, IoT Devices, Hearing Aids End User: Consumer Electronics Manufacturers, Medical Equipment Providers, Security Solutions, Telecommunications, Automotive Suppliers Technology: Thin Film, Microelectromechanical Systems, Polymer Electrolyte, Nanotechnology, Flexible Battery |
| Companies Covered | Panasonic Corporation, Samsung SDI Co. Ltd., STMicroelectronics N.V., VARTA AG, TDK Corporation, Murata Manufacturing Co. Ltd., Cymbet Corporation, Enfucell Oy, Molex LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Battery Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive pivot towards solid-state chemistries, driven by intrinsic safety advantages critical for body-worn and implantable devices. This technological shift reconfigures material science priorities and manufacturing process requirements away from traditional lithium-ion architectures.
Solid-state battery technology employs solid electrolytes to eliminate the flammable liquid components found in conventional lithium-ion cells. Medical device designers and premium electronics manufacturers are actively prototyping these chemistries for next-generation products where safety cannot be compromised. The inherent stability and higher theoretical energy density of solid-state cells is rendering obsolete the use of liquid-electrolyte lithium-ion batteries in critical applications like pacemakers and implantable sensors.
Compliance with the IEC 62133 standard for portable secondary lithium cells has become a non-negotiable prerequisite for accessing major electronics markets. This global safety benchmark is forcing manufacturers to invest significantly in cell-level design and testing to prevent thermal runaway and other hazards. The consumer electronics and medical device sectors are most affected, frequently designing products around pre-certified batteries to de-risk and accelerate their path to regulatory approval.
Customized power module co-development is displacing the transactional sale of standard, off-the-shelf battery components. Original equipment manufacturers, particularly in the medical field, now engage battery suppliers early in the design cycle to create application-specific power systems that integrate the cell, protection circuitry, and charging interface. This collaborative trend is most prominent within the advanced medical device ecosystems of Germany and the United States.
Micro Battery Market Segmentation
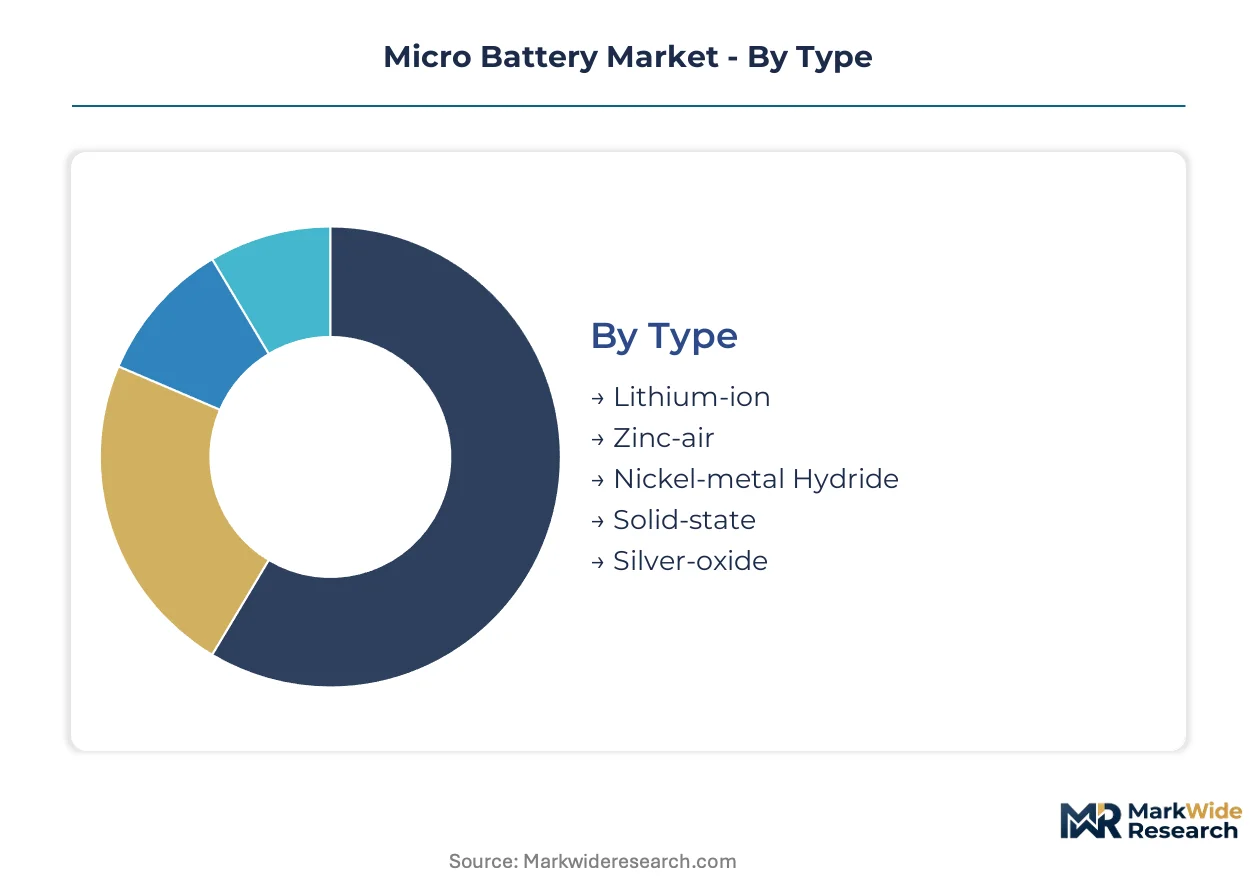
Market segmentation clarifies the diverse requirements and opportunities within the micro battery landscape. Understanding these distinct segments helps manufacturers tailor product development and strategic market entry. Each category reveals unique performance demands, cost sensitivities, and regulatory considerations for power solutions.
Type:
The after-sales service intensity for micro batteries varies significantly by chemistry type, influencing long-term device performance and replacement cycles.
- Lithium-ion:These batteries offer superior energy density, making them a prevalent choice across various electronics. Demand concentrates in wearable electronics due to their power requirements and compact form factors.
- Solid-state:This technology provides enhanced safety and high theoretical energy density without liquid electrolytes. Medical implants and critical sensors drive demand where reliability and non-flammability are paramount.
- Zinc-air:These cells deliver high energy density, primarily serving the hearing aid market.
- Nickel-metal Hydride:This chemistry offers a cost-effective solution with lower energy density for specific, less demanding applications.
- Silver-oxide:Known for stable voltage output, these batteries are common in watches and small medical devices.
Lithium-ion holds the largest share; momentum sits with Solid-state.
Application:
Micro battery applications exhibit varied cost sensitivities, ranging from premium medical devices to mass-market consumer electronics.
- Wearable Electronics:This sector requires high energy density within minimal form factors to support extended functionality. Demand is strong in fitness trackers and smartwatches, where user experience dictates performance.
- Medical Devices:These applications mandate extreme reliability and safety for critical life-sustaining and diagnostic functions. Implantable sensors and connected health monitors represent significant demand.
- IoT Devices:Micro batteries power wireless sensor nodes and smart tags for autonomous operation.
- Smart Cards:These devices utilize micro batteries to enable active functions like displays and biometric authentication.
- Hearing Aids:This segment demands long-lasting, miniaturized power sources for continuous operation.
Wearable Electronics command the largest volume; Medical Devices are expanding most quickly.
End User:
End-user segments drive distinct micro battery volumes, reflecting their production scales and integration requirements.
- Consumer Electronics Manufacturers:These companies engage in high-volume procurement for devices like smartwatches and earbuds. Demand focuses on cost-efficiency and high energy density.
- Medical Equipment Providers:This segment prioritizes extreme reliability, long cycle life, and stringent regulatory compliance for their products. Pacemakers and diagnostic wearables represent critical applications.
- Security Solutions:Micro batteries are utilized in asset tracking, access control systems, and surveillance equipment.
- Telecommunications:This sector integrates micro batteries into small network sensors and portable communication devices.
- Automotive Suppliers:Micro batteries are employed for key fobs, tire pressure monitoring systems, and other vehicle electronics.
Consumer Electronics Manufacturers account for the highest sales; Medical Equipment Providers show the steepest expansion trajectory.
Technology:
Micro battery technologies span a maturity spectrum, from established fabrication methods to nascent, high-potential innovations.
- Thin Film:This technology utilizes deposition techniques to create ultra-thin, flexible batteries. Demand concentrates in smart cards and flexible wearables due to their inherent form factor advantages.
- Solid-state:These technologies employ solid electrolytes, offering enhanced safety and stability over traditional liquid-electrolyte batteries. Medical implants and critical IoT sensors drive adoption for long-term reliability.
- Microelectromechanical Systems:This approach integrates power sources directly at the micro-scale for highly miniaturized applications.
- Polymer Electrolyte:This technology offers flexibility and enhanced safety compared to liquid electrolytes in specific battery designs.
- Nanotechnology:This field improves electrode materials and structures for higher capacity and faster charging capabilities in micro batteries.
Thin Film technologies hold a substantial share; Nanotechnology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The micro battery market exhibits varied demand elasticity across regions. Consumer electronics drive price-sensitive volume in some areas, while medical device manufacturing prioritizes uncompromising reliability, allowing for premium pricing. This dynamic shapes investment and regulatory focus in key global hubs.
United States
Demand for micro batteries in the United States stems from advanced medical implants and critical IoT sensors. The FDA sets rigorous standards for battery reliability and safety in life-sustaining devices. Boston's thriving medical technology cluster actively prototypes solid-state chemistries for next-generation wearable diagnostics.
Germany
Germany's micro battery demand primarily comes from premium hearing aids and sophisticated industrial IoT devices. The EU's Medical Device Regulation (MDR) requires extensive testing for power components in connected health products. Bavaria's electronics manufacturing centers integrate high-performance micro batteries into specialized industrial automation solutions.
South Korea
South Korea's market growth is propelled by its robust consumer wearables sector and advanced display technologies. The MFDS enforces strict safety guidelines for batteries integrated into medical and consumer devices. Seoul's dynamic technology ecosystem drives continuous miniaturization trends for smartwatches and other high-volume consumer electronics.
Japan
Japanese demand for micro batteries is significant in precision medical instruments and advanced smart cards. The METI oversees stringent safety standards for portable lithium systems used in electronics. Tokyo's research institutions and manufacturers collaborate on developing ultra-thin film batteries for next-generation smart card applications.
China
China's micro battery market is driven by mass-market IoT devices and cost-effective wearables. The SAMR enforces product quality and safety standards for all consumer electronics. Shenzhen's extensive manufacturing hub rapidly integrates micro batteries into a vast array of smart tags and other high-volume IoT solutions.
Micro Battery Market Key Industry Players
Capability concentration sits with one tier of micro battery specialists, while scale advantage sits with another tier of diversified electronics giants. The market exhibits a tiered structure, from highly specialized innovators focusing on medical-grade solutions to large-scale manufacturers serving high-volume consumer electronics. Strategic archetypes include niche technology leaders, integrated component suppliers, and mass-market producers. Dominant competitive moves involve strategic partnerships for bundled solutions and continuous R&D investment in next-generation chemistries.
Specialists in high-performance, miniaturized cells include VARTA AG, which anchors the premium medical wearables segment. Murata Manufacturing Co. Ltd., a Japan-based electronics conglomerate, exemplifies a diversified approach, leveraging its extensive background to produce ultra-small silver-oxide and lithium-ion batteries across various applications. STMicroelectronics N.V. represents an integrated component supplier, positioning its micro batteries by bundling them with its own microcontrollers and sensors for IoT applications, thereby simplifying design processes for device manufacturers.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Samsung SDI Co. Ltd. |
| STMicroelectronics N.V. |
| VARTA AG |
| TDK Corporation |
| Murata Manufacturing Co. Ltd. |
| Cymbet Corporation |
| Enfucell Oy |
| Molex LLC |
Cost & Logistics Intelligence
Commodity volatility in high-purity lithium creates significant pricing tier spreads and shapes the micro battery supply chain. This input risk influences manufacturing location decisions and strategic inventory management for battery producers.
Pricing Analysis
After-sales service contracts for medical device battery replacements drive significant lifetime value. The dominant pricing model is value-based, reflecting performance and reliability, with differentiation based on certification level and application-specific customization. Pricing pressure stems from cost-effective thin-film alternatives in consumer wearables, where consumer electronics manufacturers are most price-sensitive. Medical equipment providers, however, exhibit the least price sensitivity due to stringent reliability mandates.
Supply Chain Analysis
The upstream supply of high-purity lithium and specialized electrolyte materials heavily influences micro battery production. Geographic supply concentration sits with China, South Korea, and Japan for key battery components, creating single-source vulnerability for specific material grades. Manufacturers depend on these concentrated sources. Distribution runs primarily through direct sales to original equipment manufacturers, especially for medical and premium wearable applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The micro battery market is at a platform-economics inflection, driven by the increasing interoperability of smart devices within connected health ecosystems. This shift favors integrated solutions over standalone component sales, reshaping value capture.
For Market Incumbents: Insulate core market share by deepening application engineering capabilities for medical devices. Invest significantly in R&D for solid-state chemistries to counter the threat of emerging technologies. Pursue strategic partnerships with leading medical equipment providers to ensure captive supply channels. This strategy helps mitigate margin pressure from commoditized consumer electronics segments.
For New Entrants and Emerging Players: Build out specialized manufacturing capabilities for flexible and conformable micro batteries targeting smart textiles. Focus on the industrial IoT sector in Germany, which represents a penetrable segment for high-reliability, customized power solutions. Offer bundled micro battery and sensor modules as a go-to-market strategy, simplifying integration for device manufacturers. This approach avoids direct competition with established lithium-ion producers in high-volume consumer markets.
For Investors and Strategic Acquirers: The EU's Medical Device Regulation (MDR) reshapes the acquisition landscape, favoring companies with proven regulatory compliance and deep application expertise. Long-term viability over the next decade hinges on intellectual property in solid-state battery technology and advanced thin-film manufacturing. Target vertically integrated specialists serving the medical implant and critical sensor markets. The signal to watch is the accelerated commercialization of next-generation solid-state batteries for life-sustaining devices.
| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery R&D Acceleration | This initiative captures premium market share in medical implants requiring ultra-safe power solutions. |
| Customized Power Module Co-Development | This move strengthens relationships with medical equipment providers by integrating application-specific battery systems. |
| Flexible Battery Manufacturing Expansion | Expanding this capability addresses the growing demand from smart textiles and conformable wearables. |
| Regulatory Compliance Investment | Investing in compliance ensures market access and de-risks product launches for critical medical devices. |
| Bundled IoT Solution Offering | This strategy simplifies design processes for IoT device manufacturers by integrating battery, microcontroller, and sensor packages. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, industry association reports, and technical journals. Primary interviews engaged R&D directors, product managers, procurement leads, and regulatory affairs specialists across the micro battery value chain. This approach integrated insights from key opinion leaders with market data. Bottom-up data aggregation and top-down market sizing validated all quantitative estimates.
Forecast inputs consider technology adoption rates, regulatory compliance timelines, and end-user demand patterns across the analysis window. The analytical framework modeled segmentation by type, application, end user, and technology, including form factor innovation. Compound Annual Growth Rates (CAGRs) were derived through regression analysis. Key forecast inputs included wearable device shipment forecasts and medical device approval rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified electronics giants or specialized battery innovators would shift outcomes. Forecasts reflect documented assumptions, but critical material supply risks exist. Cross-checking against independent industry benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Zinc-Ion Battery Cells Market
Batteries
Zinc-Manganese Oxide Batteries Market
Batteries
Battery Cell Market
Batteries
48 Volt Battery System Market
Batteries
Battery Coolant-Antifreeze Refractometer Market
Batteries
South America Consumer Battery Market
Batteries
Carbon Black in Lead-Acid Battery Market
Batteries
India Battery Cell Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
Water-Based Zinc-Ion Battery Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
Drone Power Sources Market
Batteries
Solid-State Car Battery Market
Batteries
North America Industrial Battery Market
Batteries
Latin America Automotive Lead-Acid Battery Market
Batteries
GCC Rechargeable Battery Market