
 Food Grade Polyvinyl Acetate Market | 2026-2036
Food Grade Polyvinyl Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Polyvinyl Acetate Market Analysis
Ethylene-vinyl acetate copolymers is decoupling from traditional food-grade adhesive formulations as manufacturers seek lower-migration, high-clarity alternatives for flexible packaging laminates. Celanese Corporation leverages its integrated acetyls chain to sustain cost-competitive vinyl acetate monomer supply for North American food-contact adhesive producers. Wacker Chemie AG dominates European food-grade PVAc capacity with specialized polymerization technology that meets BfR and FDA indirect additive limits.
Food grade polyvinyl acetate denotes a vinyl acetate homopolymer or copolymer synthesized under controlled conditions to achieve residual monomer levels below regulatory thresholds for direct and indirect food contact, typically supplied as aqueous dispersions with solids content ranging from 50% to 60% and viscosity grades tailored to coating or adhesive application. Its primary commercial purpose centers on bonding multi-layer films, paperboard, and foil substrates in packaging structures where the adhesive layer remains separated from food by a functional barrier yet must withstand thermal processing and shelf-life migration testing. The adhesives segment leads food-grade PVAc consumption due to pervasive use in dry-food carton sealing and fresh-produce label applications, while the films segment represents the fastest-growing category as mono-material packaging mandates drive interest in water-processable barrier coatings. Food packaging applications anchor the largest margin pool because brand owners pay formulation premiums for compliance documentation and lot-specific extractables testing.
FDA indirect food additive regulations under 21 CFR 175.105 and 21 CFR 177.1390 govern adhesive composition and laminate construction for U.S. food-contact applications, while the EU Framework Regulation EC 1935/2004 and specific measures under the Plastics Regulation EU 10/2011 establish migration limits and authorized substance lists for European market access. BfR Recommendation XIV provides German formulators with detailed testing protocols that de facto shape industry-wide purity benchmarks for vinyl acetate-based food-contact materials. Stakeholders must monitor accelerating regulatory divergence between FDA notification pathways and EU harmonized standards as they evaluate regional formulation strategies and certification investments.
Market Dynamics
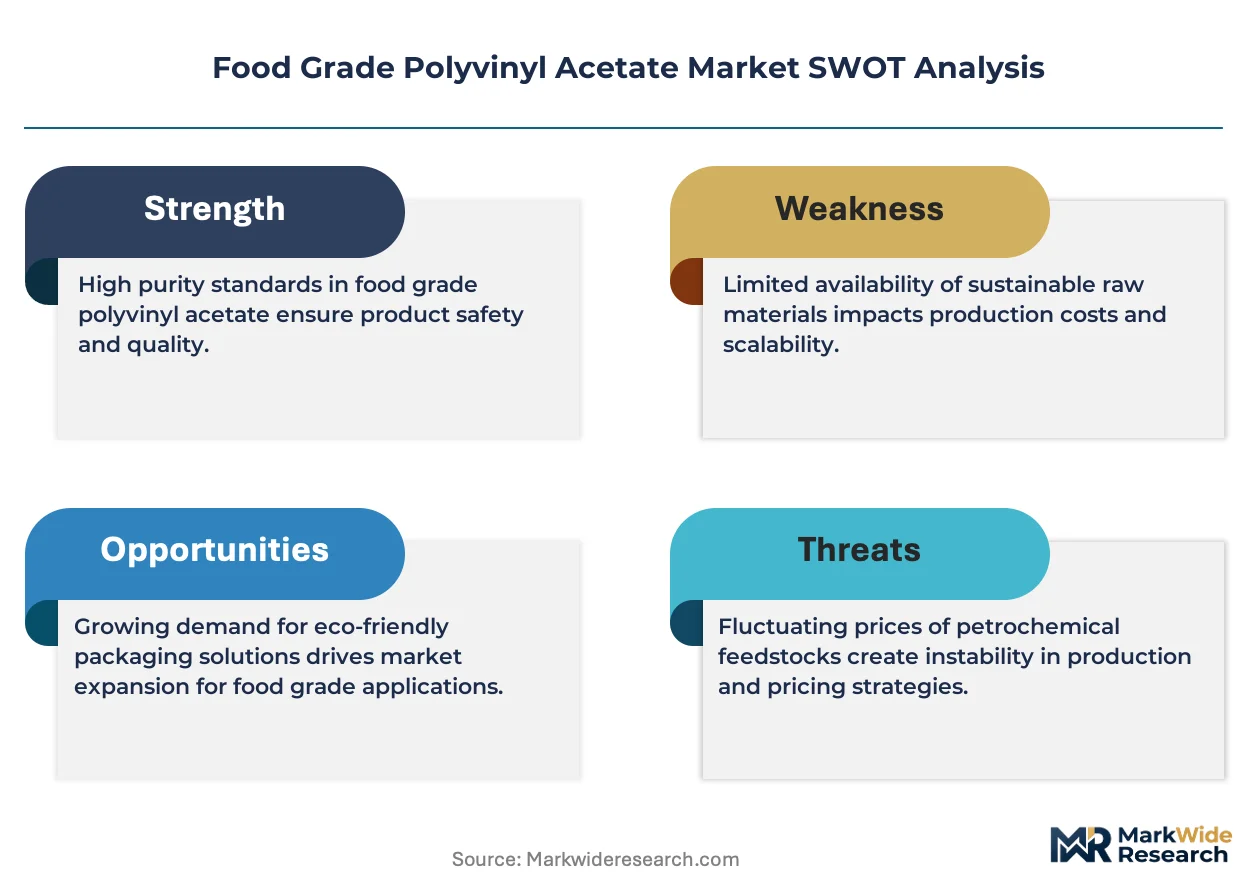
Migration limits under EU 10/2011 and FDA 21 CFR 175.105 are compressing formulation freedom for vinyl acetate adhesive producers, forcing selective monomer substitution and extractables documentation investments that reshape competitive economics.
Growth Catalysts
- Mono-material packaging mandates:EU Packaging and Packaging Waste Regulation revisions drive water-processable barrier coatings as replacement for multi-layer laminates. Fresh-produce label applications expand PVAc demand in direct-contact scenarios.
- FDA indirect additive compliance:U.S. food packaging converters seek certified low-migration adhesives for retort pouch constructions. Compliance documentation commands formulation premiums from brand owners.
- German technical service concentration:Wacker Chemie's Burghausen polymerization expertise anchors European supply security for food-grade adhesive formulators requiring BfR XIV testing protocols.
Market Restraints
- Vinyl acetate monomer price volatility:Acetyls chain input costs fluctuate with natural gas and ethylene pricing, compressing margin stability for dispersion producers.
- European supply concentration:Single-country production dominance creates geographic risk exposure for continental formulators dependent on just-in-time aqueous dispersion delivery.
- Ethylene-vinyl acetate substitution:Lower-migration copolymer alternatives displace traditional PVAc in high-clarity flexible packaging laminates requiring extended shelf-life migration testing.
Strategic Opportunities
- India food-contact material formalization:FSSAI implementation of comprehensive food-grade polymer standards creates first-mover certification advantages for compliant adhesive suppliers.
- Cellulose nanocrystal hybrid coatings:Convergence of bio-based reinforcement with PVAc dispersions enables oxygen barrier performance in paper-only packaging structures.
- E-commerce direct sourcing platforms:Industrial chemical marketplaces disintermediate traditional distributor networks for mid-volume adhesive purchasers seeking lot-specific extractables data.
Industry Challenges
- Migration testing specialist scarcity:Analytical chemists capable of designing EU 10/2011 compliant overall migration and specific migration testing protocols command premium compensation.
- Legacy formulation revalidation timelines:Reformulating established adhesives to meet tightened residual monomer thresholds requires 18-24 month customer qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Polyvinyl Acetate Market |
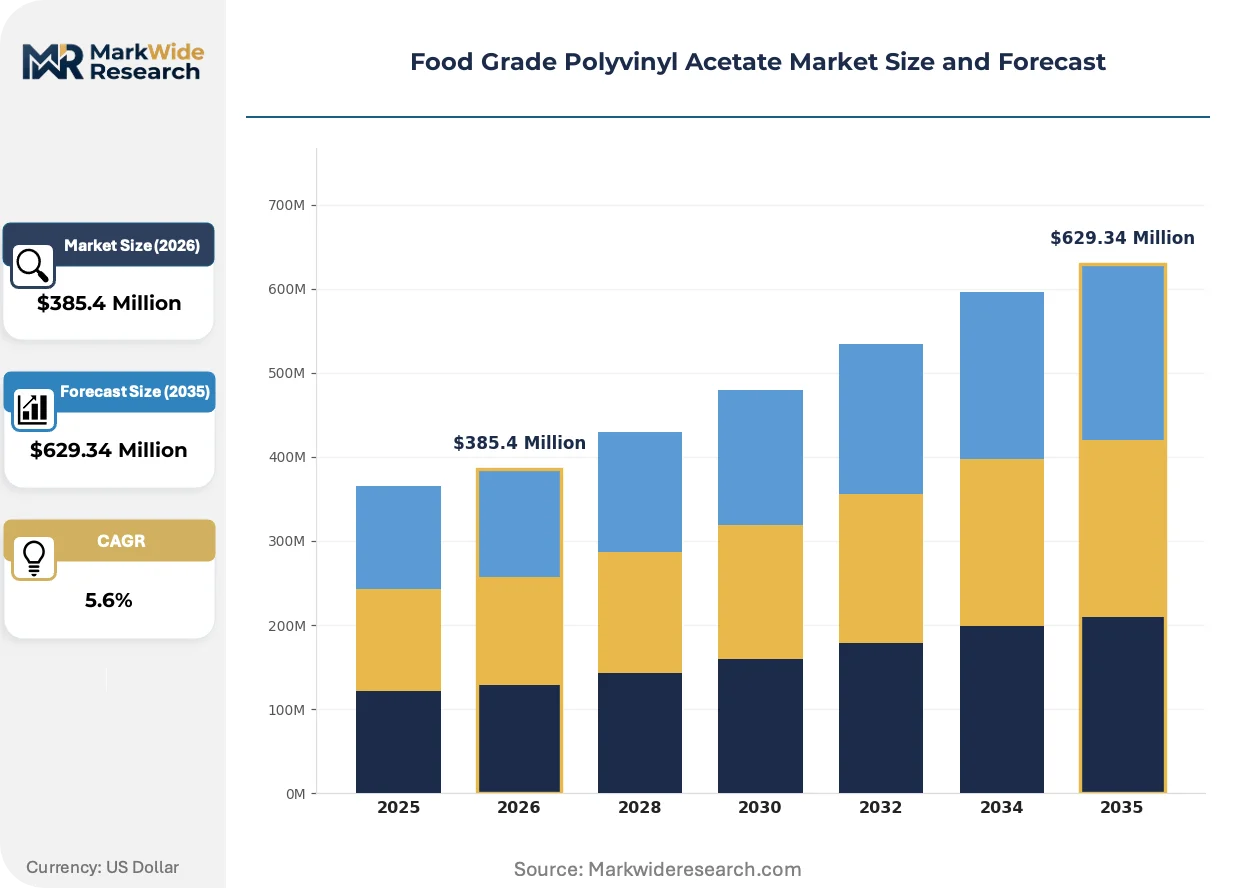
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $629.34 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Coatings, Sealants, Films Application: Food Packaging, Medical Devices, Consumer Goods, Textile End User: Food Industry, Healthcare, Retail, Manufacturing Distribution Channel: Online Stores, Wholesalers, Direct Sales, Distributors |
| Companies Covered | Jiangsu Yinyang Gumbase Materials, Celanese Corporation, Wacker Chemie AG, Shuanghui Rubber Nantong, Nacalai Tesque, VINAVIL S.p.A., Foreverest Resources Ltd., Henkel Corporation, Brenntag Specialties, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Polyvinyl Acetate Market Emerging Trajectories
Water-borne barrier technologies and regulatory migration science are converging to redefine food-grade adhesive performance specifications, with compliance documentation becoming as critical as bond strength in purchase decisions.
Polyvinyl alcohol-stabilized PVAc dispersions is absorbing regulatory scrutiny as the preferred vehicle for high-clarity laminate constructions. European flexible packaging converters are adopting these systems at accelerated pace for snack and confectionery applications. The technology is absorbing market share from solvent-borne alternatives by eliminating volatile organic compound compliance burdens while maintaining heat-seal integrity.
REACH authorization list expansion is tightening residual monomer thresholds for vinyl acetate-based food-contact materials. Industrial consequence includes mandatory supply chain communication obligations downstream to converters and brand owners. Adhesive formulators serving German retail chains are responding with lot-specific extractables certificates and third-party laboratory verification protocols.
Brand-owner sustainability scorecards are elevating bio-based content and recyclability compatibility in adhesive selection criteria. Major European retailers are disintermediating traditional specification processes by issuing direct compliance questionnaires to tier-two adhesive suppliers. This pattern is most visible in German and French fresh-produce packaging supply chains where mono-material recyclability claims require adhesive layer transparency.
Food Grade Polyvinyl Acetate Market Segmentation
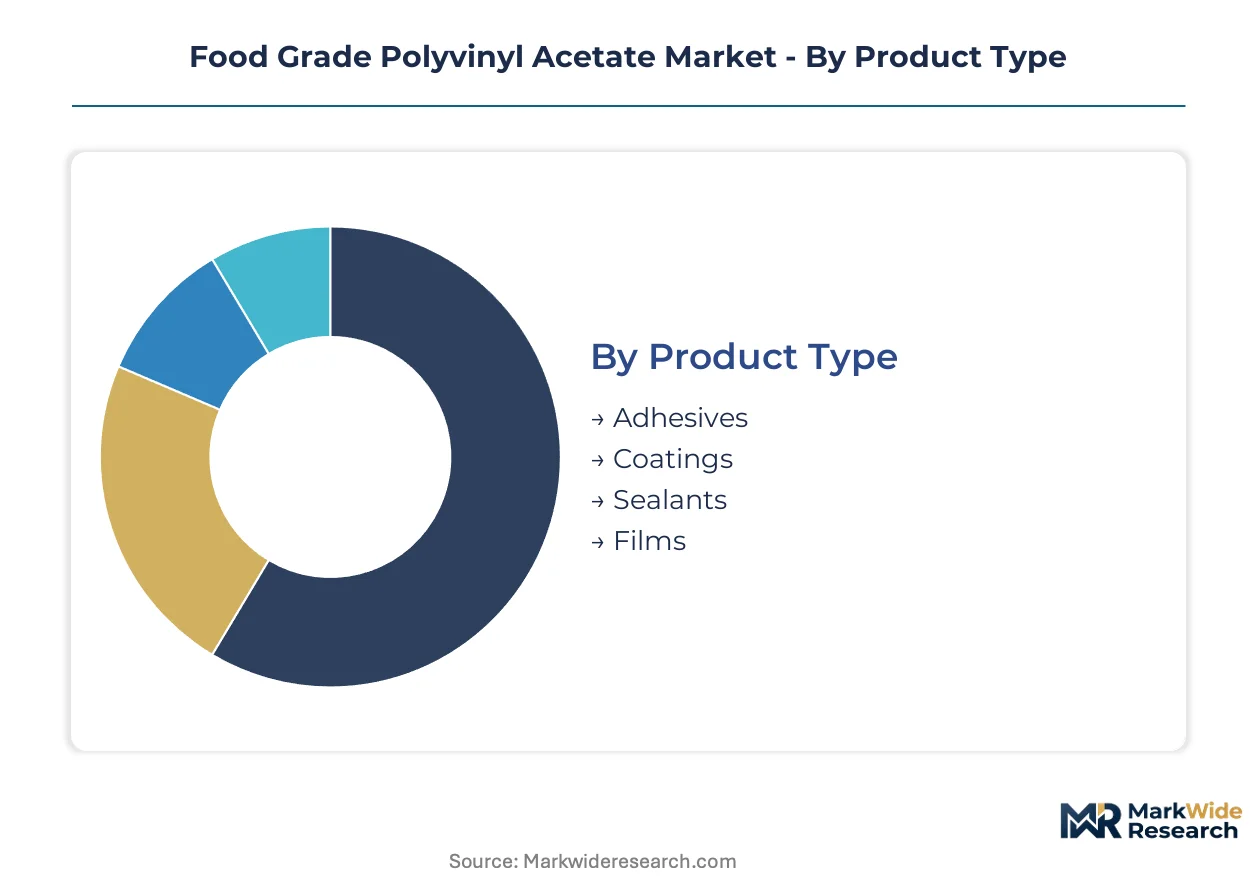
Food-grade polyvinyl acetate markets fragment across formulation chemistry and supply chain access points. Segmentation discipline reveals where compliance documentation commands premium pricing versus commodity dispersion competition.
Product Type:
Supply concentration in aqueous dispersion technology shapes competitive dynamics across formulation categories.
- Adhesives:Aqueous dispersions with solids content ranging from 50% to 60% dominate dry-food carton sealing and fresh-produce label bonding. Demand concentrates in Germany where Wacker Chemie's Burghausen facility anchors BfR XIV-compliant supply for European formulators facing EU 10/2011 migration limits.
- Films:Water-processable barrier coatings enable mono-material packaging structures replacing multi-layer laminates under EU Packaging and Packaging Waste Regulation revisions. This segment is gaining share fastest as brand owners seek recyclability-compatible adhesive layers with oxygen barrier performance.
- Coatings:Polyvinyl alcohol-stabilized PVAc systems serve high-clarity flexible packaging applications requiring heat-seal integrity without volatile organic compound burdens.
- Sealants:Low-viscosity grades target direct-contact scenarios with residual monomer thresholds below FDA 21 CFR 175.105 specifications.
Today's leader: Adhesives. Tomorrow's challenger: Films.
Application:
End-use compliance requirements stratify pricing power across customer segments.
- Food Packaging:Multi-layer film, paperboard, and foil substrate bonding commands formulation premiums for lot-specific extractables testing and thermal processing resistance. U.S. converters seek certified low-migration adhesives for retort pouch constructions under FDA indirect additive regulations.
- Medical Devices:Sterile barrier packaging applications require extended shelf-life migration testing protocols with documented biocompatibility compliance.
- Consumer Goods:Non-food contact adhesives compete on cost with reduced regulatory documentation burdens.
- Textile:Food-contact adjacent applications such as conveyor belts and processing equipment coatings face intermediate purity specifications.
Food Packaging captures the dominant margin pool. Medical Devices offers the steepest expansion trajectory as sterile packaging demand intensifies.
End User:
Customer procurement sophistication determines specification control and supplier relationship intensity.
- Food Industry:Brand owners and packaging converters drive compliance documentation requirements with direct compliance questionnaires to tier-two adhesive suppliers.
- Healthcare:Hospital and pharmaceutical packaging operations prioritize sterile barrier integrity with validated supply chain protocols.
- Retail:Major European retailers issue sustainability scorecards elevating bio-based content and recyclability compatibility in adhesive selection criteria.
- Manufacturing:Industrial equipment and processing machinery producers seek general-purpose grades with basic food-contact certifications.
Food Industry sets the specification standard. Healthcare is climbing the fastest as regulatory scrutiny intensifies.
Distribution Channel:
Channel economics reflect lot-size granularity and documentation service requirements.
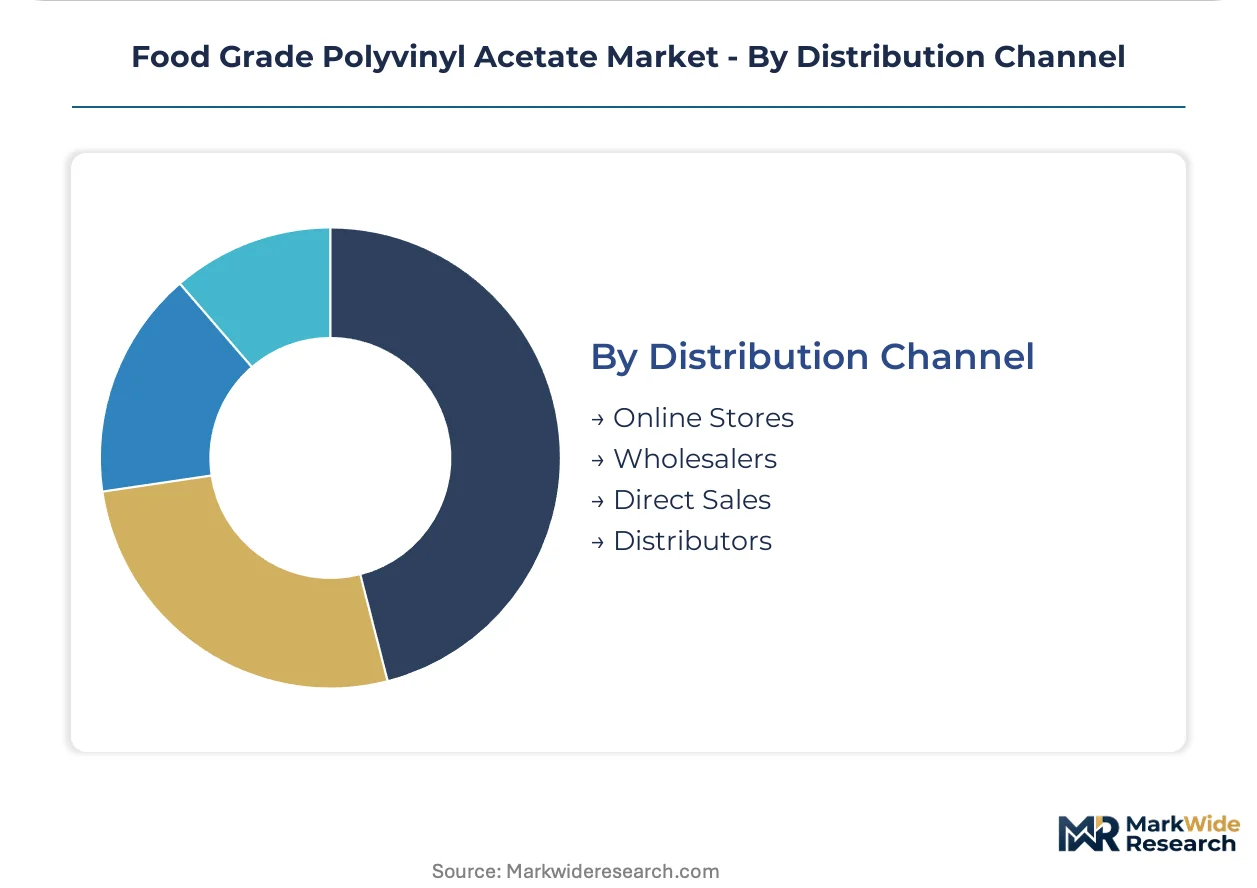
- Direct Sales:Large-volume converters negotiate supply security agreements with producers for just-in-time aqueous dispersion delivery and dedicated technical service support.
- Distributors:Regional chemical distributors maintain inventory positions for mid-volume purchasers requiring shorter lead times than direct mill supply.
- Wholesalers:Bulk aggregation serves smaller formulators with standardized viscosity grades and generic compliance certificates.
- Online Stores:Industrial chemical marketplaces disintermediate traditional networks for purchasers seeking lot-specific extractables data with transparent pricing.
Direct Sales commands the relationship premium. Online Stores represent the fastest-growing access point as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Burghausen anchors European food-grade PVAc production capacity with specialized polymerization infrastructure serving continental adhesive formulators. FDA and EU regulatory divergence is fragmenting formulation strategies across Atlantic markets. Asian converters are accelerating compliance investments as food-contact material standards formalize.
United States
Retort pouch constructions for shelf-stable meals drive certified low-migration adhesive procurement from domestic converters. FDA indirect food additive regulations under 21 CFR 175.105 govern laminate composition and extractables documentation requirements. Celanese Corporation's integrated acetyls chain supports cost-competitive vinyl acetate monomer supply for North American producers.
Germany
Flexible packaging converters seek BfR XIV-compliant aqueous dispersions for direct-contact fresh-produce label applications. EU Framework Regulation EC 1935/2004 and Plastics Regulation EU 10/2011 establish migration limits shaping formulation chemistry. Wacker Chemie's Burghausen facility concentrates technical service capabilities for continental formulators facing tightened residual monomer thresholds.
China
Mono-material packaging mandates in export-oriented manufacturing clusters drive water-processable barrier coating adoption. GB standards for food-contact materials are converging with EU migration testing protocols under SAMR oversight. Yangtze River Delta packaging hubs are qualifying PVAc-based adhesives for European private-label supply chains.
India
Domestic food packaging converters anticipate FSSAI implementation of comprehensive food-grade polymer standards. First-mover certification advantages are attracting multinational adhesive suppliers to establish technical service presence. Maharashtra and Gujarat industrial corridors concentrate laminate manufacturing capacity requiring compliant dispersion supply.
Japan
High-clarity flexible packaging for confectionery and snack applications sustains polyvinyl alcohol-stabilized PVAc demand. METI guidelines on food-contact material safety support industry-wide migration testing harmonization. Kansai region converters prioritize heat-seal integrity specifications for premium retail packaging segments.
Food Grade Polyvinyl Acetate Market Vendor Landscape
Capacity expansion dominates the current landscape as producers scale aqueous dispersion infrastructure to capture mono-material packaging conversion demand. The vendor base stratifies across integrated chemical conglomerates, specialized polymerization specialists, and regional formulation houses. Three archetypes prevail: acetyls-integrated producers controlling upstream monomer supply, European technical service leaders commanding compliance documentation premiums, and Asia-Pacific distributors aggregating mid-volume procurement. Competitive intensity centers on extractables certification speed and lot-specific testing protocol development.
Within the integrated chemical tier, Celanese Corporation exemplifies acetyls-chain producers leveraging captive vinyl acetate monomer supply for cost positioning. Wacker Chemie AG anchors the European specialist archetype with Burghausen-based polymerization expertise. Jiangsu Yinyang Gumbase Materials and Shuanghui Rubber Nantong occupy positions among Asia-Pacific dispersion suppliers serving regional packaging converter networks. These named entities represent structural positioning rather than definitive market share claims.
| Leading Market Players |
|---|
| Jiangsu Yinyang Gumbase Materials |
| Celanese Corporation |
| Wacker Chemie AG |
| Shuanghui Rubber Nantong |
| Nacalai Tesque |
| VINAVIL S.p.A. |
| Foreverest Resources Ltd. |
| Henkel Corporation |
| Brenntag Specialties |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap dispersion specialists anchor pricing discipline through captive warehouse networks and long-term ethylene supply contracts that buffer vinyl acetate monomer volatility. Their ownership structure enables patient capital allocation toward BfR XIV certification investments that command formulation premiums from German adhesive formulators facing EU 10/2011 migration thresholds.
Pricing Analysis
Acetyls chain input costs pass through to finished dispersion pricing with 60-90 day lags, compressing margin stability when natural gas benchmarks spike. Contract-based long-term offtake dominates volume procurement, with premium-mid-economy pricing differentiation separating BfR XIV-certified grades from generic food-contact certifications. Cost compression in standard-grade aqueous dispersions is intensifying because Asian producers are qualifying for European private-label supply chains. Mid-volume converters exhibit highest price sensitivity, while retort pouch specialists prioritize lot-specific extractables documentation over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and Belgium maintain hub-and-spoke patterns for just-in-time aqueous dispersion delivery to continental formulators. Manufacturing gravity draws from Wacker Chemie's Burghausen polymerization complex, Celanese's North American acetyls integration, and Yangtze River Delta dispersion plants serving export markets. Single-source vulnerability concentrates in German technical service capabilities for BfR XIV testing protocol development. Distribution runs through direct mill supply for large converters and industrial chemical marketplaces for mid-volume purchasers seeking transparent lot-specific extractables data.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU 10/2011 compliance investments and FSSAI formalization timelines in India creates first-mover certification advantages for adhesive suppliers willing to absorb 18-24 month customer qualification cycles.
For Market Incumbents: To counter ethylene-vinyl acetate copolymer substitution in high-clarity flexible packaging, deepen backward integration into vinyl acetate monomer production and expand Burghausen polymerization capacity for BfR XIV-compliant aqueous dispersions. Certification investment in lot-specific extractables testing protocols defends formulation premiums against Asian cost competitors. For New Entrants and Emerging Players: Industrial chemical marketplaces offer the lowest-friction route to mid-volume converters seeking transparent pricing with compliance documentation. Target Maharashtra and Gujarat industrial corridors where domestic laminate manufacturers anticipate FSSAI food-grade polymer standards. Position through e-commerce direct sourcing platforms that disintermediate traditional distributor networks for purchasers requiring SAMR-aligned GB standard certifications. For Investors and Strategic Acquirers: Valuations sit cheapest among Asia-Pacific dispersion suppliers lacking European regulatory documentation capabilities but possessing scalable aqueous polymerization infrastructure. Long-term viability hinges on migration testing specialist scarcity and accelerating regulatory divergence between FDA notification pathways and EU harmonized standards. Watch for FSSAI implementation announcements as inflection indicators for first-mover certification advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vinyl Acetate Monomer | Celanese's acetyls chain demonstrates cost positioning against ethylene price volatility. |
| BfR XIV Certification Investment | Wacker Chemie's Burghausen facility anchors European compliance documentation premiums. |
| Cellulose Nanocrystal Hybrid Development | Convergence with PVAc dispersions enables oxygen barrier performance in paper-only structures. |
| FSSAI First-Mover Certification | Maharashtra and Gujarat corridors attract multinational technical service presence ahead of formalization. |
| Industrial Marketplace Channel Expansion | Online platforms disintermediate distributor networks for mid-volume extractables-data purchasers. |
Methodological Framework
Bottom-up adhesive application modeling reconciled against top-down vinyl acetate monomer supply tracking forms the analytical core of this study. Primary interviews with food packaging converters, adhesive formulators, polymerization plant managers, and regulatory compliance officers combined with secondary validation from SEC 10-K filings, Cefic industry reports, customs trade data, and FDA 21 CFR 175.105 guidance documents. Triangulation between demand-side procurement patterns and supply-side capacity announcements ensures statistical integrity.
Historical trendline analysis of aqueous dispersion pricing and migration testing protocol development informs projection construction across the analysis window. Segmentation dimensions modeled include formulation chemistry grade, end-use application, compliance certification tier, and regional production hub. CAGRs derive from regression analysis of ethylene-vinyl acetate feedstock costs, laminate manufacturing capacity expansion, and regulatory threshold tightening trajectories. Forecast inputs incorporate mono-material packaging mandate implementation schedules and FSSAI standard formalization timelines.
Vinyl acetate monomer price volatility, regulatory divergence between FDA and EU migration limits, and migration testing specialist scarcity are the dominant revision risks to projection accuracy. Forecasts reflect documented assumptions regarding ethylene supply contract structures and BfR XIV testing protocol adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Russia Food Hydrocolloids Market
Food Components and Additives
Europe Fat Replacers Market
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Polydextrose Market
Food Components and Additives
Modified Starch Market
Food Components and Additives
Natural Fatty Acids Market
Food Components and Additives
Lutein and Zeaxanthin Market
Food Components and Additives
USA Food Premix Market
Food Components and Additives
Edible Films and Coating Market
Food Components and Additives
Italy Food Hydrocolloids Market
Food Components and Additives
India Food Hydrocolloids Market
Food Components and Additives
Polyunsaturated Fatty Acids Market
Food Components and Additives
Europe Food Anti Caking Agents Market
Food Components and Additives
Clean Label Pectin Market
Food Components and Additives
Asia-Pacific Food Hydrocolloids Market
Food Components and Additives
Inulin and Fructooligosaccharide Market