
 Food Hydrocolloids Market | 2026-2036
Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
Food Hydrocolloids Market Analysis
Capital-intensity divergence between integrated biopolymer processors and commodity traders is redrawing competitive boundaries in food hydrocolloids. Cargill, Incorporated leverages its agricultural supply chain to secure raw material streams for gelatin and pectin production. CP Kelco U.S., Inc. anchors its position through specialized fermentation capacity for gellan and xanthan gums. Tate & Lyle plc differentiates via refined texturizing systems tailored for bakery and beverage formulators.
Food hydrocolloids comprise high-molecular-weight polysaccharides and proteins that hydrate in aqueous systems to form viscous solutions or gels, with functional parameters including gel strength measured in Bloom grams and viscosity profiles across pH ranges. Their primary commercial purpose centers on stabilizing emulsions, controlling moisture migration, and delivering target mouthfeel in processed foods. Pectin commands mature margin pools in acidified dairy and fruit preparations where low-methoxyl grades enable calcium-set gelling without added sugar. Carrageenan dominates volume in dairy applications despite ongoing substitution pressure from label-conscious brands. Powdered formats lead across all application channels due to extended shelf stability and precise dosing control in automated manufacturing lines.
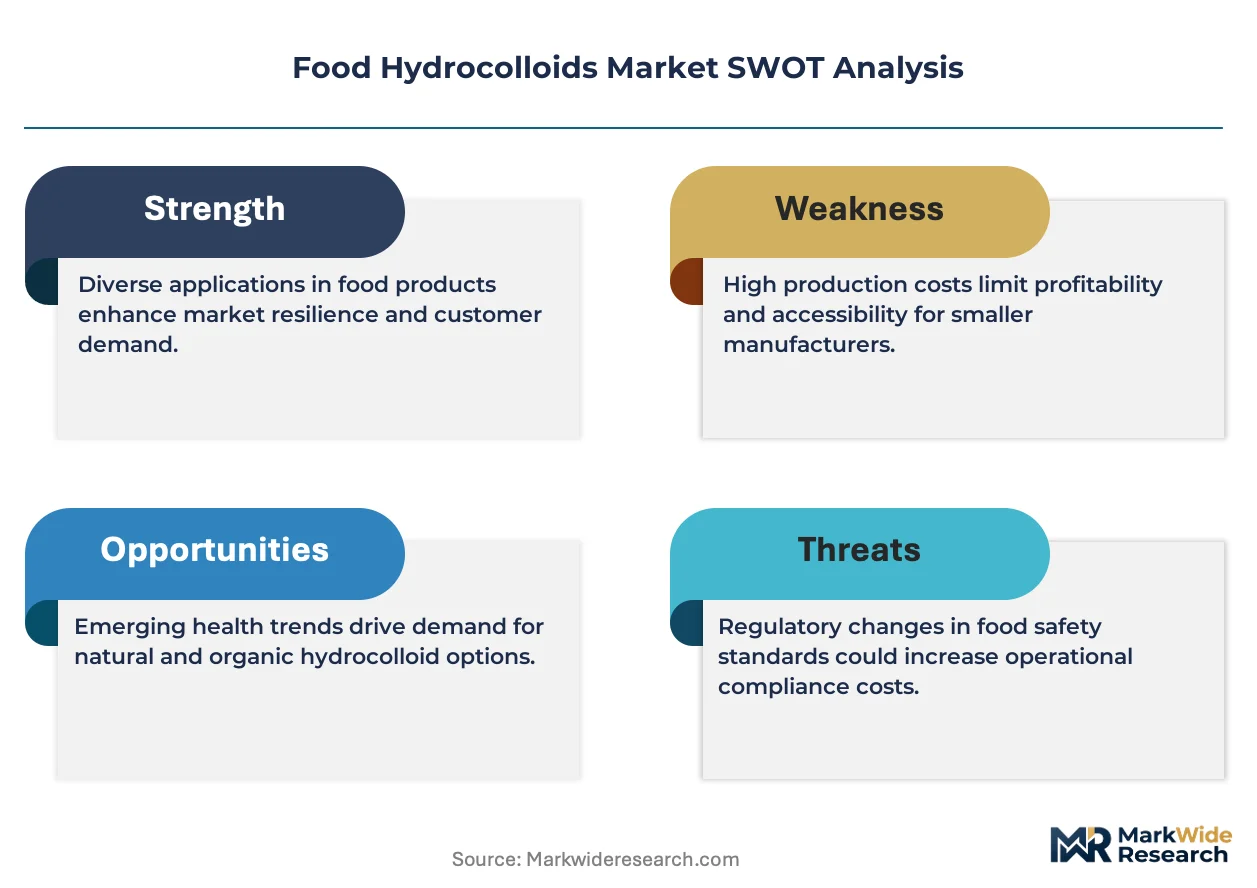
FDA food additive regulations and EFSA re-evaluations of carrageenan safety are reshaping formulation choices and supplier qualification protocols for hydrocolloid buyers. USDA organic certification requirements and EU organic regulation 2018/848 further constrain permitted processing aids and extraction methods for premium-positioned products. Stakeholders must monitor evolving clean-label definitions and regional enforcement variance to align R&D pipelines with divergent compliance thresholds.
Market Dynamics
Clean-label reformulation mandates from EFSA and FDA are compressing carrageenan utilization while accelerating pectin and gellan gum qualification timelines across dairy and beverage formulators.
Growth Catalysts
- EFSA re-evaluation protocols:Accelerated safety reviews for hydrocolloid additives are forcing rapid substitution toward pectin and locust bean gum in European dairy applications.
- Plant-based dairy alternatives:Oat and almond milk processors require stabilizer systems that prevent phase separation and deliver creamy mouthfeel without animal-derived ingredients.
- Calcium-set gelling demand:Low-methoxyl pectin grades enable sugar-free gel formation in acidified yogurts and fruit preparations, opening reformulation pathways for reduced-sugar product lines.
Market Restraints
- Seaweed supply concentration:Carrageenan raw material sourcing clusters in Philippine and Indonesian coastal regions, exposing processors to climate disruption and export policy volatility.
- Fermentation capacity scarcity:Gellan and xanthan gum production requires specialized bioreactor infrastructure with multi-year commissioning timelines, constraining supply elasticity.
- Label-driven substitution pressure:Consumer avoidance of "processed" ingredients is compressing hydrocolloid inclusion rates in premium-positioned clean-label products.
Strategic Opportunities
- Cell-cultured meat scaffolding:Emerging cultivated protein producers require food-grade hydrogel matrices for tissue engineering applications with novel texture specifications.
- USDA organic certification expansion:Permitted processing aid lists under National Organic Program standards create qualification moats for compliant hydrocolloid suppliers.
- Precision fermentation scale-up:Microbial cellulose and novel exopolysaccharide production via engineered strains offers pathway to custom-designed rheological properties.
Industry Challenges
- Food technologist specialization gap:Formulation expertise spanning hydrocolloid synergies, protein interactions, and process scale-up remains concentrated among aging technical workforces.
- Clean-label certification timelines:Non-GMO Project and organic audits require 12-18 month validation cycles that mismatch quarterly procurement planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Hydrocolloids Market |
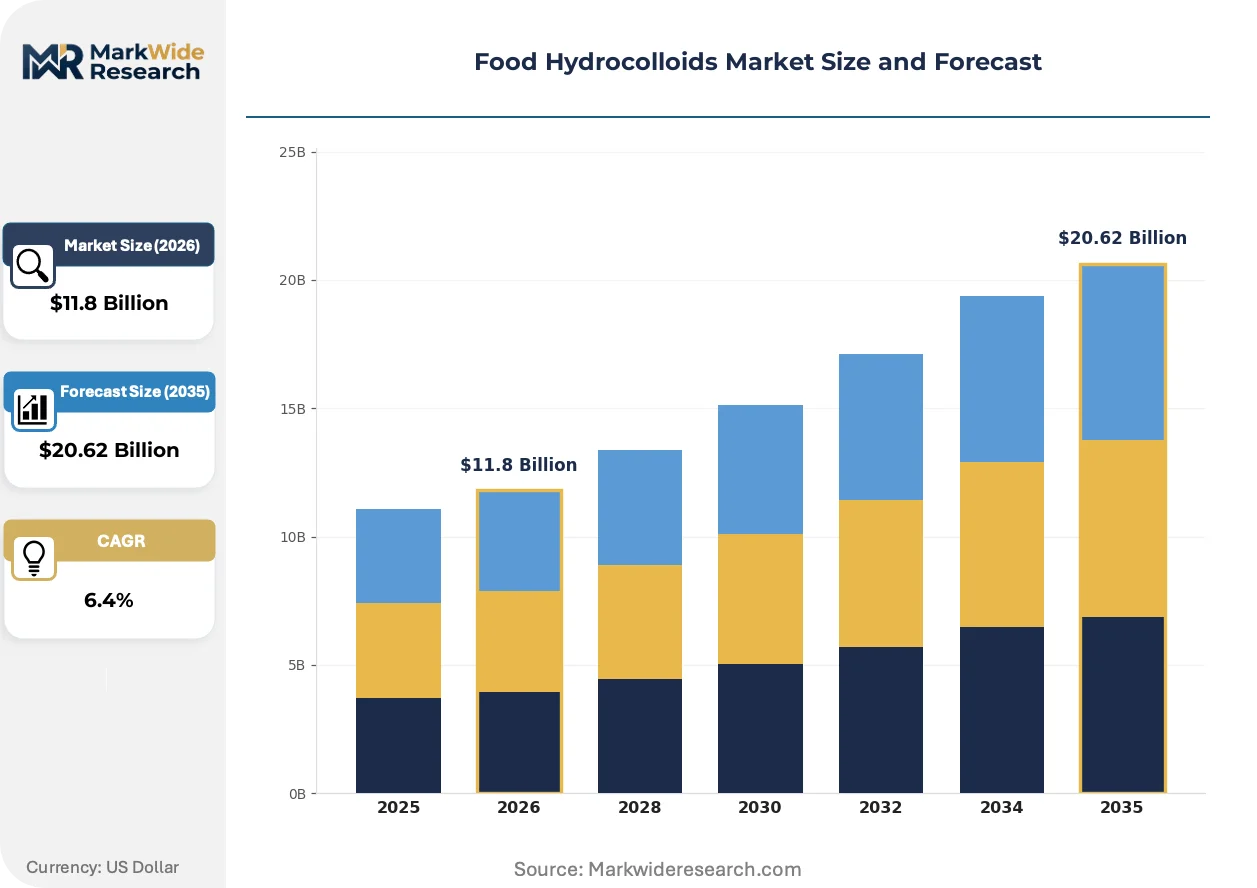
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Agar, Carrageenan, Pectin Application: Dairy Products, Bakery, Beverages, Sauces End User: Food Manufacturers, Restaurants, Retailers, Home Cooks Form: Powder, Liquid, Granule, Sheet |
| Companies Covered | Cargill, Incorporated, Ingredion Incorporated, Archer Daniels Midland Company, International Flavors & Fragrances Inc., DuPont de Nemours, Inc., Kerry Group plc, Tate & Lyle plc, CP Kelco U.S., Inc., Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Hydrocolloids Market Emerging Trajectories
Active reformulation of stabilizer systems is compressing traditional hydrocolloid hierarchies as beverage and dairy processors seek single-ingredient solutions that satisfy multiple functional requirements.
Precision-fermented hydrocolloids are supplanting extraction-dependent gums in high-margin applications. Engineered microbial strains produce tailored polysaccharide structures with consistent molecular weight distributions. Specialty beverage formulators in North America and Western Europe are accelerating adoption, compressing price premiums for plant-extracted alternatives.
EFSA's systematic re-evaluation of food additive safety profiles is reshaping supplier qualification protocols. The 2023-2025 review cycle specifically targets carrageenan and processed Eucheuma seaweed derivatives. Dairy processors across Germany, France, and Italy are preemptively reformulating toward pectin-gellan blends to avoid potential usage restrictions.
Direct-procurement relationships between hydrocolloid processors and plant-based dairy startups are displacing traditional distribution intermediaries. Oat milk and cultured cream specialists negotiate volume commitments and co-development agreements for customized stabilizer systems. This pattern concentrates in California, Netherlands, and United Kingdom where alternative protein venture funding has clustered manufacturing capacity.
Food Hydrocolloids Market Segmentation
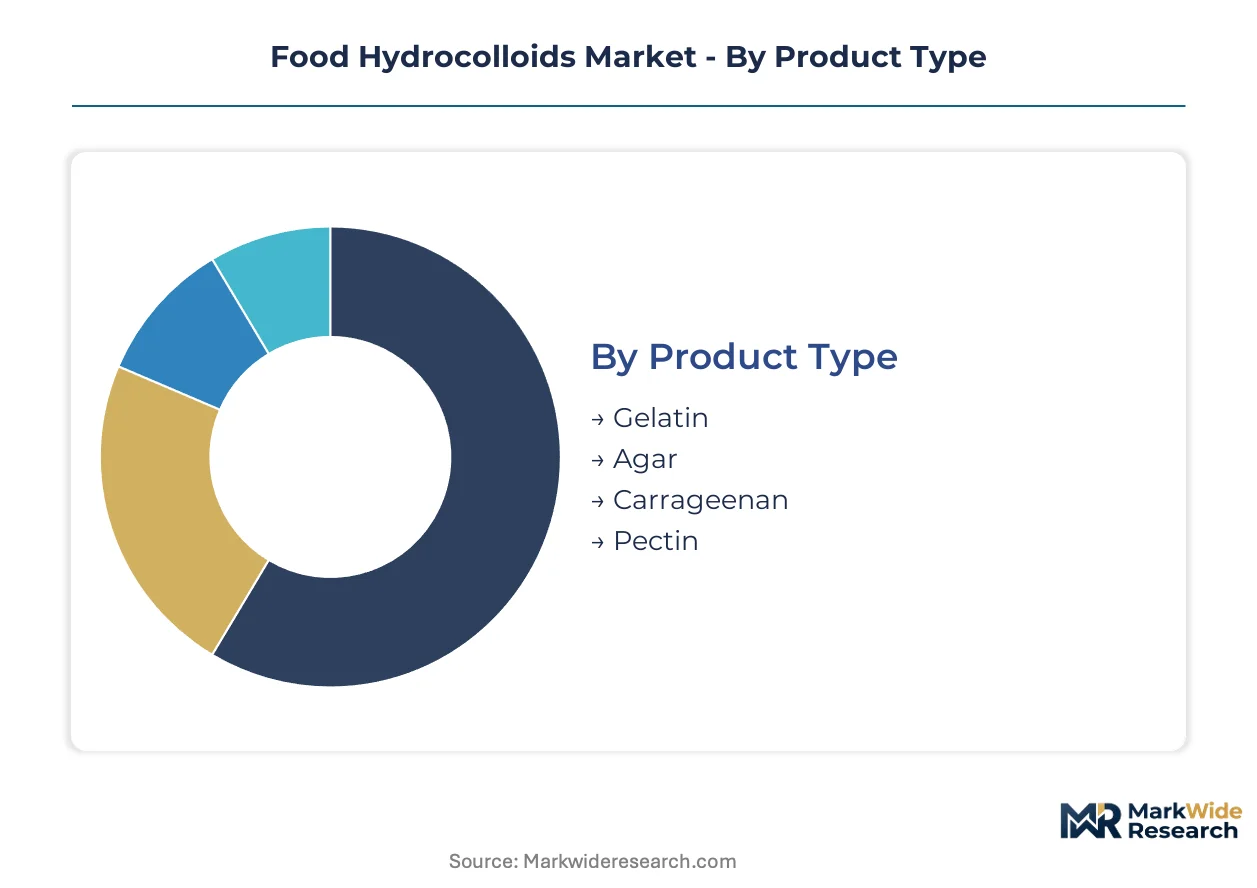
Hydrocolloid procurement decisions diverge sharply across product chemistry, application viscosity requirements, and end-user formulation capabilities. Margin capture depends on matching functional specifications to processing constraints while navigating clean-label certification thresholds.
Product Type:
Margin pools concentrate in pectin and specialty fermentation-derived gums where supply scarcity supports pricing power, while commodity gelatin faces protein alternative pressure.
- Gelatin:Derived from collagen hydrolysis of bovine and porcine sources, with Bloom strength ratings from 50 to 300 grams determining gel elasticity. Demand concentrates in United States confectionery and pharmaceutical capsule manufacturing, though plant-based substitution in gummy candies is compressing volume growth.
- Pectin:Extracted from citrus peel and apple pomace, with high-methoxyl grades requiring sugar-acid gelling and low-methoxyl variants enabling calcium-set systems for reduced-sugar applications. European dairy processors in Germany and France are accelerating qualification timelines amid EFSA additive reviews.
- Agar:Seaweed-extracted polysaccharide with superior thermal hysteresis, serving Japanese and South Korean dessert traditions and microbiological culture media.
- Carrageenan:Sulfated galactan from red algae dominating dairy stabilization, though Philippine supply concentration and label avoidance are forcing reformulation toward blends.
The dominant share belongs to gelatin by volume, while pectin is closing the gap fastest through clean-label dairy adoption.
Application:
Application-level profitability tracks processing intensity and formulation complexity, with beverage stabilization commanding premium pricing over bulk bakery inclusion.
- Dairy Products:Acidified yogurts, processed cheeses, and ice creams require hydrocolloid systems managing protein stability, syneresis control, and freeze-thaw resilience. United States plant-based milk processors in California are driving customized stabilizer development for oat and almond bases.
- Beverages:Pulp suspension, cloud stability, and mouthfeel modulation in juice, nectar, and flavored water systems demand precise hydration kinetics. Brazilian and Mexican citrus processors represent concentrated demand for beverage-grade pectin.
- Bakery:Moisture retention in extended-shelf-life breads and cake structure maintenance utilize hydrocolloid synergies with starch and protein networks.
- Sauces:Viscosity building and emulsion stability in pourable and spoonable dressings, with hot-fill processing requirements constraining gum selection.
Dairy applications retain the largest value share, though beverages are expanding most quickly through premium functional drink proliferation.
End User:
End-user sophistication determines service intensity and technical support margins, with food manufacturers requiring specification documentation that retailers and foodservice bypass.
- Food Manufacturers:Industrial-scale formulators with in-house R&D capabilities, quality systems, and multi-year supply agreements. These buyers dominate volume procurement in United States, Netherlands, and United Kingdom plant-based protein manufacturing clusters.
- Restaurants:Commercial kitchens and commissary operations utilizing hydrocolloids for texture modification, plating gels, and sous vide applications in high-end dining.
- Retailers:Private-label brand owners specifying hydrocolloid inclusion for store-brand dairy alternatives, baked goods, and prepared sauces.
- Home Cooks:Specialty ingredient consumers purchasing agar, gelatin, and pectin for artisanal preservation and molecular gastronomy experiments through specialty food channels.
Food manufacturers command the dominant procurement volume, while restaurants are gaining share fastest through modernist cuisine technique diffusion.
Form:
Form selection reflects automation compatibility and shelf stability requirements, with powder formats offering the broadest manufacturing integration.
- Powder:Dried, milled hydrocolloid with extended ambient stability and precise gravimetric dosing in automated processing lines. Dominates industrial procurement across all hydrocolloid chemistries.
- Liquid:Pre-hydrated dispersions reducing dust exposure and hydration time for high-throughput beverage and dairy operations.
- Granule:Intermediate particle size offering faster dispersion than fine powders with reduced clumping tendency in high-shear mixing environments.
- Sheet:Traditional agar presentation for East Asian culinary applications and specialized microbiological media preparation.
Powder forms hold the dominant position across all segments, while liquid concentrates are climbing the fastest through dairy and beverage processor efficiency demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European processors command pricing premiums for clean-label pectin while Southeast Asian carrageenan suppliers absorb raw material volatility. This asymmetry reflects divergent regulatory stringency and supply chain concentration across producing regions.
United States
California oat milk processors and Illinois dairy formulators drive customized stabilizer procurement for plant-based alternatives. FDA food additive regulations and USDA organic certification requirements constrain permitted processing aids for premium-positioned products. Chicago and Minneapolis anchor Midwest hydrocolloid distribution infrastructure serving beverage and bakery manufacturing clusters.
Germany
Bavarian dairy processors and North Rhine-Westphalia ingredient distributors accelerate pectin qualification timelines amid EFSA additive safety reviews. EU organic regulation 2018/848 and national implementation standards constrain extraction methods for certified products. Frankfurt chemical trading networks facilitate hydrocolloid sourcing for Central European formulators.
China
Shandong Peninsula seaweed processors and Yangtze River Delta beverage manufacturers dominate regional agar and carrageenan production capacity. SAMR food safety standards and GB quality specifications govern additive usage in processed foods. Qingdao coastal processing facilities face climate disruption risks affecting red algae harvest cycles.
Brazil
São Paulo citrus processors and Minas Gerais dairy cooperatives concentrate demand for beverage-grade pectin and yogurt stabilizers. ANVISA food additive regulations align with Mercosur harmonization protocols for regional trade. Campinas technical centers support formulation development for Latin American beverage applications.
Netherlands
Randstad ingredient trading hubs and Brabant food technology parks specialize in hydrocolloid blending and clean-label system development. EFSA guidance on processed seaweed derivatives drives reformulation toward pectin-gellan combinations in Dutch dairy applications. Wageningen research clusters advance precision fermentation for novel polysaccharide production.
Food Hydrocolloids Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the food hydrocolloids sector. Integrated agricultural processors leverage captive raw material streams to secure gelatin and pectin supply positions, while specialized fermentation operators command premium pricing for microbial gum production. The market structure separates into three strategic archetypes: diversified ingredient conglomerates, focused biopolymer specialists, and regional extraction processors. Competitive dynamics center on backward integration into seaweed farming and citrus peel sourcing, alongside co-development partnerships with plant-based dairy startups.
Among diversified ingredient conglomerates, Cargill, Incorporated and Archer Daniels Midland Company occupy positions spanning multiple hydrocolloid chemistries and geographic markets. Tate & Lyle plc exemplifies the texturizing systems specialist archetype, while CP Kelco U.S., Inc. represents focused fermentation capacity for gellan and xanthan production. Kerry Group plc anchors the integrated solutions provider position, and Ingredion Incorporated sits within the modified starch-hydrocolloid hybrid space. These named entities illustrate how competitive positioning fragments across raw material control, processing technology, and formulation service capabilities rather than concentrating in single-dominant players.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| International Flavors & Fragrances Inc. |
| DuPont de Nemours, Inc. |
| Kerry Group plc |
| Tate & Lyle plc |
| CP Kelco U.S., Inc. |
| Koninklijke DSM N.V. |
| Others |
Supply Flow & Price Mechanics
USDA organic certification requirements and EFSA additive safety protocols simultaneously gate supplier qualification and stratify price tiers across food hydrocolloid procurement. These dual regulatory filters compress commodity-grade margins while amplifying premiums for certified clean-label alternatives.
Pricing Analysis
Configured-to-order pricing for customized stabilizer systems commands spreads exceeding standard-grade pectin and gelatin quotations. Three-tier pricing structure across premium, standard, and economy levels tracks certification status, with Non-GMO Project and organic audits adding 12-18 month validation cycles that mismatch quarterly procurement planning. Price differentiation hinges on fermentation-derived specialty gums versus extraction-dependent commodities. Cost compression in carrageenan is intensifying because Philippine supply concentration and label-driven substitution pressure force reformulation toward pectin-gellan blends. Food manufacturers with multi-year supply agreements exhibit lowest price sensitivity, while retailers and foodservice operators remain most exposed to spot-market volatility.
Supply Chain Analysis
Inventory cycles for red algae-derived carrageenan stretch across monsoon-dependent harvest windows in the Philippines and Indonesia, constraining just-in-time availability. Raw material sourcing draws from citrus peel processors in Brazil and Florida for pectin, bovine and porcine rendering facilities in the United States and Europe for gelatin, and coastal seaweed farming operations in Southeast Asia for agar and carrageenan. Single-source vulnerability concentrates in Philippine carrageenan extraction capacity, where climate disruption and export policy volatility threaten continuity. Distribution runs through Chicago and Minneapolis distribution infrastructure for North American beverage and bakery manufacturing clusters, Rotterdam and Hamburg trading hubs for European dairy formulators, and Qingdao processing facilities serving Asia-Pacific demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise spanning hydrocolloid synergies, protein interactions, and process scale-up remains concentrated among aging technical workforces, creating acute capability scarcity that constrains innovation velocity across the sector.
For Market Incumbents: Fortify backward integration into citrus peel sourcing and seaweed farming operations to secure captive raw material streams against Philippine supply concentration risks. Expand fermentation capacity for gellan and xanthan production in North American and European facilities to capture clean-label substitution demand. Prioritize co-development partnerships with California and Netherlands plant-based dairy startups to lock in volume commitments before qualification timelines extend further. For New Entrants and Emerging Players: Lead with precision-fermented hydrocolloid production targeting beverage and dairy applications where engineered microbial strains offer consistent molecular weight distributions. White-space opportunities concentrate in cell-cultured meat scaffolding hydrogels and USDA organic-certified processing aids where incumbent qualification moats remain underdeveloped. Establish direct-procurement relationships with oat milk and cultured cream specialists in California, Netherlands, and United Kingdom manufacturing clusters. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fermentation specialists possessing specialized bioreactor infrastructure and multi-year commissioning timelines that constrain supply elasticity. Long-term viability across the analysis window favors precision-fermentation platforms over extraction-dependent operations facing raw material volatility. Watch EFSA additive safety review outcomes as inflection indicators for carrageenan substitution velocity and pectin-gellan blend adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Farming | Captive red algae supply from Philippine and Indonesian coastal operations insulates against climate disruption. |
| Precision Fermentation Scale-Up | Engineered microbial strains at Wageningen and North Carolina facilities produce tailored polysaccharide structures. |
| Clean-Label Certification Investment | Non-GMO Project and USDA organic audits create qualification moats for compliant hydrocolloid suppliers. |
| Co-Development Partnerships | Direct volume commitments with California oat milk processors displace traditional distribution intermediaries. |
| Formulation Technical Service Expansion | In-house R&D capabilities spanning hydrocolloid synergies address aging workforce specialization gaps. |
Methodological Framework
A spread of perspectives from food technologists at dairy and beverage manufacturers, procurement leads at plant-based protein startups, hydrocolloid R&D directors, distribution channel partners, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA food additive regulations, EFSA safety evaluation protocols, USDA organic certification standards, SEC filings from diversified ingredient conglomerates, and customs trade data tracking citrus peel and seaweed derivative flows. Bottom-up demand modeling across application segments triangulated against top-down supply capacity assessments.
Segmentation dimensions modeled include hydrocolloid chemistry type, application viscosity requirements, end-user formulation capabilities, and clean-label certification thresholds across the projection horizon. CAGRs derived from weighted scenario analysis incorporating regulatory timeline uncertainty, raw material supply elasticity constraints, and substitution elasticity parameters for carrageenan-to-pectin reformulation. Industry-specific forecast inputs encompassed fermentation capacity commissioning timelines and EFSA additive review cycle progression.
The analysis sits within stated boundaries; outcomes outside EFSA regulatory decisions, Philippine seaweed harvest stability, and precision fermentation yield improvements would require recalibration. Forecasts reflect documented assumptions regarding clean-label definition evolution and regional enforcement variance. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
Natural Antioxidants Market
Food Components and Additives
Food Texture Market
Food Components and Additives
North America Native Starch Market
Food Components and Additives
Astaxanthin Market
Food Components and Additives
Food Antimicrobial and Antioxidants Market
Food Components and Additives
Modified Starch Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
South Africa Food Hydrocolloids Market
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
India Food Hydrocolloids Market
Food Components and Additives
Food Premix Market
Food Components and Additives
Europe Food Anti Caking Agents Market
Food Components and Additives
North America Food Hydrocolloids Market
Food Components and Additives
Asia Pacific Food Grade Carbon Dioxide Market
Food Components and Additives
Europe Food Premix Market