
 Europe Food Premix Market | 2026-2036
Europe Food Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Premix Market Foresight
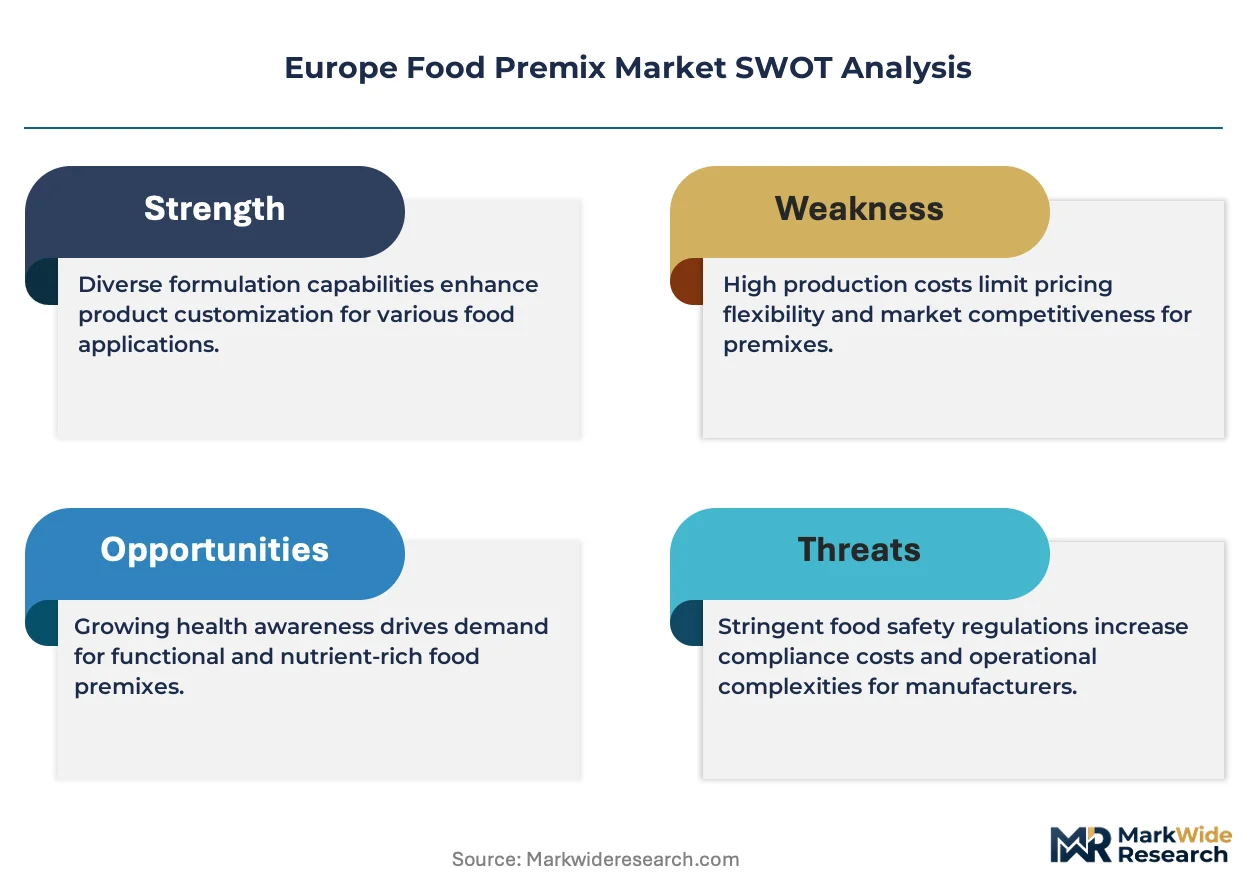
Precision dosing technology is fragmenting traditional batch-compounding methods across European premix operations. DSM-Firmenich leverages integrated nutrition science platforms to sustain formulation leadership in vitamins and minerals. Glanbia plc anchors its position through dairy-centric premix specialization, while BASF SE competes on carotenoid and omega-3 microencapsulation capabilities.
Europe food premix denotes industrially compounded micronutrient blends—typically containing vitamins A, D, E, K, B-complex, and trace minerals at 0.1–2.0% inclusion rates—manufactured via spray-drying, fluid-bed agglomeration, or extrusion-spheronization for homogeneous dispersion in finished foods. These formulations primarily fortify processed foods against nutritional deficiencies and support clean-label positioning. Vitamin premixes command the deepest margin pools due to stability engineering complexity and EFSA health claim substantiation requirements, while amino acid blends for plant-based meat alternatives represent the fastest-expanding application segment. Powder formats dominate bakery and dairy lines for shelf stability, though liquid premixes are displacing dry systems in high-speed beverage fortification where instant solubility matters.
EFSA nutrient reference values, EU Regulation 1169/2011 on food information to consumers, and the EU Green Deal Farm to Fork strategy collectively shape compositional thresholds, labeling precision, and sustainable sourcing mandates across the premix value chain. EFSA health claim authorization processes directly determine which micronutrient combinations food manufacturers can market with physiological benefit statements. Stakeholders must monitor evolving Novel Food catalog updates and carbon footprint disclosure requirements under CSRD to anticipate reformulation investments and sourcing geography decisions.
Market Dynamics
EFSA's 2023 nutrient reference value revisions are forcing dairy and bakery manufacturers across Germany, France, and the Netherlands into accelerated reformulation cycles, compressing premix development timelines from eighteen months to under nine months.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Mandatory carbon footprint disclosures under CSRD are driving food manufacturers toward premix suppliers with verified sustainable sourcing credentials, particularly for vitamin D3 and omega-3 derivatives.
- Precision dosing technology:Continuous manufacturing lines in beverage production are displacing batch-compounding methods, creating pull for liquid premix systems with real-time nutrient verification.
- Plant-based meat alternatives:Amino acid fortification requirements for texture and complete protein claims are expanding premix volumes in extruded protein manufacturing across Denmark and Sweden.
Market Restraints
- Vitamin stability engineering costs:Microencapsulation of heat-sensitive B-vitamins for bakery applications requires specialized fluid-bed equipment, elevating capital intensity for mid-tier premix compounders.
- Carotenoid supply concentration:Beta-carotene and lutein raw material sourcing clusters in China and India expose European formulators to tariff volatility and shipping corridor disruptions.
- EFSA health claim substantiation timelines:Novel nutrient combination approvals average thirty-six months, blocking rapid market entry for innovative premix formulations targeting immune or cognitive positioning.
Strategic Opportunities
- Poland and Romania food manufacturing:Underpenetrated processed dairy and infant nutrition sectors in these markets offer first-mover positioning for premix suppliers with local technical service capabilities.
- Precision fermentation-derived nutrients:Convergence of synthetic biology with premix formulation is enabling bio-identical vitamin production with traceable carbon credentials aligned to EU Green Deal targets.
- Direct-to-manufacturer digital platforms:E-procurement channels for customized micronutrient blends are compressing distributor layers and capturing margin previously allocated to regional chemical distributors.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in spray-drying parameter optimization and nutrient-matrix interaction modeling is concentrated among retiring technical staff at established compounders.
- Legacy ERP integration:Premix manufacturers with decades-old batch record systems face friction connecting to customer demand-planning platforms requiring real-time inventory visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Premix Market |
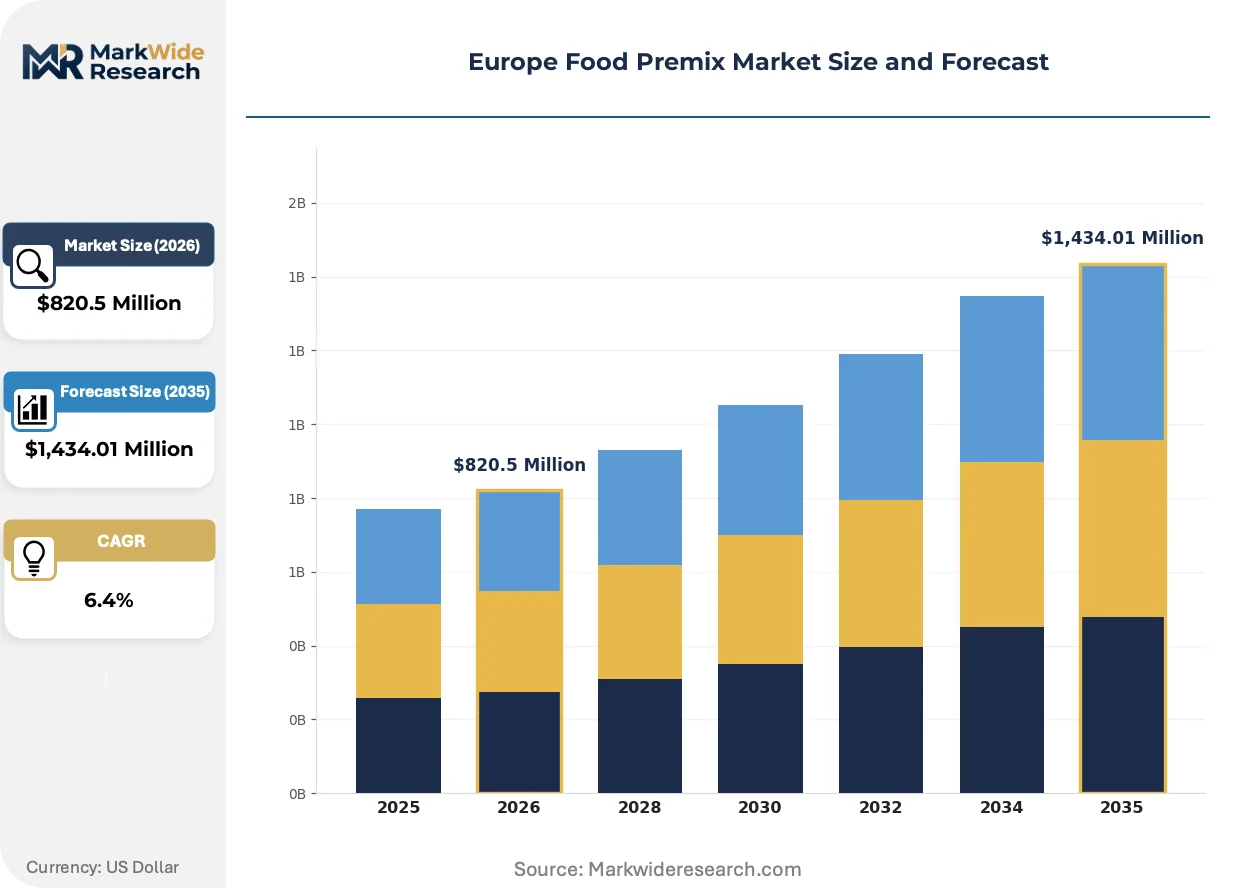
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,434.01 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Enzymes Application: Bakery, Dairy, Beverages, Convenience Foods Form: Powder, Liquid, Granular, Tablet End User: Food Manufacturers, Retailers, Wholesalers, Institutional Buyers |
| Companies Covered | DSM-Firmenich, Glanbia plc, BASF SE, Corbion, SternVitamin, Vitablend, Archer Daniels Midland Company, Barentz, Jubilant Life Sciences, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Premix Market Shifts & Advancements
Active compression of development cycles and regulatory data requirements are reshaping how premix formulators invest in stability science and customer co-development capabilities.
Microencapsulation via complex coacervation is hybridizing traditional spray-drying methods for heat-sensitive vitamins. Premium chocolate and UHT dairy manufacturers in Belgium and Switzerland are adopting these systems at pilot scale. The technology is hybridizing cost structures by reducing overage requirements from fifteen percent to under five percent while extending shelf-life claims.
CSRD carbon footprint disclosure mandates are compelling premix suppliers to deploy blockchain-tracked supply chain documentation. EFSA audit readiness now requires batch-level traceability from raw material harvest through finished goods release. Vitamin premix categories face the steepest compliance investments, with dairy fortification applications in France and Germany leading implementation timelines.
Consolidated food manufacturers are unbundling technical service from premix procurement, contracting directly with formulation specialists while sourcing commodity micronutrients through separate tenders. This bifurcation is fragmenting historical full-service relationships and pressuring mid-tier compounders to specialize or exit. The shift is most visible in German bakery and Dutch infant nutrition manufacturing, where procurement teams now separate innovation partnerships from volume supply agreements.
Europe Food Premix Market Segmentation
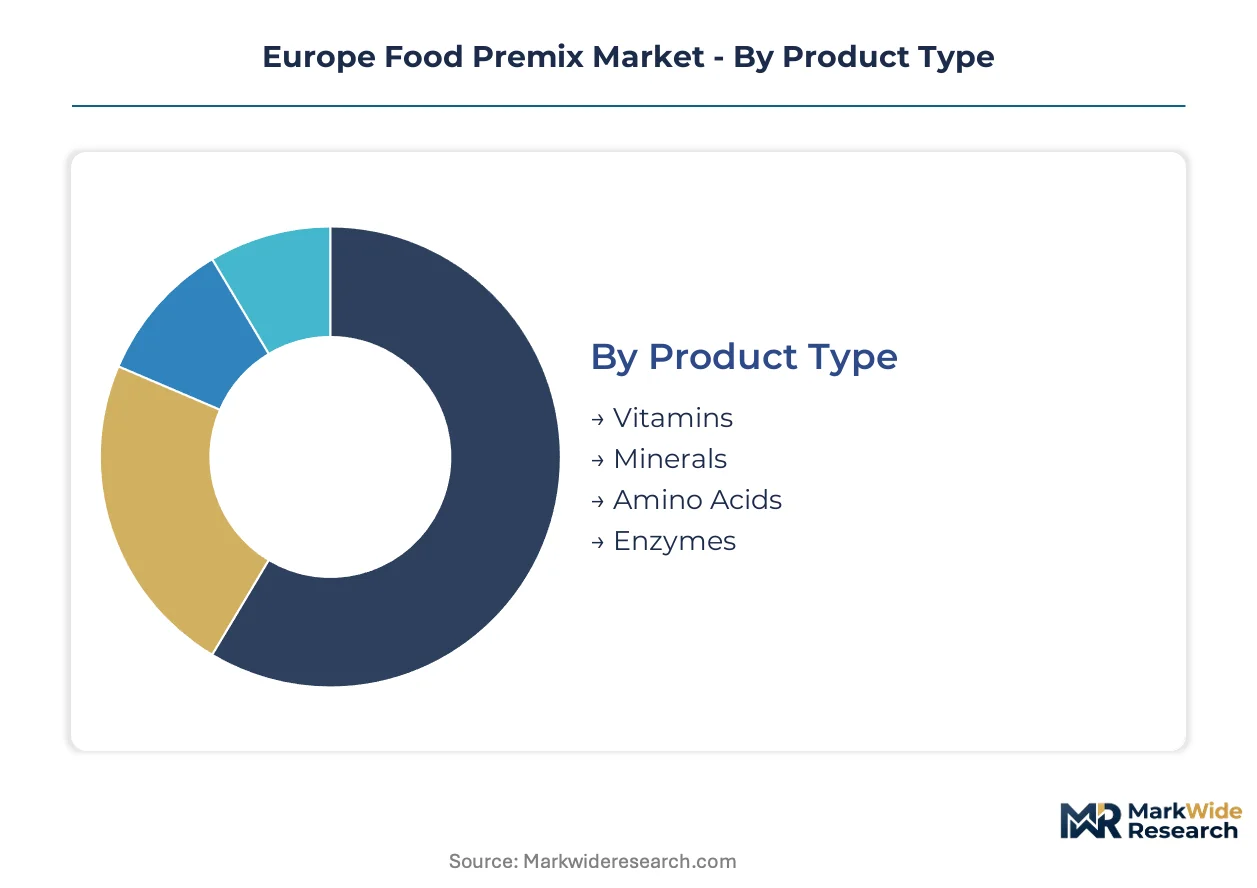
Segmentation in the Europe Food Premix Market reveals distinct technical requirements across micronutrient categories and end-use applications. Manufacturers align formulation investments with EFSA compliance pathways and processing line constraints specific to each segment.
Product Type:
Use-case spectrum spans clinical nutrition fortification through clean-label functional positioning, with stability engineering demands varying sharply by molecular category.
- Vitamins:Complex blends of fat-soluble (A, D, E, K) and water-soluble (B-complex, C) compounds requiring microencapsulation against thermal degradation. German and French dairy processors drive volumes as EFSA reference value revisions tighten minimum inclusion thresholds for health claim eligibility.
- Minerals:Chelated and inorganic trace element formulations (iron, zinc, selenium, iodine) addressing bioavailability optimization. Bakery applications across the Netherlands concentrate demand where mineral-fortified flour mandates intersect with processing tolerance requirements.
- Amino Acids:Essential and conditionally essential amino acid premixes for protein completeness claims in plant-based meat alternatives. Danish and Swedish extruded protein manufacturers represent the steepest expansion trajectory for this category.
- Enzymes:Processing aids and digestive enzyme blends for gluten modification, lactose reduction, and texture optimization in convenience food manufacturing.
Established volume favors vitamins; emerging adoption favors amino acids.
Application:
Processing environment temperature and moisture exposure dictate formulation architecture across end-use categories.
- Bakery:Heat-stable vitamin and mineral premixes engineered for oven temperatures exceeding 200°C. Belgian and Swiss premium chocolate manufacturers pilot complex coacervation microencapsulation to reduce overage requirements from fifteen percent to under five percent.
- Dairy:UHT-stable and fermentation-compatible micronutrient systems for fluid milk, yogurt, and cheese fortification. French and German processors lead implementation of blockchain-tracked supply chain documentation under CSRD carbon disclosure mandates.
- Beverages:Instant-solubility liquid and powder premixes for high-speed manufacturing lines. Continuous dosing technology is displacing batch-compounding methods across European beverage operations.
- Convenience Foods:Shelf-stable micronutrient blends for ready meals, soups, and sauces with extended distribution timelines.
Processing intensity anchors bakery and dairy as volume leaders; beverage manufacturing is climbing the fastest on precision dosing adoption.
Form:
Physical state determines dispersion kinetics, equipment compatibility, and shelf-life engineering investment.
- Powder:Spray-dried and fluid-bed agglomerated formats dominating bakery and dairy lines for shelf stability and homogeneous blending. Powder systems retain the largest demand share across European premix consumption.
- Liquid:Pumpable concentrates with real-time nutrient verification for beverage fortification. Liquid premixes are gaining traction where instant solubility and continuous manufacturing integration matter.
- Granular:Free-flowing agglomerates for reduced dusting and improved handling in high-volume food manufacturing environments.
- Tablet:Compressed premix formats for controlled-release applications and direct compression into finished nutritional products.
Legacy infrastructure favors powder; line modernization favors liquid.
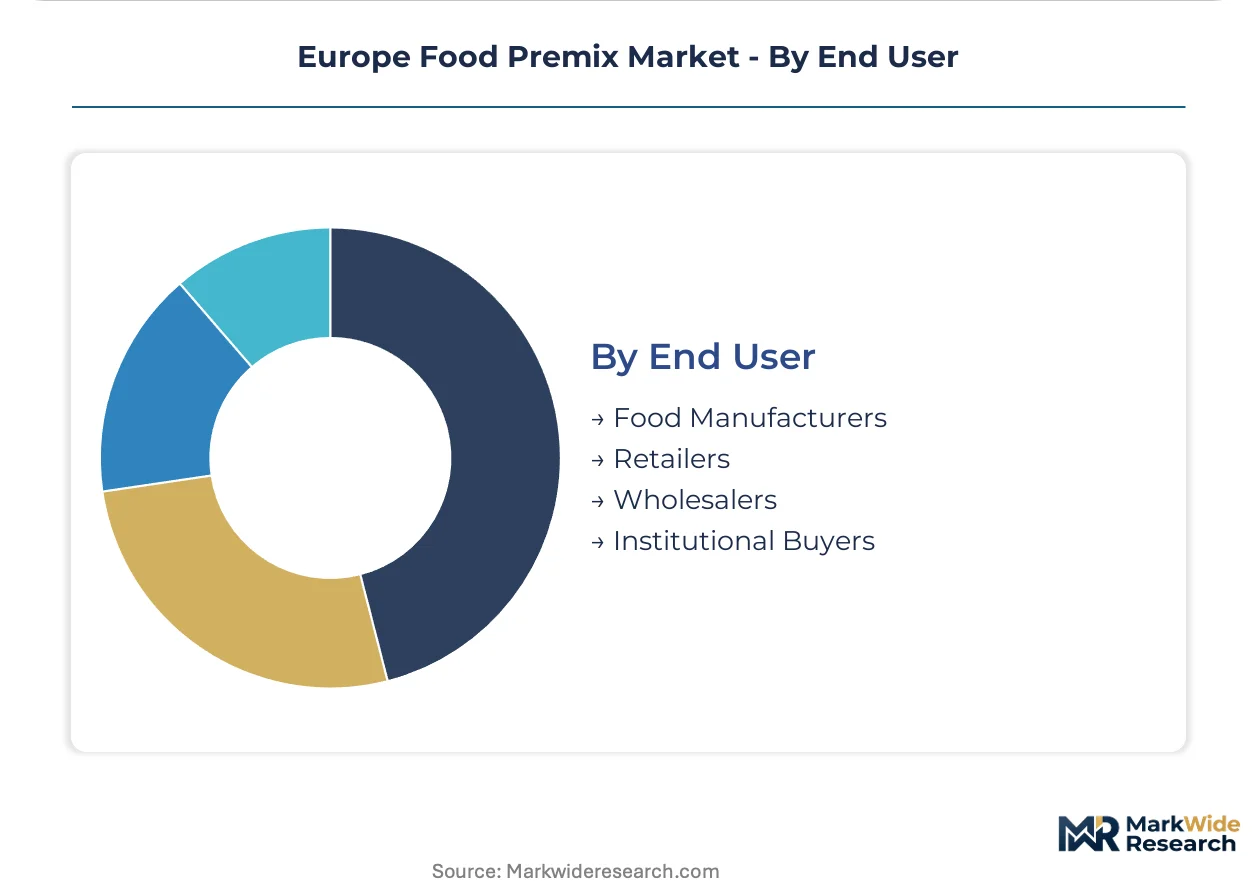
End User:
Procurement sophistication and technical service requirements stratify the customer base across formulation partnership models.
- Food Manufacturers:Integrated premix consumers with dedicated formulation chemists and quality assurance protocols. Consolidated manufacturers in German bakery and Dutch infant nutrition are unbundling technical service from commodity procurement.
- Retailers:Private-label brand owners contracting for finished fortification solutions with packaging and regulatory documentation included.
- Wholesalers:Distribution intermediaries serving smaller food processors with standardized premix SKUs and technical support limitations.
- Institutional Buyers:Healthcare, education, and military catering procurement with bulk volume requirements and specification compliance priorities.
Direct technical engagement favors food manufacturers; margin compression favors wholesaler consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement sophistication clusters among consolidated dairy and bakery manufacturers across Western Europe, while emerging food processing hubs in Central and Eastern Europe attract premix suppliers establishing local technical service capabilities.
Germany
Reformulation pressure from EFSA's 2023 nutrient reference value revisions accelerates premix procurement cycles among dairy processors. The EU Green Deal Farm to Fork strategy mandates carbon footprint disclosures that favor suppliers with blockchain-tracked supply chains. Bavarian and North Rhine-Westphalian dairy clusters drive volume for vitamin D3 and B-complex fortification systems.
France
Premium chocolate manufacturers in Belgium-adjacent border regions pilot complex coacervation microencapsulation for heat-sensitive vitamins. ANSM oversight of novel food ingredients intersects with EFSA health claim substantiation timelines. The Île-de-France food manufacturing corridor concentrates demand for UHT-stable premixes in fluid milk and yogurt applications.
Netherlands
Mineral-fortified flour mandates sustain bakery premix consumption across Dutch milling operations. REACH compliance requirements shape raw material sourcing decisions for trace element formulations. The Randstad logistics hub enables just-in-time premix delivery to high-speed manufacturing lines serving export markets.
Poland
Underpenetrated processed dairy and infant nutrition sectors attract first-mover premix suppliers building local formulation laboratories. The country's national food safety authority aligns with EU Regulation 1169/2011 on food information to consumers. Warsaw and Łódź manufacturing zones emerge as cost-competitive alternatives to Western European compounding.
Denmark
Extruded protein manufacturers drive amino acid premix volumes for plant-based meat alternative texture optimization. Danish veterinary and food administration oversight of novel protein ingredients creates regulatory clarity for fermentation-derived nutrient suppliers. Copenhagen-area food technology clusters integrate precision fermentation with premix formulation capabilities.
Europe Food Premix Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated vendor base where consolidated manufacturers unbundle technical service from commodity procurement. The market structure tilts toward scale-driven compounders with integrated nutrition science platforms and mid-tier specialists with dairy-centric or carotenoid-focused portfolios. Three archetypes dominate: full-service formulation partners, commodity micronutrient suppliers, and precision-dosing technology integrators. Competitive moves concentrate on M&A for geographic expansion and strategic partnerships for precision fermentation-derived nutrient pipelines.
Within the full-service formulation tier, DSM-Firmenich and Glanbia plc occupy positions as archetypal integrated nutrition science platforms. BASF SE exemplifies the specialty chemical compounder archetype with microencapsulation capabilities. These three anchors represent divergent strategic postures: nutrition science integration, dairy-centric specialization, and chemical process engineering respectively.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Glanbia plc |
| BASF SE |
| Corbion |
| SternVitamin |
| Vitablend |
| Archer Daniels Midland Company |
| Barentz |
| Jubilant Life Sciences |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp freight corridor volatility feeds directly into vitamin premix cost structures, amplifying price spreads between bulk commodity micronutrient suppliers and microencapsulation specialists serving French dairy processors. CSRD-mandated carbon documentation requirements widen these differentials further as blockchain-tracked supply chains command procurement premiums from EFSA-compliant manufacturers.
Pricing Analysis
Cost-plus contracts indexed to vitamin A and D3 spot markets dominate long-term supply agreements between German dairy processors and premix compounders. Three-tier pricing structure across premium, standard, and economy levels separates EFSA health claim-substantiated formulations from commodity vitamin blends and unbranded mineral premixes. Pricing pressure stems from mid-tier compounders competing on overage reduction via complex coacervation technology. Small Dutch bakery operations exhibit highest price sensitivity; Swiss premium chocolate manufacturers show lowest.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements as premix compounders manage working capital through supply-chain finance facilities. Raw material sourcing clusters in China for beta-carotene, India for B-vitamin intermediates, and Germany for chelated minerals create geographic concentration risks. Single-source vulnerability in carotenoid feedstocks exposes European formulators to Red Sea shipping disruptions. Distribution runs through regional chemical distributors unbundling into direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe food premix markets reward service-attach models where formulation partnerships and regulatory documentation subscriptions expand faster than commodity micronutrient volumes. Technical service contracts for EFSA compliance support now generate recurring revenue streams exceeding hardware-like premix sales growth.
For Market Incumbents: Pre-empt unbundling of technical service from commodity procurement by embedding blockchain-tracked carbon documentation into standard offerings. DSM-Firmenich and Glanbia plc face disintermediation from direct-to-manufacturer digital platforms; vertical integration into precision fermentation-derived vitamin production secures supply and margin. Certification investment in EFSA novel food substantiation capabilities defends against mid-tier specialists. For New Entrants and Emerging Players: Establish a beachhead in Polish processed dairy and Romanian infant nutrition sectors where local formulation laboratories remain scarce. Underpenetrated amino acid premix demand from Danish extruded protein manufacturers offers fastest volume accumulation. Direct-to-manufacturer e-procurement platforms with real-time nutrient verification compress distributor layers and capture margin. For Investors and Strategic Acquirers: EFSA's 2023 nutrient reference value revisions reshape the acquisition landscape toward compounders with accelerated reformulation capabilities and CSRD-ready supply chain infrastructure. Five-to-ten year viability favors precision fermentation integration and dairy-centric specialization over commodity micronutrient trading. Watch for Novel Food catalog updates as inflection signals for bio-identical nutrient pipeline valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Integration | Bio-identical vitamin production aligns with EU Green Deal carbon disclosure mandates. |
| Blockchain Supply Chain Documentation | CSRD-compliant traceability from raw material harvest through finished goods release. |
| Complex Coacervation Microencapsulation | Heat-sensitive vitamin stability reduces overage requirements for Belgian chocolate manufacturers. |
| Direct-to-Manufacturer Digital Platform | E-procurement channels compress distributor layers in German bakery procurement. |
| Local Formulation Laboratory Buildout | Technical service capabilities capture first-mover positioning in Polish dairy sectors. |
Research Methodology
Desk research of EFSA health claim databases, EU Regulation 1169/2011 implementation guidance, and CSRD technical standards preceded structured interviews with premix formulation chemists, dairy processor procurement directors, and precision fermentation technology specialists. Secondary validation drew from customs trade data, REACH registration dossiers, and industry association technical publications. Bottom-up volume modeling triangulated against top-down market sizing across vitamin, mineral, amino acid, and enzyme categories.
Assumptions held EFSA nutrient reference values and EU Green Deal carbon disclosure timelines fixed across the analysis window, while precision fermentation adoption rates and continuous manufacturing line penetration varied. Segmentation dimensions modeled included micronutrient category, application processing environment, physical form, and end-user procurement sophistication. CAGRs derived from regression analysis of historical premix consumption against dairy, bakery, and beverage production indices, with EFSA reformulation cycle compression as a demand accelerator.
Sensitivities concentrate around EFSA health claim authorization timelines, carotenoid supply corridor disruptions, and precision fermentation cost parity achievements. Forecasts reflect assumptions on regulatory implementation pace and technology adoption curves without guaranteeing outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Argentina Food Hydrocolloids Market
Food Components and Additives
South Africa Food Hydrocolloids Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
Russia Food Hydrocolloids Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
China Food Hydrocolloids Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
Food Coating Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
United Kingdom Food Hydrocolloids Market
Food Components and Additives
Fractionated Fatty Acid Market
Food Components and Additives
Food Grade Silica Market
Food Components and Additives
Mexico Food Hydrocolloids Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
Fructo-Oligosaccharides (FOS) Market
Food Components and Additives
Flavonoids Market