
 Germany Food Hydrocolloids Market | 2026-2036
Germany Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Food Hydrocolloids Market Foresight
Modular ingredient bundling is shifting how German food manufacturers procure hydrocolloid systems. Kerry Group plc leverages integrated taste-and-texture platforms to anchor long-term supply relationships with industrial bakeries. Cargill Incorporated competes through backward integration into guar gum sourcing, sustaining cost discipline across its European distribution network.
Food hydrocolloids comprise high-molecular-weight polysaccharides and proteins that hydrate in aqueous systems to modify viscosity, gelation, and water-binding properties, typically functioning at concentrations between 0.1% and 2.0% by weight. Gelatin dominates the product type landscape due to its unmatched thermoreversible gelation profile in confectionery and dairy matrices, though pectin gains share as German beverage producers pivot toward plant-sourced stabilizers. The application dimension shows dairy and desserts commanding the largest volume pool, while sauces and dressings represent the fastest-expanding segment as cold-prepared condiment formats multiply.
German hydrocolloid formulations fall under EFSA food additive evaluations, BfR contaminant guidelines, and EU Regulation 1333/2008 on food improvers, with ECHA REACH compliance additionally governing imported raw material purity. These frameworks elevate documentation burdens for non-EU suppliers while creating specification premiums for domestic-certified producers. Stakeholders must monitor evolving EU novel food classifications for emerging fermentation-derived hydrocolloids and calibrate R&D pipelines against tightening clean-label thresholds.
Market Dynamics
The EU Green Deal's Farm-to-Fork strategy is forcing German food manufacturers to reformulate additive portfolios, accelerating demand for clean-label hydrocolloids that satisfy EFSA transparency requirements while maintaining functional performance in dairy and confectionery matrices.
Growth Catalysts
- Clean-label mandates:EU Regulation 1333/2008 on food improvers compels manufacturers to replace synthetic stabilizers with plant-derived alternatives like pectin and carrageenan in beverage applications.
- Bavaria's processing corridor:Large-scale dairy cooperatives and meat packers in southern Germany concentrate procurement volumes, creating anchor demand for gelatin and modified starches.
- Fermentation-derived innovations:Novel hydrocolloids produced through precision fermentation gain novel food classification pathways, opening regulatory-compliant alternatives to conventional extraction.
Market Restraints
- Guar gum price volatility:Dependence on Indian monsoon-dependent crops creates input cost instability that compresses margins for European distributors.
- Import documentation burdens:ECHA REACH compliance requirements for raw material purity create specification premiums that disadvantage non-EU suppliers.
- Gelatin substitution pressure:Plant-based dietary trends threaten bovine and porcine-derived hydrocolloid demand in confectionery segments.
Strategic Opportunities
- Underpenetrated sauces segment:Cold-prepared condiment formats multiply across German retail channels, creating fastest-expanding application volume for xanthan and gellan gum systems.
- CSRD alignment:Corporate Sustainability Reporting Directive disclosures reward supply chain traceability investments, favoring domestic-certified producers with verified farm-to-fork documentation.
- Modular ingredient platforms:Bundled taste-and-texture systems allow suppliers to capture long-term supply relationships through integrated service models rather than commodity trading.
Industry Challenges
- Reformulation capex intensity:Clean-label transitions require pilot-scale testing and production line modifications that strain mid-tier manufacturer balance sheets.
- Novel food approval timelines:EFSA evaluation periods for fermentation-derived hydrocolloids extend commercialization cycles and tie up R&D resources.
- Cross-functional talent scarcity:Food science expertise combining hydrocolloid chemistry with regulatory navigation commands premium compensation in Bavaria's competitive labor market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Food Hydrocolloids Market |
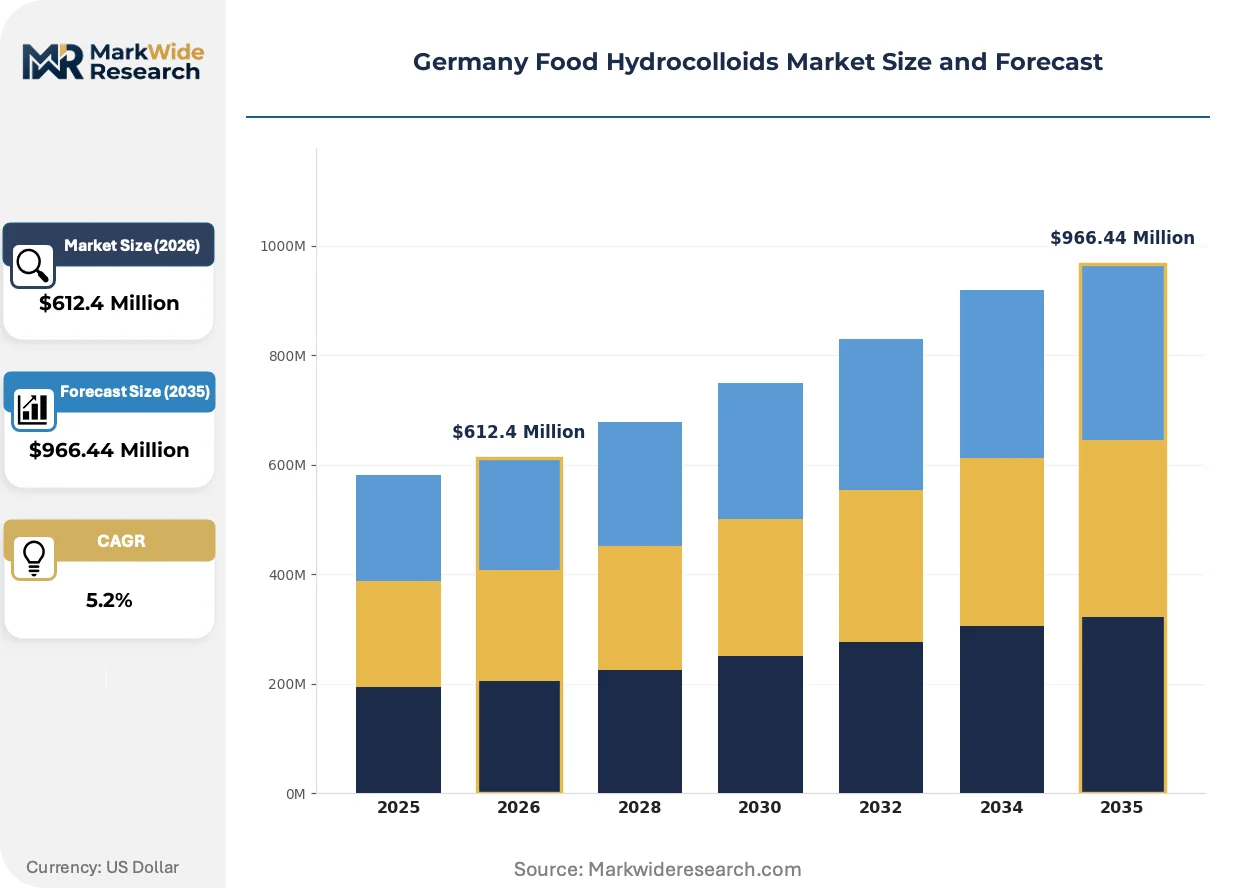
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $966.44 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Xanthan Gum, Guar Gum, Carrageenan, Pectin, Agar-Agar Application: Dairy & Desserts, Meat Processing, Beverages, Bakery, Sauces & Dressings, Confectionery Form: Powder, Liquid, Flakes, Granules End User Industry: Food Processing Companies, Bakery Manufacturers, Beverage Producers, Meat Packers, Confectionery Makers |
| Companies Covered | DuPont de Nemours, Inc., Rousselot, CP Kelco, Kerry Group plc, Ingredion, Behn Meyer Holding AG, Koninklijke DSM N.V., BASF SE, Cargill Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Food Hydrocolloids Market Shifts & Advancements
Modular hydrocolloid systems are displacing single-ingredient procurement across German food manufacturing, unifying texture modification with flavor delivery and nutritional enhancement in integrated platforms that reduce supplier complexity.
Enzymatic modification of pectin is unifying low-sugar gelling performance with clean-label positioning. Industrial bakeries in North Rhine-Westphalia adopt these systems at accelerated pace. The technology is compressing formulation development cycles from months to weeks.
EU Green Deal implementation tightens contaminant thresholds under BfR guidelines. Industrial laboratories face expanded testing protocols for heavy metals and microbial loads. Dairy processors in Lower Saxony respond by qualifying domestic-certified suppliers over import-dependent alternatives.
Buyer concentration among Bavarian dairy cooperatives is compressing negotiation leverage for mid-tier hydrocolloid distributors. Direct contracting with ingredient platforms replaces spot-market purchasing. This pattern concentrates procurement power in southern Germany's processing corridor.
Germany Food Hydrocolloids Market Segmentation
Segmentation in the Germany Food Hydrocolloids Market reveals how procurement power concentrates around specific functional requirements and regulatory compliance tiers. Bavarian dairy cooperatives and North Rhine-Westphalian industrial bakeries drive divergent specification demands that reshape supplier strategies.
Product Type:
Supply concentration around thermoreversible gelling properties and plant-derived alternatives is redrawing procurement priorities across German food manufacturers.
- Gelatin:Animal-derived protein hydrocolloid delivering unmatched thermoreversible gelation between 25-40°C. Bavarian dairy cooperatives and confectionery makers in Baden-Württemberg anchor procurement volumes, though bovine and porcine sourcing faces substitution pressure from clean-label mandates.
- Pectin:Plant-derived polysaccharide extracted from citrus peel and apple pomace, functioning as low-sugar gelling agent through amidation. Beverage producers in Hamburg and Berlin pivot toward pectin systems to satisfy EU Regulation 1333/2008 transparency requirements while maintaining stability in acidic fruit matrices.
- Xanthan Gum:Microbial polysaccharide produced via Xanthomonas campestris fermentation, valued for pseudoplastic rheology in cold-prepared sauces.
- Guar Gum:Galactomannan from Cyamopsis tetragonoloba seeds, cost-effective thickener vulnerable to Indian monsoon-driven price volatility.
- Carrageenan:Sulfated polysaccharide from red seaweed, dominant in dairy stabilization despite ongoing EFSA re-evaluation scrutiny.
- Agar-Agar:Gelose polymer from Gracilaria and Gelidium species, premium positioning in vegan confectionery and microbiological media.
Today's leader: Gelatin. Tomorrow's challenger: Pectin.
Application:
Cost tier differentiation separates high-volume commodity applications from premium formulation services across German food manufacturing.
- Dairy & Desserts:Largest volume pool demanding hydrocolloid systems for mouthfeel modification, syneresis control, and fat replacement. Lower Saxony dairy processors qualify domestic-certified suppliers to satisfy BfR contaminant guidelines, creating specification premiums over import-dependent alternatives.
- Sauces & Dressings:Cold-prepared condiment formats multiply across German retail channels, driving steepest expansion trajectory for xanthan and gellan gum systems. Industrial kitchens in Frankfurt and Stuttgart adopt pourable emulsion stabilizers requiring freeze-thaw resistance.
- Meat Processing:Injection brines and emulsified products utilize modified starches and carrageenan for water-binding and sliceability.
- Beverages:Pulp suspension and cloud stability in fruit juices and plant-based drinks.
- Bakery:Crumb softening, shelf-life extension, and gluten replacement in industrial bread production.
- Confectionery:Gummy textures, aerated marshmallows, and panned coatings.
Volume concentrates in dairy. Margins expand fastest in sauces.
Form:
Processing equipment compatibility and dispersion efficiency determine form selection across German manufacturing facilities.
- Powder:Dominant dry format enabling precise dosing in automated batching systems and extended shelf stability.
- Liquid:Pre-hydrated solutions eliminating dust exposure and hydration time constraints in continuous production lines.
- Flakes:Specialized agar-agar presentation for traditional Asian cuisine and laboratory applications.
- Granules:Reduced dusting and improved flow properties for manual handling in smaller-scale operations.
Automation favors powder. Convenience drives liquid adoption.
End User Industry:
Customer type fragmentation creates divergent service requirements from technical formulation support to commodity spot purchasing.
- Food Processing Companies:Integrated multinationals operating across dairy, meat, and prepared meals, demanding modular ingredient platforms bundling hydrocolloids with flavor systems and nutritional enhancers.
- Beverage Producers:Mid-tier manufacturers in Berlin-Brandenburg corridor requiring rapid reformulation support for clean-label transitions.
- Bakery Manufacturers:North Rhine-Westphalian industrial bakeries adopting enzymatically modified pectin for low-sugar gelling performance.
- Meat Packers:Bavarian cooperatives concentrating procurement power through direct contracting with ingredient platforms.
- Confectionery Makers:Specialty producers balancing texture innovation with gelatin substitution pressures from plant-based dietary trends.
Scale concentrates with processors. Agility resides with beverage makers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German food hydrocolloid manufacturing traces its industrial roots to Bavaria's post-war dairy cooperative expansion, where gelatin stabilization for processed cheese first achieved commercial scale during the 1950s. This historical foundation established southern Germany as the continent's dominant hydrocolloid demand center, with procurement patterns that continue to concentrate in the same geographic corridor seven decades later.
Bavaria
Dairy cooperatives and meat packers anchor procurement volumes for gelatin and modified starches. EFSA evaluations under EU Regulation 1333/2008 compel additive transparency documentation from ingredient suppliers. Munich and Nuremberg host formulation laboratories serving industrial bakeries and confectionery producers with clean-label reformulation support.
North Rhine-Westphalia
Industrial bakeries adopt enzymatically modified pectin for low-sugar gelling performance at accelerated pace. BfR contaminant guidelines drive expanded testing protocols for heavy metals in hydrocolloid raw materials. Cologne and Düsseldorf concentrate distribution infrastructure for guar gum and xanthan systems imported via Rotterdam port corridors.
Lower Saxony
Dairy processors qualify domestic-certified suppliers to satisfy BfR guidelines, creating specification premiums over import-dependent alternatives. The EU Green Deal's Farm-to-Fork strategy tightens additive transparency requirements for milk protein stabilization systems. Hanover and Oldenburg anchor technical service operations for large-scale fluid milk processors.
Baden-Württemberg
Confectionery makers in Stuttgart and Karlsruhe balance texture innovation with gelatin substitution pressures from plant-based dietary trends. ECHA REACH compliance requirements for raw material purity disadvantage non-EU suppliers in regional procurement decisions. Precision fermentation startups in the region pursue novel food classification pathways for microbial hydrocolloid alternatives.
Berlin-Brandenburg
Beverage producers require rapid reformulation support for clean-label transitions in fruit juice and plant-based drink applications. CSRD disclosures reward supply chain traceability investments among mid-tier manufacturers. Berlin hosts ingredient platform headquarters bundling hydrocolloids with integrated taste-and-texture systems for national distribution.
Germany Food Hydrocolloids Market Competitive Landscape
The competitive structure tilts toward integrated ingredient platforms rather than commodity traders. Kerry Group plc and Cargill Incorporated anchor long-term supply relationships through bundled service models that unify texture modification with flavor delivery. Three archetypes dominate: multinational chemical conglomerates with backward integration into raw material sourcing, specialized hydrocolloid distributors with regional formulation expertise, and fermentation technology ventures pursuing novel food regulatory pathways. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with suppliers investing in domestic certification infrastructure to capture specification premiums under tightening EU contaminant thresholds.
Among Ireland-based ingredient platforms, Kerry Group plc exemplifies the integrated taste-and-texture archetype that has displaced single-ingredient procurement across German food manufacturing. Cargill Incorporated, a US-based agribusiness, occupies a position within the upstream-controlled supplier tier through captive guar gum sourcing networks. Netherlands-based Koninklijke DSM N.V. and German chemical conglomerate BASF SE represent the diversified life-science archetype, leveraging fermentation capabilities and regulatory navigation expertise to serve reformulation-intensive segments. These four entities anchor the competitive landscape, with mid-tier distributors competing on technical service proximity to Bavaria's processing corridor.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Rousselot |
| CP Kelco |
| Kerry Group plc |
| Ingredion |
| Behn Meyer Holding AG |
| Koninklijke DSM N.V. |
| BASF SE |
| Cargill Incorporated |
| Others |
Supply & Pricing Matrix
The EU Green Deal's Farm-to-Fork strategy gates both qualified supply and premium-tier pricing access for German food hydrocolloid manufacturers, as EFSA transparency documentation and BfR contaminant compliance create specification premiums that only domestic-certified producers can capture. Bavarian dairy cooperatives and North Rhine-Westphalian industrial bakeries concentrate procurement power, forcing mid-tier distributors to absorb margin compression or invest in certification infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ECHA REACH-compliant domestic suppliers from import-dependent alternatives and commodity spot traders. Price differentiation rests on certification grade and volume scale, with large-scale dairy cooperatives extracting favorable terms through direct platform contracting. Cost compression in the standard tier is intensifying because Indian monsoon-driven guar gum volatility feeds into distributor margins. Beverage producers in Berlin-Brandenburg exhibit highest price sensitivity due to reformulation capex burdens, while precision fermentation ventures command lowest sensitivity as novel food premiums justify investment.
Supply Chain Analysis
Regional distribution centers in Cologne and Düsseldorf anchor hub-and-spoke patterns for guar gum and xanthan systems imported via Rotterdam port corridors. Geographic supply concentration centers on India for guar gum, China for xanthan fermentation capacity, and Southeast Asia for carrageenan seaweed harvesting. Raw material dependencies draw from citrus peel and apple pomace for pectin, bovine and porcine collagen for gelatin, and red seaweed biomass for carrageenan. Supply chain risk hinges on single-source vulnerability for Indian monsoon-dependent crops. Distribution runs through ingredient platforms bundling taste-and-texture systems rather than commodity spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German food hydrocolloids offer margin-expansion pathways as clean-label reformulation shifts procurement toward certified domestic suppliers capable of capturing specification premiums. Modular ingredient platforms displace commodity trading, rewarding integrated service capabilities over spot-market participation.
For Market Incumbents: Acquire fermentation technology assets to secure novel food classification pathways ahead of EFSA evaluation timelines. Deepen backward integration into guar gum sourcing networks to insulate margins from Indian crop volatility. Kerry Group plc and Cargill Incorporated already anchor this approach through captive supply chains and integrated taste-and-texture platforms. Certification infrastructure investments defend against mid-tier distributor displacement. For New Entrants and Emerging Players: Launch via modular ingredient bundling targeting underpenetrated sauces and dressings applications in Frankfurt and Stuttgart industrial kitchens. Cold-prepared condiment formats multiply fastest across German retail channels, creating white-space for xanthan and gellan gum specialists. Precision fermentation-derived hydrocolloids open regulatory-compliant alternatives to conventional extraction, with Baden-Württemberg startups pursuing novel food pathways. Technical service proximity to Bavaria's processing corridor accelerates customer acquisition. For Investors and Strategic Acquirers: Roll-up economics work for regional formulation specialists because buyer concentration among Bavarian dairy cooperatives compresses negotiation leverage for fragmented mid-tier distributors. Long-term viability centers on platform consolidation over commodity trading, with fermentation technology ventures offering regulatory moats. The signal to watch is EFSA novel food approval velocity for precision-derived alternatives, which would revalue microbial hydrocolloid pipelines against conventional extraction assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Guar Sourcing | Cargill's captive Indian supply networks insulate European distribution margins from monsoon volatility. |
| Novel Food Regulatory Pathway Investment | Precision fermentation ventures in Baden-Württemberg secure EFSA-compliant alternatives to animal-derived hydrocolloids. |
| Modular Ingredient Platform Expansion | Kerry Group's taste-and-texture bundling displaces single-ingredient procurement across North Rhine-Westphalian bakeries. |
| Domestic Certification Infrastructure Buildout | Lower Saxony dairy processors qualify local suppliers to satisfy tightening BfR contaminant thresholds. |
| Technical Service Proximity Investment | Munich and Nuremberg laboratories anchor clean-label reformulation support for Bavarian cooperatives. |
Research Methodology
Coverage spans Germany's federal states, with primary inputs from each region's processing corridor, combining interviews with dairy procurement directors, bakery R&D leads, meat packer technical managers, and beverage formulation specialists with secondary validation. Trade data from German customs authorities, BfR contaminant monitoring reports, EFSA food additive evaluations, and EU Regulation 1333/2008 implementation guidance anchored supply-side assessment. Bottom-up demand modeling across Bavaria, North Rhine-Westphalia, Lower Saxony, Baden-Württemberg, and Berlin-Brandenburg triangulated against top-down market sizing.
Granularity-level modeling tracked product type performance across gelatin, pectin, xanthan gum, guar gum, carrageenan, and agar-agar segments, with application-level splits for dairy, sauces, meat processing, beverages, bakery, and confectionery. End-use industry dimensions captured food processing companies, beverage producers, bakery manufacturers, meat packers, and confectionery makers. CAGRs derived from segment-level volume and value trajectories across the projection horizon, incorporating ECHA REACH compliance cost assumptions and EU Green Deal implementation timelines as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA novel food approval delays or severe Indian monsoon disruptions to guar gum supply. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that reformulation capex intensity and cross-functional talent scarcity in Bavaria's competitive labor market could accelerate or retard platform consolidation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Flavonoids Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Global Zeaxanthin Market
Food Components and Additives
Europe Food Stabilizers Market
Food Components and Additives
France Food Preservatives Market
Food Components and Additives
North America Native Starch Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
North America Food Hydrocolloids Market
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Japan Food Hydrocolloids Market
Food Components and Additives
Food Grade Silica Market
Food Components and Additives
Lutein and Zeaxanthin Market
Food Components and Additives
Food Grade Magnesium Carbonate Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
Food Grade Calcium Carbonate Market