
 Oxidized Starch Market | 2026-2036
Oxidized Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Oxidized Starch Market Outlook
Specialty paper mills and sustainable packaging converters is redrawing the traditional buyer landscape for oxidized starch, displacing legacy textile and laundry starch offtake with higher-specification industrial orders. Roquette Freres leverages its European pea and potato starch vertical integration to secure consistent feedstock for oxidation circuits. Cargill anchors North American supply through its corn wet-milling infrastructure, while Ingredion competes on modified starch formulation breadth across food and industrial segments.
Oxidized starch is a modified polysaccharide produced by treating native starch with oxidizing agents such as sodium hypochlorite, introducing carbonyl and carboxyl functional groups that reduce viscosity and improve film-forming adhesion; this chemical transformation yields cold-water solubility and enhanced binding strength for industrial applications. Food-grade oxidized starch dominates current volume through its use as a thickener and stabilizer in processed foods, though industrial-grade material commands superior margins in paper coatings and adhesive formulations where technical performance thresholds are stringent. Pharmaceutical-grade oxidized starch occupies a narrower but higher-value niche as a tablet disintegrant and excipient binder, with qualification timelines that insulate incumbent suppliers from commodity competition.
REACH registration requirements in Europe and FDA food-contact substance notifications in the United States impose documentation burdens that favor suppliers with dedicated regulatory affairs functions and analytical testing infrastructure. China's GB standards for food additives and industrial chemicals, administered by SAMR and MEE respectively, create a dual compliance track for exporters serving both food-processing and paper-manufacturing end users. Stakeholders must monitor regulatory divergence between jurisdictions, as tightening purity standards in one geography will cascade through multinational supply chains and reshape qualification investments.
Market Dynamics
Paper and packaging converters are consolidating their oxidized starch sourcing around industrial-grade specifications, compressing legacy textile and laundry starch demand while elevating technical purity requirements across supply chains.
Growth Catalysts
- REACH registration tiers:European chemical compliance documentation is filtering out undercapitalized suppliers and concentrating qualified vendor relationships with paper mills in Germany and France.
- Corrugated board adhesive demand:E-commerce fulfillment packaging is accelerating consumption of high-viscosity oxidized starch formulations for box sealing and flute bonding.
- China paper capacity expansion:Domestic production lines in Shandong and Guangdong provinces are absorbing growing volumes of modified starch for surface sizing operations.
Market Restraints
- Corn wet-milling concentration:North American feedstock supply clusters around Midwest processing infrastructure, exposing buyers to regional harvest volatility and transport cost spikes.
- Hypochlorite oxidation chemistry:Sodium hypochlorite treatment generates chlorinated byproduct streams that face tightening MEE discharge limits in Chinese manufacturing zones.
- Native starch substitution:Unmodified tapioca and potato starches compete on price for low-performance adhesive applications where cold-water solubility is not required.
Strategic Opportunities
- Pharmaceutical excipient qualification:Tablet disintegrant applications offer margin expansion for suppliers willing to absorb FDA drug master file timelines and analytical validation costs.
- Enzymatic oxidation pathways:Peroxidase and laccase biocatalysis converges with pressure-driven reactor design to eliminate chlorinated effluents and unlock green chemistry certifications.
- India packaging conversion:Domestic corrugated box manufacturing is scaling rapidly under PLI scheme incentives, creating import substitution potential for regional starch processors.
Industry Challenges
- Analytical chemistry talent scarcity:Carboxyl and carbonyl group quantification requires specialized chromatography expertise that competes with broader food safety testing demand.
- Dual-track certification burden:Suppliers serving both food-contact and industrial applications must maintain parallel GB standard compliance under SAMR and MEE oversight.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxidized Starch Market |
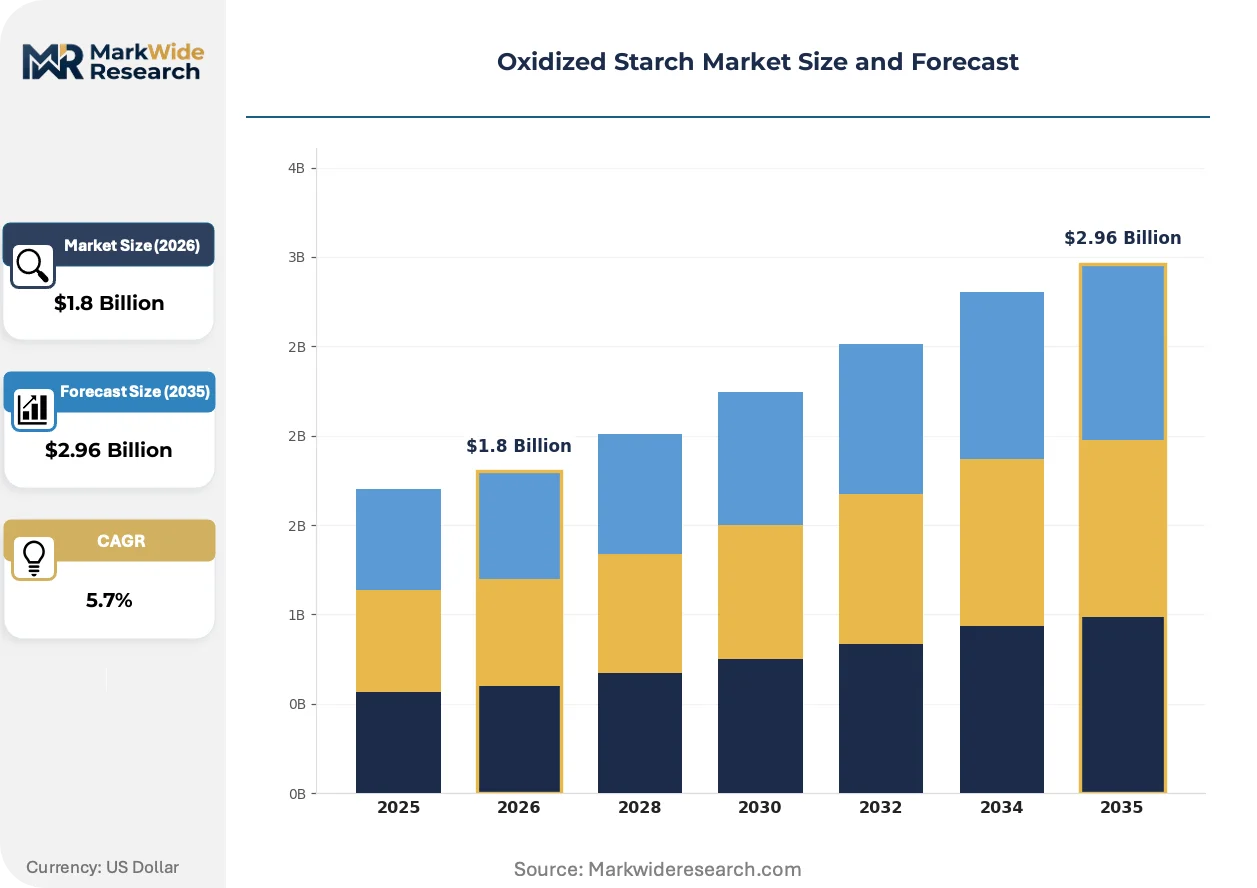
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade Application: Food Processing, Coatings, Adhesives, Pharmaceuticals End User: Food Manufacturers, Consumer Products, Pharmaceutical Companies, Cosmetics Industry Packaging Type: Bulk Bags, Sacks, Drums, Pails |
| Companies Covered | Roquette Freres, Emsland Group, Cargill, MGP Ingredients, Südzucker AG, Archer Daniels Midland, Ingredion, AGRANA, Tate & Lyle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxidized Starch Market Strategic Shifts
Biocatalytic oxidation and precision reactor engineering are displacing conventional hypochlorite chemistry, while regulatory documentation burdens reshape competitive barriers across pharmaceutical and food-contact segments.
Enzymatic oxidation systems employing peroxidase and laccase enzymes are bifurcating the technology landscape between chlorinated and chlorine-free production pathways. Specialty paper mills in Nordic countries are piloting these systems at commercial scale to secure Nordic Swan ecolabel eligibility. The structural consequence is compressing capital returns for legacy hypochlorite infrastructure while creating first-mover premiums for biocatalytic adopters.
EU F-Gas Regulation phase-down schedules are indirectly pressuring industrial adhesive formulators to eliminate solvent-based co-binders and accelerate waterborne oxidized starch adoption. German packaging converters are reformulating corrugated adhesives to exclude synthetic polymer additives ahead of 2030 restriction milestones. Food-contact board manufacturers face the steepest reformulation timelines as EFSA migration limit enforcement tightens.
Consolidated procurement desks at multinational paper groups are compressing supplier rosters and demanding integrated technical service support. Direct mill relationships are displacing traditional distributor channels for volume oxidized starch contracts in North American and European markets. This concentration is most visible in containerboard segments where top-five producers command substantial formulation specification authority.
Oxidized Starch Market Segmentation
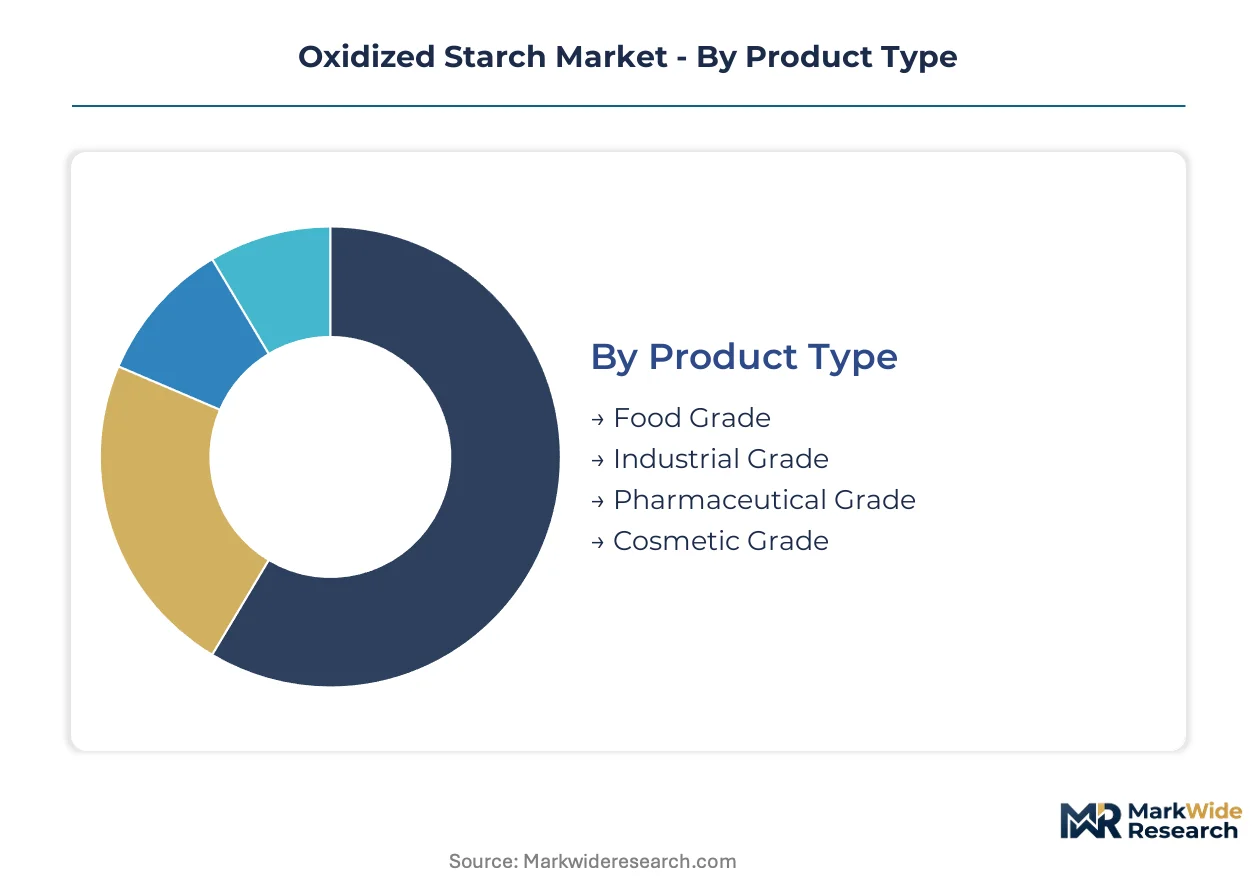
Oxidized starch specifications diverge sharply across end-use verticals, with purity thresholds, solubility profiles, and regulatory documentation requirements creating distinct commercial tracks. Food-grade and industrial-grade variants operate on separate qualification protocols, while pharmaceutical and cosmetic grades command specialized analytical validation investments.
Product Type:
Domestic production dominates food-grade supply chains in major consuming countries, whereas pharmaceutical and cosmetic grades rely heavily on export-oriented manufacturing with dedicated GMP certification.
- Food Grade:Modified starch meeting FDA food-contact and EFSA purity specifications serves as thickener and stabilizer in processed foods. Demand concentrates with multinational food processors in the United States and Germany, where clean-label formulation trends are tightening additive sourcing requirements.
- Industrial Grade:High-viscosity oxidized starch with elevated carboxyl content delivers film-forming adhesion for corrugated board manufacturing. Paper mills in Shandong province and the American Midwest absorb expanding volumes as e-commerce packaging specifications tighten.
- Pharmaceutical Grade:Tablet disintegrant and excipient binder applications require USP-NF compliance and FDA drug master file submission.
- Cosmetic Grade:Film-forming and texturizing agent for personal care formulations demands microbial limit testing and heavy metal screening.
Industrial grade holds the largest share; momentum sits with pharmaceutical grade as qualification timelines insulate incumbent suppliers from commodity competition.
Application:
Cost tier differentiation separates commodity adhesive applications from premium coating and pharmaceutical formulations with steep analytical validation requirements.
- Food Processing:Thickening, gelling, and stabilizing functions in sauces, dressings, and bakery products. Major food manufacturers in France and Japan prioritize supply security through multi-sourcing arrangements.
- Coatings:Surface sizing operations in specialty paper production demand precise viscosity control and film uniformity. Nordic paper mills are piloting enzymatically oxidized starch to secure ecolabel eligibility.
- Adhesives:Corrugated board flute bonding and box sealing applications consume high-viscosity formulations.
- Pharmaceuticals:Tablet disintegrant and binder excipient functions require batch-level documentation and stability testing.
Adhesives applications represent the highest volume tier; coatings are expanding most quickly as sustainable packaging specifications tighten across European markets.
End User:
Customer type determines procurement sophistication, with pharmaceutical companies demanding integrated technical service support while food manufacturers prioritize supply continuity.
- Food Manufacturers:Processed food and beverage producers specify oxidized starch for texture modification and shelf-life extension. Clean-label pressures in Germany and the United States are compressing synthetic additive substitution timelines.
- Consumer Products:Household goods and personal care formulators utilize oxidized starch as biodegradable binder and rheology modifier.
- Pharmaceutical Companies:Dosage form developers require excipient qualification packages with comprehensive impurity profiling.
- Cosmetics Industry:Skin care and hair care manufacturers specify oxidized starch for sensory properties and formulation stability.
Food manufacturers constitute the dominant customer base; pharmaceutical companies offer the steepest margin expansion trajectory for qualified suppliers.
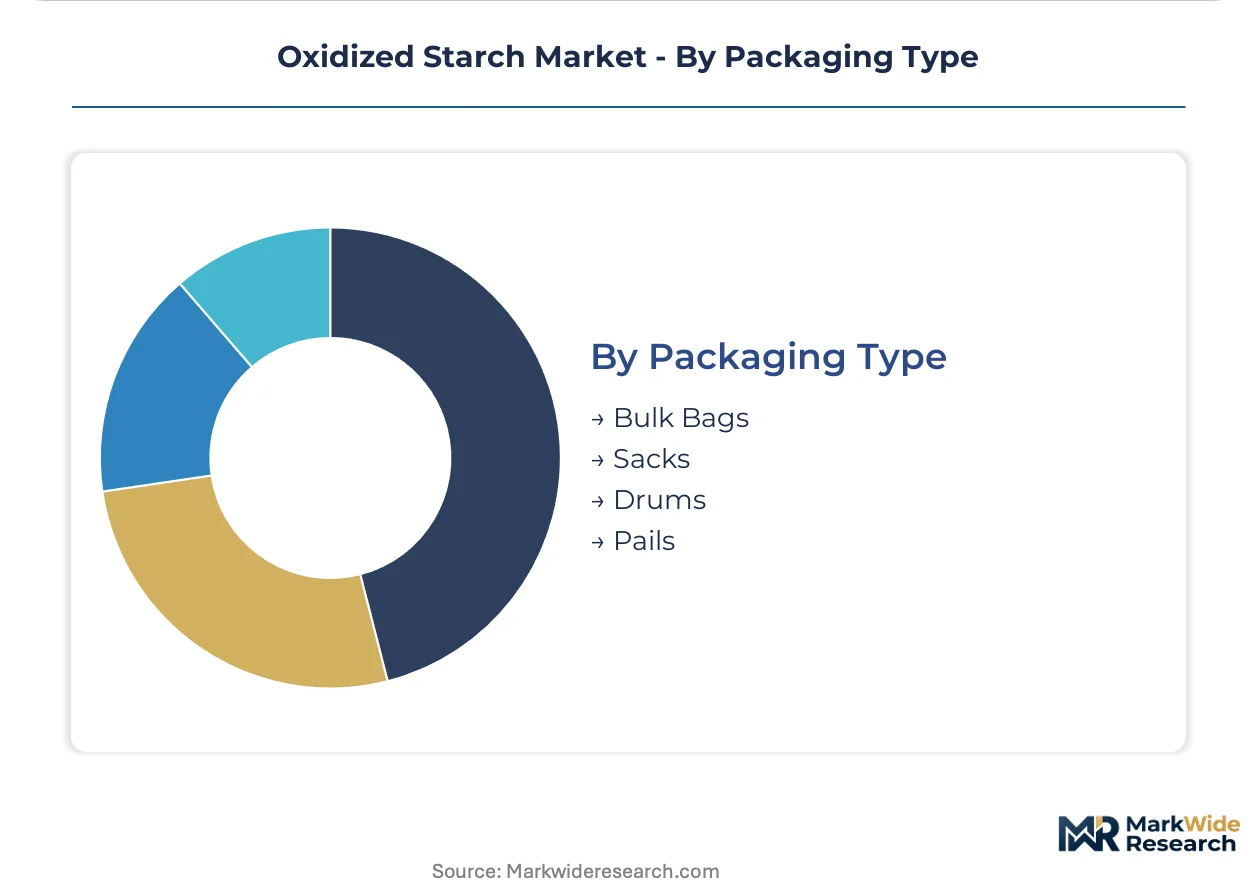
Packaging Type:
Volume scale and contamination risk separate bulk handling systems from smaller-unit pharmaceutical and cosmetic packaging with dedicated cleanroom requirements.
- Bulk Bags:Flexible intermediate bulk containers deliver industrial-grade oxidized starch to paper mill silos and adhesive compounders. Rail-served facilities in the American Midwest and Guangdong province optimize logistics costs for high-volume consumers.
- Sacks:Multi-wall paper bags serve mid-scale food processors and regional adhesive manufacturers with moderate consumption profiles.
- Drums:Steel and fiber drums protect pharmaceutical and food-grade material from moisture and contamination during extended storage.
- Pails:Small-batch containers serve cosmetic formulators and specialty pharmaceutical developers with precise lot-tracking requirements.
Bulk bags command the greatest tonnage; drums are gaining share fastest as pharmaceutical-grade qualification expands supplier rosters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deepwater port infrastructure underwrites China's dominance in oxidized starch trade flows, with Shanghai-Ningbo terminals handling bulk modified starch shipments for paper mill clusters across East Asia.
China
Shandong and Guangdong provinces absorb expanding industrial-grade volumes for corrugated board production. SAMR's GB standards for food additives and MEE discharge limits for chlorinated byproducts impose dual compliance tracks on exporters. Qingdao's paper chemical manufacturing zone hosts concentrated oxidation capacity serving domestic packaging converters.
United States
Midwest corn wet-milling infrastructure supplies feedstock for North American adhesive and coating applications. FDA food-contact substance notifications and evolving EPA effluent guidelines reshape supplier qualification protocols. Wisconsin and Iowa processing clusters optimize rail logistics to containerboard mills in the Chicago-Gary industrial corridor.
Germany
Specialty paper mills in Baden-Württemberg and North Rhine-Westphalia pilot enzymatic oxidation systems for Nordic Swan ecolabel eligibility. REACH registration tiers filter undercapitalized suppliers while EFSA migration limit enforcement tightens food-contact board specifications. Hamburg's chemical processing hub maintains analytical testing infrastructure for pharmaceutical-grade qualification.
India
Domestic corrugated box manufacturing scales under PLI scheme incentives, creating import substitution potential for regional starch processors. FSSAI food safety standards and BIS industrial chemical specifications govern parallel certification requirements. Maharashtra and Gujarat packaging corridors absorb growing modified starch volumes for e-commerce fulfillment logistics.
Japan
Processed food manufacturers in Kanto and Kansai regions specify oxidized starch for clean-label texture modification. METI industrial chemical guidelines and PMDA pharmaceutical excipient standards maintain stringent purity thresholds. Osaka's specialty chemical district hosts formulation R&D serving domestic and Southeast Asian export markets.
Oxidized Starch Market Competitive Environment
Concentration sits with diversified agricultural processors holding captive starch supply and dedicated oxidation circuits. Three strategic archetypes dominate: European pea and potato starch specialists with vertical integration into feedstock cultivation; North American corn wet-milling conglomerates leveraging Midwest grain infrastructure; and Asian tapioca and rice starch processors serving regional packaging demand. Competitive moves center on enzymatic oxidation technology licensing and pharmaceutical excipient qualification investments.
Among European-based specialists, Roquette Freres and Emsland Group exemplify the feedstock-integrated archetype, with company structures reflecting multi-generational family or cooperative ownership models. Cargill anchors the North American scale-driven tier, its corporate form indicating diversified agribusiness operations spanning multiple downstream segments. These three entities represent distinct geographic and structural positioning within oxidized starch supply chains.
| Leading Market Players |
|---|
| Roquette Freres |
| Emsland Group |
| Cargill |
| MGP Ingredients |
| Südzucker AG |
| Archer Daniels Midland |
| Ingredion |
| AGRANA |
| Tate & Lyle |
| Others |
Value Chain & Pricing Dynamics
Midwest corn wet-milling capacity utilization above 85 percent concentrates feedstock bargaining power among North American processors, compressing margin floors for smaller oxidation circuit operators while elevating price discipline at volume contract tiers.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade USP-NF material at premium multiples from industrial-grade bulk contracts for paper mill offtake. Price differentiation hinges on carboxyl content certification and FDA drug master file status, with food-grade material occupying a compressed mid-band. Cost compression in industrial-grade shipments is intensifying because Shandong province capacity additions are expanding spot market liquidity. Food manufacturers exhibit the sharpest price sensitivity due to clean-label reformulation pressures, while pharmaceutical companies absorb premiums for batch-level documentation.
Supply Chain Analysis
China and the United States anchor global oxidized starch production, with Germany maintaining specialized enzymatic oxidation capacity for Nordic ecolabel markets. Feedstock supply draws from Midwest corn wet-milling, Shandong potato starch processing, and European pea starch cultivation. Single-source vulnerability concentrates in sodium hypochlorite oxidation chemical supply chains facing MEE discharge limit enforcement. Distribution runs through rail-served bulk terminals to paper mill clusters, with drum packaging serving pharmaceutical-qualified material through dedicated chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
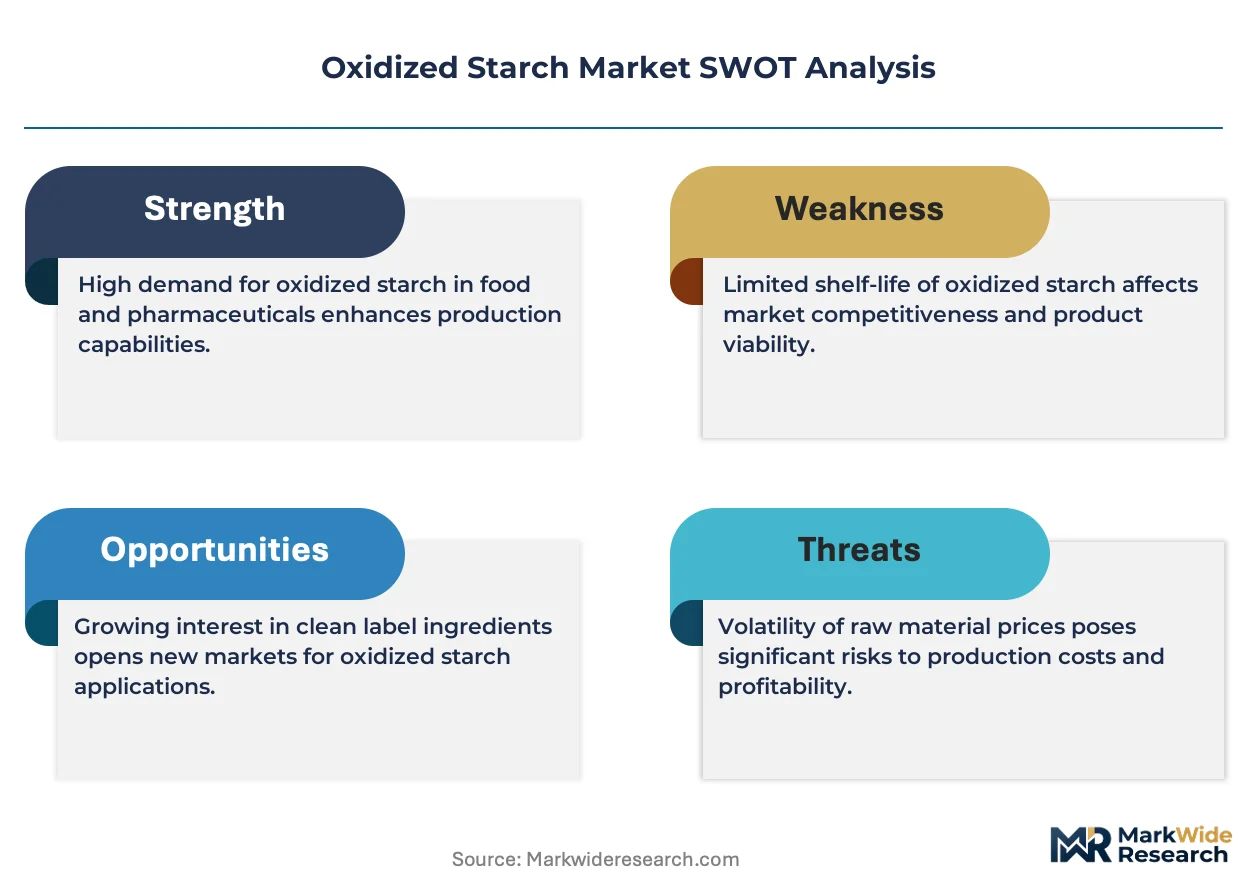
Incumbent suppliers must defend against enzymatic oxidation substitution and native starch price competition, as biocatalytic pathways erode the technical moat of legacy hypochlorite infrastructure.
For Market Incumbents: Fortify qualification barriers by accelerating FDA drug master file investments for pharmaceutical-grade material and securing backward integration into specialty feedstock cultivation. Chlorinated byproduct discharge limits under China's MEE are tightening cost structures for legacy oxidation assets, making enzymatic technology licensing the critical defensive lever. For New Entrants and Emerging Players: Differentiate on enzymatic oxidation certification to capture Nordic Swan ecolabel demand from European specialty paper mills. India's PLI-subsidized corrugated packaging expansion offers the most penetrable geography, with technical service partnerships providing the essential go-to-market mechanism against established distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-grade suppliers with locked excipient qualification timelines insulating against commodity cyclicality. Long-term viability favors processors with dual food-contact and industrial certification infrastructure under single regulatory affairs functions. Watch enzymatic oxidation patent licensing velocity as the inflection signal for technology obsolescence risk in legacy hypochlorite assets.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Oxidation Technology Licensing | Eliminates chlorinated effluent liability under tightening MEE discharge protocols. |
| Pharmaceutical Excipient Qualification | Captures USP-NF premium tiers with FDA drug master file submission timelines. |
| Backward Integration into Feedstock | Secures pea and potato starch supply against Midwest corn harvest volatility. |
| Regional Capacity Expansion in India | Positions for PLI-subsidized corrugated packaging demand in Maharashtra corridors. |
| Dual-Track Certification Investment | Enables simultaneous SAMR food-grade and MEE industrial compliance for Chinese market access. |
Study Parameters
The analysis maps food-grade, industrial-grade, pharmaceutical-grade, and cosmetic-grade oxidation circuits, each validated through technical directors at paper mills, procurement leads at adhesive compounders, regulatory affairs managers at food processors, and excipient qualification specialists at pharmaceutical developers. Primary fieldwork combined with secondary validation from FDA food-contact substance notifications, ECHA REACH registration databases, SAMR GB standard filings, and trade flow records through Shanghai-Ningbo terminals supported bottom-up and top-down triangulation.
Consistency checks against customs data and regional production capacity disclosures validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use application, packaging format, and regional regulatory cluster. CAGRs were derived from installed oxidation capacity expansion schedules correlated with downstream demand elasticity coefficients for corrugated board and pharmaceutical excipient offtake.
Material uncertainties — regulatory divergence between REACH and FDA notification timelines, enzymatic oxidation technology adoption curves, and corn feedstock price volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions about qualification timeline stability and discharge limit enforcement intensity. Recalibration cycles align with material shifts in MEE enforcement patterns and Nordic Swan ecolabel adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Supplement Ingredients Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
North America Anti-Caking Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Global Yeast and Yeast Ingredients Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
Calcium Butyrate Market
Food Additives and Ingredients
Mediterranean Sourdough Starter Cultures Market
Food Additives and Ingredients
South Africa Food Colorants Market
Food Additives and Ingredients
Cetyl Palmitate Market
Food Additives and Ingredients
Food Acidulants Market
Food Additives and Ingredients
North America Feed Additives Market
Food Additives and Ingredients
United States Food Additives Market
Food Additives and Ingredients
United States Anti-Caking Market
Food Additives and Ingredients
Russia Anti Caking Market
Food Additives and Ingredients
Asia Food Emulsifiers Market