
 Europe Food Anti Caking Agents Market | 2026-2036
Europe Food Anti Caking Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Anti Caking Agents Market Foresight
The capital-intensity gap between integrated silicate producers and commodity distributors is collapsing as input costs equalize. Evonik Industries AG leverages its captive precipitated silica capacity to sustain margin structures smaller blenders cannot match. BASF SE anchors its position through phosphate specialization across German dairy processing corridors. Solvay competes by controlling synthetic sodium bicarbonate flows into French confectionery supply chains.
Food anti caking agents comprise powdered or granular substances—typically silicates, phosphates, or modified starches—engineered to absorb moisture and prevent particle agglomeration in humid storage conditions, with particle sizes generally ranging below 100 microns for optimal dispersion. These additives preserve flowability in mechanically processed foods, enabling consistent dosing on high-speed packaging lines. Silicate-based formulations occupy the largest volume share due to their cost efficiency in salt and seasoning applications, while phosphate blends command premium positioning in dairy powder systems where calcium reactivity demands precise buffering. Starch-derived alternatives represent the fastest-adjusting segment as clean-label pressures from European retail chains force reformulation away from synthetic carriers.
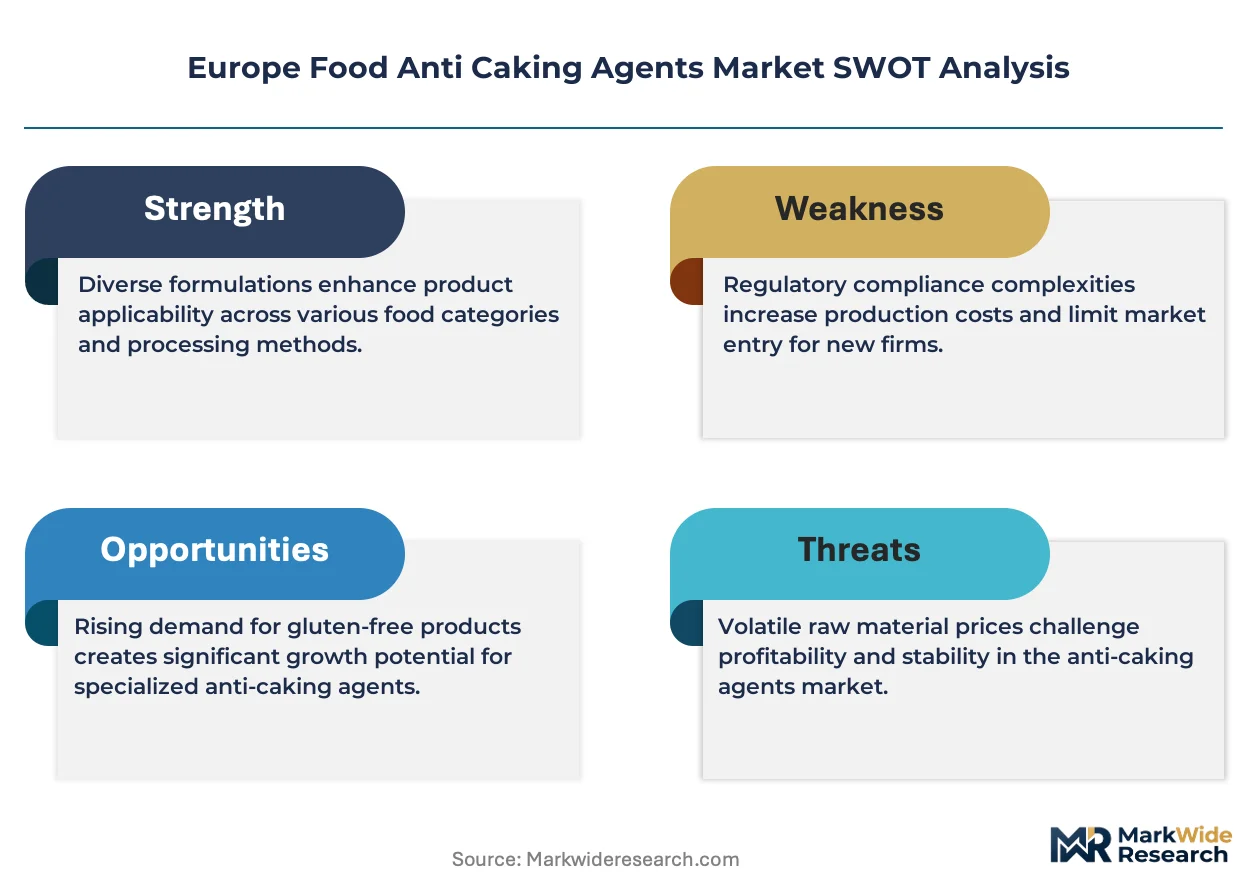
EFSA purity protocols, EU REACH chemical registration requirements, and the F-Gas Regulation's indirect pressure on refrigeration-dependent supply chains collectively tighten compliance thresholds for anti caking agent suppliers. EMA-aligned food contact material standards in Germany and France further segment market access by certification tier. Stakeholders must monitor pending EU-wide nanomaterial classification rules that could reclassify sub-micron silica grades and trigger reformulation costs before compliance deadlines crystallize.
Market Dynamics
EFSA's tightening purity protocols for food-grade silicates are forcing reformulation cycles across European seasoning and dairy powder supply chains, compressing certification timelines and redistributing procurement power toward integrated producers with captive analytical capabilities.
Growth Catalysts
- Clean-label starch alternatives:Retail chains in France and Germany are delisting synthetic carriers from private-label spice blends, accelerating demand for modified rice and tapioca starches that meet EFSA's evolving additive criteria.
- REACH registration completion:Full chemical dossier approvals for precipitated silica grades have unlocked volume procurement by pan-European salt processors seeking supply security under unified regulatory recognition.
- Italy's processed food export engine:Parmesan powder and seasoning manufacturers in the Emilia-Romagna cluster are expanding anti caking agent inventories to maintain flowability specifications for Middle Eastern and North African distribution channels.
Market Restraints
- Energy cost volatility:Synthetic sodium bicarbonate production depends on natural gas-intensive Solvay process economics, exposing French and German suppliers to input cost spikes that commodity blenders cannot hedge.
- Phosphate supply concentration:Food-grade calcium phosphates rely on Moroccan phosphate rock flows concentrated through a limited number of EU-registered importers, creating single-source vulnerability for dairy powder formulators.
- Sub-micron silica classification uncertainty:Pending EU nanomaterial registry rules threaten to reclassify precipitated silica grades below 100 nanometers, triggering costly toxicological re-evaluation before commercial deadlines.
Strategic Opportunities
- Poland's emerging dairy processing corridor:New powder production facilities in the Masovian and Silesian regions lack established anti caking agent supply relationships, creating first-mover positioning for REACH-registered suppliers.
- F-Gas Regulation refrigeration adaptation:Cold chain infrastructure upgrades across Iberian distribution networks are extending humidity-controlled storage reach, expanding addressable market for moisture-sensitive seasoning applications.
- Plant-based dairy analogues:Oat and almond milk powder formulations require novel anti caking chemistries to manage lipid oxidation and particle cohesion, opening formulation partnerships with Scandinavian alternative protein processors.
Industry Challenges
- Analytical chemist scarcity:EFSA-mandated purity testing protocols require specialized ICP-MS and SEM capabilities that smaller compounders in Italy and Spain struggle to staff and validate.
- Legacy system integration:German dairy cooperatives operate mechanical dosing equipment designed for traditional silicate grades, complicating retrofit requirements for starch-based reformulations.
- Certification timeline compression:Novel food additive approvals through EFSA's re-evaluation program now require 18-24 month safety dossier preparation, delaying product launch windows for mid-tier blenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Anti Caking Agents Market |
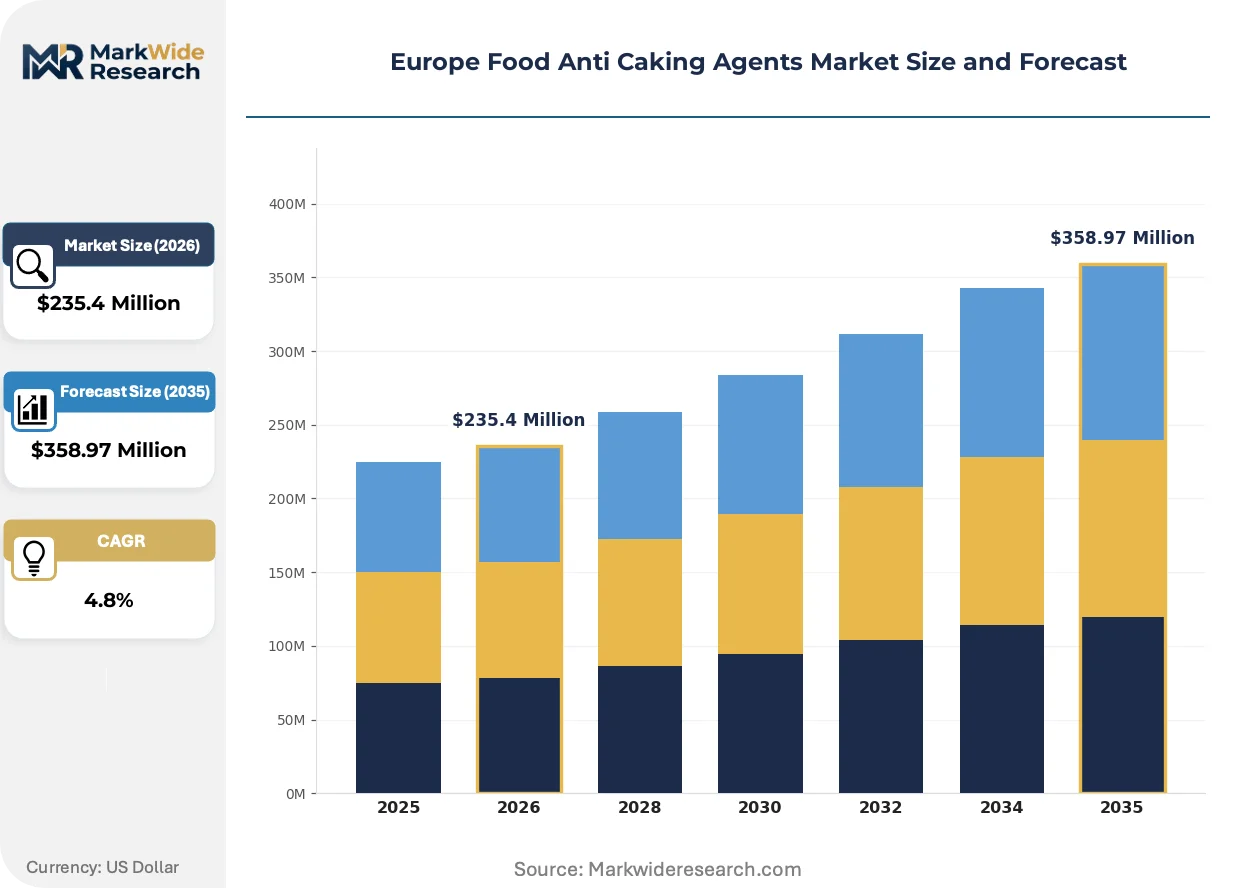
| Market Size in 2026 | $235.4 Million |
| Market Size in 2035 | $358.97 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicates, Calcium Carbonate, Phosphates, Starch Application: Dairy Products, Seasonings, Confectionery, Snack Foods End User: Food Manufacturers, Bakery Businesses, Catering Services, Retail Chains Form: Powder, Granules, Liquid, Tablets |
| Companies Covered | Evonik Industries AG, PPG Industries, BASF SE, Solvay, Merck KGaA, Huber Engineered Materials, Brenntag AG, Cargill, PQ Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Anti Caking Agents Market Shifts & Advancements
Moisture management technologies are bifurcating across synthetic efficiency and natural-origin positioning, with regulatory pressure and retail procurement standards pulling formulation strategies in opposing directions.
Encapsulated silica systems is fragmenting the traditional anti caking agent market by enabling targeted moisture release in high-fat seasoning matrices. Premium spice blend manufacturers in France are adopting these shell-core structures to prevent caking without compromising flavor release profiles. The technology is fragmenting supplier tiers by requiring spray-drying capabilities that commodity silicate distributors cannot access.
EU REACH's 2023-2025 substance evaluation wave is accelerating dossier updates for phosphate-based additives used in infant formula and medical nutrition. German dairy processors are preemptively reformulating toward calcium carbonate blends to avoid potential restriction scenarios. The regulatory pressure is concentrating procurement decisions among suppliers with established ECHA dialogue track records.
Direct-to-manufacturer digital procurement platforms are compressing distributor margins in the European anti caking agent trade. Seasoning compounders in the Netherlands and Belgium are bypassing traditional chemical distributors to contract directly with precipitated silica producers for silo-truck deliveries. The channel shift is most visible in salt and savory applications where specification standardization reduces technical service requirements.
Europe Food Anti Caking Agents Market Segmentation
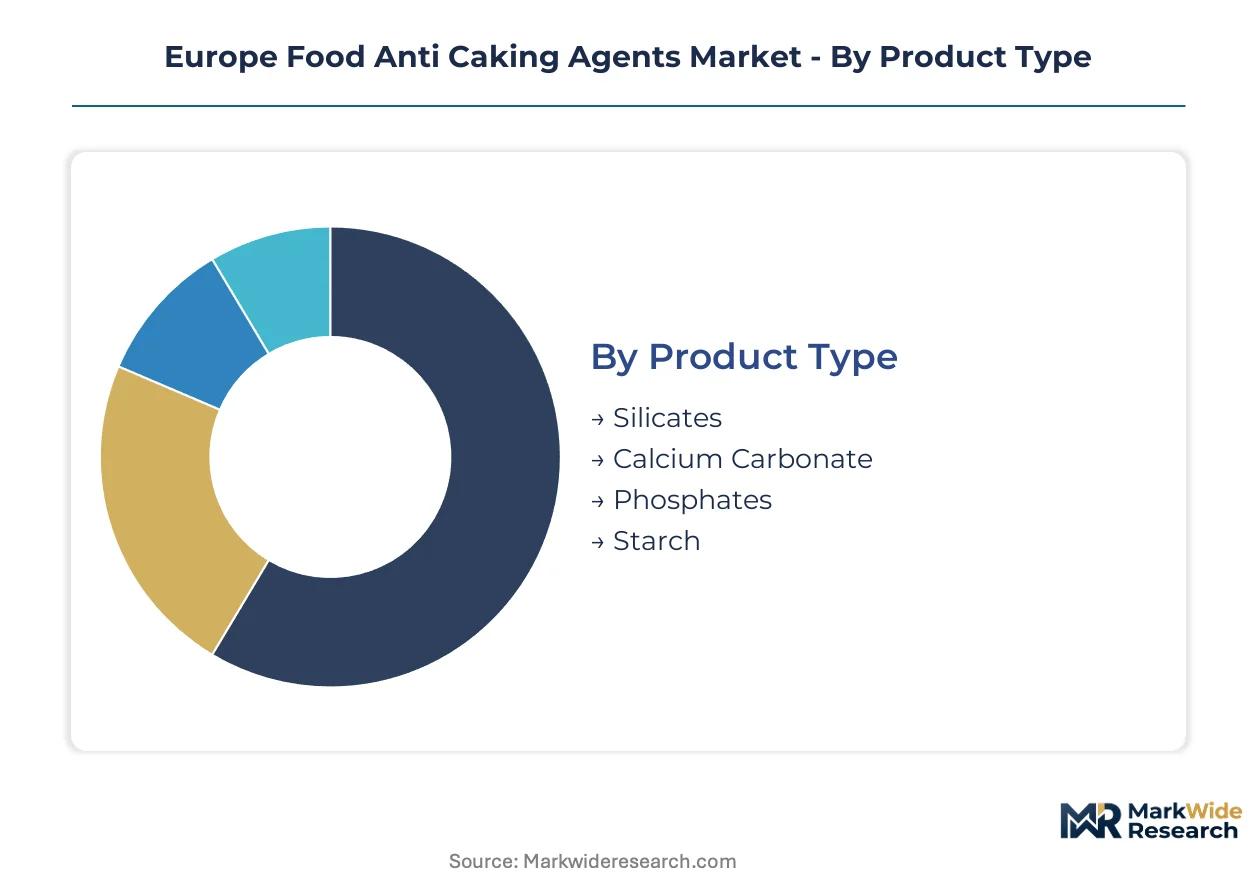
Anti caking agent selection across Europe hinges on EFSA purity tiers, REACH registration status, and end-use moisture sensitivity. Procurement patterns diver sharply between cost-driven salt processors and specification-intensive dairy powder formulators.
Product Type:
EFSA's evolving purity protocols for food-grade silicates and phosphates create tiered compliance thresholds that reshape supplier qualification requirements.
- Silicates:Precipitated silica and calcium silicate formulations dominate volume procurement for salt and seasoning applications. German salt processors in the Lower Saxony cluster specify sub-100 micron grades to maintain flowability on high-speed packaging lines under EFSA's tightened heavy metal limits.
- Phosphates:Calcium and sodium phosphate blends command premium positioning in dairy powder systems where calcium reactivity demands precise buffering. French infant formula manufacturers preemptively stockpile REACH-registered grades to avoid potential ECHA restriction scenarios.
- Calcium Carbonate:Ground and precipitated grades serve cost-sensitive seasoning applications with lower moisture absorption requirements.
- Starch:Modified rice and tapioca variants are climbing fastest as French and German retail chains delist synthetic carriers from private-label spice blends.
Established volume favors silicates; emerging adoption favors starch alternatives.
Application:
Moisture sensitivity and fat content determine anti caking chemistry selection across European food processing corridors.
- Dairy Products:Milk powders, whey proteins, and cheese powders require phosphate or silicate systems to prevent lactose-induced caking during refrigerated storage. Italian Parmesan powder exporters in Emilia-Romagna maintain elevated inventories to meet Middle Eastern distribution specifications.
- Seasonings:Spice blends and savory mixes absorb moisture rapidly in humid Mediterranean climates. Encapsulated silica systems are fragmenting this segment by enabling targeted moisture release in high-fat matrices.
- Confectionery:Sugar-based powders and cocoa mixes demand low-dosage anti caking agents to preserve dissolution characteristics.
- Snack Foods:Powdered cheese and flavor coatings for extruded snacks prioritize cost-efficient silicate grades.
Procurement scale concentrates in dairy; reformulation velocity runs highest in seasonings.
End User:
Technical service requirements and specification complexity separate procurement tiers across the European food manufacturing base.
- Food Manufacturers:Integrated seasoning and dairy powder producers in Germany, France, and Italy contract directly with precipitated silica producers for silo-truck deliveries, bypassing traditional chemical distributors.
- Bakery Businesses:Industrial bakers and premix suppliers require consistent flowability in flour-based systems.
- Catering Services:Foodservice distributors prioritize shelf-stable seasoning packets with minimal caking risk during ambient storage.
- Retail Chains:Private-label spice blend specifications in France and Germany are accelerating clean-label starch adoption through direct supplier mandates.
Direct procurement favors food manufacturers; specification influence rests with retail chains.
Form:
Dispersion efficiency and dosing equipment compatibility drive form selection across European processing lines.
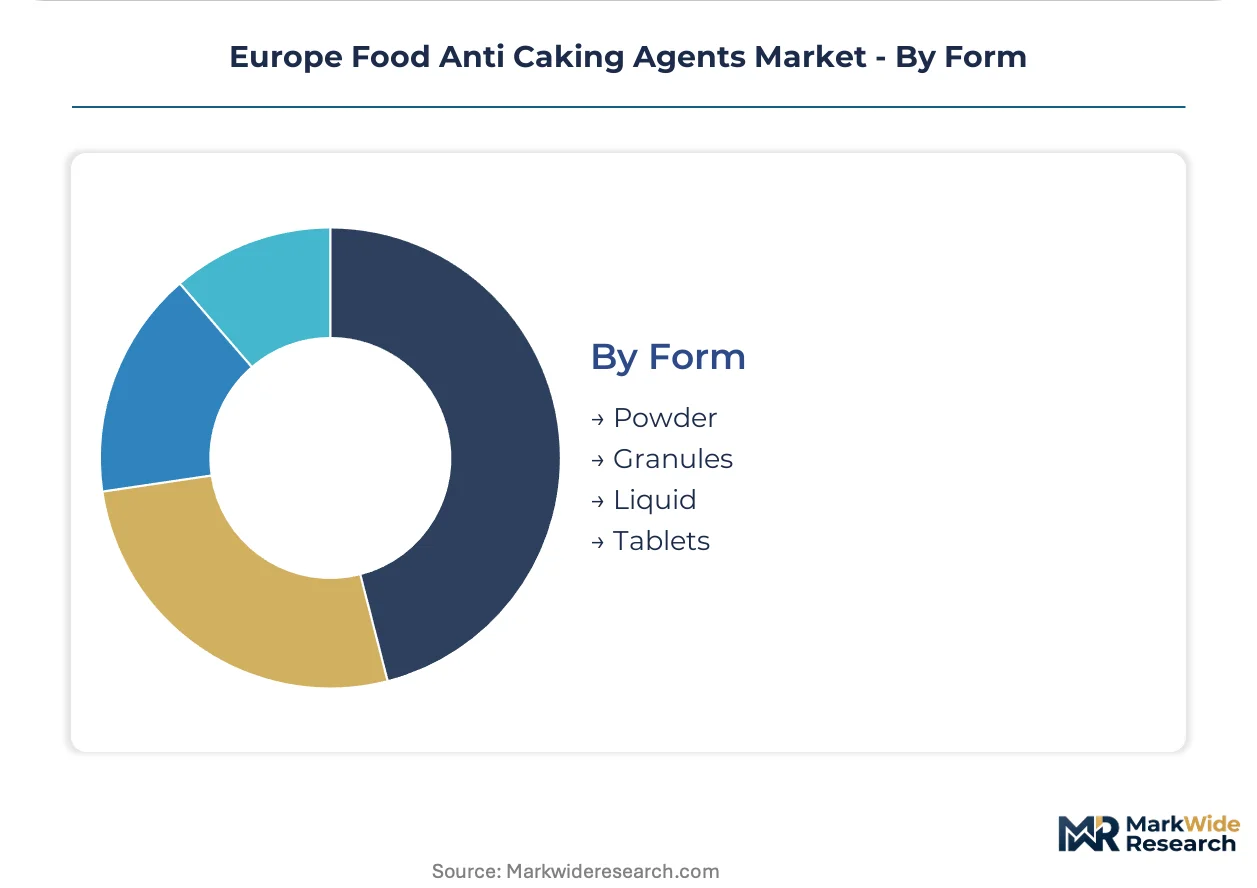
- Powder:Sub-100 micron grades enable uniform distribution in mechanically processed foods. This form captures the largest volume share across salt, seasoning, and dairy applications.
- Granules:Coarser grades serve bulk salt applications where flowability requirements are less stringent.
- Liquid:Suspension systems for specialized coating applications in confectionery and snack food processing.
- Tablets:Compressed forms for controlled-release applications in industrial seasoning dispensers.
Mechanical dosing infrastructure locks in powder dominance; liquid systems expand in coating applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German processors command pricing leverage over French and Italian buyers due to integrated silicate production corridors, while Mediterranean seasoning manufacturers absorb transport premiums for phosphate and starch alternatives.
Germany
Lower Saxony salt processors and Bavarian dairy cooperatives drive precipitated silica consumption for high-speed packaging lines. EFSA's tightened heavy metal protocols force smaller compounders toward REACH-registered suppliers with captive analytical labs. The North Rhine-Westphalia chemical cluster anchors captive production capacity that insulates domestic buyers from energy cost volatility.
France
Infant formula manufacturers in the Hauts-de-France region preemptively stockpile calcium phosphate grades ahead of ECHA's substance evaluation wave. ANSM-aligned food contact material standards segment procurement tiers by certification depth. The Île-de-France confectionery corridor depends on Solvay-process sodium bicarbonate flows for humidity-sensitive cocoa and sugar powder applications.
Italy
Emilia-Romagna Parmesan powder exporters expand anti caking agent inventories to meet Middle Eastern distribution specifications for lactose-stabilized products. EMA purity protocols compress certification timelines for seasoning compounders in the Lombardy industrial belt. Piedmont-based savory mix manufacturers face reformulation pressure from German retail chain clean-label mandates.
Netherlands
Rotterdam-port-dependent distributors face margin compression as seasoning compounders in the Randstad bypass traditional channels for direct silica producer contracts. The F-Gas Regulation's cold chain requirements extend humidity-controlled storage infrastructure into Belgian border zones. Zeeland salt refineries specify sub-100 micron silicate grades for export packaging operations.
Poland
Masovian and Silesian dairy powder facilities lack established anti caking agent supply relationships, creating first-mover positioning for REACH-registered suppliers from western neighbors. Polish food manufacturers absorb learning curves on EFSA dossier preparation that German processors resolved years earlier. The emerging processing corridor attracts technical service investment from phosphate specialists seeking volume growth outside saturated western markets.
Europe Food Anti Caking Agents Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated chemical conglomerates commanding formulation expertise while commodity distributors compete on logistics reach. The vendor base separates into three tiers: captive producers with in-house precipitated silica capacity, phosphate specialists serving dairy powder systems, and regional blenders dependent on third-party raw material sourcing. Market concentration is moderate, with top-tier players controlling critical REACH registration assets that mid-tier competitors cannot replicate. Dominant competitive moves include backward integration into raw material production and geographic expansion into underpenetrated processing corridors.
Within the integrated chemical tier, Evonik Industries AG exemplifies the captive production archetype through its precipitated silica manufacturing footprint. BASF SE occupies a parallel position in phosphate specialization, while Solvay anchors the synthetic sodium bicarbonate segment. These three Germany- and Belgium-based entities represent the technology-intensive pole of competitive positioning, distinct from the cost-driven distributor tier where Brenntag AG and regional traders operate.
| Leading Market Players |
|---|
| Evonik Industries AG |
| PPG Industries |
| BASF SE |
| Solvay |
| Merck KGaA |
| Huber Engineered Materials |
| Brenntag AG |
| Cargill |
| PQ Corporation |
| Others |
Supply & Pricing Matrix
Modified starch substitution for synthetic silicates is redrawing procurement geography toward French and German agricultural processors while compressing premium spreads that phosphate specialists previously commanded in dairy powder systems.
Pricing Analysis
The customization-premium spread between configured-to-order phosphate blends and commodity silicate grades has widened as EFSA purity protocols force dairy powder formulators toward certified suppliers. Contract-based long-term offtake dominates salt and seasoning procurement, while project-based spot purchasing persists in confectionery applications. Price differentiation hinges on REACH registration tier and captive analytical capability, with integrated producers capturing 15-20 point spreads over commodity distributors. Cost compression in standard-grade silicates is intensifying because energy-intensive Solvay-process sodium bicarbonate faces input volatility that blenders cannot hedge. Salt processors in Germany exhibit highest price sensitivity; infant formula manufacturers in France show lowest sensitivity due to specification rigidity.
Supply Chain Analysis
Elevated safety stock requirements among Italian Parmesan powder exporters signal extended lead times for REACH-registered phosphate grades ahead of ECHA's substance evaluation wave. Supply concentrates in Germany, Belgium, and France, with captive precipitated silica capacity anchored in the North Rhine-Westphalia chemical cluster. Raw material flows draw from Moroccan phosphate rock, synthetic sodium bicarbonate via Solvay process economics, and modified tapioca starch from Southeast Asian agricultural processors. Single-source vulnerability concentrates in food-grade calcium phosphate imports through limited EU-registered channels. Distribution runs through direct silo-truck contracts between integrated producers and large food manufacturers, bypassing traditional chemical distributors in salt and savory applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's food anti caking agent market is cycling through a reformulation recovery as EFSA's additive re-evaluation program forces wholesale specification upgrades across dairy and seasoning supply chains.
For Market Incumbents: Fortify analytical chemistry capabilities ahead of pending nanomaterial classification rules that threaten to reclassify sub-micron silica grades. Backward integration into precipitated silica production insulates margin structures from energy cost volatility that commodity blenders cannot hedge. Prioritize certification investment in EFSA dossier preparation to compress approval timelines for reformulated starch alternatives.
For New Entrants and Emerging Players: Anchor in Poland's Masovian and Silesian dairy powder corridor where established supply relationships remain absent and REACH-registered western suppliers have not yet locked in long-term contracts. Target plant-based dairy analogue formulators in Scandinavia seeking novel anti caking chemistries for oat and almond milk powder systems. Pursue technical service partnerships as the primary go-to-market angle, leveraging EFSA dossier expertise that Polish processors lack.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier phosphate compounders in France and Italy facing margin compression from clean-label starch substitution. The five-to-ten year viability window favors suppliers with captive analytical labs and established ECHA dialogue track records. Watch EFSA's nanomaterial registry implementation timeline as the critical inflection signal that would trigger toxicological re-evaluation costs and consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precipitated Silica | Captive production insulates German suppliers from energy cost volatility smaller blenders cannot hedge. |
| EFSA Dossier Certification Investment | Accelerated approval timelines unlock procurement relationships with infant formula manufacturers in Hauts-de-France. |
| Direct Silo-Truck Distribution Contracts | Bypassing traditional chemical distributors captures margin compression in Netherlands seasoning procurement. |
| Modified Starch Formulation Partnerships | Clean-label repositioning aligns with French and German retail chain delisting mandates for synthetic carriers. |
| Polish Dairy Corridor Technical Service Expansion | First-mover positioning in Masovian powder facilities lacking established anti caking agent supply relationships. |
Research Methodology
Desk research of EFSA additive re-evaluation dossiers, REACH registration databases, and EU customs trade flows preceded structured interviews with procurement directors at German salt processors, French infant formula manufacturers, Italian seasoning compounders, and technical R&D leads at precipitated silica producers. Bottom-up volume estimates triangulated against top-down market sizing derived from Cefic chemical industry reports and SEC filings of listed chemical conglomerates.
Variance decomposition across product type, application moisture sensitivity, end-user technical service requirements, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate analysis calibrated to EFSA compliance timeline acceleration and clean-label substitution velocity. Forecast inputs incorporated F-Gas Regulation cold chain infrastructure buildout assumptions and Poland's dairy processing capacity expansion pipeline.
Decision-makers should treat outputs as directional under base assumptions of sustained EFSA purity protocol tightening and no disruptive nanomaterial reclassification; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Polyphenols Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
Edible Films and Coating Market
Food Components and Additives
Clean Label Pectin Market
Food Components and Additives
Horseradish Peroxidase Market
Food Components and Additives
Food Grade Titanium Dioxide Market
Food Components and Additives
Titanium-Free Food Color Market
Food Components and Additives
North America Food Antimicrobial and Antioxidants Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
Food Texture Market
Food Components and Additives
Food Grade Silica Market
Food Components and Additives
North America Native Starch Market
Food Components and Additives
Natural Fatty Acids Market
Food Components and Additives
France Food Preservatives Market
Food Components and Additives
Blackcurrant Powder Market