
 Spain Food Hydrocolloids Market | 2026-2036
Spain Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Food Hydrocolloids Market Analytics
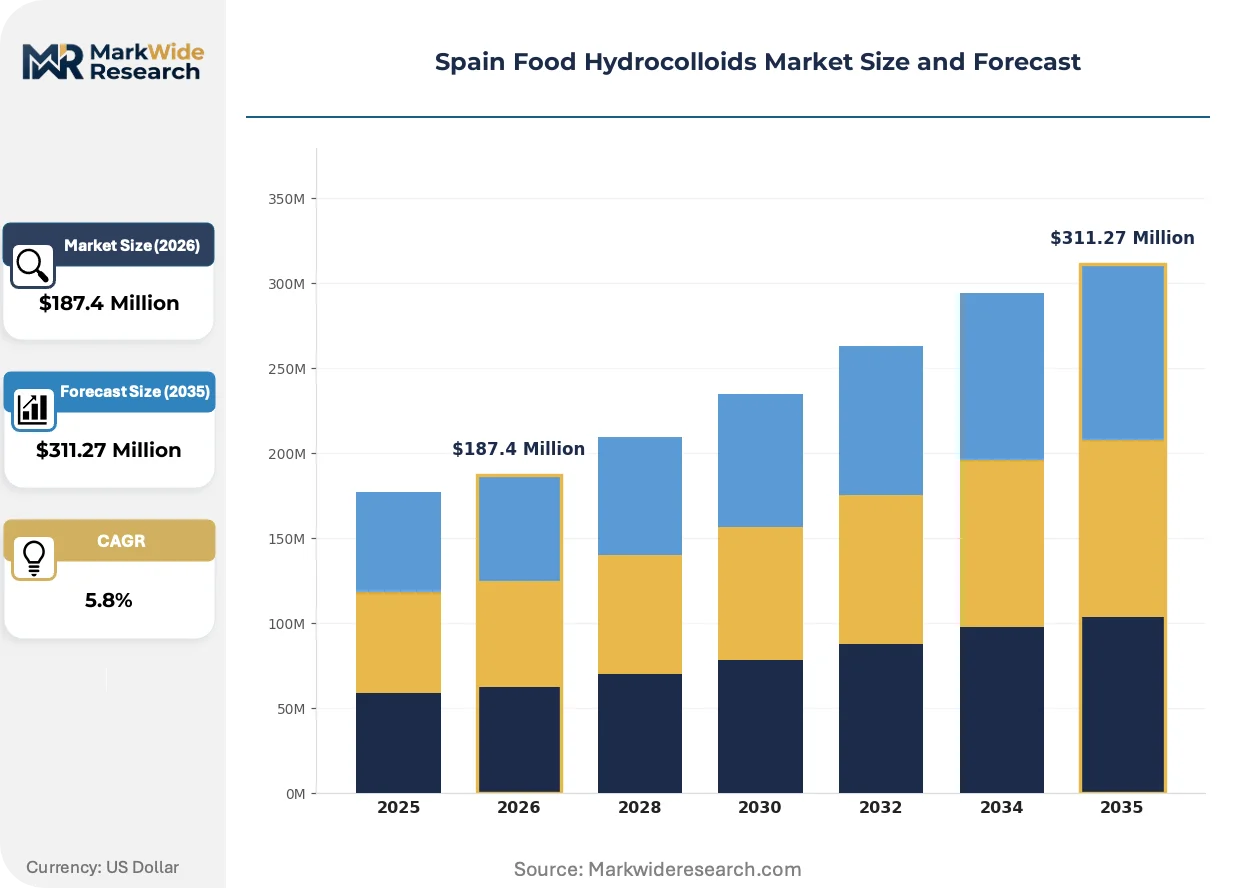
The Spain food hydrocolloids market is decoupling along a sharp fault line between premium clean-label grades and commodity bulk hydrocolloids, with price spreads widening as Spanish dairy and bakery buyers prioritize E-number reduction over cost minimization. Cargill Incorporated leverages its Barcelona distribution hub to supply tailored pectin blends for reduced-sugar yogurts across Iberian co-manufacturers. Kerry Group plc anchors its position through specialized texturizing systems for Spanish ready-meal producers seeking Mediterranean-diet positioning.
Food hydrocolloids comprise high-molecular-weight polysaccharides and proteins that hydrate in aqueous systems to modify viscosity, gelation, and water-binding behavior, with gelatin requiring controlled acid or alkaline pretreatment of collagen to achieve specific Bloom strength ratings for confectionery and pharmaceutical applications. Pectin dominates formulation activity in Spanish fruit-preparation and dairy segments where low-methoxyl grades enable calcium-set gelling without added sugars. Guar gum competes aggressively in gluten-free bakery applications across Madrid and Valencia manufacturing clusters, though margin pools concentrate in agar supply for plant-based seafood analogs targeting Barcelona's restaurant wholesale channel.
EU EFSA additive transparency requirements and Spain's national food safety agency evaluations shape hydrocolloid approval timelines and label claim permissibility, while CE marking obligations for imported processing aids filter non-compliant suppliers from Iberian distribution networks. BIS-aligned quality certifications for guar gum imports from India create additional entry barriers for Spanish traders sourcing raw material. Stakeholders must monitor pending EU Green Deal packaging regulations and evolving E-number consumer sentiment to anticipate reformulation cycles before competitive displacement accelerates in premium private-label contracts.
Market Dynamics
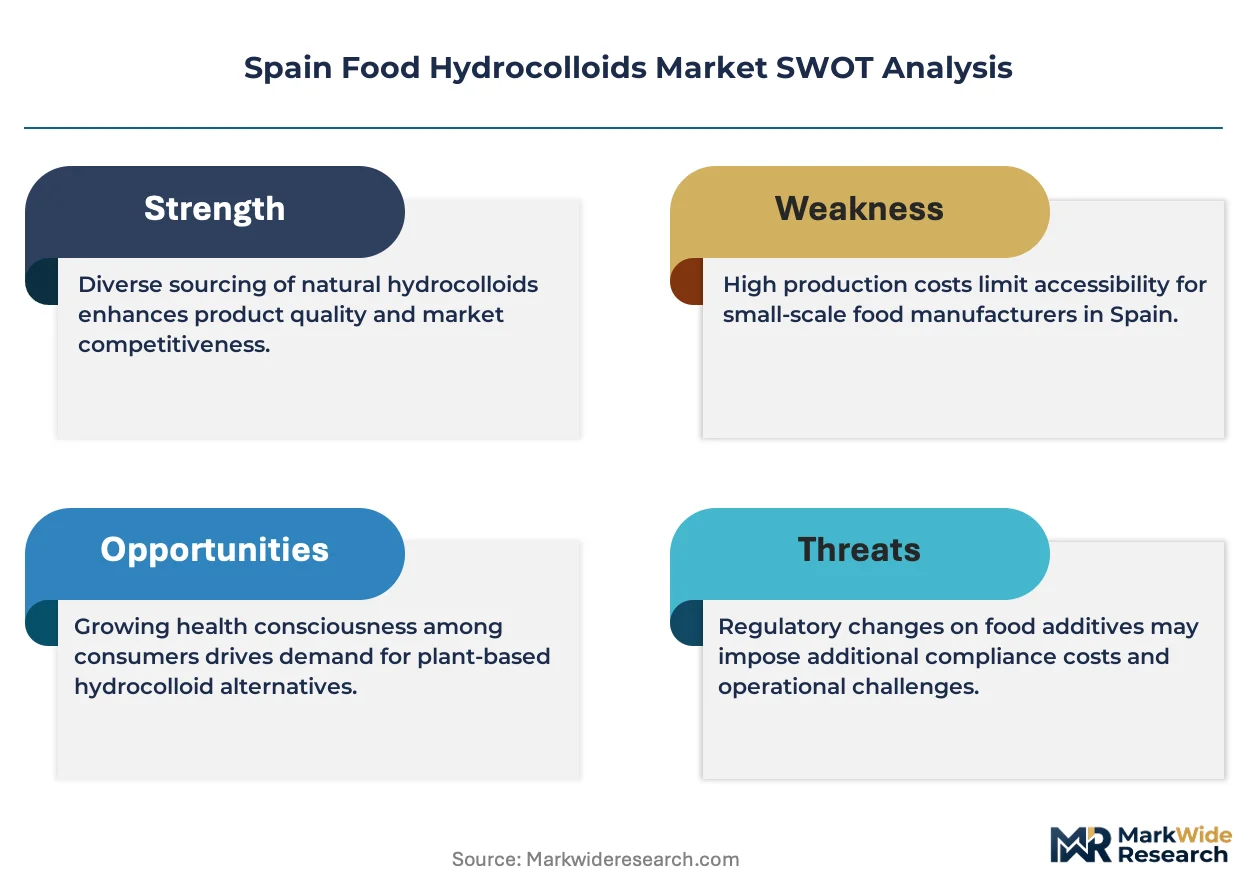
Clean-label reformulation pressure from EU EFSA additive transparency rules is splitting Spanish hydrocolloid procurement into parallel premium and commodity supply chains, with dairy and bakery manufacturers absorbing significant cost premiums for E-number-free pectin and gelatin grades.
Growth Catalysts
- EU Green Deal packaging mandates:Spanish food manufacturers are accelerating hydrocolloid adoption for plant-based barrier coatings that replace single-use plastics in ready-meal applications.
- Gluten-free bakery expansion:Madrid and Valencia manufacturing clusters are scaling guar gum and xanthan formulations to meet celiac certification demand under FACE (Spanish Federation of Celiac Associations) protocols.
- Calcium-set pectin technology:Low-methoxyl pectin grades enabling reduced-sugar dairy formulations are capturing formulation share in Catalonian yogurt production.
Market Restraints
- Indian guar gum supply concentration:Spanish traders face BIS-aligned quality certification barriers and monsoon-dependent crop volatility for primary gluten-free bakery inputs.
- Gelatin raw material limitations:Porcine and bovine collagen sourcing faces religious dietary restriction friction in halal and kosher certification tracks, compressing addressable segments.
- EFSA re-evaluation timelines:Pending additive safety reviews for carrageenan and alginates are extending reformulation approval cycles for Spanish exporters targeting German and French retail chains.
Strategic Opportunities
- Basque Country marine biotech corridor:Underdeveloped agar and carrageenan extraction from Atlantic seaweed biomass offers captive supply integration for plant-based seafood analog producers.
- FSSAI-aligned export positioning:Spanish hydrocolloid refiners can capture premium tier access in Indian food manufacturing by pre-certifying purity benchmarks for dairy and confectionery applications.
- Enzymatic pectin modification:Converging enzyme engineering with citrus peel valorization is opening low-temperature extraction routes that preserve functional esterification patterns.
Industry Challenges
- Clean-label technical staffing shortage:Spanish food science programs are producing insufficient formulation chemists trained in E-number-free hydrocolloid synergies for reduced-sugar applications.
- Multi-certification compliance overhead:Simultaneous EU organic, halal, and FSSAI purity tracking is extending batch release timelines and inflating quality assurance headcount.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Food Hydrocolloids Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Agar, Pectin, Guar Gum Application: Dairy Products, Beverages, Bakery, Confectionery End User: Food Manufacturers, Restaurants, Retail Chains, Catering Services Form: Powder, Liquid, Granulated, Paste |
| Companies Covered | Cargill Incorporated, DuPont de Nemours Inc., CP Kelco U.S. Inc., Ingredion Incorporated, Kerry Group plc, Tate & Lyle PLC, Ashland Global Holdings Inc., ADM, Brenntag AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Food Hydrocolloids Market Evolving Landscape
Spanish hydrocolloid value chains are restructuring around three converging forces: precision fermentation alternatives, regulatory-driven label simplification, and regional biomass valorization programs that extract higher functional grades from domestic agricultural waste streams.
Precision fermentation-derived collagen alternatives are modularizing traditional gelatin supply structures. Barcelona-based biotech facilities are scaling recombinant protein production for Bloom-matched gelling properties. Dairy and pharmaceutical buyers are piloting these inputs to decouple from bovine supply chain religious certification complexity.
EFSA transparency requirements under the EU Food Improvement Agents Package are compressing approved additive lists for Spanish exporters. Reformulation service providers are building dedicated clean-label pectin and starch blend portfolios. Basque dairy cooperatives are front-running compliance by eliminating carrageenan from long-life dessert formulations ahead of anticipated negative consumer sentiment shifts.
Andalusian citrus processors are vertically integrating into pectin extraction from previously waste-streamed peel biomass. Seville-area cooperatives are installing enzymatic demethoxylation capacity for low-sugar jam applications. This geographic demand rotation is reducing Spanish manufacturers' historical dependence on imported apple pomace pectin from French and German suppliers.
Spain Food Hydrocolloids Market Segmentation
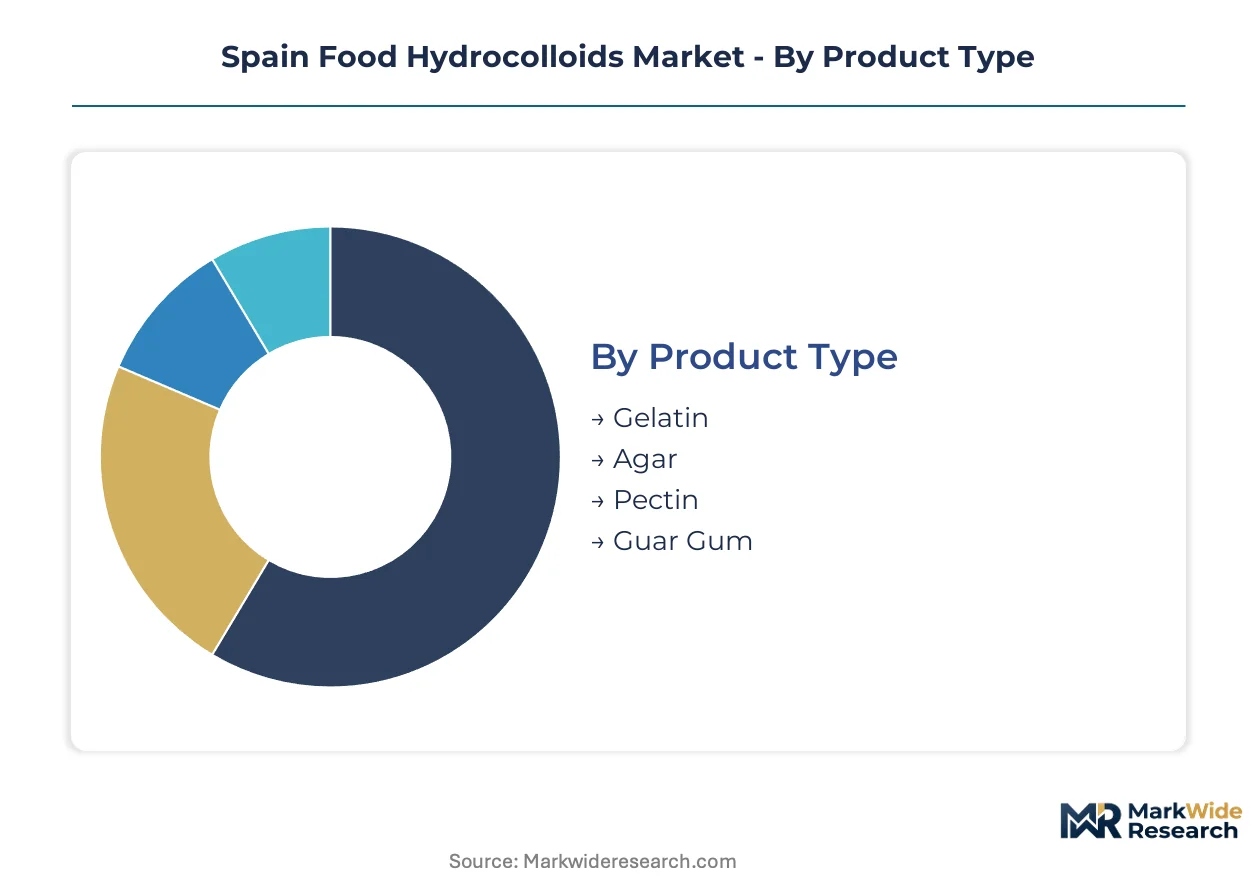
Spanish hydrocolloid procurement splits across functional specifications, application requirements, and certification tiers that determine supplier selection criteria. Manufacturers in Catalonia and the Basque Country prioritize Bloom-strength gelatin grades and low-methoxyl pectin for clean-label positioning, while Madrid bakery clusters optimize cost-performance ratios in gluten-free formulations.
Product Type:
Buyers segment hydrocolloid selection by gelling mechanism, thermal stability, and compatibility with reduced-sugar or E-number-free label claims.
- Gelatin:Collagen-derived protein hydrocolloid requiring controlled acid or alkaline pretreatment to achieve specific Bloom strength ratings for confectionery and pharmaceutical applications. Demand concentrates in Barcelona-area dairy processors seeking halal-certified grades for export-oriented yogurt production under FSSAI-aligned import benchmarks.
- Pectin:Citrus and apple-derived polysaccharide with esterification-dependent gelling behavior. Low-methoxyl grades enabling calcium-set gelation without added sugars are capturing formulation share in Catalan reduced-sugar jam and dessert applications.
- Agar:Red seaweed extract with superior thermal hysteresis for plant-based seafood analogs targeting Barcelona restaurant wholesale channels.
- Guar Gum:Legume seed galactomannan competing aggressively in Madrid and Valencia gluten-free bakery clusters facing FACE celiac certification protocols.
Volume sits with gelatin; growth tilts toward pectin.
Application:
End-use formulation requirements dictate hydrocolloid viscosity profiles, hydration temperatures, and synergy needs with other texturizing agents.
- Dairy Products:Yogurt, cheese, and dessert applications requiring protein-stabilizing and water-binding functionality. EFSA transparency rules are accelerating E-number-free pectin and clean-label starch blend adoption across Basque Country cooperatives.
- Bakery:Gluten-free bread and pastry formulations dependent on guar gum and xanthan synergies for crumb structure and moisture retention. Madrid manufacturing clusters scale these systems under FACE certification demand.
- Beverages:Suspension stabilization and mouthfeel modification in juice and dairy-alternative applications, with carrageenan facing pending EFSA re-evaluation uncertainty.
- Confectionery:Gelatin dominates gummy and marshmallow applications with Bloom-strength specifications; agar serves vegetarian alternatives in Barcelona specialty production.
Revenue concentrates in dairy; reformulation velocity peaks in bakery.
End User:
Procurement scale and technical specification complexity separate institutional buyers from fragmented foodservice operators.
- Food Manufacturers:Large-scale industrial processors with dedicated formulation chemists and multi-certification compliance requirements. These buyers drive specification innovation for clean-label pectin and enzymatically modified hydrocolloids.
- Retail Chains:Private-label developers prioritizing E-number reduction for consumer-facing label claims, absorbing significant cost premiums for premium hydrocolloid grades.
- Restaurants:Barcelona and Madrid high-end establishments sourcing agar and specialty hydrocolloids for molecular gastronomy and plant-based menu development.
- Catering Services:Volume-driven operators emphasizing cost minimization and supply security over functional differentiation.
Specification leadership resides with food manufacturers; price sensitivity concentrates in catering.
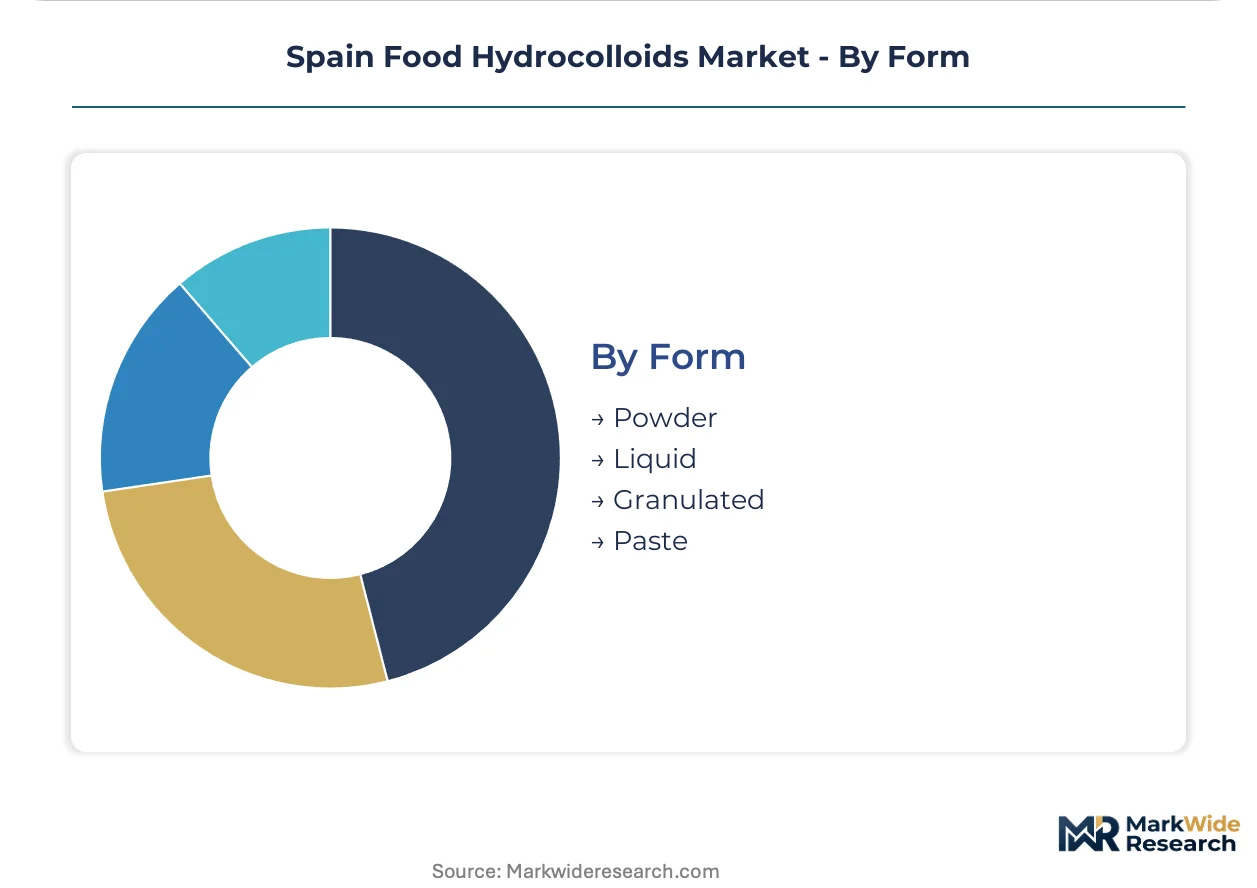
Form:
Handling efficiency, dissolution kinetics, and storage stability determine format selection across manufacturing environments.
- Powder:Dominant format for industrial-scale dispersion and extended shelf-life requirements, standard across gelatin and pectin supply.
- Liquid:Pre-hydrated systems reducing processing time for ready-meal manufacturers and high-throughput dairy operations.
- Granulated:Reduced dusting and improved flow properties for automated bakery ingredient handling systems.
- Paste:Concentrated pre-dispersed formats serving small-batch confectionery and specialty food producers with limited hydration equipment.
Industrial throughput favors powder; convenience-driven segments expand liquid adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barcelona anchors Spain's food hydrocolloids demand through its concentration of dairy processors and plant-based seafood innovators sourcing specialized agar and pectin grades. The metropolitan corridor channels reformulation activity under EU EFSA transparency mandates while serving as the primary distribution node for Iberian co-manufacturers.
Catalonia
Reduced-sugar yogurt producers in Girona and Lleida drive low-methoxyl pectin consumption for calcium-set gelation without added sugars. EFSA additive transparency rules accelerate E-number elimination from dessert formulations. Barcelona's ingredient distribution infrastructure supplies tailored hydrocolloid blends to co-manufacturers across the Mediterranean basin.
Basque Country
Marine biotech facilities in Bilbao and San Sebastián extract agar and carrageenan from Atlantic seaweed biomass for plant-based seafood analogs. EU Green Deal packaging mandates stimulate hydrocolloid barrier coating development for ready-meal applications. Dairy cooperatives in Álava eliminate carrageenan ahead of anticipated regulatory shifts.
Madrid
Gluten-free bakery clusters in the capital absorb guar gum and xanthan volumes under FACE celiac certification protocols. The national food safety agency evaluations shape hydrocolloid approval timelines for formulations targeting retail chains. Automated ingredient handling systems favor granulated formats for high-throughput production.
Andalusia
Seville-area citrus processors vertically integrate into pectin extraction from peel biomass previously waste-streamed. Enzymatic demethoxylation capacity serves low-sugar jam applications across southern Spain. This geographic rotation reduces dependence on imported apple pomace pectin from French suppliers.
Valencia
Bakery manufacturing zones scale hydrocolloid synergies for gluten-free crumb structure and moisture retention. Port infrastructure facilitates guar gum imports from India subject to BIS-aligned quality certifications. Formulation chemists cluster here to serve pan-Mediterranean export contracts.
Spain Food Hydrocolloids Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and functional-specification dimensions, with clean-label pectin and gelatin commanding significant price spreads over standard grades. The vendor base stratifies into three tiers: multinational ingredient conglomerates with integrated extraction and distribution networks, regional refiners specializing in single hydrocolloid categories, and commodity traders sourcing bulk guar gum from Indian crop cycles. Consolidation pressure intensifies as dairy and bakery manufacturers reduce supplier counts to streamline multi-certification compliance overhead. Dominant competitive moves include captive supply integration into citrus peel and seaweed biomass streams, plus enzymatic modification technology licensing for low-temperature pectin extraction.
Within the multinational conglomerate tier, Cargill Incorporated and Kerry Group plc exemplify divergent strategic positioning—Cargill anchoring pectin supply through its Barcelona distribution hub while Kerry Group plc occupies a position in specialized texturizing systems for ready-meal producers. Among US-based diversified ingredient suppliers, DuPont de Nemours Inc. and Ingredion Incorporated represent the scale-driven archetype with broad hydrocolloid portfolios spanning multiple functional categories. These named entities serve as reference points for market structure analysis without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Cargill Incorporated |
| DuPont de Nemours Inc. |
| CP Kelco U.S. Inc. |
| Ingredion Incorporated |
| Kerry Group plc |
| Tate & Lyle PLC |
| Ashland Global Holdings Inc. |
| ADM |
| Brenntag AG |
| Others |
Value Network & Pricing Analysis
Indian monsoon-dependent guar gum crop cycles feed directly into Madrid bakery procurement costs, with BIS-aligned certification premiums cascading through gluten-free formulation pricing tiers before reaching FACE-certified manufacturers.
Pricing Analysis
Value-based pricing anchors on E-number-free certification grades that command substantial spreads over standard hydrocolloid tiers. Three-tier pricing structure across premium clean-label, standard food-grade, and economy bulk levels separates Basque dairy cooperatives from Madrid cost-optimizers. Pricing pressure stems from EU EFSA transparency mandates accelerating reformulation timelines. Retail chains absorb the highest premiums; catering services exhibit greatest price sensitivity.
Supply Chain Analysis
Dual-sourcing requirements from Spanish manufacturers mandate simultaneous Indian and Pakistani guar gum qualification to mitigate monsoon crop volatility. Raw material dependencies center on citrus peel from Andalusia, Atlantic seaweed from Galicia, and collagen from European abattoirs. Single-source vulnerability concentrates in Indian guar gum supply. Distribution runs through Barcelona's ingredient hub serving Iberian co-manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation-derived collagen alternatives are displacing traditional gelatin supply structures, with Barcelona biotech facilities scaling recombinant proteins that match Bloom strength specifications without religious certification complexity.
For Market Incumbents: Anticipate EFSA carrageenan re-evaluation outcomes by accelerating clean-label pectin portfolio expansion ahead of anticipated negative consumer sentiment shifts. Backward integration into Andalusian citrus peel biomass secures captive low-methoxyl pectin supply. Certification investment in FSSAI-aligned purity benchmarks opens premium Indian export channels.
For New Entrants and Emerging Players: Begin with enzymatic pectin modification technology licensing to Basque dairy cooperatives seeking reduced-sugar formulation capabilities. The most penetrable white-space sits in marine biotech corridor agar extraction from Atlantic seaweed biomass. Direct technical service models outperform commodity trading for plant-based seafood analog producers.
For Investors and Strategic Acquirers: First commercial precision fermentation collagen production at Bloom-matched specifications is the leading indicator that traditional gelatin supply chains face structural displacement. Long-term viability favors enzymatic modification technology holders over commodity refiners. Acquisition targets should demonstrate citrus peel valorization integration or seaweed biomass captive supply. Watch for EFSA additive delisting announcements as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Pectin Modification Licensing | Enables low-temperature extraction preserving functional esterification for Catalan reduced-sugar applications. |
| Atlantic Seaweed Biomass Integration | Captures agar and carrageenan supply for Basque plant-based seafood analog producers. |
| FSSAI Purity Pre-Certification | Unlocks premium tier access in Indian dairy and confectionery manufacturing import channels. |
| Precision Fermentation Scale-Up | Decouples gelatin supply from bovine collagen religious certification constraints. |
| Citrus Peel Valorization Partnership | Reduces Andalusian processor dependence on imported French apple pomace pectin. |
Research Methodology
Independent corroboration across formulation chemists at Catalan dairy cooperatives, procurement leads at Madrid gluten-free bakery clusters, and regulatory affairs specialists at Spanish food safety agencies underwrites the qualitative findings. Secondary validation draws from EU EFSA additive safety evaluations, BIS certification protocols for Indian guar gum imports, and FACE celiac association formulation guidelines. Bottom-up volume triangulation against top-down expenditure analysis ensures convergence.
Rate-of-change decomposition across product type, application, and certification tier segments isolates growth drivers throughout the forecast period. CAGRs derive from hydrocolloid adoption elasticity in reduced-sugar dairy and gluten-free bakery verticals. Industry-specific inputs include EFSA re-evaluation timelines and monsoon crop yield correlations.
EFSA additive delisting decisions, Indian monsoon disruption severity, and precision fermentation cost parity achievement are the dominant revision risks. Deviation in regulatory timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
India Food Hydrocolloids Market
Food Components and Additives
Natural Fatty Acids Market
Food Components and Additives
Food Grade Antifoams Market
Food Components and Additives
Argentina Food Hydrocolloids Market
Food Components and Additives
USA Food Premix Market
Food Components and Additives
Fermentation Defoamer Market
Food Components and Additives
Asia-Pacific Food Anti Caking Agents Market
Food Components and Additives
Europe Food Stabilizers Market
Food Components and Additives
Food Coating Market
Food Components and Additives
Clean Label Pectin Market
Food Components and Additives
Flavonoids Market
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
Fillings and Toppings Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
Edible Oil Co-Products and by-Products Market
Food Components and Additives
Europe Omega-3 for Food Application Market