
 Polyphenol Antioxidant Market | 2026-2036
Polyphenol Antioxidant Market Size, Share, and Industry Trends Forecast 2026-2036
Polyphenol Antioxidant Market Analytics
Pharmaceutical-grade polyphenol specifications is redrawing competitive boundaries as buyers demand batch-certified purity above 95% with full traceability documentation. DSM-Firmenich AG leverages its integrated biotechnology platform to secure consistent supply chains for high-purity extracts. Kemin Industries, Inc. anchors its position through captive cultivation partnerships that control raw material quality from seed to extract. Indena S.p.A. specializes in phytosome delivery technologies that enhance bioavailability for pharmaceutical applications.
Polyphenol antioxidants comprise a class of organic compounds characterized by multiple phenol structural units, typically extracted via solvent or supercritical CO2 methods, with standardized ORAC values and total phenolic content measured by Folin-Ciocalteu assay. These compounds function primarily to neutralize free radicals in biological systems and extend oxidative stability in formulated products. Flavonoids and phenolic acids occupy the largest volume positions, reflecting mature supply infrastructure from grape seed, green tea, and berry sources. Extract and powder forms capture diverging margin pools, with extracts commanding premium positioning in nutraceuticals while powder formulations scale efficiently into mass-market food applications.
The FDA's New Dietary Ingredient notification framework and EFSA's health claims assessment process jointly determine market access timelines for novel polyphenol formulations in North America and Europe. REACH compliance and FSSC 22000 certification now function as baseline qualifiers for supplier qualification by multinational food and pharmaceutical manufacturers. Stakeholders must monitor evolving substantiation thresholds for structure-function claims, as regulatory divergence between FDA enforcement discretion and EFSA's Article 13.1 evaluation creates divergent product development pathways requiring dual-track clinical investment.
Market Dynamics
Pharmaceutical-grade purity specifications are compressing supplier margins while concentrating procurement authority among buyers capable of certifying batch-level traceability from cultivation through extraction.
Growth Catalysts
- EFSA Article 13.1 Health Claims:Tightened substantiation requirements for antioxidant claims in the European Union are pushing food and beverage manufacturers toward clinically validated polyphenol formulations, expanding demand for standardized extracts.
- Functional Beverage Fortification:Clean-label product pipelines in Germany, the Netherlands, and France are accelerating incorporation of grape seed and green tea polyphenols into ready-to-drink formulations.
- Supercritical CO2 Extraction:Adoption of solvent-free processing methods is reducing residual contamination risks and opening pharmaceutical applications previously closed to conventional solvent extracts.
Market Restraints
- Raw Material Volatility:Climate-sensitive berry and tea harvests in China and India create input cost instability that propagates through contract pricing structures.
- REACH Compliance Burden:European Chemicals Agency registration requirements for novel extract compositions impose documentation costs that exclude smaller regional suppliers from multinational qualification.
- Synthetic Antioxidant Substitution:Butylated hydroxytoluene and tertiary butylhydroquinone retain cost advantages in mass-market food preservation, limiting polyphenol penetration in price-sensitive categories.
Strategic Opportunities
- Phytosome Delivery Convergence:Integration of phospholipid complexation technology with high-purity extracts is unlocking enhanced bioavailability claims for nutraceutical applications.
- US NDI Notification Pathway:FDA's New Dietary Ingredient framework, while rigorous, creates first-mover advantages for suppliers investing in GRAS self-affirmation and clinical dossiers.
- Direct-to-Consumer Subscription Channels:Polyphenol supplement brands are bypassing traditional retail distribution through personalized nutrition platforms that capture recurring revenue and margin expansion.
Industry Challenges
- Analytical Chemist Scarcity:Folin-Ciocalteu assay standardization and ORAC value certification require specialized personnel that extract manufacturers struggle to recruit at scale.
- FSSC 22000 Audit Timelines:Certification backlogs at accredited bodies delay supplier qualification by multinational food manufacturers, compressing formulation-to-launch windows.
- Legacy Formulation Integration:Pharmaceutical clients face technical friction incorporating polyphenol extracts into existing tablet and capsule production lines optimized for synthetic actives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyphenol Antioxidant Market |
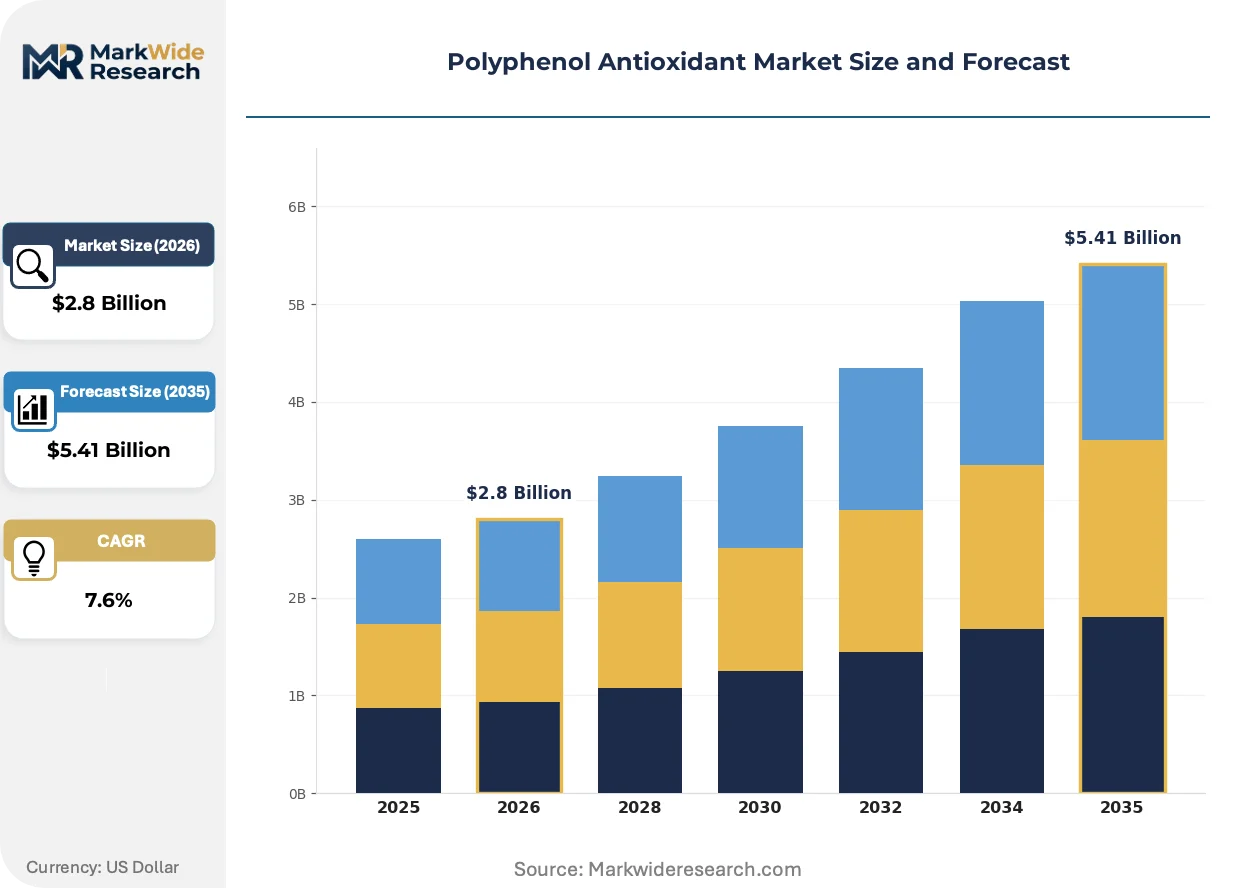
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavonoids, Phenolic Acids, Polyphenolic Compounds, Stilbenes Application: Food & Beverage, Nutraceuticals, Cosmetics, Pharmaceuticals Form: Powder, Liquid, Extracts, Capsules Source: Fruits, Vegetables, Teas, Grains |
| Companies Covered | Cargill, Incorporated, DSM-Firmenich AG, International Flavors & Fragrances Inc., Givaudan SA, Archer Daniels Midland Company, Ajinomoto Co. Inc., Indena S.p.A., Biolink Group, Kemin Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyphenol Antioxidant Market Evolving Landscape
Extraction technology advancement and regulatory claim substantiation are converging to redefine competitive positioning across pharmaceutical, nutraceutical, and food-grade supply tiers.
Supercritical CO2 extraction systems are decomposing the traditional solvent-based infrastructure that has dominated polyphenol production for decades. Pharmaceutical manufacturers in Switzerland and Germany are retrofitting facilities to capture pharmaceutical-grade certification advantages. This technology shift is compressing the addressable market for conventional ethanol and methanol extract suppliers while concentrating premium supply among capital-intensive operators.
REACH registration requirements for novel botanical substances are tightening documentation obligations across European supply chains. Industrial consequence includes extended qualification timelines that favor incumbent suppliers with existing dossiers. Small and mid-sized extract houses in Italy and Spain are responding through collaborative registration consortia that distribute compliance costs across regional cooperatives.
Clean-label procurement committees at multinational food manufacturers are mandating certified organic and non-GMO polyphenol streams for new product development. Traditional commodity brokers are losing shelf space to vertically integrated extract houses with captive cultivation and full chain-of-custody documentation. This preference shift is most visible in German and French functional beverage launches where packaging prominently features origin-specific polyphenol sourcing claims.
Polyphenol Antioxidant Market Segmentation
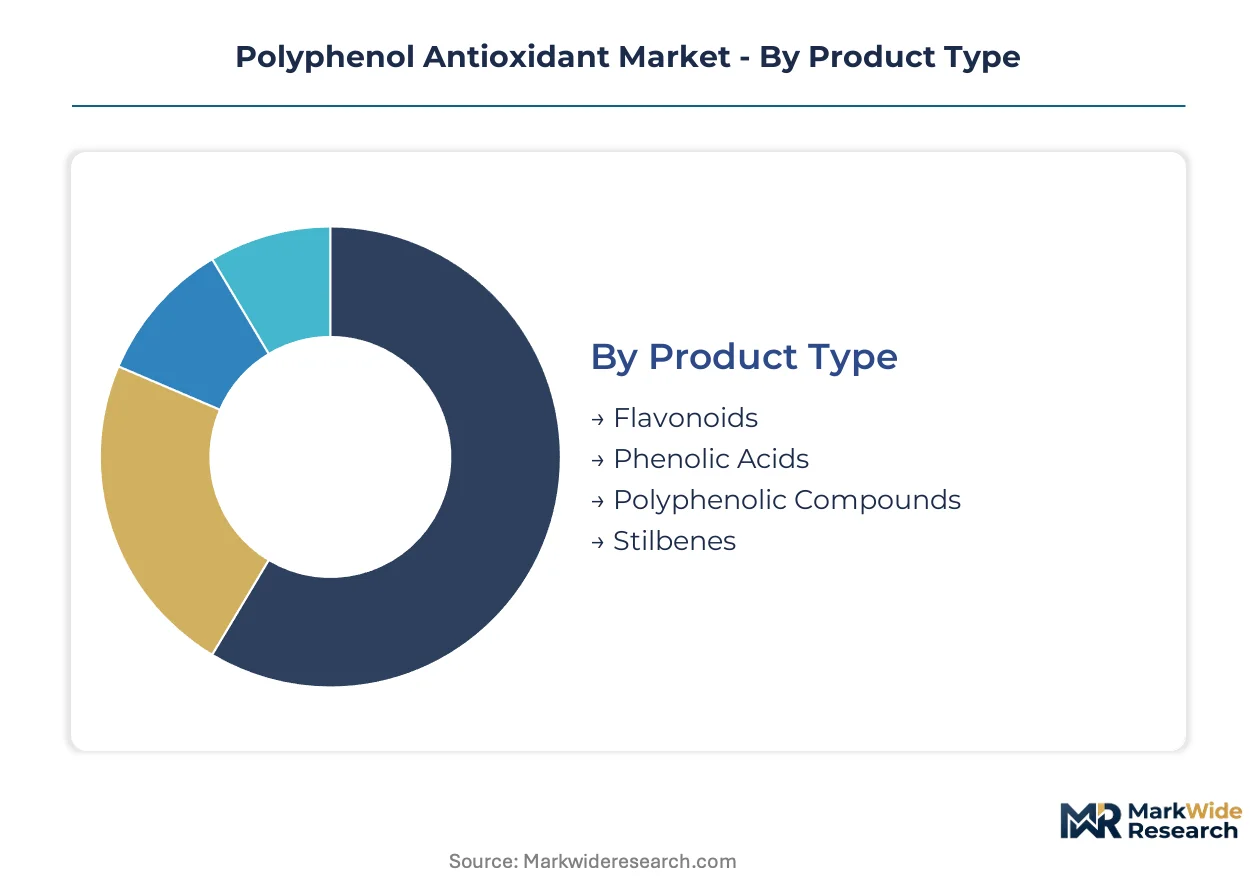
Polyphenol antioxidant procurement patterns diverge sharply across purity grades and end-use specifications, with pharmaceutical buyers demanding batch-certified documentation while food manufacturers prioritize cost-scalable powder formats. Segmentation reveals how extraction technology and regulatory claim substantiation redistribute margin pools across supply tiers.
Product Type:
Margin concentration tracks closely to bioavailability enhancement potential and clinical validation depth, with pharmaceutical-grade specifications commanding substantial premia over commodity food-grade streams.
- Flavonoids:This class encompasses catechins, anthocyanins, and proanthocyanidins extracted predominantly from grape seed and green tea matrices. Demand concentrates in German and Swiss nutraceutical formulation facilities where EFSA Article 13.1 health claim substantiation requirements favor standardized extracts with documented ORAC values and Folin-Ciocalteu certification. The phytosome delivery convergence is expanding addressable applications for high-purity flavonoid streams.
- Phenolic Acids:Hydroxycinnamic and hydroxybenzoic acid derivatives from coffee, berries, and cereal brans constitute the volume foundation for mass-market food preservation applications. Clean-label procurement committees at French and Dutch beverage manufacturers are rotating specifications toward certified organic phenolic acid streams with full seed-to-extract traceability documentation.
- Polyphenolic Compounds:Complex oligomeric structures from maritime pine bark and olive fruit deliver concentrated antioxidant capacity for premium cosmetic formulations.
- Stilbenes:Resveratrol and pterostilbene from grape skin and Japanese knotweed command niche positioning in longevity-focused supplement channels.
Flavonoids hold installed capacity. Phenolic acids is rotating up the share rankings.
Application:
End-use differentiation separates specification-intensive pharmaceutical and nutraceutical tiers from commodity food preservation markets where synthetic antioxidant substitution pressure remains acute.
- Food & Beverage:Functional beverage fortification in Germany, France, and the Netherlands is accelerating incorporation of grape seed and green tea polyphenols into ready-to-drink formulations. Clean-label product pipelines demand certified organic and non-GMO streams with origin-specific sourcing claims prominently featured on packaging.
- Nutraceuticals:Direct-to-consumer subscription channels are bypassing traditional retail distribution through personalized nutrition platforms that capture recurring revenue and margin expansion. Phytosome delivery technologies enhance bioavailability claims for high-purity extract formulations.
- Cosmetics:Topical antioxidant protection applications in Swiss and French dermocosmetic brands specify low-molecular-weight polyphenol fractions for skin penetration optimization.
- Pharmaceuticals:Batch-certified purity above 95% with full traceability documentation is compressing supplier margins while concentrating procurement authority among buyers with qualification capabilities.
Food and beverage maintains volume leadership. Nutraceuticals is climbing the fastest.
Form:
Physical presentation determines supply chain configuration and margin capture, with extracts commanding premium positioning while powder formulations scale efficiently into mass-market applications.
- Powder:Spray-dried and freeze-dried formats enable efficient incorporation into bakery, confectionery, and dry beverage premix applications. German food manufacturers specify powder streams for clean-label product pipelines where processing economics favor high-volume, low-margin procurement.
- Extracts:Standardized liquid and semi-solid concentrates with defined total phenolic content and solvent residue specifications serve pharmaceutical and nutraceutical formulation requirements. Supercritical CO2 extraction adoption is reducing residual contamination risks and opening applications previously closed to conventional solvent extracts.
- Liquid:Aqueous and hydroalcoholic solutions facilitate direct incorporation into beverage matrices without reconstitution steps.
- Capsules:Pre-dosed solid dosage forms eliminate formulation complexity for supplement brands lacking in-house tableting capabilities.
Extracts hold installed capacity. Powder is rotating up the share rankings.
Source:
Raw material provenance governs supply security and certification eligibility, with climate-sensitive harvests creating input cost instability that propagates through contract pricing structures.
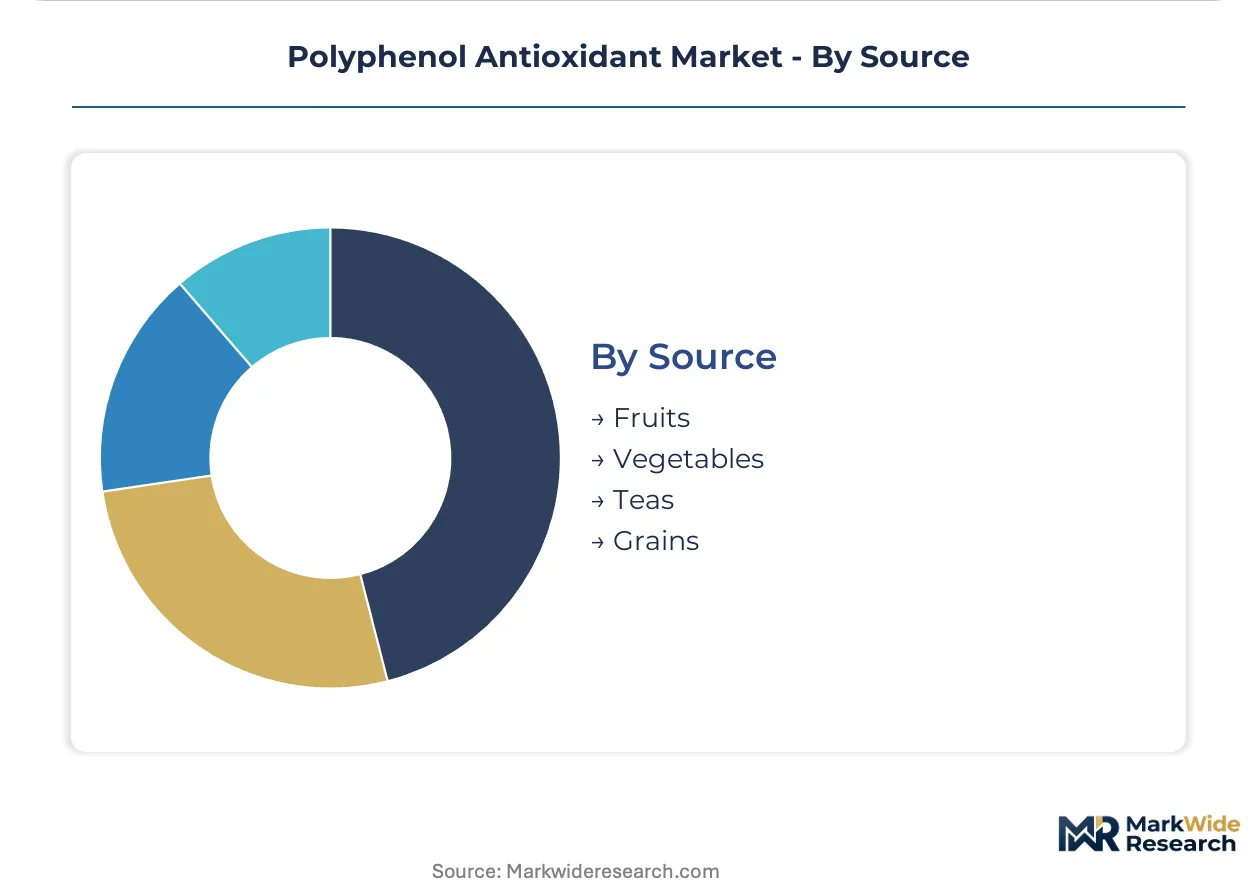
- Fruits:Berry crops from China and India supply anthocyanin-rich streams for cosmetic and nutraceutical applications. Climate volatility in these sourcing regions creates procurement risk that vertically integrated extract houses address through captive cultivation partnerships controlling quality from seed to extract.
- Teas:Camellia sinensis leaf processing in China and India generates catechin concentrates for beverage fortification and supplement applications. EFSA health claim substantiation requirements are pushing buyers toward clinically validated tea polyphenol formulations with standardized EGCG content.
- Vegetables:Onion skin and artichoke leaf supply luteolin and cynarin derivatives for niche pharmaceutical applications.
- Grains:Cereal bran fractions deliver ferulic acid and related hydroxycinnamic acids for food preservation and cosmetic antioxidant applications.
Teas hold installed capacity. Fruits is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports standardized green tea catechins to German nutraceutical formulators, while India supplies berry anthocyanins to Swiss cosmetic manufacturers. These trade corridors concentrate procurement authority among buyers with REACH-compliant qualification capabilities.
Germany
Functional beverage manufacturers in Hamburg and Frankfurt drive demand for certified organic polyphenol streams with full traceability documentation. EFSA's Article 13.1 health claims assessment process governs antioxidant claim substantiation requirements. The Frankfurt-Rhine-Main cluster hosts rapid formulation-to-market pipelines for polyphenol-enriched consumer goods.
United States
Direct-to-consumer supplement brands bypass traditional retail through personalized nutrition platforms capturing recurring revenue. FDA's New Dietary Ingredient notification framework determines market access timelines for novel polyphenol formulations. Greater Boston and San Diego biotech corridors concentrate pharmaceutical-grade extract development capabilities.
Switzerland
Swiss dermocosmetic brands specify low-molecular-weight polyphenol fractions for skin penetration optimization in topical applications. Swissmedic certification requirements anchor pharmaceutical-grade purity specifications for batch-level documentation. The Basel-Zurich corridor concentrates supercritical CO2 extraction retrofit investments for solvent-free processing advantages.
France
Clean-label procurement committees at multinational food manufacturers mandate certified organic and non-GMO polyphenol streams for new product development. ANSM and DGCCRF enforcement shapes compliance obligations for cosmetic and food applications respectively. The Lyon-Grenoble cluster advances phytosome delivery technology integration with high-purity extracts.
China
Camellia sinensis leaf processing generates catechin concentrates for beverage fortification and supplement applications. NMPA and SAMR regulations govern dietary ingredient and food additive classifications. The Zhejiang and Fujian provinces concentrate tea polyphenol extraction capacity serving international buyers.
Polyphenol Antioxidant Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and extraction technology vectors. The supplier base concentrates among integrated biotechnology platforms, captive cultivation partnerships, and specialized delivery technology developers. Three archetypes dominate: integrated life-science conglomerates with fermentation and extraction capabilities, mid-sized extract houses with backward-integrated agricultural operations, and technology specialists focused on bioavailability enhancement. Competitive moves center on supercritical CO2 capacity expansion and collaborative REACH registration consortia.
Within the integrated platform tier, DSM-Firmenich AG represents biotechnology-backed supply consistency, while Indena S.p.A. exemplifies delivery technology specialization through phytosome complexation. Kemin Industries, Inc. anchors the captive cultivation archetype with seed-to-extract quality control. These three occupy positions spanning pharmaceutical-grade certification, functional food scale, and nutraceutical bioavailability enhancement respectively.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| DSM-Firmenich AG |
| International Flavors & Fragrances Inc. |
| Givaudan SA |
| Archer Daniels Midland Company |
| Ajinomoto Co. Inc. |
| Indena S.p.A. |
| Biolink Group |
| Kemin Industries, Inc. |
| Others |
Value Network & Pricing Analysis
Supercritical CO2 extraction capacity utilization above eighty percent in Swiss and German facilities compresses unit economics for pharmaceutical-grade streams while elevating price floors for conventional solvent-based alternatives. This scale asymmetry concentrates procurement leverage among buyers with REACH-compliant qualification capabilities and full batch-traceability documentation requirements.
Pricing Analysis
Next-generation supercritical CO2 extraction systems command forty to sixty percent premia over conventional solvent infrastructure, while legacy ethanol-based processing faces accelerating price erosion from purity-grade discounting. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-standard, and food-economy levels separates batch-certified extracts with full documentation from commodity powder streams. Cost compression in food-grade tiers intensifies because synthetic antioxidant substitution remains viable for price-sensitive mass-market applications. Nutraceutical formulators in Germany and Switzerland exhibit lowest price sensitivity due to EFSA health claim substantiation requirements, while commodity food manufacturers in France and the Netherlands face acute budget constraints.
Supply Chain Analysis
Zhejiang and Fujian province tea processing chokepoints underwrite catechin concentrate availability for international nutraceutical formulators. Raw material sourcing draws from Camellia sinensis cultivation in China, berry harvests in India, and maritime pine bark extraction in southwestern France. Single-source vulnerability concentrates in climate-sensitive Indian berry regions where monsoon variability propagates through annual contract pricing. Distribution runs through Rotterdam and Hamburg port consolidation hubs serving European pharmaceutical and food manufacturers with just-in-time qualification documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction technology diffusion is disrupting incumbent solvent-based infrastructure, while EFSA Article 13.1 health claim tightening creates regulatory moats for clinically validated suppliers.
For Market Incumbents: Shield installed capacity advantages by accelerating FSSC 22000 certification coverage across all production facilities and securing captive cultivation partnerships in climate-stable sourcing regions. Synthetic antioxidant cost competition threatens mass-market food-grade margins; pharmaceutical-grade purity specifications offer defensive repositioning toward substantiation-intensive nutraceutical channels. For New Entrants and Emerging Players: Direct-to-consumer subscription fulfillment gaps where incumbents under-serve create white-space opportunities for personalized nutrition platforms with recurring revenue capture. Target phytosome delivery technology integration for bioavailability-enhanced formulations; Swiss and German pharmaceutical buyers show highest penetration readiness for novel delivery mechanisms. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors extract houses with backward-integrated agricultural operations and existing REACH registration dossiers. Long-term viability across the analysis window rests on supercritical CO2 capacity scale and clinical validation depth. Watch EFSA Article 13.1 claim approval velocity as inflection indicator for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Swiss and German pharmaceutical manufacturers retrofit facilities to capture solvent-free processing certification advantages. |
| Captive Cultivation Partnership | Kemin Industries anchors seed-to-extract quality control through backward-integrated agricultural operations in specified regions. |
| Phytosome Delivery Development | Indena S.p.A. specializes in phospholipid complexation technology enhancing bioavailability for nutraceutical applications. |
| REACH Registration Consortium | Italian and Spanish extract houses distribute compliance costs through collaborative regional cooperatives. |
| Direct-to-Consumer Channel Launch | Polyphenol supplement brands bypass traditional retail through personalized nutrition platforms capturing recurring revenue. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA health claim registers, FDA New Dietary Ingredient notifications, and FSSC 22000 certification databases. Extract manufacturer executives, pharmaceutical formulation scientists, and food procurement directors at multinational manufacturers provided operational validation. Customs trade data, botanical extract import records, and REACH registration filings supplied quantitative anchoring. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Segmentation dimensions modeled include purity grade tier, extraction technology type, end-use application, and geographic regulatory cluster across the projection horizon. CAGRs derive from installed capacity utilization trajectories, EFSA claim approval pipelines, and supercritical CO2 adoption curves. Forecast inputs incorporate climate volatility indices for Indian and Chinese sourcing regions and synthetic antioxidant price parity thresholds.
Forecasts assume regulatory continuity in EFSA Article 13.1 evaluation procedures and FDA NDI enforcement discretion; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as REACH documentation requirements and climate adaptation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Germany Food Preservatives Market
Food Components and Additives
Food Texture Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
United Kingdom Food Hydrocolloids Market
Food Components and Additives
France Food Hydrocolloids Market
Food Components and Additives
Isoflavones Market
Food Components and Additives
Polyphenols Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Food Grade Xanthan Gum Market
Food Components and Additives
Food Coating Market
Food Components and Additives
Fermentation Defoamer Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Food Grade Antifoams Market
Food Components and Additives
Europe Food Premix Market