
 Smelting Furnace Equipment Market | 2026-2036
Smelting Furnace Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Smelting Furnace Equipment Market Analytics
India's steel sector capacity build-out is fragmenting the supplier landscape for large-scale furnace systems. Tenova S.p.A. leverages its electric arc furnace technology leadership to anchor major greenfield projects across South Asia. SMS Group competes through integrated plant engineering that extends from furnace design to downstream rolling equipment. ANDRITZ AG specializes in environmental and process efficiency retrofits that sustain margins in mature metallurgy markets.
Smelting furnace equipment comprises industrial thermal processing systems designed to melt, refine, and cast metals at temperatures exceeding 1,500°C, utilizing refractory-lined vessels with controlled atmosphere and energy delivery mechanisms. Electric arc furnaces command the largest installed base due to scrap-metal flexibility and lower carbon intensity relative to integrated blast furnace routes, though blast furnaces retain dominance in primary iron production where ore quality and scale economics favor coke-based reduction. Induction furnaces represent the fastest-expanding product category in non-ferrous metallurgy and foundry applications, driven by precise temperature control and alloy consistency requirements in aluminum and copper processing.
EPA emissions standards and OSHA workplace exposure limits in the United States compel furnace operators to invest in fume extraction and refractory dust containment systems, directly shaping equipment specification sheets and procurement criteria. China's MEE enforces dual carbon goals that restrict new blast furnace approvals while accelerating electric heating technology substitutions in steelmaking. Stakeholders must monitor how regulatory divergence between carbon-border-adjustment regimes and domestic emissions trading systems reshapes furnace technology investment timelines and geographic equipment deployment priorities.
Market Dynamics
The electric arc furnace transition in China's steel sector is compressing blast furnace equipment procurement cycles while fragmenting supplier relationships across Asia-Pacific project sites.
Growth Catalysts
- China's dual carbon goals:The MEE restrictions on new blast furnace approvals are accelerating electric heating technology substitutions in steelmaking, redirecting capital toward scrap-metal-flexible furnace systems.
- Non-ferrous metallurgy expansion:India's foundry sector is scaling induction furnace deployments for aluminum and copper processing, driven by precise temperature control requirements in alloy consistency-sensitive applications.
- Refractory material advances:Ceramic matrix composite linings are extending vessel campaign lives beyond 7,000 heats, reducing rebuild frequency and total cost of ownership for continuous casting operations.
Market Restraints
- Graphite electrode supply concentration:Ultra-high-power electrode manufacturing clusters in China and India expose electric arc furnace operators to price volatility and single-source dependency risks.
- Refractory raw material scarcity:Magnesite ore export quotas from Chinese provinces are constraining dolomite brick availability and inflating lining replacement costs for integrated steelworks.
- Blast furnace route lock-in:High-grade iron ore dependencies in Western Australia and Brazil perpetuate coke-based reduction economics for primary steel producers despite carbon intensity penalties.
Strategic Opportunities
- Vietnam's steel capacity build-out:Greenfield electric arc furnace projects in Ba Ria-Vung Tau and Ha Tinh provinces are creating demand for turnkey furnace-electrical-transformer packages from European engineering firms.
- Hydrogen-ready furnace retrofits:The EU Green Deal's carbon border adjustment mechanism is incentivizing blast furnace operators to install tuyere injection systems compatible with hydrogen-natural gas blends.
- Digital twin integration:Real-time thermal modeling software is converging with furnace control systems, enabling predictive refractory wear monitoring and optimized energy input sequencing.
Industry Challenges
- Refractory installation specialist shortage:Certified gunning and bricklaying crews for hot repair work are scarce in Southeast Asian project corridors, extending outage schedules.
- Legacy DCS integration complexity:Brownfield furnace upgrades require protocol bridging between 1990s-era distributed control systems and modern IIoT sensor networks, inflating commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smelting Furnace Equipment Market |
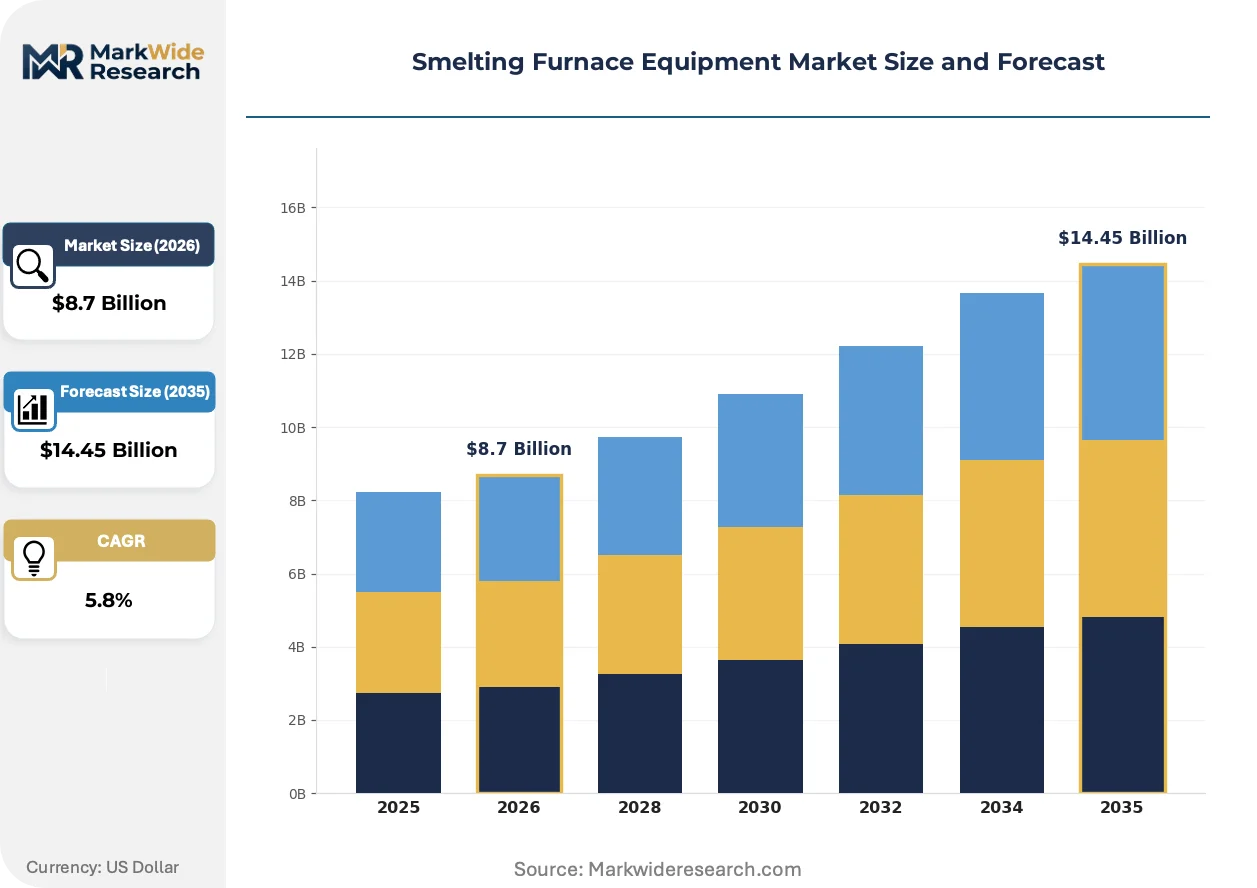
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Induction Furnaces, Electric Arc Furnaces, Blast Furnaces, Cupola Furnaces Technology: Electric Heating, Gas Heating, Coal Heating, Induction Heating End User: Metal Recycling, Steel Manufacturing, Non-Ferrous Metallurgy, Foundries Application: Metal Extraction, Alloy Production, Waste Management, Casting |
| Companies Covered | ANDRITZ AG, Tenova S.p.A., SMS Group, SECO/WARWICK Group, Inductotherm Group, ABB Group, Ipsen International GmbH, Carbolite Gero, Lindberg/MPH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smelting Furnace Equipment Market Evolving Landscape
Smelting furnace architecture is fragmenting into modular, electrified configurations that decouple melting capacity from fixed infrastructure investments.
Plasma torch technology is hybridizing with conventional electric arc furnace shells to enable direct reduced iron melting at lower specific energy consumption. Mini-mill operators in Turkey and Italy are piloting 50-ton hybrid vessels for specialty steel grades. This convergence is compressing the cost gap between scrap-based and ore-based steelmaking routes.
The EU's F-Gas Regulation is phasing down sulfur hexafluoride use in magnesium die-casting protection systems, compelling furnace operators to adopt sulfur dioxide or carbon dioxide alternative cover gases. German automotive foundries are retrofitting holding furnaces with sealed lid designs and automated gas injection. Induction furnace suppliers are integrating closed-loop atmosphere control to capture this compliance-driven replacement cycle.
Equipment-as-a-service contracting is displacing capital purchase models for mid-scale non-ferrous producers. Furnace OEMs in India are offering throughput-based pricing with bundled refractory maintenance and energy optimization consulting. This shift is most visible in Gujarat's aluminum extrusion cluster, where foundries prioritize operational expenditure predictability over asset ownership.
Smelting Furnace Equipment Market Segmentation
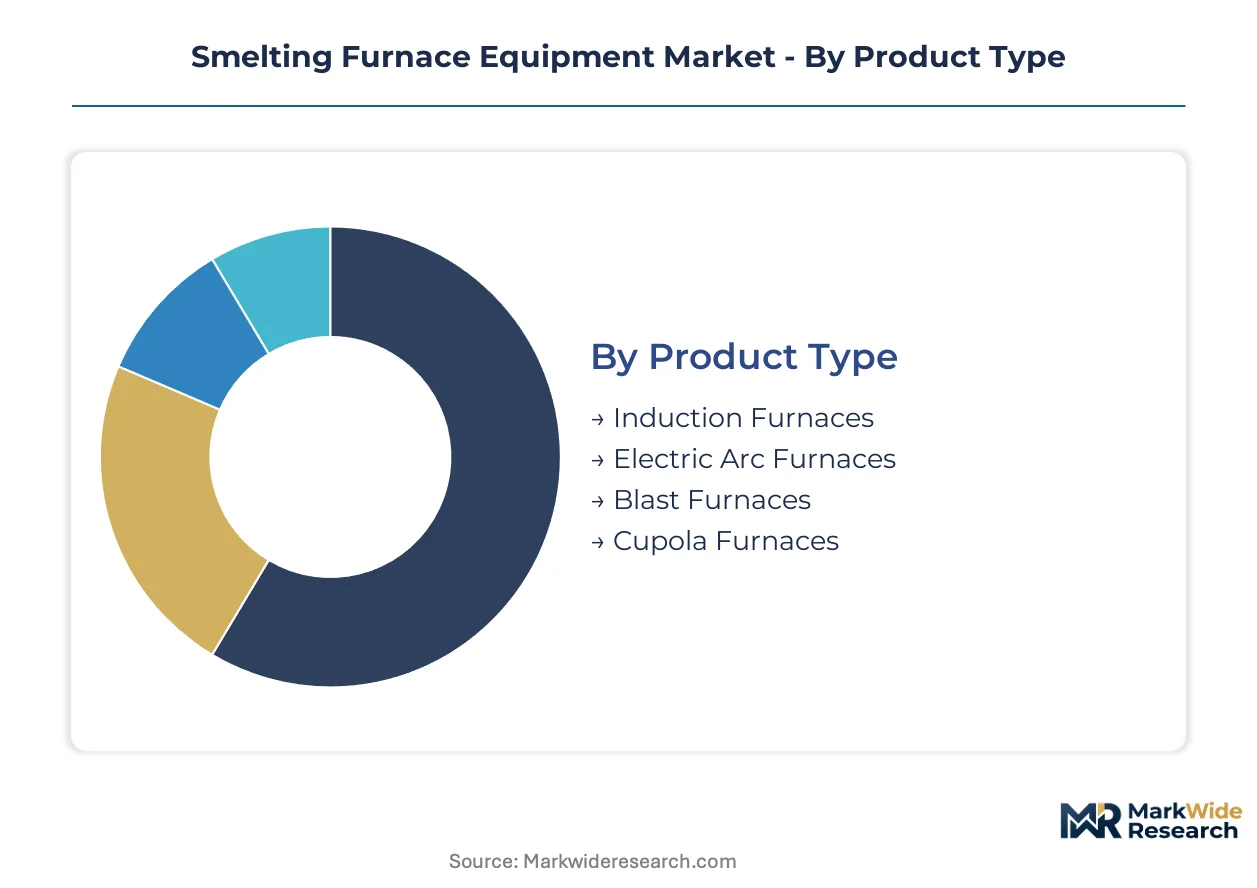
Equipment segmentation in smelting furnace systems determines procurement specifications, energy input configurations, and aftermarket service bundling. Buyers align furnace category selection with feedstock chemistry, production scale targets, and emissions compliance pathways.
Product Type:
After-sales service intensity varies sharply across furnace architectures, with refractory-dependent systems demanding scheduled rebuild contracts and electrode-based designs requiring continuous consumables management.
- Electric Arc Furnaces:Graphite electrode systems operating at 1,600-1,800°C enable scrap-metal flexibility with lower carbon intensity than integrated blast furnace routes. Steel manufacturers in China are redirecting capital toward these systems under MEE restrictions on new blast furnace approvals.
- Induction Furnaces:Electromagnetic field heating delivers precise temperature control for aluminum and copper alloy consistency. Foundries across India's Gujarat cluster are scaling deployments for extrusion-grade billet production.
- Blast Furnaces:Coke-based reduction vessels retain dominance in primary iron production where Western Australian and Brazilian high-grade ore dependencies favor scale economics.
- Cupola Furnaces:Shaft melting systems using coke fuel remain concentrated in gray iron foundries serving automotive brake component manufacturers.
By volume, blast furnaces lead in installed base. By growth pace, induction furnaces are expanding most quickly.
Technology:
Energy input modality shapes capital expenditure profiles and operating cost structures across metallurgy operations.
- Electric Heating:Resistive and arc-based systems command procurement priority in markets with carbon pricing mechanisms. The EU Green Deal's carbon border adjustment mechanism accelerates electric technology substitutions.
- Induction Heating:Eddy current systems eliminate combustion emissions and enable rapid thermal cycling for specialty alloy batches. Non-ferrous producers in Southeast Asia favor these for copper wire rod casting lines.
- Gas Heating:Natural gas and hydrogen-blend combustion systems are gaining traction in hydrogen-ready furnace retrofits targeting tuyere injection compatibility.
- Coal Heating:Coke and pulverized coal combustion remains entrenched in legacy integrated steelworks with captive coking capacity.
Electric heating dominates new order books. Induction heating posts the steepest expansion trajectory in non-ferrous segments.
End User:
Customer category determines specification complexity, with integrated steelworks demanding turnkey plant engineering and foundries prioritizing modular throughput flexibility.
- Steel Manufacturing:Primary and secondary steel producers drive demand for ultra-high-power electric arc furnace systems with transformer ratings exceeding 150 MVA.
- Non-Ferrous Metallurgy:Aluminum smelters and copper refiners specify induction systems with electromagnetic stirring for alloy homogenization.
- Foundries:Job shop casting operations favor medium-frequency induction furnaces with quick alloy changeover capability.
- Metal Recycling:Scrap processors deploy electric arc and induction systems optimized for contaminated feedstock with elevated residual element tolerance.
Steel manufacturing anchors equipment revenue. Metal recycling is climbing the fastest on circular economy policy tailwinds.
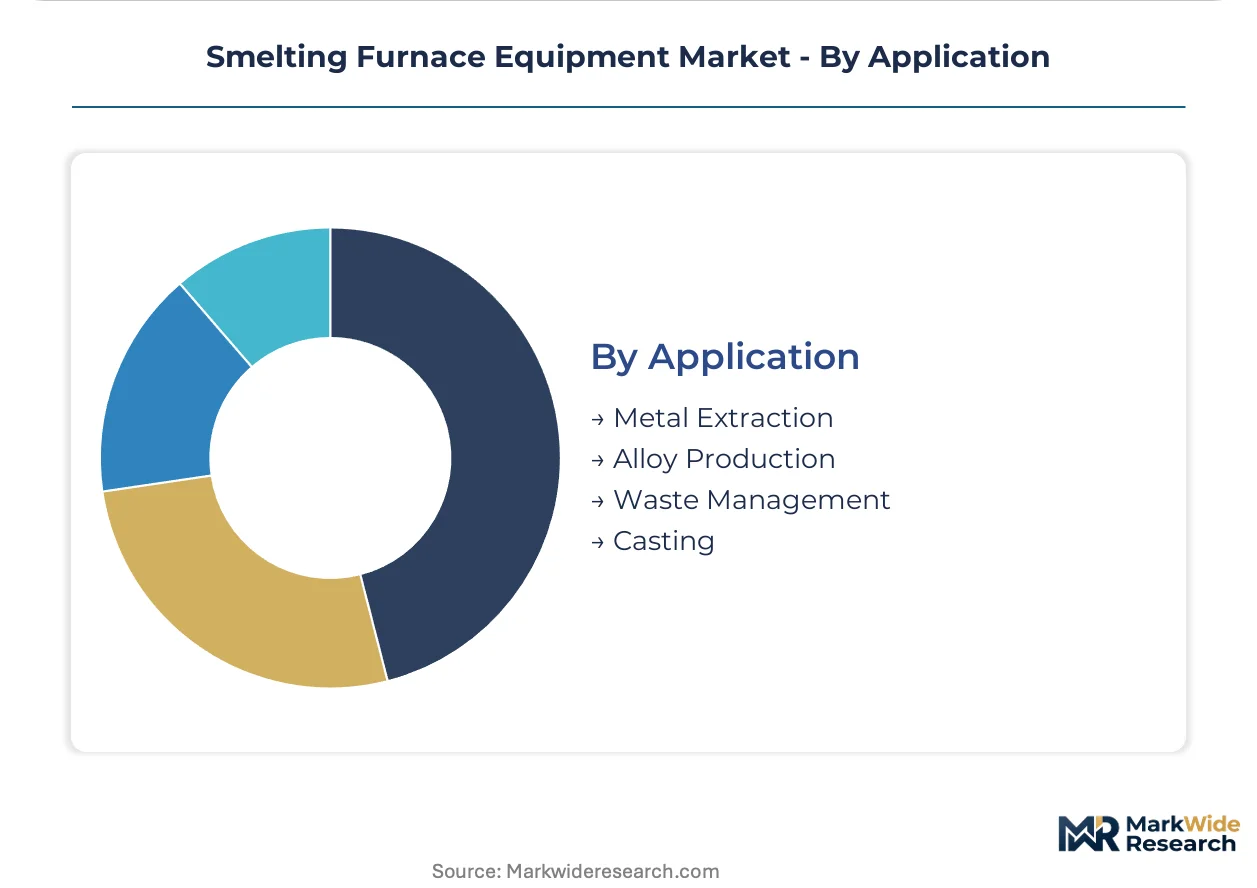
Application:
Process stage requirements dictate refractory chemistry, atmosphere control, and thermal profile specifications.
- Metal Extraction:Pyrometallurgical reduction and converting operations in primary copper and nickel production require high-intensity smelting with sulfur capture systems.
- Alloy Production:Precision melting for stainless steel and superalloy grades demands argon oxygen decarburization vessel integration.
- Casting:Liquid metal delivery systems for continuous casting and ingot pouring prioritize superheat control and inclusion management.
- Waste Management:Slag cleaning and metal recovery from industrial residues employs plasma arc and rotary furnace configurations.
Metal extraction commands the largest equipment footprint. Alloy production is gaining share fastest on aerospace and energy sector material specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deepwater port network underwrites China's dominance in electric arc furnace equipment procurement, while Germany's Rhine-Main industrial corridor anchors European demand for hydrogen-ready furnace retrofits.
China
Steelmakers in Jiangsu and Hebei provinces are dismantling coal-based blast furnaces at record pace. The Ministry of Ecology and Environment enforces dual carbon goals that block new blast furnace permits while fast-tracking electric heating substitutions. Baosteel's Zhanjiang complex is installing 300-ton electric arc furnaces with transformer ratings exceeding 150 MVA.
Germany
ThyssenKrupp's Duisburg steelworks and Salzgitter AG are piloting hydrogen injection tuyere systems for blast furnace retrofits. The EU Green Deal's carbon border adjustment mechanism penalizes imported steel emissions, forcing domestic producers to decarbonize. North Rhine-Westphalia's Ruhr Valley hosts the continent's densest cluster of furnace engineering consultancies and refractory service providers.
India
Induction furnace deployments are accelerating across Gujarat's aluminum extrusion belt and Tamil Nadu's copper wire rod sector. The Bureau of Indian Standards mandates energy efficiency labeling for melting equipment above 500 kW capacity. Rajkot's foundry cluster alone added 200 medium-frequency induction units in the past 24 months for automotive component casting.
United States
Nucor's micro-mill network in the Southeast and Steel Dynamics' Texas operations are expanding electric arc furnace capacity for flat-rolled steel. EPA emissions standards and OSHA workplace exposure limits compel investment in fume extraction and refractory dust containment. The Port of Houston's scrap metal throughput supports Gulf Coast furnace feedstock security.
Vietnam
Greenfield steel projects in Ba Ria-Vung Tau and Ha Tinh provinces are creating demand for turnkey furnace-electrical-transformer packages. The country's national industrial policy prioritizes secondary steelmaking over imported coke-dependent routes. Hoa Phat Group's Dung Quat complex is integrating electric arc furnaces with continuous casting lines for construction-grade rebar.
Smelting Furnace Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying electrodes, refractories, and automation modules. The supplier base fragments across three tiers: full-line plant engineering houses, furnace-specific OEMs, and aftermarket service contractors. Two strategic archetypes dominate—European engineering firms bundling furnace-to-rolling-mill integration, and Asian fabricators competing on equipment cost and delivery speed. Competitive moves center on geographic expansion into Southeast Asian greenfield sites and technology licensing for hydrogen-ready retrofit packages.
Among European engineering groups, Tenova S.p.A., SMS Group, and ANDRITZ AG exemplify contrasting strategic positions. Tenova S.p.A. occupies a leadership position in electric arc furnace technology deployment across South Asian greenfield projects. SMS Group represents the integrated plant engineering archetype, extending scope from furnace design through downstream rolling equipment. ANDRITZ AG anchors the environmental retrofit specialist tier, focusing on process efficiency upgrades that sustain margins in mature metallurgy markets. These three firms illustrate how geographic origin and organizational structure shape competitive positioning without requiring identical capability portfolios.
| Leading Market Players |
|---|
| ANDRITZ AG |
| Tenova S.p.A. |
| SMS Group |
| SECO/WARWICK Group |
| Inductotherm Group |
| ABB Group |
| Ipsen International GmbH |
| Carbolite Gero |
| Lindberg/MPH |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta's deepwater port network channels graphite electrode and refractory ceramic imports through Shanghai-Ningbo corridors, concentrating inbound logistics costs for electric arc furnace operators while enabling volume-discount procurement leverage for integrated steelworks that consolidate transformer and vessel orders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates turnkey plant engineering with bundled after-sales service from equipment-only procurement and basic fabricator-supplied vessels. Price differentiation hinges on certification grade (ISO 3834 welding compliance versus basic factory acceptance) and after-sales service bundling (scheduled refractory rebuild contracts versus ad-hoc maintenance). Pricing pressure stems from graphite electrode cost volatility and magnesite export quota constraints inflating lining replacement expenses. Foundry operators in India's Gujarat cluster exhibit highest price sensitivity due to thin aluminum extrusion margins, while integrated steelworks in China prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Supplier-financing facilities extended by European engineering houses to Vietnamese greenfield projects are compressing payment cycles for furnace-transformer packages while shifting working capital burdens upstream. Manufacturing concentration clusters in China for graphite electrodes and ultra-high-power transformers, Germany for hydrogen-ready tuyere injection systems, and India for medium-frequency induction coil assemblies. Raw material dependencies center on magnesite ore from Liaoning province, high-purity copper for induction windings sourced from Chilean concentrate, and specialty steel for pressure vessels from Western European mills. Single-source vulnerability risks concentrate in Chinese graphite electrode production. Distribution runs through EPC contractor-led turnkey procurement for large steelworks and regional equipment distributors serving foundry clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among integrated steelworks in China and Vietnam that bundle furnace orders with rolling mill contracts, fragmenting supplier pricing leverage and compressing equipment margins for standalone furnace OEMs.
For Market Incumbents: Insulate service revenue streams by embedding predictive refractory wear monitoring software into long-term maintenance contracts, countering Asian fabricators competing on equipment cost alone. Deepen backward integration into ceramic matrix composite lining production to capture margin erosion from Chinese magnesite quota restrictions. Prioritize hydrogen-ready retrofit certification investment to anchor European blast furnace upgrade cycles. For New Entrants and Emerging Players: Vietnam's Ba Ria-Vung Tau greenfield corridor offers underpenetrated demand for modular electric arc furnace packages sized below 100 tons, a segment European majors underserve due to minimum efficient scale thresholds. Target India's Rajkot foundry cluster with medium-frequency induction furnaces featuring quick-change coil designs for alloy flexibility, selling through regional distributors rather than direct EPC relationships to bypass incumbent channel control. For Investors and Strategic Acquirers: The EU Green Deal's carbon border adjustment mechanism reshapes the acquisition landscape by penalizing imported steel emissions and accelerating hydrogen-ready furnace retrofit demand. Long-term viability favors targets with hydrogen injection tuyere intellectual property and European installed base relationships. Watch for MEE permit acceleration signals in Hebei province as inflection indicators for Chinese electric arc furnace replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Retrofit Certification | EU carbon border adjustments force blast furnace operators toward tuyere injection compatibility. |
| Backward Integration into Refractories | Captive magnesite brick production insulates margins from Chinese export quota volatility. |
| Digital Twin Platform Integration | Real-time thermal modeling software locks in recurring service revenue from steelworks. |
| Modular Furnace Architecture Development | Decoupled melting capacity appeals to Southeast Asian mini-mill operators seeking capital flexibility. |
| Equipment-as-a-Service Contracting | Throughput-based pricing with bundled maintenance captures India's foundry preference for operational expenditure predictability. |
Research Methodology
A standing panel of plant engineers at integrated steelworks, procurement directors at aluminum smelters, aftermarket service heads at furnace OEMs, and refractory installation contractors provided ongoing calibration across primary interview cycles. Secondary validation drew from MEE permit disclosure filings, EU ETS carbon price registries, Indian Bureau of Energy Efficiency equipment labeling databases, and customs trade data for graphite electrode flows. Bottom-up unit economics triangulated against top-down steel capacity build-out projections.
Scenario-bracketing framed low, base, and high cases across the projection horizon, modeling electric arc furnace penetration rates, induction furnace share in non-ferrous segments, blast furnace retirement timelines, and hydrogen injection adoption curves. Segmentation dimensions spanned furnace architecture, energy input modality, end-user category, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, greenfield capacity announcements, and technology substitution elasticities calibrated against historical furnace order data.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed engineering consortia into European retrofit markets would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
North America Mobile Light Tower Market
Construction Equipment
Wood Chipping Machinery Market
Construction Equipment
Heating Roller Press Calender Machine Market
Construction Equipment
Cold Heading Machine Market
Construction Equipment
Cranes Rental Market
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
Global Riveting Equipment Market
Construction Equipment
TBR Hydraulic Curing Press Market
Construction Equipment
Boom Lifts Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Thermal Spray Equipment Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market
Construction Equipment
Asia-Pacific Completion Equipment and Services Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
Construction Camera [Time Lapse Camera] Market
Construction Equipment
China Elevator Ropes Market