
 Construction Equipment Market | 2026-2036
Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Equipment Market Analysis
Equipment electrification and telematics integration is unwinding legacy diesel-centric product hierarchies across the construction equipment sector. Caterpillar Inc. leverages its integrated dealer network and remanufacturing infrastructure to sustain aftermarket revenue density. Komatsu Ltd. anchors its position through autonomous haulage systems and IoT-enabled fleet management platforms. XCMG Group competes aggressively on manufacturing scale and cost-engineered hydraulic architectures for developing markets.
Construction equipment encompasses mobile machinery engineered for earthmoving, material handling, and site preparation tasks, typically powered by diesel engines rated between 75 and 750 horsepower and governed by hydraulic or electric drivetrain systems. Its primary commercial purpose is to mechanize heavy civil engineering, building construction, and mining operations where manual labor proves economically or physically unfeasible. Excavators command the largest product-type revenue pool due to versatility across demolition and earth-moving applications, while electric technology represents the fastest-growing segment as battery energy density improves and on-site charging infrastructure proliferates. The infrastructure end-user segment absorbs the highest equipment volume, though residential contractors generate superior margin capture through rental fleet utilization rates.
The United States EPA Tier 4 Final standards and the European Union Stage V emission regulations are tightening particulate matter and nitrogen oxide thresholds, forcing engine recalibration and after-treatment system adoption across OEM product lines. China's MIIT dual carbon goals and GB standards for non-road mobile machinery are accelerating domestic electric and hybrid platform development. India's CEA power quality mandates and BIS certification requirements for construction machinery imports are raising technical barriers for new market entrants. Stakeholders must monitor regulatory divergence across these jurisdictions to optimize platform standardization versus regional customization investments.
Market Dynamics
Electrification mandates and emission compliance deadlines are compressing product development cycles across the construction equipment sector, forcing simultaneous redesign of powertrain architectures and hydraulic systems.
Growth Catalysts
- India's National Infrastructure Pipeline:Metro rail expansions and highway corridors are accelerating procurement of excavators and earth-moving machinery.
- Tier 4 Final and Stage V standards:EPA and EU emission regulations are compelling fleet operators to replace aging diesel equipment with compliant models.
- Battery energy density improvements:Lithium-ion cell chemistry advances are extending electric equipment runtime between charging cycles.
Market Restraints
- Steel and rare earth input volatility:Fluctuating prices for high-grade steel and permanent magnet materials compress margin predictability for hydraulic component manufacturers.
- After-treatment system complexity:Diesel particulate filters and selective catalytic reduction add maintenance burden and downtime risk for contractors.
- Charging infrastructure gaps:Rural and remote construction sites lack grid capacity for electric equipment deployment.
Strategic Opportunities
- Autonomous haulage convergence:Integration of LiDAR and machine vision with telematics platforms creates unmanned fleet operation potential in mining applications.
- Remanufacturing services:Component refurbishment and engine rebuild programs capture aftermarket revenue from aging installed base.
- CEA power quality mandates:India's certification requirements for construction machinery imports raise technical barriers that favor established suppliers with compliance infrastructure.
Industry Challenges
- Hydraulics-electronics integration:Legacy mechanical systems require extensive redesign to accommodate sensor networks and predictive maintenance algorithms.
- Technician skill gaps:Shortage of technicians trained in high-voltage battery systems and CAN bus diagnostics limits service network expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Equipment Market |
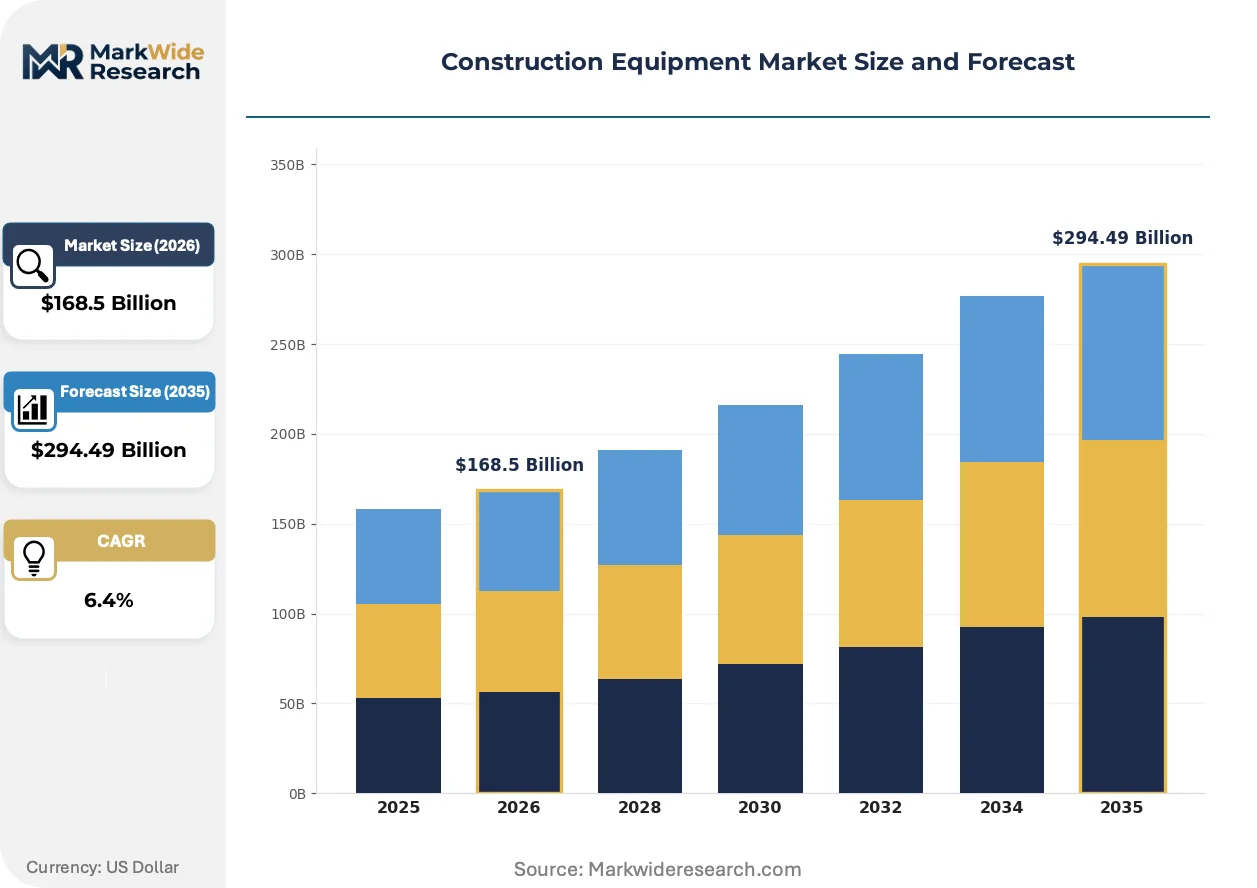
| Market Size in 2026 | $168.5 Billion |
| Market Size in 2035 | $294.49 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
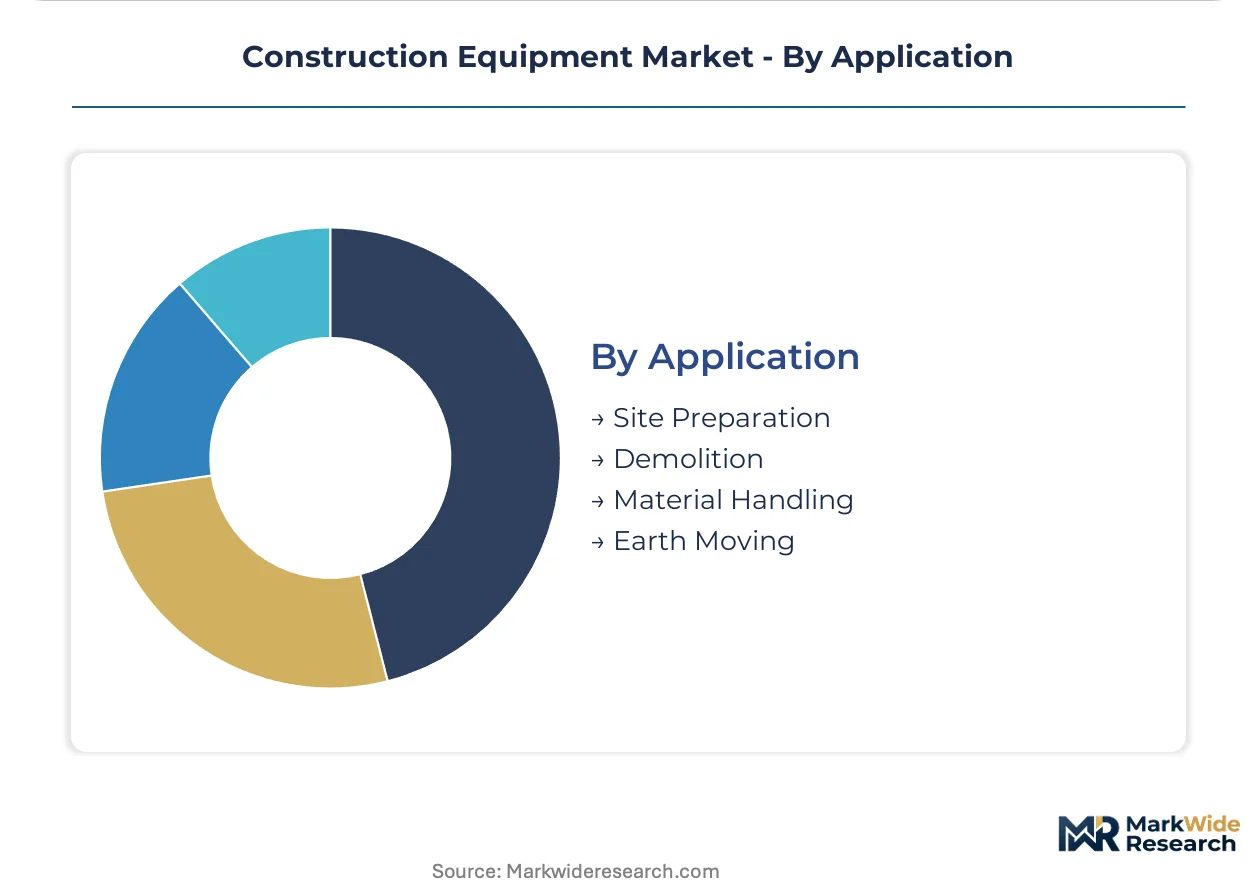
| Segmentation | Product Type: Excavators, Loaders, Cranes, Bulldozers Technology: Hydraulic, Electric, Pneumatic, Mechanical End User: Commercial, Residential, Infrastructure, Industrial Application: Site Preparation, Demolition, Material Handling, Earth Moving |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Deere & Company, XCMG Group, SANY Group, Volvo Construction Equipment, Liebherr Group, Hitachi Construction Machinery, JCB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Equipment Market Emerging Trajectories
Telematics and predictive maintenance systems are transforming equipment utilization models from ownership-based to performance-optimized contracts, compressing traditional service intervals.
Electrified auxiliary power units for hydraulic excavators are miniaturizing onboard battery packs while maintaining breakout force specifications. Urban demolition contractors in Germany and Japan are adopting these configurations to comply with municipal noise ordinances. The technology is miniaturizing the physical footprint of zero-emission equipment without sacrificing lift capacity.
China's MIIT dual carbon goals and GB standards for non-road mobile machinery are mandating domestic electric platform development by 2025. Manufacturers must redesign chassis architectures to accommodate battery thermal management. The excavator and compact loader segments face the steepest compliance timelines.
Rental fleet operators are consolidating procurement decisions through telematics-enabled utilization tracking. Equipment-as-a-service contracts now bundle maintenance and uptime guarantees, displacing traditional lease structures. This pattern concentrates most visibly in United States metropolitan construction markets where project timelines compress equipment turnover cycles.
Construction Equipment Market Segmentation
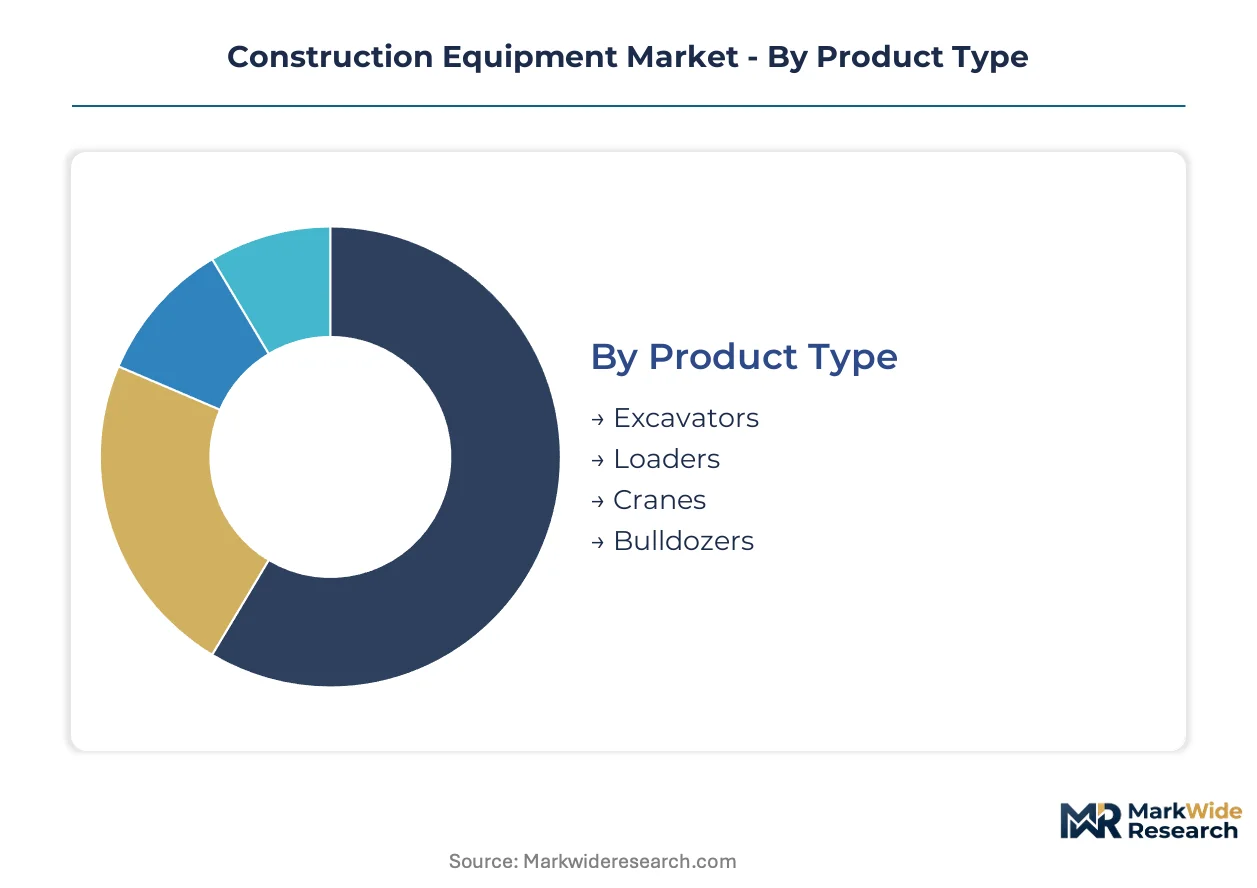
Equipment segmentation in this market tracks divergent procurement patterns between fleet operators and project contractors. Technology and application splits reveal where electrification investments concentrate versus where diesel architectures retain residual demand.
Product Type:
Export-heavy segments dominate Asian manufacturing output, while domestic absorption in India and China favors earth-moving categories for infrastructure corridors.
- Excavators:Hydraulic boom and bucket configurations rated from 3 to 800 metric tons enable trenching, grading, and lifting operations. India's National Infrastructure Pipeline absorbs crawler and wheeled variants for highway and metro earthworks, though diesel particulate filter maintenance burdens fleet operators in Tier 4 Final jurisdictions.
- Loaders:Articulated chassis designs with bucket capacities from 1 to 30 cubic yards handle aggregate and soil transport. Wheel loader procurement concentrates in Chinese urban demolition markets where GB emission standards accelerate electric platform adoption for municipal noise compliance.
- Cranes:Lattice boom and telescopic configurations serve vertical construction and heavy industrial installation.
- Bulldozers:Track-type tractors with blade attachments perform grading and clearing for mining overburden removal.
Excavators command the established base. The steepest expansion runs through loaders as compact electric variants penetrate European urban sites.
Technology:
Cost tiers separate mature hydraulic architectures from emerging electric platforms requiring battery thermal management investments.
- Hydraulic:Pressurized fluid systems transmitting force through cylinders and motors power 90% of installed construction machinery. Indian contractors favor these configurations for remote site reliability where grid infrastructure remains inadequate, though after-treatment system complexity elevates total cost of ownership in EPA-regulated markets.
- Electric:Battery-electric and tethered powertrains eliminate tailpipe emissions and reduce noise signatures. German and Japanese demolition contractors deploy compact electric excavators to satisfy municipal ordinances, with runtime limitations compressing utilization models to intermittent-duty cycles.
- Pneumatic:Compressed air systems drive specialized drilling and breaking tools in underground mining applications.
- Mechanical:Direct mechanical linkages persist in low-cost emerging market equipment and vintage machine refurbishment.
Hydraulic systems anchor current fleet composition. Electric configurations are climbing the fastest as lithium-ion energy density improvements extend operational runtime.
End User:
Customer type determines whether procurement flows through rental intermediaries or direct OEM relationships.
- Infrastructure:Government-backed highway, rail, and utility projects generate the highest equipment volume absorption. India's metro expansions and China's high-speed rail corridors sustain excavator and crane procurement cycles, though payment delays from public sector clients compress contractor cash conversion.
- Commercial:Office, retail, and hospitality construction drives demand for versatile mid-size equipment. United States metropolitan contractors favor telematics-enabled rental fleets to match equipment turnover with compressed project timelines.
- Residential:Single-family and multi-family housing construction generates superior margin capture through compact equipment utilization.
- Industrial:Manufacturing facility and energy infrastructure projects require specialized heavy-lift and material handling configurations.
Infrastructure commands the established base. The steepest expansion runs through commercial end users as Equipment-as-a-Service contracts displace traditional lease structures.
Application:
Volume concentration varies by whether tasks demand continuous earth movement or intermittent material placement.
- Earth Moving:Mass excavation, grading, and trenching operations consume the largest diesel fuel volumes and equipment hours. India's highway corridor projects under the National Infrastructure Pipeline sustain demand for 20-40 ton excavators and articulated dump trucks, though Stage V compliance costs elevate European fleet replacement thresholds.
- Material Handling:Loading, lifting, and transporting bulk materials and prefabricated components. United States port and logistics infrastructure investments drive demand for reach stackers and container handlers, with electrification pilots constrained by charging infrastructure gaps at remote intermodal terminals.
- Site Preparation:Land clearing, drainage installation, and subgrade stabilization precede vertical construction.
- Demolition:Building deconstruction and debris processing requires specialized attachments and dust suppression systems.
Earth moving commands the established base. The steepest expansion runs through material handling as warehouse and logistics construction accelerates in North American metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-heavy manufacturing bases in Asia supply equipment to import-dependent infrastructure markets across the Middle East and Africa. Trade flows concentrate diesel-powered earth-moving machinery toward corridor development projects. Regional procurement patterns diverge sharply between emission-regulated replacement markets and volume-driven expansion economies.
United States
Highway rehabilitation and port modernization sustain excavator and loader procurement through federal infrastructure legislation. EPA Tier 4 Final standards accelerate fleet turnover as contractors retire pre-compliant diesel units. Equipment rental consolidation in Texas and Florida concentrates telematics-enabled fleet decisions among national lessors.
China
Urban demolition and metro expansion absorb compact electric excavators under municipal noise ordinances. MIIT dual carbon goals and GB standards mandate domestic battery platform development by 2025. Manufacturing clusters in Jiangsu and Shandong provinces export cost-engineered hydraulic architectures to Belt and Road corridor projects.
Germany
Precision engineering demand from industrial construction sustains premium hydraulic system procurement. EU Stage V emission regulations and the EU Green Deal compress diesel equipment residual values. Bavarian equipment manufacturers integrate autonomous haulage software with legacy mechanical platforms for mining export markets.
India
National Infrastructure Pipeline corridor projects drive 20-40 ton excavator absorption for highway and metro earthworks. CEA power quality mandates and BIS certification requirements raise technical barriers for import-dependent contractors. Equipment deployment concentrates in Maharashtra and Gujarat where state-level urban rail expansions compress procurement cycles.
Saudi Arabia
NEOM linear city and Red Sea tourism infrastructure generate heavy-lift crane and articulated dump truck demand. Local content requirements under Vision 2030 compel joint-venture assembly arrangements with Asian OEMs. Eastern Province industrial zones anchor fleet staging for desert corridor construction where grid infrastructure constraints favor diesel retention.
Construction Equipment Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and geographic reach dimensions. The vendor base stratifies into three tiers: integrated full-line manufacturers, regional specialists, and component-focused niche players. Strategic archetypes include telematics-integrated fleet solution providers, cost-engineered volume exporters, and remanufacturing service operators. Competitive moves concentrate on autonomous system licensing partnerships and captive battery supply chain development.
Within the integrated manufacturing tier, Caterpillar Inc. and Komatsu Ltd. occupy positions defined by aftermarket infrastructure density and autonomous haulage platform maturity. XCMG Group exemplifies the scale-driven archetype through manufacturing footprint expansion in cost-sensitive developing markets. These three anchors represent divergent strategic bets on electrification timing, rental fleet penetration, and regional customization depth.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Deere & Company |
| XCMG Group |
| SANY Group |
| Volvo Construction Equipment |
| Liebherr Group |
| Hitachi Construction Machinery |
| JCB |
| Others |
Supply Flow & Price Mechanics
EPA Tier 4 Final and EU Stage V certification regimes simultaneously gate supplier qualification and stratify price tiers across diesel and electric equipment platforms, compressing margin structures for non-compliant manufacturers while rewarding OEMs with established after-treatment engineering capabilities.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with premium tiers capturing brand equity from Caterpillar and Komatsu dealer density while economy tiers compete on hydraulic component standardization. Price differentiation stems from emission certification tier and aftermarket service bundling, with Tier 4 Final-compliant units commanding substantial premiums over pre-compliant legacy inventory. Pricing pressure stems from Chinese manufacturing scale in Jiangsu and Shandong provinces, eroding margin capture in cost-sensitive developing markets. Rental fleet operators exhibit highest price sensitivity due to utilization-rate economics, while mining contractors demonstrate lowest sensitivity given uptime-guarantee requirements.
Supply Chain Analysis
Strait of Malacca transit underwrites steel and rare earth magnet flows from Chinese refineries to ASEAN assembly plants, with alternative routing through Suez Canal adding logistics cost exposure for European-bound equipment. Manufacturing concentrates in China, India, and Germany, with Jiangsu province anchoring hydraulic component forging and Bavaria hosting precision sensor integration. Raw material dependencies include high-grade structural steel, neodymium permanent magnets, and lithium-ion cell chemistries. Single-source vulnerability in rare earth processing creates supply chain risk, with distribution running through captive OEM dealer networks and independent rental fleet lessors in North American metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction equipment sits in early-cycle expansion as India's National Infrastructure Pipeline accelerates equipment procurement velocity beyond replacement-demand baselines, with metro rail and highway corridor investments lifting absorption rates for 20-40 ton excavator classes.
For Market Incumbents: Consolidate aftermarket service density through remanufacturing program expansion and captive parts distribution, defending against Chinese cost-engineered entrants by embedding telematics-enabled uptime guarantees into equipment-as-a-service contracts. Deepen backward integration into battery thermal management systems to capture electrification value pools as Stage V compliance deadlines compress diesel residual values. For New Entrants and Emerging Players: Lead with compact electric excavator platforms targeting German and Japanese urban demolition contractors facing municipal noise ordinances, where runtime-limited duty cycles match current battery energy density constraints. Pursue joint-venture assembly arrangements with Saudi Vision 2030 local content requirements, leveraging Asian manufacturing partnerships to bypass CEA and BIS certification barriers in Indian import markets. For Investors and Strategic Acquirers: EU Stage V and China's MIIT dual carbon goals reshape the acquisition landscape by elevating stranded asset risk in pre-compliant diesel portfolios while rewarding electric platform development capabilities. Long-term viability centers on OEMs with autonomous haulage software maturity and captive battery supply chain positioning. Watch for inflection in charging infrastructure deployment rates at remote mining and corridor construction sites as the signal for electric equipment penetration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Haulage System Licensing | LiDAR and machine vision integration unlocks unmanned mining fleet operations for Komatsu and Caterpillar dealer networks. |
| Battery Supply Chain Partnership | Captive lithium-ion cell sourcing secures thermal management component availability for XCMG and SANY electric platform launches. |
| Remanufacturing Service Expansion | Engine rebuild and hydraulic refurbishment programs capture aftermarket revenue from India's aging installed base under National Infrastructure Pipeline deployment. |
| Telematics Platform Integration | IoT-enabled fleet management compresses service intervals and enables performance-based equipment-as-a-service contracts for United States rental consolidators. |
| Joint Venture Assembly Arrangement | Local content compliance under Saudi Vision 2030 positions Asian OEMs for NEOM linear city and Red Sea tourism infrastructure procurement. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with equipment OEM procurement directors, rental fleet operations managers, mining contractor maintenance heads, and aftermarket service specialists, combined with secondary validation through SEC 10-K filings, customs and trade flow databases, EPA and EU emission compliance registries, and Indian BIS certification records. Bottom-up equipment unit economics triangulated against top-down infrastructure investment pipeline valuations across the analysis window.
Forecasts span the projection horizon through segmented modeling across product type, technology architecture, end-user category, and application intensity dimensions, with CAGRs derived from historical replacement cycles, emission compliance deadline clustering, and infrastructure procurement pipeline visibility. Key inputs include battery energy density improvement trajectories, steel and rare earth price volatility indices, and regional grid infrastructure deployment rates for electric equipment charging.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure investment execution, stable raw material input costs, or accelerated charging infrastructure buildout would require recalibration. Practitioners should keep alternative scenarios live as regulatory divergence across EPA, EU Stage V, and China MIIT frameworks evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Earthmoving Equipment Tyres Market
Construction Equipment
Winch Market
Construction Equipment
LAMEA Water Pump Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
Small Bulldozers Market
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Bale Openers Market
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Skid Steer Loader Market
Construction Equipment
Mill Pulverizer Market
Construction Equipment
Earthmoving Equipment Undercarriage Market
Construction Equipment
Brazil Metal Fabrication Equipment Market
Construction Equipment
Global Welding Market